
 Global B2B E-Commerce Market | 2026-2036
Global B2B E-Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
Global B2B E-Commerce Market Foresight
API-first architecture is consolidating as the foundational material replacing legacy EDI systems in B2B transaction infrastructure, cutting integration costs by eliminating custom middleware. Amazon.com Inc. leverages its fulfillment network to anchor industrial supply contracts, while Alibaba Group Holding Ltd. dominates cross-border wholesale corridors through verified supplier ecosystems. W.W. Grainger Inc. specializes in MRO category depth, competing on same-day delivery density rather than assortment breadth.
B2B E-Commerce denotes digital platforms facilitating commercial transactions between business entities, typically requiring multi-user account hierarchies, negotiated contract pricing, purchase order workflows, and ERP integration through REST or GraphQL APIs rather than consumer-grade checkout flows. Wholesale trade platforms currently occupy the largest transaction volume pool, though manufacturing procurement segments are recording the fastest expansion as OEMs digitize direct material sourcing. Cloud-based deployment models lead new platform adoption, while hybrid architectures persist among regulated industries requiring on-premise data residency for sensitive supplier negotiations.
The EU AI Act, GDPR, and REACH frameworks collectively shape European platform requirements, mandating algorithmic transparency in procurement matching engines and chemical substance traceability across supplier tiers. In the United States, the SEC climate disclosure rules and FDA traceability mandates for food and pharmaceutical supply chains are accelerating investment in audit-ready platform infrastructure. Stakeholders must monitor emerging interoperability standards between national digital procurement networks, as fragmented certification regimes threaten to segment cross-border platform access.
Market Dynamics
API-first architecture is consolidating as the foundational material replacing legacy EDI systems in B2B transaction infrastructure, cutting integration costs by eliminating custom middleware and compressing supplier onboarding timelines from months to days.
Growth Catalysts
- Cloud Migration:Manufacturing procurement teams are expanding platform adoption to streamline supplier discovery and contract management through centralized dashboards.
- GDPR Compliance Requirements:The EU AI Act and GDPR are pushing European buyers toward certified cloud-based procurement platforms with algorithmic transparency.
- Supply Chain Digitization:Demand is concentrating in the United States, China, and Germany as these markets build out integrated supply chain digitization infrastructure.
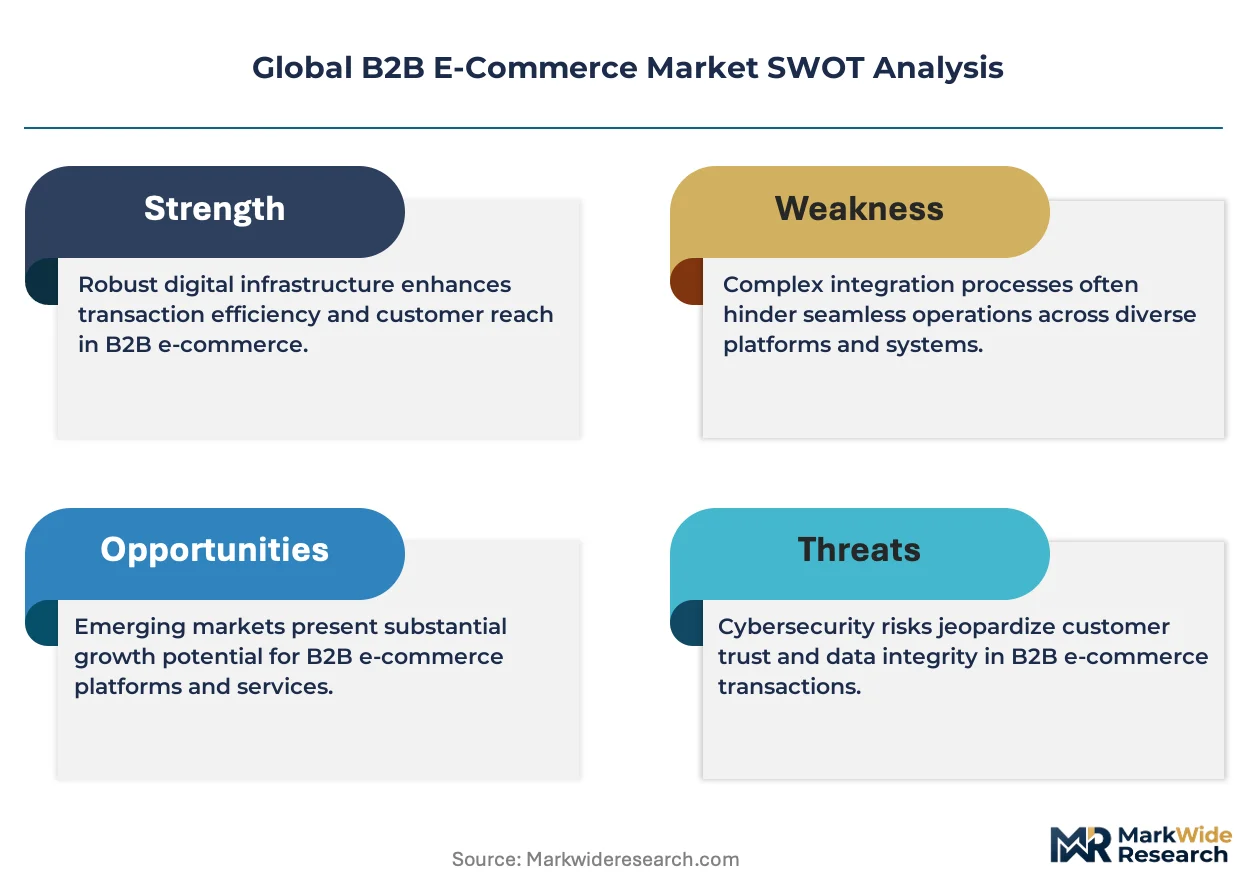
Market Restraints
- Data Residency Mandates:Hybrid architectures persist among regulated industries requiring on-premise data residency for sensitive supplier negotiations, limiting pure-cloud adoption.
- Integration Complexity:Legacy ERP systems in industrial manufacturing create technical debt that slows API migration and extends implementation cycles.
- REACH Traceability:Chemical substance traceability requirements across supplier tiers add compliance overhead that smaller trading platforms struggle to absorb.
Strategic Opportunities
- Cross-Border Wholesale Corridors:Verified supplier ecosystems are unlocking trade finance integration and customs pre-clearance for emerging market exporters.
- MRO Category Depth:Same-day delivery density in industrial maintenance supplies represents an underexploited wedge against broad-assortment competitors.
- SEC Climate Disclosure Rules:Audit-ready platform infrastructure for carbon accounting is creating premium tier demand among publicly traded manufacturers.
Industry Challenges
- Interoperability Fragmentation:Emerging national digital procurement networks lack unified certification regimes, threatening to segment cross-border platform access.
- API Talent Scarcity:REST and GraphQL integration specialists command premium wages, constraining mid-market platform development velocity.
- Algorithmic Audit Burden:Procurement matching engines now require documented decision logic to satisfy EU AI Act transparency mandates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global B2B E-Commerce Market |
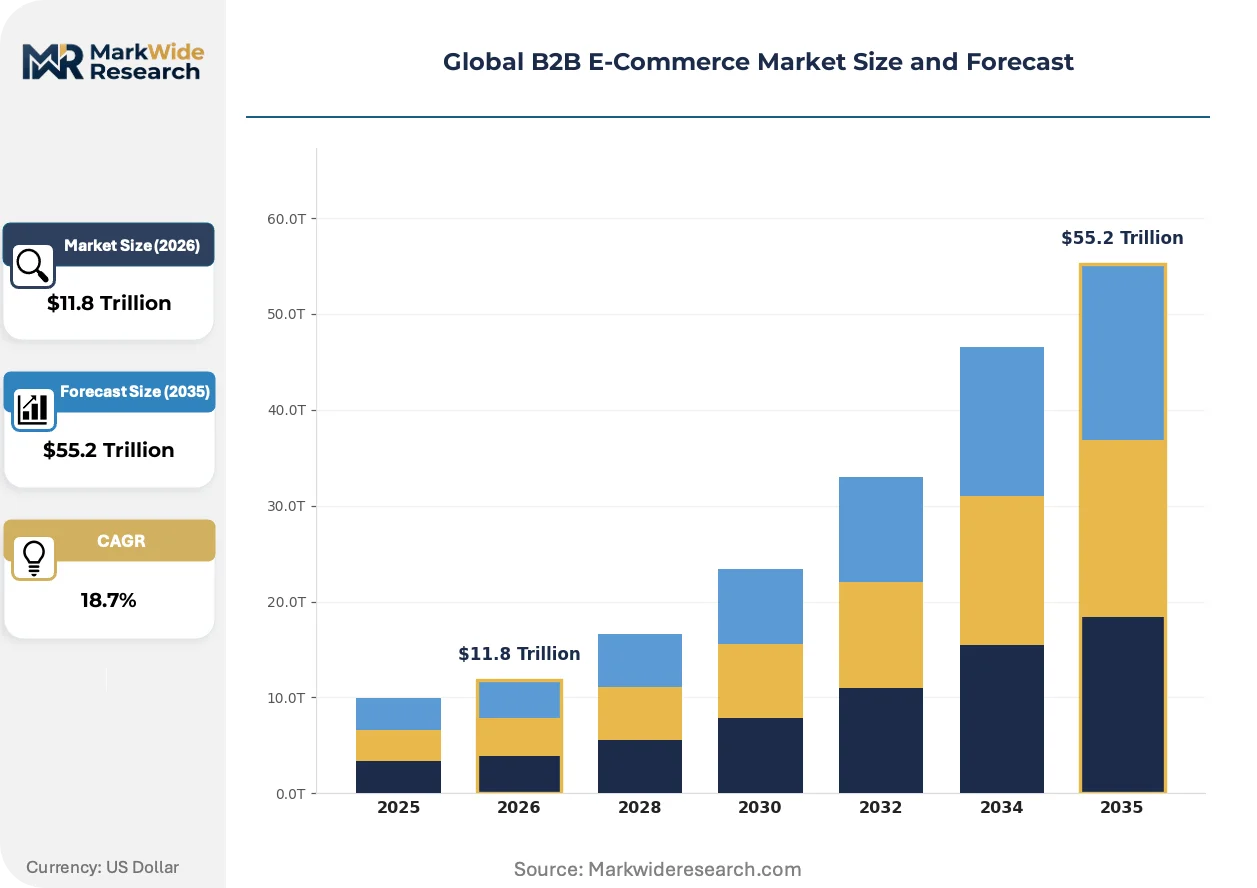
| Market Size in 2026 | $11.8 Trillion |
| Market Size in 2035 | $55.2 Trillion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform Type: Supplier Oriented, Buyer Oriented, Intermediary Oriented, Vertical Marketplace Application: Wholesale Trade, Manufacturing Procurement, Distributors, Institutional Purchasing Deployment Model: Cloud-Based, On-Premise, Hybrid, SaaS Buyer Type: Large Enterprises, Small & Medium Enterprises, Resellers, Government Agencies |
| Companies Covered | Alibaba Group Holding Ltd., Amazon.com Inc., eBay Inc., IndiaMART InterMESH Ltd., Global Sources Ltd., W.W. Grainger Inc., Walmart Inc., Shopify Inc., DHgate.com, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global B2B E-Commerce Market Shifts & Advancements
Platform architecture is pivoting from transaction facilitation toward embedded financial services and predictive supply risk analytics, embedding credit, insurance, and compliance verification directly into procurement workflows.
Composable commerce stacks built on headless architecture are expanding into industrial procurement, separating frontend interfaces from backend fulfillment logic. Automotive and aerospace OEMs are adopting these modular systems fastest, with tier-one suppliers following within eighteen months. This shift is expanding into adjacent categories previously locked into monolithic ERP purchasing modules.
The EU AI Act's algorithmic transparency requirements are forcing procurement platforms to expose matching logic and recommendation engines to buyer audit. Industrial purchasers in Germany and France now demand documented training data provenance for supplier ranking algorithms. Food and pharmaceutical buyers subject to FDA traceability mandates are extending these requirements to ingredient-level provenance tracking.
Self-service procurement portals are displacing traditional sales representative relationships in mid-market manufacturing. Buyers expect real-time inventory visibility and dynamic contract pricing without human negotiation. This behavioral shift is most visible in United States industrial distribution, where procurement teams now rate platform UX parity with product availability and price competitiveness.
Global B2B E-Commerce Market Segmentation
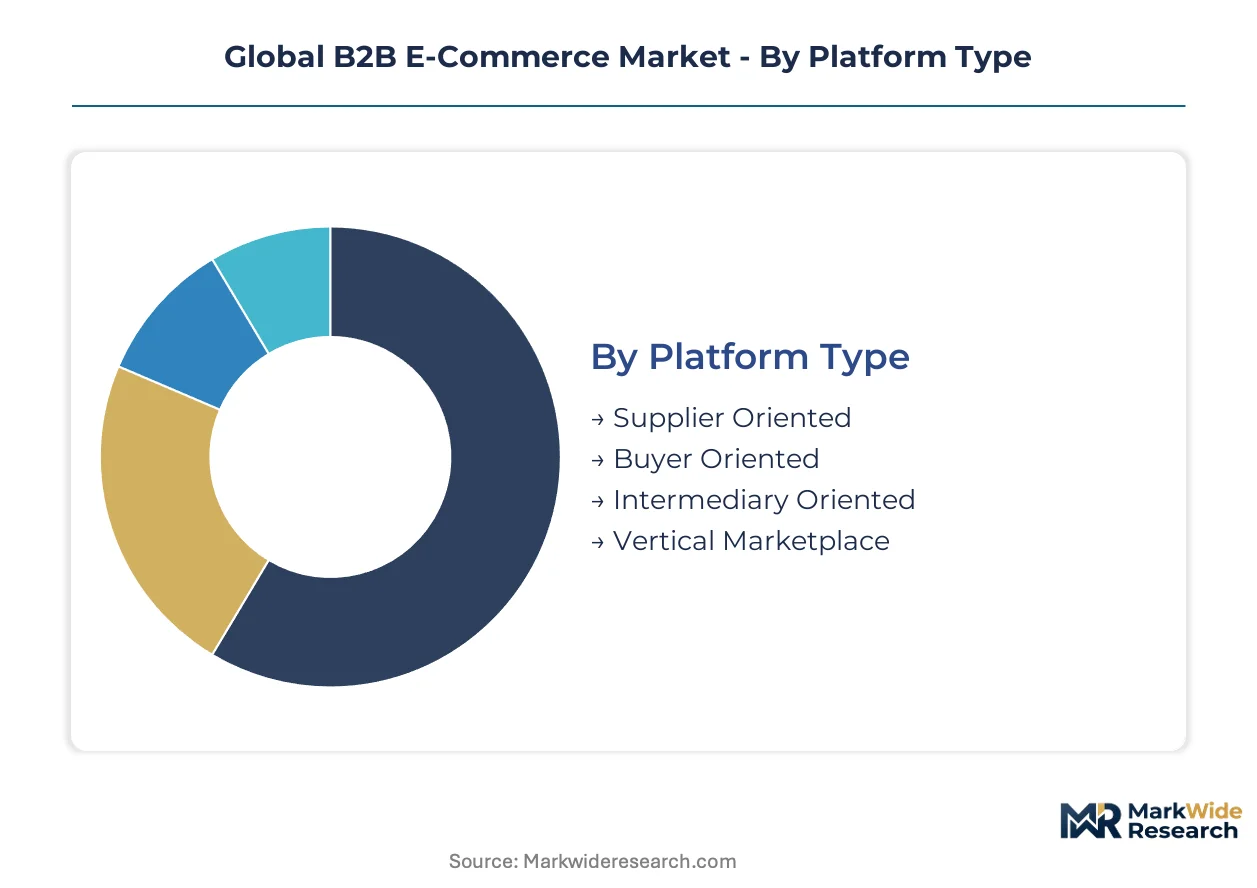
Platform architecture and procurement workflows vary sharply across deployment configurations and buyer sophistication levels. Understanding these divides reveals where integration costs concentrate and which segments drive margin expansion for infrastructure providers.
Platform Type:
Supplier-oriented platforms demand the heaviest upfront capital investment due to inventory carrying requirements and fulfillment network buildout.
- Supplier Oriented:Platforms where manufacturers or distributors list catalog inventory directly to buyers, controlling pricing and fulfillment terms. Industrial MRO suppliers in Germany and the United States dominate this segment as they digitize legacy sales representative relationships. Demand concentrates among buyers seeking direct manufacturer relationships to bypass distributor markups.
- Buyer Oriented:Procurement systems configured around enterprise purchasing requirements, with reverse auction functionality and approved vendor lists. Large manufacturers in China deploy these platforms to consolidate fragmented supplier bases across provincial industrial clusters. The EU AI Act's algorithmic transparency mandates are reshaping how matching engines rank vendor bids.
- Intermediary Oriented:Third-party platforms facilitating transactions without taking inventory positions, earning fees on transaction value or subscription access. Cross-border trade corridors between Southeast Asian exporters and European buyers rely heavily on these neutral intermediaries.
- Vertical Marketplace:Industry-specific platforms serving narrow categories such as chemicals, electronics components, or medical supplies. REACH compliance verification and chemical substance traceability requirements elevate platform stickiness in European chemical procurement.
Supplier-oriented platforms absorb the bulk of installed capacity; vertical marketplaces are expanding most quickly.
Application:
Procurement complexity and transaction frequency determine platform feature requirements across use cases.
- Wholesale Trade:High-volume, low-complexity transactions between distributors and downstream retailers or smaller businesses. Alibaba's verified supplier ecosystems anchor cross-border wholesale corridors, with customs pre-clearance integration reducing delivery friction. Demand concentrates in consumer goods and electronics categories with standardized specifications.
- Manufacturing Procurement:Direct material sourcing with engineering specification validation, quality certification, and long-term contract frameworks. Automotive OEMs in Germany and aerospace manufacturers in France are digitizing these workflows fastest, driven by tier-one supplier compliance requirements.
- Distributors:Inventory aggregation platforms serving as digital intermediaries between multiple suppliers and fragmented buyer bases. W.W. Grainger's same-day delivery density in United States industrial distribution exemplifies competitive positioning through fulfillment speed rather than assortment breadth.
- Institutional Purchasing:Government and healthcare procurement subject to public tender regulations and audit transparency requirements. The SEC climate disclosure rules are extending carbon accounting requirements into public sector supplier qualification in the United States.
Wholesale trade carries the highest transaction volumes; manufacturing procurement is climbing the fastest as OEMs digitize direct material sourcing.
Deployment Model:
Data residency requirements and integration legacy dictate infrastructure choices across regulated and unregulated industries.
- Cloud-Based:Fully hosted platforms with multi-tenant architecture, API-first integration, and automatic compliance updates. GDPR and EU AI Act requirements are pushing European buyers toward certified cloud deployments with documented algorithmic decision logic. Pharmaceutical buyers subject to FDA traceability mandates favor these platforms for audit-ready infrastructure.
- On-Premise:Self-hosted installations maintaining data within buyer-controlled data centers, typically in defense, classified government, or sensitive chemical procurement. Germany's industrial Mittelstand retains significant on-premise deployment for supplier negotiation confidentiality.
- Hybrid:Split architectures with sensitive data on-premise and transaction processing in cloud environments. REACH traceability requirements across chemical supplier tiers drive hybrid adoption among European specialty chemical purchasers.
- SaaS:Subscription-accessed platforms with standardized configurations and limited customization, targeting mid-market buyers without dedicated IT procurement teams. Self-service portals displacing traditional sales relationships in United States industrial distribution fall predominantly into this category.
Cloud-based deployments dominate new platform adoption; hybrid architectures are gaining share fastest among regulated industries.
Buyer Type:
Organizational scale determines purchasing workflow complexity and platform integration depth.
- Large Enterprises:Multi-divisional buyers with ERP integration requirements, negotiated contract pricing, and multi-user approval hierarchies. These buyers drive API-first architecture adoption and demand REST or GraphQL connectivity rather than legacy EDI systems.
- Small & Medium Enterprises:Resource-constrained buyers prioritizing self-service interfaces and pre-negotiated supplier terms over customization. Real-time inventory visibility and dynamic contract pricing without human negotiation are becoming baseline expectations.
- Resellers:Intermediary buyers purchasing through B2B platforms for downstream resale, requiring drop-ship integration and white-label fulfillment capabilities. Cross-border wholesale platforms serving emerging market exporters target this segment with trade finance integration.
- Government Agencies:Public sector buyers subject to procurement regulations, transparency requirements, and domestic preference rules. Audit-ready platform infrastructure for carbon accounting is creating premium tier demand among agencies implementing climate disclosure frameworks.
Large enterprises command the deepest platform integration; small and medium enterprises are adopting cloud-based procurement tools fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement digitization investment concentrates in the United States, China, and Germany as these markets build integrated supply chain infrastructure. The EU AI Act and SEC climate disclosure rules are reshaping platform compliance requirements across jurisdictions.
United States
Industrial distribution buyers prioritize self-service portals with real-time inventory visibility and dynamic contract pricing. SEC climate disclosure rules mandate audit-ready carbon accounting infrastructure for publicly traded manufacturers. Procurement digitization accelerates fastest in Chicago and Detroit industrial corridors as automotive OEMs digitize tier-one supplier compliance.
China
Cross-border wholesale corridors drive verified supplier ecosystem expansion for emerging market exporters. MIIT cloud computing standards and data localization requirements shape platform architecture decisions. Manufacturing procurement digitization clusters in the Yangtze River Delta as provincial industrial bases consolidate fragmented supplier networks.
Germany
REACH chemical traceability mandates and EU AI Act algorithmic transparency requirements elevate platform compliance overhead. The industrial Mittelstand retains hybrid deployment models for sensitive supplier negotiation confidentiality. Procurement platform adoption concentrates in Bavaria and Baden-Württemberg as automotive and aerospace OEMs digitize direct material sourcing workflows.
India
Small and medium enterprises drive cloud-based procurement tool adoption for supplier discovery and contract management. DGFT export promotion frameworks and BIS certification requirements shape cross-border platform integration. Digitization accelerates in Maharashtra and Gujarat as manufacturing hubs build API-first supplier onboarding infrastructure.
United Kingdom
Post-Brexit customs complexity pushes buyers toward platforms with integrated trade finance and pre-clearance capabilities. UKCA marking requirements and evolving data adequacy arrangements with the EU influence platform deployment choices. Procurement digitization concentrates in London and the Midlands as distributors rebuild continental supply relationships.
Global B2B E-Commerce Market Competitive Landscape
API-first architecture consolidation dominates the current landscape as platforms eliminate legacy EDI middleware. The vendor base organizes around three strategic archetypes: fulfillment-anchored industrial suppliers, cross-border wholesale intermediaries, and composable commerce infrastructure providers. M&A activity targets vertical marketplace depth and regional compliance expertise. Technology licensing partnerships accelerate ERP integration capabilities among mid-market platforms.
Among Asia-Pacific-based platform operators, Alibaba Group Holding Ltd. and IndiaMART InterMESH Ltd. exemplify divergent archetypes spanning cross-border wholesale corridors and domestic SME supplier aggregation. W.W. Grainger Inc. represents the fulfillment-anchored industrial distributor model competing on same-day delivery density. These three occupy positions across the intermediary-to-supplier spectrum, reflecting how geographic origin and capitalization scale shape competitive positioning within procurement digitization infrastructure.
| Leading Market Players |
|---|
| Alibaba Group Holding Ltd. |
| Amazon.com Inc. |
| eBay Inc. |
| IndiaMART InterMESH Ltd. |
| Global Sources Ltd. |
| W.W. Grainger Inc. |
| Walmart Inc. |
| Shopify Inc. |
| DHgate.com |
| Others |
Supply & Pricing Matrix
Automotive OEM procurement teams in Germany and the United States concentrate purchasing power through centralized supplier qualification programs, anchoring contract-based long-term offtake pricing with volume-scaled rebates and tiered service bundles.
Pricing Analysis
Volume-scale buyers extract margin through committed offtake agreements while mid-market purchasers face subscription-tier SaaS pricing with per-seat licensing. Three-tier pricing structure across premium, standard, and economy levels separates API-first enterprise integrations from self-service portal access and basic catalog browsing. Cost compression in the mid-market tier is intensifying because Alibaba and Amazon fulfillment networks compress delivery premiums. Small and medium enterprises exhibit highest price sensitivity, while large manufacturers prioritize integration depth over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with Chinese cloud infrastructure providers serving European platform operators under MIIT data localization mandates. Platform architecture draws from Taiwan semiconductor foundries, German industrial automation components, and Indian software engineering talent. Tariff exposure runs through cross-border wholesale corridors between Southeast Asian exporters and EU buyers. Distribution runs through fulfillment-anchored industrial distributors in Chicago and Detroit corridors, with same-day delivery density replacing inventory breadth as the competitive wedge.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
API-first architecture consolidation is forcing marginal platform operators toward distressed exits as talent scarcity and compliance overhead outstrip capitalization runway.
For Market Incumbents: Hedge against algorithmic audit burden by documenting procurement matching engine decision logic ahead of EU AI Act enforcement waves. Acquire regional compliance expertise in REACH traceability and FDA food pharmaceutical mandates to defend against emerging vertical marketplace specialists. Capacity addition in Bavaria and Baden-Württemberg industrial clusters secures proximity to automotive OEM digitization programs.
For New Entrants and Emerging Players: Capture self-service procurement portal demand among United States mid-market manufacturers displacing legacy sales representative relationships. White-space concentration sits in MRO category depth with same-day delivery density commitments rather than broad-assortment competition. Go-to-market angle: pre-negotiated supplier terms with real-time inventory visibility bypassing human negotiation friction.
For Investors and Strategic Acquirers: Distressed-cycle entries favor hybrid-deployment specialists with REACH chemical traceability certification in Germany and France. Long-term viability hinges on audit-ready platform infrastructure for SEC climate disclosure compliance among publicly traded manufacturers. Signal to watch: tier-one supplier compliance requirements accelerating automotive and aerospace OEM workflow digitization.
| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Migration | Eliminates custom EDI middleware and compresses supplier onboarding timelines for automotive OEM procurement teams. |
| Backward Integration into Fulfillment | Same-day delivery density in Chicago and Detroit corridors anchors industrial MRO contract retention against Amazon. |
| EU AI Act Compliance Certification | Documented algorithmic transparency in procurement matching engines unlocks German and French public sector tenders. |
| Vertical Marketplace Acquisition | REACH traceability expertise in European chemical procurement creates defensive moats against broad-platform competitors. |
| Cross-Border Trade Finance Integration | Customs pre-clearance capabilities for Southeast Asian exporters reduce delivery friction in Alibaba wholesale corridors. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced against primary interviews with procurement platform CTOs, industrial distribution category managers, ERP integration specialists, and automotive OEM supplier quality directors. SEC climate disclosure submissions, EU AI Act implementation guidance, FDA traceability mandates, and REACH chemical substance databases supplied regulatory boundary conditions. Bottom-up platform deployment counts and top-down wholesale transaction value estimates underwent iterative reconciliation.
Data-stream reconciliation across deployment model, buyer organization scale, platform architecture type, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs emerged from segmented growth rate calibration against cloud migration velocity and compliance-driven replacement cycles. Forecast inputs incorporated API talent wage inflation trajectories and tier-one supplier compliance requirement diffusion patterns across automotive and aerospace supply chains.
The model holds under stable regulatory enforcement timelines and uninterrupted cloud infrastructure access; deviation in data residency mandate expansion or semiconductor supply disruption would shift platform adoption curves. Forecasts reflect documented assumptions regarding procurement team self-service behavioral shifts and ERP legacy system replacement cycles. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
Live Commerce Platforms Market
E-Commerce Solutions
E-Commerce Market
E-Commerce Solutions
Global Online Book Services Market
E-Commerce Solutions
E-Tailing Market
E-Commerce Solutions
Quick Commerce Market
E-Commerce Solutions
Czech Republic E-Commerce Market
E-Commerce Solutions
Global Subscription E-Commerce Platform Market
E-Commerce Solutions
Romania E-Commerce Market
E-Commerce Solutions
Online to Offline Commerce Market
E-Commerce Solutions
Alcohol E-Commerce Market
E-Commerce Solutions
Clothing E-Commerce Platform Market
E-Commerce Solutions
Germany E-Commerce Market
E-Commerce Solutions
Bedding E-Commerce Platform Market
E-Commerce Solutions
India Quick Commerce Market
E-Commerce Solutions
Europe E-Commerce Apparel Market
E-Commerce Solutions
United Kingdom E-Commerce Market