
 Hepatic Insufficiency/Liver Failure Market | 2026-2036
Hepatic Insufficiency/Liver Failure Market Size, Share, and Industry Trends Forecast 2026-2036
Hepatic Insufficiency/Liver Failure Market Intelligence
EU MDR is rebalancing the cost-of-entry calculus for device manufacturers seeking European market access, forcing smaller developers to consolidate regulatory capabilities. Gilead Sciences leverages its antiviral portfolio dominance to sustain leadership in hepatitis-related liver disease management. Bristol Myers Squibb anchors its position through immunology assets that address autoimmune-driven hepatic complications. AbbVie differentiates via hepatology-focused R&D pipelines targeting fibrosis progression pathways.
Hepatic insufficiency denotes the liver's progressive inability to perform metabolic, synthetic, and detoxification functions, quantified clinically by rising Model for End-Stage Liver Disease scores and declining albumin production. This condition drives commercial demand for interventions that restore ammonia clearance, coagulation factor synthesis, and drug metabolism capacity. The therapy area dimension shows cirrhosis management occupying the largest revenue pool due to chronic care requirements, while acute liver failure commands premium pricing for intensive interventions. Among end users, hospitals retain the dominant share through captive referral networks, though homecare settings are gaining traction for nutritional supplement administration and post-acute monitoring.
FDA breakthrough therapy designations compress development timelines for novel hepatic targets, while EMA's adaptive pathways framework creates parallel European access routes. The EU AI Act introduces compliance layers for diagnostic algorithms used in liver imaging and fibrosis staging. Stakeholders must monitor how reimbursement authorities in key markets weight clinical outcomes against total cost-of-care for competing modalities.
Market Dynamics
Hospital procurement departments in the United States, Germany, and Japan are consolidating vendor relationships for liver support devices, compressing supplier margins while accelerating adoption of integrated diagnostic-therapeutic platforms.
Growth Catalysts
- EU MDR breakthrough pathway:The European Medicines Agency's adaptive pathways framework accelerates conditional approvals for novel hepatic therapeutics, shortening time-to-reimbursement for developers targeting fibrosis progression.
- Japan's hepatology center expansion:METI-funded specialized liver units in Tokyo and Osaka are driving demand for advanced albumin replacement systems and molecular adsorbent recirculating devices.
- Ammonia clearance biotechnology:Enzymatic approaches to hyperammonemia management are attracting venture investment, with clinical validation programs expanding across German university hospitals.
Market Restraints
- Human hepatocyte supply concentration:Primary cell sourcing for bioartificial liver systems depends on a limited network of US and European tissue banks, creating batch-to-batch variability risks.
- Albumin cost volatility:Plasma fractionation capacity constraints and plasma collection economics in the United States drive input cost instability for synthetic function replacement therapies.
- FDA IND timeline friction:Investigational new drug application requirements for cell-based liver support devices extend preclinical development phases beyond typical venture capital horizons.
Strategic Opportunities
- Homecare nutritional monitoring:Post-acute cirrhosis patients in Germany represent an underpenetrated segment for remote albumin tracking and automated dietary intervention systems.
- AI-assisted fibrosis staging:The EU AI Act's risk-classification framework for diagnostic algorithms creates first-mover advantages for vendors achieving CE marking under the new conformity assessment routes.
- Telehepatology referral networks:Japan's regional health disparities between metropolitan and rural prefectures enable platform-based specialist access models that bypass traditional hospital gatekeeping.
Industry Challenges
- Bioartificial liver manufacturing scale-up:GMP-compliant bioreactor production for three-dimensional hepatocyte culture requires capital-intensive cleanroom infrastructure that exceeds mid-cap developer balance sheet capacity.
- Cross-border clinical data harmonization:Divergent endpoint definitions between FDA and EMA guidance documents for acute liver failure trials complicate multi-registrational study designs.
- Legacy EMR integration:Hepatic encephalopathy monitoring algorithms face deployment friction within hospital information systems that lack standardized API architectures for real-time ammonia telemetry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hepatic Insufficiency/Liver Failure Market |
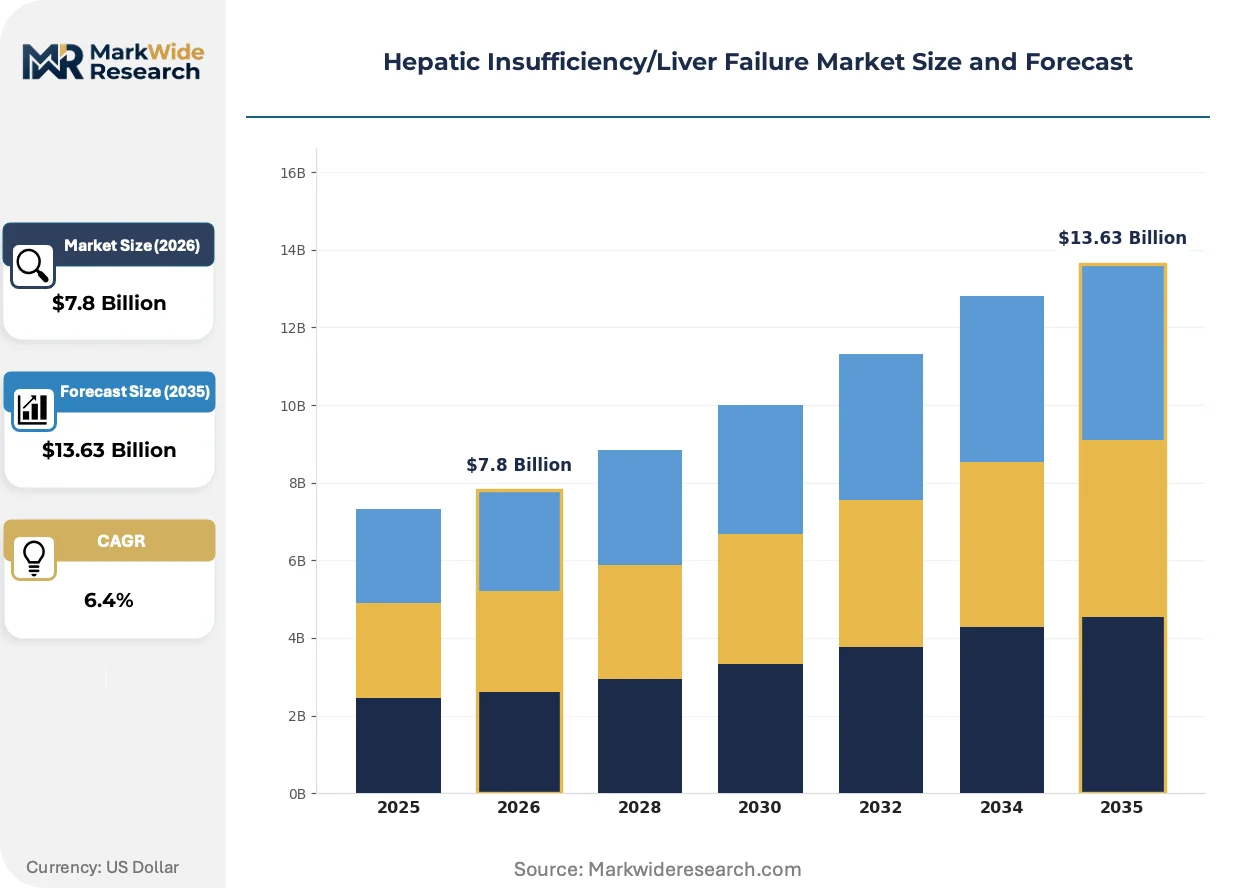
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.63 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drugs, Diagnostics, Devices, Nutritional Supplements Therapy Area: Cirrhosis, Hepatitis, Drug-Induced Liver Injury, Acute Liver Failure End User: Hospitals, Clinics, Homecare Settings, Diagnostic Laboratories Administration Route: Oral, Intravenous, Subcutaneous, Rectal |
| Companies Covered | Gilead Sciences, Inc., AbbVie Inc., Bristol Myers Squibb, Novartis AG, Pfizer Inc., F. Hoffmann-La Roche Ltd., Johnson & Johnson Services, Inc., Abbott Laboratories, Merck & Co., Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hepatic Insufficiency/Liver Failure Market Strategic Shifts & Innovations
Artificial intelligence is restructuring how hepatology centers stage fibrosis and prioritize transplant referrals, compressing diagnostic timelines while generating new liability frameworks for algorithm-assisted clinical decisions.
Extracorporeal liver support devices are absorbing functions previously managed through intensive care pharmacology, with albumin dialysis and plasma separation systems now standard in German tertiary centers and expanding into Japanese emergency departments. Hepatology units in the United States are piloting hybrid configurations that combine molecular adsorbent recirculating with continuous renal replacement, consolidating device footprints and nursing labor requirements.
EMA's adaptive pathways framework is compressing traditional phase sequencing for regenerative hepatic therapies, allowing conditional marketing authorization based on surrogate biomarker endpoints with post-authorization efficacy commitments. German and French regulators are coordinating on real-world evidence collection standards, creating a template that other EU member state competent authorities are adopting for breakthrough-designated liver products.
Japanese hospital groups are unbundling acute liver failure interventions from bundled diagnosis-related group payments, shifting toward severity-adjusted fee-for-service models that reward rapid ammonia normalization. This reimbursement evolution favors device-intensive protocols over pharmaceutical monotherapy in Tokyo and Osaka metropolitan hospital networks, with procurement committees now evaluating total cost-of-episode rather than per-unit acquisition costs.
Hepatic Insufficiency/Liver Failure Market Segmentation
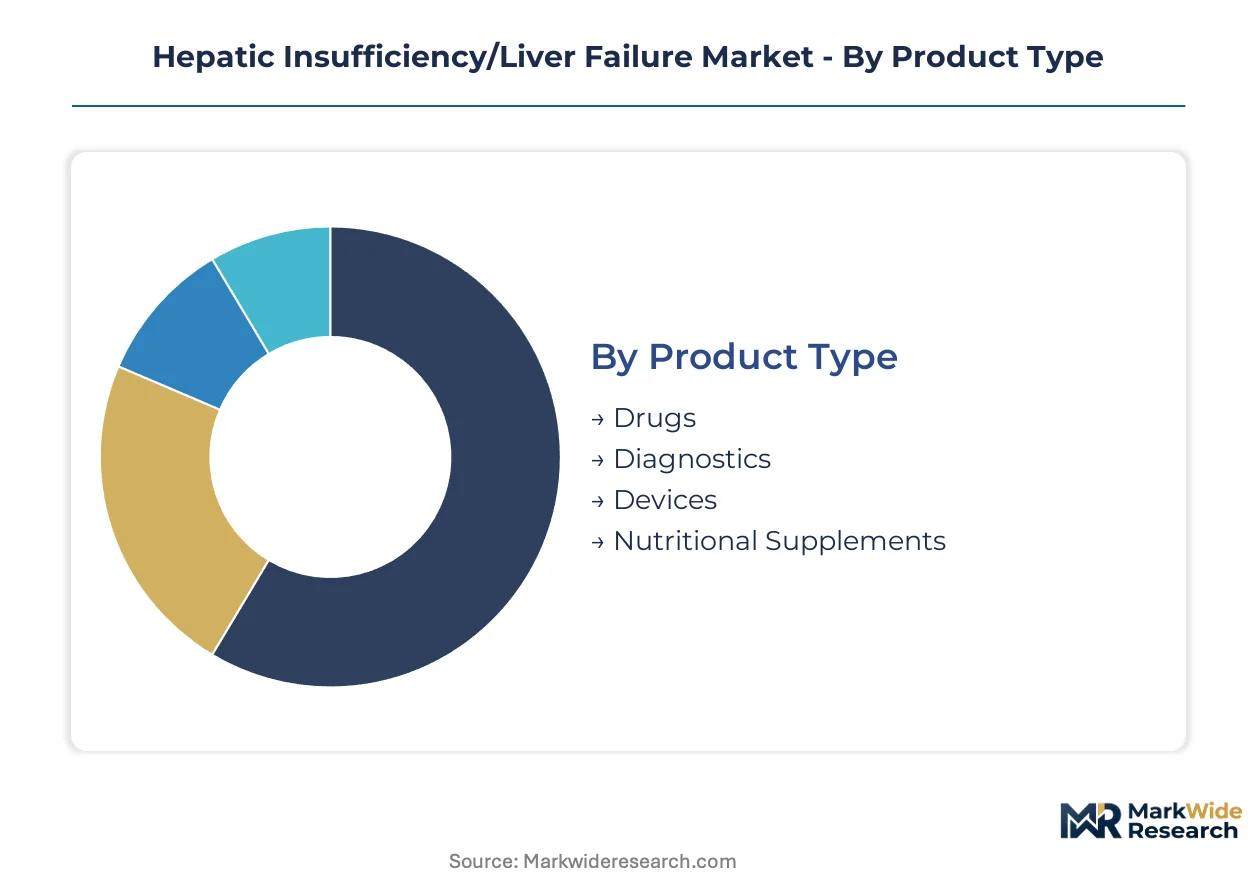
Segmentation in hepatic insufficiency reveals how clinical workflows fragment across acute intervention, chronic disease management, and monitoring infrastructure. Understanding these divisions exposes where procurement budgets concentrate and which delivery modalities command premium positioning.
Product Type:
Standalone pharmaceuticals and nutritional formulations operate independently of capital equipment, while diagnostics and devices require embedded integration into hospital infrastructure and electronic medical record systems.
- Drugs:Small-molecule therapeutics and biologics targeting ammonia clearance, coagulation restoration, and inflammation modulation. Demand concentrates in United States tertiary centers where FDA breakthrough designations accelerate formulary adoption for novel hepatic targets.
- Devices:Extracorporeal liver support systems including molecular adsorbent recirculating systems and albumin dialysis platforms. German university hospitals drive procurement of integrated diagnostic-therapeutic configurations that consolidate nursing labor and device footprints.
- Diagnostics:Fibrosis staging assays, ammonia monitoring systems, and imaging modalities for liver architecture assessment. Japanese hepatology centers in Tokyo and Osaka prioritize non-invasive elastography platforms for transplant referral triage.
- Nutritional Supplements:Branched-chain amino acid formulations and specialized enteral nutrition for sarcopenia prevention in cirrhosis patients. Homecare settings in Germany represent emerging demand for remote albumin tracking integration.
Drugs lead volumes today; devices are gaining share fastest.
Therapy Area:
Cost tier stratification separates chronic maintenance regimens from premium-priced acute interventions, with reimbursement authorities weighting total episode costs against per-unit acquisition economics.
- Cirrhosis:Chronic care protocols managing portal hypertension, ascites, and hepatic encephalopathy through pharmaceutical and nutritional intervention. Hospital systems in the United States and Germany allocate largest procurement budgets to decompensated cirrhosis management due to readmission penalty exposure.
- Acute Liver Failure:Intensive interventions including extracorporeal support and emergency transplantation evaluation. Japanese metropolitan hospitals command premium pricing for rapid ammonia normalization protocols under severity-adjusted fee-for-service reimbursement.
- Hepatitis:Antiviral therapy for hepatitis B and C with curative intent in select genotypes. European EMA adaptive pathways have compressed development timelines for next-generation direct-acting antiviral combinations.
- Drug-Induced Liver Injury:Supportive care and causality assessment for pharmaceutical, herbal, and toxin-mediated hepatic damage. Diagnostic laboratories in Germany specialize in standardized causality algorithm implementation for regulatory reporting.
Cirrhosis dominates revenue pools; acute liver failure commands steepest expansion trajectory.
End User:
Customer type determines purchasing authority structure, with hospitals retaining centralized procurement committees while homecare and laboratory segments fragment across regional distributors.
- Hospitals:Tertiary hepatology centers with captive referral networks and integrated transplant programs. United States hospital systems consolidate vendor relationships for liver support devices, compressing supplier margins while accelerating platform adoption.
- Diagnostic Laboratories:Centralized testing facilities for fibrosis biomarkers, ammonia levels, and coagulation profiles. German and French regulators coordinate real-world evidence collection standards for breakthrough-designated liver products tested in these settings.
- Clinics:Community gastroenterology practices managing stable cirrhosis and hepatitis monitoring. Japan's regional health disparities between metropolitan and rural prefectures constrain specialist access in clinic-based care.
- Homecare Settings:Post-acute monitoring and nutritional administration for compensated cirrhosis patients. Post-acute cirrhosis patients in Germany represent underpenetrated segment for remote albumin tracking and automated dietary intervention systems.
Hospitals retain dominant share; homecare settings are climbing the fastest.
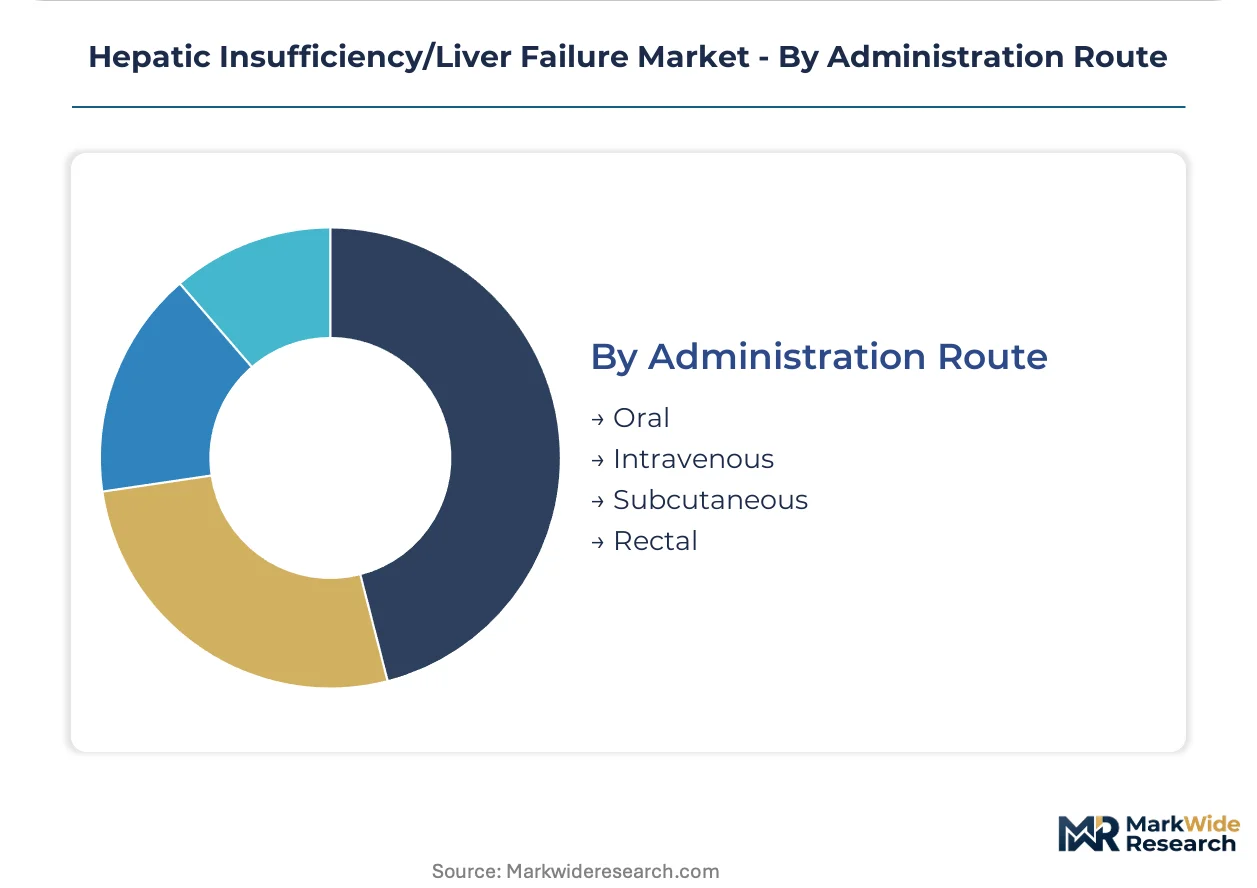
Administration Route:
Application context drives route selection, with acute inpatient care favoring intravenous delivery and outpatient chronic management shifting toward patient-administered alternatives.
- Intravenous:Rapid ammonia clearance agents, coagulation factor concentrates, and emergency nutritional support. Intensive care units in German tertiary centers standardize intravenous protocols for hepatic encephalopathy grade III-IV.
- Oral:Chronic diuretics, beta-blockers for portal hypertension, and maintenance nutritional supplementation. Outpatient cirrhosis management in United States health systems prioritizes oral regimens to reduce infusion center utilization.
- Subcutaneous:Interferon-based therapies and select biologics for autoimmune hepatic conditions. Japanese PMDA review pathways influence subcutaneous formulation development timelines for domestic manufacturers.
- Rectal:Lactulose and select antimicrobial agents for hepatic encephalopathy when oral intake is contraindicated. Emergency departments in United States and German hospitals maintain rectal formulation stock for encephalopathy grade II-III.
Intravenous leads volumes today; oral formulations are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized hepatology workforce concentrations in the United States, Germany, and Japan anchor regional demand for advanced liver support technologies and transplant infrastructure.
United States
Tertiary hepatology centers in Houston and Pittsburgh drive procurement of integrated diagnostic-therapeutic platforms for acute liver failure management. FDA breakthrough therapy designations compress development timelines for novel hepatic targets, accelerating formulary adoption at major hospital systems. The Texas Medical Center cluster maintains the highest transplant volume globally, creating concentrated demand for molecular adsorbent recirculating systems.
Germany
University hospitals in Berlin and Munich standardize extracorporeal liver support protocols for hepatic encephalopathy grade III-IV patients. EMA adaptive pathways enable conditional marketing authorization for regenerative hepatic therapies based on surrogate biomarker endpoints. The Munich metropolitan hospital network coordinates real-world evidence collection standards with French regulators, creating a template for EU member state adoption.
Japan
METI-funded specialized liver units in Tokyo and Osaka drive demand for albumin replacement systems and ammonia clearance biotechnology. PMDA review pathways influence subcutaneous formulation development timelines for domestic manufacturers. Osaka's emergency departments command premium pricing for rapid ammonia normalization protocols under severity-adjusted fee-for-service reimbursement models.
United Kingdom
London hepatology centers prioritize non-invasive elastography platforms for transplant referral triage, compressing diagnostic timelines through AI-assisted fibrosis staging. MHRA alignment with EMA guidance documents streamlines multi-registrational study designs for acute liver failure trials. The Cambridge-Oxford corridor attracts venture investment for enzymatic hyperammonemia management approaches.
France
Parisian hospital groups unbundle acute liver failure interventions from bundled diagnosis-related group payments, shifting toward severity-adjusted reimbursement. ANSM coordination with German regulators on real-world evidence standards creates parallel European access routes for breakthrough-designated liver products. Lyon-based diagnostic laboratories specialize in standardized causality algorithm implementation for drug-induced liver injury regulatory reporting.
Hepatic Insufficiency/Liver Failure Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across the hepatic insufficiency landscape, creating a tiered structure where scale-driven pharmaceutical portfolios intersect with device-intensive platform developers. Large-cap diversified players leverage antiviral and immunology asset breadth to sustain formulary positioning, while mid-cap specialists concentrate regulatory capabilities for EU MDR compliance. Three archetypes dominate: portfolio conglomerates with hepatology-adjacent assets, pure-play device manufacturers scaling GMP-compliant bioreactor production, and diagnostic platform vendors achieving CE marking under AI Act conformity routes. Competitive moves center on hospital vendor consolidation for liver support devices and strategic partnerships to secure human hepatocyte supply networks.
Within the portfolio conglomerate tier, Gilead Sciences, Inc. and Bristol Myers Squibb exemplify diversified players anchoring market positioning through antiviral dominance and immunology assets respectively. AbbVie Inc. occupies a specialist position within this tier, differentiating via hepatology-focused R&D pipelines. These three companies collectively represent how pharmaceutical breadth intersects with targeted hepatic therapeutic development, with each anchoring distinct strategic approaches to fibrosis progression and autoimmune-driven complications.
| Leading Market Players |
|---|
| Gilead Sciences, Inc. |
| AbbVie Inc. |
| Bristol Myers Squibb |
| Novartis AG |
| Pfizer Inc. |
| F. Hoffmann-La Roche Ltd. |
| Johnson & Johnson Services, Inc. |
| Abbott Laboratories |
| Merck & Co., Inc. |
| Others |
Cost & Logistics Intelligence
Hospital procurement committees in the United States, Germany, and Japan command pricing leverage through consolidated vendor relationships for liver support devices, shifting negotiations toward total cost-of-episode models rather than per-unit acquisition economics. This buyer concentration forces suppliers to bundle device placement with consumable contracts and service agreements.
Pricing Analysis
Bundled diagnosis-related group payments dominate European acute liver failure interventions while unbundled severity-adjusted fee-for-service models prevail in Japanese metropolitan hospitals. Price differentiation hinges on FDA breakthrough designation status and EU MDR certification tier, with premium tiers capturing conditional marketing authorization products. Cost compression in standard device categories intensifies as German university hospitals consolidate supplier rosters. Homecare nutritional supplement segments exhibit highest price sensitivity due to limited reimbursement coverage.
Supply Chain Analysis
Regional distribution centers in Frankfurt and Tokyo coordinate hub-and-spoke patterns for molecular adsorbent recirculating systems and albumin dialysis platforms. Manufacturing concentrates in the United States, Germany, and Switzerland for GMP-compliant bioreactor production. Raw material dependencies include human hepatocyte sourcing from US and European tissue banks, plasma fractionation feedstock, and specialized membrane filtration components. Single-source vulnerability in primary cell supply creates batch variability risks. Distribution runs through hospital procurement consortia and specialized hepatology equipment distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where FDA breakthrough therapy designations and EMA adaptive pathways accelerate product development timelines and reshape competitive access. The EU AI Act introduces additional compliance layers for diagnostic algorithms.
For Market Incumbents: Deploy GMP-compliant bioreactor capacity additions in Germany to secure human hepatocyte supply networks against emerging pure-play specialists. Consolidate hospital vendor relationships through integrated diagnostic-therapeutic platform offerings that compress nursing labor requirements. Anchor formulary positioning by accelerating FDA submissions for novel hepatic targets before adaptive pathway competitors achieve conditional European authorization. For New Entrants and Emerging Players: EU MDR breakthrough pathway in Germany opens a window for enzymatic hyperammonemia management approaches with surrogate biomarker endpoints. Target post-acute cirrhosis patients in German homecare settings for remote albumin tracking systems. Pursue telehepatology referral network partnerships in Japan's rural prefectures to bypass traditional hospital gatekeeping structures. For Investors and Strategic Acquirers: Diversified pharmaceutical conglomerates with hepatology-adjacent antiviral portfolios are the most active acquirers in this space. Long-term viability rests on regulatory navigation capabilities across FDA, EMA, and PMDA frameworks rather than single-jurisdiction approvals. Monitor CE marking progress under EU AI Act conformity assessment routes for diagnostic algorithm vendors as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| EMA Adaptive Pathway Submission | Conditional marketing authorization compresses time-to-reimbursement for fibrosis progression therapies in Germany. |
| Hospital System Partnership | Texas Medical Center cluster procurement consolidates molecular adsorbent recirculating system vendor relationships. |
| CE Marking Pathway | EU AI Act risk-classification framework creates first-mover advantages for AI-assisted fibrosis staging algorithms. |
| Reimbursement Strategy | Japanese severity-adjusted fee-for-service models reward rapid ammonia normalization protocols in Osaka emergency departments. |
| Manufacturing Scale-Up | GMP-compliant cleanroom infrastructure for three-dimensional hepatocyte culture exceeds mid-cap developer balance sheet capacity. |
Research Approach
Direct dialogue with hepatology center directors, hospital procurement managers, regulatory affairs leads at device manufacturers, and GPO contracts specialists grounded qualitative findings. Secondary validation drew from FDA 510(k) filings, EMA adaptive pathway submissions, ClinicalTrials.gov hepatic insufficiency protocols, and hospital procurement databases. Bottom-up patient population estimates triangulated against top-down therapy area spending benchmarks.
Segmented outputs across the projection horizon reflect modeling by therapy area, product type, end user, and administration route dimensions. CAGRs derived from regression analysis against historical adoption curves for breakthrough-designated hepatic therapeutics. Forecast inputs incorporated EU MDR implementation timelines, Japanese METI hepatology center expansion schedules, and plasma fractionation capacity constraints.
Revisions become necessary when FDA IND timeline friction extends cell-based liver support device development phases, or when cross-border clinical data harmonization failures complicate multi-registrational study designs. Forecasts reflect assumptions about reimbursement authority weighting of clinical outcomes against total cost-of-care. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Cervical Dystonia Market
Specialty Medicine
Global Autism Spectrum Disorders Market
Specialty Medicine
Microcephaly Market
Specialty Medicine
Diffuse Large B-Cell Lymphoma Therapeutics Market
Specialty Medicine
Global Spinal Muscular Atrophy Treatment Market
Specialty Medicine
Fibrodysplasia Ossificans Progressiva (FOP) Treatment Market
Specialty Medicine
Phenylketonuria Therapeutics Market
Specialty Medicine
Tinnitus Management Market
Specialty Medicine
Primary Sclerosing Cholangitis (PSC) Market
Specialty Medicine
Vesicoureteral Reflux Market
Specialty Medicine
Breakthrough Therapy Designation Market
Specialty Medicine
Cerebral Vasospasm Market
Specialty Medicine
Sjogrens Syndrome Market
Specialty Medicine
Axial Spondyloarthritis Treatment Market
Specialty Medicine
Systemic Lupus Erythematosus (SLE) Market
Specialty Medicine
Whim Syndrome Management Market