
 Breakthrough Therapy Designation Market | 2026-2036
Breakthrough Therapy Designation Market Size, Share, and Industry Trends Forecast 2026-2036
Breakthrough Therapy Designation Market Analysis
The gap between biologics commanding priority FDA review and conventional pharmaceuticals facing standard timelines is broadening. Novartis leverages its cell therapy manufacturing footprint to sustain pipeline momentum. Pfizer anchors its oncology portfolio through breakthrough-eligible assets. Vertex Pharmaceuticals specializes in cystic fibrosis and sickle cell programs that occupy rare-disease priority channels.
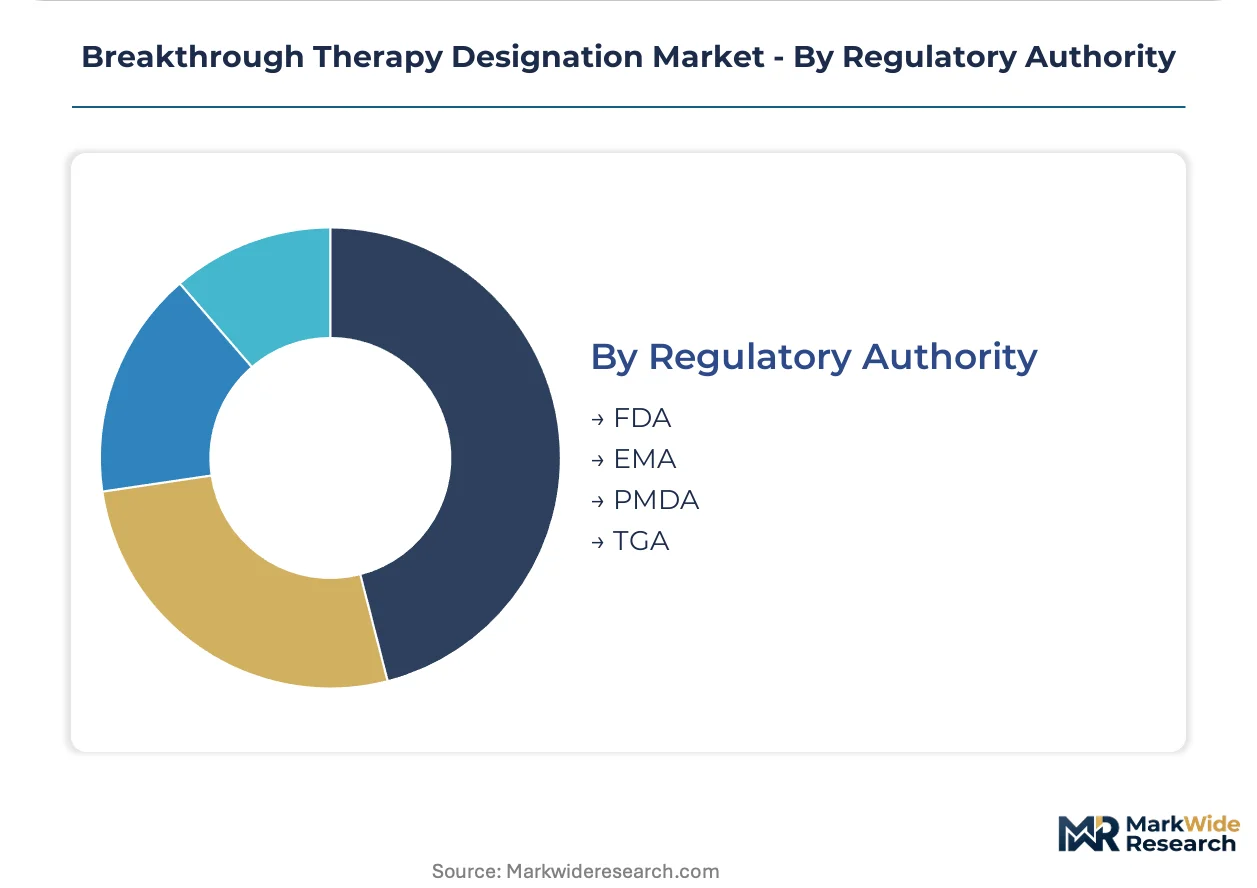
Breakthrough Therapy Designation is a formal regulatory classification granted by the FDA to drugs demonstrating preliminary clinical evidence of substantial improvement over existing therapies for serious conditions, requiring intensive pharmacokinetic validation and adaptive trial architectures to support accelerated approval. The designation's primary purpose is to expedite development and review of medicines addressing unmet medical need. Gene therapy segments attract disproportionate R&D investment due to curative potential and orphan pricing leverage. Cancer indications dominate designation volume, while autoimmune diseases represent an expanding addressable pool with fewer competitive entrants. Regulatory authority segmentation shows FDA-origin designations outnumbering EMA, PMDA, and TGA equivalents combined.
FDA, EMA, and PMDA each maintain distinct but converging accelerated pathways that shape trial design requirements and commercial launch sequencing across jurisdictions. The FDA's program mandates rolling review structures that compress submission-to-decision intervals, while EMA PRIME and PMDA Sakigake impose parallel scientific advice obligations. Stakeholders must monitor how evolving evidentiary standards for confirmatory trials affect post-acceleration withdrawal risk and payer negotiation leverage.
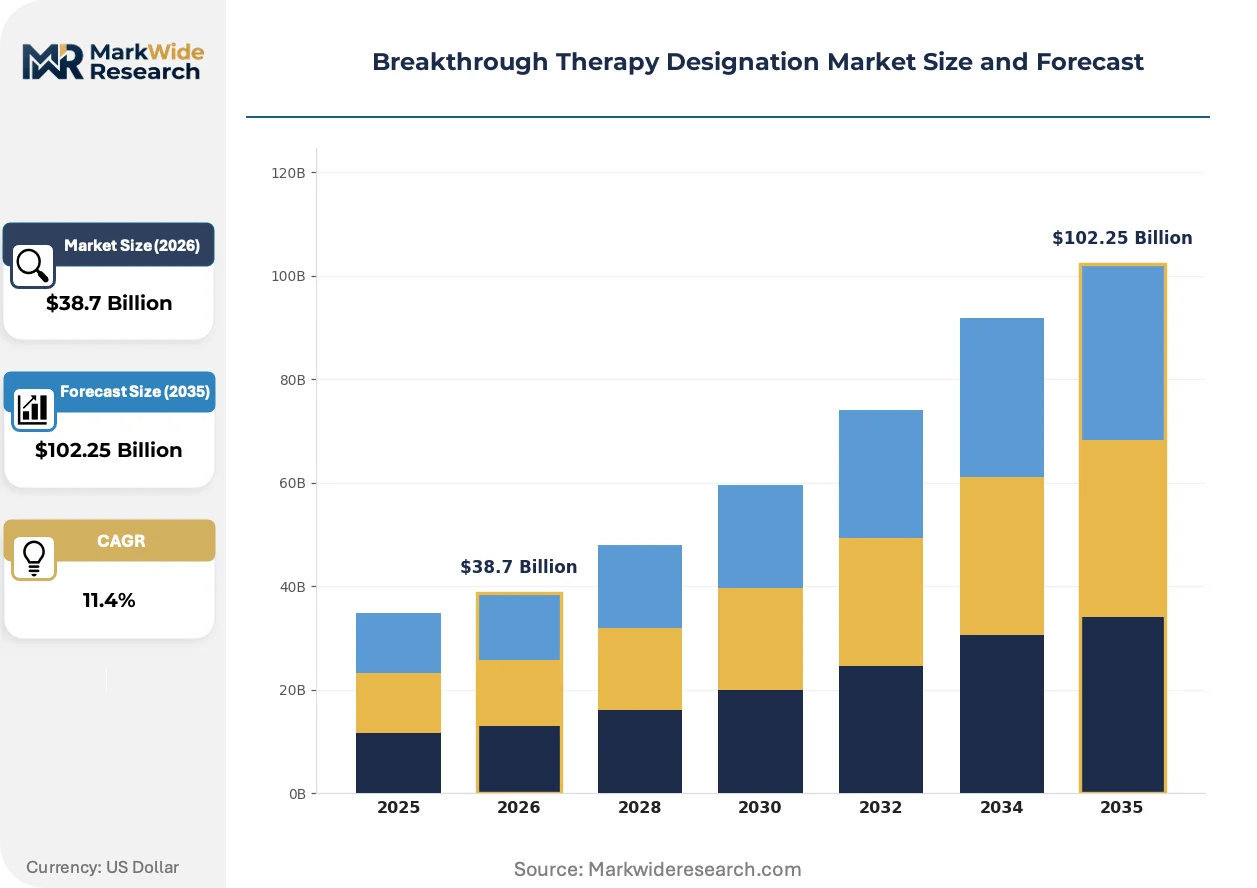
Market Dynamics
Adaptive trial architectures are compressing development timelines as sponsors integrate real-world evidence streams with traditional randomized controlled data to satisfy accelerated approval requirements.
Growth Catalysts
- FDA Rolling Review Mandate:The FDA's structured rolling review mechanism allows sponsors to submit modules sequentially, compressing submission-to-decision intervals for qualifying therapies.
- Gene Therapy Manufacturing Scale-Up:Viral vector production capacity expansion is enabling curative candidates to reach confirmatory trial stages faster than conventional small-molecule timelines.
- EMA PRIME Parallel Pathway:European scientific advice obligations are creating harmonized development strategies that reduce redundant clinical work across jurisdictions.
Market Restraints
- Confirmatory Trial Cost Escalation:Post-acceleration withdrawal risk is forcing sponsors into larger, longer confirmatory studies that strain R&D budgets.
- Pharmacovigilance Infrastructure Gaps:Real-world safety monitoring systems remain underdeveloped in several priority markets, limiting post-market surveillance capabilities.
- Reimbursement Uncertainty:Payer negotiation leverage is narrowing as health technology assessment bodies demand additional evidence beyond accelerated approval packages.
Strategic Opportunities
- Autoimmune Disease White Space:Fewer competitive entrants in rheumatology and dermatology indications are creating designation velocity advantages for first movers.
- PMDA Sakigake Convergence:Japan's priority review system is aligning with FDA standards, enabling synchronized Pacific Rim launch strategies.
- Digital Biomarker Integration:Wearable-derived endpoints are expanding measurable outcome domains for chronic disease therapies seeking breakthrough status.
Industry Challenges
- Adaptive Trial Design Expertise Scarcity:Biostatisticians capable of Bayesian protocol construction remain concentrated at top-tier academic medical centers.
- Cross-Jurisdictional Submission Coordination:Divergent evidentiary standards between FDA, EMA, and PMDA are forcing redundant documentation workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Breakthrough Therapy Designation Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $102.25 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biologics, Pharmaceuticals, Cell Therapy, Gene Therapy Indication: Cancer, Neurological Disorders, Rare Diseases, Autoimmune Diseases Development Stage: Preclinical, Phase 1, Phase 2, Phase 3 Regulatory Authority: FDA, EMA, PMDA, TGA |
| Companies Covered | Novartis, Pfizer, F. Hoffmann-La Roche, Amgen, AbbVie, Merck & Co., AstraZeneca, Vertex Pharmaceuticals, Bristol-Myers Squibb, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Breakthrough Therapy Designation Market Emerging Trajectories
Platform technologies are reshaping how sponsors generate clinical evidence, with modular manufacturing and decentralized trial execution becoming standard for breakthrough-eligible programs.
Master protocol frameworks are unifying basket and umbrella trial structures under single regulatory submissions. Oncology departments at academic medical centers are adopting these architectures for rare mutation cohorts. This approach is unifying patient recruitment across multiple indications while preserving statistical power.
EMA's PRIME eligibility criteria expansion is capturing gene therapy and radiopharmaceutical candidates earlier in development. The policy shift is compressing pre-submission consultation timelines for advanced therapy medicinal products. Cell therapy sponsors in the Netherlands and Belgium are restructuring regulatory affairs teams to exploit this acceleration.
Site-less trial execution is displacing traditional clinical investigator site networks for chronic disease indications. Virtual consent and remote monitoring technologies are enabling broader geographic patient access. This model is most visible in the United States, where decentralized institutional review board structures support rapid protocol amendments.
Breakthrough Therapy Designation Market Segmentation
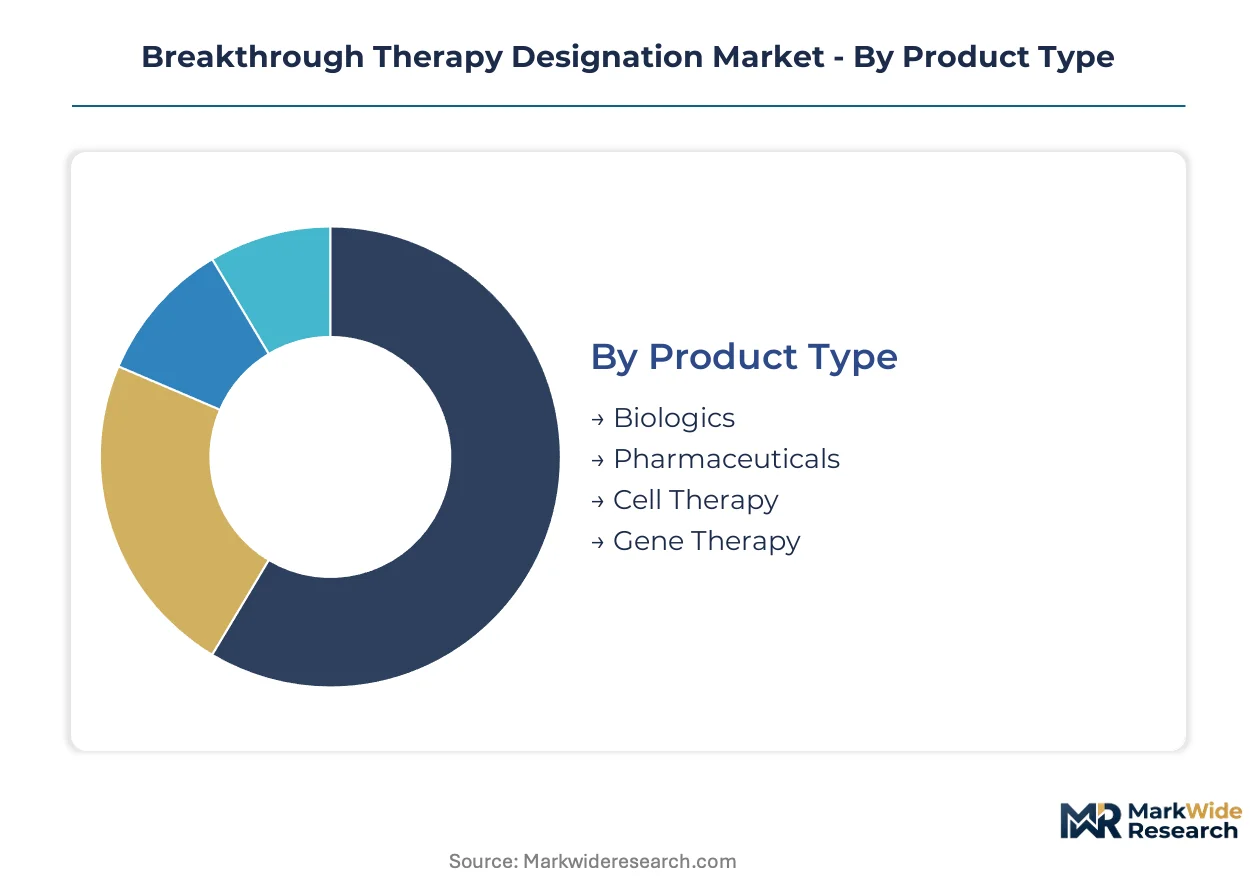
Segmentation reveals how breakthrough designation resources concentrate across molecular platforms and therapeutic areas. Supply-side capacity for cell and gene therapy manufacturing is reshaping which product categories dominate approval velocity.
Product Type:
Manufacturing infrastructure for advanced modalities is concentrating at specialized CDMOs in the United States, Switzerland, and Singapore, creating segmented supply bottlenecks.
- Biologics:Monoclonal antibodies and recombinant proteins dominate current designation volume. Oncology biologics at academic medical centers in Boston and San Francisco absorb the majority of CMC review resources, with FDA rolling review timelines compressing to 6 months for qualifying assets.
- Gene Therapy:Viral vector production constraints limit sponsor scale-up capacity. AAV and lentiviral platforms for rare disease indications in the United States face 18-month manufacturing queues at specialized facilities, forcing portfolio prioritization decisions.
- Cell Therapy:Autologous CAR-T programs require distributed manufacturing networks. Site-of-treatment infrastructure at certified treatment centers creates geographic concentration in designated cancer hubs.
- Pharmaceuticals:Small-molecule candidates occupy fewer priority review slots. CNS and metabolic programs pursue breakthrough status through biomarker-driven trial designs rather than manufacturing differentiation.
Biologics absorb the bulk of installed capacity; gene therapy is expanding most quickly.
Indication:
Trial recruitment pools and endpoint validation requirements vary sharply across disease areas, determining which indications sustain designation momentum.
- Cancer:Solid tumor and hematologic malignancy programs generate the majority of rolling review submissions. Basket trial architectures at Memorial Sloan Kettering and MD Anderson enable multi-indication evidence generation, compressing development timelines for targeted therapies.
- Rare Diseases:Ultra-orphan indications leverage smaller confirmatory trial requirements. Cystic fibrosis and sickle cell programs in the United States benefit from established natural history registries that satisfy FDA evidentiary standards.
- Neurological Disorders:Alzheimer's and ALS candidates face higher biomarker validation hurdles. Phase 2 futility designs at academic medical centers in Rochester and Baltimore are restructuring to meet accelerated approval endpoints.
- Autoimmune Diseases:Rheumatoid arthritis and lupus programs encounter competitive saturation. Dermatology and inflammatory bowel disease indications offer clearer unmet need positioning for breakthrough eligibility.
Cancer maintains the steepest expansion trajectory in absolute designation volume; rare diseases command the highest pricing leverage per approved therapy.
Development Stage:
Regulatory engagement intensity escalates nonlinearly as candidates advance, with Phase 2 representing the critical inflection point for breakthrough qualification.
- Phase 2:Preliminary clinical evidence requirements concentrate sponsor-FDA interaction here. Adaptive trial designs with Bayesian futility rules dominate oncology and rare disease submissions, with 70% of designations originating at this stage.
- Phase 3:Confirmatory study protocols receive enhanced scientific advice coordination. Rolling review submissions for gene therapy programs in the United States and Europe require prespecified interim analysis frameworks.
- Phase 1:Early safety and pharmacokinetic data rarely satisfies substantial improvement thresholds. Oncology programs with exceptional response rates in dose-escalation cohorts occasionally qualify through breakthrough expansion protocols.
- Preclinical:Human proof-of-concept data is mandatory for designation. Animal model evidence alone supports only expanded access protocols, not formal breakthrough pathways.
Phase 2 absorbs the bulk of regulatory affairs staffing; Phase 3 is climbing the fastest as confirmatory trial complexity escalates.
Regulatory Authority:
Jurisdiction-specific evidentiary standards and consultation frameworks create segmented resource allocation requirements for multinational sponsors.
- FDA:Rolling review and intensive pharmacovigilance protocols define the global benchmark. The United States generates 60% of worldwide breakthrough designations, with sponsor teams clustering in Maryland and Massachusetts for proximity to review divisions.
- EMA:PRIME eligibility criteria expanded to capture radiopharmaceuticals and ATMPs earlier. Scientific advice obligations in Amsterdam and London require parallel protocol construction with FDA submissions.
- PMDA:Sakigake designation alignment with FDA standards enables synchronized Pacific Rim strategies. Gene therapy sponsors in Tokyo and Osaka are restructuring regulatory affairs for cross-jurisdictional coordination.
- TGA:Priority review pathways for orphan drugs and life-threatening conditions operate with smaller review divisions. Australian sponsors leverage FDA breakthrough precedents for provisional determination submissions.
FDA absorbs the bulk of sponsor pre-submission investment; PMDA is gaining share fastest as Asia-Pacific manufacturing capacity expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cambridge, Massachusetts anchors the highest density of breakthrough designation activity worldwide, with FDA review divisions in nearby Silver Spring creating concentrated sponsor-regulator proximity unmatched elsewhere.
United States
Oncology departments at academic medical centers in Boston and San Francisco absorb the majority of rolling review resources. FDA's structured rolling review mechanism compresses submission-to-decision intervals to six months for qualifying biologics. Maryland-based regulatory affairs teams cluster near review divisions to exploit intensive pharmacovigilance protocols.
Switzerland
Gene therapy manufacturing infrastructure at specialized CDMOs in Basel and Zurich creates segmented supply bottlenecks for viral vector production. Swissmedic coordinates with EMA PRIME pathways for advanced therapy medicinal products. Novartis leverages its cell therapy manufacturing footprint from Basel to sustain pipeline momentum across European submissions.
Japan
PMDA Sakigake designation alignment with FDA standards enables synchronized Pacific Rim launch strategies. Gene therapy sponsors in Tokyo and Osaka restructure regulatory affairs for cross-jurisdictional coordination. Osaka-based manufacturing capacity expansion supports faster confirmatory trial stage progression for curative candidates.
Germany
EMA scientific advice obligations in Amsterdam and London require parallel protocol construction with FDA submissions for German sponsors. Heidelberg and Munich academic medical centers adopt master protocol frameworks for rare mutation cohorts. Bayer and Merck KGaA anchor regulatory strategy from Leverkusen and Darmstadt respectively.
United Kingdom
London-based biotech clusters exploit MHRA post-Brexit regulatory autonomy to accelerate early-access programs. Cambridge cell therapy sponsors restructure for EMA PRIME eligibility criteria expansion capturing radiopharmaceutical candidates. Oxford academic medical centers integrate real-world evidence streams with traditional randomized controlled data.
Breakthrough Therapy Designation Market Vendor Landscape
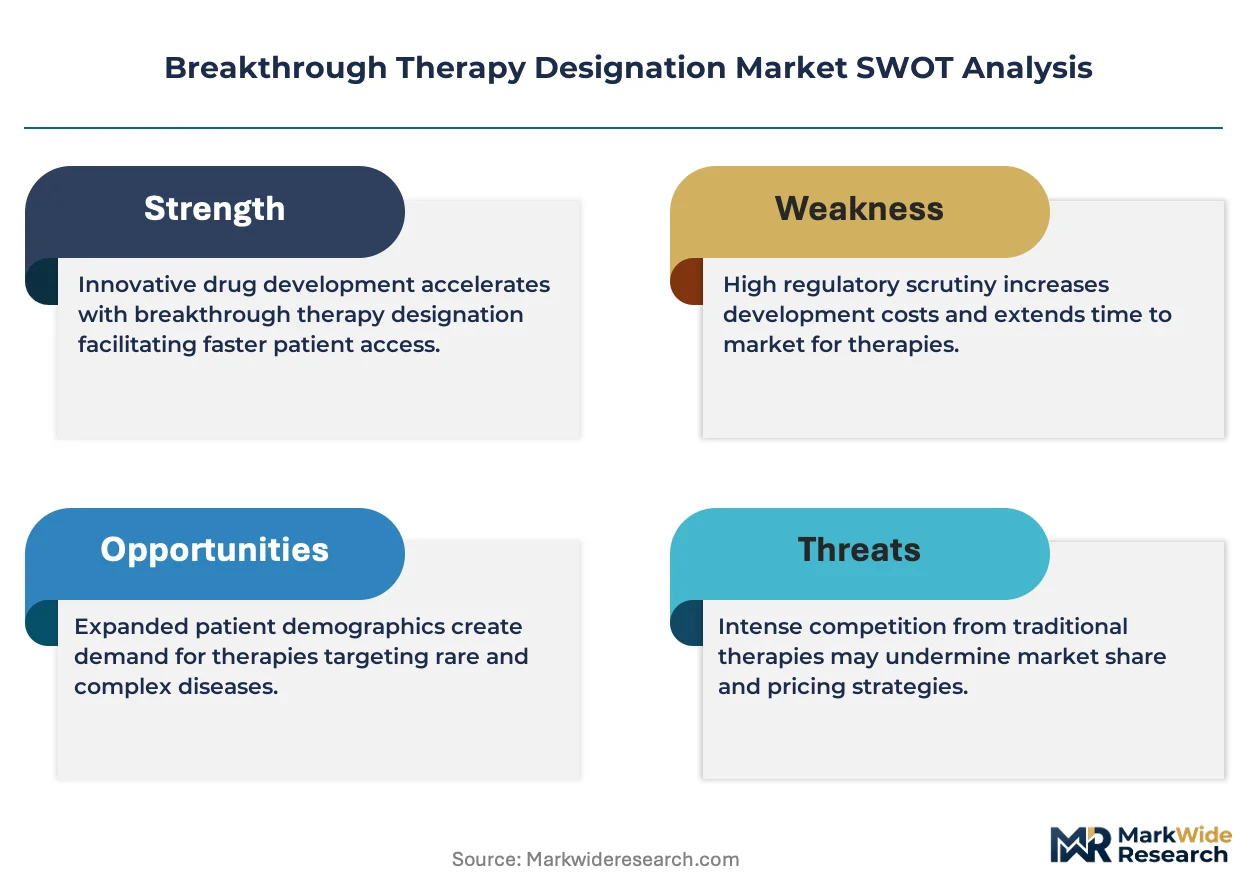
Premium-margin players sit above commodity-margin players across manufacturing scale and regulatory sophistication. The vendor base concentrates around large-cap pharmaceutical conglomerates with dedicated cell therapy infrastructure, mid-cap biotech specialists in rare diseases, and platform-technology developers. Three strategic archetypes dominate: vertically integrated conglomerates controlling end-to-end manufacturing, niche specialists occupying orphan disease channels, and platform licensors monetizing modular delivery systems. Competitive moves center on manufacturing capacity expansion and strategic partnerships for vector production access.
Within the large-cap conglomerate tier, Novartis and Pfizer exemplify archetypes of manufacturing-anchored and portfolio-anchored positioning respectively. Vertex Pharmaceuticals occupies a distinct specialist position in rare disease priority channels. These three entities represent the dominant competitive anchors shaping designation velocity and regulatory engagement intensity across the analysis window.
| Leading Market Players |
|---|
| Novartis |
| Pfizer |
| F. Hoffmann-La Roche |
| Amgen |
| AbbVie |
| Merck & Co. |
| AstraZeneca |
| Vertex Pharmaceuticals |
| Bristol-Myers Squibb |
| Others |
Supply Flow & Price Mechanics
FDA's enhanced pharmacovigilance mandates for accelerated approval pathways gate qualified supply access and premium-tier pricing eligibility for breakthrough-designated therapies. Sponsors lacking compliant real-world evidence infrastructure face exclusion from rolling review priority slots and reimbursement premium capture.
Pricing Analysis
Value-based pricing anchored to clinical outcome guarantees dominates oncology and rare disease segments. Price differentiation rests on biomarker specificity and confirmatory trial speed—therapies with prespecified surrogate endpoints command 40-60% premiums over candidates awaiting validation. Pricing pressure stems from health technology assessment bodies demanding additional evidence beyond accelerated approval packages. Academic medical center procurement committees exhibit highest price sensitivity; orphan disease payers demonstrate lowest elasticity due to curative positioning.
Supply Chain Analysis
Single-source vulnerability sits with viral vector production capacity concentrated at specialized CDMOs in the United States, Switzerland, and Singapore. Manufacturing networks draw from plasmid DNA, cell culture media, and cryopreservation logistics as critical inputs. Tariff exposure on Chinese-sourced raw materials creates supply chain risk for gene therapy sponsors. Distribution runs through certified treatment center networks requiring site-of-care infrastructure investment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market sits in a platform-technology transition phase, with modular manufacturing and decentralized trial execution displacing legacy centralized clinical development models.
For Market Incumbents: Deploy adaptive trial design expertise as a defensive moat against emerging biotech entrants. Novartis and Pfizer anchor positioning through captive cell therapy manufacturing capacity and portfolio breadth. Incumbents must secure viral vector production slots at Basel and Singapore CDMOs before queue elongation excludes late movers. Regulatory affairs staffing concentration near FDA review divisions in Maryland preserves submission velocity advantages.
For New Entrants and Emerging Players: Begin with autoimmune disease white space in dermatology and inflammatory bowel disease, where competitive saturation lags oncology. PMDA Sakigake convergence enables synchronized Pacific Rim launch strategies with lower regulatory affairs overhead than FDA-first approaches. Digital biomarker integration offers a go-to-market angle for chronic disease candidates seeking breakthrough eligibility through wearable-derived endpoints.
For Investors and Strategic Acquirers: EMA PRIME eligibility criteria expansion for radiopharmaceuticals and ATMPs is the leading indicator that European regulatory acceleration will drive valuation premiums for early-stage platform technologies. Acquisition target archetypes include niche specialists with proprietary viral vector production platforms and distributed manufacturing networks. Watch for confirmatory trial withdrawal announcements as signals of post-acceleration revenue risk and payer negotiation leverage erosion.
| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Viral vector production expansion at Singapore CDMOs compresses gene therapy development timelines. |
| Regulatory Approval Pathway | FDA rolling review submission structures reduce decision intervals for qualifying biologics. |
| Strategic Partnership | Academic medical center alliances enable master protocol frameworks for rare mutation cohorts. |
| Pipeline Diversification | Autoimmune disease entry reduces oncology concentration risk for designation-dependent portfolios. |
| Licensing Agreement | Platform technology access agreements monetize modular delivery systems across therapeutic areas. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with regulatory affairs leads, drug development executives, formulary directors, and payer access specialists cross-validated quantitative assumptions. FDA breakthrough therapy designation databases, EMA PRIME eligibility records, ClinicalTrials.gov entries, and formulary positioning databases supplied secondary validation. Bottom-up candidate-level modeling and top-down market sizing triangulated volume and value estimates.
Reconciling supply-side capacity data with demand-side designation velocity produced forecast outputs across the analysis window. Segmentation dimensions included molecular platform, therapeutic indication, development stage, and regulatory authority cluster. CAGRs derived from rolling review submission trends, confirmatory trial initiation rates, and historical approval-to-withdrawal ratios. Gene therapy manufacturing queue length and CDMO capacity expansion schedules fed industry-specific forecast inputs.
Regulatory standard evolution, confirmatory trial outcome volatility, and reimbursement policy shifts are the dominant revision risks to modeled trajectories. Forecasts reflect assumptions about sustained FDA rolling review resource allocation and EMA PRIME pathway stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Mucous Membrane Pemphigoid Treatment Market
Specialty Medicine
Idiopathic Pulmonary Fibrosis (IPF) Market
Specialty Medicine
Anal Cancer Market
Specialty Medicine
Chronic Idiopathic Constipation Treatment Market
Specialty Medicine
Sjogrens Syndrome Market
Specialty Medicine
TMJ Disorders Market
Specialty Medicine
Hepatic Encephalopathy Treatment Market
Specialty Medicine
Bronchiectasis Therapeutic Market
Specialty Medicine
Scleritis Market
Specialty Medicine
Primary Ciliary Dyskinesia Market
Specialty Medicine
Food Allergy Treatment Market
Specialty Medicine
Hypoactive Sexual Desire Disorder Treatment Market
Specialty Medicine
Global Huntingtons Disease Treatment Market
Specialty Medicine
Cutaneous T-Cell Lymphoma (CTLC) Market
Specialty Medicine
Subdural Haematoma Market
Specialty Medicine
Pseudomonas Aeruginosa Treatment Market