
 Sjogrens Syndrome Market | 2026-2036
Sjogrens Syndrome Market Size, Share, and Industry Trends Forecast 2026-2036
Sjogrens Syndrome Market Outlook
Biologics is rebalancing treatment economics away from conventional immunosuppressants by delivering superior efficacy in glandular function preservation. AbbVie Inc. leverages its immunology platform to sustain dominance in TNF-alpha and interleukin-targeted pipelines. Novartis AG anchors its position through deep specialization in B-cell modulation pathways. Bristol Myers Squibb Co. competes via integrated autoimmune R&D spanning oral small molecules and monoclonal antibodies.
Sjogren's syndrome constitutes a systemic autoimmune disorder characterized by lymphocytic infiltration of exocrine glands, principally salivary and lacrimal tissues, resulting in sicca symptoms and extraglandular manifestations ranging from interstitial lung disease to non-Hodgkin lymphoma; its primary commercial purpose centers on preserving quality of life and preventing organ-threatening complications through chronic immunomodulation. Biologics commands the highest margin pool among product types due to premium pricing and unmet need in refractory cases, while injectable delivery modes capture growing share as subcutaneous formulations reduce hospital dependency. Disease modifying treatment stages represent the fastest-expanding segment as payers shift reimbursement toward therapies demonstrating measurable glandular function improvement.
FDA accelerated approval pathways and EMA conditional marketing authorization frameworks shape demand by compressing development timelines for novel biologics targeting type I interferon pathways and BAFF signaling. The EU AI Act and GDPR impose data governance requirements on digital biomarker platforms used in decentralized Sjogren's trials, raising compliance costs for sponsors deploying remote salivary flow monitoring. Stakeholders must monitor evolving payer evidence requirements linking objective glandular measures to patient-reported outcomes as gatekeeping mechanisms for premium access expand across Medicare and national health technology assessment bodies.
Market Dynamics
FDA accelerated approval pathways compress development timelines for type I interferon and BAFF-targeting biologics, forcing sponsors to redesign evidence generation around objective glandular function endpoints.
Growth Catalysts
- Accelerated Approval Pathways:FDA's streamlined frameworks for autoimmune indications reduce phase III duration requirements. Sponsors now design registrational trials around salivary flow biomarkers.
- Biologic Manufacturing Scale-Up:Contract development organizations in Massachusetts and North Carolina expand GMP capacity for monoclonal antibody production. This infrastructure supports pipeline candidates entering pivotal trials.
- Specialist Care Infrastructure:Hospital-based rheumatology departments in the United States deepen adoption of targeted immunomodulation. Academic medical centers establish dedicated Sjogren's clinics with integrated diagnostic protocols.
Market Restraints
- Plasma Fractionation Concentration:Immunoglobulin feedstock supply concentrates among four global collectors. This input bottleneck constrains capacity expansion for IVIG-dependent refractory cases.
- EMA Conditional Marketing Friction:European confirmatory trial requirements create post-approval uncertainty. Sponsors face reimbursement risk if surrogate endpoints fail conversion.
- Small Molecule Substitution:JAK inhibitors in competing autoimmune indications threaten biologic pricing power. Payers apply cross-disease reference pricing pressure.
Strategic Opportunities
- Decentralized Trial Infrastructure:Remote salivary flow monitoring platforms enable patient recruitment beyond academic centers. This channel innovation reduces site dependency.
- EU AI Act Compliance Services:Data governance requirements for digital biomarkers create vendor opportunity. Specialized CROs package GDPR-validated remote monitoring.
- Japan's Rare Disease Framework:PMDA's sakigake designation offers priority review for novel mechanisms. Early entrants secure pricing premiums in this underpenetrated market.
Industry Challenges
- Interferon Signature Assay Standardization:Biomarker heterogeneity across diagnostic platforms complicates patient stratification. FDA has issued no qualified biomarker guidance.
- Glandular Function Endpoint Validation:Schirmer test and unstimulated salivary flow lack harmonization. Regulators demand patient-reported outcome linkage that trials struggle to demonstrate.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sjogrens Syndrome Market |
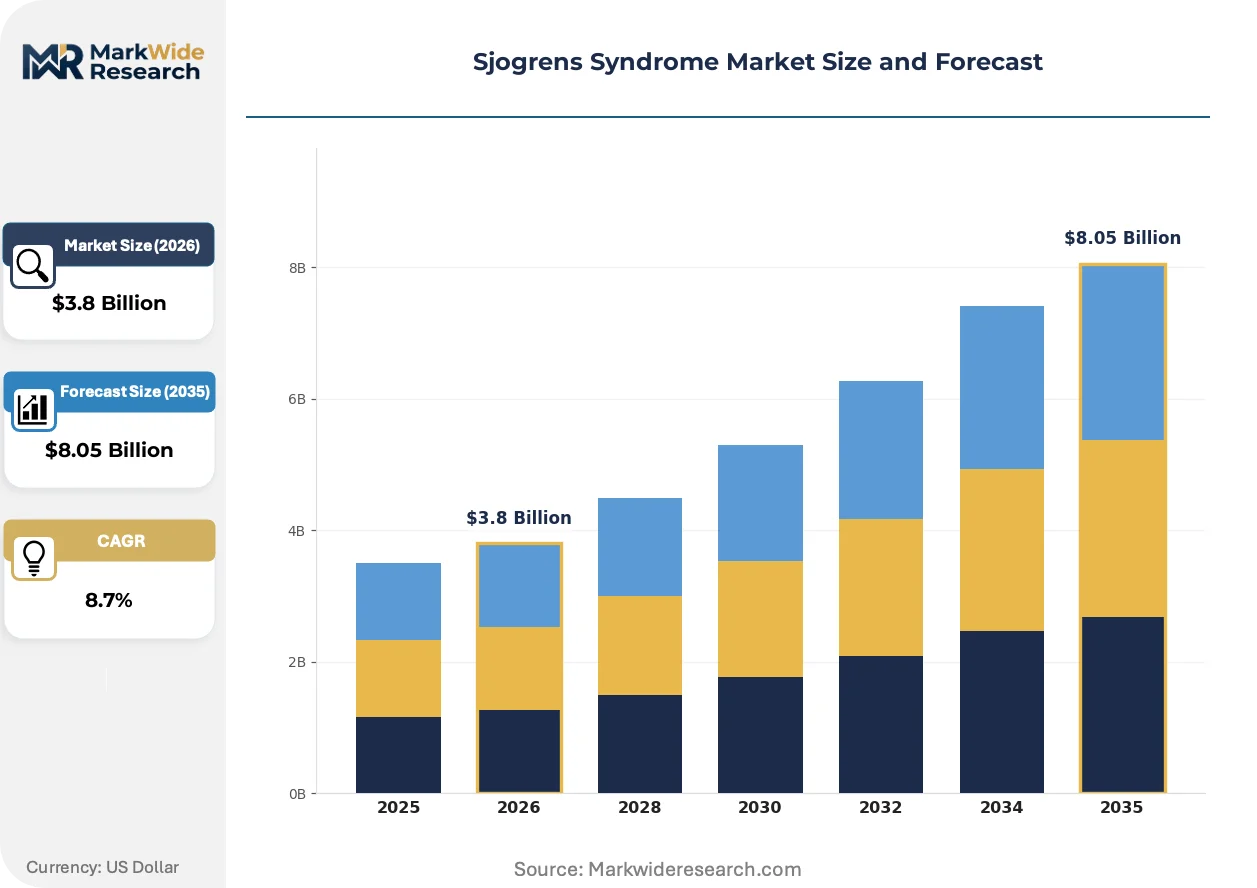
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biologics, Corticosteroids, Immunosuppressants, Over-the-Counter Treatments Treatment Stage: Acute Phase, Chronic Management, Symptomatic Relief, Disease Modifying Delivery Mode: Oral, Injectable, Topical, Infusion End User: Clinics, Hospitals, Home Care, Long-Term Care Facilities |
| Companies Covered | AbbVie Inc., Novartis AG, Bristol Myers Squibb Co., Johnson & Johnson, Horizon Therapeutics Plc, Amgen, F. Hoffmann-La Roche Ltd, GlaxoSmithKline Plc, RemeGen Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sjogrens Syndrome Market Strategic Shifts
Biologic development is compressing around modular trial designs and real-world evidence generation, with regulatory science and digital biomarkers converging to reshape how sponsors demonstrate clinical value.
Subcutaneous formulation technology is modularizing administration paradigms across the biologic pipeline. Rheumatology practices and infusion centers adopt self-injection training protocols for patient home administration. This delivery evolution reduces hospital dependency and expands addressable prescriber base beyond academic specialists.
EMA's conditional marketing authorization framework tightens evidentiary requirements for post-approval confirmatory studies. Sponsors must now pre-specify conversion timelines for surrogate endpoints to clinical outcomes. Biologics targeting BAFF signaling face particular scrutiny given prior failures in lupus analogues.
Specialist referral patterns are fragmenting as community rheumatologists gain confidence with biologic initiation. Academic medical centers respond by unbundling diagnostic services from treatment management. This channel rotation is most visible in the United States, where Medicare reimbursement for remote therapeutic monitoring creates new revenue streams.
Sjogrens Syndrome Market Segmentation
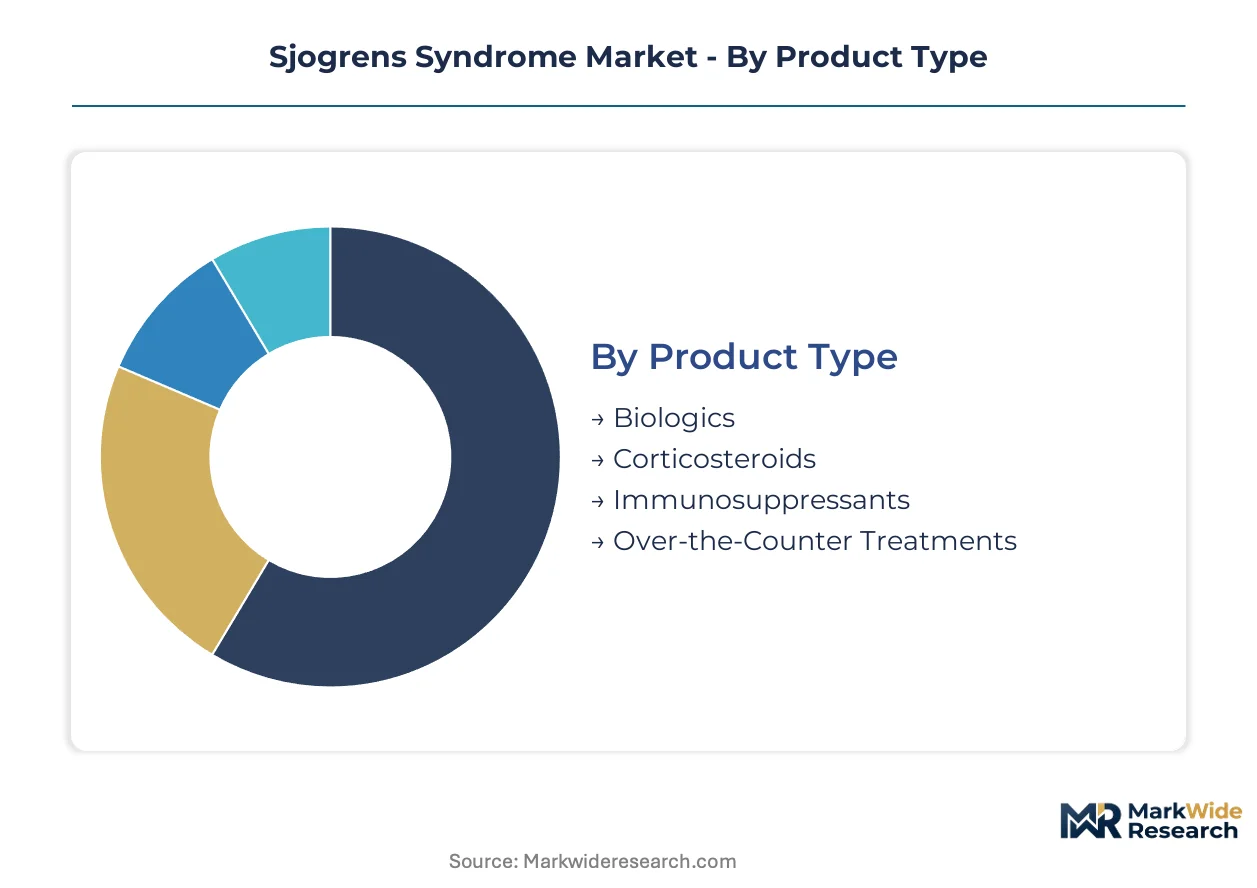
Sjogren's syndrome treatment segmentation reflects divergent regulatory pathways and reimbursement tiers across autoimmune therapeutics. Each category maps distinct certification burdens to commercial access corridors, from FDA-accelerated biologics to symptomatic OTC exemptions.
Product Type:
FDA breakthrough therapy designation concentrates on biologics and novel immunosuppressants, while corticosteroids and OTC treatments face abbreviated review cycles through established monograph pathways.
- Biologics:Monoclonal antibodies and fusion proteins targeting BAFF, type I interferon, and interleukin pathways require BLA submission with immunogenicity profiling. Massachusetts and North Carolina biomanufacturing clusters supply hospital rheumatology departments seeking refractory case solutions. FDA accelerated approval compresses phase III duration around salivary flow biomarkers.
- Immunosuppressants:Small-molecule calcineurin inhibitors and antimetabolites demand NDA submission with renal and hepatic safety monitoring protocols. Community rheumatology practices in the United States drive volume as confidence with biologic initiation spreads beyond academic centers. Payers apply cross-disease reference pricing pressure from JAK inhibitor analogues in competing autoimmune indications.
- Corticosteroids:Established ANDA pathways for prednisone and methylprednisolone formulations carry minimal regulatory burden.
- Over-the-Counter Treatments:Artificial tears and saliva substitutes bypass prescription requirements through FDA monograph compliance.
Leading the category by volume: Immunosuppressants. Growing fastest: Biologics.
Treatment Stage:
Reimbursement gatekeeping intensifies with therapeutic ambition, from symptomatic relief requiring minimal documentation to disease-modifying claims demanding measurable glandular function improvement.
- Disease Modifying:Therapies demonstrating objective preservation of lacrimal and salivary gland function command premium formulary placement. Medicare and commercial payers in the United States increasingly require patient-reported outcome linkage to objective measures. Academic medical centers establish dedicated Sjogren's clinics to capture this high-margin segment.
- Chronic Management:Long-term immunomodulation protocols balance efficacy against cumulative toxicity profiles. Hospital-based rheumatology departments in the United States deepen adoption as specialist infrastructure expands. Integrated diagnostic protocols separate academic centers from community practice revenue streams.
- Symptomatic Relief:Palliative approaches targeting sicca symptoms face commoditization pressure from generic substitution.
- Acute Phase:Flare management protocols concentrate in emergency and urgent care settings with limited specialty involvement.
Dominant by patient volume: Chronic Management. Steepest expansion trajectory: Disease Modifying.
Delivery Mode:
Administration complexity determines site-of-care economics and prescriber addressability, from self-managed oral regimens to infusion-dependent biologics requiring facility-based reimbursement.
- Injectable:Subcutaneous formulations of monoclonal antibodies modularize administration paradigms across the biologic pipeline. Rheumatology practices adopt self-injection training protocols enabling patient home administration. This delivery evolution reduces hospital dependency and expands addressable prescriber base.
- Infusion:Intravenous biologic delivery concentrates revenue in hospital outpatient departments and standalone infusion centers. Massachusetts and North Carolina GMP capacity expansion supports pipeline candidates entering pivotal trials. Site-of-service reimbursement differentials create channel arbitrage opportunities.
- Oral:Small-molecule immunosuppressants and corticosteroids enable pharmacy benefit management with minimal site-of-care cost.
- Topical:Ophthalmic and oral cavity preparations address localized sicca symptoms with limited systemic exposure.
Highest reimbursement per dose: Infusion. Gaining share fastest: Injectable.
End User:
Care setting selection reflects disease severity stratification and biologic eligibility, concentrating complex immunomodulation in hospital systems while fragmenting maintenance therapy across community channels.
- Hospitals:Academic medical centers and hospital-based rheumatology departments capture biologic initiation and refractory case management. Dedicated Sjogren's clinics with integrated diagnostic protocols concentrate in the United States specialist infrastructure. Medicare reimbursement for remote therapeutic monitoring creates new revenue streams separating diagnosis from treatment.
- Clinics:Community rheumatology practices gain confidence with biologic initiation as referral patterns fragment. This channel rotation is most visible in the United States where prescriber education programs expand addressable base. Academic centers respond by unbundling diagnostic services.
- Home Care:Self-administered oral and subcutaneous therapies shift site of care toward patient residence.
- Long-Term Care Facilities:Institutional settings manage elderly patients with polypharmacy complexity and extraglandular manifestations.
Leading by biologic revenue concentration: Hospitals. Expanding most quickly: Clinics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States hospitals and academic medical centers command the largest share of biologic revenue, with specialist infrastructure and reimbursement frameworks for rare autoimmune conditions concentrating demand in this market. Germany and Japan follow as distinct regulatory environments shape commercial access. Emerging markets in Asia-Pacific present expansion corridors through rare disease frameworks and manufacturing scale-up.
United States
Hospital-based rheumatology departments drive biologic adoption through integrated diagnostic protocols and dedicated Sjogren's clinics. FDA accelerated approval pathways compress development timelines for type I interferon and BAFF-targeting therapies. Massachusetts and North Carolina biomanufacturing clusters expand GMP capacity to supply pipeline candidates entering pivotal trials.
Germany
Academic medical centers in Bavaria and North Rhine-Westphalia anchor specialist care infrastructure with established referral networks for systemic autoimmune conditions. EMA conditional marketing authorization frameworks create post-approval uncertainty that shapes sponsor evidence generation strategies. Berlin-Brandenburg hosts regulatory science consultancies specializing in autoimmune trial design.
Japan
PMDA's sakigake designation offers priority review for novel mechanisms targeting unmet need in refractory cases. The Kanto region concentrates biopharma R&D activity with integrated hospital networks for patient recruitment. Tokyo-based academic centers lead glandular function endpoint validation research for regulatory qualification.
China
NMPA's rare disease catalog inclusion drives investment in local clinical trial infrastructure for autoimmune indications. The Yangtze River Delta biocluster attracts multinational sponsors seeking patient access and manufacturing partnerships. Shanghai and Suzhou house contract research organizations specializing in decentralized trial deployment.
United Kingdom
London and Southeast England concentrate specialist rheumatology services with NHS England commissioning frameworks shaping formulary access. The MHRA's reliance on EMA decisions post-Brexit creates regulatory alignment friction for novel biologics. Cambridge and Oxford academic medical centers participate in EU-wide confirmatory trial networks despite jurisdictional separation.
Sjogrens Syndrome Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with biologic developers capturing premium margins through targeted immunomodulation while generic manufacturers supply commoditized symptomatic relief. The market structure tilts toward consolidation among immunology platform holders with cross-disease pipelines. Three archetypes dominate: large-cap diversified pharmas with autoimmune franchises, mid-cap biotechs with single-disease focus, and emerging-market biosimilar developers. Competitive moves center on M&A for pipeline acquisition and strategic partnerships for manufacturing capacity access.
Within the large-cap immunology tier, AbbVie Inc. and Novartis AG occupy anchor positions through platform breadth and B-cell specialization respectively. Bristol Myers Squibb Co. exemplifies the integrated autoimmune R&D archetype spanning oral small molecules and monoclonal antibodies. These entities represent the competitive standard against which mid-cap entrants and biosimilar challengers position pipeline differentiation claims.
| Leading Market Players |
|---|
| AbbVie Inc. |
| Novartis AG |
| Bristol Myers Squibb Co. |
| Johnson & Johnson |
| Horizon Therapeutics Plc |
| Amgen |
| F. Hoffmann-La Roche Ltd |
| GlaxoSmithKline Plc |
| RemeGen Co. Ltd. |
| Others |
Value Chain & Pricing Dynamics
Payer consolidation around value-based reimbursement frameworks in the United States and Germany is compressing margins on conventional immunosuppressants while forcing biologic sponsors to absorb higher evidence-generation costs. This demand-side compression reshapes supplier priorities toward demonstrable glandular function endpoints and modular manufacturing configurations that can pivot between dosage forms.
Pricing Analysis
Volume-margin splits concentrate revenue in biologics despite immunosuppressants dominating prescription counts. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and administration complexity. Cost compression in the immunosuppressant tier is intensifying because JAK inhibitor cross-disease reference pricing allows payers to extract concessions. Community rheumatology practices exhibit highest price sensitivity; academic medical centers with dedicated Sjogren's clinics demonstrate lowest.
Supply Chain Analysis
Plasma fractionation feedstock rests on four global collectors operating collection networks across the United States, Germany, and Japan. Monoclonal antibody production draws from Chinese hamster ovary cell banks, single-use bioreactor systems, and affinity chromatography resins. Single-source vulnerability in immunoglobulin supply constrains IVIG capacity expansion for refractory cases. Distribution runs through hospital outpatient departments, specialty pharmacies, and direct-to-site cold chain logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as FDA accelerated approval pathways raise capital requirements for confirmatory trial design, forcing subscale developers toward partnership or exit.
For Market Incumbents: Anticipate biosimilar pressure on legacy biologics by deepening backward integration into plasma collection networks and captive GMP capacity in Massachusetts and North Carolina. Lock in formulary placement through integrated diagnostic-treatment protocols at academic medical centers. Prioritize investment in interferon signature assay standardization to create technical moats around patient stratification.
For New Entrants and Emerging Players: The mid-tier pricing gap between infused biologics and generic immunosuppressants offers white-space entry through subcutaneous formulations with self-administration training support. Target community rheumatology practices in the United States where prescriber education programs expand addressable base beyond academic centers. Pursue Japan's sakigake designation as a go-to-market angle securing priority review and pricing premiums in an underpenetrated market.
For Investors and Strategic Acquirers: The window for entry favors mid-cap biotechs with single-disease focus and qualified biomarker platforms. Long-term viability hinges on demonstrating conversion of surrogate endpoints to clinical outcomes across the analysis window. Acquisition target archetype: developers with modular trial infrastructure and EU AI Act-compliant digital biomarker capabilities. Watch EMA conditional marketing authorization conversion timelines as the inflection signal for portfolio rebalancing.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA accelerated approval compresses phase III duration around salivary flow biomarkers. |
| Manufacturing Scale-Up | Massachusetts and North Carolina GMP clusters expand monoclonal antibody production capacity. |
| Pipeline Diversification | Type I interferon and BAFF signaling targets spread mechanism risk across autoimmune portfolios. |
| Licensing Agreement | EU AI Act-compliant digital biomarker platforms reduce decentralized trial deployment costs. |
| Clinical Trial Advancement | Remote salivary flow monitoring enables patient recruitment beyond academic medical centers. |
Study Parameters
FDA filings, EMA submissions, and ClinicalTrials.gov formed the secondary backbone, cross-referenced with CMS Medicare reimbursement data and hospital procurement databases. Primary interviews with drug development executives, regulatory affairs leads, formulary directors, and payer access specialists validated demand assumptions and pricing dynamics. Bottom-up patient flow modeling and top-down epidemiological triangulation converged on segment-level estimates.
Bottom-up volume builds by treatment stage, delivery mode, and regional regulatory cluster anchored the analytical lens, with top-down epidemiological constraints ensuring consistency across the projection horizon. CAGRs derived from fitted growth curves applied to each segment's addressable patient population and pricing trajectory. Forecast inputs incorporated interferon signature assay adoption curves and biologic penetration rates in hospital versus community settings.
Inputs from FDA, EMA, and PMDA regulatory databases were available through the study window; gaps in real-world evidence conversion timelines for surrogate endpoints introduce uncertainty bands around biologic revenue projections. Forecasts reflect documented assumptions regarding payer evidence requirements and manufacturing capacity expansion schedules. Pricing pressure from JAK inhibitor cross-disease reference and plasma fractionation supply constraints warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Cervical Dystonia Market
Specialty Medicine
Pseudomonas Aeruginosa Treatment Market
Specialty Medicine
Perennial Allergic Rhinitis Market
Specialty Medicine
Dry Eye Syndrome Market
Specialty Medicine
Primary Hyperoxaluria Treatment Market
Specialty Medicine
Vesicoureteral Reflux Market
Specialty Medicine
Pleurisy Market
Specialty Medicine
Partial Onset Seizures Market
Specialty Medicine
Nephroblastoma Therapeutics Market
Specialty Medicine
Cytomegalovirus Retinitis Market
Specialty Medicine
Hashimoto's Thyroiditis Therapeutics Market
Specialty Medicine
Global Lupus Market
Specialty Medicine
Amyotrophic Lateral Sclerosis (ALS) Market
Specialty Medicine
Global Autoimmune Disease Therapeutics Market
Specialty Medicine
Endometriosis Market
Specialty Medicine
Odontogenic Tumor Market