
 Drug-Induced Dyskinesia Market | 2026-2036
Drug-Induced Dyskinesia Market Size, Share, and Industry Trends Forecast 2026-2036
Drug-Induced Dyskinesia Market Foresight
North American clinical infrastructure is reconfiguring how drug-induced dyskinesia is diagnosed and managed across outpatient neurology networks. Neurocrine Biosciences leverages its VMAT2 inhibitor portfolio to anchor the therapeutic landscape for tardive dyskinesia. Teva Pharmaceutical Industries sustains competitive presence through generic alternatives and specialty neurology distribution. Sun Pharmaceutical Industries competes on cost-efficient manufacturing scale for emerging market access.
Drug-induced dyskinesia comprises involuntary, repetitive movement disorders triggered by dopamine receptor antagonists, particularly first- and second-generation antipsychotics, with symptoms ranging from orofacial tardive dyskinesia to generalized choreoathetosis that severely impairs functional capacity and quality of life. The condition demands precise pharmacological management through VMAT2 inhibition or dopamine modulation to restore motor control without compromising underlying psychiatric treatment. Among product type segments, antipsychotics generate the largest absolute caseload of dyskinesia requiring intervention, while the injectable delivery mode commands premium positioning due to depot formulations ensuring compliance in schizophrenia maintenance. Hospitals remain the dominant end-user setting for initial diagnosis and acute management, though homecare channels are gaining traction as oral VMAT2 inhibitors enable outpatient maintenance protocols.
FDA neurology division guidelines shape clinical trial endpoints and approval pathways for novel dyskinesia therapeutics, directly influencing R&D investment allocation across the industry. EMA orphan drug incentives and the EU AI Act's clinical decision-support standards are creating parallel regulatory frameworks that manufacturers must navigate for transatlantic market access. Stakeholders should monitor how real-world evidence requirements evolve at both agencies, as post-market surveillance data will increasingly determine formulary placement and reimbursement durability for movement disorder therapies.
Market Dynamics
VMAT2 inhibitor commercialization is concentrating therapeutic investment around tardive dyskinesia management while antipsychotic prescribing expansion continuously generates new patient cohorts requiring intervention. The structural tension between psychiatric medication necessity and motor complication liability is forcing parallel development of prophylactic and rescue pharmacology.
Growth Catalysts
- Medicare Part D reimbursement expansion:Broadened coverage for VMAT2 inhibitors in the United States removes financial barriers to chronic therapy maintenance.
- Neurology clinic network densification:Outpatient screening infrastructure across North America enables earlier detection of antipsychotic-induced movement disorders.
- Long-acting injectable antipsychotic proliferation:Depot formulations extend exposure duration, expanding the addressable dyskinesia population requiring ongoing management.
Market Restraints
- VMAT2 inhibitor manufacturing concentration:Active pharmaceutical ingredient synthesis relies on limited specialized chemical production facilities in Western Europe.
- Trial recruitment friction:FDA-mandated movement disorder rating scale validation extends clinical development timelines for novel mechanisms.
- Generic dopamine antagonist cost floor:First-generation antipsychotic commoditization constrains pricing headroom for adjunctive dyskinesia therapy.
Strategic Opportunities
- Pediatric neuropsychiatric expansion:Rising antipsychotic prescribing for autism spectrum irritability creates a treatment-naive dyskinesia population in the United States.
- Real-world evidence integration:FDA's patient-focused drug development guidance enables label expansion through post-market surveillance data streams.
- Homecare channel penetration:Oral VMAT2 inhibitor protocols allow movement disorder management outside hospital-based neurology departments.
Industry Challenges
- Movement disorder specialist scarcity:Fellowship-trained neurologist pipeline constraints limit diagnostic throughput in community healthcare systems.
- Psychiatric-neurology care coordination:Split treatment models between antipsychotic prescribers and dyskinesia managers fragment patient monitoring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drug-Induced Dyskinesia Market |
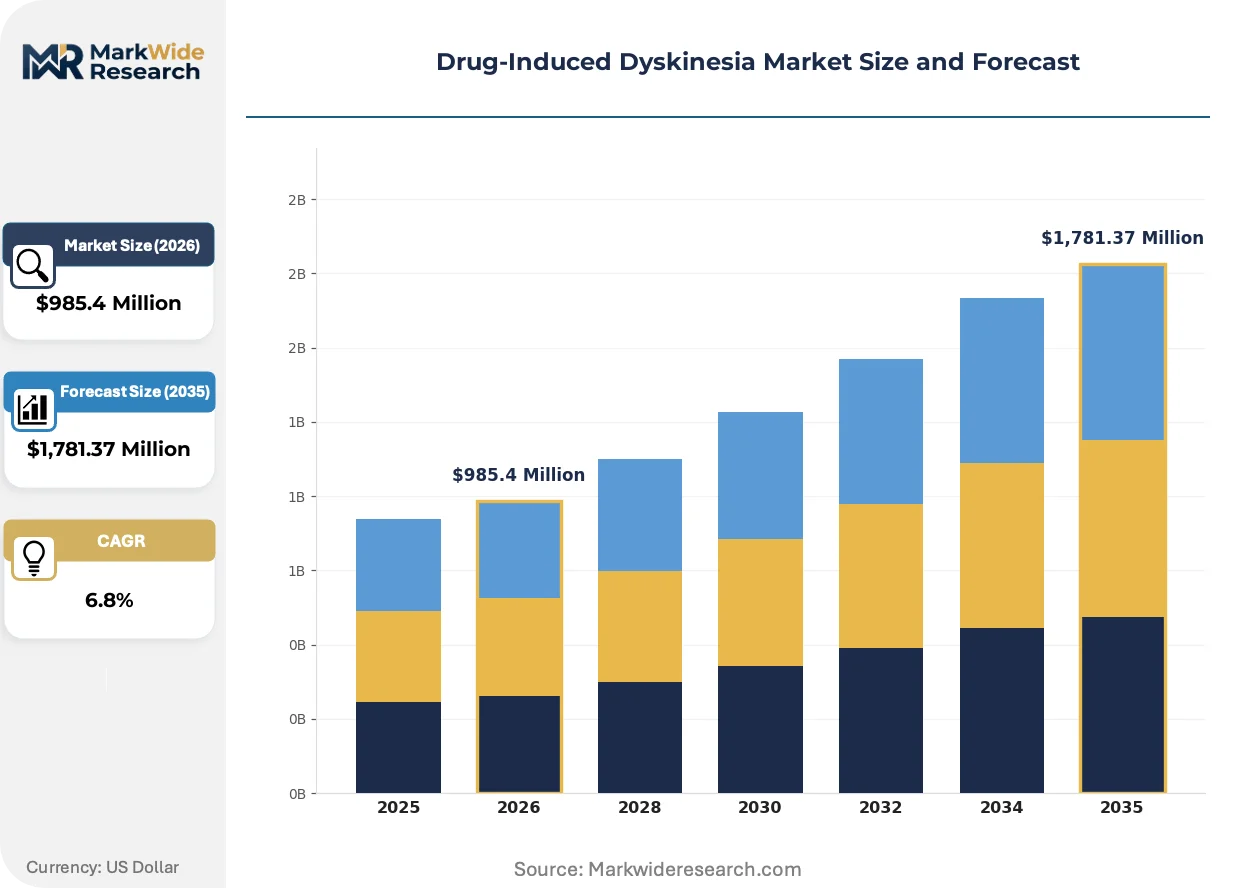
| Market Size in 2026 | $985.4 Million |
| Market Size in 2035 | $1,781.37 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antipsychotics, Anticonvulsants, Antidepressants, Others Delivery Mode: Oral, Injectable, Transdermal, Inhalation End User: Hospitals, Clinics, Homecare, Rehabilitation Centers Treatment Stage: Initial Treatment, Maintenance Therapy, Emergency Care, Supportive Care |
| Companies Covered | Neurocrine Biosciences, Teva Pharmaceutical Industries, Sun Pharmaceutical Industries, AbbVie, Adamas Pharmaceuticals, Lannett Co, SteriMax, Mitsubishi Tanabe Pharma Corporation, Acadia Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drug-Induced Dyskinesia Market Shifts & Advancements
Digital biomarker capture and machine learning classification are transforming how involuntary movements are quantified and tracked across clinical and real-world settings. These technologies are compressing the gap between subjective physician assessment and objective motor function measurement.
Computer vision-based dyskinesia scoring algorithms trained on standardized video protocols are rendering obsolete traditional in-clinic human rater dependency for severity assessment. Academic medical centers in the United States are piloting these systems for remote monitoring of tardive dyskinesia progression. The technology is enabling decentralized clinical trial endpoints and expanding prescriber confidence in patient-reported outcome correlation.
EMA's updated guideline on central nervous system clinical investigation now mandates patient-reported outcome measures alongside clinician-rated scales for movement disorder therapeutics. This dual-endpoint requirement is elevating investment in electronic patient diary platforms and wearable sensor correlation studies. Manufacturers targeting European market authorization must now integrate patient-centric measurement into protocol design from phase II forward.
Specialty pharmacy distribution is consolidating patient access for high-cost oral VMAT2 inhibitors through hub-and-spoke models that bundle medication with adherence monitoring. These arrangements displace traditional retail pharmacy dispensing for chronic neurology maintenance therapy. The United States exhibits the most pronounced channel concentration, where limited distribution networks now handle the majority of deutetrabenazine and valbenazine fulfillment.
Drug-Induced Dyskinesia Market Segmentation
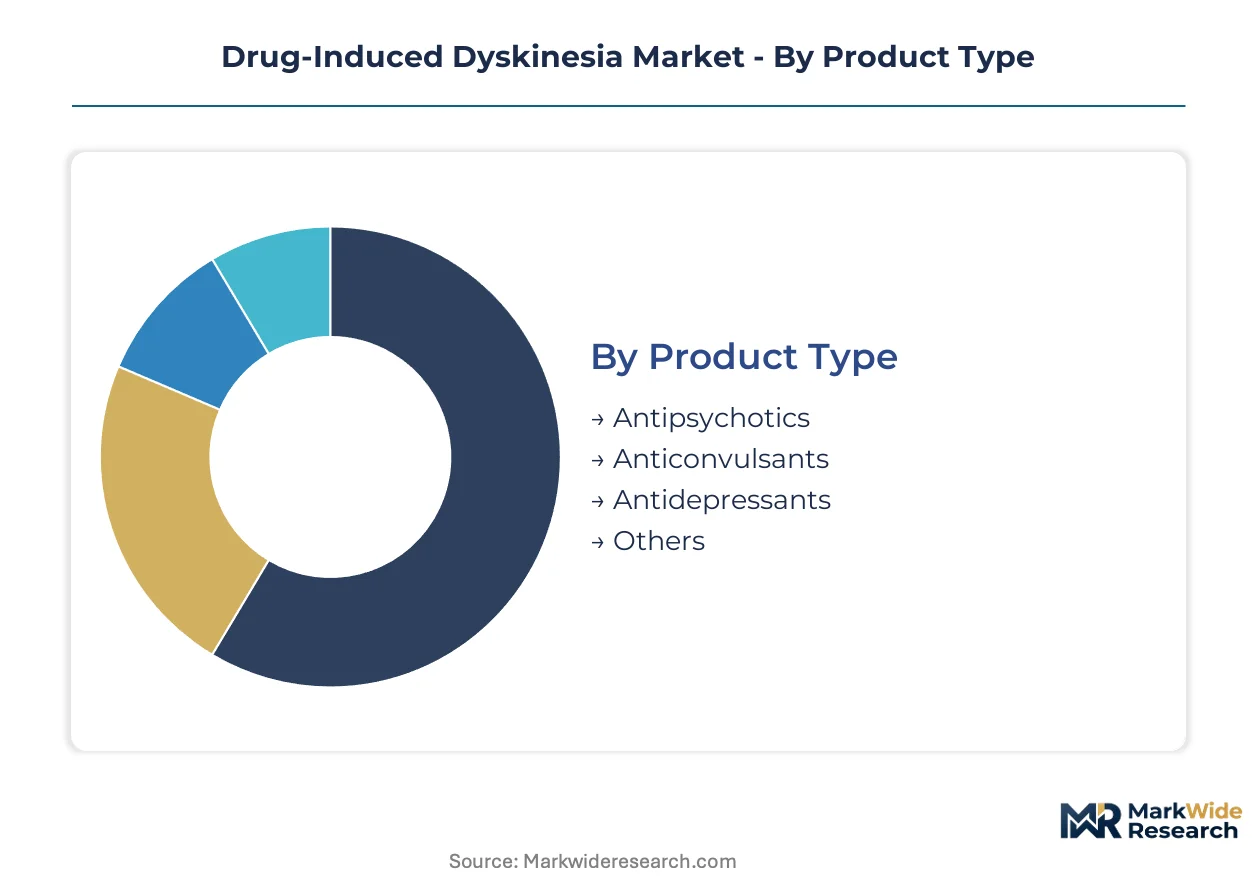
Drug-induced dyskinesia therapeutics fragment across pharmacological triggers, administration routes, and care settings. Each segmentation axis reveals distinct competitive dynamics between established psychiatric medication classes and emerging movement disorder management protocols.
Product Type:
Mature psychiatric drug classes dominate absolute caseload generation, while emerging therapeutic categories reshape intervention timing.
- Antipsychotics:First- and second-generation dopamine receptor antagonists generate the largest population requiring dyskinesia intervention. Tardive dyskinesia prevalence concentrates in long-term schizophrenia and bipolar maintenance populations across the United States. VMAT2 inhibitor prescribing correlates directly with antipsychotic exposure duration.
- Anticonvulsants:Sodium channel modulators and GABAergic agents produce choreiform movements and asterixis at therapeutic thresholds. Demand for adjunctive movement disorder management tracks epilepsy polytherapy rates in academic medical centers. Carbamazepine and phenytoin remain the principal culprits in this category.
- Antidepressants:Selective serotonin reuptake inhibitors and tricyclic compounds occasionally induce akathisia and tremor syndromes. SSRI-associated movement disorders typically resolve with dose reduction rather than requiring specialized dyskinesia pharmacology.
- Others:Metoclopramide, levodopa, and lithium carbonate complete the pharmacological spectrum of dyskinesia-inducing agents. Each requires distinct recognition patterns for appropriate intervention selection.
Antipsychotics handle the majority of throughput; anticonvulsants are gaining share fastest as epilepsy surgical candidacy screening intensifies.
Delivery Mode:
Cost tier stratification separates acute intervention formats from chronic maintenance protocols.
- Oral:Immediate-release and extended-release tablet formulations enable outpatient titration of VMAT2 inhibitors. Deutetrabenazine and valbenazine tablets dominate maintenance prescribing in Medicare Part D populations. Adherence monitoring through specialty pharmacy hubs supports long-term compliance.
- Injectable:Depot antipsychotic formulations extend exposure windows and expand the addressable dyskinesia population. Long-acting risperidone and paliperidone palmitate drive screening demand in Assertive Community Treatment programs. Intramuscular VMAT2 inhibitor development remains preclinical.
- Transdermal:Patch-based delivery systems for antipsychotics and antiemetics reduce peak plasma fluctuations implicated in motor complications. Rotigotine patches for Parkinson's disease complicate differential diagnosis in drug-induced movement disorders.
- Inhalation:Loxapine inhaled powder represents the sole approved inhalation antipsychotic with dyskinesia surveillance requirements. Limited commercial penetration constrains segment significance.
Oral formulations capture the highest prescription volume; injectable modes command premium positioning through compliance assurance.
End User:
Application concentration shifts from institutional diagnosis toward distributed maintenance management.
- Hospitals:Inpatient neurology and psychiatry services handle acute dyskinesia recognition and initial VMAT2 inhibitor loading. Academic medical centers train movement disorder fellows in standardized rating scale administration. Emergency departments manage severe akathisia and dystonic reactions.
- Clinics:Outpatient neurology practices across the United States are densifying tardive dyskinesia screening infrastructure. Nurse practitioner-led movement disorder clinics extend specialist access in community health systems. Telemedicine protocols now support remote severity assessment.
- Homecare:Oral VMAT2 inhibitor maintenance enables direct-to-patient dispensing models. Specialty pharmacy nursing services monitor adherence and adverse events outside institutional settings. Medicare home health benefit coverage varies by contractor jurisdiction.
- Rehabilitation Centers:Post-acute facilities manage persistent dyskinesia in patients transitioning from institutional psychiatric care. Physical therapy protocols address functional impairment from orofacial and truncal movement disorders.
Hospitals anchor diagnostic throughput; homecare channels are expanding most quickly as oral maintenance protocols mature.
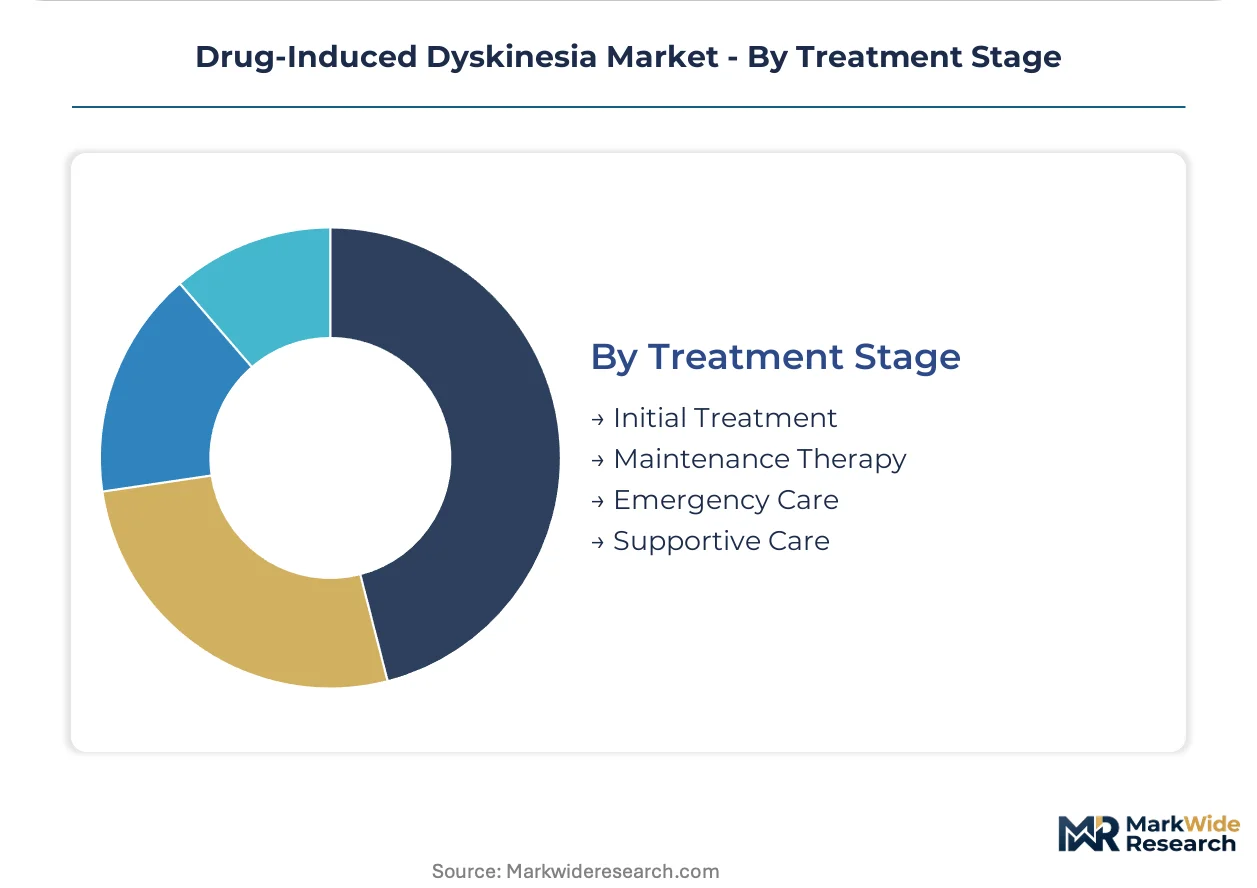
Treatment Stage:
Customer type stratification separates acute intervention from longitudinal management responsibilities.
- Initial Treatment:First-line VMAT2 inhibitor selection requires distinguishing drug-induced from idiopathic movement disorders. Diagnostic delay averages months in community settings without movement disorder specialist access.
- Maintenance Therapy:Chronic VMAT2 inhibitor administration demands psychiatric-neurology care coordination to preserve underlying antipsychotic efficacy. Dose optimization occurs over quarters rather than weeks.
- Emergency Care:Acute dystonic reactions and severe akathisia require immediate anticholinergic or benzodiazepine intervention. Emergency department protocols prioritize rapid symptom control over etiological clarification.
- Supportive Care:Adjunctive physical therapy, speech therapy, and patient education address functional consequences of persistent dyskinesia. Multidisciplinary coordination remains underdeveloped in fee-for-service reimbursement environments.
Maintenance therapy handles the majority of chronic pharmaceutical expenditure; emergency care commands disproportionate attention in residency training curricula.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
VMAT2 inhibitor manufacturing concentrates in specialized chemical production corridors, with clinical trial density and reimbursement infrastructure determining commercial penetration. The United States anchors prescription volume through Medicare Part D expansion, while Western European facilities handle active pharmaceutical ingredient synthesis.
United States
Medicare Part D reimbursement broadened access to deutetrabenazine and valbenazine, removing financial barriers for chronic therapy maintenance. FDA neurology division guidelines shape clinical trial endpoints for novel dyskinesia therapeutics. Movement disorder screening infrastructure densifies across outpatient neurology networks in Massachusetts and California.
Germany
EMA orphan drug incentives attract tardive dyskinesia therapeutic development toward centralized European market authorization. The country's national pharmaceutical regulator enforces stringent post-market surveillance for CNS-active agents. Chemical production clusters in North Rhine-Westphalia supply specialized VMAT2 inhibitor intermediates to global formulation sites.
Japan
PMDA accelerated approval pathways for movement disorder therapeutics compress regulatory timelines for tardive dyskinesia candidates. METI pharmaceutical industry support programs subsidize domestic clinical trial infrastructure. Tokyo-based academic medical centers pioneer digital biomarker validation for remote dyskinesia severity assessment.
Switzerland
Swissmedic maintains alignment with EMA central nervous system investigation standards while offering streamlined access for orphan indications. The country's precision chemical manufacturing base supports high-purity active pharmaceutical ingredient production. Basel-region contract research organizations coordinate multi-site European tardive dyskinesia trials.
India
CDSCO streamlined approval processes for VMAT2 inhibitor generics expand patient access across price-sensitive segments. The country's national pharmaceutical regulator harmonizes bioequivalence standards with ICH guidelines. Hyderabad and Mumbai manufacturing clusters scale cost-efficient deutetrabenazine production for emerging market distribution.
Drug-Induced Dyskinesia Market Competitive Landscape
VMAT2 inhibitor specialists and diversified neurology portfolios split the market between focused therapeutic development and broad psychiatric distribution. The competitive structure tiers across originator molecule holders, generic challengers, and regional manufacturing scale players. Three archetypes dominate: single-mechanism biotechs with FDA-approved tardive dyskinesia labels, multinational pharmaceutical conglomerates leveraging psychiatry sales infrastructure, and emerging market manufacturers competing on cost-efficient supply. Portfolio diversification through CNS pipeline expansion and specialty pharmacy distribution partnerships constitute the dominant competitive moves.
Within the VMAT2 inhibitor specialist tier, Neurocrine Biosciences and Adamas Pharmaceuticals exemplify focused therapeutic development archetypes. Among diversified pharmaceutical conglomerates, Teva Pharmaceutical Industries and AbbVie occupy positions anchored by psychiatry franchise breadth and neurology commercial infrastructure. Sun Pharmaceutical Industries represents the emerging market manufacturing scale archetype, with cost-efficient production capabilities supporting generic VMAT2 inhibitor supply.
| Leading Market Players |
|---|
| Neurocrine Biosciences |
| Teva Pharmaceutical Industries |
| Sun Pharmaceutical Industries |
| AbbVie |
| Adamas Pharmaceuticals |
| Lannett Co |
| SteriMax |
| Mitsubishi Tanabe Pharma Corporation |
| Acadia Pharmaceuticals |
| Others |
Supply & Pricing Matrix
Single-source dependency on Western European active pharmaceutical ingredient synthesis for VMAT2 inhibitors compresses pricing tier spreads while simultaneously elongating supply chain lead times. This concentration dynamic forces manufacturers to absorb regulatory compliance costs into premium-tier formulations while generic competitors exploit cost-efficient Indian production corridors for economy positioning.
Pricing Analysis
Medicare Part D reimbursement dictates the pricing tier structure across the United States market, establishing a three-tier pricing structure across premium, standard, and economy levels based on FDA approval status and bioequivalence certification. Price differentiation hinges on originator molecule exclusivity versus generic substitution eligibility, with originator brands commanding substantial premiums in Medicare Advantage formularies. Pricing pressure stems from CDSCO accelerated generic approvals in India, which compress margins for standard-tier products. Hospital procurement committees exhibit the highest price sensitivity due to bundled payment constraints, while specialty pharmacy direct dispensing demonstrates lower elasticity through patient assistance program offset mechanisms.
Supply Chain Analysis
Extended payment terms from specialty pharmacy distributors to VMAT2 inhibitor manufacturers now stretch to 90-120 days, straining working capital requirements for mid-tier producers. Geographic supply concentration centers on North Rhine-Westphalia in Germany for high-purity chemical intermediates, Hyderabad and Mumbai in India for cost-efficient generic API production, and Basel-region Switzerland for precision formulation manufacturing. Raw material dependencies encompass tetrabenazine-derived alkaloid precursors, specialized hydrogenation catalysts, and high-barrier blister packaging films. Single-source vulnerability pervades the European intermediate supply base, where regulatory inspection backlogs constrain alternative qualification timelines. Distribution runs through limited specialty pharmacy networks that bundle medication fulfillment with adherence monitoring services for chronic neurology maintenance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The scarcity of fellowship-trained movement disorder specialists constrains diagnostic throughput and fragments care coordination between psychiatry and neurology, creating bottlenecks that determine market access velocity more than manufacturing capacity.
For Market Incumbents: Entrench VMAT2 inhibitor market position through backward integration into captive API production in Indian chemical corridors, insulating against European supply disruption. Secure exclusive distribution partnerships with dominant specialty pharmacy networks to lock out generic challengers from preferred formulary tiers. Prioritize investment in digital biomarker platforms that render competitor severity assessment protocols obsolete. For New Entrants and Emerging Players: Pediatric neuropsychiatric indications for autism spectrum irritability represent the most penetrable entry point, with treatment-naive dyskinesia populations lacking established therapeutic relationships. Homecare channel protocols for oral maintenance therapy enable direct-to-patient models that bypass hospital-based neurology gatekeepers. Pursue licensing arrangements with academic medical centers for computer vision-based remote monitoring technology to differentiate from incumbent in-clinic assessment dependency. For Investors and Strategic Acquirers: FDA patient-focused drug development guidance reshapes the acquisition landscape by elevating real-world evidence platforms to strategic assets capable of supporting label expansion without traditional trial infrastructure. Long-term viability centers on portfolio diversification across prophylactic and rescue pharmacology mechanisms rather than single-mechanism concentration. Target acquisition archetypes include digital biomarker developers with validated video-based severity scoring algorithms. Monitor EMA post-market surveillance enforcement intensity as the critical inflection signal for European market authorization durability.| Strategic Initiative | Industry Significance |
|---|---|
| Real-World Evidence Platform Development | FDA patient-focused guidance enables label expansion through post-market surveillance data streams without redundant clinical trials. |
| Specialty Pharmacy Network Consolidation | Limited distribution partnerships bundle medication with adherence monitoring, displacing retail pharmacy for chronic neurology maintenance. |
| Pediatric Indication Expansion | Rising antipsychotic prescribing for autism spectrum irritability creates treatment-naive dyskinesia populations requiring first-line intervention. |
| Digital Biomarker Validation | Computer vision algorithms trained on standardized video protocols enable decentralized clinical trial endpoints and remote severity tracking. |
| API Manufacturing Regionalization | Hyderabad and Mumbai production clusters reduce dependency on Western European single-source chemical synthesis corridors. |
Research Methodology
A spread of perspectives from movement disorder specialists, specialty pharmacy operations directors, Medicare formulary strategists, and VMAT2 inhibitor regulatory affairs leads converged on the working assumptions driving this analysis. Primary interviews with these stakeholders combined with secondary validation against FDA approval documents, EMA centralized procedure filings, ClinicalTrials.gov registry entries, and CMS Medicare Part D utilization data. Bottom-up prescription volume modeling and top-down therapeutic class expenditure analysis triangulated market size estimates across the projection horizon.
Demand-supply balance framing anchored the forecast framework, with patient cohort generation from antipsychotic prescribing trends cross-referenced against VMAT2 inhibitor manufacturing capacity and specialty pharmacy distribution throughput. Segmentation dimensions encompassed pharmacological trigger class, administration route, care setting, and regional regulatory cluster. CAGRs were derived from longitudinal prescribing pattern analysis and reimbursement expansion trajectories. Key forecast inputs included Medicare Part D enrollment demographics and long-acting injectable antipsychotic proliferation rates.
Macroeconomic conditions sit as an overlay; deviation in Medicare reimbursement policy, FDA neurology division guidance timelines, or EMA post-market surveillance enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions about antipsychotic prescribing elasticity and VMAT2 inhibitor manufacturing scale-up feasibility. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Viral Conjunctivitis Pipeline Drugs Market
Pharmaceuticals
Optic Nerve Disorders Drugs Market
Pharmaceuticals
Warts Therapeutics Market
Pharmaceuticals
Asia-Pacific Over-The-Counter (OTC) Drugs Market
Pharmaceuticals
Amylin Analogs Market
Pharmaceuticals
Anti-Platelet Agents Market
Pharmaceuticals
Amoxicillin Sodium Clavulanate Potassium for Injection Market
Pharmaceuticals
Dual Antiplatelet Therapy Market
Pharmaceuticals
Global Neuroprotective Agents Market
Pharmaceuticals
North America Small Molecule Sterile Injectable Drugs Market
Pharmaceuticals
Allergic Rhinitis Drugs Market
Pharmaceuticals
China Plasma Protein Therapeutics Market
Pharmaceuticals
Live Vaccines Market
Pharmaceuticals
Traveler's Diarrhea Treatment Market
Pharmaceuticals
Mitochondrial-Based Therapeutics Market
Pharmaceuticals
Azathioprine API Market