
 Global Stroke Therapeutics Market | 2026-2036
Global Stroke Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Stroke Therapeutics Market Foresight
The EU MDR is shifting the cost-of-entry calculus for neurointerventional device manufacturers, demanding expanded clinical trial footprints and post-market surveillance systems that favor well-capitalized incumbents. Boehringer Ingelheim leverages its thrombolytic heritage to anchor European hospital formularies. Bristol-Myers Squibb competes through anticoagulant portfolio breadth across ischemic stroke prevention. Daiichi Sankyo specializes in novel oral anticoagulant development, particularly for atrial fibrillation-related stroke risk reduction.
Stroke therapeutics encompass pharmacological and interventional modalities designed to restore cerebral perfusion, prevent neuronal death, and mitigate post-stroke disability through clot dissolution, mechanical retrieval, or neuroprotection. Tissue plasminogen activator remains the benchmark intravenous thrombolytic with a narrow therapeutic window, while endovascular mechanical thrombectomy has redefined care for large-vessel occlusions. Thrombolytics and antiplatelet agents occupy mature, high-volume positions with thinning margins, whereas neuroprotective agents represent the fastest-expanding frontier as multiple Phase III candidates target excitotoxicity and inflammation pathways. Surgical devices command premium pricing in specialized stroke centers where interventional neuroradiology capabilities concentrate.
FDA breakthrough device designation pathways and EMA adaptive licensing frameworks are accelerating market access for novel stroke interventions, though reimbursement harmonization lags between the United States and European systems. Japan's PMDA has streamlined reviews for regenerative medicine products, including stem-cell-based neuroprotective therapies. China's NMPA is implementing priority review channels for innovative drugs addressing unmet neurological needs. Stakeholders must monitor how real-world evidence requirements evolve across these three regulatory domains to anticipate which development pipelines will secure accelerated commercialization timelines.
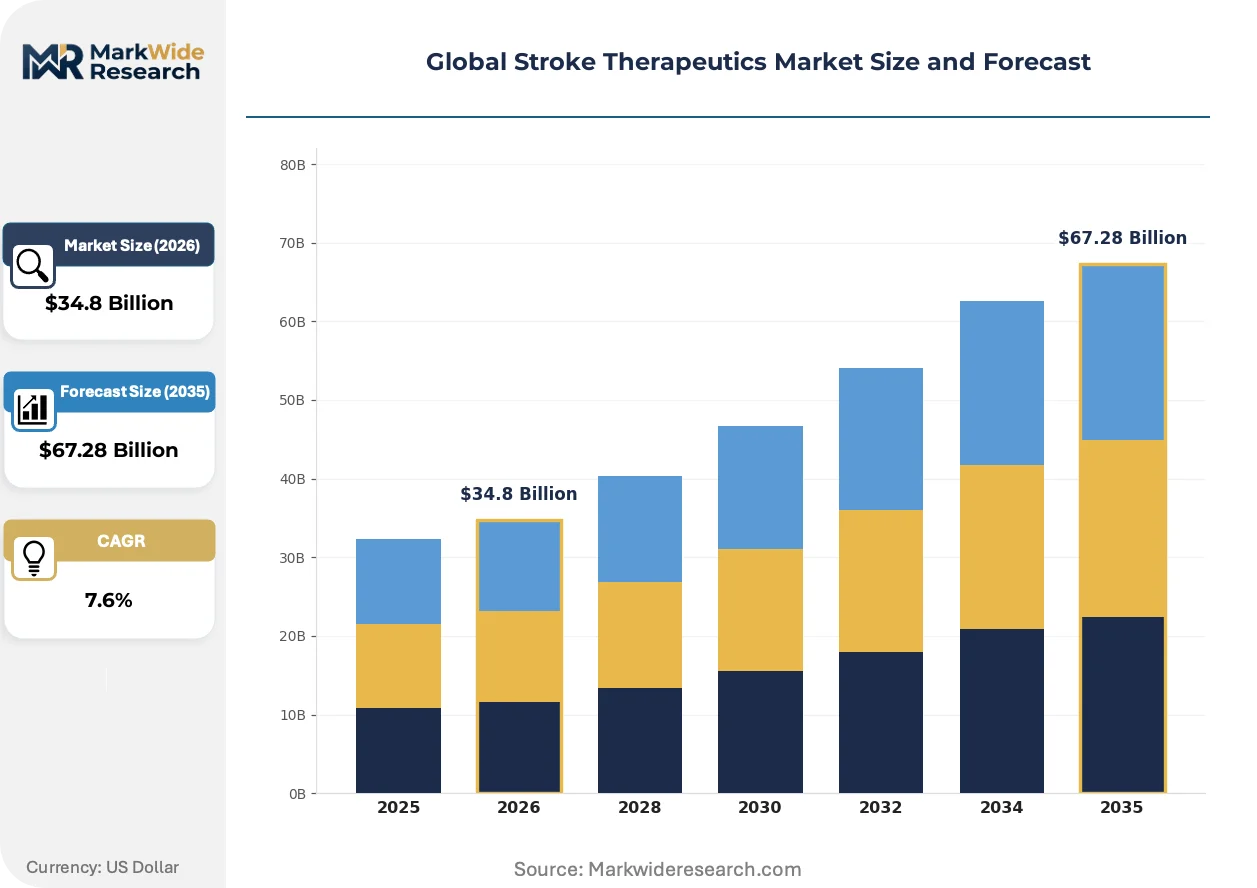
Market Dynamics
The EU MDR's expanded clinical evidence requirements are restructuring competitive entry costs, favoring manufacturers with established post-market surveillance infrastructure and forcing consolidation among mid-scale neurointerventional device suppliers.
Growth Catalysts
- Japan's PMDA streamlined pathways:Accelerated reviews for regenerative neuroprotective therapies compress development-to-commercialization timelines for stem-cell-based candidates targeting excitotoxicity pathways.
- Hospital stroke unit expansion:Dedicated capacity investments in the United States, Germany, and Japan create pull-through demand for mechanical thrombectomy devices and thrombolytic formularies.
- Mechanical thrombectomy:Endovascular clot retrieval for large-vessel occlusions has displaced intravenous tPA as first-line intervention in specialized centers, expanding addressable procedure volumes.
Market Restraints
- Therapeutic window constraints:Tissue plasminogen activator's narrow 4.5-hour administration window limits eligible patient populations and creates treatment-access disparities between urban stroke centers and rural emergency departments.
- Input concentration in nitinol:Superelastic alloy supply for stent retrievers and aspiration catheters concentrates among a limited supplier base, exposing device manufacturers to price volatility and allocation risk.
- EU MDR technical documentation:Expanded clinical evaluation requirements and notified body capacity constraints extend certification timelines, freezing pipeline commercialization for emerging neurointerventional platforms.
Strategic Opportunities
- China's NMPA priority channels:Accelerated review designation for innovative neurological drugs addressing unmet needs offers first-mover positioning for neuroprotective agents targeting inflammation cascades.
- Neuroprotection-anticoagulant convergence:Combination protocols integrating novel oral anticoagulants with cytoprotective agents for atrial fibrillation-related stroke risk reduction represent underdeveloped therapeutic whitespace.
- Telestroke network expansion:Hub-and-spoke models connecting comprehensive stroke centers with community hospitals via teleradiology and mobile stroke units create channel innovation for thrombolytic and diagnostic device distribution.
Industry Challenges
- Interventional neuroradiology workforce scarcity:Fellowship-trained specialists capable of mechanical thrombectomy concentrate in tertiary academic centers, constraining procedure penetration into community hospital settings.
- Real-world evidence harmonization:Divergent FDA, EMA, and PMDA requirements for post-market surveillance and patient registry data complicate global trial design and delay label expansion submissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Stroke Therapeutics Market |
| Market Size in 2026 | $34.8 Billion |
| Market Size in 2035 | $67.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thrombolytics, Antiplatelet Agents, Neuroprotective Agents, Anticoagulants, Surgical Devices Therapy Area: Ischemic Stroke, Hemorrhagic Stroke, Transient Ischemic Attack, Cerebral Venous Thrombosis End User: Hospitals, Specialized Stroke Centers, Rehabilitation Facilities, Ambulatory Surgical Centers Delivery Mode: Intravenous, Intra-arterial, Oral, Subcutaneous, Inhalation |
| Companies Covered | Boehringer Ingelheim, Bristol-Myers Squibb, AstraZeneca, Bayer, Pfizer, Johnson & Johnson, Genentech, Daiichi Sankyo, Merck & Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Stroke Therapeutics Market Shifts & Advancements
Artificial intelligence integration into stroke imaging workflows is compressing door-to-needle and door-to-puncture intervals, while next-generation neuroprotective agents target multiple ischemic cascade nodes simultaneously.
Artificial intelligence-powered large-vessel occlusion detection software is unifying CT angiography interpretation across emergency departments and comprehensive stroke centers. Community hospitals lacking on-site neuroradiology coverage deploy these platforms to accelerate transfer decisions. The technology is unifying diagnostic thresholds between hub-and-spoke networks, reducing inter-facility variation in thrombectomy eligibility determination.
The EU MDR's clinical evidence requirements are extending neurointerventional device approval timelines and expanding post-market surveillance obligations. Manufacturers must now generate prospective registry data beyond pre-market trials to maintain CE marking. European notified bodies are prioritizing review capacity toward high-risk Class III devices, creating backlog-induced delays for medium-risk stroke diagnostic platforms.
Hospital procurement for stroke devices is consolidating under value-analysis committees with cardiology and neurology joint representation. Single-source contracting for thrombectomy platforms is displacing device-agnostic purchasing in United States health systems. This concentration is most visible in integrated delivery networks across Texas and Florida, where stroke volume thresholds drive exclusive vendor arrangements with mechanical retrieval device manufacturers.
Global Stroke Therapeutics Market Segmentation
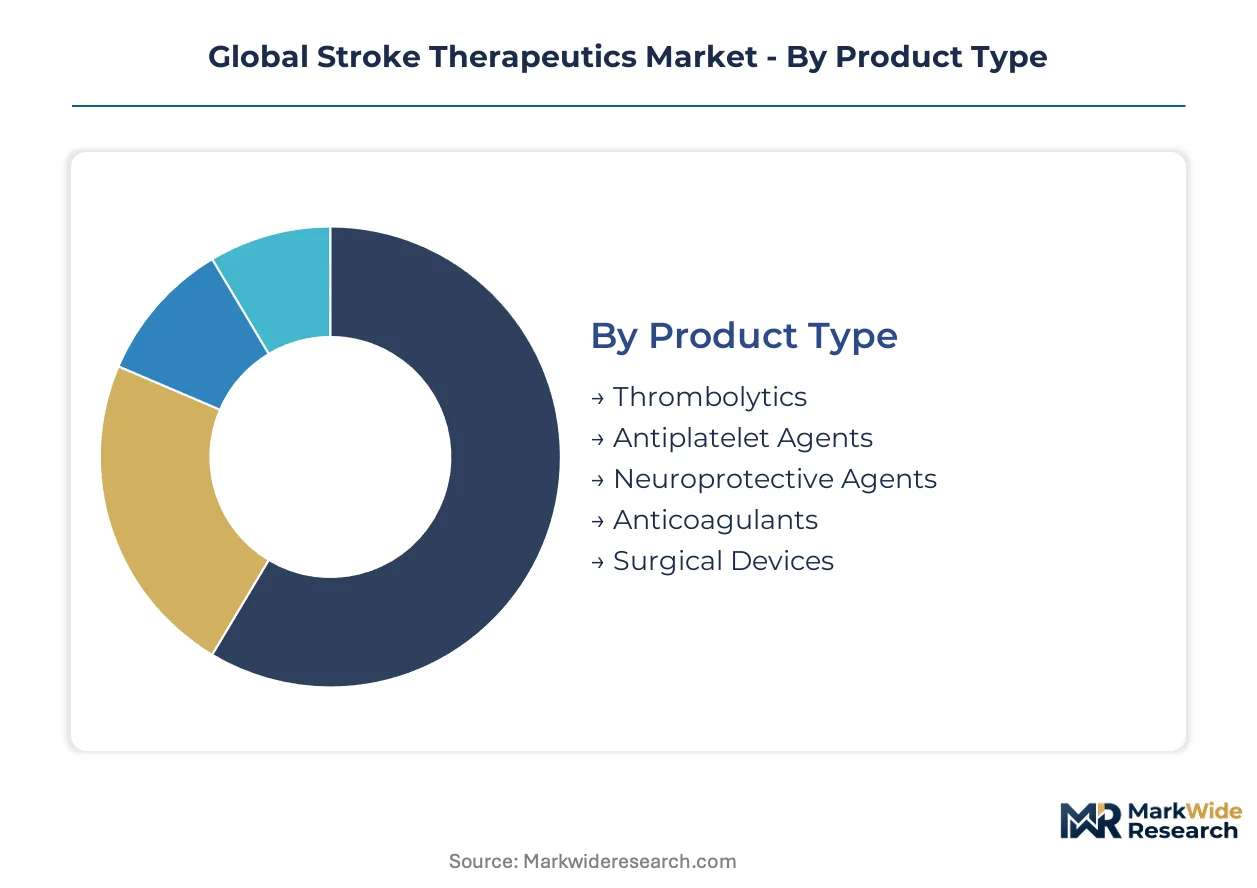
Stroke therapeutics segmentation reveals divergent margin profiles across pharmacological and interventional modalities, with mechanical devices commanding premium pricing while thrombolytics face volume-driven commoditization pressures.
Product Type:
Thrombolytics anchor global procedure volumes while neuroprotective agents capture the steepest pricing premiums per treated patient.
- Thrombolytics:Recombinant tissue plasminogen activator and tenecteplase formulations dominate emergency department formularies with standardized dosing protocols. United States urban stroke centers drive demand concentration, though reimbursement compression under Medicare's inpatient prospective payment system constrains manufacturer margins.
- Neuroprotective Agents:Experimental compounds targeting excitotoxicity, oxidative stress, and inflammatory cascades occupy pipeline stages from Phase II through regulatory submission. Japan's PMDA streamlined pathways for regenerative therapies accelerate commercialization timelines for stem-cell-based candidates addressing ischemic penumbra salvage.
- Antiplatelet Agents:Aspirin, clopidogrel, and ticagrelor maintain post-stroke secondary prevention protocols with generic penetration thinning branded returns.
- Anticoagulants:Direct oral anticoagulants displace warfarin for atrial fibrillation-related stroke prophylaxis in Germany and United States cardiology practices.
- Surgical Devices:Stent retrievers, aspiration catheters, and embolic protection systems command five-figure pricing per mechanical thrombectomy procedure.
Today's leader: Thrombolytics. Tomorrow's challenger: Neuroprotective Agents.
Therapy Area:
Ischemic stroke concentrates addressable patient populations while hemorrhagic stroke presents the most acute unmet therapeutic need.
- Ischemic Stroke:Large-vessel occlusions and small vessel disease account for the majority of pharmacological and interventional treatment volumes. Mechanical thrombectomy eligibility criteria continue expanding as imaging protocols improve patient selection beyond traditional time windows.
- Hemorrhagic Stroke:Intracerebral hemorrhage and subarachnoid hemorrhage lack disease-modifying therapies beyond blood pressure management and surgical evacuation. United States neurocritical care units drive demand for minimally invasive hematoma evacuation devices.
- Transient Ischemic Attack:ABCD2 scoring protocols guide antiplatelet and statin initiation in emergency department observation units.
- Cerebral Venous Thrombosis:Heparin anticoagulation remains standard of care with endovascular rescue reserved for deteriorating patients.
Ischemic applications generate current revenue concentration. Hemorrhagic modalities offer the deepest clinical whitespace for first-mover positioning.
End User:
Hospital infrastructure investments determine device procurement patterns while specialized stroke centers concentrate interventional procedure economics.
- Hospitals:General medical centers with emergency department stroke protocols administer the majority of intravenous thrombolytic doses. Germany's hospital reform programs are consolidating stroke unit certification requirements across federal state healthcare systems.
- Specialized Stroke Centers:Comprehensive stroke centers with 24/7 interventional neuroradiology coverage capture mechanical thrombectomy reimbursement premiums. Japan designates specific institutions for advanced stroke care through Ministry of Health, Labour and Welfare certification pathways.
- Rehabilitation Facilities:Post-acute settings focus on neuroplasticity optimization and secondary prevention medication adherence.
- Ambulatory Surgical Centers:Limited stroke therapeutics penetration due to emergency presentation requirements and imaging infrastructure needs.
Specialized centers concentrate margin capture. Hospital networks expand access breadth.
Delivery Mode:
Intravenous administration dominates emergency settings while intra-arterial delivery enables localized intervention for large-vessel occlusions.
- Intravenous:Peripheral catheter delivery of thrombolytics enables treatment initiation in community emergency departments without neuroradiology coverage. Door-to-needle time metrics drive formulary standardization across United States hospital systems participating in Get With The Guidelines stroke quality programs.
- Intra-arterial:Catheter-based drug delivery and mechanical retrieval access proximal clot locations in middle cerebral artery and internal carotid artery territories. Specialized stroke centers in Japan and Germany report superior recanalization rates with combined intravenous-intra-arterial protocols.
- Oral:Antiplatelet and anticoagulant maintenance therapy supports long-term secondary prevention.
- Subcutaneous:Low-molecular-weight heparin bridges anticoagulation in specific clinical scenarios.
- Inhalation:Investigational neuroprotective delivery routes target rapid blood-brain barrier penetration.
Intravenous routes anchor volume scale. Intra-arterial modalities concentrate value extraction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fellowship-trained interventional neuroradiologists concentrate in tertiary academic centers across the United States, Germany, and Japan, anchoring mechanical thrombectomy capacity and creating geographic disparities in stroke intervention access.
United States
Comprehensive stroke centers in Texas and Florida drive exclusive vendor contracting for mechanical retrieval devices through integrated delivery networks. The FDA breakthrough device designation pathway accelerates market access for novel neurointerventional platforms. The Greater Boston cluster anchors neuroprotective agent development with proximity to academic medical centers running Phase III excitotoxicity trials.
Germany
Hospital reform programs consolidate stroke unit certification requirements across federal state healthcare systems, standardizing thrombolytic formulary deployment. The EU MDR extends neurointerventional device approval timelines through expanded clinical evaluation obligations. The North Rhine-Westphalia industrial corridor concentrates catheter manufacturing for European stent retriever supply.
Japan
Ministry of Health, Labour and Welfare certification pathways designate specific institutions for advanced stroke care, concentrating mechanical thrombectomy economics. The PMDA streamlined review framework compresses development timelines for stem-cell-based neuroprotective therapies. The Kanto region around Tokyo anchors regenerative medicine commercialization with proximity to academic medical centers.
China
Priority review channels at the NMPA accelerate innovative neurological drugs addressing unmet needs, attracting first-mover neuroprotective development. Aging demographics in coastal provinces expand addressable patient populations for anticoagulant stroke prophylaxis. The Yangtze River Delta cluster concentrates diagnostic imaging equipment manufacturing serving domestic hospital procurement.
United Kingdom
NHS England stroke service reconfiguration centralizes thrombectomy capacity in hyper-acute stroke units, consolidating device procurement volumes. The MHRA operates post-Brexit regulatory autonomy while maintaining alignment with EMA scientific standards. The London-Southeast corridor anchors clinical trial infrastructure for novel oral anticoagulant development programs.
Global Stroke Therapeutics Market Competitive Landscape
The competitive structure tilts toward well-capitalized incumbents with established post-market surveillance infrastructure. Tiered differentiation separates thrombolytic volume leaders from neuroprotective pipeline specialists and interventional device premium-positioned players. Consolidation pressures intensify as EU MDR compliance costs force mid-scale neurointerventional suppliers toward acquisition or exit. Dominant competitive moves include strategic partnerships for real-world evidence generation and geographic expansion through telestroke network integration.
Within the pharmaceutical archetype, Boehringer Ingelheim leverages thrombolytic heritage to anchor European hospital formularies, while Bristol-Myers Squibb competes through anticoagulant portfolio breadth across ischemic stroke prevention channels. Daiichi Sankyo occupies a specialist position in novel oral anticoagulant development, particularly for atrial fibrillation-related stroke risk reduction. These three represent the dominant strategic postures: legacy thrombolytic anchoring, portfolio breadth competition, and targeted specialty indication focus.
| Leading Market Players |
|---|
| Boehringer Ingelheim |
| Bristol-Myers Squibb |
| AstraZeneca |
| Bayer |
| Pfizer |
| Johnson & Johnson |
| Genentech |
| Daiichi Sankyo |
| Merck & Co. |
| Others |
Supply & Pricing Matrix
Integrated delivery networks in Texas and Florida anchor procurement concentration for mechanical thrombectomy platforms, driving exclusive vendor contracting that collapses pricing into bundled per-procedure fees rather than device-unit transactions. This buyer consolidation reshapes supplier economics across the United States, Germany, and Japan where stroke unit expansion concentrates purchasing power.
Pricing Analysis
Bundled service contracts for mechanical thrombectomy procedures dominate United States comprehensive stroke centers, while unbundled device pricing persists in European hospital systems with fragmented procurement. Three-tier pricing structure across premium aspiration catheters, standard stent retrievers, and economy thrombolytic vials reflects FDA breakthrough designation premiums and generic tenecteplase commoditization. Cost compression in intravenous thrombolytics intensifies because Medicare's inpatient prospective payment system constrains manufacturer margins. Community emergency departments exhibit highest price sensitivity due to formulary standardization mandates, while specialized stroke centers absorb premium device pricing through reimbursement carve-outs.
Supply Chain Analysis
Reverse-logistics flows for explanted stent retrievers and used aspiration catheters remain underdeveloped, though EU MDR post-market surveillance obligations are forcing manufacturers to establish device-traceability systems that could enable refurbishment pathways. Nitinol superelastic alloy supply for neurointerventional devices concentrates in the United States, Germany, and Japan, with shape-memory wire drawing anchored in the North Rhine-Westphalia industrial corridor. Device manufacturing draws from platinum-iridium radiopaque marker sources, polymer extrusion capabilities, and cleanroom assembly capacity. Single-source vulnerability in nitinol ingot supply exposes stent retriever manufacturers to allocation risk during aerospace demand spikes. Distribution runs through hospital value-analysis committees with joint cardiology-neurology representation, displacing traditional distributor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
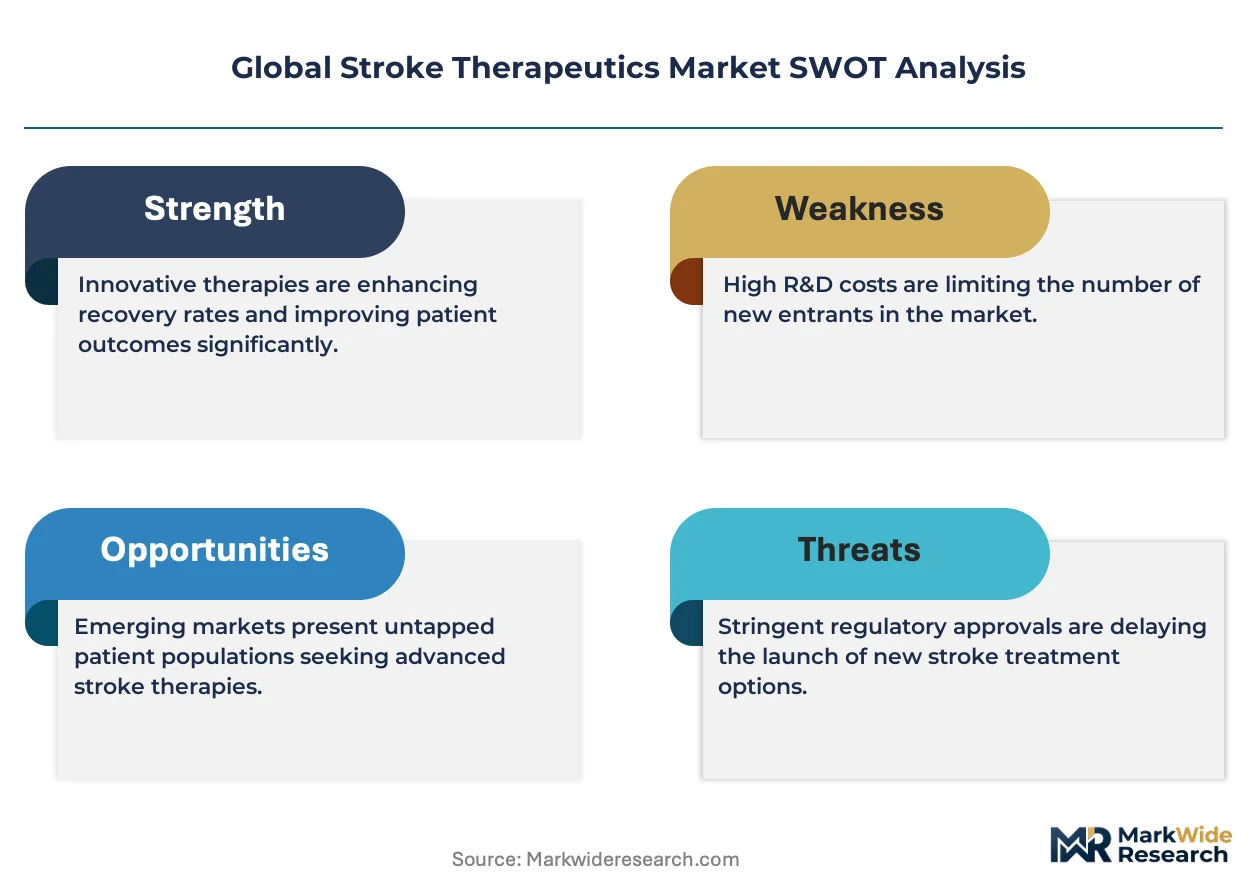
The Global Stroke Therapeutics Market represents a late-cycle quality story where mechanical thrombectomy eligibility expansion and neuroprotective pipeline maturation are shifting demand toward premium interventional platforms and regenerative therapies with superior outcome profiles.
For Market Incumbents: Extend post-market surveillance infrastructure investments to satisfy EU MDR expanded clinical evidence requirements and consolidate notified body relationships before capacity constraints worsen. Acquire mid-scale neurointerventional suppliers facing compliance cost pressures to capture mechanical thrombectomy device portfolios and interventional neuroradiology specialist networks. Vertical integration into nitinol wire drawing and shape-memory alloy processing reduces input cost volatility for stent retriever manufacturing. For New Entrants and Emerging Players: The price-point gap between premium mechanical thrombectomy platforms and economy thrombolytic formularies creates entry space for hybrid intravenous-intra-arterial protocol devices. Target community hospital telestroke networks in the United States and Germany where hub-and-spoke models concentrate transfer volumes but lack on-site interventional capacity. Pursue PMDA streamlined review pathways for stem-cell-based neuroprotective candidates targeting excitotoxicity cascades in Japan's designated advanced stroke care institutions. For Investors and Strategic Acquirers: Large-cap pharmaceutical companies with anticoagulant portfolios are the most active acquirers in this space, seeking mechanical thrombectomy device capabilities to complement stroke prevention franchises. Five-to-ten year viability hinges on neuroprotective agent commercialization timelines and real-world evidence harmonization across FDA, EMA, and PMDA jurisdictions. Monitor Phase III readouts for excitotoxicity-targeting compounds as inflection indicators for pipeline valuation repricing.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | CE marking retention for Class III neurointerventional devices requires expanded clinical evaluation and post-market surveillance systems. |
| Hospital System Partnership | Exclusive vendor contracting with integrated delivery networks in Texas and Florida secures mechanical thrombectomy volume commitments. |
| PMDA Streamlined Review Pursuit | Accelerated pathways for regenerative neuroprotective therapies compress development timelines for stem-cell-based candidates in Japan. |
| Telestroke Network Integration | Hub-and-spoke model partnerships expand thrombolytic and diagnostic device distribution into community hospital emergency departments. |
| Real-World Evidence Generation | Prospective registry data beyond pre-market trials satisfies EMA adaptive licensing and FDA breakthrough device post-approval requirements. |
Research Methodology
Multiple input streams — primary interviews with interventional neuroradiologists and hospital procurement managers, secondary validation through FDA 510(k) filings and EMA submission databases, and trade data reconciliation — were synthesized to construct market estimates. Conversations with formulary directors at comprehensive stroke centers, GPO contracts managers, and biomedical engineers informed device adoption timelines and pricing dynamics. Secondary sources included ClinicalTrials.gov stroke therapy registrations, CMS Medicare reimbursement schedules, and hospital procurement database extracts. Bottom-up procedure volume modeling and top-down pharmaceutical revenue triangulation cross-validated segment-level outputs.
Historical mechanical thrombectomy procedure growth patterns were cross-referenced against expert panel inputs from stroke system administrators and neurointerventional device manufacturers across the analysis window. Segmentation modeling incorporated therapy area, delivery mode, end-user facility type, and regional regulatory cluster dimensions. CAGRs were derived from elasticity-adjusted adoption curves and reimbursement scenario testing. Forecast inputs included EU MDR implementation pace, PMDA regenerative medicine review timelines, and hospital stroke unit certification expansion trajectories.
Caveats apply where regulatory harmonization delays, interventional neuroradiology workforce scarcity, or nitinol supply disruptions could materially shift the outlook. Practitioners should monitor Phase III neuroprotective trial readouts, notified body capacity allocation decisions, and telestroke network reimbursement policy developments for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Acute Hepatic Porphyria (APH) Market
Specialty Medicine
Cholangitis Market
Specialty Medicine
Intussusception Market
Specialty Medicine
Europe Precision Medicine Market
Specialty Medicine
Pituitary Stalk Interruption Syndrome Treatment Market
Specialty Medicine
Global Bladder Disorders Market
Specialty Medicine
Psoriatic Arthritis (Psa) Treatment Market
Specialty Medicine
Bartonellosis Therapeutics Market
Specialty Medicine
Multiple Sclerosis Market
Specialty Medicine
Hemifacial Spasm Market
Specialty Medicine
Respiratory Syncytial Virus (RSV) Therapeutics Market
Specialty Medicine
Osteogenesis Imperfecta Treatment Market
Specialty Medicine
Piriformis Syndrome Treatment Market
Specialty Medicine
Global Liver Cancer Therapeutics Market
Specialty Medicine
Cutaneous Fibrosis Treatment Market
Specialty Medicine
Hyperuricemia Market