
 Hepatic Encephalopathy Market | 2026-2036
Hepatic Encephalopathy Market Size, Share, and Industry Trends Forecast 2026-2036
Hepatic Encephalopathy Market Outlook
A capital-intensity divergence between large-cap pharmaceutical manufacturers and mid-size specialty firms is redrawing competitive boundaries in hepatic encephalopathy therapeutics. Mallinckrodt Pharmaceuticals leverages its established hospital channel relationships to sustain formulary positioning for acute intervention therapies. ASKA Pharmaceutical Co., Ltd. anchors its presence in East Asian markets through region-specific ammonia scavenger formulations. Takeda Pharmaceutical Company Limited competes on global manufacturing scale for lactulose-based maintenance therapies.
Hepatic encephalopathy constitutes a neuropsychiatric syndrome arising from liver dysfunction, characterized by elevated blood ammonia levels that disrupt astrocyte metabolism and cerebral blood flow regulation; its primary clinical purpose centers on preventing progression from subclinical cognitive impairment to overt coma in cirrhotic patients. Pharmaceuticals dominates product type revenue, with lactulose and rifaximin capturing the majority of maintenance and recurrence-prevention prescriptions. Diagnostic Kits represents the fastest-expanding segment, as point-of-care ammonia testing and computerized psychometric tools displace slower laboratory workflows. Hospitals anchor end-user demand, though Home Care is gaining traction as oral therapies enable outpatient management of stable chronic cases.
The FDA's orphan drug designation program and the EMA's conditional marketing authorization framework both accelerate entry for novel ammonia-lowering mechanisms, while the EPA monitors environmental discharge from active pharmaceutical ingredient manufacturing. Japan's PMDA imposes stringent pharmacovigilance requirements on hepatic encephalopathy therapies given the elderly cirrhotic population's comorbidity burden. Stakeholders must monitor regulatory divergence between stringent neuropsychiatric safety requirements in developed markets and evolving pharmacovigilance standards in high-volume emerging economies.
Market Dynamics
Hospital formulary committees now prioritize ammonia-lowering protocols that reduce 30-day readmission penalties, compressing procurement cycles for acute intervention therapies and favoring suppliers with integrated care pathway documentation.
Growth Catalysts
- Orphan Drug Incentives:The FDA's orphan drug designation program accelerates development timelines for novel ammonia scavengers by granting tax credits and seven-year market exclusivity to qualifying therapies.
- Point-of-Care Testing:Portable ammonia analyzers are reducing diagnostic turnaround from hours to minutes in emergency departments, enabling earlier intervention and expanding addressable patient populations.
- Japan:PMDA's streamlined review pathways for drugs addressing unmet needs in elderly cirrhotic populations are attracting development investment toward region-specific formulations.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:Lactulose API production concentrates among Indian and Chinese contract manufacturers, exposing formulators to import tariff volatility and supply disruption risk.
- Reimbursement Compression:CMS hospital outpatient prospective payment system rate adjustments are narrowing margins for acute hepatic encephalopathy interventions administered in infusion centers.
- Diagnostic Substitution:Psychometric screening tools are displacing some blood ammonia testing volumes in subclinical case detection, constraining companion diagnostic revenue streams.
Strategic Opportunities
- Home Care Transition:Oral maintenance therapies enabling stable chronic patient management outside hospital settings are opening reimbursement negotiations with Medicare Advantage plans for remote monitoring bundles.
- EMA Conditional Authorization:The conditional marketing authorization framework allows novel mechanisms to reach European Union markets while confirmatory trials continue, compressing time-to-revenue for innovators.
- Digital Therapeutics Convergence:Smartphone-based cognitive assessment apps paired with pharmacotherapy are creating integrated disease management platforms eligible for digital health reimbursement codes.
Industry Challenges
- Specialized Hepatology Nursing Shortage:Complex ammonia-lowering protocol administration requires trained personnel that tertiary medical centers struggle to recruit and retain.
- Multinational Trial Complexity:Divergent neuropsychiatric safety endpoints across FDA, EMA, and PMDA guidelines are extending clinical development timelines and inflating study costs.
- Legacy IT Integration:Electronic health record systems at community hospitals lack standardized hepatic encephalopathy severity scoring modules, complicating quality metric reporting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hepatic Encephalopathy Market |
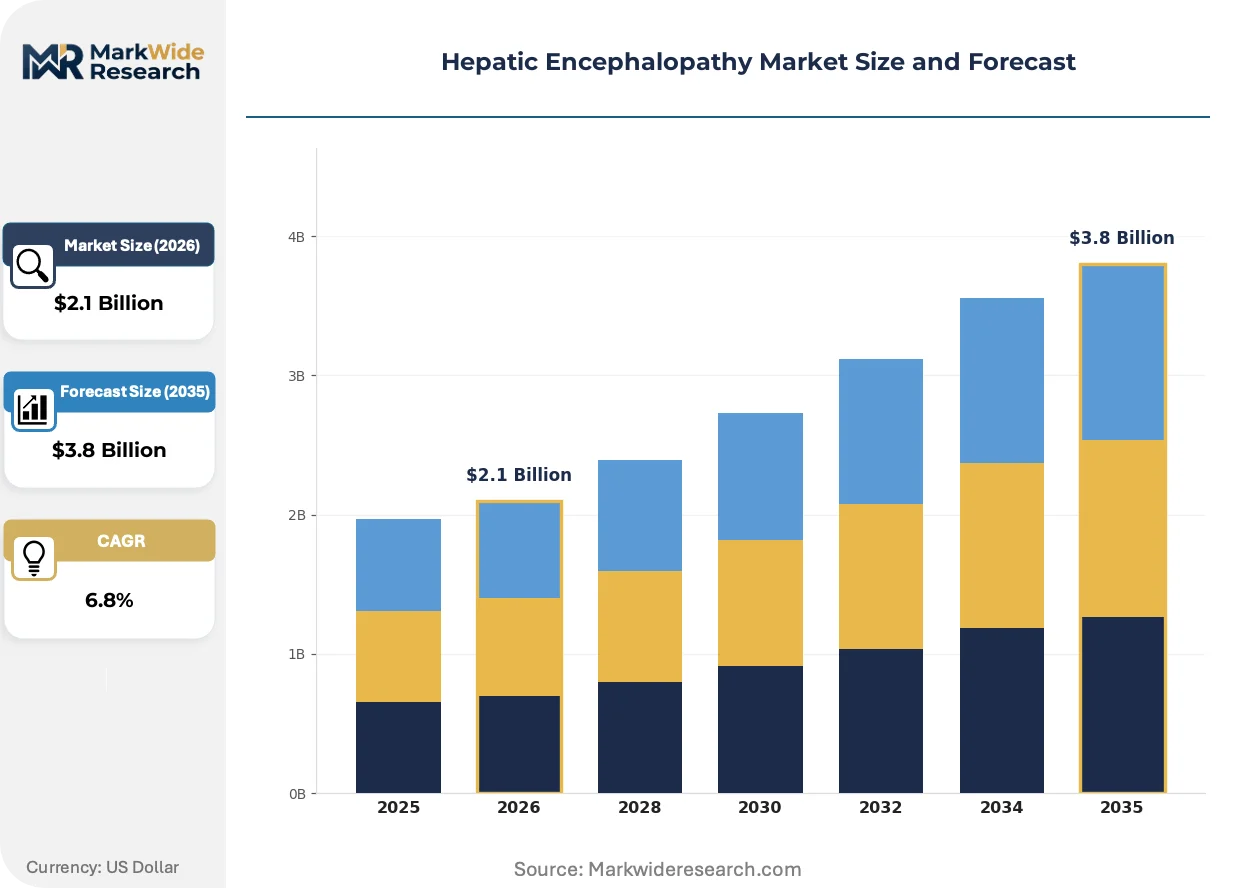
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmaceuticals, Nutraceuticals, Therapeutic Devices, Diagnostic Kits End User: Hospitals, Clinics, Home Care, Long-term Care Facilities Treatment Type: Medications, Dietary Interventions, Cognitive Therapy, Supportive Care Stage of Disease: Acute, Chronic, Recurrent, Precipitating Factors |
| Companies Covered | GlaxoSmithKline plc., ASKA Pharmaceutical Co., Ltd., Mallinckrodt Pharmaceuticals, Takeda Pharmaceutical Company Limited, Cosmo Pharmaceuticals N.V., Salix Pharmaceuticals, Pfizer Inc., Merck & Co., Inc., Bausch Health Companies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hepatic Encephalopathy Market Strategic Shifts
Technology convergence between diagnostic platforms and therapeutic monitoring is compressing the interval between symptom onset and clinical intervention, reshaping competitive advantage toward integrated system suppliers.
Continuous ammonia monitoring biosensors are supplanting intermittent venous blood draws in intensive care settings. Critical care units at academic medical centers in Germany and the United States are piloting subcutaneous sensors that transmit real-time data to nursing stations. This capability is enabling closed-loop dosing algorithms that reduce nursing workload and compress length-of-stay metrics.
The EMA's revised guideline on clinical investigation of hepatic encephalopathy mandates computerized neuropsychometric testing as a primary endpoint, displacing subjective clinical grading scales. European trial sponsors must now validate digital cognitive assessment platforms against historical West-Haven criteria. This regulatory shift favors developers with established partnerships with psychometric software vendors and compresses timelines for protocols designed around paper-based instruments.
Hospital procurement committees are unbundling acute intervention therapies from bundled payment contracts and negotiating standalone value-based agreements with manufacturers. Gastroenterology service lines at US academic medical centers are leading this transition, replacing fee-for-service purchasing with episode-of-care guarantees that tie reimbursement to 90-day readmission avoidance. This restructuring concentrates purchasing power within integrated delivery networks and marginalizes standalone community hospital buyers.
Hepatic Encephalopathy Market Segmentation
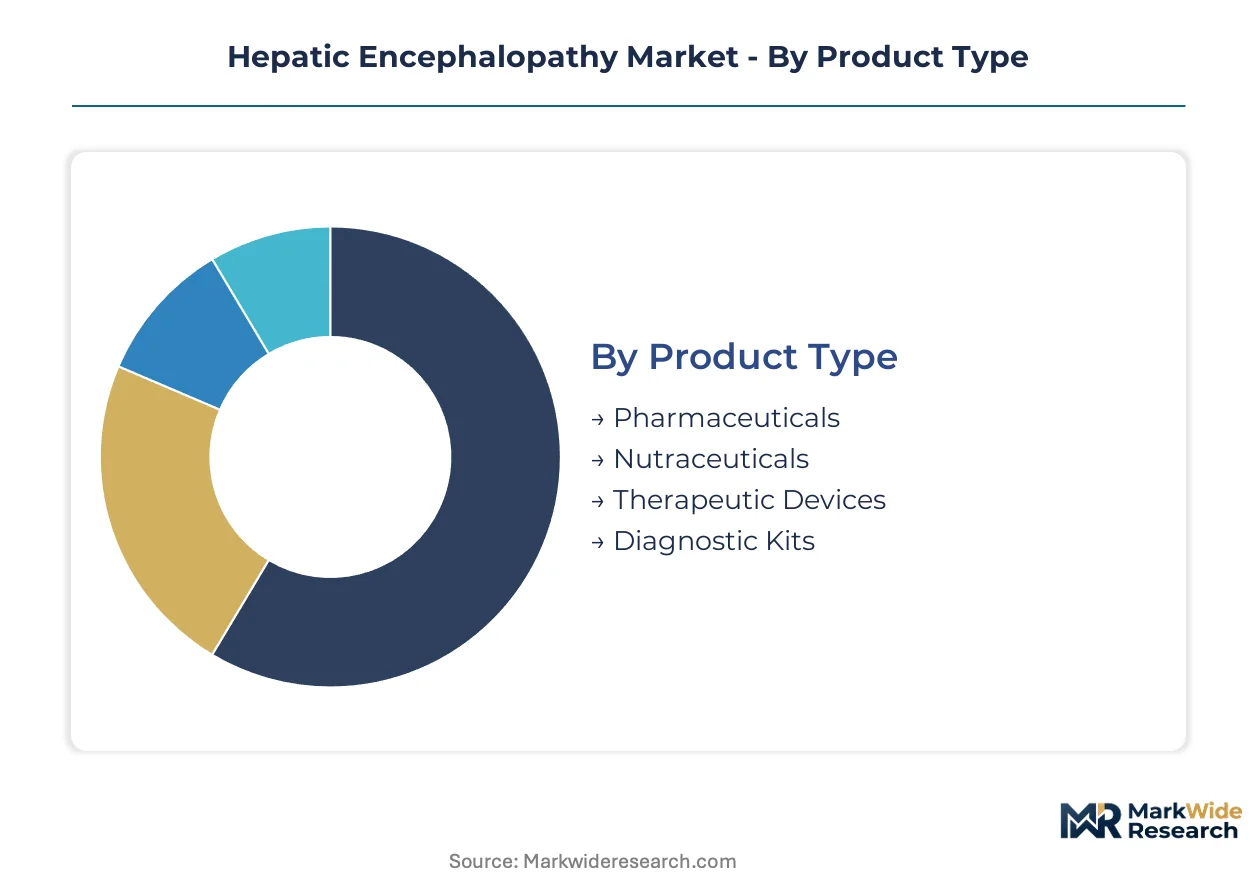
Hepatic encephalopathy treatment pathways fragment across intervention modalities, care settings, and disease severity strata. Procurement committees and prescribing specialists prioritize different segment combinations based on readmission risk profiles and reimbursement architecture.
Product Type:
Pharmaceuticals concentrate the highest margin pools through maintenance therapy prescriptions and acute intervention protocols.
- Pharmaceuticals:Lactulose and rifaximin formulations dominate maintenance and recurrence-prevention prescribing. Hospital-based gastroenterology departments in the United States drive volume through ammonia-lowering protocols integrated into cirrhosis care pathways.
- Diagnostic Kits:Point-of-care ammonia analyzers and computerized psychometric tools are displacing slower laboratory workflows. Emergency departments at academic medical centers in Germany and the United States are piloting portable systems that reduce diagnostic turnaround from hours to minutes.
- Therapeutic Devices:Continuous ammonia monitoring biosensors enable closed-loop dosing algorithms in intensive care settings.
- Nutraceuticals:Branched-chain amino acid formulations target malnutrition correction in cirrhotic populations.
Pharmaceuticals hold installed capacity. Diagnostic Kits is rotating up the share rankings.
End User:
Volume concentration tilts toward institutional buyers with integrated care pathway documentation and value-based contracting capability.
- Hospitals:Tertiary medical centers with specialized hepatology nursing staff administer complex ammonia-lowering protocols. Gastroenterology service lines at US academic medical centers are negotiating episode-of-care guarantees that tie reimbursement to 90-day readmission avoidance.
- Home Care:Oral maintenance therapies enable stable chronic patient management outside hospital settings. Medicare Advantage plans are opening reimbursement negotiations for remote monitoring bundles covering stable cirrhotic populations.
- Clinics:Community gastroenterology practices manage subclinical cases through psychometric screening and blood ammonia monitoring.
- Long-term Care Facilities:Skilled nursing facilities handle post-acute transitions for recurrent hepatic encephalopathy patients.
Hospitals anchor procurement volume. Home Care is climbing the fastest as oral therapy protocols expand.
Treatment Type:
Reimbursement codes and clinical guidelines favor pharmacological interventions over supportive modalities.
- Medications:Ammonia scavengers and gut microbiome modulators constitute the evidence-based standard of care. The FDA's orphan drug designation program accelerates development timelines for novel mechanisms by granting tax credits and seven-year market exclusivity.
- Dietary Interventions:Protein restriction protocols and branched-chain amino acid supplementation address malnutrition-driven ammonia production. Japanese PMDA guidelines emphasize nutritional management given the elderly cirrhotic population's comorbidity burden.
- Cognitive Therapy:Neuropsychiatric rehabilitation targets residual deficits in recurrent cases.
- Supportive Care:Electrolyte management and infection control address precipitating factors.
Medications command formulary priority. Dietary Interventions is gaining protocol integration in East Asian markets.
Stage of Disease:
Pricing power concentrates in acute intervention where readmission penalties create urgency.
- Acute:Overt hepatic encephalopathy with altered consciousness requires immediate ammonia-lowering intervention. Hospital formulary committees prioritize protocols that reduce 30-day readmission penalties, compressing procurement cycles.
- Chronic:Persistent subclinical cognitive impairment demands maintenance therapy to prevent progression. Outpatient management through oral lactulose and rifaximin enables Home Care transition.
- Recurrent:Multiple episodes within defined timeframes trigger secondary prophylaxis intensification.
- Precipitating Factors:Infection, bleeding, and electrolyte disturbance management prevents decompensation.
Acute holds the premium pricing tier. Chronic is expanding most quickly as screening protocols capture subclinical populations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in hepatic encephalopathy therapeutics tilts toward the United States, where liver disease prevalence and specialized care infrastructure sustain premium reimbursement, while Japanese and European markets operate under tighter cost-containment regimes that compress margins for maintenance therapies.
United States
Hospital-based gastroenterology departments drive acute intervention volume through ammonia-lowering protocols integrated into cirrhosis care pathways. The FDA's orphan drug designation program accelerates novel ammonia scavenger development by granting seven-year market exclusivity to qualifying therapies. Academic medical centers in Boston and the Research Triangle pilot episode-of-care guarantees that tie manufacturer reimbursement to 90-day readmission avoidance.
Germany
Critical care units at university hospitals pioneer continuous ammonia monitoring biosensors that enable closed-loop dosing algorithms and reduce nursing workload. The EMA's revised guideline mandates computerized neuropsychometric testing as a primary endpoint, displacing subjective clinical grading scales in European trials. Medical technology clusters in Munich and Heidelberg validate digital cognitive assessment platforms against historical West-Haven criteria.
Japan
An elderly cirrhotic population with substantial comorbidity burden sustains demand for region-specific ammonia scavenger formulations. PMDA imposes stringent pharmacovigilance requirements that extend post-market surveillance obligations for hepatic encephalopathy therapies. Pharmaceutical development concentrates in the Kanto region, where streamlined review pathways for unmet needs attract investment toward geriatric-optimized dosing regimens.
India
Lactulose active pharmaceutical ingredient production concentrates among contract manufacturers serving global formulators with cost-competitive supply. The country's national pharmaceutical regulator enforces Good Manufacturing Practice standards that govern export eligibility to regulated markets. Manufacturing clusters in Gujarat and Maharashtra face exposure to import tariff volatility and supply disruption risk from concentrated API sourcing.
United Kingdom
Integrated care systems negotiate value-based agreements that unbundle acute intervention therapies from bundled payment contracts. NHS England's specialized commissioning frameworks prioritize protocols demonstrating measurable reduction in 30-day readmission penalties. London-based gastroenterology service lines lead procurement restructuring toward episode-of-care guarantees that concentrate purchasing power within academic medical center networks.
Hepatic Encephalopathy Market Competitive Environment
Concentration sits with diversified pharmaceutical conglomerates possessing established hospital channel relationships and global manufacturing scale for lactulose-based maintenance therapies. Large-cap manufacturers leverage formulary positioning and integrated care pathway documentation to defend procurement cycles, while mid-size specialty firms compete on region-specific formulations and orphan drug exclusivity windows. Strategic archetypes include hospital-centric acute intervention suppliers, East Asian market specialists, and global maintenance therapy scale players. Competitive moves center on M&A to capture point-of-care diagnostic integration and strategic partnerships to secure continuous monitoring biosensor distribution.
Within the hospital-centric tier, Mallinckrodt Pharmaceuticals and Salix Pharmaceuticals exemplify acute intervention positioning through established formulary relationships and integrated care pathway documentation. ASKA Pharmaceutical Co., Ltd. occupies a specialist position anchored in East Asian markets through region-specific ammonia scavenger formulations. Takeda Pharmaceutical Company Limited represents global manufacturing scale archetypes competing on lactulose-based maintenance therapy volume and distribution reach across multiple regulatory jurisdictions.
| Leading Market Players |
|---|
| GlaxoSmithKline plc. |
| ASKA Pharmaceutical Co., Ltd. |
| Mallinckrodt Pharmaceuticals |
| Takeda Pharmaceutical Company Limited |
| Cosmo Pharmaceuticals N.V. |
| Salix Pharmaceuticals |
| Pfizer Inc. |
| Merck & Co., Inc. |
| Bausch Health Companies Inc. |
| Others |
Value Chain & Pricing Dynamics
Point-of-care ammonia analyzers replacing centralized laboratory workflows simultaneously shift supply geography toward device manufacturing clusters in Germany and the United States while compressing diagnostic pricing premiums that previously sustained hospital laboratory profit pools. This substitution dynamic redistributes value capture from reagent suppliers to sensor manufacturers and forces traditional lactulose formulators to defend maintenance therapy margins through volume contracting rather than clinical premium positioning.
Pricing Analysis
The customization-premium spread between standard lactulose formulations and patient-specific ammonia scavenger dosing regimens spans roughly 3-4x at hospital procurement, with acute intervention therapies commanding the upper tier through readmission risk guarantees. Price differentiation hinges on FDA orphan drug exclusivity status and the depth of integrated care pathway documentation bundled with supply contracts. Pricing pressure stems from CMS outpatient prospective payment system rate compression that narrows infusion center margins for acute interventions. Community hospital buyers exhibit highest price sensitivity due to exclusion from episode-of-care guarantee negotiations, while academic medical center networks leverage volume concentration for preferential tier placement.
Supply Chain Analysis
Just-in-time inventory strategies dominate ammonia scavenger distribution to hospital pharmacies, though strategic stockpiling of lactulose API persists among Indian and Chinese contract manufacturers to buffer against monsoon season production disruptions. Geographic supply concentration centers on India and China for active pharmaceutical ingredients, the United States for finished formulation and device assembly, and Germany for continuous monitoring biosensor prototyping. Raw material dependencies include synthetic sugars for lactulose synthesis, specialized polymers for subcutaneous sensor membranes, and high-purity reagents for point-of-care test cartridges. Single-source vulnerability concentrates in lactulose API production where three contract manufacturers serve global formulator demand. Distribution runs through integrated delivery networks that consolidate purchasing power within academic medical center systems and marginalize standalone community hospital buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hepatic encephalopathy market sits at an inflection where continuous ammonia monitoring biosensors and closed-loop dosing algorithms threaten to commoditize traditional pharmacotherapy maintenance revenues, creating urgency for positioning adjustments across stakeholder categories.
For Market Incumbents: Secure formulary positioning through exclusive integrated care pathway documentation partnerships with academic medical center networks before episode-of-care guarantee contracts solidify around rival suppliers. Deepen backward integration into point-of-care diagnostic distribution to capture value migrating from therapeutics to monitoring platforms, as biosensor-enabled closed-loop systems displace intermittent blood draws and compress nursing workload metrics that hospitals now prioritize in procurement scoring. For New Entrants and Emerging Players: Anchor in the home care transition segment where Medicare Advantage plans are piloting remote monitoring bundles for stable cirrhotic populations, a whitespace largely uncontested by hospital-centric incumbents. Target region-specific ammonia scavenger formulations for Japan's elderly cirrhotic demographic, where PMDA streamlined review pathways reward geriatric-optimized dosing regimens with accelerated market entry timelines unavailable in saturated Western acute intervention markets. For Investors and Strategic Acquirers: The market sits at a platform consolidation phase that favors acquirers of continuous monitoring biosensor technology with validated closed-loop algorithms and existing pilot deployments in German and US academic medical centers. Long-term viability across the projection horizon hinges on capturing diagnostic-therapeutic integration rather than standalone pharmaceutical scale. The signal to watch is FDA breakthrough device designation velocity for subcutaneous ammonia sensors, which would trigger rapid repricing of maintenance therapy-dependent assets and validate premium valuations for monitoring-platform targets.| Strategic Initiative | Industry Significance |
|---|---|
| Point-of-Care Diagnostic Integration | Captures value migrating from centralized laboratories to emergency department bedside testing workflows. |
| Orphan Drug Designation Pursuit | Secures seven-year exclusivity and tax credits for novel ammonia scavenger mechanisms under FDA incentives. |
| Episode-of-Care Guarantee Structuring | Aligns manufacturer reimbursement with hospital 90-day readmission avoidance metrics at US academic centers. |
| Continuous Monitoring Biosensor Development | Enables closed-loop dosing algorithms that reduce nursing workload and compress length-of-stay metrics. |
| Region-Specific Formulation Investment | Addresses Japan's elderly cirrhotic population through PMDA-streamlined geriatric dosing pathways. |
Study Parameters
Cross-validation between primary interviews with hospital formulary directors, hepatology nursing managers, and regulatory affairs specialists and secondary validation through FDA orphan drug designation filings, EMA conditional marketing authorization decisions, and CMS Medicare reimbursement code updates anchors the qualitative findings. Bottom-up demand modeling triangulates against top-down pharmaceutical shipment data and hospital procurement database extracts to constrain estimate variance.
Sensitivity analysis across the projection horizon tests forecast robustness against alternative scenarios for CMS rate adjustment timing and continuous monitoring biosensor adoption velocity. Segmentation dimensions include product type, end user setting, disease severity stage, and regional regulatory cluster. CAGRs derive from exponential smoothing of historical pharmaceutical volume trends adjusted for point-of-care diagnostic substitution effects and orphan drug exclusivity windows.
Decision-makers should treat outputs as directional under assumptions of stable orphan drug incentive structures and gradual biosensor reimbursement code expansion; material deviation would warrant model refresh. Revision becomes warranted when continuous ammonia monitoring biosensor FDA breakthrough designation velocity crosses thresholds that accelerate hospital procurement committee preference shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
US Optic Neuritis Market
Neurology
Neurodegenerative Disease Treatment Market
Neurology
Acute Repetitive Seizures Market
Neurology
Asia-Pacific Neurology Monitoring Market
Neurology
Sweden Neurology Devices Market
Neurology
Neurocognitive Assessment and Rehabilitation Market
Neurology
Spasticity Treatment Market
Neurology
Canada Neurology Devices Market
Neurology
Global Narcolepsy Therapeutics Market
Neurology
Brain Tumor Diagnosis and Treatments Market
Neurology
China Neurology Devices Market
Neurology
Lewy Body Dementia Treatment Market
Neurology
United States Neurology Devices Market
Neurology
Global Vertigo Treatment Market
Neurology
Benign Positional Vertigo Treatment Market
Neurology
South Korea Neurology Devices Market