
 Vesicoureteral Reflux Market | 2026-2036
Vesicoureteral Reflux Market Size, Share, and Industry Trends Forecast 2026-2036
Vesicoureteral Reflux Market Outlook
Pediatric urology fellowship training capacity is collapsing across North American academic medical centers, tightening the specialist pipeline that manages vesicoureteral reflux cases. Pfizer Inc. leverages its established pediatric antibiotic portfolio to sustain presence in medical therapy protocols. Takeda Pharmaceutical Company anchors its position through gastrointestinal-urology crossover research infrastructure. Novartis AG competes via nephrology-focused clinical development networks.
Vesicoureteral reflux denotes the retrograde flow of urine from the bladder into the ureters and renal pelvis, graded I-V by the International Reflux Study Committee based on calyceal dilation and ureteral tortuosity; this condition primarily serves pediatric diagnostic and interventional markets where preventing pyelonephritis and renal scarring drives clinical urgency. Endoscopic injection now leads product type deployment due to shorter recovery profiles compared to open surgical repair, while ureteral stenting occupies faster-growing niches in complex anatomical cases. Diagnostic imaging sustains foundational demand through voiding cystourethrogram protocols, though radiation exposure concerns are shifting preference toward contrast-enhanced ultrasound alternatives.
FDA pediatric device consortia and EMA pediatric investigation plans shape product development timelines, with both agencies mandating age-stratified safety data that extends regulatory pathways for novel injectable bulking agents. ISO 14155 clinical investigation standards govern trial conduct across participating sites, creating compliance cost barriers for smaller device developers. Stakeholders must monitor how payer coverage policies for endoscopic versus surgical approaches evolve, as reimbursement differentials will determine which treatment modalities achieve scalable clinical adoption.
Market Dynamics
Pediatric urology fellowship training capacity is collapsing across North American academic medical centers, tightening the specialist pipeline that manages vesicoureteral reflux cases and forcing device manufacturers to design for generalist operators.
Growth Catalysts
- FDA pediatric device consortia:Accelerated regulatory pathways for endoscopic injectable bulking agents reduce time-to-market for novel biomaterials targeting grade III-V reflux.
- Minimally invasive procedure adoption:Pediatric specialty centers in the United States, Germany, and Japan are standardizing endoscopic injection protocols that shorten recovery profiles versus open ureteral reimplantation.
- Contrast-enhanced ultrasound:Voiding cystourethrogram radiation exposure concerns are driving diagnostic imaging demand toward non-ionizing alternatives in European and North American pediatric nephrology clinics.
Market Restraints
- Specialist supply contraction:The declining number of fellowship-trained pediatric urologists limits case volume scalability in community hospital settings.
- ISO 14155 compliance costs:Clinical investigation standards create capital barriers for smaller device developers attempting multi-site pediatric safety trials.
- Antibiotic prophylaxis persistence:Medical management protocols continue to capture low-grade reflux cases, constraining interventional procedure penetration in initial diagnosis workflows.
Strategic Opportunities
- EMA pediatric investigation plans:Structured regulatory frameworks enable preemptive age-stratified trial design that accelerates European market access for novel bulking agents.
- Complex anatomical stenting:Ureteral stenting applications are expanding into duplex systems and neurogenic bladder populations previously managed with open reconstruction.
- Telemedicine follow-up protocols:Post-procedure monitoring via remote consultation is reducing geographic access barriers for families in rural United States regions distant from pediatric specialty centers.
Industry Challenges
- Reimbursement policy fragmentation:Payer coverage differentials between endoscopic and surgical approaches create adoption friction across United States state Medicaid programs.
- Long-term durability data requirements:Pediatric device regulations mandate extended follow-up periods that compress development timelines and inflate trial costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vesicoureteral Reflux Market |
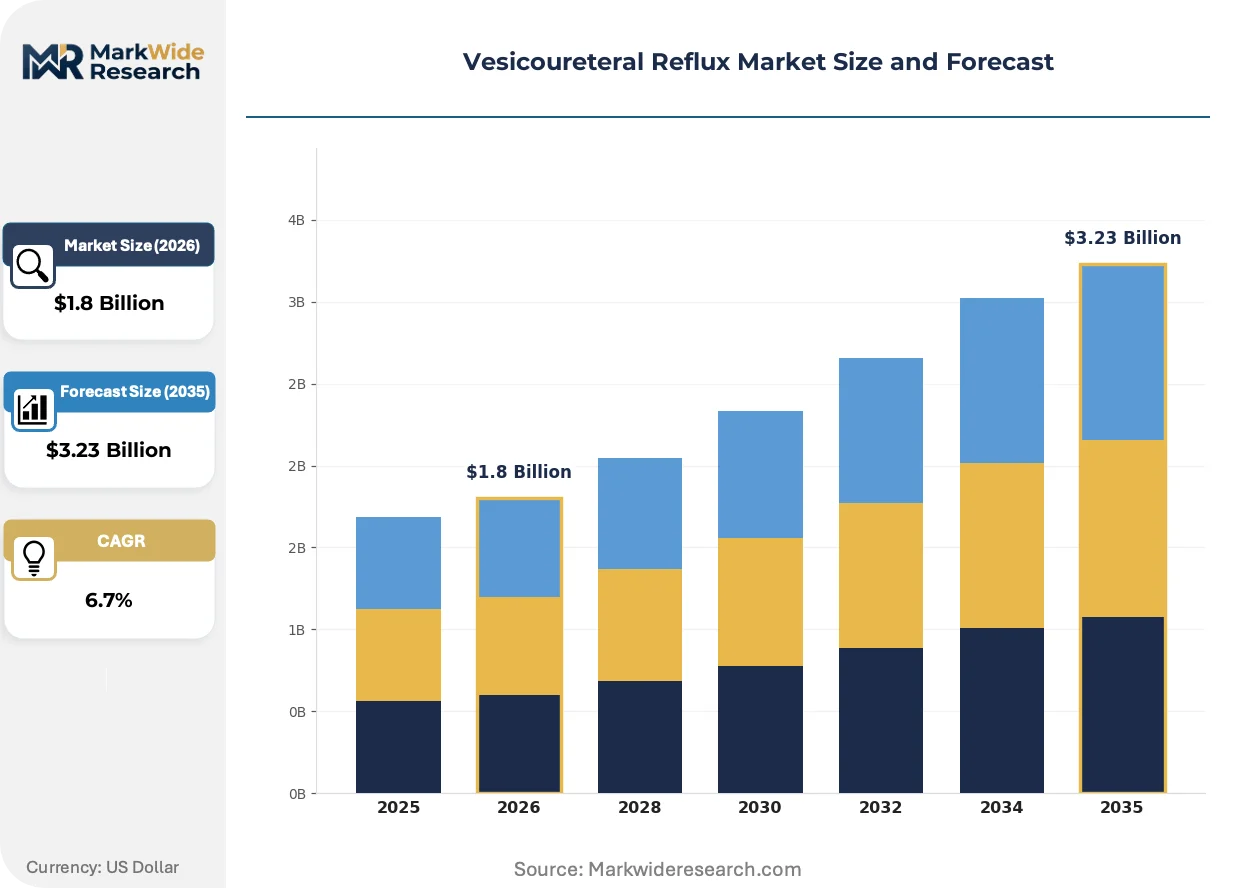
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Endoscopic Injection, Ureteral Stenting, Surgical Intervention, Diagnostic Imaging End User: Pediatric Clinics, Urology Hospitals, Research Facilities, Ambulatory Surgical Centers Treatment Approach: Minimally Invasive, Surgical Repair, Medical Therapy, Observation Severity Level: Mild, Moderate, Severe, Recurrent |
| Companies Covered | Pfizer Inc., Takeda Pharmaceutical Company, Merck & Co., Inc., Novartis AG, Abbott Laboratories, Johnson & Johnson, AstraZeneca, Boehringer Ingelheim GmbH, Sanofi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vesicoureteral Reflux Market Strategic Shifts
Bioresorbable bulking agents and radiation-sparing diagnostics are actively restructuring how vesicoureteral reflux is diagnosed, graded, and treated across pediatric care networks.
Injectable dextranomer/hyaluronic acid copolymers are displacing polytetrafluoroethylene-based bulking agents in endoscopic reflux correction due to superior biocompatibility profiles and reduced granuloma formation risk. Pediatric urology departments at academic medical centers in the United States and Germany are completing this transition within eighteen-month procurement cycles. The technology is displacing open surgical repair as first-line intervention for grades II-IV, compressing the addressable market for ureteral reimplantation hardware.
EMA pediatric investigation plans and FDA pediatric device consortia are mandating age-stratified safety databases that extend premarket approval timelines for novel injectable formulations. Device manufacturers must now enroll neonatal, infant, and adolescent cohorts separately, multiplying per-study costs. European notified bodies are applying these requirements most stringently to subureteric injection systems, forcing developers to prioritize transurethral delivery platforms.
Parental preference for same-day discharge is compressing institutional commitment to overnight observation following endoscopic procedures. Freestanding pediatric surgery centers in the United States are capturing cases previously routed to hospital-based operating rooms, unbundling facility fees from specialist professional charges. This channel shift is most visible in Texas, Florida, and California markets where ambulatory surgery center certificate-of-need restrictions are minimal.
Vesicoureteral Reflux Market Segmentation
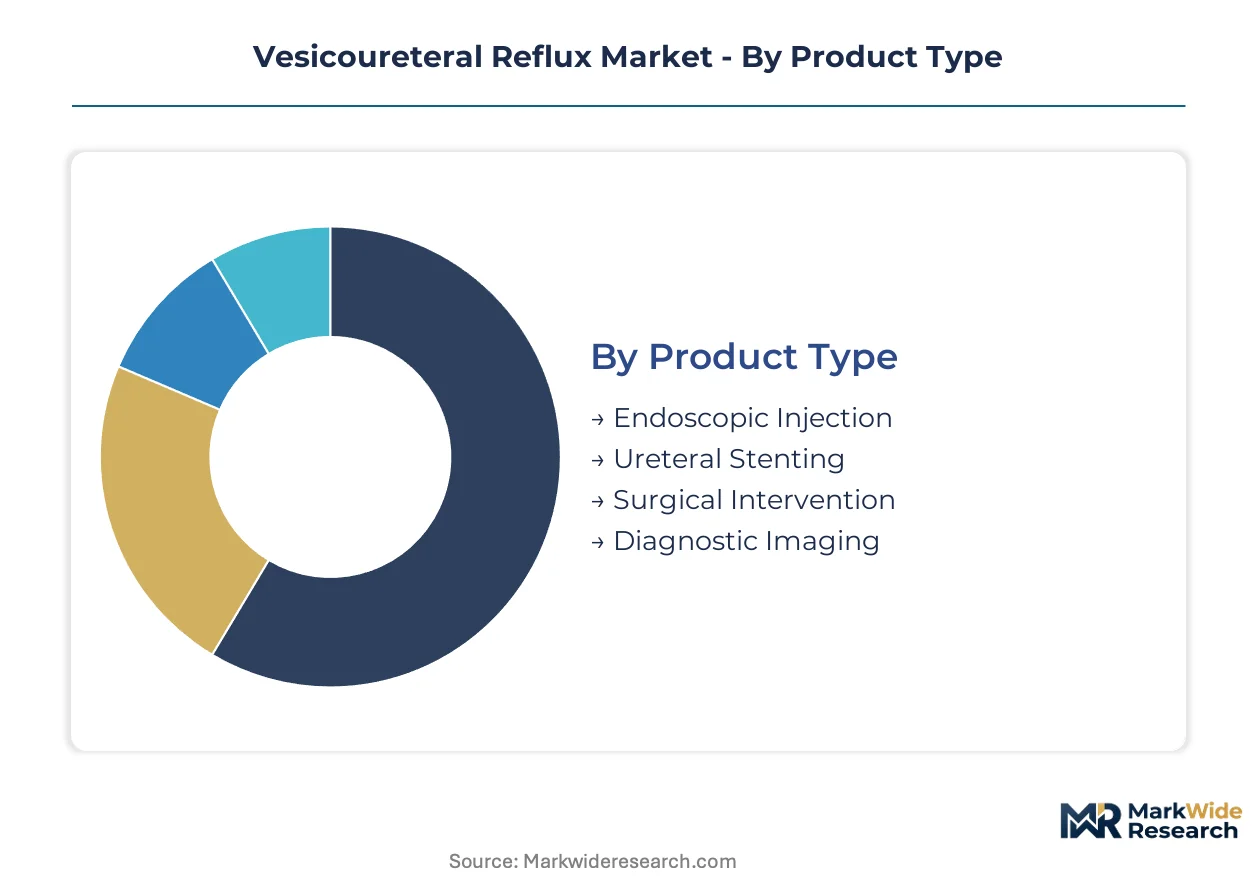
Segmentation in vesicoureteral reflux reveals how substitution pressures reshape commercial boundaries between interventional and conservative management pathways. Treatment modality selection increasingly depends on reimbursement alignment rather than clinical severity alone.
Product Type:
Endoscopic injection systems face intensifying substitution from bioresorbable bulking agents that displace older polymer formulations, while surgical hardware manufacturers confront volume erosion as minimally invasive protocols capture grade II-IV cases previously routed to open repair.
- Endoscopic Injection:Injectable dextranomer/hyaluronic acid copolymers deliver subureteric bulking with reduced granuloma risk versus polytetrafluoroethylene predecessors. Demand concentrates in pediatric specialty centers across the United States and Germany where same-day discharge protocols have become standard. FDA pediatric device consortia accelerate regulatory timelines for novel biomaterial formulations targeting high-grade reflux.
- Ureteral Stenting:Temporary and indwelling stent systems address duplex collecting systems and neurogenic bladder anatomies unsuited to injection therapy. Adoption is climbing fastest in complex anatomical cases at academic medical centers in Japan, where reimbursement for stent-based management has expanded beyond salvage indications.
- Surgical Intervention:Open ureteral reimplantation and laparoscopic variants retain dominance for grade V reflux and failed endoscopic cases.
- Diagnostic Imaging:Voiding cystourethrogram and contrast-enhanced ultrasound protocols establish reflux grade before treatment selection.
Endoscopic injection retains volume leadership; ureteral stenting holds the steepest expansion curve.
End User:
Facility type determines capital equipment requirements and reimbursement capture, with freestanding centers extracting margin through unbundled facility fees that hospital-based departments cannot match.
- Pediatric Clinics:Outpatient diagnostic and follow-up services manage low-grade reflux surveillance and antibiotic prophylaxis monitoring. Volume concentrates in United States metropolitan clusters where pediatric urology fellowship-trained specialists maintain practice.
- Ambulatory Surgical Centers:Freestanding facilities in Texas, Florida, and California capture endoscopic injection cases through streamlined scheduling and reduced overhead structures. Certificate-of-need minimal states enable fastest penetration.
- Urology Hospitals:Tertiary referral centers manage complex reconstruction and salvage procedures requiring overnight observation.
- Research Facilities:Academic medical centers conduct age-stratified safety trials under ISO 14155 and EMA pediatric investigation plans.
Pediatric clinics retain volume leadership; ambulatory surgical centers hold the steepest expansion curve.
Treatment Approach:
Cost tier stratification separates capital-intensive interventions from pharmaceutical management, with reimbursement differentials across United States state Medicaid programs creating adoption friction.
- Minimally Invasive:Endoscopic injection and laparoscopic repair protocols reduce recovery duration and parental work disruption. Demand concentrates in commercially insured populations where copay structures favor outpatient settings.
- Medical Therapy:Continuous antibiotic prophylaxis captures initial low-grade reflux management, constraining interventional penetration. Pfizer's established pediatric antibiotic portfolio sustains presence in this pathway.
- Surgical Repair:Open ureteral reimplantation remains definitive for grade V and failed endoscopic cases.
- Observation:Spontaneous resolution monitoring applies to selected low-grade presentations with reliable follow-up.
Medical therapy retains volume leadership; minimally invasive approaches hold the steepest expansion curve.
Severity Level:
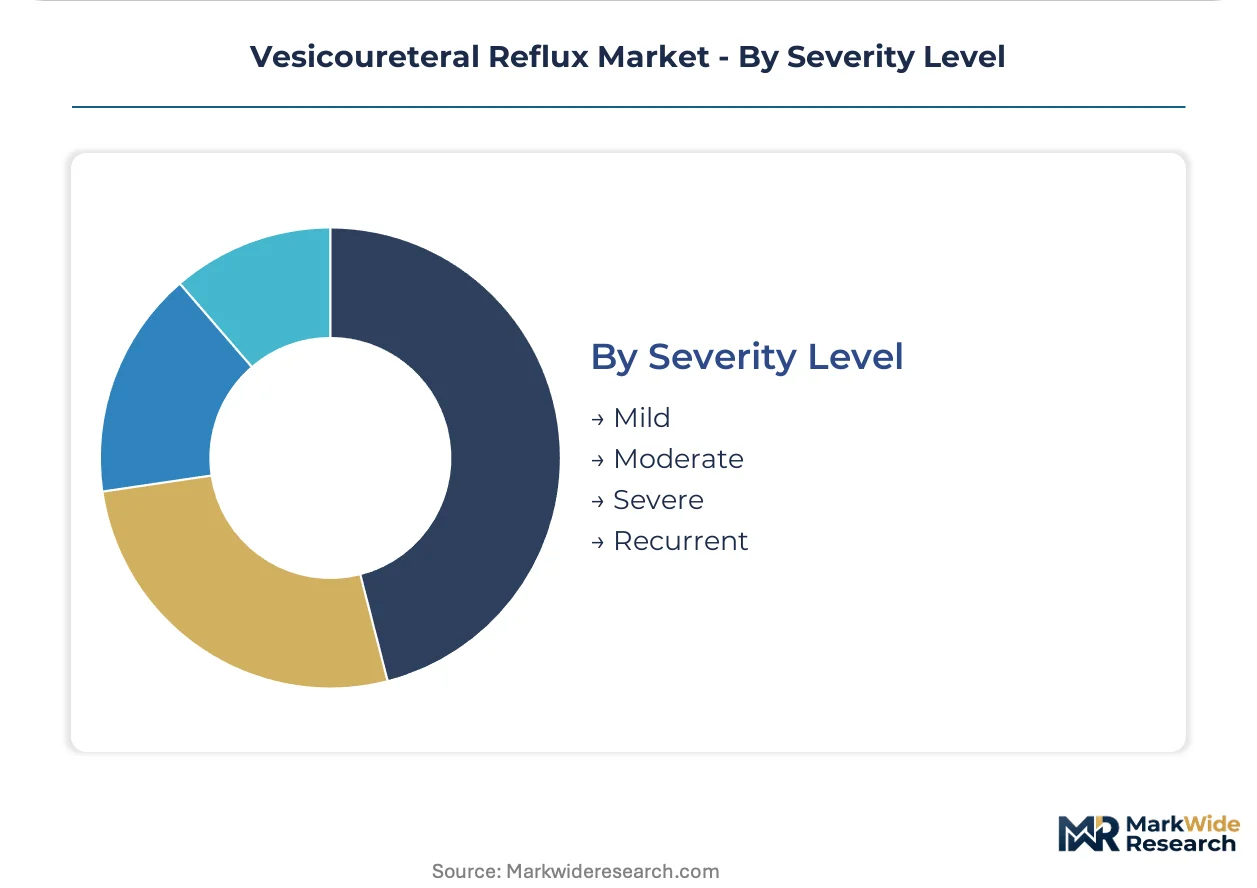
Clinical grading by International Reflux Study Committee criteria dictates intervention threshold, with moderate cases representing the contested zone between competing management philosophies.
- Moderate:Grades III-IV reflux generates maximum clinical uncertainty and treatment variability. Endoscopic injection has displaced open surgery as first-line intervention in United States and German pediatric centers, compressing addressable surgical volume.
- Severe:Grade V disease with calyceal distortion requires definitive surgical reconstruction. Cases concentrate at academic medical centers with fellowship-trained specialists.
- Mild:Grades I-II with minimal ureteral dilation typically resolve spontaneously or with antibiotic prophylaxis.
- Recurrent:Post-treatment failure drives salvage intervention and diagnostic re-evaluation.
Moderate severity retains volume leadership; recurrent presentations hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA pediatric device consortia anchor United States market development, while EMA pediatric investigation plans structure European pathways. Japan's PMDA accelerates complex anatomical stent approvals. National reimbursement policies and specialist training capacity determine regional adoption velocity.
United States
Pediatric specialty centers in Texas, Florida, and California drive endoscopic injection volume through ambulatory surgery center expansion. FDA pediatric device consortia compress regulatory timelines for novel bulking agents. Freestanding facilities in Houston and Dallas capture cases previously routed to hospital-based operating rooms.
Germany
Academic medical centers in Bavaria and North Rhine-Westphalia standardize dextranomer/hyaluronic acid protocols across eighteen-month procurement cycles. EMA pediatric investigation plans mandate age-stratified safety databases for subureteric injection systems. Berlin and Munich pediatric urology departments lead transitions from open surgical repair.
Japan
Complex anatomical cases at Tokyo and Osaka academic centers expand ureteral stenting beyond salvage indications. PMDA reimbursement policy shifts enable stent-based management for duplex collecting systems. METI-supported research infrastructure accelerates neurogenic bladder population access to minimally invasive alternatives.
United Kingdom
NHS England referral patterns concentrate severe grade V cases at London and Manchester tertiary centers. MHRA alignment with EMA pediatric investigation plans streamlines bulking agent approval pathways. Contrast-enhanced ultrasound adoption accelerates in Birmingham and Leeds pediatric nephrology clinics.
Vesicoureteral Reflux Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in the vesicoureteral reflux market structure. Pharmaceutical conglomerates with established pediatric portfolios occupy the upper tier, while device specialists and regional antibiotic suppliers fill mid-market positions. Two strategic archetypes dominate: diversified healthcare conglomerates leveraging cross-divisional research infrastructure, and focused urology device developers pursuing regulatory fast-tracks through pediatric consortia. Competitive moves center on portfolio diversification into adjacent nephrology segments and geographic expansion through EMA pediatric investigation plan harmonization.
Among diversified pharmaceutical conglomerates, Pfizer Inc. and Novartis AG exemplify archetypes anchored by pediatric therapeutic portfolios. Takeda Pharmaceutical Company occupies a position bridging gastrointestinal and urology crossover research. These entities represent scale-driven approaches to medical therapy pathways, contrasting with device specialists pursuing endoscopic injection and stenting platforms.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Takeda Pharmaceutical Company |
| Merck & Co., Inc. |
| Novartis AG |
| Abbott Laboratories |
| Johnson & Johnson |
| AstraZeneca |
| Boehringer Ingelheim GmbH |
| Sanofi |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety day procurement cycles for dextranomer/hyaluronic acid copolymers concentrate purchasing power among United States pediatric specialty centers, compressing margins for device manufacturers while amplifying price leverage for high-volume ambulatory surgical center networks.
Pricing Analysis
United States-Germany price spreads for endoscopic injection systems exceed twenty percent, reflecting reimbursement differentials across Medicaid programs. Three-tier pricing structure across premium bioresorbable formulations, standard polymer alternatives, and economy-grade diagnostic bundles dominates procurement. Pricing pressure stems from antibiotic prophylaxis protocols capturing low-grade cases, forcing interventional tiers toward cost compression. Pediatric clinics demonstrate highest price sensitivity; academic medical centers with bundled research contracts show lowest.
Supply Chain Analysis
Hyaluronic acid raw material transit through Rotterdam-Antwerp corridor underwrites European manufacturing continuity for injectable bulking agents. Supply concentrates in United States, Germany, and Japan for finished device assembly, drawing from Swedish and Swiss biomaterial feedstock sources. Single-source vulnerability persists in subureteric injection needle production. Distribution runs through GPO contracts at tertiary hospitals and direct procurement at freestanding surgical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vesicoureteral reflux management sits in early-cycle expansion as minimally invasive protocols displace open surgery across grade II-IV presentations, with endoscopic injection volumes accelerating fastest in certificate-of-need minimal states.
For Market Incumbents: Fortify pediatric device consortia relationships with FDA to accelerate novel bulking agent pathways ahead of specialist supply contraction. Deepen backward integration into hyaluronic acid raw material sourcing to offset biomaterial cost volatility. Lock GPO contracts at academic medical centers before ambulatory surgical center networks consolidate purchasing. For New Entrants and Emerging Players: FDA Breakthrough Device Designation offers fastest regulatory on-ramp for radiation-sparing diagnostic platforms targeting voiding cystourethrogram substitution. White-space concentrates in telemedicine follow-up protocols for rural United States populations distant from pediatric urology specialists. Partner with existing ambulatory surgery center management companies to bypass hospital credentialing barriers. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified pharmaceutical conglomerates seeking to divest non-core urology device portfolios as antibiotic prophylaxis volumes plateau. Long-term viability hinges on reimbursement policy convergence across United States state Medicaid programs. Monitor EMA pediatric investigation plan harmonization progress as inflection signal for European market access scalability.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Pediatric Device Consortium Enrollment | Accelerated premarket approval timelines compress competitive entry windows for novel bulking agents. |
| Bioresorbable Formulation Pipeline Expansion | Dextranomer/hyaluronic acid successors displace polytetrafluoroethylene remnants in German procurement cycles. |
| Ambulatory Surgery Center Partnership | Freestanding facility networks in Texas and Florida capture cases previously routed to hospital operating rooms. |
| Contrast-Enhanced Ultrasound Platform Development | Radiation-sparing diagnostics address parental preference shifts in United States metropolitan pediatric clinics. |
| Telemedicine Follow-Up Protocol Integration | Remote monitoring reduces geographic access barriers for families in rural regions distant from specialty centers. |
Study Parameters
Desk research of FDA 510(k) filings, EMA pediatric investigation plan submissions, and hospital procurement databases preceded structured interviews with pediatric urologists, biomedical engineers, and GPO contracts managers. Primary fieldwork with ambulatory surgery center administrators and reimbursement specialists validated secondary findings. Bottom-up procedure volume estimates triangulated against top-down pharmaceutical and device revenue disclosures.
Variance decomposition across treatment modality, severity grade, and end-user facility type shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include product type, end-user channel, treatment approach, and geographic regulatory cluster. CAGRs derived from procedure volume trajectories and average selling price evolution, incorporating antibiotic prophylaxis persistence rates and minimally invasive adoption curves as key inputs.
Decision-makers should treat outputs as directional under assumptions of stable reimbursement policy and continued specialist training contraction; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as FDA pediatric device consortium prioritization and EMA pediatric investigation plan harmonization evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
US Opioid Use Disorder (OUD) Market
Specialty Medicine
Spinal and Bulbar Muscular Atrophy Treatment Market
Specialty Medicine
Global Eye Allergy Therapeutics Market
Specialty Medicine
Non Small Cell Lung Cancer (NSCLC) Therapeutics Market
Specialty Medicine
Hepatic Encephalopathy Treatment Market
Specialty Medicine
Kidney Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Cat Scratch Disease (CSD) Treatment Market
Specialty Medicine
Global Photodynamic Therapy Market
Specialty Medicine
Global Herpes Market
Specialty Medicine
Hyperuricemia Market
Specialty Medicine
Complement 3 Glomerulopathy (C3G) Market
Specialty Medicine
Small Molecule Targeted Cancer Therapy Market
Specialty Medicine
Food Allergy Treatment Market
Specialty Medicine
Global Actinic Keratosis Treatment Market
Specialty Medicine
Cryoglobulinemia Treatment Market
Specialty Medicine
Nocturnal Polyuria Treatment Market