
 Global Autism Spectrum Disorders Market | 2026-2036
Global Autism Spectrum Disorders Market Size, Share, and Industry Trends Forecast 2026-2036
Global Autism Spectrum Disorders Market Foresight
North American pharmaceutical manufacturing is broadening its neurodevelopmental pipeline capacity. Roche leverages its diagnostics-to-therapeutics integration across European and Asian markets. Pfizer anchors its position through sustained R&D spending on pediatric neurology targets. Eli Lilly and Company differentiates via specialized clinical trial networks focused on autism spectrum biomarker validation.
Autism spectrum disorders encompass a range of neurodevelopmental conditions characterized by altered social communication, restricted interests, and repetitive behavioral patterns, typically assessed through standardized diagnostic instruments such as the ADOS-2 and ADI-R with calibrated severity scores. These conditions drive demand for clinical intervention tools, educational support infrastructure, and pharmacological management across pediatric and adult populations. Diagnostic kits represent the most mature revenue pool, while telehealth platforms within the delivery mode category capture the fastest structural expansion as reimbursement frameworks adapt to remote care models. Applied behavior analysis dominates therapy area spending, though cognitive behavioral therapy segments gain share among adolescent and adult cohorts seeking adaptive skill development.
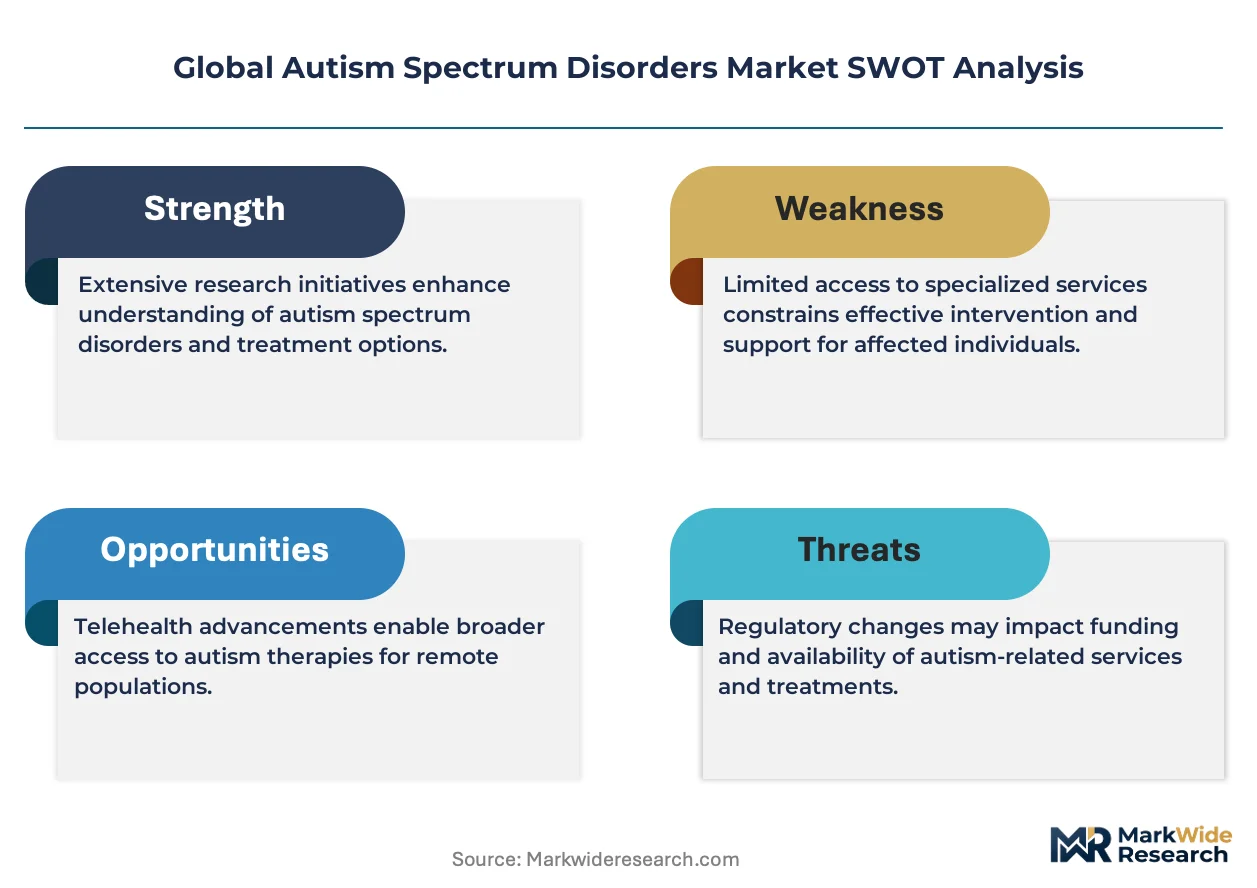
The FDA regulates diagnostic device accuracy and pharmacological safety for autism-related products in the United States, while the EMA oversees centralized marketing authorization across European member states, with both agencies intensifying focus on pediatric trial inclusivity. WHO neurodevelopmental guidelines and the EU Green Deal's sustainable manufacturing standards further constrain supply chain configurations for device manufacturers and pharmaceutical formulators. Stakeholders must monitor evolving reimbursement codes for digital therapeutics and wearable monitoring systems as payers recalibrate coverage policies for technology-enabled interventions.
Market Dynamics
Medicaid expansion across US states is compressing diagnostic timelines while telehealth reimbursement parity is redistributing service delivery from clinic-based to home-based models, fundamentally restructuring how autism interventions reach pediatric populations.
Growth Catalysts
- Medicaid Expansion:US state-level coverage mandates for early intervention services are broadening access to Applied Behavior Analysis for children under five, particularly in states that adopted expansion under the Affordable Care Act.
- FDA Accelerated Approval:The FDA's breakthrough therapy designation for neurodevelopmental drug candidates is compressing Phase II-to-approval timelines, incentivizing biopharmaceutical investment in pediatric neurology pipelines.
- Telehealth Infrastructure:Remote diagnostic platforms leveraging ADOS-2 adaptation protocols are extending specialist reach into rural and underserved counties across the United States, Canada, and Australia.
Market Restraints
- Behavioral Therapist Shortages:Board Certified Behavior Analyst credential scarcity in the United States creates waitlists exceeding twelve months in high-demand metropolitan areas, constraining service expansion regardless of funding availability.
- Diagnostic Device Concentration:Supply of calibrated ADOS-2 kits and ADI-R protocols concentrates among three specialized publishers, creating procurement bottlenecks for clinics scaling assessment capacity.
- Reimbursement Fragmentation:Inconsistent CPT code coverage for digital therapeutic interventions across US state Medicaid plans and European national health systems limits platform monetization and investor confidence.
Strategic Opportunities
- Adult Diagnosis Surge:Recognition of autism spectrum conditions in working-age adults across Germany, the United Kingdom, and Japan is opening service demand beyond traditional pediatric-focused providers.
- Wearable Biomarker Integration:Convergence of galvanic skin response sensors with machine learning analytics is enabling objective behavioral monitoring for medication response validation in clinical trials.
- School-Mandated Coverage:US Individuals with Disabilities Education Act enforcement actions are compelling district-level contracting for specialized educational support services, creating institutional procurement channels distinct from medical reimbursement.
Industry Challenges
- Clinical Workforce Pipeline:University training programs for speech-language pathologists and occupational therapists with autism specialization are failing to match graduation rates with vacancy growth in community health centers.
- Interoperability Standards:Electronic health record integration between diagnostic assessment tools, therapy progress trackers, and school-based individualized education plan systems remains technically fragmented across vendor platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Autism Spectrum Disorders Market |
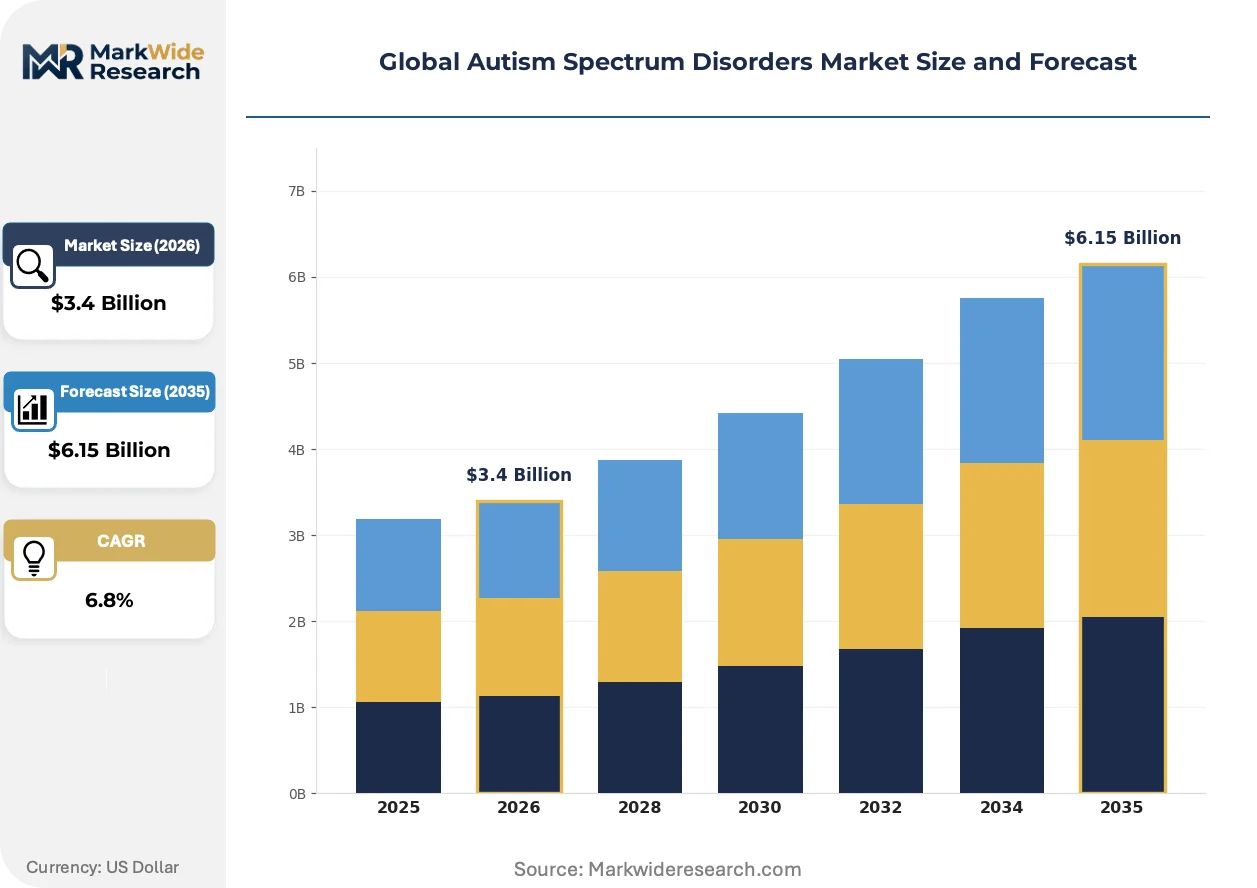
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $6.15 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Kits, Behavioral Therapy Tools, Assistive Communication Devices, Educational Software Therapy Area: Applied Behavior Analysis, Speech Therapy, Occupational Therapy, Cognitive Behavioral Therapy End User: Specialized Clinics, Neurodevelopmental Centers, Educational Institutions, Home Care Providers Delivery Mode: In-person Sessions, Telehealth Platforms, Mobile Applications, Wearable Devices |
| Companies Covered | Jazz Pharma, Pfizer, Roche, QIAGEN, PaxMedica, Johnson & Johnson, Eli Lilly and Company, Zynerba Pharmaceuticals, Otsuka, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Autism Spectrum Disorders Market Shifts & Advancements
Digital phenotype extraction from passive sensor data is displacing subjective caregiver reports as the primary outcome measure in clinical trials, while regulatory agencies are recalibrating evidentiary standards to accommodate these novel endpoints.
Artificial intelligence-assisted diagnostic screening is modularizing the initial assessment workflow. Pediatric primary care networks in the United States and Netherlands are deploying tablet-based adaptive algorithms to triage referrals before specialist consultation. This compression of front-end evaluation is reallocating specialist capacity toward complex differential diagnosis cases.
The European Medicines Agency's pediatric investigation plan requirements are mandating earlier inclusion of autism spectrum populations in neurodevelopmental drug development programs. Pharmaceutical sponsors must now submit age-appropriate formulation strategies and biomarker validation protocols at Phase I. This regulatory pressure is accelerating investment in juvenile toxicology models and patient-reported outcome instruments calibrated for nonverbal participants.
Parent-directed therapy models are displacing clinic-exclusive service delivery as the dominant reimbursement category in several US state Medicaid programs. Self-managed applied behavior analysis protocols with remote professional supervision are capturing budget share from traditional center-based intensive programs. This shift is most pronounced in Texas, Florida, and Arizona, where workforce shortages have forced payer experimentation with alternative benefit designs.
Global Autism Spectrum Disorders Market Segmentation
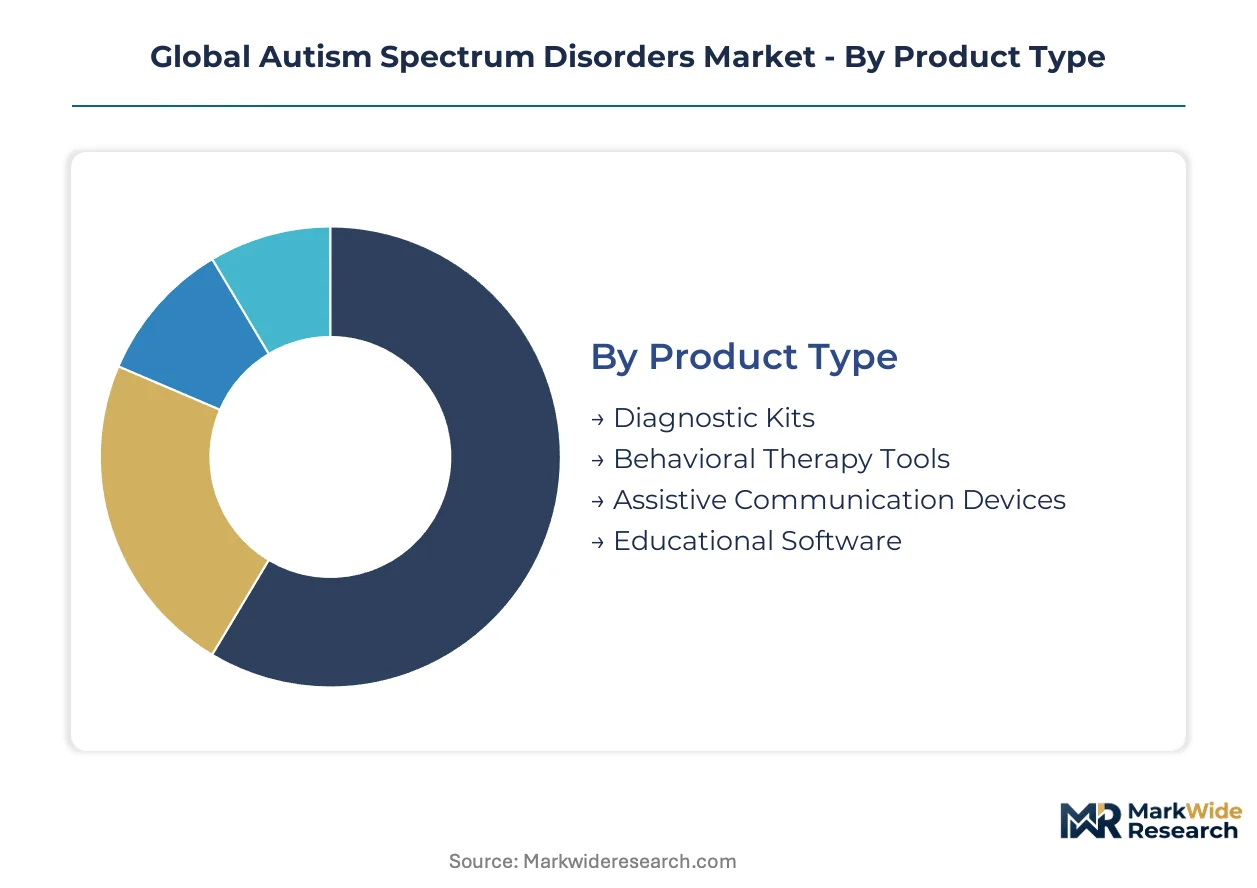
Segmentation in the autism spectrum disorders market reflects divergent reimbursement pathways, regulatory classifications, and care delivery infrastructure across pediatric and adult populations. Product and service configurations must align with Medicaid coding conventions, FDA device classifications, and school district procurement frameworks to achieve commercial viability.
Product Type:
Standardization dominates diagnostic instruments while customization pressures intensify for therapeutic and assistive technologies.
- Diagnostic Kits:Standardized assessment protocols including ADOS-2 and ADI-R modules comprise the most mature revenue pool. Demand concentrates in US metropolitan markets where Medicaid expansion has compressed diagnostic timelines for children under five. Procurement bottlenecks persist due to publisher concentration among three specialized vendors.
- Behavioral Therapy Tools:Customizable intervention protocols and data collection systems support applied behavior analysis delivery. Specialized clinics across North America and Europe are expanding budgets for these tools as workforce shortages force efficiency investments. Parent-directed therapy models are redistributing demand toward home-compatible configurations.
- Assistive Communication Devices:Speech-generating devices and symbol-based communication boards serve nonverbal populations. School districts under US Individuals with Disabilities Education Act enforcement represent the primary procurement channel.
- Educational Software:Adaptive learning platforms target skill acquisition in academic and social domains. European markets under EU accessibility standards show particular regulatory traction for inclusive design features.
Most installed capacity flows through Diagnostic Kits. Expansion is steepest in Behavioral Therapy Tools.
Therapy Area:
Volume concentration sits with established behavioral modalities while margin expansion follows cognitive and adaptive skill development segments.
- Applied Behavior Analysis:Intensive, data-driven behavioral intervention remains the dominant reimbursement category across US state Medicaid programs. Texas, Florida, and Arizona have pioneered parent-directed models with remote supervision to address Board Certified Behavior Analyst scarcity.
- Cognitive Behavioral Therapy:Structured psychological intervention targeting anxiety and adaptive skills gains share among adolescent and adult cohorts in Germany, the United Kingdom, and Japan. Recognition of autism in working-age populations is opening service demand beyond traditional pediatric providers.
- Speech Therapy:Communication-focused intervention addresses receptive and expressive language deficits. Educational institutions represent the primary delivery setting for school-age children.
- Occupational Therapy:Sensory integration and daily living skills training supports functional independence. Community health centers face persistent vacancy growth that university training programs fail to match.
Applied Behavior Analysis captures the largest service volume. Cognitive Behavioral Therapy is climbing the fastest as adult diagnosis recognition expands.
End User:
Customer concentration shifts from medical to educational and home-based settings as reimbursement frameworks adapt.
- Specialized Clinics:Dedicated autism assessment and intervention centers anchor diagnostic accuracy and intensive therapy delivery. These facilities concentrate in US states with Medicaid expansion and school-mandated intervention coverage.
- Educational Institutions:School districts procure specialized support services under federal enforcement of disability education mandates. Institutional procurement channels operate distinct from medical reimbursement systems.
- Neurodevelopmental Centers:Hospital-affiliated programs integrate multidisciplinary care for complex differential diagnoses. EMA pediatric investigation plan requirements are mandating earlier autism population inclusion in drug development.
- Home Care Providers:Family-directed service delivery captures expanding budget share as workforce shortages force payer experimentation with alternative benefit designs.
Specialized Clinics retain the deepest installed base. Home Care Providers are gaining share fastest under parent-directed reimbursement innovations.
Delivery Mode:
Technology-enabled modalities are redistributing service delivery from clinic-exclusive to distributed care models.
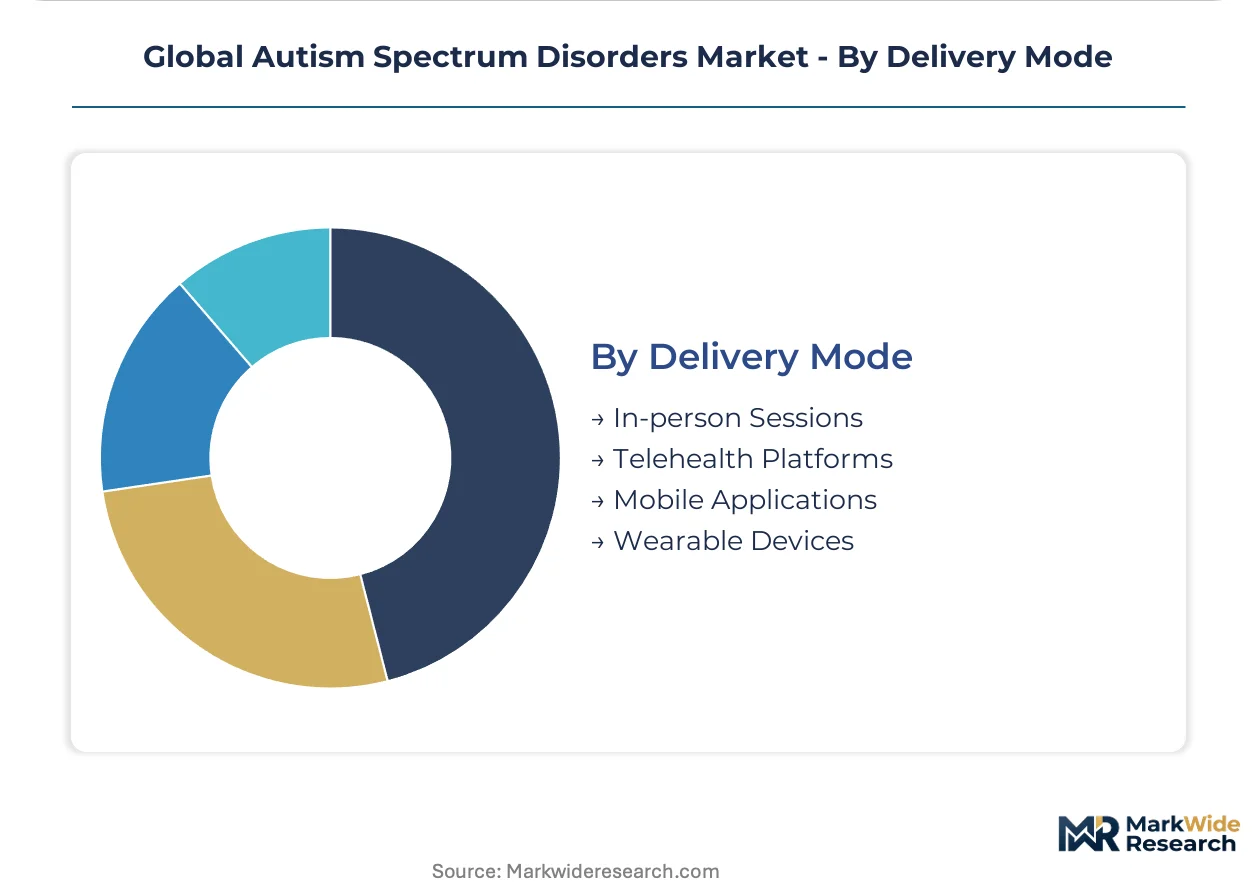
- Telehealth Platforms:Remote diagnostic and therapeutic delivery extends specialist reach into rural and underserved US counties. Reimbursement parity policies are restructuring how interventions reach pediatric populations.
- Mobile Applications:Tablet-based adaptive algorithms triage referrals before specialist consultation in US and Netherlands primary care networks. This compression reallocates specialist capacity toward complex cases.
- In-person Sessions:Traditional clinic-based delivery remains necessary for standardized assessments and intensive behavioral intervention. Waitlists exceeding twelve months in high-demand metropolitan areas constrain expansion.
- Wearable Devices:Passive sensor data enables objective behavioral monitoring for medication response validation. Convergence with machine learning analytics supports clinical trial endpoint innovation.
In-person Sessions still dominate service volume. Telehealth Platforms are expanding most quickly as reimbursement frameworks adapt to remote care models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing clinical trial investment toward jurisdictions with streamlined pediatric investigation pathways, while reimbursement generosity determines where service delivery infrastructure scales fastest.
United States
Medicaid expansion across 40 states has compressed diagnostic timelines for children under five, with Texas and Florida pioneering parent-directed ABA models to address Board Certified Behavior Analyst scarcity. The FDA's breakthrough therapy designation for neurodevelopmental candidates accelerates Phase II-to-approval timelines. Specialized clinics concentrate in California's Bay Area and Boston's Route 128 corridor, where hospital-affiliated neurodevelopmental centers integrate multidisciplinary care.
Germany
Recognition of autism spectrum conditions in working-age adults is opening service demand beyond traditional pediatric providers, particularly in Berlin and Munich metropolitan regions. The EMA's pediatric investigation plan mandates earlier autism population inclusion in drug development programs. Heidelberg and Mannheim host concentrated clinical research infrastructure for biomarker validation trials.
United Kingdom
NHS England's autism diagnosis waiting list initiatives are driving investment in digital triage platforms, with London and Manchester emerging as telehealth service hubs. The MHRA operates under EMA centralized marketing authorization frameworks while maintaining national reimbursement discretion. Cambridge's biomedical cluster supports diagnostic device development aligned with NICE technology appraisal pathways.
Japan
PMDA consultation programs for pediatric neurodevelopmental drugs are attracting multinational trial sponsorship, with Tokyo and Osaka anchoring clinical research organization capacity. METI funding for assistive technology development supports domestic educational software innovation. Yokohama's Kanagawa Prefecture hosts specialized educational support service providers targeting school-mandated intervention coverage.
Australia
Telehealth reimbursement parity has extended specialist reach into rural New South Wales and Queensland counties, redistributing service delivery from clinic-based to home-based models. The TGA regulates diagnostic device accuracy while state-level disability insurance schemes determine therapy funding allocation. Melbourne's biomedical precinct concentrates wearable biomarker development for clinical trial applications.
Global Autism Spectrum Disorders Market Competitive Landscape
United States pharmaceutical developers anchor one tier; European diagnostics-to-therapeutics integrators hold specialized positioning in standardized assessment markets. The vendor base exhibits moderate concentration, with large-cap diversified players competing against focused neurology specialists across distinct reimbursement channels. Three archetypes dominate: vertically integrated pharma-diagnostics hybrids, pure-play behavioral therapy platform developers, and educational technology specialists. Capacity expansion through specialized clinical trial networks and strategic partnerships with Medicaid-managed care organizations represent the dominant competitive vectors.
Within the large-cap pharmaceutical tier, Roche exemplifies the diagnostics-to-therapeutics integration archetype across European and Asian markets. Pfizer occupies a position as a sustained R&D spender anchoring pediatric neurology targets. Eli Lilly and Company sits within the specialized clinical trial network tier, focused on autism spectrum biomarker validation. These three entities represent divergent strategic postures toward the neurodevelopmental pipeline without implying specific market share or revenue claims.
| Leading Market Players |
|---|
| Jazz Pharma |
| Pfizer |
| Roche |
| QIAGEN |
| PaxMedica |
| Johnson & Johnson |
| Eli Lilly and Company |
| Zynerba Pharmaceuticals |
| Otsuka |
| Others |
Supply & Pricing Matrix
Specialized diagnostic kit pricing indices from US and European publishers cascade through autism service supply chains, compressing margins for independent clinics while reinforcing procurement leverage for hospital-affiliated neurodevelopmental centers and Medicaid-managed care networks.
Pricing Analysis
Distributor margins on ADOS-2 and ADI-R standardized assessment kits absorb 15-25% of end-user costs before clinic markup. Three-tier pricing structure across institutional volume, mid-tier clinic, and individual practitioner levels reflects certification tier and purchase scale. Price erosion runs through the behavioral therapy tools segment as parent-directed reimbursement models force vendors toward SaaS-tiered subscription formats. Medicaid-funded specialized clinics exhibit highest price sensitivity; pharmaceutical-sponsored neurodevelopmental centers show lowest.
Supply Chain Analysis
Transoceanic freight cost volatility on electronics components for assistive communication devices and wearable sensors has compressed logistics budgets for European and Australian distributors. Manufacturing concentrates in China for tablet-based adaptive algorithms, the United States for diagnostic software platforms, and Germany for precision sensor hardware. Component dependencies span lithium-ion cells, medical-grade polymers, and specialized ASIC processors. Single-source vulnerability concentrates in ADOS-2 kit publishing rights held by three specialized vendors. Distribution runs through hospital procurement consortia and school district cooperative purchasing agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Autism spectrum disorder service markets reward geographic arbitrage between US states with Medicaid expansion generosity and European jurisdictions with EMA pediatric investigation plan streamlining, exploiting regulatory cost differentials exceeding 40% in clinical trial placement.
For Market Incumbents: Extend diagnostic-to-therapeutic integration capabilities by acquiring telehealth platform specialists and deepening backward integration into wearable sensor development. Counter workforce shortage-driven margin compression through AI-assisted diagnostic screening deployment in primary care networks. Prioritize certification investment for FDA breakthrough therapy designation to compress competitor Phase II timelines. For New Entrants and Emerging Players: Begin with adult diagnosis service white space in Germany, the United Kingdom, and Japan where recognition of working-age autism spectrum conditions outpaces specialized provider capacity. Target cognitive behavioral therapy delivery for adolescent and adult cohorts seeking adaptive skill development. Pursue school-district direct contracting under US Individuals with Disabilities Education Act enforcement as the most penetrable go-to-market channel. For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated diagnostics-to-therapeutics platforms possessing both standardized assessment publishing rights and neurodevelopmental drug pipeline exposure. Long-term viability over a multi-year horizon hinges on reimbursement code capture for digital therapeutics and wearable monitoring systems. Watch for inflection in state Medicaid telehealth parity policy expansion as the signal for platform monetization acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Therapy Designation Pursuit | Compresses Phase II-to-approval timelines for neurodevelopmental candidates under FDA accelerated pathways. |
| Telehealth Platform Integration | Extends specialist reach into rural US counties and Australian disability insurance scheme regions. |
| Biomarker Validation Network Expansion | Supports EMA pediatric investigation plan compliance and objective clinical trial endpoint innovation. |
| Parent-Directed Therapy Model Deployment | Captures Medicaid budget share in Texas, Florida, and Arizona where BCBA scarcity forces payer experimentation. |
| Wearable Sensor Supply Agreement | Secures galvanic skin response hardware for medication response validation in pharmaceutical trials. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with board certified behavior analysts, neurodevelopmental center medical directors, Medicaid managed care formulary specialists, and school district special education procurement officers against secondary validation from FDA 510(k) filings, EMA pediatric investigation plan submissions, ClinicalTrials.gov neurodevelopmental trial registries, and state Medicaid reimbursement code databases. Bottom-up service delivery volume estimates triangulated against top-down pharmaceutical pipeline investment flows.
Segment-weighting approaches distributed analytical focus across diagnostic kits, behavioral therapy tools, assistive communication devices, and educational software product types, with therapy area splits across applied behavior analysis, cognitive behavioral therapy, speech therapy, and occupational therapy. End-user segmentation captured specialized clinics, educational institutions, neurodevelopmental centers, and home care providers. Delivery mode differentiation modeled telehealth platforms, mobile applications, in-person sessions, and wearable devices. CAGRs derived from Medicaid expansion trajectory analysis, FDA approval pathway velocity, and telehealth reimbursement parity policy diffusion curves.
Several conditions sit outside the modeled scope, including speculative pharmacological approvals without existing Phase II data, unregulated digital therapeutic platforms lacking CPT code assignment, and macroeconomic shifts in federal Medicaid matching fund formulas. Forecasts reflect documented assumptions on regulatory pathway timelines and payer behavior continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Global Stroke Therapeutics Market
Specialty Medicine
Global Plasma Protease C1 Inhibitor Treatment Market
Specialty Medicine
Specialty Generics Market
Specialty Medicine
Progressive Pulmonary Fibrosis (PPF) Treatment Market
Specialty Medicine
Global Huntingtons Disease Treatment Market
Specialty Medicine
Gouty Arthritis Market
Specialty Medicine
Marfan Syndrome Management Market
Specialty Medicine
Mucinoses Management Market
Specialty Medicine
Pseudomonas Aeruginosa Treatment Market
Specialty Medicine
Epileptic Seizures Treatment Market
Specialty Medicine
Cystic Fibrosis Therapeutics Market
Specialty Medicine
Cervical Cancer Therapeutics Market
Specialty Medicine
Rosacea Therapeutics Market
Specialty Medicine
Primary Ciliary Dyskinesia Market
Specialty Medicine
Brugada Syndrome Market
Specialty Medicine
Middle East and Africa Kidney Cancer Therapeutics and Diagnostics Market