
 Neglected Tropical Diseases Diagnosis Market | 2026-2036
Neglected Tropical Diseases Diagnosis Market Size, Share, and Industry Trends Forecast 2026-2036
Neglected Tropical Diseases Diagnosis Market Intelligence
Point-of-care nucleic acid amplification technology is narrowing the diagnostic gap between centralized laboratories and rural health posts in endemic regions. Abbott Laboratories leverages its established tropical disease assay portfolio to sustain presence across African and Southeast Asian procurement channels. bioMérieux SA anchors its competitive position through integrated microbiology platforms that combine automated sample prep with pathogen-specific detection protocols. Danaher Corporation navigates fragmented public-sector purchasing by controlling distribution networks that reach district-level health facilities.
Neglected tropical diseases diagnosis encompasses the detection and identification of infectious pathogens including helminths, protozoa, and bacteria that disproportionately affect populations in tropical and subtropical climates, utilizing immunoassay reagents, nucleic acid probes, and optical imaging systems designed for field-deployable or laboratory-confirmed results. The primary commercial purpose centers on enabling treatment initiation, disease surveillance, and elimination program monitoring where healthcare infrastructure remains limited. Molecular diagnostics commands the highest unit economics due to multiplexing capabilities for co-endemic pathogen screening, while lateral flow rapid tests dominate volume throughput in community-based mass drug administration settings. Public health organizations represent the most concentrated end-user segment, with procurement patterns shaped by donor-funded vertical disease programs rather than conventional hospital capital budgets.
WHO prequalification standards and the EU In Vitro Diagnostic Regulation shape market access requirements for manufacturers seeking eligibility in Global Fund and PEPFAR supply chains. FDA Emergency Use Authorization pathways for tropical disease assays during outbreak scenarios create parallel regulatory tracks that accelerate time-to-market for novel platforms. National regulators in endemic countries, including Nigeria's NAFDAC and India's CDSCO, enforce import testing requirements that filter non-conforming products from public tenders. Stakeholders must monitor shifting donor prioritization between disease-specific elimination targets and integrated diagnostic platforms that address multiple neglected tropical diseases through single-test configurations.
Market Dynamics
WHO prequalification requirements for in vitro diagnostics are compressing product development timelines while simultaneously elevating technical barriers for manufacturers seeking access to Global Fund procurement channels in endemic regions.
Growth Catalysts
- Point-of-care nucleic acid amplification:Field-deployable molecular platforms enable same-day treatment initiation for lymphatic filariasis and onchocerciasis in district-level health facilities across Nigeria and Ghana.
- EU In Vitro Diagnostic Regulation harmonization:Standardized technical documentation requirements reduce redundant testing costs for manufacturers serving multiple endemic markets through centralized production.
- Mass drug administration surveillance protocols:National control programs in Ethiopia and Tanzania mandate post-treatment prevalence monitoring using standardized immunoassay panels.
Market Restraints
- Reagent cold chain dependency:Temperature-sensitive nucleic acid probes require uninterrupted refrigeration infrastructure that remains sparse in rural health posts across the Democratic Republic of Congo.
- Donor funding concentration:Vertical disease programs tied to specific pathogen elimination targets limit procurement flexibility for integrated diagnostic platforms addressing multiple neglected tropical diseases.
- Import testing bottlenecks:NAFDAC's mandatory batch verification protocols in Nigeria delay product registration by 8-14 months for novel assay formats.
Strategic Opportunities
- Multiplexing platform convergence:Single-test configurations combining helminth, protozoan, and bacterial detection are capturing procurement preference in co-endemic regions of Southeast Asia.
- District-level distribution networks:Direct-to-facility logistics partnerships bypass centralized laboratory procurement bottlenecks in Kenya's devolved health system.
- PEPFAR supply chain eligibility:Dual WHO-FDA qualification pathways unlock parallel funding streams for manufacturers targeting HIV-NTD co-screening programs.
Industry Challenges
- Field technician molecular biology competency:Nucleic acid amplification protocols require specialized training that exceeds the skill base of community health workers in remote Indonesian archipelago clinics.
- Legacy lateral flow inventory amortization:Existing stockpiles of single-pathogen rapid tests create procurement inertia against multiplex platform adoption in Bangladesh's national program.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neglected Tropical Diseases Diagnosis Market |
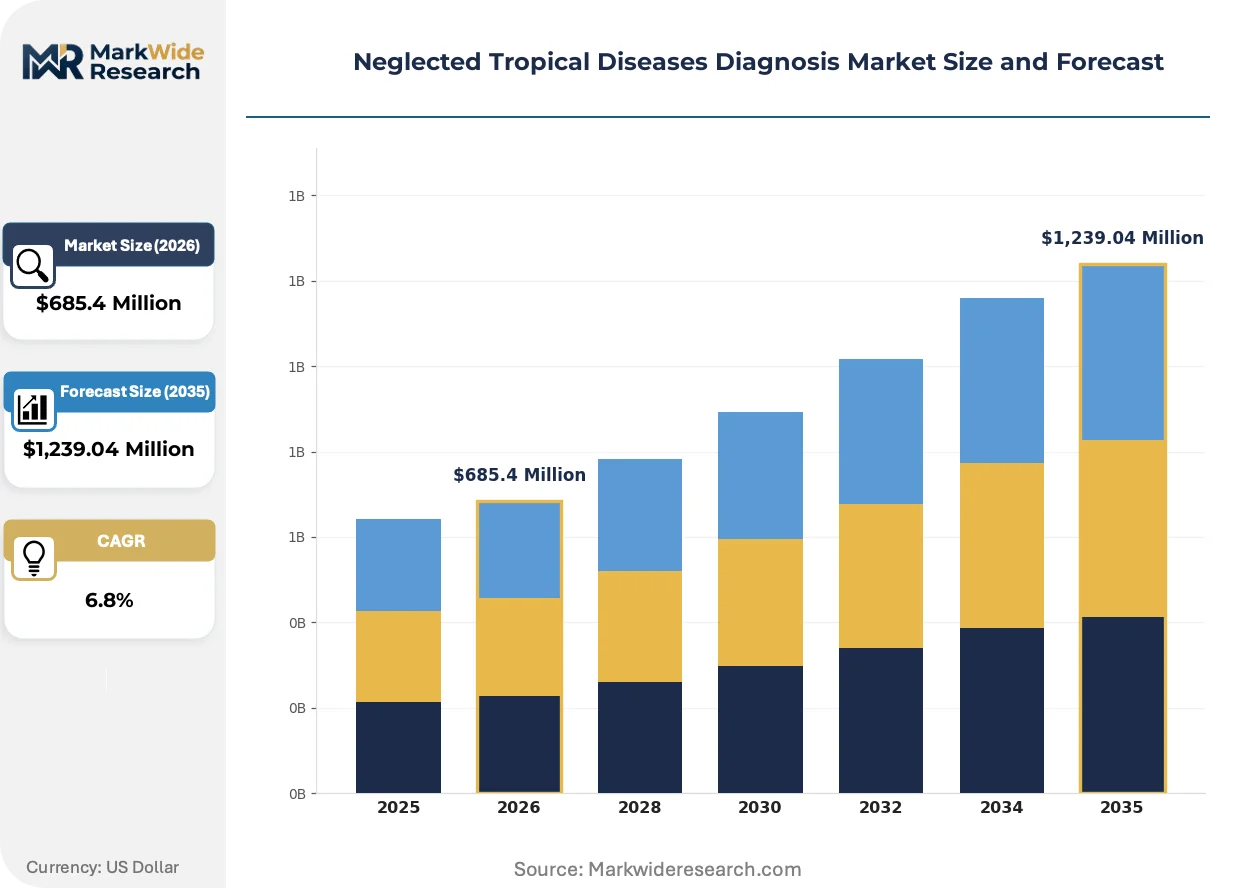
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rapid Tests, Serological Tests, Molecular Diagnostics, Microscopy Application: Infection Control, Patient Diagnosis, Epidemiological Studies, Drug Efficacy Testing End User: Hospitals, Laboratories, Research Institutions, Public Health Organizations Technology: PCR, ELISA, Lateral Flow, Next-Generation Sequencing |
| Companies Covered | Abbott Laboratories, F. Hoffmann-La Roche Ltd, Thermo Fisher Scientific Inc., bioMérieux SA, Siemens Healthineers AG, Bio-Rad Laboratories, Inc., Danaher Corporation, InBios International, Inc., ZeptoMetrix, LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neglected Tropical Diseases Diagnosis Market Strategic Shifts & Innovations
Diagnostic platform miniaturization and regulatory pathway bifurcation are compressing the traditional centralized-to-peripheral testing hierarchy that has structured neglected tropical disease programs for decades.
Loop-mediated isothermal amplification (LAMP) technology eliminates thermal cycler dependency through constant-temperature nucleic acid amplification. District hospitals in Uganda and Mozambique are deploying battery-powered LAMP devices for onchocerciasis detection at one-third the capital cost of conventional PCR. This distributed molecular capability is rendering obsolete the sample transport networks that previously funneled all specimens to regional reference laboratories.
The EU Medical Device Regulation's performance evaluation requirements are mandating clinical validation studies in intended-use populations. Manufacturers must now generate diagnostic accuracy data from endemic-region field trials rather than relying on European reference laboratory studies. Assay developers are responding by establishing satellite clinical validation sites in Nigeria and Indonesia to satisfy notified body expectations.
Bulk procurement consortia are displacing single-tender national purchasing across West African economic communities. Pooled demand mechanisms aggregate volume commitments from Ghana, Côte d'Ivoire, and Burkina Faso to secure price concessions from prequalified suppliers. This regional aggregation model concentrates most visibly in lymphatic filariasis elimination programs where synchronized mass drug administration schedules create synchronized diagnostic demand cycles.
Neglected Tropical Diseases Diagnosis Market Segmentation
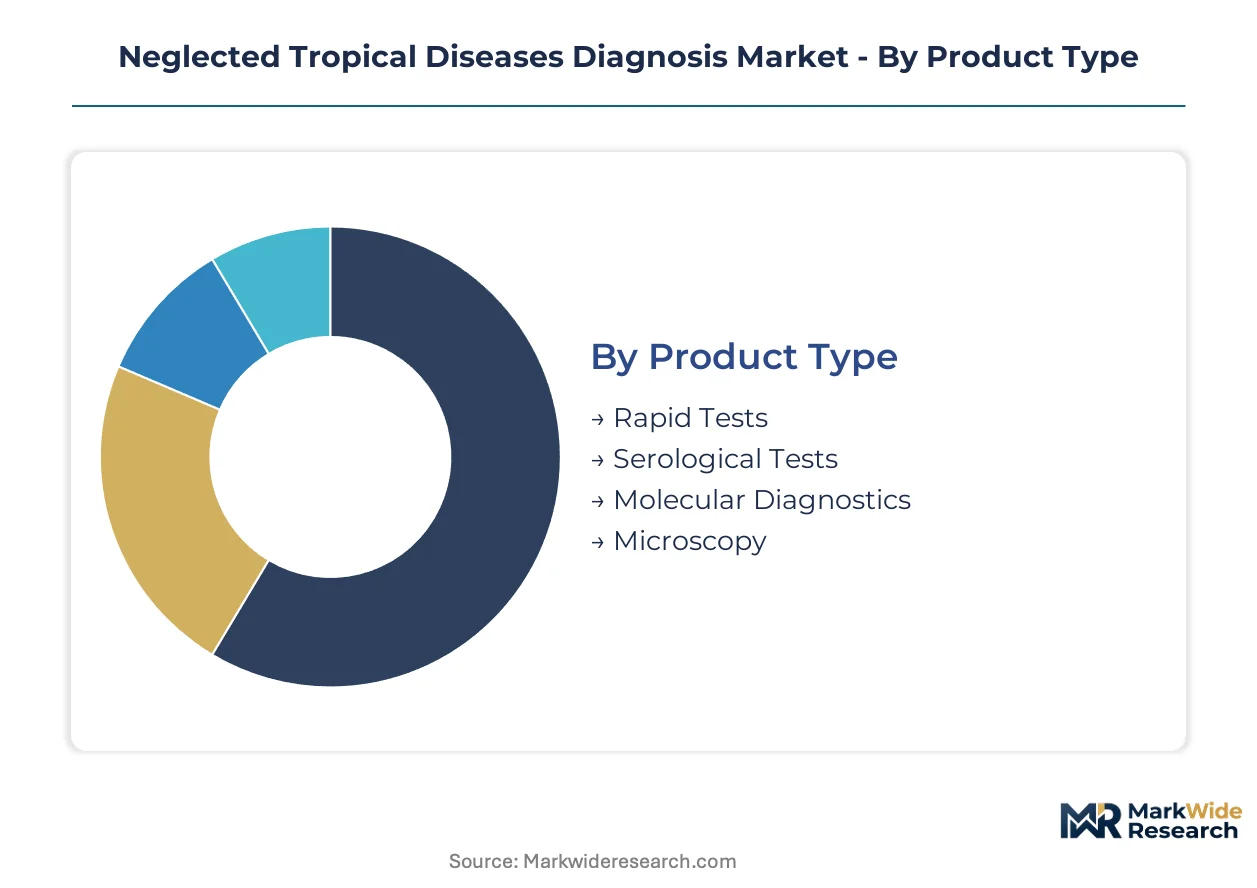
Diagnostic platform segmentation reveals divergent capital intensity and replacement cycles across the neglected tropical diseases market. Procurement patterns vary sharply between donor-funded bulk purchases and facility-level consumable replenishment.
Product Type:
Replacement cycles stretch from single-use rapid tests to decade-long molecular platform deployments, creating distinct inventory management challenges for procurement officers.
- Rapid Tests:Lateral flow immunoassays deliver visual results within fifteen minutes without instrumentation. Mass drug administration programs in Nigeria and Ethiopia consume these at highest velocity, with village health workers deploying millions of units annually during lymphatic filariasis screening rounds.
- Molecular Diagnostics:Nucleic acid amplification platforms multiplex pathogen detection through automated thermal cycling or isothermal protocols. District hospitals in Ghana prioritize these for onchocerciasis confirmation where microscopy skill gaps persist, though cold chain requirements for reagent storage constrain rural deployment.
- Serological Tests:Enzyme-linked immunosorbent assay kits detect antibody responses with higher specificity than rapid formats. Reference laboratories in Tanzania standardize on these for epidemiological baseline surveys.
- Microscopy:Conventional light microscopy remains the default confirmatory method for soil-transmitted helminth identification. Training infrastructure limitations restrict this to centralized facilities in Kenya and Uganda.
Rapid tests anchor the volume base while molecular diagnostics gains share at the steepest rate.
Application:
Cost tiers separate routine screening from capital-intensive research protocols, with reimbursement pathways diverging accordingly.
- Patient Diagnosis:Individual case confirmation triggers treatment eligibility under national elimination guidelines. Clinics in Burkina Faso prioritize this application for schistosomiasis detection where praziquantel distribution depends on verified infection status.
- Infection Control:Healthcare-associated transmission prevention requires rapid turnaround for returning travelers. Airport screening facilities in Southeast Asian hubs deploy PCR-based protocols for dengue-chikungunya differentiation.
- Epidemiological Studies:Population-level prevalence mapping informs resource allocation for mass drug administration. Research consortia in Mozambique fund these surveys through bilateral health partnerships.
- Drug Efficacy Testing:Post-treatment surveillance monitors for emerging resistance patterns. WHO collaborating centers conduct these studies under standardized protocols.
Patient diagnosis commands the largest procurement budget while infection control applications expand most quickly.
End User:
Customer type determines pricing leverage, with consolidated public tenders achieving steeper discounts than fragmented institutional purchasing.
- Public Health Organizations:National control programs and vertical disease initiatives aggregate demand across thousands of facilities. Ghana's Neglected Tropical Diseases Program centralizes all diagnostic procurement through Global Fund mechanisms.
- Hospitals:District and regional medical centers require confirmatory capacity for complex cases. Facilities in Nigeria's Kebbi State report stockout-driven delays in lymphatic filariasis verification.
- Laboratories:Reference laboratories maintain quality assurance networks for peripheral testing sites. Kenya's KEMRI operates regional hubs serving county health systems.
- Research Institutions:Academic and nonprofit investigators purchase specialized platforms for assay development. The Uganda Virus Research Institute maintains sequencing capacity for emerging pathogen characterization.
Public health organizations dominate volume commitments while research institutions pursue the steepest technology upgrade cycles.
Technology:
Platform maturity separates established formats with extensive validation literature from emerging methods requiring clinical evidence generation.
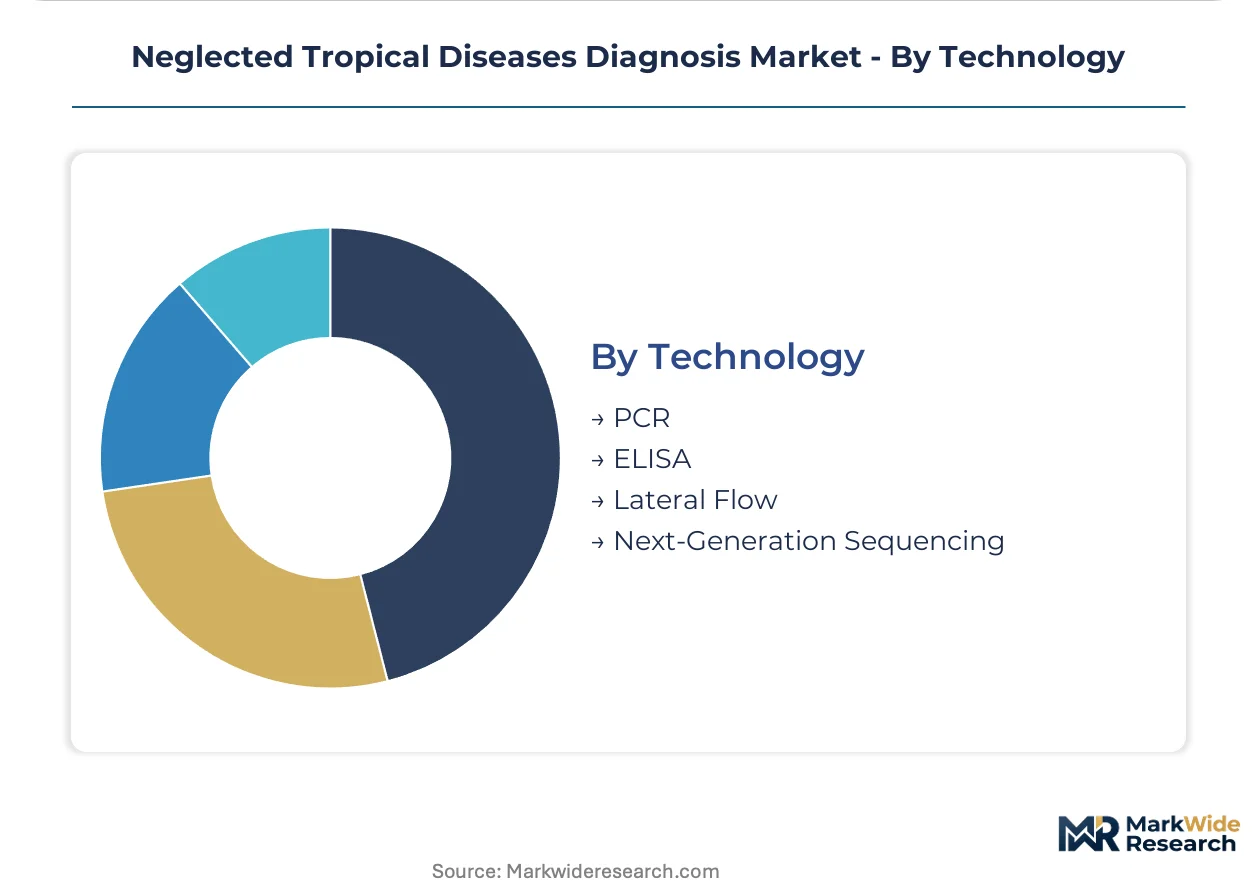
- PCR:Polymerase chain reaction delivers quantitative pathogen detection with established regulatory pathways. Nigerian reference laboratories standardize on these platforms for lymphatic filariasis molecular xenomonitoring.
- Lateral Flow:Immunochromatographic strips require no electricity or cold chain, enabling deployment to village-level health posts. Indonesia's archipelago clinics depend on these for filariasis mapping across remote island chains.
- ELISA:Enzyme-linked assays offer higher throughput than rapid formats for serosurvey applications. Ethiopian public health laboratories process thousands of samples annually through automated plate readers.
- Next-Generation Sequencing:Massively parallel sequencing identifies novel resistance mutations and co-infection patterns. Research partnerships in Brazil apply these for Leishmania strain differentiation.
Lateral flow technology sustains the broadest installed base while next-generation sequencing climbs the fastest among technology categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India exports rapid diagnostic test kits to procurement channels serving Nigeria's national control programs, while German manufacturers supply molecular platforms to reference laboratories across Ghana and Tanzania.
Nigeria
Lymphatic filariasis and onchocerciasis elimination programs drive centralized laboratory investment in Abuja and Lagos. NAFDAC enforces mandatory batch verification protocols that delay novel assay registration by 8-14 months. The Kebbi State health system reports persistent stockout-driven delays in filariasis verification capacity.
Ghana
District hospitals prioritize molecular diagnostics for onchocerciasis confirmation where microscopy skill gaps persist. The national Neglected Tropical Diseases Program centralizes all diagnostic procurement through Global Fund mechanisms. Kumasi's regional laboratory hub serves peripheral testing sites across the Ashanti Region.
Tanzania
National control programs mandate post-treatment prevalence monitoring using standardized immunoassay panels. The country's public health laboratories process thousands of samples annually through automated plate readers in Dar es Salaam. Research consortia in the Lake Zone fund epidemiological surveys through bilateral health partnerships.
Uganda
District hospitals deploy battery-powered LAMP devices for onchocerciasis detection at reduced capital cost versus conventional PCR. The Uganda Virus Research Institute maintains sequencing capacity for emerging pathogen characterization in Entebbe. Satellite clinical validation sites generate diagnostic accuracy data for EU Medical Device Regulation compliance.
Indonesia
Archipelago clinics depend on lateral flow rapid tests for filariasis mapping across remote island chains where cold chain infrastructure remains sparse. The national pharmaceutical regulator enforces import testing requirements that filter non-conforming products from public tenders. Research partnerships in Java apply next-generation sequencing for Leishmania strain differentiation.
Neglected Tropical Diseases Diagnosis Market Key Industry Players
On the supply side, the industry is consolidating around integrated platform manufacturers capable of serving both centralized reference laboratories and peripheral health posts through unified product architectures. Three archetypes dominate competitive positioning: diversified life sciences conglomerates with tropical disease assay portfolios, specialized in vitro diagnostics firms with WHO prequalification expertise, and emerging point-of-care technology developers. Strategic moves concentrate on multiplexing platform convergence and district-level distribution network expansion.
Among diversified diagnostics manufacturers, Abbott Laboratories, F. Hoffmann-La Roche Ltd, and bioMérieux SA occupy positions spanning molecular, serological, and rapid test formats. These firms exemplify the integrated platform archetype through combined automated sample preparation with pathogen-specific detection protocols. Their geographic reach extends across African and Southeast Asian procurement channels where public health organizations aggregate demand through donor-funded vertical disease programs.
| Leading Market Players |
|---|
| Abbott Laboratories |
| F. Hoffmann-La Roche Ltd |
| Thermo Fisher Scientific Inc. |
| bioMérieux SA |
| Siemens Healthineers AG |
| Bio-Rad Laboratories, Inc. |
| Danaher Corporation |
| InBios International, Inc. |
| ZeptoMetrix, LLC |
| Others |
Cost & Logistics Intelligence
Single-source dependency on temperature-controlled reagent manufacturing in Germany and the United States compresses pricing spreads between premium molecular platforms and economy rapid tests while simultaneously forcing supply chain redundancy investments across African distribution networks. WHO prequalification bottlenecks at centralized production sites amplify this concentration risk, widening price gaps between certified and non-certified assay tiers as procurement officers navigate donor-mandated quality thresholds.
Pricing Analysis
The technology-generation pricing gap separates legacy lateral flow strips from current-generation LAMP devices and emerging next-generation CRISPR-based detection platforms. Three-tier pricing structure across premium, standard, and economy levels dominates procurement, with differentiation driven by WHO prequalification status and cold chain infrastructure requirements. Pricing pressure stems from bulk procurement consortia aggregating West African demand, squeezing margins on standardized rapid tests. Public health organizations exhibit highest price sensitivity due to fixed Global Fund allocations, while research institutions tolerate premium pricing for novel multiplex configurations.
Supply Chain Analysis
Tariff exposure between India and Nigeria dominates supply chain risk planning for rapid diagnostic kit importers serving national control programs. Manufacturing concentrates in India, Germany, and the United States, with reagent production drawing from specialized enzyme suppliers in Denmark and synthetic probe manufacturers in Switzerland. Single-source vulnerability persists for lyophilized master mix components essential to field-stable molecular assays. Distribution runs through regional pharmaceutical wholesalers in Nairobi and Lagos before final-mile delivery to district health facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Point-of-care nucleic acid amplification represents a high-growth disruption, with battery-powered isothermal platforms collapsing the cost barrier that previously confined molecular diagnostics to centralized reference laboratories. EU Medical Device Regulation harmonization accelerates this inflection by streamlining clinical validation requirements across endemic markets.
For Market Incumbents: Harden competitive moats through backward integration into lyophilized reagent manufacturing, reducing dependency on European enzyme suppliers vulnerable to cold chain disruptions. Anchor market position by establishing satellite clinical validation sites in Nigeria and Indonesia to compress WHO prequalification timelines against emerging point-of-care specialists. For New Entrants and Emerging Players: District-level health facilities in Kenya's devolved system represent the most penetrable entry point, bypassing centralized procurement bottlenecks through direct-to-facility logistics partnerships. Battery-powered LAMP platforms for onchocerciasis detection in Ugandan district hospitals offer a second white-space target. Pursue dual WHO-FDA qualification pathways to unlock parallel PEPFAR and Global Fund funding streams. For Investors and Strategic Acquirers: Point-of-care technology developers with established district-level distribution networks in sub-Saharan Africa constitute the priority acquisition archetype, capturing infrastructure that incumbents cannot replicate organically. Long-term viability hinges on platform convergence toward multiplex configurations addressing co-endemic pathogen screening. Monitor donor funding shifts from vertical disease programs toward integrated diagnostic platforms as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Pathway | Accelerates market access for manufacturers targeting Global Fund procurement channels in Nigeria and Ghana. |
| District-Level Distribution Partnership | Bypasses centralized laboratory procurement bottlenecks in Kenya's devolved health system. |
| Multiplex Platform Convergence | Captures procurement preference in Southeast Asian co-endemic regions through single-test configurations. |
| Satellite Clinical Validation Site | Generates diagnostic accuracy data for EU Medical Device Regulation compliance in intended-use populations. |
| Lyophilized Reagent Manufacturing Scale-Up | Eliminates cold chain dependency that constrains rural deployment of nucleic acid amplification platforms. |
Research Approach
Cross-validation between procurement officer interviews at Ghana's Neglected Tropical Diseases Program and WHO prequalification database records anchors the qualitative findings. Primary discussions with diagnostic platform engineers, Global Fund supply chain managers, and NAFDAC regulatory affairs leads combined with secondary analysis of FDA Emergency Use Authorization filings, EU MDR technical documentation, and hospital procurement databases. Bottom-up facility-level demand modeling and top-down donor funding allocation analysis provided convergent value estimates.
Calibration against historical procurement volumes from Nigerian and Tanzanian national control programs validated the analytical framework across the projection horizon. Segmentation dimensions modeled include diagnostic platform type, application purpose, end-user category, and technology maturity tier. CAGRs derived from compound growth trajectory analysis incorporating mass drug administration surveillance protocol expansions and point-of-care molecular platform adoption curves. Forecast inputs incorporated LAMP device deployment rates in Ugandan district hospitals and regional procurement consortium formation timelines in West Africa.
Stress conditions across donor funding volatility, regulatory approval delays at NAFDAC, and cold chain infrastructure gaps were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding sustained WHO prequalification requirements and PEPFAR supply chain eligibility criteria. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Hydrogen Breath Test Analyzer Market
Diagnostics
Elisa Tests Market
Diagnostics
Global Diagnostic Radiopharmaceuticals and Contrast Media Market
Diagnostics
Global Coagulation Analyzers Market
Diagnostics
Brain Cancer Diagnostics Market
Diagnostics
Sperm Count Test Market
Diagnostics
Vibrio Diagnostics Market
Diagnostics
H. Pylori Breath Test Kit Market
Diagnostics
US Influenza Diagnostics Market
Diagnostics
Fructosamine Test Market
Diagnostics
HIV Diagnostics Market
Diagnostics
Glucose Biosensors Market
Diagnostics
Preterm Birth Diagnostic Test Kits Market
Diagnostics
Global Chemiluminescence Immunoassay (CLIA) Market
Diagnostics
Global Kidney Cancer Diagnostics Market
Diagnostics
Lipid Panel Test Market