
 Axial Spondyloarthritis Treatment Market | 2026-2036
Axial Spondyloarthritis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Axial Spondyloarthritis Treatment Market Analysis
Biologics-grade manufacturing standards is collapsing the barrier between reference molecules and biosimilar competitors. AbbVie Inc. anchors its position through in-house monoclonal antibody production capacity and rheumatology specialist channel control. Pfizer Inc. leverages global manufacturing scale to supply both originator and biosimilar portfolios across multiple autoimmune indications.
Axial spondyloarthritis treatment encompasses pharmacologic and non-pharmacologic interventions targeting inflammation of the sacroiliac joints and spine, with biologic DMARDs typically requiring cold-chain distribution at two to eight degrees Celsius and subcutaneous or intravenous administration to modulate tumor necrosis factor, interleukin-17, or interleukin-23 pathways. The primary commercial purpose centers on preventing irreversible spinal fusion and preserving functional mobility in patients with both radiographic and non-radiographic disease phenotypes. Biological DMARDs command the dominant margin pool due to patent-protected moieties and specialist-administered dosing protocols that limit commoditization pressure. Specialty clinics represent the fastest-growing end-user channel as integrated care models concentrate biologic infusion and injection training in settings with on-site rheumatology nursing support.
The FDA's Risk Evaluation and Mitigation Strategy requirements for biologic DMARDs shape prescriber certification and patient monitoring protocols, while the EMA's Good Manufacturing Practice inspections for active substance production determine European market access eligibility. Japan's PMDA imposes additional local clinical trial requirements that extend registration timelines for novel interleukin-targeting therapies. Stakeholders must monitor how CMS reimbursement rate adjustments for physician-administered drugs and evolving FDA biosimilar interchangeability standards reshape competitive dynamics between originator and follow-on biologic portfolios.
Market Dynamics
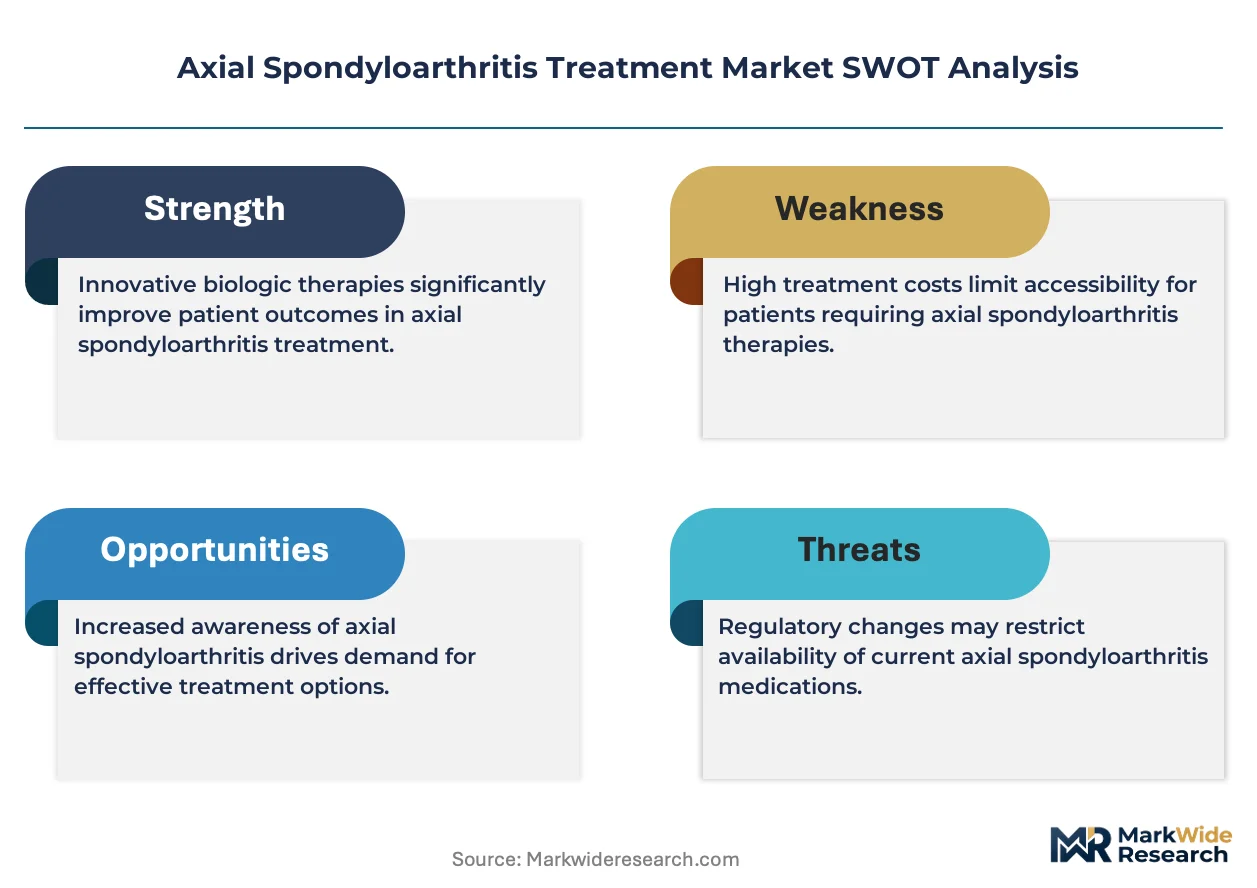
Biologics-grade manufacturing standards is collapsing the barrier between reference molecules and biosimilar competitors, compressing pricing power for originator therapies while expanding patient access across rheumatology networks.
Growth Catalysts
- Accelerated Approval Pathways:The FDA's expedited review mechanisms for interleukin-17 and interleukin-23 inhibitors compress development timelines, enabling faster commercialization of novel biologics targeting non-radiographic disease phenotypes.
- Specialist Infrastructure Expansion:Rheumatology departments in academic medical centers across the United States, Germany, and Japan are standardizing biologic DMARDs as first-line therapy, creating concentrated demand pools with premium reimbursement support.
- Cold-Chain Distribution Maturation:Two-to-eight-degree Celsius logistics networks now reliably reach specialty clinics, reducing site-of-care limitations that previously constrained subcutaneous and intravenous biologic administration.
Market Restraints
- Manufacturing Concentration Risk:Active substance production for monoclonal antibodies concentrates in a limited number of EMA-inspected facilities, creating single-source vulnerability for European market access.
- Input Cost Volatility:Cell culture media and single-use bioreactor components face price instability due to petrochemical feedstock fluctuations, squeezing margin structures for both originator and biosimilar producers.
- Substitution Threat:Interchangeable biosimilars eligible for pharmacy-level substitution in the United States threaten prescriber control over brand selection, accelerating commoditization pressure on reference products.
Strategic Opportunities
- Integrated Care Models:Specialty clinics with on-site rheumatology nursing support represent the fastest-growing end-user channel, capturing patient volume through bundled infusion and injection training services.
- Japan Registration Pathway:PMDA's local clinical trial requirements, while extending timelines, create defensible market positions for sponsors willing to invest in domestic evidence generation for novel interleukin-targeting therapies.
- Oral Small-Molecule Convergence:Janus kinase inhibitors and other oral agents are converging with biologic treatment paradigms, opening white space for combination protocols and sequence-optimized therapy switching.
Industry Challenges
- Prescriber Certification Complexity:FDA Risk Evaluation and Mitigation Strategy requirements demand ongoing prescriber training and patient monitoring protocol adherence, creating administrative burden for rheumatology practices.
- Reimbursement Rate Compression:CMS adjustments to physician-administered drug payment rates directly impact infusion center economics, forcing operational restructuring in hospital outpatient departments.
- IP Licensing Friction:Biosimilar developers face patent thicket navigation around monoclonal antibody formulation and manufacturing process claims, delaying market entry despite regulatory approval.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Axial Spondyloarthritis Treatment Market |
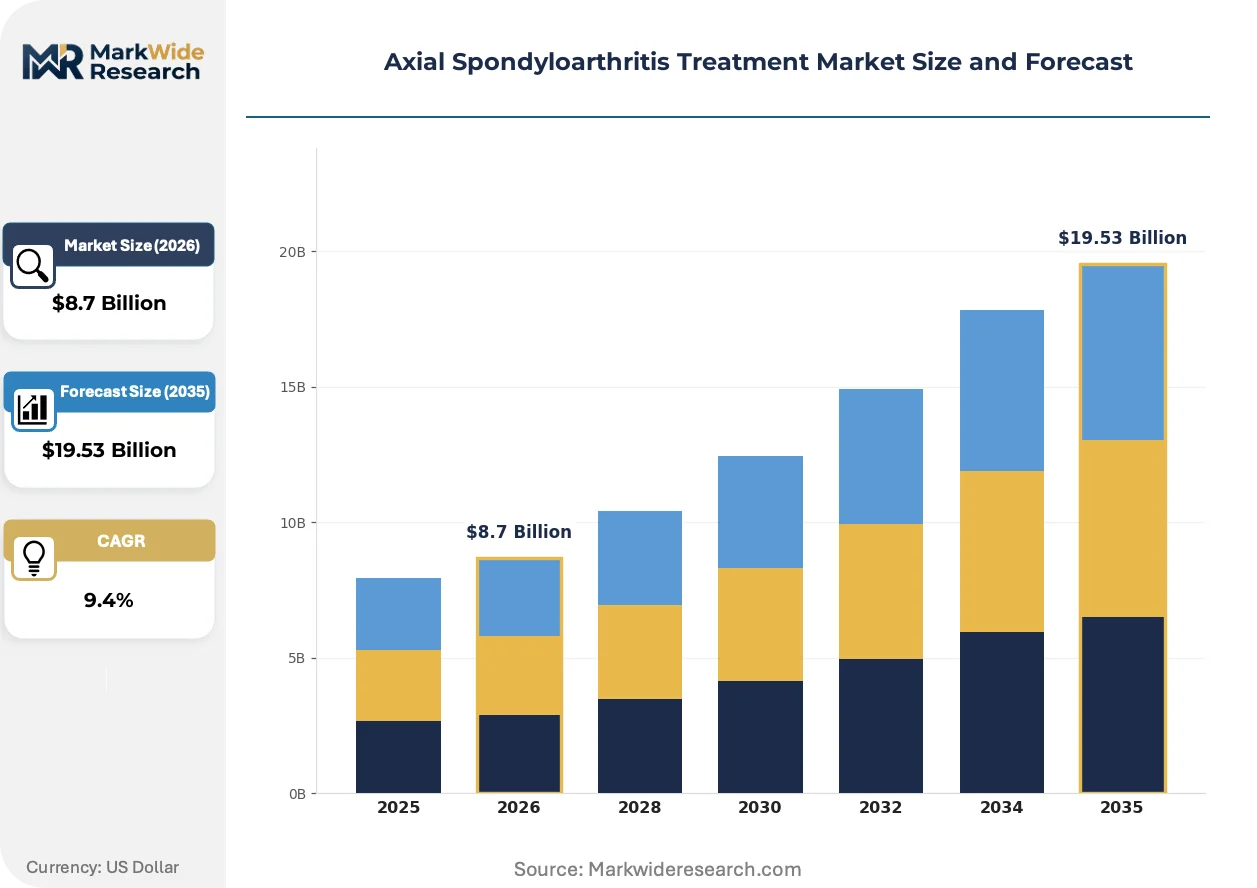
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Non-Steroidal Anti-Inflammatory Drugs, Biological DMARDs, Corticosteroids, Targeted Synthetic DMARDs End User: Hospitals, Specialty Clinics, Homecare, Ambulatory Care Centers Therapy Area: Rheumatology, Orthopedics, Pain Management, Physical Therapy Delivery Mode: Injection, Oral, Infusion, Topical |
| Companies Covered | AbbVie Inc., Pfizer Inc., Novartis AG, Eli Lilly and Company, Johnson & Johnson, UCB S.A., Bristol-Myers Squibb Company, Amgen Inc., Janssen Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Axial Spondyloarthritis Treatment Market Emerging Trajectories
Interleukin pathway modulation is actively reshaping competitive positioning, with novel inhibitor classes displacing tumor necrosis factor blockers in treatment sequencing algorithms and manufacturing scale determining market access viability.
Subcutaneous autoinjector technology is bifurcating patient administration models. These devices enable home-based dosing without infusion center dependency. Academic medical centers in Germany and Japan are rapidly adopting patient self-injection training protocols. The shift is compressing site-of-care revenue pools while expanding addressable patient populations beyond metropolitan specialist networks.
EMA Good Manufacturing Practice inspections for active substance production are tightening European market access eligibility. Facilities failing inspection face suspension of importation rights. Biologics manufacturers with multi-source supply architectures are consolidating production into pre-qualified sites to preempt regulatory disruption.
Integrated care procurement is consolidating biologic purchasing decisions within specialty clinic networks. Hospital systems are replacing fragmented physician-level ordering with centralized pharmacy and therapeutics committee oversight. The United States exhibits the most pronounced concentration, with academic medical center networks capturing disproportionate volume through formulary control mechanisms.
Axial Spondyloarthritis Treatment Market Segmentation
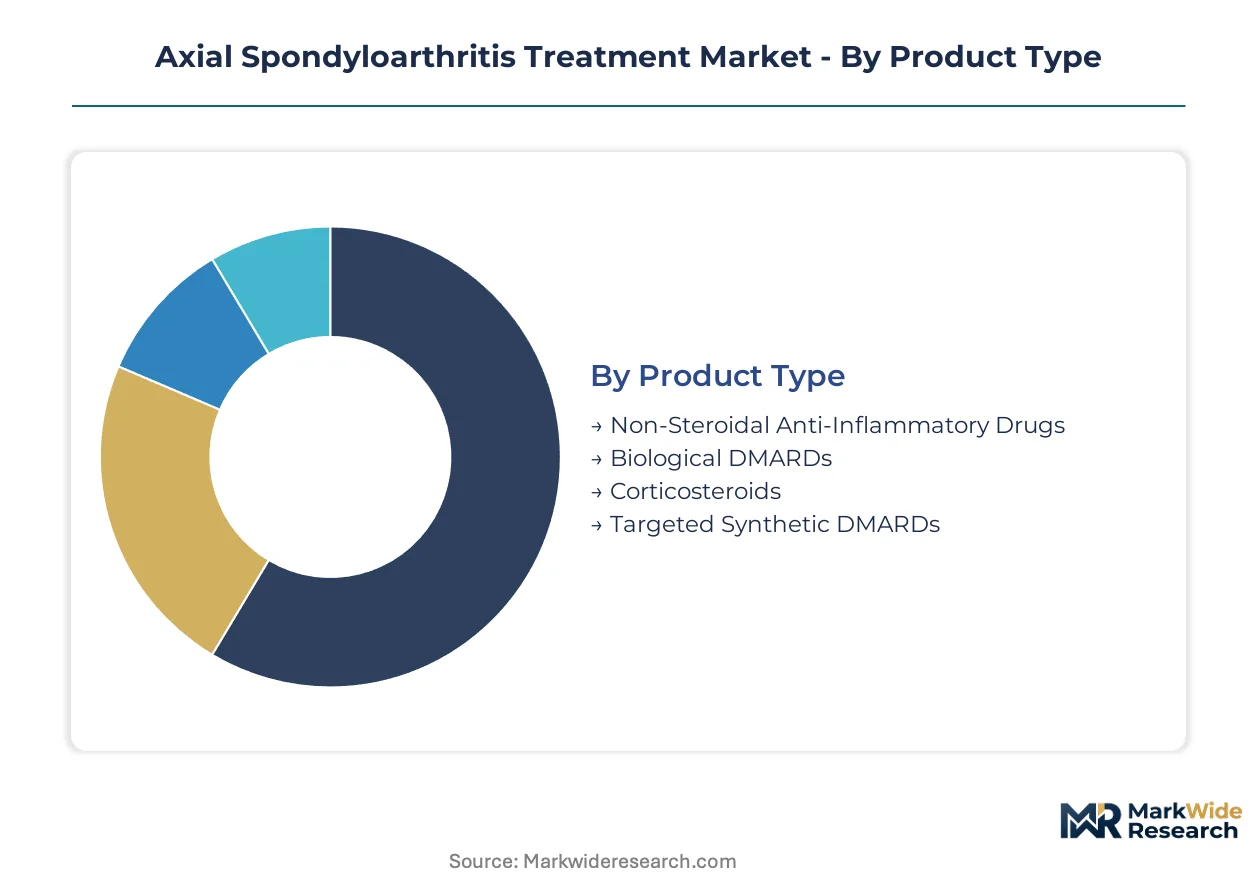
Segmentation in axial spondyloarthritis treatment reveals how reimbursement pathways, site-of-care economics, and molecular complexity allocate margin pools across distinct commercial channels. Understanding these divisions exposes where originator biologics defend pricing power against biosimilar encroachment.
Product Type:
Biological DMARDs capture the dominant margin pool due to cold-chain requirements, patent-protected manufacturing processes, and specialist-administered protocols that resist commoditization.
- Biological DMARDs:Monoclonal antibodies and fusion proteins targeting TNF-alpha, IL-17, and IL-23 pathways require two-to-eight-degree Celsius distribution and subcutaneous or intravenous administration. Demand concentrates in United States academic medical centers and German rheumatology departments where bundled reimbursement supports premium therapy access.
- Non-Steroidal Anti-Inflammatory Drugs:Oral small molecules including celecoxib and diclofenac serve as first-line symptomatic therapy. Volume concentrates in Japan and primary care settings where diagnostic delays prolong non-biologic treatment phases.
- Targeted Synthetic DMARDs:Janus kinase inhibitors offer oral administration with biologic-comparable efficacy. Germany and United States specialists are sequencing these agents before biologic escalation.
- Corticosteroids:Intra-articular and systemic formulations provide short-term flare management. Rheumatology practices in Japan maintain higher utilization rates for bridging therapy.
Biological DMARDs hold installed capacity. Targeted Synthetic DMARDs is rotating up the share rankings.
End User:
Site-of-care migration is redistributing volume toward settings that capture infusion and injection administration revenue.
- Specialty Clinics:Integrated rheumatology centers with on-site nursing support bundle biologic administration, patient education, and monitoring into single-visit protocols. United States hospital outpatient departments and German rheumatology networks are consolidating purchasing decisions through centralized pharmacy committees.
- Hospitals:Academic medical centers maintain high-complexity infusion capacity for intravenous biologics and manage comorbid cases requiring multidisciplinary coordination. CMS reimbursement rate adjustments directly impact hospital outpatient department economics.
- Homecare:Subcutaneous autoinjector technology enables self-administration outside specialist facilities. Patient training programs in Germany and Japan are expanding addressable populations beyond metropolitan centers.
- Ambulatory Care Centers:Freestanding infusion suites compete on convenience and cost for stable patients requiring periodic biologic administration. United States commercial payers are steering volume toward lower-cost settings.
Specialty Clinics are expanding most quickly. Hospitals retain the highest absolute procedure volume.
Therapy Area:
Clinical ownership determines treatment sequencing and biologic adoption timing.
- Rheumatology:Board-certified specialists control biologic DMARD prescribing through FDA Risk Evaluation and Mitigation Strategy certification. United States and German academic centers standardize IL-17 and IL-23 inhibitors as first-line for non-radiographic disease.
- Pain Management:Anesthesiology and physiatry practices manage refractory axial pain with interventional procedures and coordinate biologic referrals. Japanese pain clinics participate in diagnostic pathways for delayed spondyloarthritis recognition.
- Orthopedics:Surgical specialists address structural complications and refer persistent inflammatory cases to rheumatology. German orthopedic-rheumatology collaboration models accelerate biologic initiation.
- Physical Therapy:Rehabilitation professionals deliver non-pharmacologic interventions and monitor functional outcomes that inform treatment escalation decisions. United States integrated care models embed physical therapists within specialty clinic workflows.
Rheumatology holds prescribing authority. Pain Management is climbing the fastest in referral influence.
Delivery Mode:
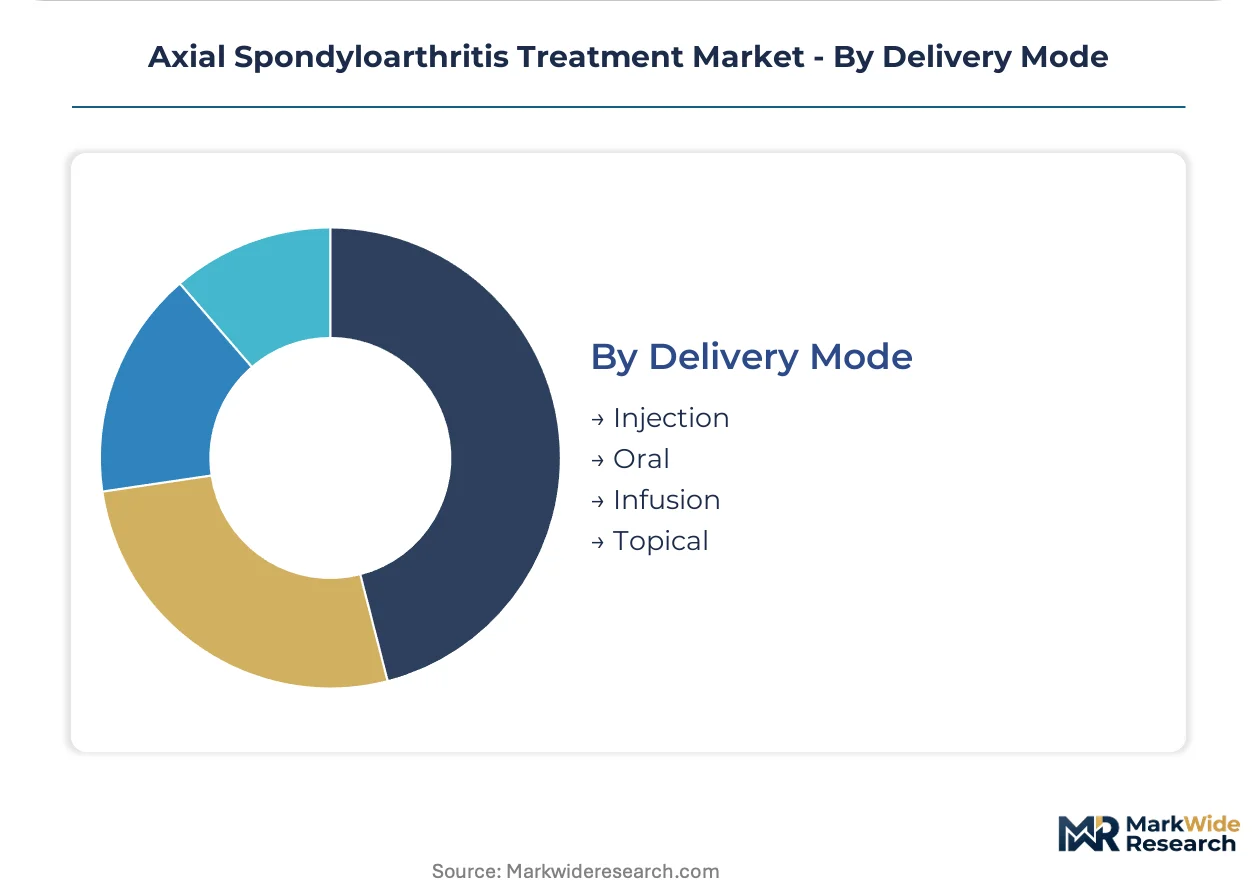
Administration route shapes patient adherence, site-of-care dependency, and competitive dynamics between originator and biosimilar products.
- Injection:Subcutaneous autoinjectors and prefilled syringes enable home administration for TNF and IL-17 inhibitors. Patient self-injection training protocols in Germany and Japan are reducing infusion center dependency.
- Infusion:Intravenous administration in controlled settings supports high-dose induction regimens and manages hypersensitivity risks. United States hospital outpatient departments capture revenue through physician-administered drug billing.
- Oral:Small-molecule formulations eliminate cold-chain requirements and expand geographic reach. Japanese PMDA local trial requirements favor sponsors with established oral agent portfolios.
- Topical:Limited application for peripheral manifestations with minimal systemic absorption. Rheumatology practices in Germany utilize topical NSAIDs as adjunctive therapy.
Injection holds manufacturing investment. Oral is gaining share fastest through convenience differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in biologic DMARDs favor manufacturing-heavy economies, with finished formulations shipped from EMA-inspected facilities to markets lacking domestic monoclonal antibody production capacity. The United States, Germany, and Japan absorb disproportionate volume due to specialist infrastructure density and premium reimbursement frameworks.
United States
Academic medical centers in Boston, New York, and Philadelphia standardize IL-17 and IL-23 inhibitors as first-line therapy for non-radiographic axial spondyloarthritis. FDA Risk Evaluation and Mitigation Strategy requirements shape prescriber certification protocols across rheumatology networks. The Southeast concentration of specialty clinics in Atlanta and Miami captures growing patient volume through bundled infusion services.
Germany
Rheumatology departments in Munich, Berlin, and Hamburg accelerate biologic DMARD adoption through integrated care contracts with statutory health insurers. EMA Good Manufacturing Practice inspections determine European market access eligibility for active substance production. The Baden-Württemberg cluster of biologics manufacturing facilities supplies both domestic demand and export markets.
Japan
PMDA local clinical trial requirements extend registration timelines for novel interleukin-targeting therapies while creating defensible positions for compliant sponsors. Tokyo and Osaka academic centers concentrate specialist prescribing authority. The Kansai region's pharmaceutical manufacturing base supports domestic formulation and packaging operations.
United Kingdom
NICE technology appraisals determine National Health Service reimbursement for biologic DMARDs, constraining prescribing to cost-effectiveness thresholds. London and Manchester rheumatology networks participate in early-access programs for novel mechanism inhibitors. The Cambridge-London corridor houses clinical trial infrastructure for sponsor-sponsored studies.
Canada
Health Canada and PMRA joint review pathways align regulatory standards with FDA determinations, accelerating market entry for approved biologics. Toronto and Vancouver academic centers manage provincial formulary access through centralized pharmacy and therapeutics committees. Ontario's hospital outpatient departments capture infusion administration revenue under physician-administered drug billing.
Axial Spondyloarthritis Treatment Market Vendor Landscape
Listed leaders compete with private specialists across manufacturing scale and channel control dimensions. The market structure consolidates around entities with captive monoclonal antibody production capacity and rheumatology specialist network penetration. Three archetypes dominate: integrated biopharmaceutical conglomerates with in-house manufacturing, mid-cap autoimmune specialists with focused portfolios, and emerging biosimilar developers leveraging abbreviated approval pathways. Competitive moves center on capacity expansion in EMA-inspected facilities and strategic partnerships for cold-chain distribution reach.
Within the integrated conglomerate tier, AbbVie Inc. and Pfizer Inc. anchor positions through manufacturing scale advantages. Novartis AG, Eli Lilly and Company, and Johnson & Johnson occupy the specialist-access tier with rheumatology-focused commercial infrastructure. UCB S.A., Bristol-Myers Squibb Company, and Amgen Inc. exemplify the autoimmune-dedicated archetype with concentrated therapeutic area investment. Janssen Pharmaceuticals represents the hospital-channel specialist model with infusion center network relationships.
| Leading Market Players |
|---|
| AbbVie Inc. |
| Pfizer Inc. |
| Novartis AG |
| Eli Lilly and Company |
| Johnson & Johnson |
| UCB S.A. |
| Bristol-Myers Squibb Company |
| Amgen Inc. |
| Janssen Pharmaceuticals |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between biologics manufacturers and academic medical center networks lock in both supply access and price visibility for monoclonal antibody therapies, insulating originator portfolios from spot-market volatility while embedding volume commitments that sustain EMA-inspected production capacity. United States hospital outpatient departments and German rheumatology networks leverage these contracts to secure cold-chain distribution priority amid input cost fluctuations in cell culture media.
Pricing Analysis
Industrial OEM buyers anchor premium-mid-economy pricing differentiation across biologic DMARD portfolios, with originator monoclonal antibodies commanding tiered premiums based on FDA REMS certification requirements and bundled infusion services while interchangeable biosimilars compress margins in the self-administered subcutaneous segment. Price differentiation rests on patent-protected manufacturing processes and specialist-administered protocols versus pharmacy-level substitution eligibility. Cost compression in the biosimilar tier is intensifying because of abbreviated FDA approval pathways and prescriber control erosion. Rheumatology practices in Japan exhibit highest price sensitivity due to PMDA-mandated local trial cost recovery, while United States academic medical centers show lowest sensitivity through bundled reimbursement mechanisms.
Supply Chain Analysis
United States, Germany, and Switzerland anchor monoclonal antibody active substance production, with Baden-Württemberg and Basel-region facilities supplying both domestic formulation and export markets to Asia-Pacific. Cell culture media, single-use bioreactor components, and purified water systems feed manufacturing operations across these hubs. Single-source vulnerability concentrates in EMA-inspected facilities facing suspension risk from inspection failures. Distribution runs through validated two-to-eight-degree Celsius logistics networks reaching specialty clinics and hospital outpatient departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating around integrated specialty clinic networks and academic medical center procurement committees, fragmenting prescriber-level purchasing autonomy into centralized pharmacy and therapeutics oversight that squeezes originator pricing leverage.
For Market Incumbents: Secure multi-source supply architectures across EMA-inspected facilities to preempt regulatory disruption from single-site inspection failures, while deepening rheumatology specialist channel control through bundled patient education and monitoring services that resist pharmacy-level biosimilar substitution. Interchangeable biosimilars eligible for automatic substitution threaten prescriber brand selection authority. Vertical integration into in-house monoclonal antibody production capacity defends margin structures against input cost volatility. For New Entrants and Emerging Players: Anchor in Japan's extended PMDA registration pathway where local clinical trial investments create defensible market positions for novel interleukin-targeting therapies, while targeting oral small-molecule convergence opportunities in Germany and United States where Janus kinase inhibitors are displacing biologics in treatment sequencing. The penetrable segment lies in homecare self-administration models enabled by subcutaneous autoinjector technology. Go-to-market execution demands patient injection training partnerships with metropolitan rheumatology networks. For Investors and Strategic Acquirers: Autoimmune-dedicated mid-cap specialists with concentrated IL-17 and IL-23 inhibitor pipelines present acquisition targets that compound manufacturing scale with rheumatology commercial infrastructure. Long-term viability hinges on regulatory moat sustainability and cold-chain distribution reach extension. The inflection signal to monitor is FDA biosimilar interchangeability determination timing for TNF-alpha blockers.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | EMA-inspected facility expansion secures European market access eligibility for novel biologics. |
| Regulatory Approval Pathway | FDA accelerated review mechanisms compress development timelines for interleukin-targeting therapies. |
| Strategic Partnership | Specialty clinic network alliances bundle infusion services with patient monitoring protocols. |
| Pipeline Diversification | Oral small-molecule programs complement biologic portfolios in treatment sequencing algorithms. |
| Geographic Expansion | PMDA local trial execution opens defensible positions in Japan's extended registration pathway. |
Methodological Framework
A spread of perspectives from drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers converged on the working assumptions that shaped this analysis, combining structured primary interviews with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Bottom-up patient population estimates and top-down reimbursement flow analysis were triangulated to anchor market sizing.
Segmentation dimensions modeled encompass treatment line, dosage form, administration route, patient population phenotype, and regional regulatory cluster across the analysis window. CAGRs were derived from epidemiological progression modeling and biologic adoption curve analysis, incorporating infusion center capacity expansion rates and biosimilar penetration assumptions as forecast inputs.
Decision-makers should treat outputs as directional under stable reimbursement frameworks and regulatory inspection pass-rate assumptions; material deviation in CMS rate adjustments or EMA facility suspensions would warrant model refresh. Recalibration cycles align with material shifts in biosimilar interchangeability determinations and interleukin inhibitor approval velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Global Myeloproliferative Disorders (MPD) Treatment Market
Specialty Medicine
Granulomatosis with Polyangiitis Treatment Market
Specialty Medicine
Global Stroke Therapeutics Market
Specialty Medicine
Carcinoid Tumor Syndrome Management Market
Specialty Medicine
Carcinoid Syndrome Diarrhea Treatment Market
Specialty Medicine
Hemifacial Spasm Market
Specialty Medicine
Endometriosis Market
Specialty Medicine
ADHD Therapeutics Market
Specialty Medicine
Liver Fibrosis Treatment Market
Specialty Medicine
Nephrogenic Systemic Fibrosis (NSF) Treatment Market
Specialty Medicine
Global Dry Eye Syndrome Treatment Market
Specialty Medicine
Bronchiectasis Therapeutic Market
Specialty Medicine
Cat Scratch Disease (CSD) Treatment Market
Specialty Medicine
Specialty Generics Market
Specialty Medicine
Transthyretin Amyloidosis Treatment Market
Specialty Medicine
Generalized Anxiety Disorder (GAD) Market