
 Whim Syndrome Management Market | 2026-2036
Whim Syndrome Management Market Size, Share, and Industry Trends Forecast 2026-2036
Whim Syndrome Management Market Analytics
Specialized immunology nursing pools is collapsing across tertiary care networks, forcing hospitals to consolidate rare disease treatment into regional hubs. Pfizer sustains broad manufacturing scale across biologics and small-molecule platforms. X4 Pharmaceuticals anchors its position through deep specialization in CXCR4 pathway modulation. Takeda competes via established hematology and immunology channel relationships.
WHIM syndrome management encompasses therapeutic and diagnostic protocols targeting the rare autosomal dominant immunodeficiency characterized by warts, hypogammaglobulinemia, infections, and myelokathexis, with treatment protocols requiring continuous immunoglobulin monitoring and targeted CXCR4 antagonist administration to restore leukocyte trafficking. The primary purpose centers on preventing life-threatening bacterial infections while managing cutaneous manifestations and hematologic dysfunction. Biologics command attention as the fastest-expanding product category due to mechanistic precision in CXCR4 inhibition, while immunosuppressants retain volume leadership through broader accessibility. Combination therapy strategies concentrate margin pools where payers demand demonstrated efficacy across multiple symptom domains.
FDA orphan drug incentives and EMA priority medicines frameworks shape developer pipelines by compressing regulatory timelines and extending market exclusivity for WHIM-targeted therapies. ISO 15189 standards for molecular diagnostic laboratories govern test reliability where genetic confirmation of CXCR4 mutations determines treatment eligibility. Stakeholders must monitor evolving payer evidence requirements for ultra-rare indications as health technology assessment bodies tighten reimbursement criteria for single-gene disorders.
Market Dynamics
FDA orphan drug designation programs and EMA priority medicines frameworks are compressing regulatory timelines for CXCR4-targeted therapies, while specialized immunology nursing shortages force consolidation of rare disease care into regional referral hubs across tertiary networks.
Growth Catalysts
- Orphan Drug Incentives:FDA orphan drug designation and priority review vouchers extend market exclusivity periods, accelerating developer commitment to ultra-rare indications.
- Pediatric Immunology Expansion:Dedicated pediatric immunology units in United States referral centers are deepening diagnostic capacity and patient capture for WHIM syndrome protocols.
- Genetic Diagnostic Precision:ISO 15189-accredited molecular laboratories are standardizing CXCR4 mutation confirmation workflows, streamlining treatment eligibility determination.
Market Restraints
- Plasma-Derived Input Volatility:Immunoglobulin replacement therapy supply depends on fractionated plasma availability, exposing cost structures to donor pool fluctuations and collection center geography.
- Specialized Nursing Concentration:Rare disease immunology expertise clusters in United States academic medical centers, creating access bottlenecks for dispersed patient populations.
- Reimbursement Compression:Health technology assessment bodies in Europe and United States are tightening evidence requirements for single-gene disorder therapies, extending payer negotiation timelines.
Strategic Opportunities
- Subcutaneous Administration Formats:Patient-administered immunoglobulin delivery systems are reducing infusion center dependency and expanding home-based care models.
- Companion Diagnostic Integration:CXCR4 mutation testing bundled with therapeutic protocols creates streamlined reimbursement pathways and treatment initiation workflows.
- Emerging Market Diagnostic Infrastructure:Molecular genetics laboratory networks in India and Brazil are expanding rare disease identification capacity outside traditional referral centers.
Industry Challenges
- Clinical Trial Recruitment Friction:Ultra-rare patient populations require multi-site international protocols, complicating endpoint standardization and regulatory alignment across FDA and EMA jurisdictions.
- Biologics Manufacturing Scale Constraints:CXCR4 antagonist production requires specialized cell culture capacity, limiting batch economics and supply security for small-volume indications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Whim Syndrome Management Market |
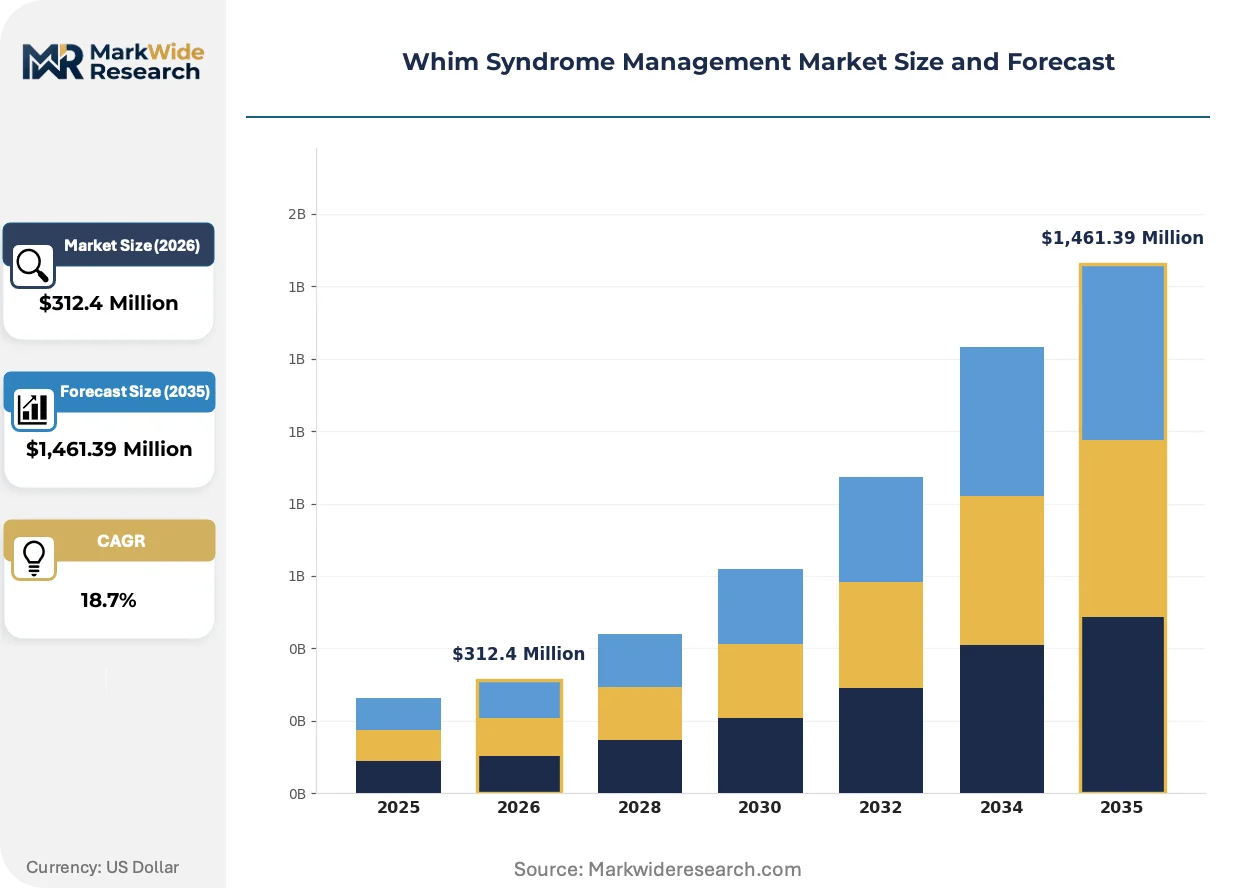
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $1,461.39 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Immunosuppressants, Antihistamines, Steroids, Biologics Application: Pediatric Care, Immunology, Dermatology, Allergy Treatment End User: Hospitals, Outpatient Clinics, Research Laboratories, Home Care Treatment Strategy: Monotherapy, Combination Therapy, Preventive Care, Symptomatic Treatment |
| Companies Covered | X4 Pharmaceuticals, Pfizer, Takeda, Thermo Fisher Scientific, Invitae, Amgen, Sandoz, Rocket Pharmaceuticals, Orchard Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Whim Syndrome Management Market Evolving Landscape
Mechanistic precision in leukocyte trafficking modulation is displacing empirical immunosuppression protocols, while regulatory frameworks and care delivery models co-evolve around patient-centered rare disease management.
Next-generation CXCR4 antagonist formulations are miniaturizing dosing volumes and extending administration intervals. Adult and adolescent patient cohorts in United States academic centers are transitioning from intravenous to subcutaneous delivery platforms. This shift is compressing site-of-care requirements and enabling decentralized treatment monitoring through remote nursing protocols.
EMA's priority medicines designation and FDA's rare disease endpoint advancement pilot are synchronizing evidentiary standards for ultra-rare immunodeficiencies. Developers now align clinical trial designs across Atlantic regulatory frameworks from protocol inception. Biologics developers targeting WHIM syndrome are responding by embedding European sites in United States-led studies to accelerate dual-market authorization.
Patient advocacy organizations are consolidating purchasing influence through dedicated rare disease pharmacy benefit structures. United States specialty pharmacies are displacing traditional hospital outpatient infusion centers for immunoglobulin and biologic delivery. This channel migration concentrates in states with established home health nursing infrastructure and permissive self-administration regulations.
Whim Syndrome Management Market Segmentation
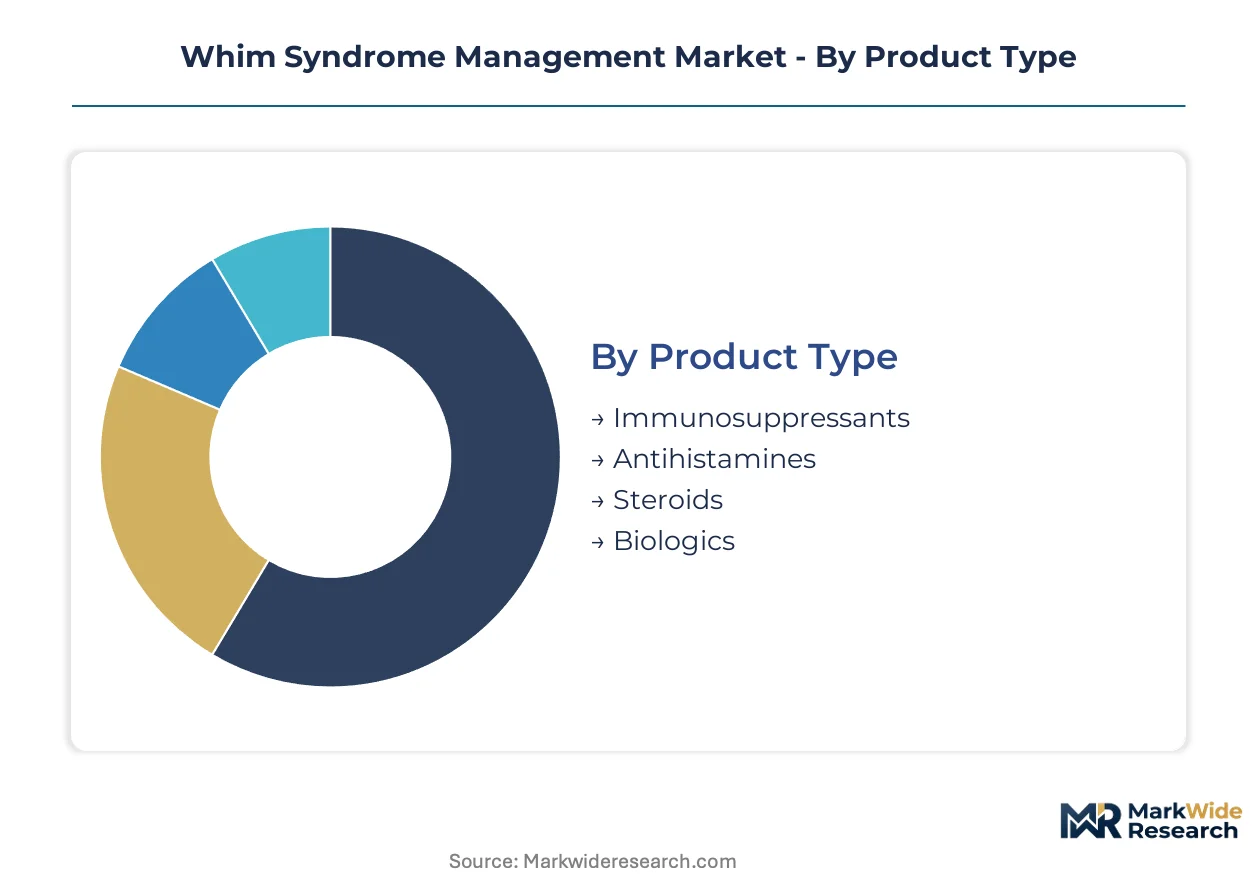
Segmentation in WHIM syndrome management reveals how therapeutic complexity fragments across clinical settings and patient populations. Product innovation, site-of-care economics, and genetic diagnostic precision create distinct commercial zones within this ultra-rare indication.
Product Type:
Domestic production of immunosuppressants and antihistamines anchors supply security in the United States and European manufacturing hubs, while biologics development concentrates in specialized cell culture facilities with export-dependent distribution networks.
- Biologics:Recombinant CXCR4 antagonists engineered for leukocyte trafficking restoration. Demand clusters in United States academic medical centers with dedicated immunology units, driven by mechanistic precision and orphan drug exclusivity incentives.
- Immunosuppressants:Broad-spectrum agents including calcineurin inhibitors and antimetabolites. Volume concentrates in European hospital systems with established plasma fractionation partnerships, constrained by donor pool geography and collection center capacity.
- Steroids:Corticosteroid protocols for acute inflammatory management in cutaneous and pulmonary manifestations.
- Antihistamines:Adjunctive therapy for mast cell-mediated symptoms in dermatology and allergy protocols.
Immunosuppressants command the established base. The steepest expansion runs through Biologics.
Application:
Cost tier stratification separates high-complexity immunology units from volume-driven dermatology and allergy services, with pediatric care commanding premium reimbursement through specialized nursing requirements.
- Immunology:Definitive management protocols encompassing genetic diagnosis, CXCR4 mutation confirmation, and targeted leukocyte trafficking modulation. Patient capture concentrates in United States referral networks with ISO 15189-accredited molecular laboratories, shaped by FDA orphan drug designation pathways and priority review voucher economics.
- Pediatric Care:Early intervention programs for congenital immunodeficiency presentation. Demand localizes in tertiary pediatric centers with dedicated rare disease units, driven by EMA priority medicines frameworks compressing regulatory timelines for pediatric indications.
- Dermatology:Cutaneous wart management and secondary infection prevention in outpatient settings.
- Allergy Treatment:Symptomatic protocols for hypersensitivity manifestations in community practice.
Immunology commands the established base. Pediatric Care is climbing the fastest as diagnostic protocols expand.
End User:
Customer type fragmentation tracks reimbursement complexity, with hospitals retaining high-acuity cases and home care gaining share where subcutaneous administration formats reduce site-of-care dependency.
- Hospitals:Inpatient and outpatient infusion centers managing intravenous immunoglobulin and biologic administration. Volume anchors in United States academic medical centers with specialized immunology nursing pools, constrained by workforce concentration forcing regional hub consolidation.
- Home Care:Patient-administered subcutaneous immunoglobulin and remote nursing protocols. Expansion concentrates in states with permissive self-administration regulations and established home health infrastructure, enabled by specialty pharmacy channel migration.
- Outpatient Clinics:Community-based monitoring and symptomatic management in dermatology and allergy settings.
- Research Laboratories:CXCR4 mutation testing and clinical trial site functions in molecular genetics facilities.
Hospitals command the established base. Home Care is gaining share fastest through decentralized delivery models.
Treatment Strategy:
Maturity differentiation separates long-standing symptomatic approaches from emerging mechanistic protocols, with combination therapy capturing margin where payers demand multi-domain efficacy demonstration.
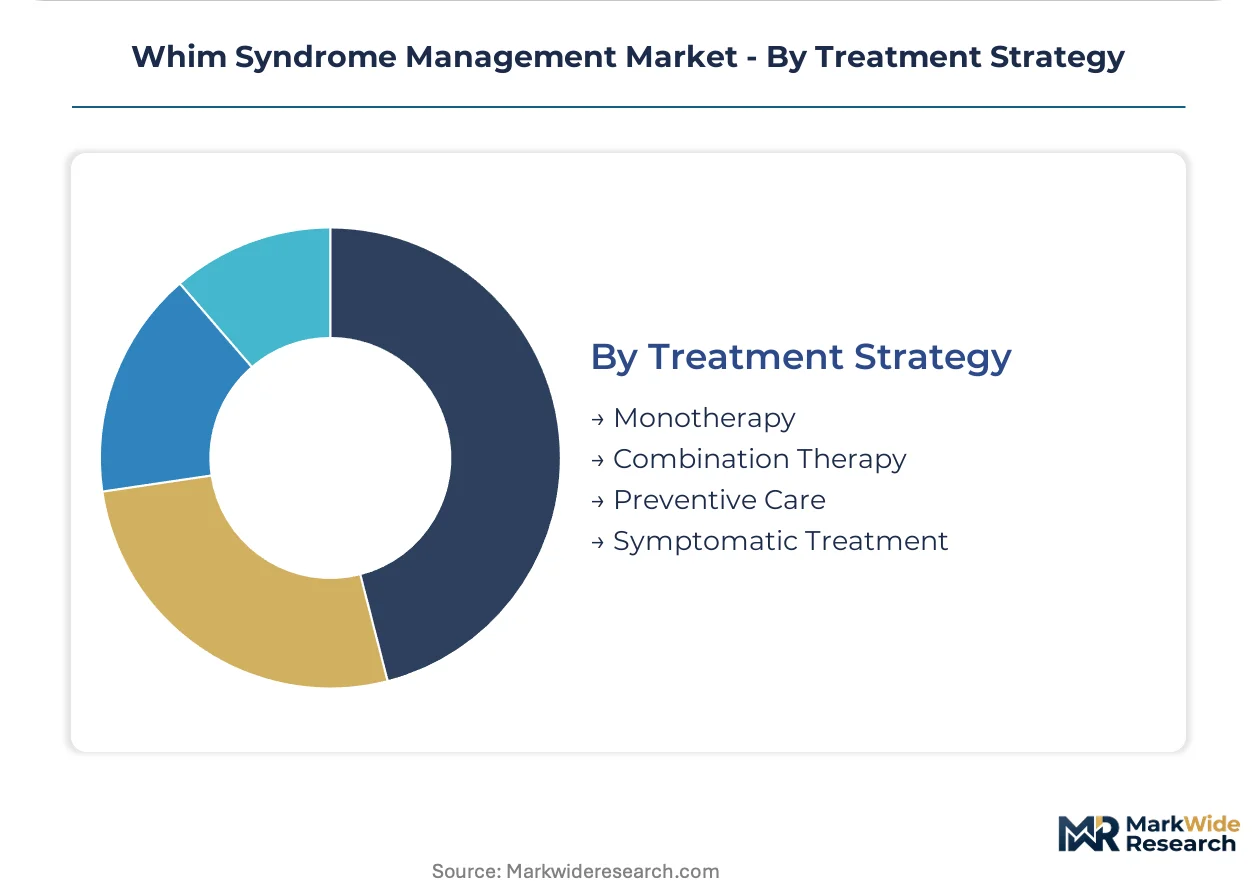
- Combination Therapy:Integrated protocols pairing CXCR4 antagonists with immunoglobulin replacement and antimicrobial prophylaxis. Adoption concentrates in United States specialty pharmacy networks and European hematology centers, driven by payer evidence requirements for ultra-rare indications demanding demonstrated efficacy across infection prevention, hematologic function, and cutaneous domains.
- Preventive Care:Prophylactic immunoglobulin and antibiotic protocols for infection prevention. Implementation localizes in pediatric immunology units with established referral relationships, shaped by health technology assessment bodies tightening reimbursement criteria for single-gene disorders.
- Monotherapy:Single-agent CXCR4 antagonist protocols in genetically confirmed cases.
- Symptomatic Treatment:Empirical management of warts, infections, and cytopenias without genetic targeting.
Symptomatic Treatment commands the established base. Combination Therapy shows the steepest expansion trajectory as mechanistic precision displaces empirical protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates CXCR4-targeted therapy consumption through academic medical centers with dedicated immunology units, while European markets distribute immunoglobulin replacement across hematology networks and emerging economies rely on plasma-derived products for empirical management.
United States
Pediatric immunology expansion and specialty pharmacy channel migration drive demand concentration. FDA orphan drug designation and priority review voucher programs compress regulatory timelines for developers. Boston and New York metro academic centers anchor referral network consolidation as nursing shortages force regional hub formation.
Germany
Established plasma fractionation partnerships and hematology channel relationships sustain immunosuppressant volume leadership. EMA priority medicines frameworks align evidentiary standards with FDA protocols for dual-market authorization. Munich and Heidelberg molecular genetics clusters standardize CXCR4 mutation confirmation workflows under ISO 15189 accreditation.
United Kingdom
Health technology assessment bodies tighten reimbursement criteria for single-gene disorder therapies, extending payer negotiation timelines. NHS specialized commissioning frameworks concentrate rare disease care into designated treatment centers. London and Cambridge immunology units deepen diagnostic capacity through integrated genomic medicine programs.
Japan
PMDA sakigake designation pathways accelerate review for ultra-rare immunodeficiency therapies with unmet medical need. METI industrial competitiveness programs support domestic biologics manufacturing scale-up. Tokyo and Osaka academic medical centers expand dedicated immunology units for congenital immunodeficiency management.
India
Molecular genetics laboratory networks in metropolitan centers expand rare disease identification capacity outside traditional referral systems. CDSCO orphan drug regulations under development aim to mirror FDA incentive structures. Mumbai and Bengaluru diagnostic hubs standardize CXCR4 mutation testing protocols for treatment eligibility determination.
Whim Syndrome Management Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with large-cap pharmaceutical conglomerates leveraging biologics manufacturing scale against focused biotechnology developers concentrating on CXCR4 pathway modulation. The structure bifurcates between hematology-immunology channel incumbents and rare disease specialists pursuing mechanistic precision. Two archetypes dominate: diversified biopharmaceutical platforms with orphan drug portfolio breadth, and single-pathway biotechnology specialists with deep genetic disease expertise. Competitive moves center on regulatory exclusivity capture through priority review vouchers and subcutaneous formulation development to reduce site-of-care dependency.
Among the named developers, X4 Pharmaceuticals exemplifies the single-pathway specialist archetype with concentrated CXCR4 antagonist development, while Pfizer represents the diversified platform model spanning biologics and small-molecule manufacturing capabilities. Takeda occupies a position bridging both tiers through established hematology channel relationships and immunology portfolio breadth. These three anchors illustrate how developer incentives reshape around FDA orphan drug designations and EMA priority medicines frameworks.
| Leading Market Players |
|---|
| X4 Pharmaceuticals |
| Pfizer |
| Takeda |
| Thermo Fisher Scientific |
| Invitae |
| Amgen |
| Sandoz |
| Rocket Pharmaceuticals |
| Orchard Therapeutics |
| Others |
Value Network & Pricing Analysis
FDA orphan drug designation pathways gate both manufacturer qualification and price differentiation in WHIM syndrome therapeutics, compressing regulatory timelines for approved developers while extending market exclusivity windows that insulate premium pricing tiers from immediate generic pressure.
Pricing Analysis
Long-term offtake agreements between United States academic medical centers and specialty pharmacies anchor CXCR4 antagonist pricing, with contract structures spanning 12-36 month terms that bundle genetic testing with therapeutic delivery. Price differentiation separates mechanistic biologics from empirical immunosuppressants, with ISO 15189-accredited diagnostic workflows commanding premium tiers. Pricing pressure stems from health technology assessment bodies tightening evidence requirements for single-gene disorder reimbursement. Pediatric immunology units show highest price sensitivity due to constrained Medicaid formulary budgets, while private referral networks absorb premium positioning.
Supply Chain Analysis
The United States and Germany anchor plasma fractionation capacity for immunoglobulin replacement therapies, with domestic production securing supply security against donor pool volatility. Raw material dependencies center on fractionated human plasma, recombinant cell culture media, and specialized bioreactor components. Single-source vulnerability concentrates in CXCR4 antagonist manufacturing, where small-batch biologics production limits supplier diversification. Distribution runs through specialty pharmacy networks displacing traditional hospital outpatient infusion centers, particularly in states with permissive self-administration regulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through United States specialty pharmacy consolidation and European hospital procurement alliance formation, fragmenting purchasing decisions across fewer intermediaries with expanded formulary control.
For Market Incumbents: Fortify manufacturing scale advantages through backward integration into plasma collection networks and captive bioreactor capacity. Defend against emerging gene therapy substitutes by embedding companion diagnostic workflows within treatment protocols. Priority investment targets subcutaneous formulation development to reduce site-of-care dependency and lock in specialty pharmacy channel relationships. For New Entrants and Emerging Players: Lead with subcutaneous administration platform innovation targeting home care segments where nursing shortages have created service gaps. White-space concentration exists in molecular diagnostic laboratory partnerships outside traditional United States and European referral hubs, particularly in India and Brazil where rare disease identification capacity is expanding. Go-to-market positioning should bundle CXCR4 mutation testing with therapeutic protocols to streamline reimbursement pathways. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across biologics manufacturing scale-up, favoring platform acquisitions over greenfield development. Long-term viability over a decade horizon hinges on regulatory exclusivity capture through priority review voucher accumulation and mechanistic precision displacing empirical protocols. Acquisition target archetype: single-pathway biotechnology specialists with deep CXCR4 genetic disease expertise and existing FDA orphan drug designations. Signal to monitor: EMA-FDA evidentiary standard synchronization accelerating dual-market authorization timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Integration | Bundled CXCR4 mutation testing with therapeutic protocols streamlines payer reimbursement and treatment initiation workflows. |
| Subcutaneous Formulation Development | Patient-administered delivery reduces infusion center dependency and expands home-based care models in nursing-constrained markets. |
| Plasma Collection Network Expansion | Backward integration into fractionated plasma sourcing insulates immunoglobulin supply against donor pool geography constraints. |
| Dual-Market Clinical Trial Design | EMA and FDA protocol alignment from inception accelerates regulatory authorization across Atlantic jurisdictions. |
| Specialty Pharmacy Channel Partnership | Direct relationships with United States rare disease pharmacy benefit structures displace traditional hospital outpatient infusion centers. |
Research Methodology
A spread of perspectives from drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA orphan drug designations, EMA priority medicines submissions, ClinicalTrials.gov protocols, and formulary database snapshots. Bottom-up patient population estimates and top-down market sizing triangulated on volume and value outputs.
Segmentation dimensions modeled include product type, application, end user, treatment strategy, and regional regulatory cluster across the analysis window. CAGRs derived from epidemiological prevalence projections, treatment penetration curves, and pricing trajectory assumptions. Forecast inputs incorporated ISO 15189 laboratory accreditation expansion rates and specialty pharmacy channel migration patterns.
Forecasts assume regulatory continuity in FDA orphan drug incentive structures and EMA priority medicines frameworks; material policy shifts would require re-modeling. Specific risks include plasma supply disruptions, health technology assessment body reimbursement restrictions, and gene therapy substitution effects. Recalibration cycles align with material shifts in regulatory designations, manufacturing scale milestones, and payer evidence requirement changes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Pigmentosa Treatment Market
Specialty Medicine
North America Sports Medicine Market
Specialty Medicine
Hemifacial Spasm Market
Specialty Medicine
Atrophic Vaginitis Treatment Market
Specialty Medicine
Global Bile Duct Cancer Market
Specialty Medicine
Global Stroke Therapeutics Market
Specialty Medicine
Global Wolff Parkinson White Syndrome Market
Specialty Medicine
Global Scleroderma Therapeutics Market
Specialty Medicine
Dupuytrens Disease Market
Specialty Medicine
Acute Lymphoblastic Leukemia Therapeutics Market
Specialty Medicine
Frontotemporal Dementia Management Market
Specialty Medicine
Cutaneous Radiation Injury Treatment Market
Specialty Medicine
Necrobiosis Lipoidica Diabeticorum Market
Specialty Medicine
Diffuse Large B-Cell Lymphoma Therapeutics Market
Specialty Medicine
Rhabdomyosarcoma Treatment Market
Specialty Medicine
Combined Immune Deficiency (CID) Market