
 Systemic Lupus Erythematosus (SLE) Market | 2026-2036
Systemic Lupus Erythematosus (SLE) Market Size, Share, and Industry Trends Forecast 2026-2036
Systemic Lupus Erythematosus (SLE) Market Analytics
Market Context
North American biopharma manufacturing capacity is decoupling from traditional small-molecule batch economics toward flexible biologic production suites. Sanofi leverages its established immunology infrastructure to sustain commercial scale across multiple autoimmune indications. AstraZeneca anchors its SLE portfolio through deep development partnerships in B-cell targeted therapies. Pfizer Inc. competes by extending its inflammation and immunology franchise into rare autoimmune subsets with high unmet need.
Technical Definition and Segment Structure
Systemic Lupus Erythematosus is a chronic multisystem autoimmune disease characterized by loss of self-tolerance, production of autoantibodies against nuclear antigens, and immune-complex mediated tissue damage, requiring sustained immunomodulation to prevent organ-threatening flares. Biologics command the dominant value share as novel monoclonal antibodies displace chronic corticosteroid dependence in refractory patients. Intravenous delivery mode retains primacy for hospital-administered biologics, though subcutaneous formulations are gaining fastest in outpatient rheumatology settings where patient convenience and site-of-care economics reshape prescribing patterns.
Regulatory Framework and Outlook
FDA, EMA, and WHO prequalification standards collectively govern clinical trial endpoints, safety monitoring protocols, and post-market surveillance requirements for SLE therapeutics, with stringent lupus nephritis trial design criteria filtering which candidates advance to registration. The EU AI Act and FDA guidance on real-world evidence are converging to redefine how digital biomarkers and patient-reported outcomes supplement traditional efficacy measures in regulatory submissions. Stakeholders must monitor how payer evidence requirements evolve alongside these regulatory shifts to align development programs with market access thresholds.
Market Dynamics
Biologic infusion capacity expansion in hospital-based rheumatology departments is compressing site-of-care economics and forcing outpatient migration toward subcutaneous alternatives. This infrastructure tension between hospital revenue protection and patient convenience is restructuring prescriber behavior and pharmacy network contracting.
Growth Catalysts
- FDA Accelerated Approval Pathways:Conditional marketing authorizations from the FDA and EMA are compressing development timelines for novel B-cell modulators, enabling earlier patient access to refractory disease therapies.
- Specialty Pharmacy Networks:United States-based coordinated care models are consolidating SLE patient management, reducing fragmentation between rheumatologists, nephrologists, and infusion centers.
- Biologic Production Suites:Flexible manufacturing infrastructure is displacing traditional batch economics, allowing multi-indication immunology assets to achieve commercial scale without dedicated SLE-only facilities.
Market Restraints
- Chronic Corticosteroid Dependence:Deep-rooted prescribing patterns for prednisone and methylprednisolone create inertia against biologic uptake, particularly in community rheumatology practices with limited infusion infrastructure.
- Lupus Nephritis Trial Design:Stringent FDA and EMA endpoint criteria for renal response are filtering development candidates, elevating failure rates in Phase III programs and constraining pipeline diversity.
- Plasma Cell Biology Complexity:Incomplete mechanistic understanding of long-lived plasma cell persistence limits durability of B-cell targeted therapies, necessitating retreatment cycles that burden payers.
Strategic Opportunities
- Digital Biomarker Integration:Patient-reported outcomes and wearable-derived activity metrics are converging with traditional efficacy measures, creating regulatory submission pathways that differentiate novel assets.
- Subcutaneous Formulation Migration:Outpatient rheumatology settings are capturing volume from hospital infusion centers, rewarding developers with convenient delivery platforms and site-of-care cost advantages.
- EU AI Act Convergence:Real-world evidence frameworks are aligning across European markets, enabling post-market surveillance designs that support label expansion and payer negotiations.
Industry Challenges
- Lupus-Specific Clinical Expertise Scarcity:Trial investigators with deep lupus nephritis experience concentrate in academic medical centers, creating site activation bottlenecks that delay enrollment.
- Post-Market Safety Surveillance Complexity:Immunosuppression-related infection risk requires intensive pharmacovigilance infrastructure that strains smaller developers without established autoimmune franchises.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Systemic Lupus Erythematosus (SLE) Market |
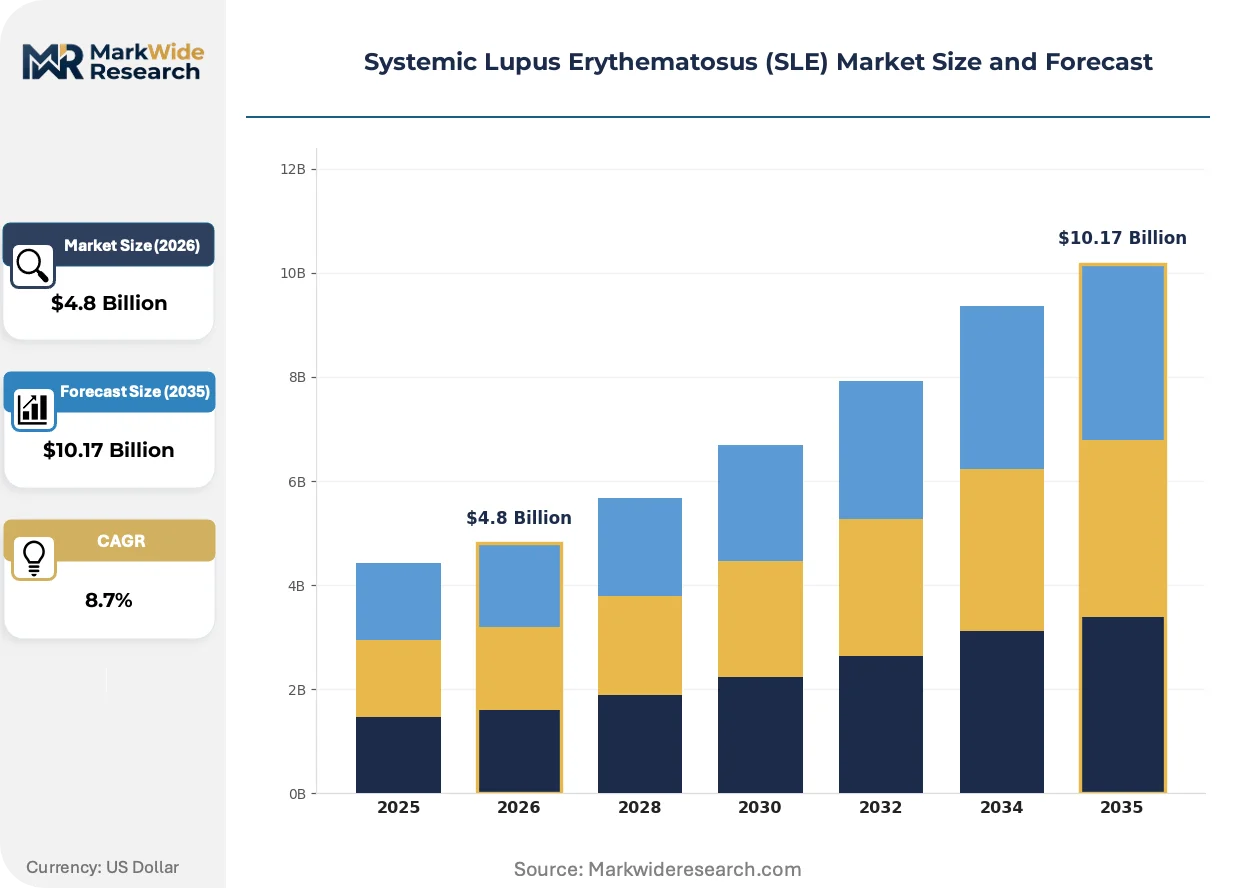
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biologics, Corticosteroids, Immunosuppressants, Antimalarials Therapy Area: Autoimmune Disorders, Rheumatology, Dermatology, Immunology End User: Hospitals, Outpatient Clinics, Specialty Pharmacies, Research Institutes Delivery Mode: Intravenous, Subcutaneous, Oral, Intramuscular |
| Companies Covered | Sanofi, AstraZeneca, Novartis AG, Eli Lilly and Company, Pfizer Inc., GSK plc, Bristol-Myers Squibb Company, UCB S.A., F. Hoffmann-La Roche Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Systemic Lupus Erythematosus (SLE) Market Evolving Landscape
Mechanism-of-action diversification is fragmenting the B-cell targeting landscape beyond CD20 depletion, with novel pathways entering Phase II development. This biological expansion is pressuring incumbent assets to demonstrate differentiated durability or safety profiles.
Type I interferon receptor antagonists are unifying previously distinct patient stratification approaches by matching molecular signature to therapy selection. Academic medical centers in the United States are adopting interferon gene signature testing at accelerating pace, compressing the trial-and-error period for therapy matching and enabling more precise resource allocation across biologic and non-biologic options.
EMA conditional marketing authorization requirements are tightening evidentiary standards for accelerated lupus nephritis approvals, forcing sponsors to pre-specify renal biopsy endpoints and long-term follow-up protocols. European regulators are rejecting surrogate endpoints that previously sufficed for full approval, compelling developers to design larger, longer trials or accept restricted labels with mandatory post-authorization studies.
Patient advocacy organizations are consolidating purchasing influence through specialty pharmacy benefit manager partnerships, unbundling traditional prescriber-pharmacy relationships. United States-based lupus foundations are directing members toward preferred network pharmacies with dedicated nursing support, shifting volume away from hospital-owned infusion centers and compressing margins for sites without competitive convenience offerings.
Systemic Lupus Erythematosus (SLE) Market Segmentation
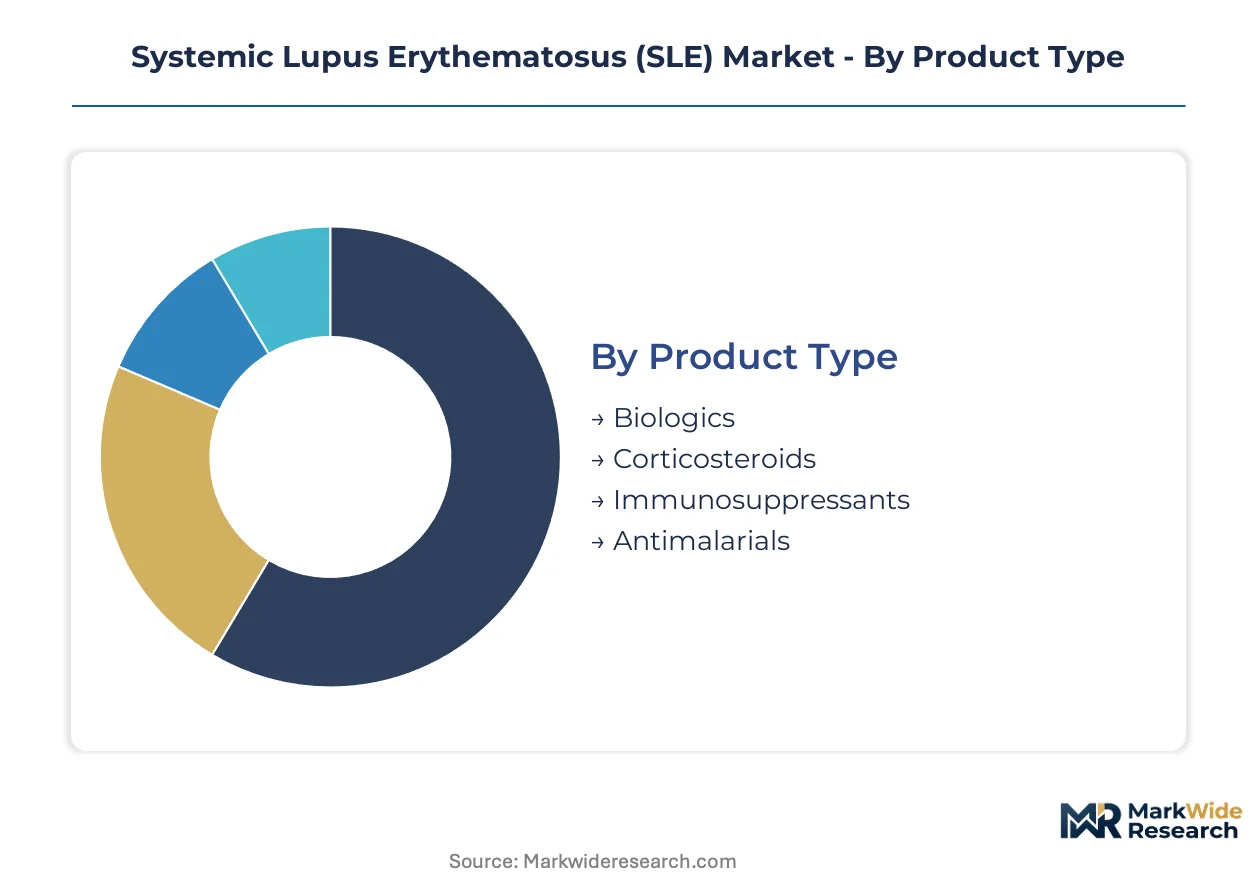
SLE therapeutic segmentation reveals competing site-of-care economics and formulation strategies that reshape prescriber behavior. Biologic manufacturers optimize across delivery modes to capture volume migrating from hospital infusion centers toward outpatient administration.
Product Type:
Monoclonal antibody engineering and small-molecule immunomodulation define the technical axis for commercial differentiation.
- Biologics:Engineered monoclonal antibodies targeting B-cell surface markers or cytokine pathways displace chronic steroid dependence in refractory patients. United States academic medical centers concentrate demand for novel B-cell modulators seeking accelerated FDA approval pathways.
- Corticosteroids:Prednisone and methylprednisolone remain foundational for acute flare management despite long-term toxicity profiles. Community rheumatology practices across Germany and France sustain volume through entrenched prescribing habits and limited infusion infrastructure.
- Immunosuppressants:Azathioprine and mycophenolate mofetil bridge maintenance therapy between biologic cycles.
- Antimalarials:Hydroxychloroquine anchors first-line SLE management with established safety records.
Biologics lead on scale; biologics lead on momentum.
Therapy Area:
Organ-specific expertise concentration determines referral patterns and site-of-care allocation.
- Autoimmune Disorders:Cross-disease immunology platforms allow developers to leverage manufacturing scale across multiple indications. Japanese rheumatology departments prioritize interferon signature testing to stratify patients across biologic and non-biologic options.
- Rheumatology:Hospital-based departments command biologic infusion capacity and complex case referral networks. United Kingdom NHS trusts are consolidating SLE services into designated centers of excellence with embedded clinical trial units.
- Dermatology:Cutaneous lupus subsets drive demand for topical and systemic combination approaches.
- Immunology:Broad immune modulation research supports pipeline expansion into novel mechanism classes.
Rheumatology captures the highest patient volume; autoimmune disorders expand most quickly across indication breadth.
End User:
Revenue protection incentives and convenience economics restructure patient flow between institutional settings.
- Hospitals:Academic medical centers retain complex lupus nephritis cases and biologic infusion capacity with embedded nephrology-rheumatology coordination. United States hospital systems are defending revenue through specialty pharmacy carve-outs that capture dispensing margin.
- Outpatient Clinics:Community rheumatology practices capture stable maintenance patients requiring subcutaneous administration. German ambulatory care networks are expanding nursing support for home-based biologic injection training.
- Specialty Pharmacies:United States-based coordinated care models consolidate prior authorization management and adherence monitoring.
- Research Institutes:Academic trial sites concentrate lupus nephritis expertise and biomarker validation capacity.
Hospitals lead on scale; specialty pharmacies gain share fastest through benefit manager partnerships.
Delivery Mode:
Formulation chemistry and device engineering determine site-of-care flexibility and patient adherence profiles.
- Intravenous:Hospital-administered infusions require refrigeration infrastructure and nursing supervision for hypersensitivity monitoring. French hospital pharmacies maintain tight control over biologic distribution through centralized procurement agreements.
- Subcutaneous:Prefilled syringes and autoinjector devices enable home administration with reduced healthcare utilization. Italian rheumatology practices are converting stable patients from hospital infusion to outpatient subcutaneous protocols.
- Oral:Small-molecule immunosuppressants and antimalarials support chronic maintenance without injection burden.
- Intramuscular:Depot formulations extend dosing intervals for corticosteroid taper protocols.
Intravenous retains the largest installed base; subcutaneous climbs the fastest as outpatient migration accelerates.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are pulling biologic manufacturing toward jurisdictions with streamlined EMA parallel assessment pathways and consolidated health technology appraisal processes, compressing time-to-reimbursement gaps between the United States and select European markets.
United States
FDA accelerated approval pathways for B-cell modulators concentrate demand among academic medical centers with embedded nephrology-rheumatology coordination. The Inflation Reduction Act's Medicare price negotiation provisions are reshaping biologic launch sequencing. Boston and New York Metro clusters retain dominant trial site activation capacity for lupus nephritis programs.
Germany
Hospital-based rheumatology departments in Bavaria and North Rhine-Westphalia defend biologic infusion revenue through specialty pharmacy carve-outs. The Federal Joint Committee's benefit assessment protocols filter which novel immunomodulators achieve statutory reimbursement. Berlin-Brandenburg academic centers concentrate interferon gene signature validation research.
France
ANSM conditional marketing authorizations for accelerated lupus nephritis approvals are tightening evidentiary standards beyond prior EMA flexibility. Hospital pharmacies in Île-de-France maintain centralized procurement control over biologic distribution. Lyon and Marseille rheumatology networks are expanding subcutaneous administration training for outpatient migration.
United Kingdom
NICE technology appraisals for SLE biologics create reimbursement bottlenecks that delay patient access versus continental European timelines. NHS trusts in London and the Midlands are consolidating services into designated centers of excellence with embedded clinical trial units. Manchester and Birmingham are capturing regional referral volume through embedded nephrology coordination.
Japan
PMDA sakigake designation pathways compress development timelines for novel B-cell targeted therapies targeting refractory patient subsets. Tokyo and Osaka rheumatology departments prioritize interferon signature testing to stratify patients across biologic options. Kansai academic centers are validating digital biomarker endpoints for regulatory submission packages.
Systemic Lupus Erythematosus (SLE) Market Competitive Landscape
United States and European Union producers anchor the commercialization tier; Swiss and Japanese specialists hold development-stage positioning. The market structures around consolidated immunology franchises with cross-indication manufacturing scale, fragmented mid-cap biologics developers, and emerging gene-signature diagnostics players. Three archetypes dominate: diversified pharma incumbents leveraging autoimmune infrastructure, biotech specialists with single-asset lupus programs, and academic spinouts commercializing biomarker platforms. Competitive moves center on B-cell biology licensing transactions and subcutaneous formulation acquisitions that capture outpatient volume migration.
Within the diversified pharma tier, Sanofi, AstraZeneca, and Pfizer Inc. exemplify distinct strategic positioning. Sanofi occupies a position anchored through established immunology manufacturing infrastructure spanning multiple autoimmune indications. AstraZeneca sits within the partnership-dependent archetype, relying on deep development collaborations for B-cell targeted therapy access. Pfizer Inc. represents the inflammation-and-immunology franchise extension model, targeting rare autoimmune subsets with high unmet need through portfolio breadth rather than lupus-specific concentration.
| Leading Market Players |
|---|
| Sanofi |
| AstraZeneca |
| Novartis AG |
| Eli Lilly and Company |
| Pfizer Inc. |
| GSK plc |
| Bristol-Myers Squibb Company |
| UCB S.A. |
| F. Hoffmann-La Roche Ltd |
| Others |
Value Network & Pricing Analysis
Flexible biologic production suites are displacing traditional batch economics across North American manufacturing, simultaneously compressing unit production costs and concentrating supply leverage among multi-indication immunology franchises with captive capacity. This technology transition rewards developers who can amortize facility investments across autoimmune portfolios while squeezing single-asset competitors into contract manufacturing dependencies.
Pricing Analysis
Specialty pharmacy carve-outs capture dispensing margin through coordinated prior authorization management and adherence monitoring programs. Three-tier pricing structure across premium biologics, standard immunosuppressants, and economy corticosteroid tiers reflects differentiation by clinical efficacy profile and administration convenience. Pricing pressure stems from Medicare price negotiation provisions in the United States that reshape biologic launch sequencing. Community rheumatology practices exhibit highest price sensitivity due to limited infusion infrastructure and entrenched prednisone prescribing patterns.
Supply Chain Analysis
Regional distribution centers in Massachusetts, North Carolina, and California anchor hub-and-spoke patterns for temperature-controlled biologic distribution. Active pharmaceutical ingredient production draws from Switzerland, Ireland, and Singapore for monoclonal antibody cell culture media and purification resins. Single-source vulnerability concentrates in plasma-derived raw materials and specialized filtration membranes. Distribution runs through hospital-owned specialty pharmacies and independent infusion centers competing for patient volume migration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The SLE therapeutic landscape functions as a stable compounder anchored by chronic disease prevalence and sustained immunomodulation requirements that prevent therapy discontinuation.
For Market Incumbents: To counter outpatient migration toward subcutaneous alternatives, defend hospital infusion revenue through specialty pharmacy carve-outs that capture dispensing margin and deepen nephrology-rheumatology coordination in academic medical centers. Expand flexible manufacturing capacity in North Carolina and Massachusetts to amortize biologic production costs across multiple autoimmune indications. For New Entrants and Emerging Players: FDA accelerated approval pathways in the United States open a window for refractory lupus nephritis candidates with differentiated B-cell mechanisms. Target community rheumatology practices in Germany and France with limited infusion infrastructure and entrenched corticosteroid dependence. Deploy digital biomarker companion platforms to differentiate regulatory submissions and payer negotiations. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap biologics developers with single-asset lupus programs facing Phase III endpoint risk. Long-term viability hinges on cross-indication immunology platform breadth and manufacturing scale rather than SLE-specific concentration. Watch interferon gene signature testing adoption rates in United States academic medical centers as inflection indicator for precision medicine positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Subcutaneous Formulation Development | Captures outpatient volume migrating from hospital infusion centers toward community rheumatology settings. |
| Interferon Signature Diagnostic Partnership | Enables patient stratification across biologic and non-biologic options in Japanese and United States academic centers. |
| EMA Conditional Marketing Authorization Pursuit | Compresses European time-to-market for novel B-cell modulators with pre-specified renal biopsy endpoints. |
| Specialty Pharmacy Network Integration | Consolidates prior authorization management and adherence monitoring through United States benefit manager partnerships. |
| Flexible Manufacturing Scale-Up | Amortizes biologic production costs across multiple autoimmune indications without dedicated SLE-only facilities. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient-flow modeling and top-down revenue triangulation anchored market sizing across the analysis window.
Segment-weighting approaches distributed volume and value across therapy lines, dosage forms, administration routes, and regional regulatory clusters. CAGRs derived from patient prevalence trajectories, treatment penetration curves, and pricing evolution assumptions throughout the forecast period. Forecast inputs incorporated lupus nephritis trial enrollment rates, interferon signature testing adoption patterns, and biologic infusion capacity expansion timelines.
Revisions become necessary when regulatory endpoint criteria tighten, manufacturing capacity constraints materialize, or payer access restrictions expand beyond modeled assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Global Acquired Aplastic Anemia Market
Specialty Medicine
Global Post Traumatic Stress Disorder (PTSD) Therapeutics Market
Specialty Medicine
Irritable Bowel Syndrome (IBS) Treatment Market
Specialty Medicine
Global Graves Disease Market
Specialty Medicine
Diamond-Blackfan Anemia Syndrome Therapeutics Market
Specialty Medicine
Global Pancreatic Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Reactive Arthritis Treatment Market
Specialty Medicine
Fatty Liver Treatment Market
Specialty Medicine
Herpes Zoster (Shingles) Market
Specialty Medicine
Oral Cancer Treatment Market
Specialty Medicine
Ovarian Cysts Market
Specialty Medicine
Epileptic Seizures Treatment Market
Specialty Medicine
Wilms Tumor Treatment Market
Specialty Medicine
Middle East and Africa Kidney Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Cholangiocarcinoma (CCA) Therapeutics Market
Specialty Medicine
Fibroadenoma Market