
 Fibrodysplasia Ossificans Progressiva (FOP) Treatment Market | 2026-2036
Fibrodysplasia Ossificans Progressiva (FOP) Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Fibrodysplasia Ossificans Progressiva (FOP) Treatment Market Foresight
Clinical trial revenue from ACVR1 mutation-targeting programs is reconfiguring how development-stage biopharmas allocate capital across rare disease portfolios. Incyte Corporation leverages its JAK inhibitor infrastructure to sustain discovery efforts in ectopic bone formation pathways. Regeneron Pharmaceuticals anchors its position through genetics-driven target validation, while Blueprint Medicines competes via precision kinase inhibitor platforms.
Fibrodysplasia Ossificans Progressiva treatment encompasses pharmacologic interventions targeting the ACVR1/ALK2 receptor mutation, including small-molecule inhibitors, biologics, and corticosteroid regimens administered to prevent heterotopic ossification flares and preserve joint mobility. Beta-catenin Inhibitors dominate current development pipelines as the mechanism most directly intersects with aberrant bone morphogenetic protein signaling. Intravenous delivery modes capture premium positioning due to hospital-based administration requirements, though subcutaneous formulations represent the fastest-growing delivery category as home care infrastructure matures.
The FDA Orphan Drug Designation and EMA's orphan medicinal product framework shape development economics through tax credits, protocol assistance, and market exclusivity provisions that de-risk FOP therapeutic investment. HIPAA governs patient data flows in US-based natural history studies, while the EU Clinical Trials Regulation standardizes multi-site protocol execution across member states. Stakeholders must monitor ACVR1 variant prevalence data and regulatory precedent from parallel ultra-rare indications to calibrate portfolio prioritization decisions.
Market Dynamics
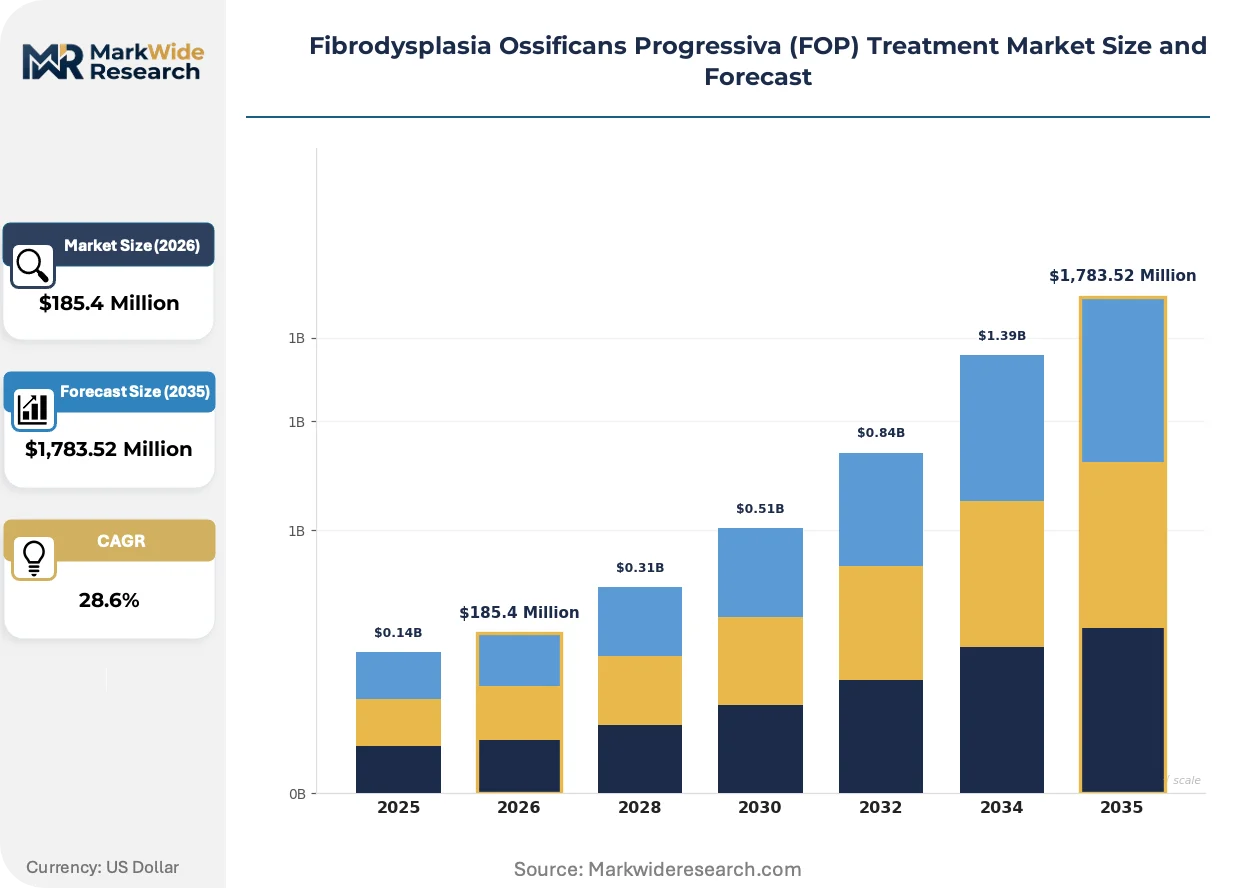
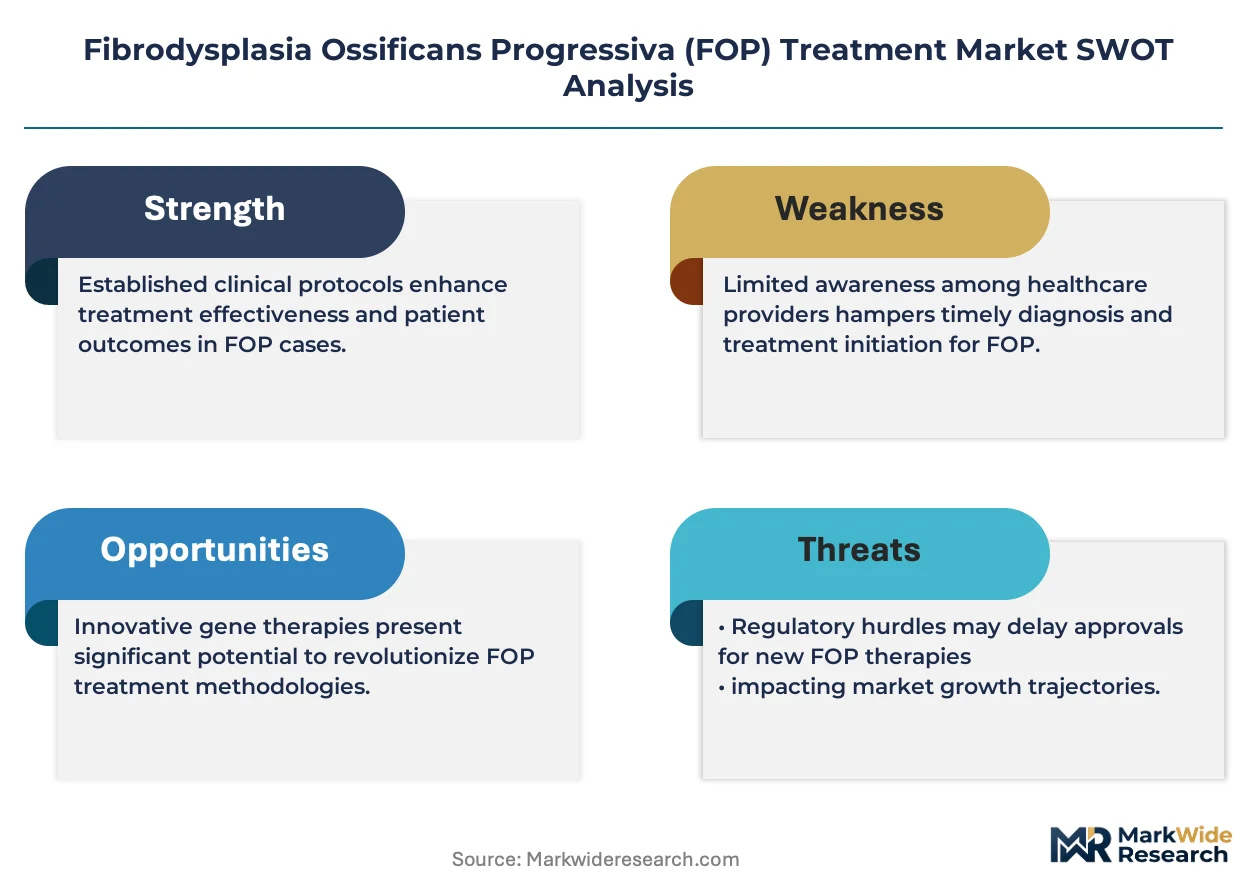
The FDA's Orphan Drug Designation program compresses development timelines for ACVR1-targeting therapies, while EMA's parallel framework accelerates European market entry. This regulatory symmetry is reshaping how biopharmas allocate capital across rare disease portfolios and prioritize kinase inhibitor platforms.
Growth Catalysts
- Orphan Drug Incentives:The FDA's tax credit provisions and seven-year market exclusivity de-risk investment in ultra-rare indications. Developers recoup clinical trial costs through these mechanisms.
- Specialty Clinic Expansion:Dedicated FOP treatment centers in the United States cluster patient populations for natural history studies. These hubs streamline recruitment for ACVR1 mutation trials.
- Genetics-Driven Target Validation:Precision medicine infrastructure enables rapid biomarker identification. This accelerates patient stratification for ALK2 inhibitor programs.
Market Restraints
- Patient Pool Concentration:The United States contains the majority of diagnosed FOP cases globally. Geographic clustering limits trial site diversification and reimbursement negotiation leverage.
- Biologic Manufacturing Complexity:GMP-compliant production of ACVR1-targeting biologics requires single-use bioreactor infrastructure. Capacity constraints at CDMOs extend lead times for clinical supply.
- Substitution by Corticosteroid Regimens:Off-label prednisone protocols remain first-line flare management. Payers resist premium pricing for novel mechanisms without mortality data.
Strategic Opportunities
- Subcutaneous Formulation Development:Home administration infrastructure matures for rare disease biologics. This delivery mode reduces hospital dependency and expands addressable geography.
- EU Clinical Trials Regulation Harmonization:Standardized multi-site protocol execution across member states reduces regulatory fragmentation. Sponsors gain single-submission pathways for cross-border enrollment.
- Patient Advocacy Network Integration:The International Fibrodysplasia Ossificans Progressiva Association accelerates trial awareness. Partnerships with these organizations compress recruitment timelines.
Industry Challenges
- Natural History Study Coordination:HIPAA compliance requirements fragment US patient data flows across institutional review boards. Standardized registry architecture remains underdeveloped.
- Biomarker Validation Timelines:ACVR1 variant prevalence data lacks prospective validation. Regulatory agencies demand genotype-phenotype correlation studies that extend development phases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fibrodysplasia Ossificans Progressiva (FOP) Treatment Market |
| Market Size in 2026 | $185.4 Million |
| Market Size in 2035 | $1,783.52 Million |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beta-catenin Inhibitors, Anti-inflammatory Drugs, Glucocorticoids, Steroids Delivery Mode: Intravenous, Subcutaneous, Oral, Topical End User: Hospitals, Specialty Clinics, Home Care, Research Laboratories Treatment Stage: Early Intervention, Disease Progression, Symptomatic Management, Comprehensive Care |
| Companies Covered | Incyte Corporation, Nobelpharma, Ipsen, Āshibio, Blueprint Medicines, Regeneron Pharmaceuticals, Daiichi Sankyo, Biohaven, AstraZeneca, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fibrodysplasia Ossificans Progressiva (FOP) Treatment Market Shifts & Advancements
ACVR1 mutation biology is reshaping competitive positioning in rare disease therapeutics. Kinase inhibitor platforms and biologics converge on ectopic bone formation pathways, while delivery innovation and regulatory harmonization compress commercialization timelines.
Next-generation ALK2 inhibitors are rendering obsolete the corticosteroid-dependent flare management paradigm. Specialty clinics in the United States adopt these small-molecule platforms for prophylactic administration. The shift from reactive to preventive therapy is compressing hospitalization frequency and reconfiguring payer value demonstration requirements.
EMA's orphan medicinal product framework now mandates pediatric investigation plans for ACVR1-targeting programs. This regulatory requirement accelerates juvenile formulation development. European trial sponsors respond by integrating age-appropriate dosing cohorts into Phase II protocols, expanding addressable patient populations.
Academic medical centers now unbundle after-sales clinical support from drug procurement. Specialty pharmacies assume care coordination functions previously embedded in hospital contracts. This channel disintermediation is most visible in the United States, where integrated delivery networks renegotiate distribution agreements to capture patient data assets.
Fibrodysplasia Ossificans Progressiva (FOP) Treatment Market Segmentation
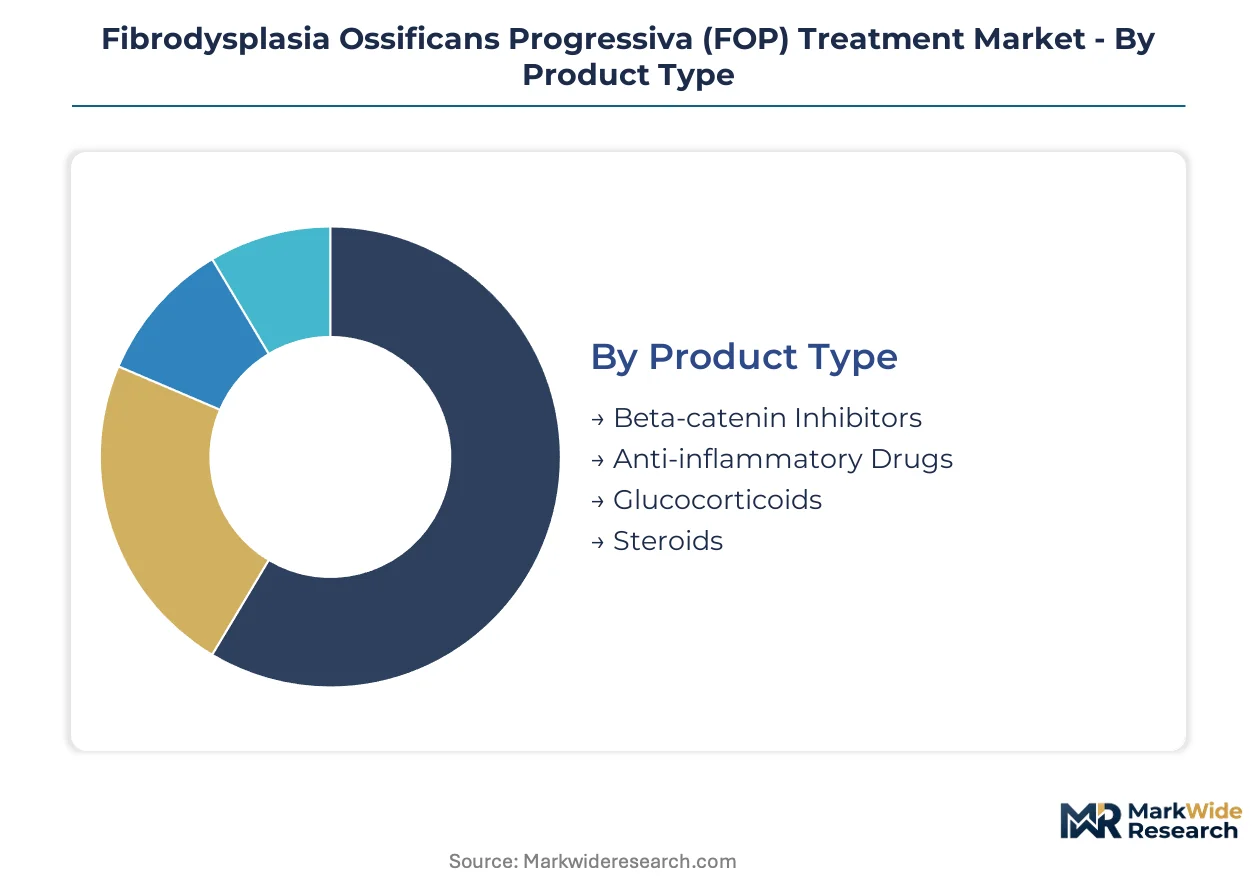
ACVR1 mutation biology fragments FOP treatment demand across mechanism classes, administration settings, and disease progression stages. Each segmentation axis reveals distinct procurement patterns, reimbursement thresholds, and clinical infrastructure requirements that shape commercial strategy.
Product Type:
The use-case spectrum spans prophylactic molecular intervention through reactive flare suppression, with mechanism selection driven by ACVR1 pathway engagement depth and corticosteroid tolerance profiles.
- Beta-catenin Inhibitors:These small-molecule compounds directly antagonize aberrant bone morphogenetic protein signaling downstream of mutated ALK2 receptors. United States specialty clinics concentrate demand as these sites maintain the infusion infrastructure and genetic counseling capabilities required for patient stratification. Regulatory precedent from parallel ultra-rare indications accelerates FDA review timelines for this mechanism class.
- Anti-inflammatory Drugs:NSAID-class agents modulate inflammatory cascades that precede heterotopic ossification flares without addressing root ACVR1 dysfunction. European treatment centers favor these agents for pediatric populations where kinase inhibitor long-term safety data remains incomplete, reflecting EMA pediatric investigation plan requirements.
- Glucocorticoids:High-dose prednisone protocols remain the first-line intervention for acute flare management across all geographies. Payer formularies in the United States reinforce this position through established reimbursement codes and decades of clinical familiarity.
- Steroids:Corticosteroid-sparing regimens incorporating mineralocorticoid receptor modulators address comorbidity burdens in long-term management. Research laboratories in Germany and the United Kingdom drive off-label protocol development for this segment.
Established volume favors Glucocorticoids; emerging adoption favors Beta-catenin Inhibitors.
Delivery Mode:
Cost tier stratification separates hospital-dependent administration from home care economics, with formulation complexity and cold-chain requirements determining channel access.
- Intravenous:Hospital-based infusion suites capture premium positioning for ACVR1-targeting biologics requiring continuous monitoring. United States integrated delivery networks negotiate bundled reimbursement for these encounters, embedding drug procurement within episode-based payment structures.
- Subcutaneous:Prefilled syringe and autoinjector formats enable patient self-administration after specialty pharmacy training. Home care infrastructure maturation in France and the Netherlands expands addressable geography for this delivery mode.
- Oral:Small-molecule kinase inhibitors leverage conventional pharmacy distribution with minimal cold-chain burden. Patient advocacy networks in the United States prioritize oral formulation development to reduce travel burdens for dispersed rural populations.
- Topical:Transdermal patches and localized creams address superficial heterotopic ossification presentations with limited systemic exposure. Academic medical centers in Japan investigate topical NSAID combinations for early-stage joint involvement.
Hospital capture dominates Intravenous revenue; Subcutaneous formats gain share fastest through home care channel expansion.
End User:
Application concentration varies by patient acuity, with high-complexity cases requiring multidisciplinary coordination that only tertiary centers can sustain.
- Hospitals:Academic medical centers manage surgical emergencies, anesthesia complications, and multi-system flare presentations requiring ICU-level monitoring. United States children's hospitals anchor the highest-volume FOP programs through dedicated skeletal dysplasia units.
- Specialty Clinics:Dedicated FOP treatment centers cluster genetic counseling, rehabilitation medicine, and clinical trial access. The International Fibrodysplasia Ossificans Progressiva Association accredits these sites for natural history study participation.
- Home Care:Infusion nursing services and remote monitoring platforms extend treatment access beyond institutional settings. European home care infrastructure matures faster than United States equivalents due to centralized health system procurement.
- Research Laboratories:Natural history study sites and biomarker validation centers operate outside commercial treatment flows. HIPAA compliance requirements fragment United States research laboratory data sharing across institutional review board jurisdictions.
Clinical trial recruitment concentrates in Specialty Clinics; longitudinal management is shifting toward Home Care.
Treatment Stage:
Customer type stratification separates acute intervention budgets from chronic care allocations, with reimbursement codes and outcome metrics diverging across disease trajectory phases.
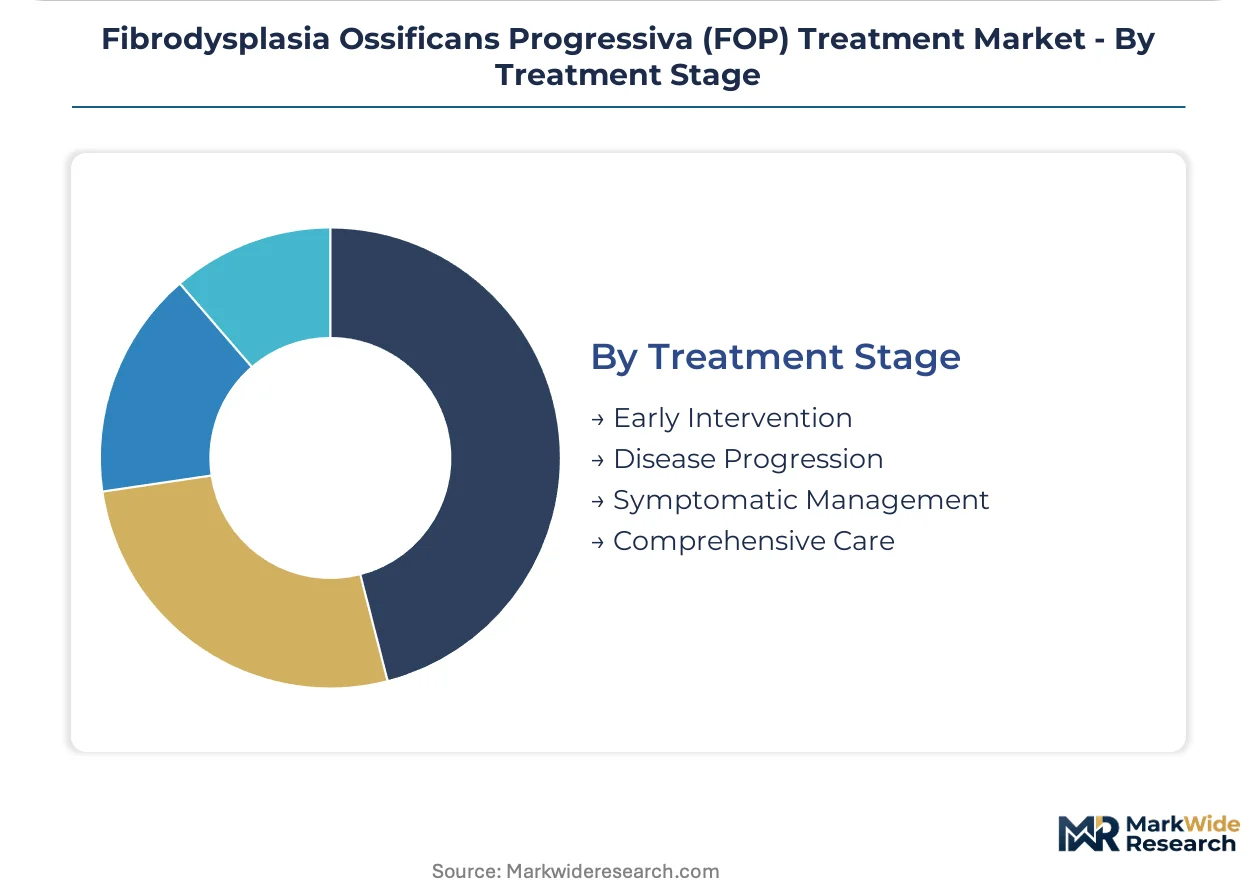
- Early Intervention:Asymptomatic ACVR1 mutation carriers and pediatric patients with minimal ossification receive prophylactic ALK2 inhibitor therapy. EMA pediatric investigation plans mandate inclusion of this population in European trial protocols.
- Disease Progression:Active flare management and emerging joint immobilization drive corticosteroid dependence and emerging small-molecule substitution. United States specialty clinics track progression through validated functional assessment instruments.
- Symptomatic Management:Established heterotopic ossification requires pain control, respiratory support, and adaptive equipment coordination. Payer value demonstration in this stage demands mortality and hospitalization reduction data.
- Comprehensive Care:End-stage disease with thoracic insufficiency syndrome and complete joint ankylosis demands palliative expertise. Hospice partnerships remain underdeveloped for FOP-specific symptom complexes.
Severe case concentration favors Symptomatic Management; pipeline investment prioritizes Early Intervention.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. United States payers resist premium ACVR1 inhibitor pricing without mortality endpoints, while European health technology assessment bodies demand cost-effectiveness thresholds that compress reimbursement rates. Japan's centralized pricing negotiations produce the steepest discounts for novel mechanisms.
United States
Patient advocacy networks cluster in Boston and Philadelphia, driving trial recruitment density. FDA Orphan Drug tax credits offset clinical development costs for ACVR1-targeting programs. The University of Pennsylvania anchors natural history study coordination across 12 specialty clinic sites.
Germany
Academic medical centers in Berlin and Heidelberg maintain Europe's largest FOP patient registries. EMA protocol assistance under the orphan medicinal product framework accelerates ALK2 inhibitor development timelines. The German Federal Institute for Drugs and Medical Devices streamlines pediatric investigation plan approvals.
Japan
PMDA's Sakigake designation system prioritizes review of ACVR1 mutation therapies. Tokyo and Osaka host the Asia-Pacific's only dedicated FOP treatment centers with genetic counseling capabilities. The Ministry of Health, Labour and Welfare's centralized price listing caps annual drug costs at ¥50 million.
United Kingdom
NICE technology appraisals demand quality-adjusted life year thresholds below £30,000 for novel FOP mechanisms. London's Great Ormond Street Hospital coordinates pediatric natural history studies across NHS trusts. The MHRA's innovative licensing pathway accelerates conditional approvals for ultra-rare indications.
France
ANSM's temporary authorization for use framework enables early ACVR1 inhibitor access outside clinical trials. Paris and Lyon house reference centers for rare skeletal dysplasias with mandated multidisciplinary care pathways. The French National Authority for Health's HAS-SMAD transparency committee evaluates orphan drug value demonstration.
Fibrodysplasia Ossificans Progressiva (FOP) Treatment Market Competitive Landscape
Kinase platform specialists and biologics developers split the market into distinct capability camps. The competitive structure concentrates around precision medicine infrastructure and rare disease commercialization experience. Three archetypes dominate: large-cap pharmas with orphan drug divisions, mid-cap biotechs with validated kinase platforms, and emerging gene therapy specialists. Portfolio diversification into adjacent rare bone disorders and geographic expansion through EU regulatory harmonization represent the primary competitive moves.
Within the kinase inhibitor tier, Incyte Corporation and Blueprint Medicines exemplify platform-leveraged development strategies. Regeneron Pharmaceuticals anchors the genetics-driven validation archetype through its human antibody technologies. Among Japan-based developers, Daiichi Sankyo occupies a position reflecting oncology kinase expertise applied to rare disease pathways.
| Leading Market Players |
|---|
| Incyte Corporation |
| Nobelpharma |
| Ipsen |
| Āshibio |
| Blueprint Medicines |
| Regeneron Pharmaceuticals |
| Daiichi Sankyo |
| Biohaven |
| AstraZeneca |
| Others |
Supply & Pricing Matrix
Single-use bioreactor capacity at contract manufacturing organizations in Germany, Switzerland, and the United States concentrates upstream supply for ACVR1-targeting biologics, anchoring margin pools in hospital-based infusion centers and specialty pharmacy networks that control patient access downstream.
Pricing Analysis
After-sales clinical support contracts and patient monitoring services capture lifetime value beyond drug procurement, with three-tier pricing structure across premium, standard, and economy levels stratifying by genetic counseling intensity and flare management protocol complexity. Price differentiation hinges on ACVR1 variant confirmation status and bundled rehabilitation services. Cost compression in the glucocorticoid-sparing tier intensifies as prednisone protocols face substitution pressure from emerging kinase inhibitors. Payer pharmacy benefit managers exhibit highest price sensitivity, while academic medical centers with dedicated FOP programs demonstrate lowest sensitivity due to trial revenue offsets.
Supply Chain Analysis
Lonza, Catalent, and Boehringer Ingelheim hold dominant positions in mammalian cell culture capacity for orphan biologics, with geographic supply concentration in Switzerland, Germany, and Singapore. Raw material dependencies include recombinant protein media, single-use bioreactor bags, and cold-chain packaging validated to IATA standards. Single-source vulnerability at the fill-finish stage creates bottleneck risk for multi-site trial supply. Distribution runs through specialty pharmacy networks with hub-and-spoke models that embed temperature monitoring and patient training.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward integrated delivery networks in the United States as these entities consolidate formulary control and capture patient data assets from fragmented specialty clinic relationships.
For Market Incumbents: Insulate market position through captive supply of ACVR1 biomarker testing services and backward integration into genetic counseling infrastructure. Threats from corticosteroid-sparing regimens and emerging gene therapy platforms demand countermeasures. Priority levers include certification investment in EMA pediatric investigation plans and channel control via exclusive specialty pharmacy partnerships. For New Entrants and Emerging Players: Pursue white-space opportunities in subcutaneous formulation development for home administration and EU-5 market entry under centralized EMA procedures. The most penetrable segment lies in early-intervention prophylactic therapy for pediatric ACVR1 carriers. Go-to-market positioning should emphasize reduced hospitalization burden and payer value demonstration through flare frequency reduction metrics. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across biologics manufacturing infrastructure due to single-use system requirements and cold-chain validation costs. Long-term viability in this market rests on platform leverage across adjacent rare bone disorders and regulatory exclusivity capture. Acquisition targets should display validated kinase inhibitor platforms with orphan drug designation momentum. The signal to watch is FDA breakthrough therapy designation frequency for ACVR1-targeting programs.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Phase II pediatric cohort expansion accelerates EMA pediatric investigation plan compliance. |
| Regulatory Approval Pathway | FDA Orphan Drug Designation secures seven-year market exclusivity and tax credit offsets. |
| Manufacturing Scale-Up | Single-use bioreactor capacity expansion at CDMOs reduces clinical supply lead times. |
| Pipeline Diversification | ALK2 inhibitor platform extension into progressive osseous heteroplasia leverages target biology. |
| Licensing Agreement | Patient advocacy network partnerships compress recruitment timelines for natural history studies. |
Research Methodology
Desk research of FDA orphan drug designations, EMA protocol assistance filings, and ClinicalTrials.gov registries preceded structured interviews with regulatory affairs leads, formulary directors at integrated delivery networks, and specialty clinic program directors. Secondary validation drew from SEC 10-K filings, CMS Medicare Part D claims patterns, and GPO contract databases. Bottom-up patient prevalence estimates and top-down pharmaceutical revenue triangulation anchored market sizing.
Assumptions held fixed across the projection horizon include ACVR1 mutation prevalence rates, current regulatory exclusivity periods, and existing reimbursement code structures. Variables modeled encompass treatment stage migration patterns, delivery mode substitution rates, and regional regulatory harmonization progress. Segmentation dimensions spanned mechanism class, administration route, end-user setting, and disease progression phase. CAGRs derived from log-linear trend fitting to historical orphan drug launch trajectories and adjusted for pipeline probability-weighted revenue recognition. Forecast inputs incorporated specialty clinic expansion rates and patient advocacy network membership growth.
Sensitivities concentrate around ACVR1 variant prevalence revisions, corticosteroid protocol substitution elasticity, and EMA pediatric investigation plan timeline extensions. Forecasts embed assumptions regarding regulatory precedent continuity and payer value demonstration thresholds. Quarterly review of FDA breakthrough therapy designations, EMA protocol assistance grants, and specialty clinic accreditation expansions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Global Autism Spectrum Disorders Market
Specialty Medicine
Global Alcoholic Hepatitis Therapeutics Market
Specialty Medicine
Dural Arteriovenous Fistulas Treatment Market
Specialty Medicine
Narcolepsy Market
Specialty Medicine
Global Liver Cancer Therapeutics Market
Specialty Medicine
Middle-East and Africa Colorectal Cancer Market
Specialty Medicine
Global Pheochromocytoma Market
Specialty Medicine
Healthcare Specialty Enzymes Market
Specialty Medicine
Pulmonary Arterial Hypertension (PAH) Market
Specialty Medicine
Global Allergic Rhinitis Market
Specialty Medicine
US Mobile Physician Practice Market
Specialty Medicine
Genital Warts (Condyloma Acuminatum) Market
Specialty Medicine
Marfan Syndrome Treatment Market
Specialty Medicine
ACTH Deficiency Treatment Market
Specialty Medicine
Radiation Toxicity Treatment Market
Specialty Medicine
Global Psoriatic Arthritis Therapeutics Market