
 Cerebral Vasospasm Market | 2026-2036
Cerebral Vasospasm Market Size, Share, and Industry Trends Forecast 2026-2036
Cerebral Vasospasm Market Analysis
Neurovascular clinics are redrawing procurement priorities toward continuous hemodynamic monitoring systems. Stryker dominates the surgical intervention segment with integrated neurovascular portfolios. B. Braun Melsungen AG anchors European supply chains through specialized catheter manufacturing. Koninklijke Philips N.V. extends its position in diagnostic imaging for subarachnoid hemorrhage detection.
Cerebral vasospasm denotes pathological narrowing of cerebral arteries following aneurysmal subarachnoid hemorrhage, characterized by delayed onset 3-14 days post-bleed and measurable reduction in vessel diameter on digital subtraction angiography. The condition demands urgent intervention to prevent cerebral infarction and permanent neurological deficit. Medications command the largest revenue pool among product types due to sustained nimodipine protocol adherence and emerging endothelin antagonist development. Diagnostic Tools represent the fastest-expanding segment as non-invasive transcranial Doppler systems displace repeated angiography in surveillance protocols. Intravenous delivery mode retains clinical preference in critical care settings where oral administration proves unfeasible.
FDA 510(k) pathways govern neurovascular device commercialization in the United States, while EMA centralized procedures coordinate European market access for pharmaceutical interventions. ISO 13485 certification requirements shape manufacturing quality benchmarks for intracranial monitoring equipment. Stakeholders must weigh reimbursement volatility against the clinical imperative for earlier detection technologies.
Market Dynamics
Neurovascular clinics are consolidating monitoring protocols around continuous hemodynamic surveillance, compressing purchasing cycles for integrated diagnostic-intervention systems and forcing device manufacturers to bundle hardware with algorithmic interpretation services.
Growth Catalysts
- FDA 510(k) Streamlining:The FDA has accelerated clearance pathways for intracranial pressure monitoring devices, reducing time-to-market for novel catheter-based sensors and stimulating R&D investment in minimally invasive form factors.
- Stroke Center Network Expansion:Specialized stroke centers in the United States, Germany, and Japan are scaling bed capacity and procedural volume, generating concentrated demand for nimodipine delivery systems and transcranial Doppler units.
- Digital Subtraction Angiography Integration:Hybrid operating rooms combining angiography with microsurgical capability are becoming standard in tertiary neurovascular centers, pulling through sales of compatible monitoring hardware and contrast injection systems.
Market Restraints
- Reimbursement Volatility:Medicare severity-adjusted diagnosis-related group payments for subarachnoid hemorrhage fluctuate across US hospital systems, creating margin pressure on high-acuity interventions and compressing capital equipment budgets.
- Supply Concentration in Catheter Manufacturing:European supply chains for specialized neurovascular catheters cluster in southern Germany and northern Italy, exposing procurement to single-source dependencies and transport disruption risk.
- Technical Limitation in Non-Invasive Surveillance:Transcranial Doppler ultrasound suffers from operator-dependent variability and bone window constraints in elderly patients, limiting reliable detection of distal vessel vasospasm without confirmatory angiography.
Strategic Opportunities
- Underpenetrated Japanese Tertiary Centers:Japan's neurovascular intervention penetration lags behind US and German benchmarks, presenting expansion opportunity for endothelin antagonist trials and continuous monitoring protocol licensing.
- EMA Centralized Procedure Alignment:The EMA's centralized marketing authorization for orphan neurological indications creates regulatory tailwind for novel vasospasm therapeutics targeting small patient populations with premium pricing potential.
- AI-Enhanced Doppler Interpretation:Machine learning algorithms for automated transcranial Doppler waveform analysis are converging with cloud-based telemetry platforms, enabling remote monitoring services that displace on-site specialist interpretation.
Industry Challenges
- Interventional Neuroradiologist Training Bottleneck:The specialized skill set for microcatheter navigation and aneurysm coiling requires fellowship-level training with limited program slots, constraining procedural capacity expansion regardless of equipment availability.
- ISO 13485 Certification Timeline:Intracranial monitoring device manufacturers face 12-18 month quality system certification cycles, delaying product launches and consuming technical documentation resources that could redirect toward R&D.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cerebral Vasospasm Market |
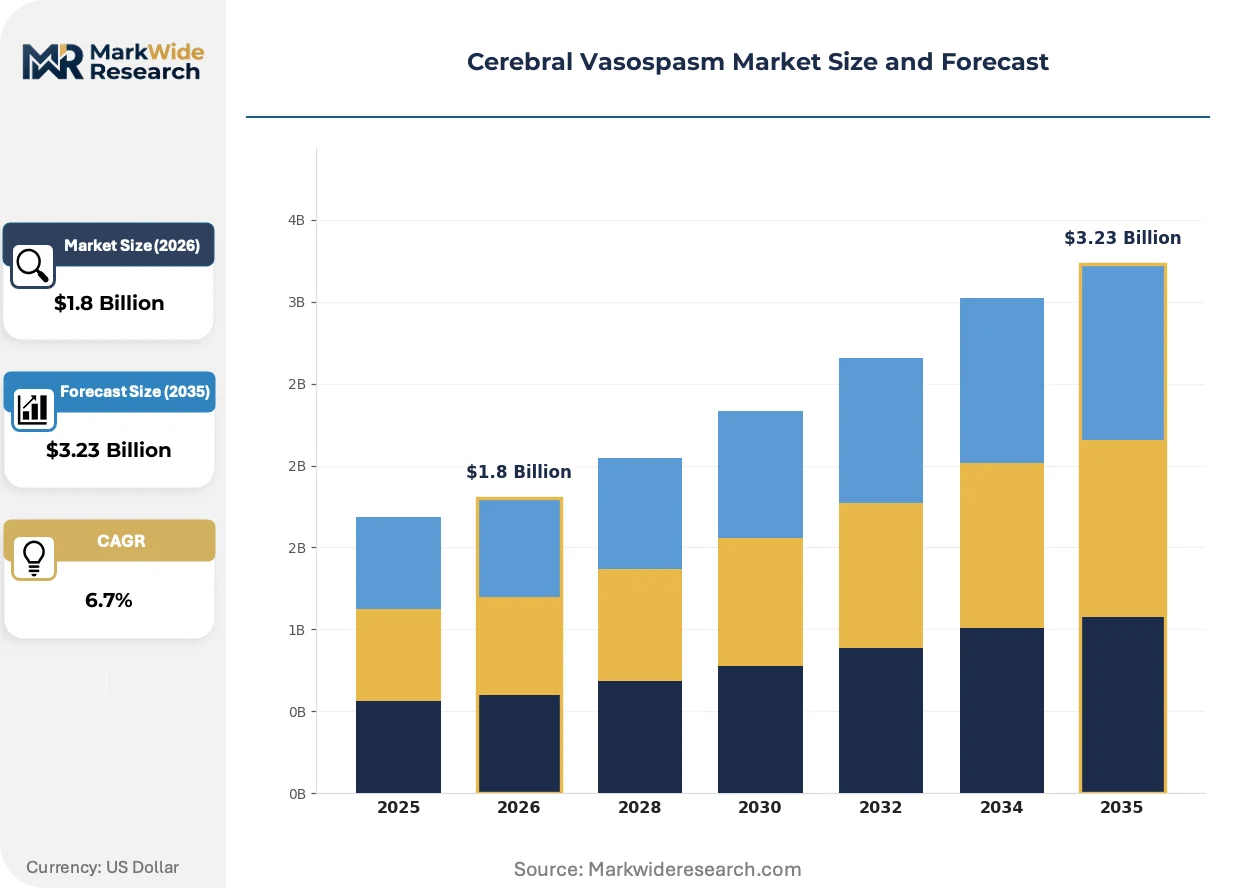
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medications, Surgery, Diagnostic Tools, Support Therapies End User: Hospitals, Clinics, Rehabilitation Centers, Home Care Therapy Area: Neurology, Emergency Medicine, Critical Care, Pain Management Delivery Mode: Oral, Intravenous, Topical, Inhalation |
| Companies Covered | HeadSense Medical, Bristol-Myers Squibb Company, Actelion Pharmaceuticals Ltd, Stryker, Teva Pharmaceutical Industries Ltd., Edge Therapeutics, Inc, B. Braun Melsungen AG, Boston Scientific, Koninklijke Philips N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cerebral Vasospasm Market Emerging Trajectories
Continuous hemodynamic surveillance is displacing episodic assessment in neurocritical care, compressing the window between vasospasm onset and therapeutic intervention while demanding tighter integration between diagnostic hardware and pharmaceutical delivery systems.
Implantable intracranial pressure sensors are miniaturizing from tethered catheter systems toward wireless, bioresorbable formats that eliminate transcutaneous infection risk. Academic medical centers in Boston and Heidelberg are piloting these devices in aneurysmal subarachnoid hemorrhage protocols, with early adoption concentrated in research-intensive stroke centers. This miniaturization is compressing the distinction between acute monitoring and chronic surveillance, opening post-discharge revenue streams for device manufacturers.
The EU Medical Device Regulation is reclassifying active implantable neurological devices from Class IIb to Class III, requiring clinical evidence from prospective studies and notified body consultation for intracranial sensor approvals. Manufacturers with legacy CE marks under the Medical Device Directive face renewal deadlines that demand substantial technical file updates. German and French neurovascular device firms are responding by consolidating regulatory affairs functions and prioritizing MDR-compliant design history files over new product development.
Hospital procurement for neurovascular monitoring systems is consolidating from departmental purchasing toward centralized value analysis committees that bundle capital equipment, disposables, and service contracts into multi-year agreements. This shift compresses vendor access to clinical decision-makers and elevates total cost-of-ownership calculations over device performance specifications. The United States exhibits the most pronounced concentration, with integrated delivery networks in Texas and Florida standardizing across 10+ hospital systems.
Cerebral Vasospasm Market Segmentation
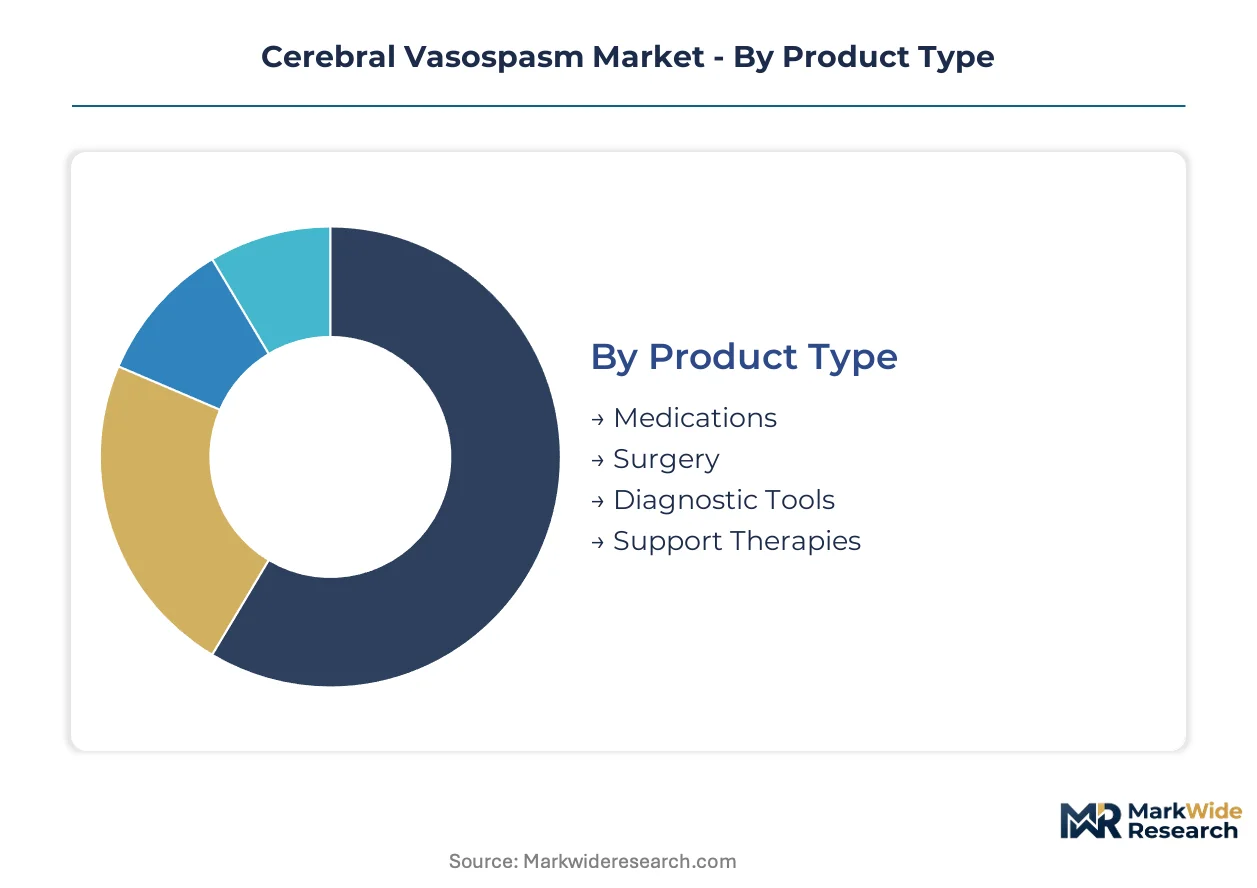
Segmentation in cerebral vasospasm management reveals divergent regulatory pathways and purchasing dynamics across intervention types. Product categories face distinct FDA 510(k) versus EMA centralized approval timelines, while delivery modes trigger different reimbursement coding strategies in Medicare severity-adjusted diagnosis-related groups.
Product Type:
FDA 510(k) clearances govern diagnostic tools and monitoring hardware, while EMA centralized procedures coordinate pharmaceutical market access for endothelin antagonists and nimodipine formulations.
- Medications:Nimodipine calcium channel blockers dominate acute protocol adherence, with sustained-release formulations capturing critical care preference. Demand concentrates in United States stroke centers where Medicare reimbursement supports continuous infusion setups, constrained by generic competition compressing margin structures.
- Diagnostic Tools:Transcranial Doppler ultrasound systems and intracranial pressure monitors enable non-invasive surveillance. Germany and Japan are scaling procurement of portable Doppler units for bedside monitoring, displacing repeated digital subtraction angiography in surveillance protocols.
- Surgery:Microvascular decompression and angioplasty interventions address refractory vasospasm. Academic medical centers in Boston and Heidelberg pilot hybrid operating room integration.
- Support Therapies:Temperature management systems and cerebrospinal fluid drainage adjuncts stabilize hemodynamic parameters. Adoption tracks tertiary center bed expansion.
Medications handle the majority of throughput; Diagnostic Tools is the fastest mover on share.
End User:
Procurement authority varies sharply by facility type, with integrated delivery networks in the United States consolidating purchasing through centralized value analysis committees while European hospital systems retain departmental autonomy.
- Hospitals:Tertiary stroke centers command capital equipment budgets for hybrid angiography suites and continuous monitoring infrastructure. Texas and Florida integrated delivery networks standardize across 10+ hospital systems, compressing vendor access and elevating total cost-of-ownership calculations.
- Clinics:Neurovascular specialty clinics drive ambulatory diagnostic volume for transcranial Doppler surveillance. Outpatient reimbursement codes in Germany support protocol expansion beyond acute episodes.
- Rehabilitation Centers:Post-acute facilities manage neurological deficit recovery. Patient volume tracks aneurysmal subarachnoid hemorrhage survival rates.
- Home Care:Emerging segment for wireless intracranial pressure telemetry. Bioresorbable sensor miniaturization enables post-discharge monitoring revenue streams.
Hospitals absorb the dominant capital expenditure; Home Care is expanding most quickly as wireless formats mature.
Therapy Area:
Specialty certification requirements shape staffing models and device utilization patterns across clinical departments.
- Neurology:Fellowship-trained interventional neuroradiologists perform microcatheter navigation and aneurysm coiling. Limited program slots constrain procedural capacity expansion regardless of equipment availability.
- Emergency Medicine:Front-line subarachnoid hemorrhage stabilization and nimodipine initiation. Door-to-treatment time metrics drive protocol standardization.
- Critical Care:Continuous hemodynamic surveillance and intracranial pressure management. Neurocritical care unit bed expansion in Japan lags US benchmarks.
- Pain Management:Adjunctive therapy for post-hemorrhage headache syndromes. Utilization remains episodic rather than protocol-driven.
Neurology directs the intervention volume; Critical Care is gaining share fastest through monitoring protocol consolidation.
Delivery Mode:
Route selection determines reimbursement coding, supply chain configuration, and patient eligibility for outpatient transition.
- Intravenous:Continuous nimodipine infusion in neurocritical care settings where oral administration proves unfeasible. Retains clinical preference for acute-phase patients with impaired consciousness.
- Oral:Enteral nimodipine for stable patients transitioning from intensive care. Medicare severity-adjusted diagnosis-related group bundling creates margin pressure on pharmaceutical selection.
- Topical:Limited application for transdermal adjunctive agents. Regulatory pathway uncertainty constrains development investment.
- Inhalation:Experimental delivery for targeted cerebral vasodilation. Academic research programs in Heidelberg evaluate nebulized formulations.
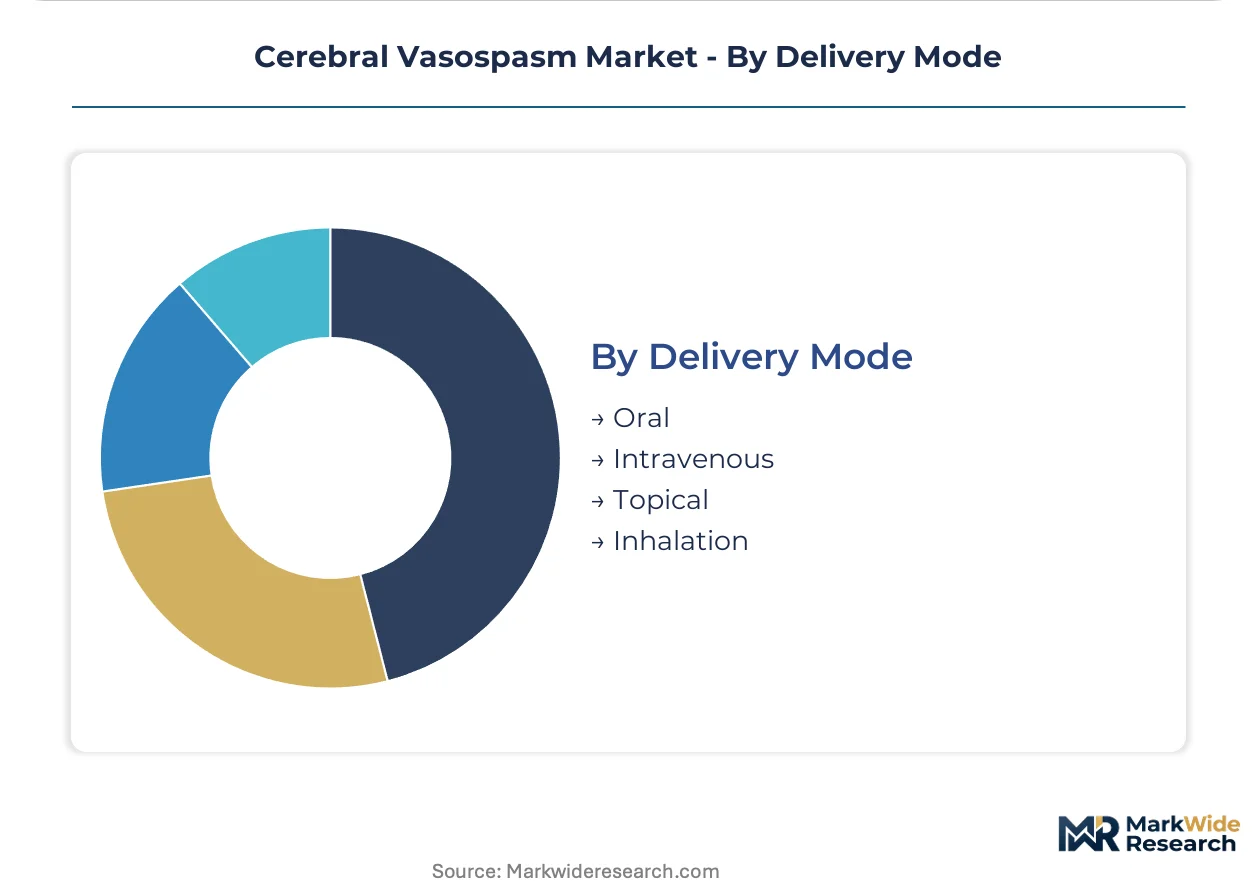
Intravenous maintains the acute-care standard; Oral is climbing the fastest as early mobilization protocols shorten intensive care length of stay.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stroke center procurement teams in the United States, Germany, and Japan concentrate capital expenditure for nimodipine delivery systems and transcranial Doppler units. These three markets absorb the majority of specialized neurovascular device demand through tertiary center network expansion.
United States
Medicare severity-adjusted diagnosis-related group payments shape pharmaceutical selection and capital equipment budgets across integrated delivery networks. FDA 510(k) pathways govern neurovascular device commercialization, accelerating clearance timelines for catheter-based sensors. Texas and Florida health systems standardize procurement across 10+ hospital networks, compressing vendor access to clinical decision-makers.
Germany
Outpatient reimbursement codes support transcranial Doppler surveillance protocol expansion beyond acute episodes. EMA centralized procedures coordinate marketing authorization for pharmaceutical interventions, while EU Medical Device Regulation reclassification demands clinical evidence from prospective studies. Southern German catheter manufacturing clusters face MDR renewal deadlines requiring substantial technical file updates.
Japan
Neurovascular intervention penetration lags US and German benchmarks, presenting expansion opportunity for endothelin antagonist trials. PMDA regulatory frameworks govern pharmaceutical and device market access. Academic medical centers in Tokyo and Osaka pilot hybrid operating room integration for angiography-microsurgical capability.
United Kingdom
NHS specialized commissioning frameworks determine access to nimodipine infusion protocols and continuous monitoring infrastructure. MHRA post-Brexit regulatory autonomy maintains alignment with EMA standards for pharmaceutical approvals. London and Southeast England tertiary centers concentrate interventional neuroradiologist training programs with limited fellowship slots.
Switzerland
Swissmedic marketing authorization requirements create premium pricing potential for orphan neurological indications targeting small patient populations. Cantonal hospital procurement retains departmental autonomy rather than centralized value analysis. Basel and Zurich academic medical centers anchor clinical trial activity for wireless bioresorbable sensor development.
Cerebral Vasospasm Market Vendor Landscape
Player mix skews toward diversified medtech conglomerates with integrated neurovascular portfolios alongside specialized pharmaceutical developers. The competitive terrain exhibits tiered concentration with surgical intervention hardware consolidating around scale-driven manufacturers while diagnostic and therapeutic segments retain fragmentation. Three strategic archetypes dominate: full-stack neurovascular platform providers, nimodipine-focused pharmaceutical specialists, and continuous monitoring technology developers. M&A activity targets algorithmic interpretation capabilities and wireless sensor miniaturization, while geographic expansion concentrates on underpenetrated Japanese tertiary centers.
Within the diversified medtech tier, Stryker, Koninklijke Philips N.V., and B. Braun Melsungen AG represent distinct geographic anchors for platform competition. Stryker exemplifies the integrated surgical intervention archetype through its neurovascular portfolio breadth. Koninklijke Philips N.V. occupies a diagnostic imaging position centered on subarachnoid hemorrhage detection workflows. B. Braun Melsungen AG anchors European supply chain concentration for specialized catheter manufacturing, situating the German conglomerate within critical component dependencies.
| Leading Market Players |
|---|
| HeadSense Medical |
| Bristol-Myers Squibb Company |
| Actelion Pharmaceuticals Ltd |
| Stryker |
| Teva Pharmaceutical Industries Ltd. |
| Edge Therapeutics, Inc |
| B. Braun Melsungen AG |
| Boston Scientific |
| Koninklijke Philips N.V. |
| Others |
Supply Flow & Price Mechanics
Catheter manufacturing scale economies in southern Germany and northern Italy compress unit economics for intracranial pressure sensors while elevating price floors for smaller device entrants lacking comparable batch throughput. This concentration creates asymmetric pricing power across the neurovascular device tier, with ISO 13485-certified manufacturers commanding premium positioning against uncertified challengers.
Pricing Analysis
Cost-plus contracts with raw material indexation dominate procurement agreements for nimodipine formulations and catheter components, insulating B. Braun Melsungen AG and Stryker from commodity volatility while transferring risk to downstream buyers. Price differentiation hinges on FDA 510(k) clearance tier and bundled service contracts, with stroke center networks in Texas and Florida exhibiting lowest price sensitivity due to standardized procurement across integrated delivery networks. Cost compression in generic nimodipine is intensifying because Medicare severity-adjusted diagnosis-related group bundling limits pharmaceutical margin recovery. Outpatient clinics in Germany demonstrate highest price sensitivity, driving demand for portable transcranial Doppler units over fixed angiography suites.
Supply Chain Analysis
Strategic stockpiling of specialized neurovascular catheters prevails over just-in-time inventory given the 12-18 month ISO 13485 certification timelines and single-source dependencies in southern German manufacturing clusters. Supply concentrates in Germany, Italy, and the United States for microcatheter systems, with raw material dependencies spanning medical-grade polymers, platinum-iridium alloys for radiopaque markers, and precision-machined hypotubes. Single-source vulnerability in European catheter manufacturing exposes procurement to transport disruption risk, particularly for academic medical centers in Boston and Heidelberg piloting wireless bioresorbable sensors. Distribution runs through hospital value analysis committees in the United States and departmental procurement in European cantonal systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cerebral vasospasm market operates as a regulatory-moat story where FDA 510(k) clearance timelines and ISO 13485 certification cycles create entrenched switching costs that protect incumbent positioning against rapid competitive displacement.
For Market Incumbents: Fortify algorithmic interpretation capabilities through acquisition of machine learning Doppler analysis platforms, defending against AI-enabled entrants threatening remote monitoring revenue streams. Deepen backward integration into bioresorbable polymer supply to secure wireless sensor manufacturing capacity ahead of EU Medical Device Regulation Class III reclassification deadlines. Prioritize certification investment in Japanese PMDA pathways to capture underpenetrated tertiary center expansion. For New Entrants and Emerging Players: Remote specialist interpretation services represent the most penetrable service-layer gap, where incumbent device manufacturers under-serve community hospitals lacking on-site interventional neuroradiologists. Target Japanese stroke centers for endothelin antagonist trial partnerships and continuous monitoring protocol licensing. Pursue cloud-based telemetry platforms as the primary go-to-market angle, displacing capital-intensive hardware sales with subscription-based surveillance services. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors wireless bioresorbable sensor developers with MDR-compliant design history files and prospective clinical evidence packages. Long-term viability across the projection horizon rests on regulatory entrenchment rather than manufacturing scale, making acquisition targets with cleared Japanese PMDA or Swissmedic orphan indication pathways most defensible. Monitor EMA centralized procedure approval velocity for novel vasospasm therapeutics as the signal to watch for inflection in premium pricing potential.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Stryker and Boston Scientific compress clearance timelines for catheter-based pressure sensors through predicate device strategies. |
| CE Marking Pathway Consolidation | German and French device firms prioritize MDR-compliant technical files over new product development to meet renewal deadlines. |
| Hospital System Partnership | Texas and Florida integrated delivery networks standardize procurement across 10+ facilities, elevating total cost-of-ownership calculations. |
| Software Companion Development | Machine learning algorithms for automated transcranial Doppler waveform analysis enable remote monitoring service revenue streams. |
| Reimbursement Strategy Alignment | Medicare severity-adjusted diagnosis-related group bundling shapes pharmaceutical selection and capital equipment budgets across US networks. |
Methodological Framework
Cross-validation between hospital procurement database analysis and CMS Medicare reimbursement filings anchors the qualitative findings on nimodipine protocol economics and stroke center capital expenditure patterns. Primary interviews with interventional neuroradiologists, neurocritical care unit directors, biomedical engineers, and GPO contracts managers combined with secondary validation from FDA 510(k) filings, EMA centralized procedure submissions, ClinicalTrials.gov entries, and hospital value analysis committee records. Bottom-up device shipment modeling and top-down pharmaceutical revenue triangulation converge on segment-level estimates.
Sensitivity analysis around regulatory approval velocity and stroke center bed expansion assumptions shapes the analytical framework across the projection horizon. Segmentation dimensions span product type, delivery mode, end-user facility tier, and regional regulatory cluster, with CAGRs derived from fitted growth curves adjusted for Medicare reimbursement volatility and EU MDR compliance cost absorption. Industry-specific forecast inputs include interventional neuroradiologist fellowship program expansion rates and hybrid operating room installation pipelines.
Underlying assumptions cover sustained nimodipine protocol adherence and ISO 13485 certification timeline stability, with deviation risk concentrated in Medicare severity-adjusted diagnosis-related group payment recalibration and single-source catheter manufacturing disruption. Forecasts reflect these assumptions with explicit acknowledgment that EMA centralized procedure delays or PMDA pathway friction could compress premium pricing realization for novel therapeutics. Revision becomes warranted when interventional neuroradiologist training program expansion crosses thresholds that materially expand procedural capacity beyond equipment availability constraints.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Asia-Pacific Kidney Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Histamine Toxicity Market
Specialty Medicine
Global Specialty Injectable Generics Market
Specialty Medicine
Global Multiple Sclerosis Therapeutics Market
Specialty Medicine
Carcinoid Syndrome Diarrhea Treatment Market
Specialty Medicine
Asia-Pacific Primary Angle-Closure Glaucoma Market
Specialty Medicine
Dravet Syndrome Treatment Market
Specialty Medicine
Low-Grade Glioma Therapeutics Market
Specialty Medicine
Global Glaucoma Therapeutics Market
Specialty Medicine
Thoracic Outlet Syndrome Market
Specialty Medicine
Myelofibrosis Market
Specialty Medicine
Global Phenylketonuria Treatment Market
Specialty Medicine
Cystic Fibrosis Transmembrane Conductance Regulator (CFTR) Market
Specialty Medicine
Cystinuria Treatment Market
Specialty Medicine
Global Huntingtons Disease Treatment Market
Specialty Medicine
APOL1 Mediated Kidney Disease Market