
 Global Spinal Muscular Atrophy Treatment Market | 2026-2036
Global Spinal Muscular Atrophy Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Spinal Muscular Atrophy Treatment Market Foresight
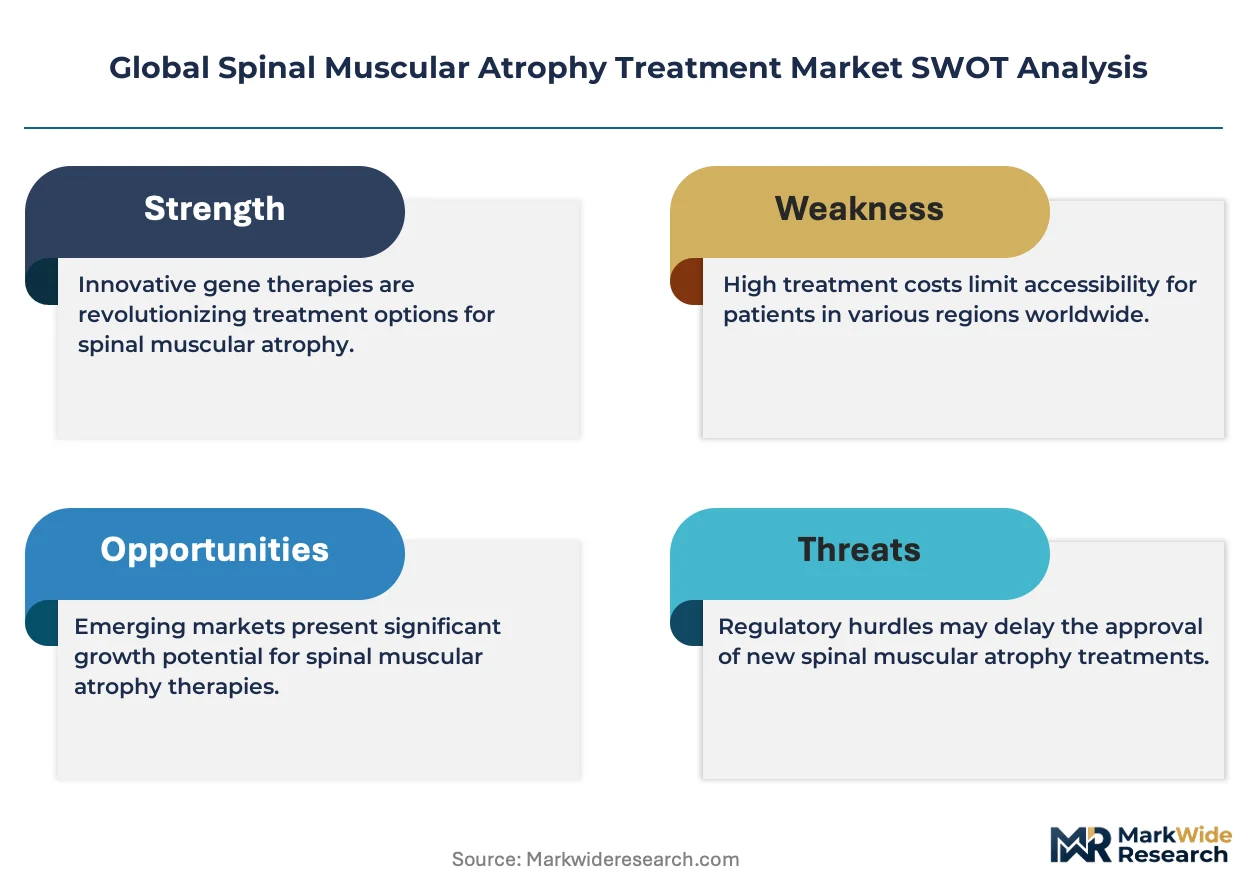
The capital-intensity divergence between gene therapy manufacturers and small-molecule developers is collapsing as platform technologies commodify viral vector production. Biogen sustains its early-mover advantage through intrathecal delivery infrastructure built around nusinersen. Novartis AG anchors the high-value segment with onasemnogene abeparvovec, the one-time gene therapy that redefined SMA pricing paradigms. Roche Holding AG competes via risdiplam, an oral small molecule that eliminates the invasive administration barrier entirely.
Spinal muscular atrophy treatment encompasses disease-modifying therapies targeting survival motor neuron protein deficiency through gene replacement, splicing modification, or neuroprotection. Antisense oligonucleotides dominate current revenue streams due to established reimbursement and long-term safety data, while gene therapy captures the fastest growth trajectory despite manufacturing bottlenecks and access limitations. Small molecules occupy a structural middle ground, expanding addressable populations through oral administration in community settings rather than specialized infusion centers. Delivery mode segmentation reveals intrathecal injection as the mature margin pool, with subcutaneous and oral routes representing the technical frontier for patient convenience.
FDA's accelerated approval pathways and orphan drug exclusivity frameworks shape US market entry economics, while EMA's PRIME designation and EU-wide health technology assessment convergence determine European commercial viability. WHO inclusion of nusinersen and onasemnogene abeparvovec on essential medicines watchlists signals emerging market access expansion. Stakeholders must monitor payer adaptation to single-dose curative pricing models versus chronic therapy paradigms as gene therapy pipelines mature.
Market Dynamics
Platform commodification of adeno-associated viral vector manufacturing is collapsing the historical cost barrier between gene therapy and small-molecule production, forcing incumbents to defend margin positions through delivery infrastructure rather than manufacturing scale alone.
Growth Catalysts
- EMA PRIME Designation:The European Medicines Agency's accelerated assessment pathway compresses regulatory timelines for rare disease therapies, enabling faster European commercial entry for SMA gene replacement candidates.
- Intrathecal Delivery Infrastructure:Established neuromuscular centers in the United States have built specialized infusion capabilities that lower patient access barriers for antisense oligonucleotide administration.
- Newborn Screening Expansion:State-level mandates in California, New York, and Texas have added SMA to mandatory screening panels, creating presymptomatic treatment populations that expand addressable incidence.
Market Restraints
- Plasmid DNA Supply Concentration:Contract manufacturing organizations in the United States and Belgium control critical viral vector raw material supply, creating single-source vulnerability for gene therapy developers.
- Single-Dose Reimbursement Friction:Payer actuarial models built for chronic therapy paradigms struggle to accommodate curative gene therapy pricing, generating prior authorization delays and coverage uncertainty.
- Cold Chain Complexity:Frozen storage requirements for onasemnogene abeparvovec and similar gene therapies limit distribution to specialized treatment centers, excluding community hospital settings.
Strategic Opportunities
- Adult Phenotype Expansion:Type 3 and Type 4 SMA populations in Germany and Japan remain undertreated relative to infantile-onset segments, representing incremental volume for oral small-molecule therapies.
- Subretinal Delivery Convergence:Ophthalmic gene therapy platforms developed for inherited retinal diseases are transferring surgical techniques and vector engineering insights to CNS-targeted SMA applications.
- Home Administration Pathways:Subcutaneous and oral formulations enable direct-to-patient distribution models that bypass infusion center capacity constraints entirely.
Industry Challenges
- Gene Therapy Manufacturing Talent Scarcity:Viral vector production requires specialized bioprocess engineers with experience in suspension cell culture and empty capsid separation, functions where experienced personnel pool remains shallow.
- Long-Term Follow-Up Infrastructure:Fifteen-year durability studies for single-dose gene therapies demand sustained clinical trial site engagement and patient retention systems that strain traditional post-marketing surveillance budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Spinal Muscular Atrophy Treatment Market |
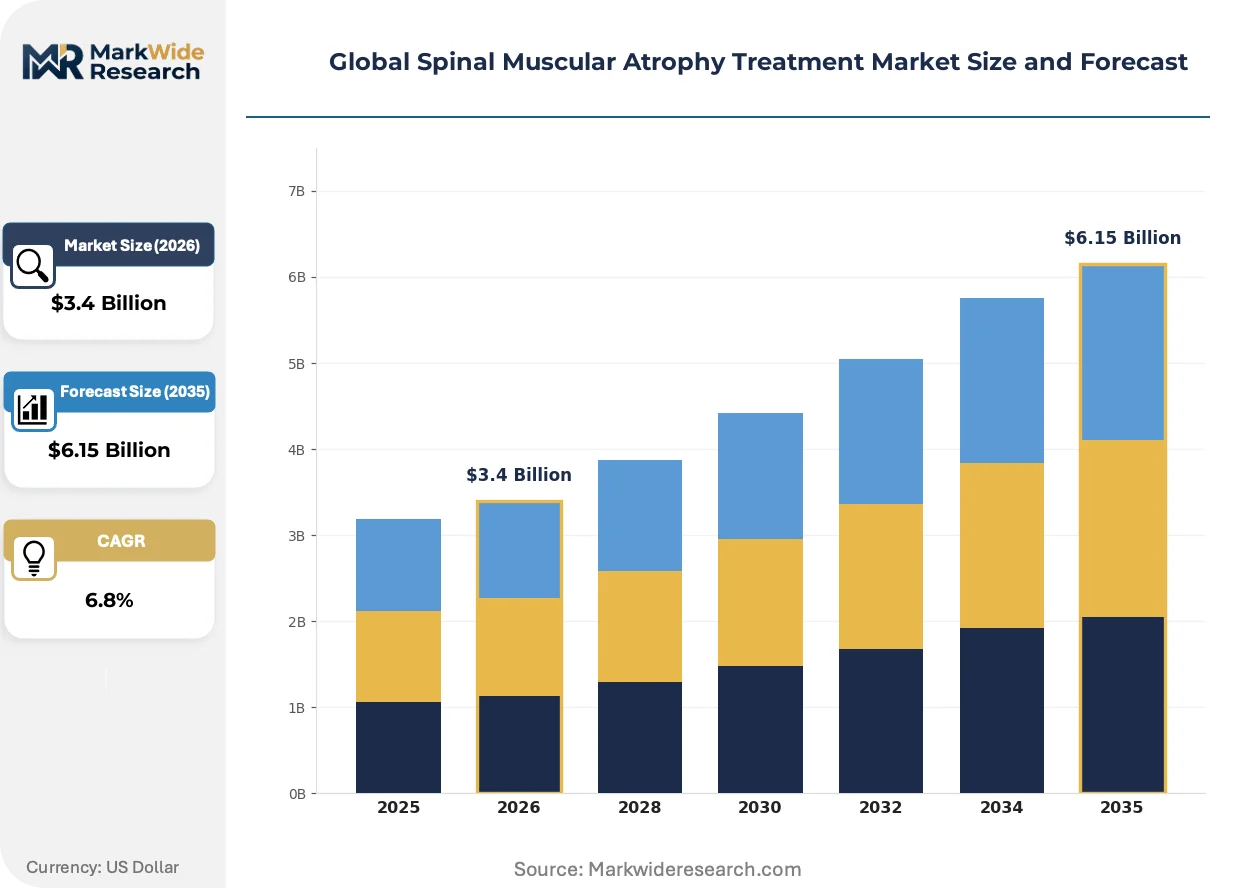
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $6.15 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Therapy Area: Type 1 SMA, Type 2 SMA, Type 3 SMA, Type 4 SMA Product Type: Gene Therapy, Antisense Oligonucleotides, Small Molecules, Neuroprotective Agents End User: Specialty Clinics, Neuromuscular Centers, Rehabilitation Facilities, Research Institutes Delivery Mode: Intrathecal Injection, Intravenous Infusion, Oral Administration, Subcutaneous Injection |
| Companies Covered | Biogen, Novartis AG, Roche Holding AG, Pfizer Inc., Ionis Pharmaceuticals, Cytokinetics, PTC Therapeutics, Scholar Rock, Inc., Biohaven Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Spinal Muscular Atrophy Treatment Market Shifts & Advancements
Gene therapy manufacturing scale-up and regulatory science convergence are compressing the historical timeline between clinical proof-of-concept and commercial readiness for neuromuscular indications.
Next-generation AAV capsid engineering is displacing first-generation serotypes in preclinical SMA programs. Biotech developers in Massachusetts and California are selecting variants with reduced immunogenicity and improved blood-brain barrier penetration. This capsid evolution is enabling repeat dosing scenarios that were previously excluded by neutralizing antibody responses.
FDA's accelerated approval pathway for gene therapies is tightening evidentiary standards for surrogate endpoints. The agency now demands motor milestone validation that extends beyond historical biomarker acceptance, forcing sponsors to design larger Phase 3 trials with longer observation periods. Pediatric neuromuscular specialists in academic medical centers are adapting enrollment protocols to accommodate these evidentiary requirements.
Patient advocacy organizations are consolidating purchasing influence through managed access programs. In the United States, the Cure SMA Foundation and similar groups are negotiating outcome-based rebate structures directly with manufacturers, bypassing traditional pharmacy benefit manager intermediaries. This direct contracting model is most visible in states with high newborn screening penetration where treatment-naive cohorts concentrate.
Global Spinal Muscular Atrophy Treatment Market Segmentation
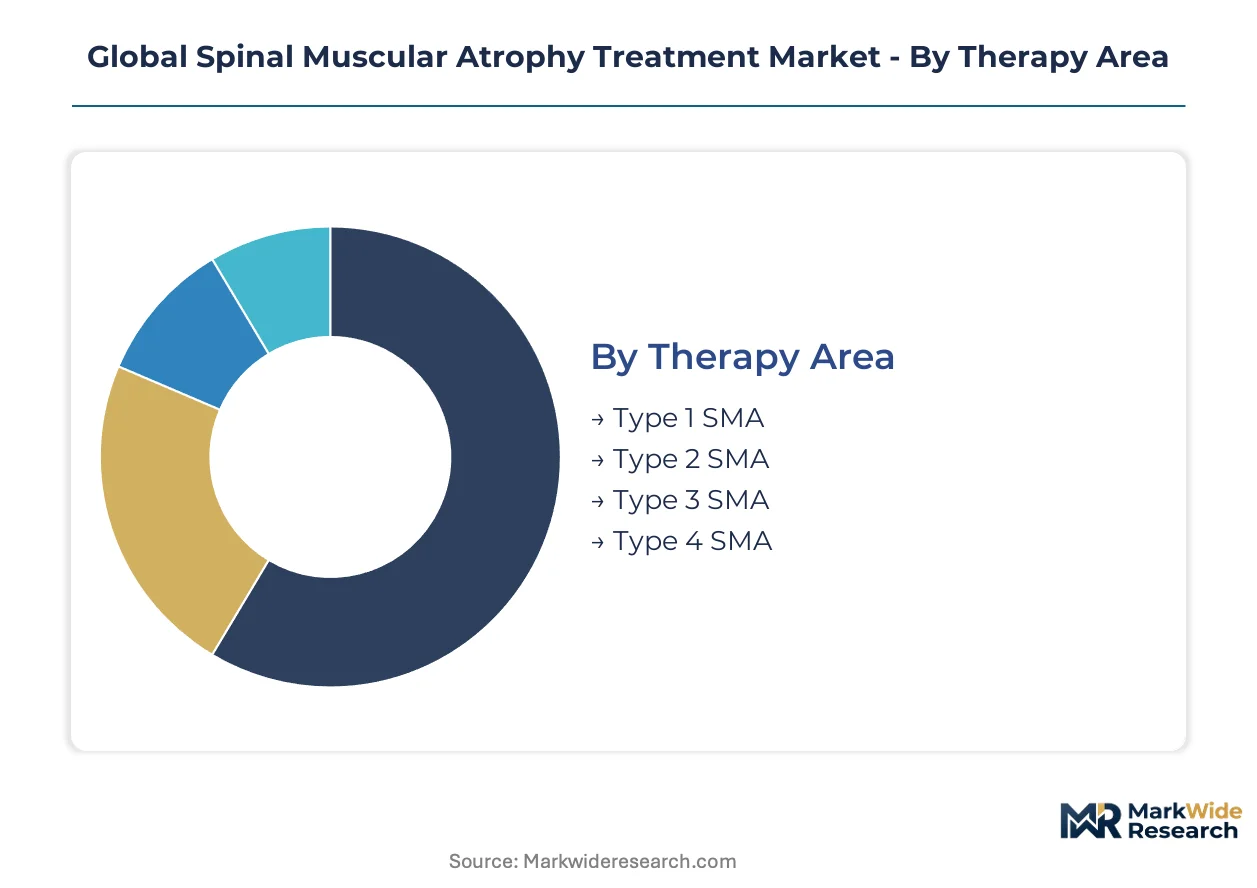
Treatment modality selection in spinal muscular atrophy hinges on disease severity, patient age, and reimbursement pathways. Segmentation reveals how delivery infrastructure constraints and pricing models reshape competitive boundaries across patient populations.
Therapy Area:
FDA's accelerated approval pathways and EMA's PRIME designation create divergent access timelines across SMA phenotypes, with regulatory risk tolerance highest for the most severe infantile presentations.
- Type 1 SMA:Severe infantile-onset form presenting before six months with rapid motor neuron degeneration. Presymptomatic treatment cohorts are expanding in California, New York, and Texas following state-level newborn screening mandates that capture incident cases at birth.
- Type 2 SMA:Intermediate chronic form with onset between six and eighteen months and preserved sitting ability. German and Japanese reimbursement frameworks now cover maintenance therapy for this population, driving volume in established European and Asian markets.
- Type 3 SMA:Juvenile-onset variant with independent ambulation preserved into adolescence. Oral small-molecule access is climbing fastest among this group due to community-based administration advantages.
- Type 4 SMA:Adult-onset form with mild, slowly progressive weakness. Undertreated relative to pediatric segments; represents incremental volume opportunity for therapies with favorable chronic administration profiles.
Type 1 SMA handles the majority of throughput; Type 3 SMA is expanding most quickly on share.
Product Type:
Manufacturing scale economics and vector production commodification are collapsing historical cost barriers between biologics and small molecules, forcing competitive differentiation toward delivery infrastructure rather than production technology alone.
- Gene Therapy:Single-dose adeno-associated viral vector delivery replacing defective SMN1 gene. Cold chain complexity and fifteen-year durability study requirements limit distribution to specialized treatment centers in the United States, Germany, and Japan.
- Antisense Oligonucleotides:Splicing modifiers that increase functional SMN protein through intrathecal delivery. Established intrathecal infrastructure at US pediatric neuromuscular centers sustains this segment's revenue concentration despite invasive administration.
- Small Molecules:Oral SMN2 splicing enhancers eliminating infusion center dependency. Roche's risdiplam anchors this category with community pharmacy distribution that bypasses capacity constraints entirely.
- Neuroprotective Agents:Adjunctive therapies targeting secondary pathologies like muscle atrophy and neuronal degeneration. Development pipelines concentrate in Massachusetts and California biotech clusters with ophthalmic gene therapy platform cross-application.
Antisense oligonucleotides retain the dominant revenue position; gene therapy is gaining share fastest.
End User:
Site-of-care economics and infusion center capacity constraints are fragmenting prescribing authority across institutional settings with varying reimbursement sophistication.
- Specialty Clinics:Dedicated neuromuscular practices with genetic counseling and multidisciplinary care coordination. Concentrate in Boston, Philadelphia, and London where academic medical center proximity enables clinical trial access.
- Neuromuscular Centers:Comprehensive care hubs with intrathecal delivery infrastructure and long-term follow-up protocols. US centers built around nusinersen administration now face gene therapy conversion pressure.
- Rehabilitation Facilities:Post-acute and chronic management settings emphasizing functional preservation. Expansion in German statutory health insurance networks supports oral therapy uptake for Type 3 and Type 4 patients.
- Research Institutes:Academic sites conducting natural history studies and interventional trials. Fifteen-year follow-up infrastructure demands strain traditional post-marketing surveillance budgets.
Neuromuscular centers handle the majority of throughput; specialty clinics are climbing the fastest on patient volume.
Delivery Mode:
Route of administration directly determines addressable geography by matching cold chain requirements, surgical capability, and patient convenience preferences to local healthcare infrastructure.
- Intrathecal Injection:Direct cerebrospinal fluid delivery via lumbar puncture requiring specialized neuromuscular center access. Mature margin pool sustained by Biogen's established US infusion infrastructure.
- Intravenous Infusion:Systemic gene therapy vector delivery with intensive care monitoring for acute reactions. Frozen storage requirements restrict distribution to tertiary centers in reimbursed markets.
- Oral Administration:Small-molecule delivery enabling direct-to-patient distribution and home-based compliance. Eliminates geographic access barriers entirely, expanding addressable populations in community settings.
- Subcutaneous Injection:Emerging delivery frontier with reduced immunogenicity profiles from engineered AAV capsids. Preclinical programs in Massachusetts and California are selecting variants with improved blood-brain barrier penetration.
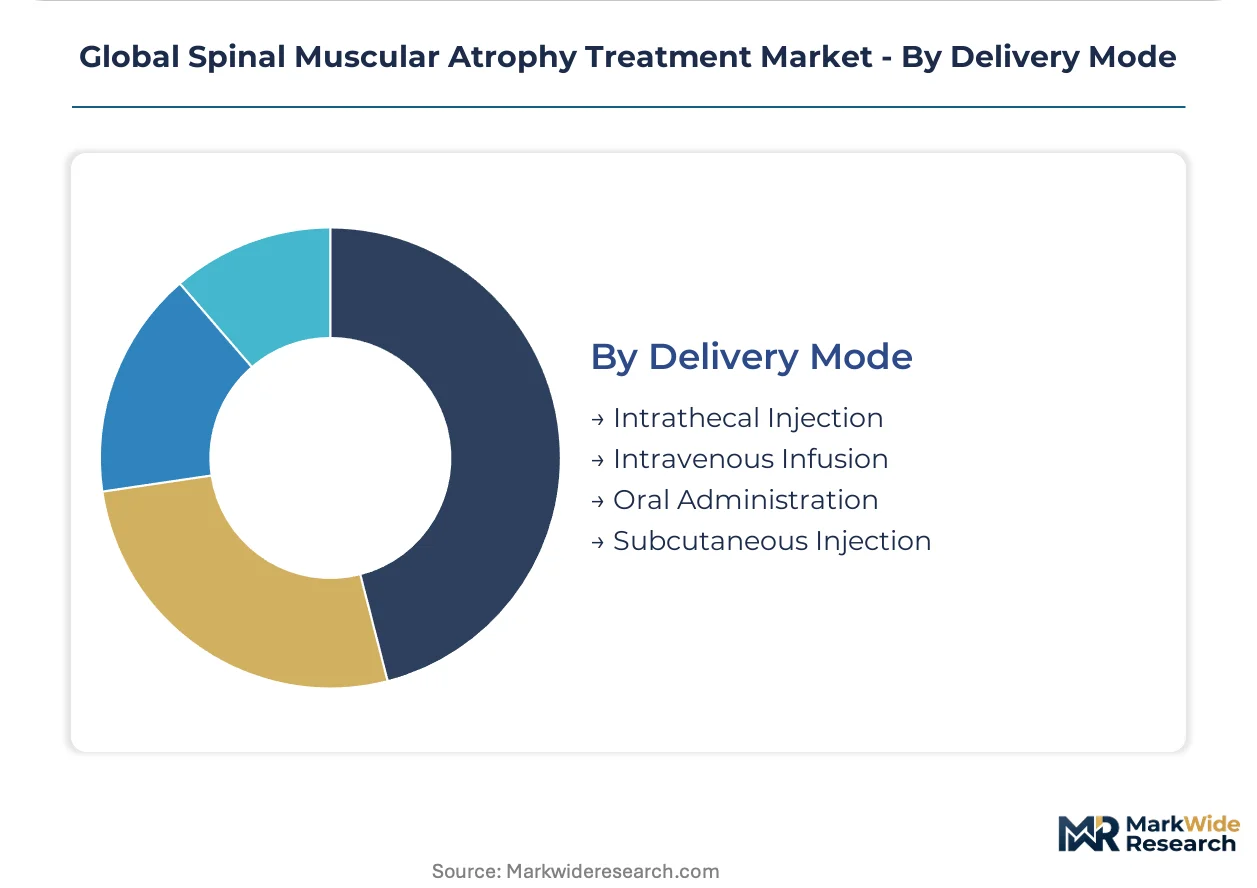
Intrathecal injection handles the majority of throughput; oral administration is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reimbursement elasticity varies sharply across national healthcare systems. Germany and Japan absorb single-dose gene therapy premiums through statutory pooling mechanisms. United States payers impose prior authorization friction that slows access velocity despite higher nominal prices.
United States
FDA's accelerated approval pathways and orphan drug exclusivity frameworks concentrate gene therapy launches in Boston and Philadelphia academic medical centers. State-level newborn screening mandates in California, New York, and Texas create presymptomatic treatment cohorts. Pediatric neuromuscular specialists at Massachusetts General and Children's Hospital of Philadelphia anchor clinical trial infrastructure.
Germany
Statutory health insurance funds cover maintenance therapy for Type 2 and Type 3 SMA populations with minimal cost-sharing. EMA's PRIME designation accelerates European commercial entry timelines for gene replacement candidates. Heidelberg and Munich host specialized neuromuscular centers with intrathecal delivery capabilities.
Japan
METI and PMDA coordinate rare disease reimbursement through premium pricing mechanisms that reward clinical innovation. National newborn screening expansion in Tokyo and Osaka metropolitan areas captures incident cases earlier. Kansai region academic hospitals built risdiplam prescribing networks that bypass infusion center constraints.
Switzerland
Swissmedic's streamlined assessment for advanced therapy medicinal products enables rapid market access for gene therapies. Cantonal health systems in Zurich and Geneva negotiate outcome-based contracts directly with manufacturers. Basel's pharmaceutical cluster hosts vector manufacturing capabilities serving European demand.
United Kingdom
NICE technology appraisals create binary access decisions that delay gene therapy uptake pending cost-effectiveness modeling. NHS England's specialized commissioning framework concentrates treatment at London and Manchester neuromuscular centers. Oxford and Cambridge biotech incubators host next-generation AAV capsid engineering programs.
Global Spinal Muscular Atrophy Treatment Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes. Gene therapy developers command premium pricing through single-dose curative claims but face manufacturing bottlenecks and cold chain constraints. Small-molecule specialists capture volume through oral administration that eliminates infusion center dependency. The market structure consolidates around three archetypes: intrathecal delivery incumbents with established neuromuscular center relationships, gene therapy platforms with vector manufacturing scale, and oral therapy specialists with community pharmacy distribution. Dominant competitive moves include strategic partnerships for viral vector supply security and geographic expansion into reimbursed European and Asian markets.
Within the gene therapy tier, Novartis AG and Biogen exemplify divergent strategic positions. Novartis AG anchors the high-value segment through one-time gene replacement positioning that redefined SMA pricing paradigms. Biogen sustains early-mover advantage through intrathecal delivery infrastructure built around chronic administration models. Roche Holding AG occupies a structural middle ground with oral small-molecule distribution that bypasses specialized treatment center capacity constraints entirely.
| Leading Market Players |
|---|
| Biogen |
| Novartis AG |
| Roche Holding AG |
| Pfizer Inc. |
| Ionis Pharmaceuticals |
| Cytokinetics |
| PTC Therapeutics |
| Scholar Rock, Inc. |
| Biohaven Pharmaceuticals |
| Others |
Supply & Pricing Matrix
Ninety-day vector production lead times concentrate pricing power with contract manufacturing organizations in Belgium and the United States, forcing gene therapy developers to absorb upstream cost volatility or sacrifice margin through fixed-price patient access commitments. Cold chain complexity for single-dose therapies amplifies this dynamic by restricting distribution to specialized infusion centers that command premium site-of-care fees.
Pricing Analysis
After-sales revenue from fifteen-year durability monitoring and patient retention programs drives lifetime value for gene therapy developers more than the initial single-dose transaction. Three-tier pricing structure across curative gene replacement, chronic antisense maintenance, and oral small-molecule convenience separates Novartis from Biogen and Roche. Cost compression in the chronic therapy tier intensifies because payer actuarial models favor predictable annual spend over lump-sum curative payments. Hospital procurement committees exhibit highest price sensitivity due to bundled reimbursement constraints, while statutory health insurance funds in Germany and Japan absorb premiums with minimal friction.
Supply Chain Analysis
Inbound logistics costs from transatlantic plasmid DNA shipments face chronic container availability constraints on the Antwerp-Philadelphia trade lane, elevating working capital requirements for viral vector manufacturers. Plasmid DNA supply concentrates in Belgium and the United States, with fill-finish capacity clustering in Switzerland and Singapore. Raw material dependencies span plasmid DNA, recombinant baculovirus stocks, and suspension cell culture media. Single-source vulnerability at the plasmid tier creates acute exposure to regulatory inspection delays. Distribution runs through specialized hospital pharmacy channels with cryogenic storage validation rather than wholesale distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating through the Cure SMA Foundation's direct outcome-based contracting with manufacturers, bypassing traditional pharmacy benefit manager intermediaries in high newborn-screening states.
For Market Incumbents: Compound your intrathecal delivery infrastructure advantage by embedding patient retention services that gene therapy competitors cannot replicate without fifteen-year follow-up commitments. Secure viral vector supply through captive manufacturing investments in Massachusetts or Switzerland to neutralize plasmid DNA concentration risk. Lock in formulary positioning with integrated neuromuscular center networks before subcutaneous delivery platforms mature. For New Entrants and Emerging Players: Home administration pathways for Type 3 and Type 4 SMA populations represent the most penetrable white space, as incumbents under-serve adult phenotypes with pediatric-focused delivery infrastructure. Target German statutory health insurance networks where maintenance therapy coverage for chronic SMA forms has matured without gene therapy conversion pressure. Enter through community pharmacy distribution partnerships that eliminate infusion center dependency entirely. For Investors and Strategic Acquirers: Long-term, this sits as a manufacturing-capability play because viral vector production talent scarcity and plasmid DNA supply concentration create durable moats around scaled producers. Acquisition targets should display suspension cell culture expertise and empty capsid separation capabilities. Watch for FDA evidentiary standard tightening on surrogate endpoints as the inflection signal for Phase 3 trial cost escalation.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Platform commodification of AAV production collapses cost barriers between gene therapy and small-molecule economics. |
| Regulatory Approval Pathway | EMA PRIME designation compresses European commercial entry timelines for rare disease gene replacement candidates. |
| Licensing Agreement | Next-generation capsid engineering from Massachusetts biotech clusters enables repeat dosing scenarios previously excluded by immunogenicity. |
| Pipeline Diversification | Subretinal delivery convergence from ophthalmic gene therapy platforms transfers surgical techniques to CNS-targeted applications. |
| Reimbursement Strategy | Outcome-based rebate structures negotiated directly with patient advocacy organizations bypass pharmacy benefit manager intermediaries. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with drug development executives, regulatory affairs leads, formulary directors, and payer access specialists; and secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Bottom-up patient flow modeling triangulated against top-down revenue estimates from disclosed therapy pricing and treated population estimates.
Across the analysis window, the forecasting framework modeled treatment modality, SMA phenotype severity, administration route, and regional regulatory cluster as core segmentation dimensions. CAGRs were derived from incidence-based patient cohort projections and pricing elasticity assumptions calibrated to reimbursement framework maturity. Forecast inputs incorporated newborn screening expansion trajectories in California, New York, and Texas, plus vector manufacturing capacity buildout timelines in Basel and Singapore.
Underlying assumptions cover payer adaptation to single-dose curative pricing models, with deviation risk concentrated in prior authorization friction and long-term durability study outcomes. Forecasts reflect these conditions; outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Healthcare Specialty Enzymes Market
Specialty Medicine
Bulimia Nervosa Market
Specialty Medicine
Animal Hormone Therapy Market
Specialty Medicine
Primary Biliary Cholangitis (PBC) Treatment Market
Specialty Medicine
Pulmonary Arterial Hypertension (PAH) Market
Specialty Medicine
Polychondritis Disease Treatment Market
Specialty Medicine
Subdural Haematoma Market
Specialty Medicine
Alcoholic Liver Diseases Treatment Market
Specialty Medicine
Acute Myeloid Leukemia Therapeutics Market
Specialty Medicine
Bronchiectasis Therapeutic Market
Specialty Medicine
Allergic Conjunctivitis Market
Specialty Medicine
Cystic Fibrosis Market
Specialty Medicine
Complement 3 Glomerulopathy (C3G) Market
Specialty Medicine
Hermansky Pudlak Syndrome Therapeutics Market
Specialty Medicine
Global Cough Hypersensitivity Syndrome Treatment Market
Specialty Medicine
Acute Intermittent Porphyria Market