
 Primary Sclerosing Cholangitis (PSC) Market | 2026-2036
Primary Sclerosing Cholangitis (PSC) Market Size, Share, and Industry Trends Forecast 2026-2036
Primary Sclerosing Cholangitis (PSC) Market Analytics
Aftermarket service revenue from patient support programs and companion diagnostics is tilting toward biologic manufacturers. Intercept Pharmaceuticals leverages its bile acid modulator expertise to sustain hepatology-focused prescriber relationships. Gilead Sciences anchors its immunology pipeline through deep PSC program investment. Dr. Falk Pharma GmbH dominates European cholestatic disease management with established ursodeoxycholic acid formulations.
Primary sclerosing cholangitis is a chronic cholestatic liver disease characterized by progressive inflammation and fibrosis of the bile ducts, with diagnostic criteria requiring magnetic resonance cholangiopancreatography or endoscopic retrograde cholangiography confirmation of multifocal stricturing. Biologics command premium positioning due to targeted immunomodulatory mechanisms in autoimmune-driven disease progression. Oral delivery modes retain volume leadership in maintenance therapy, though intravenous biologics capture the fastest-growing share in severe, transplant-eligible populations. Antifibrotic agents represent an emerging margin pool as developers target cirrhosis reversal endpoints.
The FDA orphan drug program and EMA's protocol assistance framework shape clinical trial design and accelerate market access for PSC therapies with limited treatment alternatives. REACH compliance requirements influence excipient selection and manufacturing location decisions for European supply chains. Stakeholders must monitor biomarker-qualified surrogate endpoint negotiations between sponsors and regulators, as these determinations will reshape Phase III investment thresholds and reimbursement negotiations across major markets.
Market Dynamics
The orphan drug designation pathway from the FDA and EMA protocol assistance framework is compressing clinical trial timelines and reshaping how biologic developers allocate Phase III capital against qualified surrogate endpoints.
Growth Catalysts
- FDA Orphan Drug Designation:The accelerated review pathway reduces regulatory friction for novel bile acid modulators and immunomodulatory biologics targeting the cholestatic mechanism.
- Magnetic resonance cholangiopancreatography (MRCP) adoption:Non-invasive diagnostic confirmation expands addressable patient pools beyond tertiary academic centers into community hepatology practices.
- Transplant-eligible population concentration:Severe disease cohorts at high-volume liver transplant centers generate concentrated demand for intravenous biologic maintenance therapy.
Market Restraints
- Biologic manufacturing complexity:Cold-chain intravenous formulations impose distribution constraints and per-dose cost structures that limit penetration outside academic medical centers.
- Surrogate endpoint uncertainty:Negotiations between sponsors and regulators over biomarker-qualified endpoints for antifibrotic agents create investment threshold ambiguity for cirrhosis reversal programs.
- Ursodeoxycholic acid substitution:Established oral formulations for symptomatic management anchor prescriber comfort and payer reimbursement protocols, compressing uptake curves for novel mechanisms.
Strategic Opportunities
- Companion diagnostic integration:Patient stratification tools linked to biologic eligibility criteria open aftermarket revenue streams and lock-in prescriber relationships.
- EMA REACH compliance leverage:Excipient selection and European manufacturing localization decisions create supply chain differentiation for EU market access.
- Antifibrotic mechanism white space:Cirrhosis reversal endpoints represent an unoccupied margin pool with distinct regulatory and reimbursement negotiation dynamics from immunomodulatory approaches.
Industry Challenges
- Specialized hepatology trial infrastructure:Enrollment velocity depends on finite investigator networks at high-volume transplant centers, creating site activation bottlenecks.
- Legacy ursodeoxycholic acid integration:Novel agents must demonstrate incremental clinical utility against entrenched maintenance therapy protocols without standardized head-to-head trial designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Primary Sclerosing Cholangitis (PSC) Market |
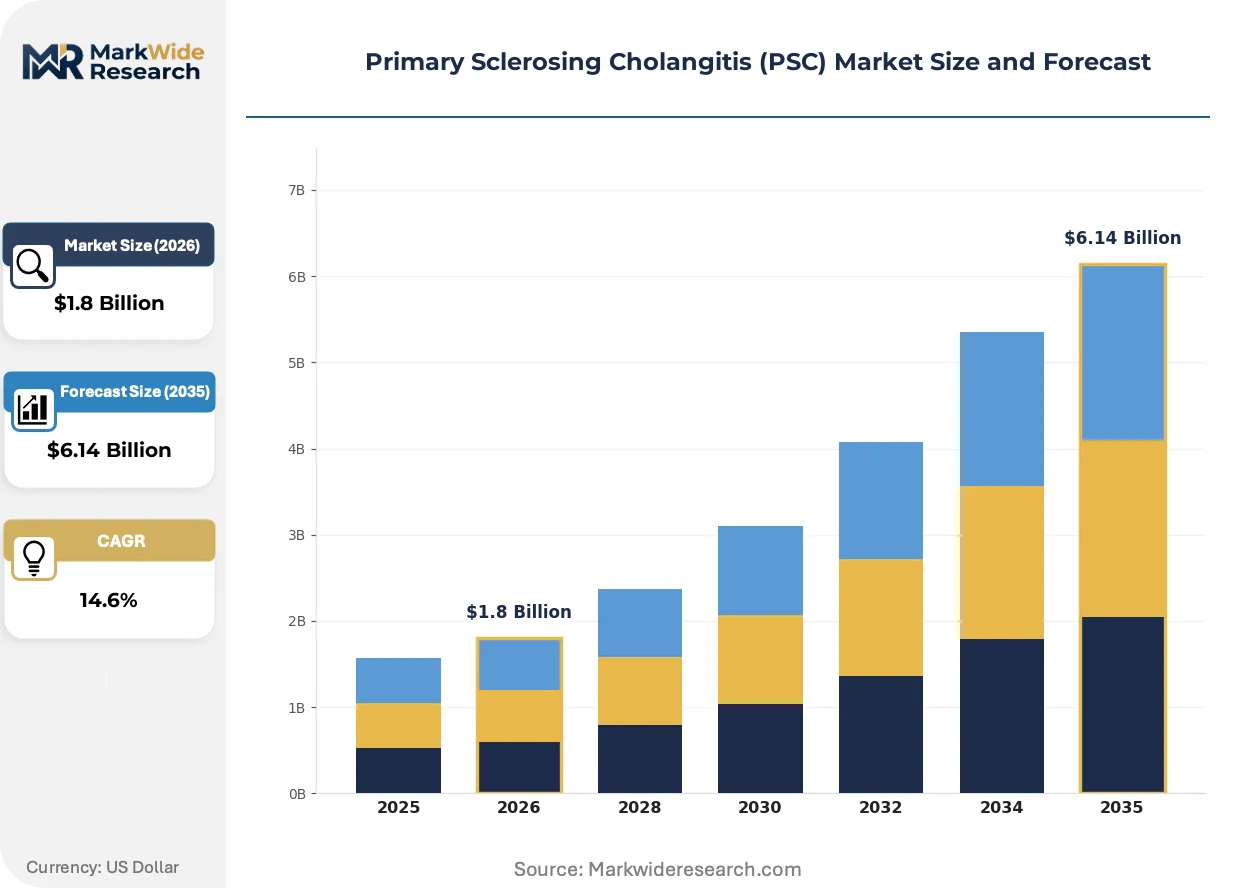
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Immunosuppressants, Biologics, Antibiotics, Antifibrotic Agents Therapy Area: Liver Disorders, Autoimmune Diseases, Digestive Disorders, Cholestasis Delivery Mode: Oral, Injectable, Intravenous, Subcutaneous End User: Hospitals, Specialty Clinics, Home Care, Research Laboratories |
| Companies Covered | Gilead Sciences, Inc., Intercept Pharmaceuticals, Inc., NGM Biopharmaceuticals, Inc., Acorda Therapeutics, Inc., Dr. Falk Pharma GmbH, HighTide Therapeutics, Pliant Therapeutics, Inc., CymaBay Therapeutics, Mirum Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Primary Sclerosing Cholangitis (PSC) Market Evolving Landscape
Non-invasive diagnostic workflows and biomarker-driven trial designs are compressing the gap between symptom onset and therapeutic intervention, while regulatory frameworks adapt to accelerated approval mechanisms for rare cholestatic diseases.
Artificial intelligence-assisted MRCP interpretation is rendering obsolete reliance on invasive endoscopic retrograde cholangiography for multifocal stricturing confirmation. Community hepatology practices in the United States are adopting these tools faster than European counterparts, enabling earlier specialist referral and expanding the window for biologic intervention before transplant eligibility.
REACH compliance requirements for European pharmaceutical manufacturing are forcing excipient substitution and supply chain relocalization decisions. Sponsors targeting EMA market access must reformulate around restricted chemical classes, with oral maintenance therapies facing tighter compositional constraints than intravenous biologics produced in controlled environments.
Academic medical centers are unbundling patient support programs from drug procurement, creating standalone service revenue streams. Specialty clinics in Germany and the United States now contract directly with biologic manufacturers for compliance monitoring and adverse event management, displacing traditional pharmacy benefit manager intermediation in severe disease populations.
Primary Sclerosing Cholangitis (PSC) Market Segmentation
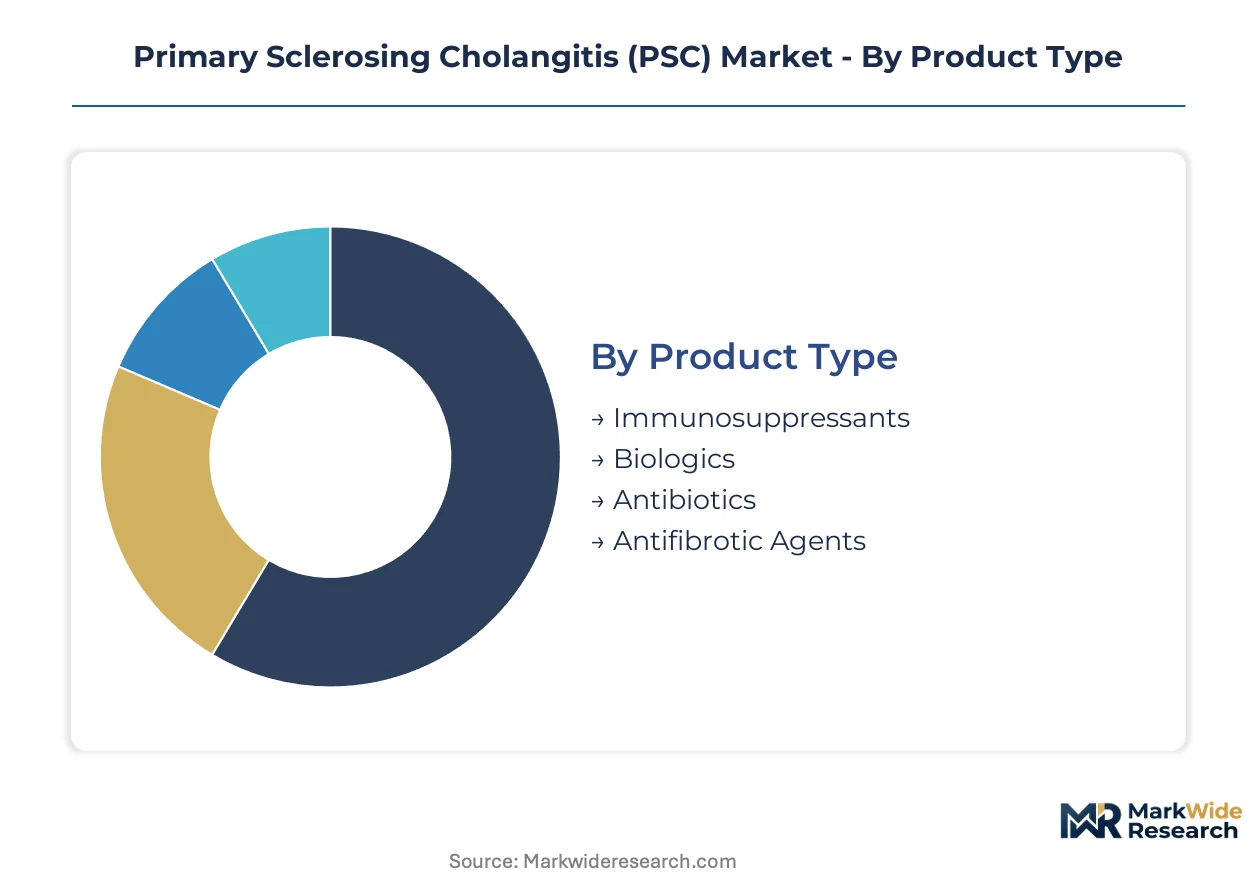
PSC treatment pathways diverge sharply across product mechanisms, therapy targets, and care settings. Segmentation reveals where biologic premiumization concentrates versus where oral maintenance therapies defend volume leadership.
Product Type:
Cost tier determines manufacturing complexity, distribution infrastructure requirements, and prescriber access pathways for PSC therapeutics.
- Biologics:Targeted immunomodulatory monoclonal antibodies and fusion proteins manufactured under cold-chain conditions. Demand concentrates at high-volume liver transplant centers in the United States, where intravenous administration protocols and specialist nursing support justify per-dose cost structures.
- Antifibrotic Agents:Emerging small-molecule and biologic candidates targeting cirrhosis reversal through TGF-beta inhibition or LOXL2 antagonism. Development pipelines cluster around surrogate endpoint negotiations with the FDA and EMA, creating investment threshold uncertainty for Phase III commitments.
- Immunosuppressants:Corticosteroid and calcineurin inhibitor formulations for autoimmune-driven disease modulation.
- Antibiotics:Rifaximin and other agents targeting bacterial translocation complications in advanced cholestasis.
Biologics command the established base. The steepest expansion runs through antifibrotic agents.
Therapy Area:
Application focus shapes regulatory pathway selection, endpoint qualification, and prescriber specialty targeting across development programs.
- Cholestasis:Bile acid modulators and apical sodium-dependent bile acid transporter inhibitors addressing the core pathophysiologic mechanism. Prescriber relationships concentrate among hepatologists at academic medical centers in Germany and the United States, where magnetic resonance cholangiopancreatography confirmation protocols are most established.
- Autoimmune Diseases:Immunomodulatory approaches targeting the T-cell mediated inflammatory cascade driving bile duct fibrosis. Clinical trial enrollment depends on finite investigator networks at specialized transplant centers, creating site activation bottlenecks for multi-regional studies.
- Liver Disorders:Broad hepatology positioning encompassing cirrhosis complications and portal hypertension management.
- Digestive Disorders:Inflammatory bowel disease comorbidity targeting, given the PSC-ulcerative colitis overlap.
Cholestasis mechanisms anchor current revenue. Autoimmune targeting offers the fastest regulatory precedent for novel biologic entrants.
Delivery Mode:
Volume distribution and margin capture split sharply between maintenance-friendly oral formats and acute-intervention parenteral routes.
- Oral:Ursodeoxycholic acid formulations and emerging small-molecule bile acid modulators dominating maintenance therapy. Community hepatology practices in the United States drive volume expansion as non-invasive diagnostic workflows enable earlier specialist referral.
- Intravenous:Hospital-administered biologics for severe, transplant-eligible populations requiring intensive immunomodulation. REACH compliance requirements in Europe favor controlled-environment manufacturing for these formulations over oral excipient substitution challenges.
- Injectable:Intramuscular corticosteroid depot formulations for intermittent disease flares.
- Subcutaneous:Patient-administered biologics under evaluation for maintenance therapy migration from hospital settings.
Oral delivery maintains volume leadership. Intravenous administration captures margin concentration in severe disease cohorts.
End User:
Customer type determines procurement channel structure, reimbursement negotiation leverage, and patient support program integration depth.
- Specialty Clinics:Dedicated hepatology and transplant centers unbundling patient support programs from drug procurement into standalone service contracts. German and United States clinics now contract directly with biologic manufacturers for compliance monitoring, displacing traditional pharmacy benefit manager intermediation.
- Hospitals:Academic medical centers with embedded research infrastructure driving clinical trial enrollment and early commercial uptake. FDA orphan drug designation pathways accelerate formulary access negotiations at these institutions.
- Home Care:Subcutaneous biologic self-administration and oral maintenance therapy monitoring.
- Research Laboratories:Biomarker validation and companion diagnostic development partnerships.
Hospitals anchor trial infrastructure and early adoption. Specialty clinics are gaining the fastest share in service-integrated commercial models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Switzerland show the lowest price elasticity for novel biologics, while United States commercial payers impose steeper cost-effectiveness hurdles. Academic medical centers in North America and Europe anchor transplant-eligible patient concentration. Manufacturing localization decisions track REACH compliance thresholds.
United States
High-volume liver transplant centers at Mayo Clinic Rochester and Massachusetts General Hospital drive clinical trial enrollment velocity for intravenous biologics. FDA orphan drug designation compresses regulatory review timelines for bile acid modulators. The Southeast cluster around Emory University and Duke University anchors prescriber network expansion into community hepatology practices.
Germany
Dr. Falk Pharma's established ursodeoxycholic acid presence creates entrenched prescriber relationships across academic and community settings. EMA protocol assistance frameworks accelerate market access negotiations for novel mechanisms. The North Rhine-Westphalia hepatology corridor between Düsseldorf and Cologne concentrates diagnostic imaging infrastructure and specialist referral networks.
Switzerland
Swissmedic's streamlined rare disease pathways attract Phase III trial investment for antifibrotic candidates. Basel's biopharmaceutical manufacturing cluster supports excipient-compliant production for European supply chains. The Zurich-Geneva axis hosts specialized transplant centers with integrated patient support program contracting.
United Kingdom
NHS England's specialized commissioning frameworks create concentrated procurement channels for high-cost biologics. The MHRA's post-Brexit recognition pathways maintain alignment with EMA orphan drug standards. The Greater Manchester and London hepatology networks drive biomarker validation partnerships for companion diagnostic development.
Primary Sclerosing Cholangitis (PSC) Market Competitive Landscape
Capability concentration sits with hepatology-focused biopharmaceutical developers; scale advantage sits with diversified immunology platforms. The market structures around three tiers: established bile acid specialists defending maintenance therapy share, immunomodulatory biologic developers capturing transplant-center margin, and antifibrotic mechanism pioneers negotiating surrogate endpoint precedents. Dominant competitive moves include companion diagnostic integration and patient support program unbundling from drug procurement.
Within the hepatology-specialist tier, Intercept Pharmaceuticals and Dr. Falk Pharma GmbH anchor distinct regional positions. Gilead Sciences occupies the diversified immunology platform archetype, leveraging deep PSC program investment to sustain prescriber relationships across academic medical centers. These three entities exemplify the capability-scale tension shaping competitive dynamics.
| Leading Market Players |
|---|
| Gilead Sciences, Inc. |
| Intercept Pharmaceuticals, Inc. |
| NGM Biopharmaceuticals, Inc. |
| Acorda Therapeutics, Inc. |
| Dr. Falk Pharma GmbH |
| HighTide Therapeutics |
| Pliant Therapeutics, Inc. |
| CymaBay Therapeutics |
| Mirum Pharmaceuticals |
| Others |
Value Network & Pricing Analysis
The Rhine-Alpine freight corridor's cold-chain logistics costs directly shape margin distribution between biologic manufacturers and oral formulation suppliers, concentrating pricing power with sponsors who control temperature-controlled distribution networks while forcing cost absorption downstream to community hepatology practices lacking infusion infrastructure.
Pricing Analysis
Patient support program contracts now generate the dominant lifetime value stream, with specialty clinics in Germany and the United States unbundling compliance monitoring services from drug procurement. Three-tier pricing structure across premium intravenous biologics, standard oral maintenance therapies, and economy ursodeoxycholic acid formulations anchors prescriber decision frameworks. Cost compression in the oral tier intensifies because Dr. Falk Pharma's established ursodeoxycholic acid presence anchors reimbursement benchmarks. Academic medical centers show the least price sensitivity due to orphan drug designation procurement protocols, while community hepatology practices face the steepest budget constraints.
Supply Chain Analysis
REACH export-control restrictions on specific excipient classes limit formulation flexibility for European market access, forcing sponsors to reformulate around restricted chemical categories. Manufacturing concentration centers on Switzerland, Germany, and the United States, with Basel's biopharmaceutical cluster supporting compliant production for EU supply chains. Active pharmaceutical ingredient sourcing draws from established hepatology-focused contract manufacturers in North Rhine-Westphalia and the Boston-Cambridge corridor. Single-source vulnerability runs through cold-chain distribution partnerships for intravenous biologics. Distribution runs through direct manufacturer-specialty clinic contracting models that displace traditional pharmacy benefit manager intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The PSC market sits in early-cycle expansion, with FDA orphan drug designation accelerating clinical trial enrollment velocity beyond historical rare-disease benchmarks.
For Market Incumbents: Harden prescriber relationships at high-volume transplant centers through companion diagnostic integration and patient support program unbundling. Deepen backward integration into biomarker validation partnerships to lock in site activation networks before emerging biologic developers capture investigator bandwidth. For New Entrants and Emerging Players: Community hepatology practices in the United States Southeast represent the most penetrable entry point, where non-invasive MRCP adoption expands addressable patient pools beyond established academic medical center networks. Target prescriber education partnerships emphasizing early intervention windows before transplant eligibility crystallizes. For Investors and Strategic Acquirers: Hepatology-focused mid-cap developers with Phase II antifibrotic assets offer the clearest acquisition target archetype, given surrogate endpoint negotiation precedents that will reshape Phase III investment thresholds. Watch for FDA biomarker qualification determinations as the inflection signal for cirrhosis reversal mechanism valuation repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Integration | Patient stratification tools lock in prescriber relationships and aftermarket revenue streams. |
| EMA Protocol Assistance Engagement | Early regulatory alignment accelerates market access for novel bile acid modulators. |
| Patient Support Program Unbundling | Standalone service contracts displace pharmacy benefit manager intermediation. |
| REACH-Compliant Manufacturing Localization | Excipient substitution decisions create European supply chain differentiation. |
| Surrogate Endpoint Negotiation | FDA biomarker qualification precedents reshape antifibrotic program investment thresholds. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA orphan drug designations, EMA protocol assistance filings, ClinicalTrials.gov enrollment data, and formulary database audits. Interviews with hepatology department heads, regulatory affairs leads at biologic developers, payer access specialists, and specialty clinic procurement managers informed demand-side assumptions. Top-down market sizing from epidemiology-based prevalence models triangulated against bottom-up revenue aggregation across disclosed clinical trial funding and early commercial contracts.
Forecast inputs span treatment line positioning, administration route, patient transplant eligibility status, and regional regulatory cluster across the analysis window. CAGRs derive from segmented growth rate reconciliation against overall market expansion. Modeled variables include MRCP adoption curves, orphan drug designation velocity, and biomarker qualification timelines.
The forecast holds incumbent behavior within observed patterns; aggressive moves by diversified immunology platforms would shift outcomes. Material shifts in FDA surrogate endpoint policy or EMA REACH excipient restrictions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Neurodegenerative Disorder Market
Specialty Medicine
APAC Uterine Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Global Huntingtons Disease Treatment Market
Specialty Medicine
Irritable Bowel Syndrome (IBS) Treatment Market
Specialty Medicine
Advanced Basal Cell Carcinoma Market
Specialty Medicine
Myelofibrosis Market
Specialty Medicine
Global Primary Angle-Closure Glaucoma Market
Specialty Medicine
Transthyretin Amyloidosis Treatment Market
Specialty Medicine
Global Endometriosis Treatment Market
Specialty Medicine
Atrial Septal Defect Market
Specialty Medicine
Aarskog Syndrome Treatment Market
Specialty Medicine
Chronic Myelogenous Leukemia Treatment Market
Specialty Medicine
Global Dry Eye Syndrome Treatment Market
Specialty Medicine
Bipolar Disorders Treatment Market
Specialty Medicine
Behcet's Syndrome Market
Specialty Medicine
Balantidiasis Treatment Market