
 Hemodialysis Equipment Market | 2026-2036
Hemodialysis Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Hemodialysis Equipment Market Intelligence
The traditional distribution channel, centered on large-scale dialysis centers, is tilting toward home care settings and smaller ambulatory clinics. This shift is reshaping the service delivery model for chronic kidney care. Fresenius Medical Care leverages its extensive network of clinics to maintain market leadership. Baxter International competes aggressively in the home hemodialysis segment, while Nipro Corporation sustains a strong position through its focus on dialyzers and blood tubing sets, particularly in Japan and other Asian markets.
Hemodialysis equipment comprises integrated systems designed for extracorporeal blood purification in patients with renal failure. These devices utilize a dialyzer containing thousands of hollow fibers acting as a semipermeable membrane to facilitate waste removal. High-flux dialyzers now dominate the product landscape, offering superior clearance of uremic toxins. While dialysis centers constitute the largest end-user segment, home care settings are expanding rapidly, supported by advances in portable hemodialysis technology.
Regulatory oversight from bodies like the US FDA, the European Medicines Agency (EMA), and Japan's PMDA imposes strict requirements for device approval and post-market surveillance. These standards govern material biocompatibility, sterilisation processes, and clinical efficacy, creating significant barriers to entry for new manufacturers. Navigating evolving reimbursement policies for home-based therapies and investing in user-friendly portable systems are critical for future competitive positioning.
Market Dynamics
The decentralization of care delivery, driven by the development of portable hemodialysis systems, is the central force shaping the market. This structural shift moves treatment from large, centralized clinics to home care settings, altering service models and equipment requirements.
Growth Catalysts
- Expanding Healthcare Access:Public healthcare expansion in countries like China is significantly increasing the diagnosed population with access to renal replacement therapy, directly fueling demand for new hemodialysis machines and consumables.
- Portable Technology:The development of more compact, user-friendly, and automated hemodialysis systems reduces the clinical expertise required for operation, making home-based treatment a viable option for a larger patient cohort.
- Disease Prevalence:A rising global incidence of chronic kidney disease and end-stage renal disease, linked to aging populations and lifestyle factors, provides a continuous and expanding base of patients requiring dialysis.
Market Restraints
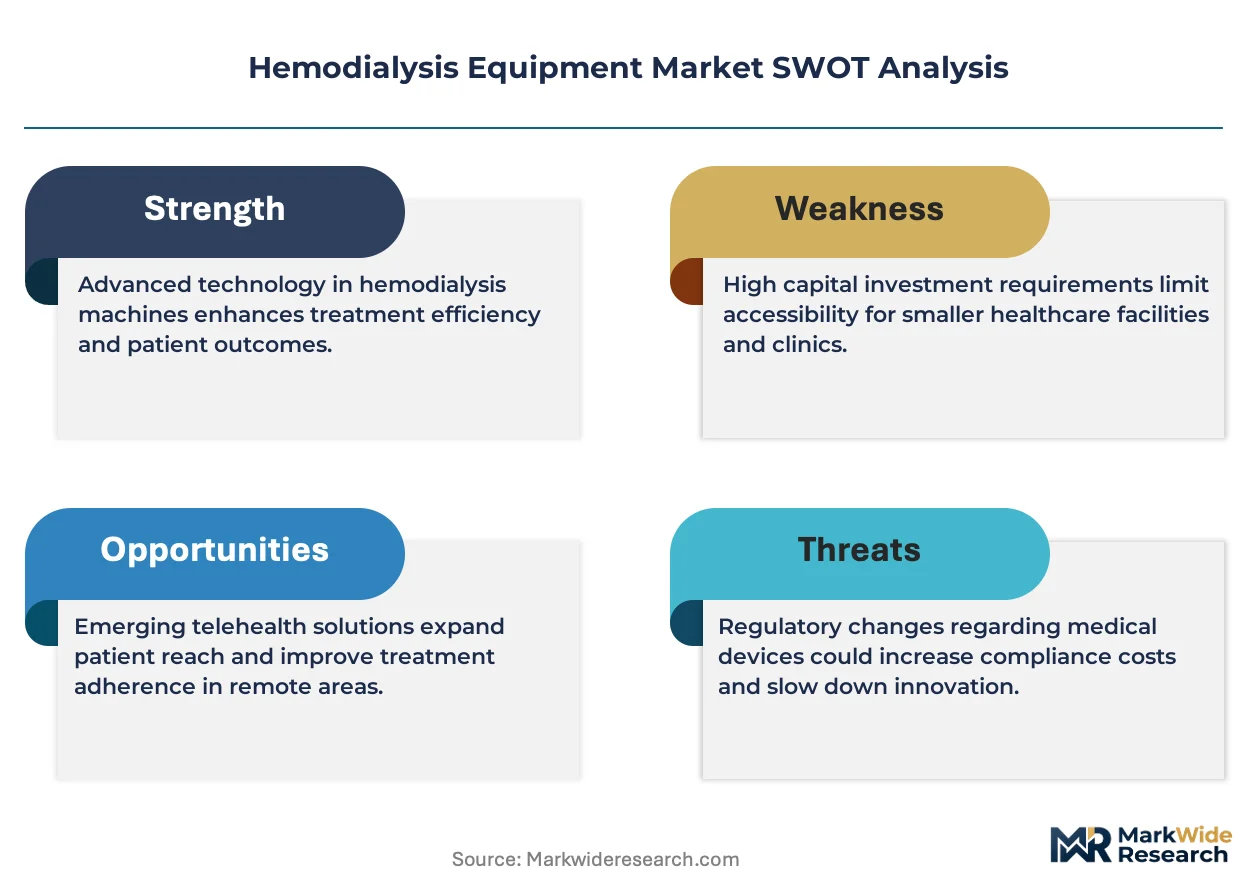
- Stringent Regulatory Hurdles:Strict pre-market approval processes from bodies like the US FDA and EMA, which mandate extensive data on material biocompatibility and clinical efficacy, create high barriers to entry for new competitors.
- High Capital Investment:The substantial upfront cost of acquiring and maintaining integrated hemodialysis systems and related water treatment infrastructure can be prohibitive for smaller ambulatory clinics or healthcare systems in developing economies.
- Alternative Therapies:The availability of peritoneal dialysis as an alternative renal replacement therapy competes for patients, particularly those in earlier stages of renal failure or with specific clinical profiles, limiting the total addressable market.
Strategic Opportunities
- Telehealth Integration:Incorporating remote monitoring and data management capabilities into home hemodialysis systems allows for real-time oversight by clinicians, improving patient safety and adherence while creating new service revenue streams.
- Underpenetrated Geographies:Markets in Latin America and Southeast Asia, where healthcare infrastructure is improving but dialysis penetration remains low, represent significant expansion opportunities for equipment manufacturers and service providers.
- Favorable Reimbursement Policies:Evolving payment models from government and private payers that offer enhanced reimbursement for home-based dialysis therapies create strong financial incentives for both patients and providers to adopt these technologies.
Industry Challenges
- Patient and Caregiver Training:The shift to home care necessitates robust training programs to ensure patients and their families can safely and effectively operate complex medical equipment, manage supplies, and respond to potential complications.
- System Interoperability:Ensuring seamless integration of data from new portable hemodialysis devices with disparate hospital Electronic Health Record (EHR) systems poses a significant technical and logistical challenge for providers.
- Distributed Post-Market Surveillance:Monitoring device performance and managing adverse event reporting across thousands of individual home users presents a greater compliance complexity than surveillance within a controlled clinical environment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hemodialysis Equipment Market |
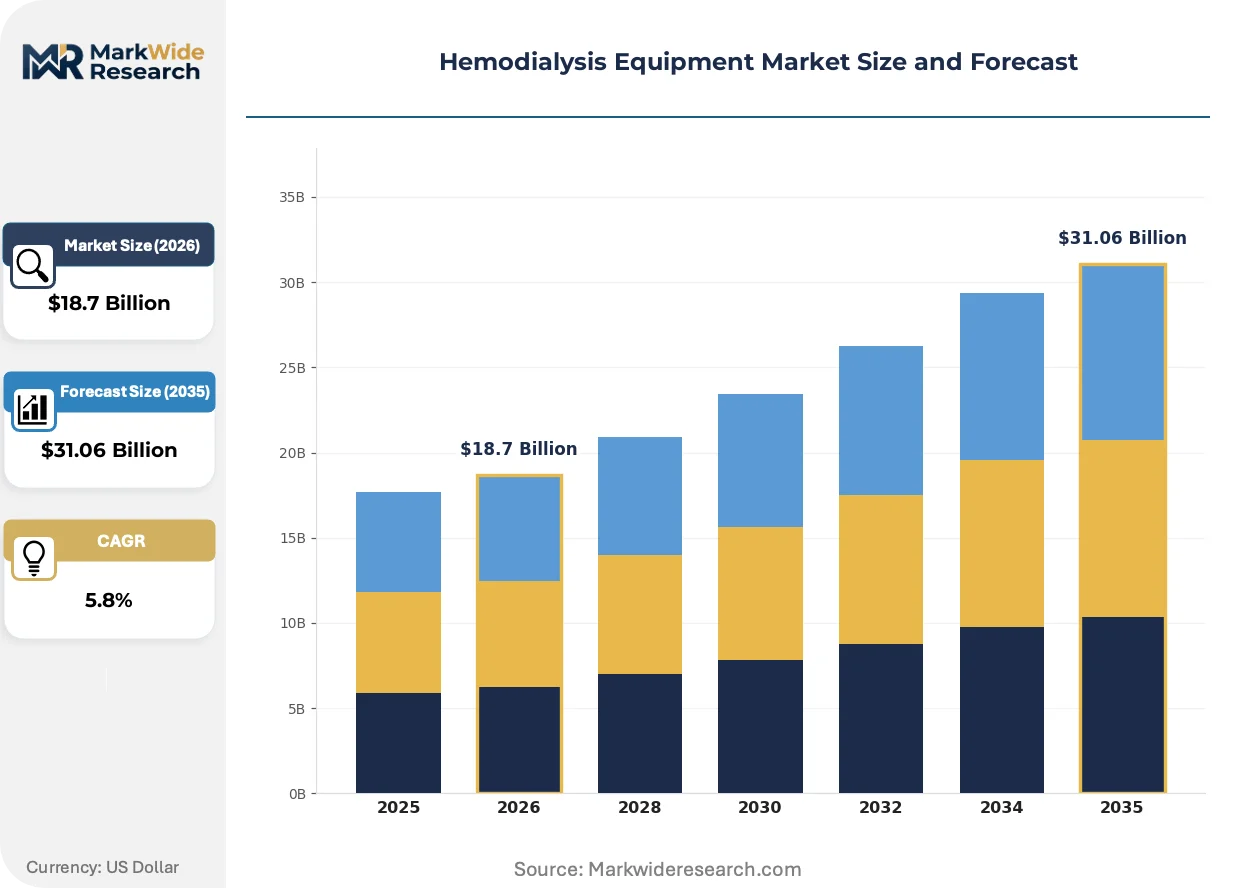
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dialyzers, Hemodialysis Machines, Blood Tubing Sets, Dialysis Concentrates, Ultrafiltration Systems Technology: High-Flux Dialysis, Low-Flux Dialysis, Continuous Renal Replacement Therapy, Portable Hemodialysis Application: End-Stage Renal Disease, Acute Kidney Injury, Chronic Kidney Disease Management, Fluid Overload Treatment End User: Dialysis Centers, Ambulatory Care Facilities, Specialty Clinics, Home Care Settings |
| Companies Covered | Fresenius Medical Care, Baxter International, B. Braun Melsungen, Nipro Corporation, Nikkiso Co., Asahi Kasei Corporation, Toray Industries, JMS Co., Outset Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hemodialysis Equipment Market Strategic Shifts & Innovations
The convergence of advanced membrane science with digital connectivity is redefining the capabilities of hemodialysis equipment. This enables more personalized and effective treatment, supporting the broader transition of chronic kidney care from the clinic to the home.
Dialyzer technology now incorporates high-flux and medium cut-off (MCO) membranes that provide superior clearance of larger middle-molecule uremic toxins. Dialysis centers are adopting these advanced dialyzers to improve clinical outcomes beyond what conventional low-flux membranes can achieve. The standard of care is migrating from basic waste filtration toward more comprehensive toxin removal, which these sophisticated semipermeable membranes make possible.
Europe's Medical Device Regulation (MDR) imposes more stringent requirements for clinical evidence, risk management, and post-market surveillance on manufacturers. This directive elevates the compliance burden and extends development timelines for companies seeking CE marking for new hemodialysis systems and consumables. The dialyzer and blood tubing set segments are particularly affected, compelling investment in updated quality management systems to maintain European market access.
A patient-centric care model emphasizing greater treatment autonomy is gaining momentum. This movement disrupts the traditional, provider-directed approach where large dialysis centers were the default, with more patients actively selecting home hemodialysis to fit their lifestyles. This behavioral shift is most visible in the United States and parts of Western Europe, where patient advocacy and supportive reimbursement structures accelerate adoption.
Hemodialysis Equipment Market Segmentation
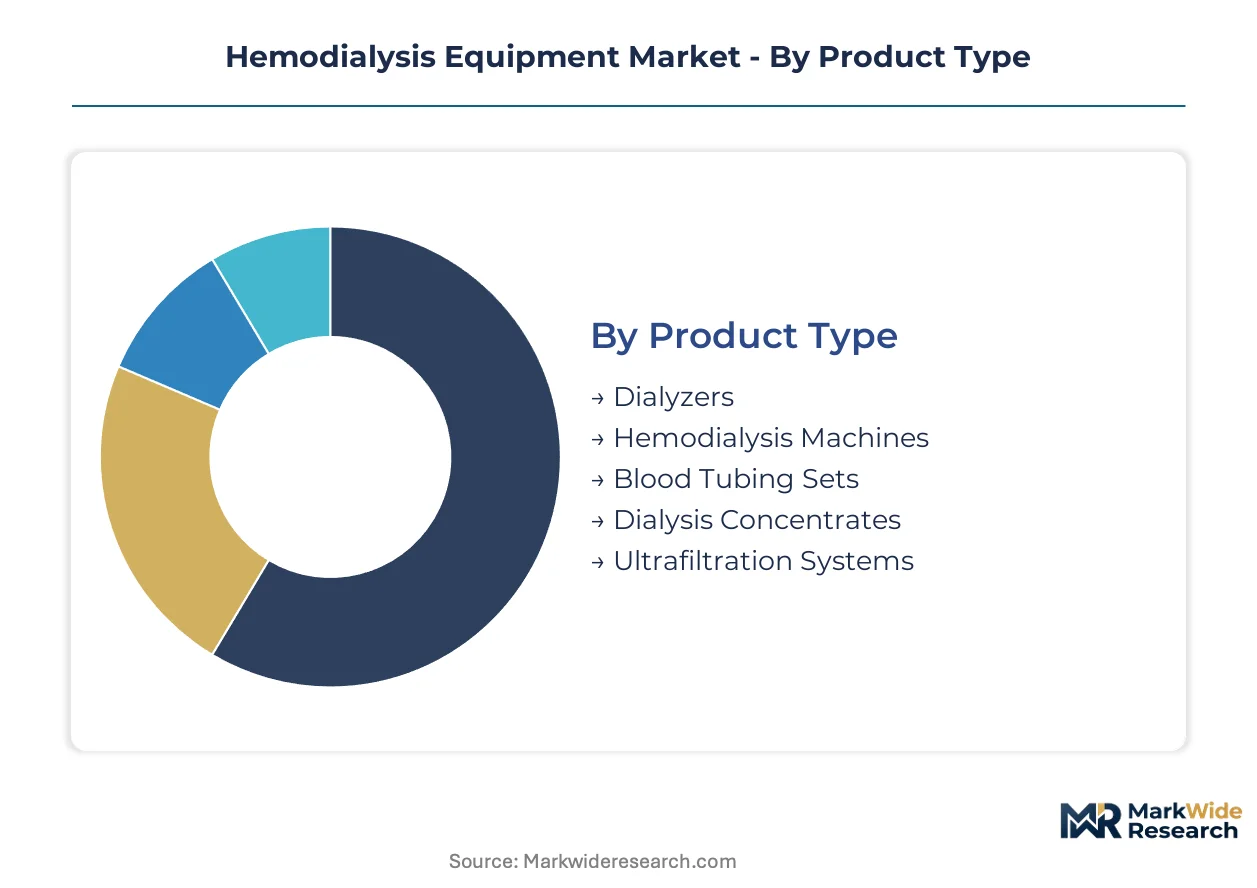
The hemodialysis equipment market segmentation reveals distinct product requirements and service models across varied end-user environments. Understanding these granular segments allows manufacturers to tailor product development and distribution strategies for optimal market penetration and sustained revenue growth.
Product Type:
After-sales service intensity significantly differentiates the product types, with complex machinery requiring extensive maintenance and support compared to disposable consumables. This influences pricing structures and manufacturer-provider relationships.
- Hemodialysis Machines:These integrated systems perform extracorporeal blood purification, typically incorporating blood pumps, dialysate delivery systems, and monitoring functions. Demand concentrates in China, driven by expanding public healthcare access for renal replacement therapy.
- Dialyzers:These are the core components containing semipermeable membranes, facilitating the removal of waste products and excess fluid from the blood. High-flux dialyzers now dominate, offering superior clearance of middle-molecule uremic toxins.
- Blood Tubing Sets:These disposable lines connect the patient to the dialyzer and hemodialysis machine, ensuring sterile blood flow throughout the treatment circuit. Nipro Corporation sustains a strong position in Asian markets for these essential consumables.
- Dialysis Concentrates:These liquid or powder formulations are mixed with treated water to create the dialysate solution, crucial for effective waste removal.
- Ultrafiltration Systems:These devices manage fluid removal during dialysis, preventing fluid overload in patients.
By volume, Dialyzers lead. By growth pace, Hemodialysis Machines are ahead.
Technology:
Application complexity drives the differentiation across hemodialysis technologies, ranging from standard treatments to highly specialized and continuous therapies. Each technology addresses specific patient needs and clinical scenarios.
- Portable Hemodialysis:These compact, user-friendly systems enable home-based treatments, offering greater patient autonomy and reduced travel burdens. Baxter International competes aggressively in this decentralized treatment segment.
- High-Flux Dialysis:This technology utilizes dialyzers with larger pore sizes, allowing for more efficient removal of larger middle-molecule uremic toxins. Dialysis centers increasingly adopt these advanced dialyzers for improved clinical outcomes.
- Low-Flux Dialysis:This traditional technology uses dialyzers with smaller pore sizes, primarily removing smaller solutes and excess fluid.
- Continuous Renal Replacement Therapy:This specialized therapy provides slow, continuous blood purification for critically ill patients with acute kidney injury in intensive care units.
Investment in research and development often targets next-generation portable devices, reflecting a clear strategic shift.
Application:
The customer type for each application segment dictates the treatment duration, frequency, and equipment sophistication required. Chronic conditions necessitate long-term solutions, while acute needs demand immediate, often temporary, interventions.
- End-Stage Renal Disease:This segment represents the largest application, where patients require lifelong renal replacement therapy, typically three times a week. The rising global incidence of chronic kidney disease provides a continuous patient base.
- Chronic Kidney Disease Management:This broader category includes interventions designed to slow disease progression and manage complications before end-stage renal failure. Telehealth integration supports remote monitoring for these patients.
- Acute Kidney Injury:This application involves temporary dialysis for sudden kidney function loss, often in hospital settings.
- Fluid Overload Treatment:Dialysis is used to remove excess fluid from patients who cannot be managed by diuretics alone, often in critical care.
Patient demographics for End-Stage Renal Disease continue to expand globally, particularly in aging populations.
End User:
The maturity of healthcare infrastructure and patient preferences heavily influence the end-user landscape, with established clinical settings contrasting with rapidly expanding home-based care. Decentralization alters equipment requirements and service delivery models.
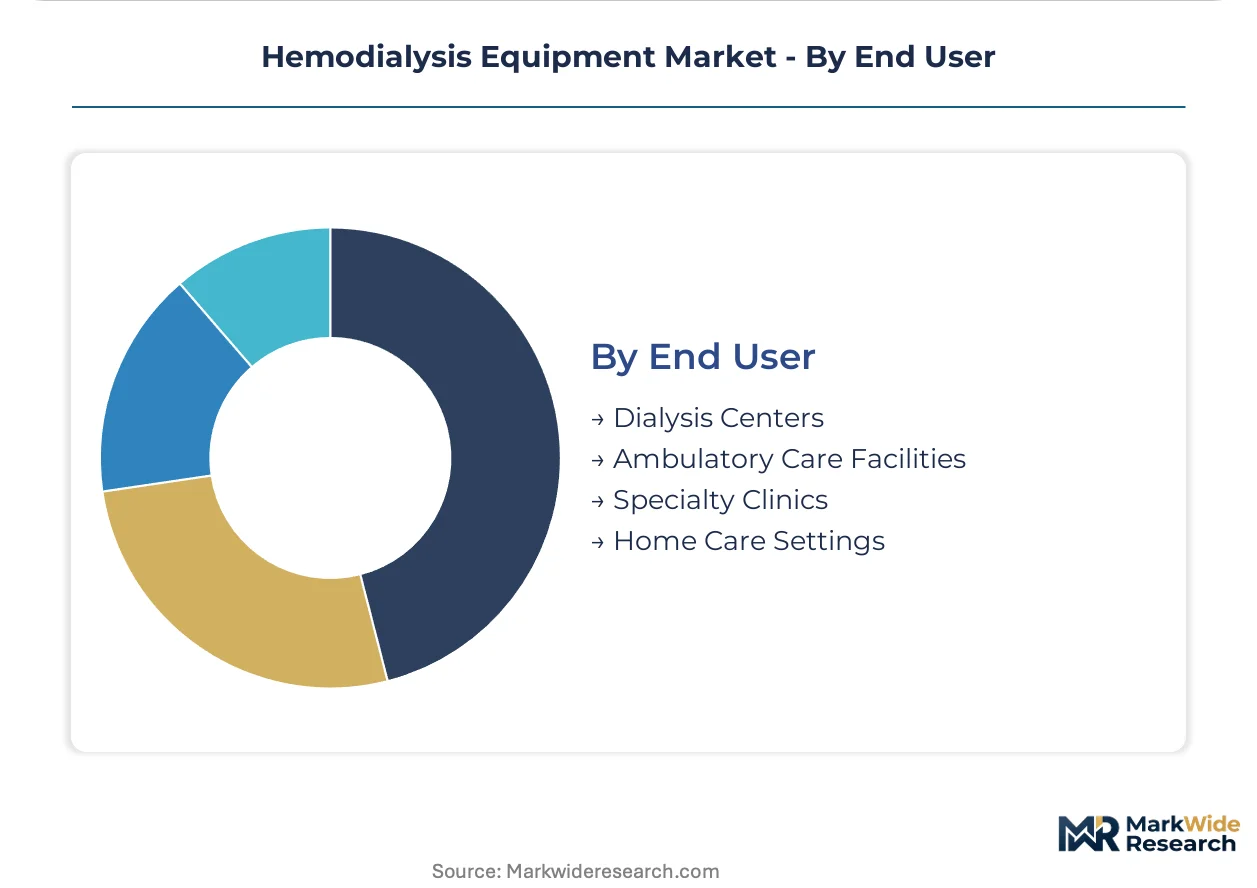
- Home Care Settings:This segment is expanding rapidly, supported by advances in portable hemodialysis technology and patient demand for greater autonomy. Favorable reimbursement policies for home-based therapies create strong financial incentives.
- Dialysis Centers:These large-scale facilities constitute the largest current end-user segment, providing comprehensive dialysis services to a high volume of patients. Fresenius Medical Care leverages its extensive network to maintain market leadership.
- Ambulatory Care Facilities:These smaller clinics offer outpatient dialysis services, often serving as a bridge between large centers and home care.
- Specialty Clinics:These facilities cater to specific patient populations or offer specialized renal care services.
Home Care Settings are gaining share fastest, while Dialysis Centers maintain the largest installed base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The regional pricing power asymmetry between China and the United States significantly influences global hemodialysis equipment distribution. China's expanding public healthcare system drives high volume demand for new machines and consumables, often prioritizing cost-effectiveness. Conversely, the United States market emphasizes advanced home care solutions and patient autonomy, supporting premium pricing for innovative portable systems.
China
Demand for hemodialysis equipment in China is expanding due to increasing public healthcare access and a rising prevalence of chronic kidney disease. The NMPA regulates medical device approvals, ensuring product safety and efficacy within the domestic market. Shanghai and Shenzhen serve as key medical device manufacturing and distribution hubs, facilitating widespread product availability.
United States
The United States market sees a rapid expansion of home care settings, driven by patient advocacy and favorable reimbursement policies for home-based therapies. The US FDA imposes stringent requirements for device approval and post-market surveillance, shaping product development. Major medical technology clusters, such as those in Massachusetts and California, lead innovation in portable hemodialysis systems.
Germany
Germany exhibits strong demand for high-flux dialyzers and advanced hemodialysis technologies, supported by a well-developed healthcare infrastructure. The European Medical Device Regulation (MDR) sets rigorous standards for clinical evidence and risk management for devices sold here. Medical technology companies in regions like Bavaria and Baden-Württemberg contribute significantly to product development and manufacturing.
Japan
Japan maintains a robust market for hemodialysis equipment, characterized by an aging population and a high prevalence of end-stage renal disease. The PMDA oversees strict regulatory processes for medical devices, ensuring compliance with national standards. Companies in the Tokyo and Osaka metropolitan areas are prominent in the development and production of dialyzers and blood tubing sets.
Brazil
Brazil represents a significant growth opportunity due to improving healthcare infrastructure and currently low dialysis penetration rates. ANVISA, the national health surveillance agency, regulates medical device market entry and post-market activities. Major urban centers like São Paulo and Rio de Janeiro act as primary distribution points for hemodialysis equipment across the country.
Hemodialysis Equipment Market Key Industry Players
Integrated service providers and specialized technology developers split the hemodialysis equipment market into distinct competitive arenas. The industry structure favors companies with established distribution networks or those leading innovation in decentralized care solutions. Companies frequently engage in strategic partnerships to expand geographic reach and invest in portfolio diversification to capture emerging segments.
Within the integrated solutions tier, Fresenius Medical Care exemplifies a global leader leveraging an extensive network of clinics and comprehensive product offerings. Baxter International occupies a position as a key innovator in the home hemodialysis segment, aggressively competing with portable system advancements. Nipro Corporation anchors the specialized component segment, particularly strong in dialyzers and blood tubing sets across Asian markets.
| Leading Market Players |
|---|
| Fresenius Medical Care |
| Baxter International |
| B. Braun Melsungen |
| Nipro Corporation |
| Nikkiso Co. |
| Asahi Kasei Corporation |
| Toray Industries |
| JMS Co. |
| Outset Medical |
| Others |
Cost & Logistics Intelligence
Regulatory chokepoints, particularly stringent device approvals, determine pricing tier spreads and significantly shape the hemodialysis equipment supply chain. This oversight influences manufacturing locations and market access for complex systems.
Pricing Analysis
Configured-to-order pricing for advanced hemodialysis machines contrasts with standard transactional pricing for high-volume consumables. The dominant pricing structure is a hybrid, combining per-unit transactional sales for machines with contract-based long-term offtake for dialyzers and blood tubing sets. Price differentiation drivers include extensive after-sales service bundles and stringent regulatory compliance, particularly for US FDA and European MDR standards. Pricing pressure stems from public healthcare budgets in China, while advanced home care users in the United States exhibit lower price sensitivity due to autonomy benefits.
Supply Chain Analysis
Export-control regimes for critical medical technologies could limit the flow of advanced hemodialysis components. Geographic supply concentration for dialyzers and blood tubing sets centers on Japan, Germany, and China. Raw material dependencies include specialized polymeric membranes, medical-grade plastics, and precision electronic components. A structural risk involves single-source vulnerability for specific high-flux dialyzer membranes. Distribution runs through direct sales channels to large dialysis centers and specialized medical distributors for the rapidly expanding home care segment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hemodialysis equipment market is in a cyclical recovery phase, driven by expanding public healthcare access in emerging economies. This creates sustained demand for both new installations and consumable replenishment.
For Market Incumbents: Entrench market leadership by aggressively investing in portable hemodialysis technology research and development. Expand home care support infrastructure to counter the threat from alternative therapies like peritoneal dialysis. Leverage established clinical networks to integrate new user-friendly systems, ensuring seamless patient transitions. Focus on regulatory compliance for advanced systems, particularly under Europe's MDR.
For New Entrants and Emerging Players: Underpenetration in Latin America and Southeast Asia represents a significant white-space opportunity for new market entrants. Target home care settings within these geographies, focusing on cost-effective and user-friendly portable systems. A go-to-market strategy centered on localized manufacturing partnerships can overcome high capital investment barriers. Prioritize regulatory navigation in these specific regional markets.
For Investors and Strategic Acquirers: The market sits at a growth phase that favors agile, specialized technology developers. Long-term viability remains strong over the next 5-10 years, driven by increasing chronic kidney disease prevalence. Identify acquisition targets specializing in portable hemodialysis systems with strong intellectual property. The signal to watch is evolving reimbursement policies for home-based therapies in key Western markets, indicating accelerated adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop Next-Gen Portable Systems | Enhances patient autonomy, supporting decentralized care delivery models. |
| Expand Home Care Training Programs | Ensures safe and effective operation of complex equipment by patients. |
| Integrate Telehealth Capabilities | Enables remote monitoring and improves clinical oversight for home users. |
| Secure Regional Regulatory Approvals | Facilitates market access in underpenetrated geographies like Brazil. |
| Invest in Advanced Dialyzer Membranes | Improves toxin clearance, advancing clinical outcomes for ESRD patients. |
Research Approach
Cross-validation between primary interviews and extensive secondary research anchors the qualitative findings of this study. The analysis involved discussions with nephrologists, hospital procurement managers, biomedical engineers, and patient advocacy group representatives. Secondary validation utilized US FDA filings, European Medicines Agency reports, and national healthcare expenditure databases. A bottom-up and top-down triangulation approach ensured robust data integrity.
The forecast framework was calibrated against historical market performance and projected industry shifts across the analysis window. Segmentation dimensions modeled include product type, technology, application, end user, and regional regulatory clusters. Compound annual growth rates were derived from historical trends and anticipated market dynamics. Key industry-specific forecast inputs included chronic kidney disease prevalence rates and public healthcare spending allocations.
Practitioners should monitor major regulatory changes or rapid technological obsolescence for early signals impacting market trajectories. Forecasts reflect assumptions regarding healthcare infrastructure development and patient adoption rates. Material shifts in reimbursement policies for home-based therapies would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Global Optometry Equipment Market
Medical Equipment
Tissue Processing Systems Market
Medical Equipment
Global Emergency Medical Equipment Market
Medical Equipment
Mortuary Refrigerator Market
Medical Equipment
MRI Transport Market
Medical Equipment
Medical Equipment Leasing Market
Medical Equipment
Cell Washer Market
Medical Equipment
Global Surgical Table Market
Medical Equipment
Asia-Pacific Medical Carts Market
Medical Equipment
Global Vacuum Mixing Devices Market
Medical Equipment
Global Kidney Dialysis Equipment and Supplies Market
Medical Equipment
Global Cardiopulmonary Stress Testing Systems Market
Medical Equipment
Radiotherapy Motion Management Market
Medical Equipment
US Biomedical Refrigerators and Freezers Market
Medical Equipment
Global Medical Refrigerators Market
Medical Equipment
Global Plasma Sterilizers Market