
 MRI Transport Market | 2026-2036
MRI Transport Market Size, Share, and Industry Trends Forecast 2026-2036
MRI Transport Market Foresight
Lightweight cryogen-free superconducting magnet designs is narrowing the engineering trade-off between field strength and transportability that has long constrained mobile MRI deployment. Stryker leverages its hospital logistics infrastructure to bundle transport with installation services across integrated delivery networks. Magnetica anchors its position in helium-recovery systems that reduce cryogen dependency during long-haul magnet relocation. Newmatic Medical specializes in patient-handling accessories that integrate with transport frames to protect coil assemblies in transit.
MRI transport encompasses the engineered movement of superconducting imaging systems, typically involving active shielding coils operating at 1.5–3.0 Tesla and cryostat assemblies maintaining 4 Kelvin via liquid helium or closed-cycle refrigeration, with primary purpose being the relocation of diagnostic capacity to underserved clinical settings or temporary surge sites. Fixed MRI dominates installed base value but generates minimal transport revenue outside replacement cycles, whereas MRI trailers represent the fastest-expanding product type as health systems pursue asset-light capacity models. Rental services command superior margins compared with one-time transport logistics due to recurring revenue and bundled technical support.
FDA center for devices and radiological health oversees magnet safety certification for interstate transport, while DOT pipeline and hazardous materials safety administration regulates helium and nitrogen cryogen shipment classifications that constrain routing options. ISO 13485 quality management standards further govern service providers performing installation and maintenance during relocation events. Stakeholders must weigh total cost of ownership against utilization rates when choosing between captive transport fleets and third-party logistics specialization.
Market Dynamics
Cryogen-free superconducting magnet architectures are dissolving the historical engineering compromise between diagnostic field strength and roadworthy transportability, unlocking rural stroke networks and surge-capacity deployment models that fixed installations cannot serve.
Growth Catalysts
- Rural Emergency Networks:Stroke triage protocols in underserved North American regions now mandate 90-minute imaging windows that only mobile MRI trailers can satisfy.
- EMA Transport Guidelines:Harmonized cross-border magnet movement standards across European Economic Area members are reducing customs friction for leased equipment circulation.
- Helium Recovery Infrastructure:Closed-loop cryogen recapture systems are cutting per-relocation helium costs by half, making repeat transport economically viable for mid-sized health systems.
Market Restraints
- Liquid Helium Supply Concentration:Qatar and the United States control over 80% of global helium production, exposing transport operators to price volatility and export quota disruptions.
- DOT Hazmat Routing Constraints:Pipeline and Hazardous Materials Safety Administration cryogen classifications force circuitous highway paths that extend delivery timelines and inflate fuel costs.
- Active Shielding Weight Penalties:Electromagnetic interference suppression coils add 3-4 tonnes to magnet assemblies, restricting trailer axle configurations and bridge clearance compliance.
Strategic Opportunities
- University Hospital Satellite Leasing:German academic medical centers are consolidating procurement through shared mobile fleets that rotate between urban hubs and rural affiliates.
- ISO 13485-Certified Logistics:Third-party transport providers with quality management certification can capture installation and maintenance bundling contracts from OEM service divisions.
- AI-Assisted Route Optimization:Machine learning algorithms predicting cryogen boil-off rates against traffic patterns are enabling longer-haul magnet movements without intermediate helium replenishment.
Industry Challenges
- Cryogen Handling Certification Shortage:Licensed technicians qualified for 4 Kelvin system maintenance during transport events command premium wages that compress service margins.
- FDA 510(k) Parallel Pathway Complexity:Magnet relocation triggering installation modification reviews can add 90-120 days to deployment schedules for refurbished systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | MRI Transport Market |
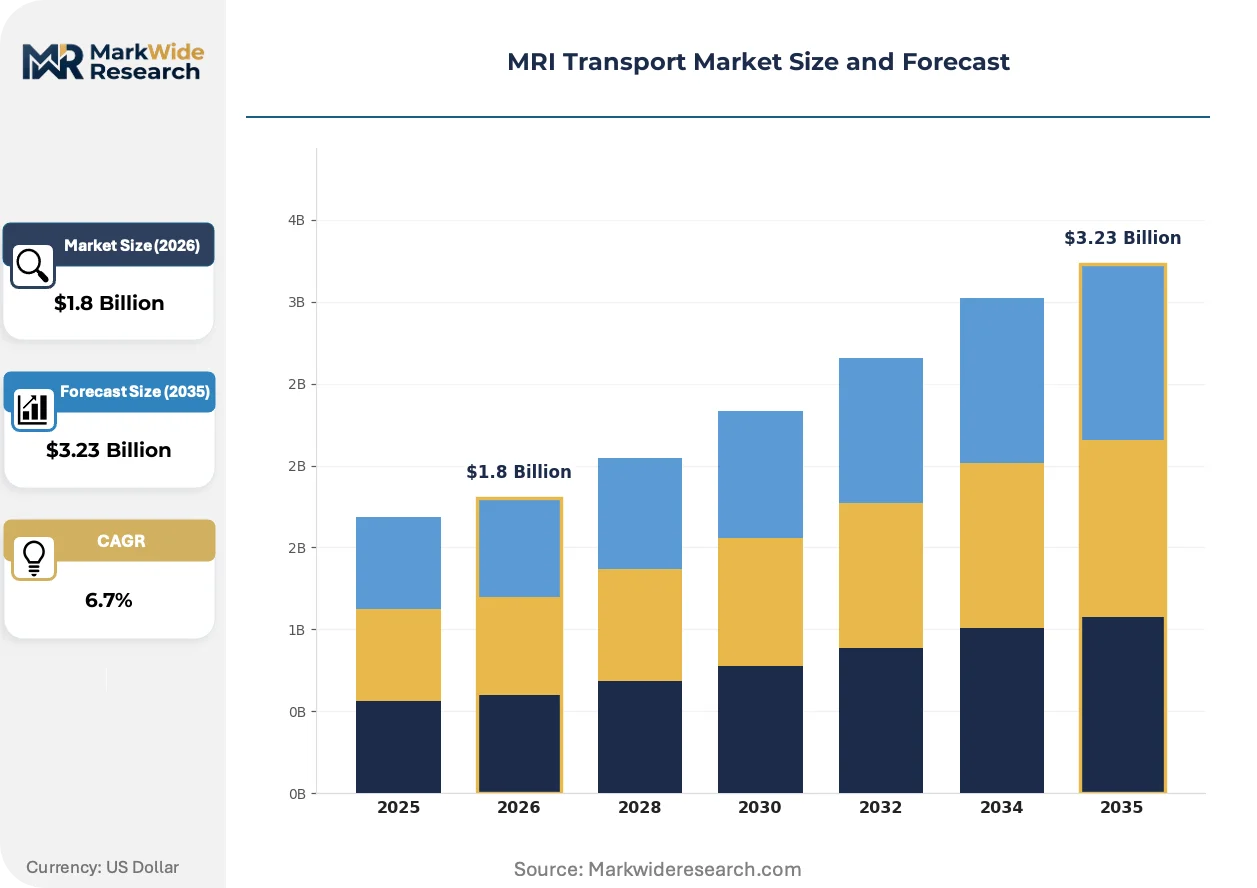
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed MRI, Mobile MRI, MRI Trailers, MRI Shipping Containers End User: Hospitals, Imaging Centers, Research Institutions, Emergency Services Technology: Gradient Magnets, Superconducting Magnets, Open MRI, Closed MRI Service Type: Installation, Maintenance, Transport Logistics, Rental Services |
| Companies Covered | Biodex Medical Systems, Newmatic Medical, Magmedix, Stryker, Alstom, Magnetica, Patient Handling, Ergoline, Stand-Up MRI Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
MRI Transport Market Shifts & Advancements
Equipment mobility is redefining asset ownership economics across diagnostic imaging, compressing capital deployment cycles and fragmenting traditional vendor-service relationships into specialized logistics ecosystems.
Closed-cycle cryocooler technology is collapsing the dependency on liquid helium replenishment during magnet transport. Rural health districts in the United States are adopting these systems for 72-hour autonomous operation. The shift is collapsing transport logistics from scheduled cryogen tanker convoys to standard flatbed freight.
Europe's F-Gas Regulation is phasing down hydrofluorocarbon refrigerants used in MRI cooling subsystems, compelling manufacturers to redesign cryostat architectures for lower-global-warming-potential alternatives. Transport operators must now certify compatibility with new refrigerant classifications before cross-border equipment movement. German leasing networks are responding by consolidating refurbishment cycles to synchronize with refrigerant transition deadlines.
Asset-light procurement through per-scan rental agreements is displacing capital purchase models among mid-sized health systems. Third-party logistics providers are capturing recurring revenue streams previously retained by OEM service divisions. This behavioral pivot concentrates in North American integrated delivery networks seeking balance-sheet flexibility for capacity surge events.
MRI Transport Market Segmentation
Transport modality selection determines capital deployment cycles and regulatory compliance burden across health systems. Segment-specific engineering requirements create divergent margin profiles and vendor specialization patterns.
Product Type:
Mature hospital infrastructure contrasts sharply with emerging mobile deployment models reshaping asset ownership economics.
- Fixed MRI:Permanent installations with active shielding coils and integrated cryostat infrastructure dominate replacement-driven transport revenue. Hospital consolidation in Germany concentrates demand for decommissioning and site-to-site relocation within university networks.
- Mobile MRI:Self-contained imaging units mounted on heavy-duty chassis enable rapid deployment to underserved clinical settings. Stroke triage protocols across rural United States districts mandate 90-minute imaging windows that mobile units alone satisfy.
- MRI Trailers:Custom-engineered transport platforms with independent power and climate systems support multi-day autonomous operation. Leasing networks rotate these assets between urban hubs and rural affiliates.
- MRI Shipping Containers:Standardized intermodal enclosures facilitate ocean freight and rail movement for international equipment circulation. EMA harmonized transport guidelines reduce customs friction for containerized magnet cross-border movement.
Fixed MRI retains volume leadership; MRI trailers hold the steepest expansion curve.
End User:
Institutional scale and reimbursement structure differentiate procurement patterns across customer categories.
- Hospitals:Acute care facilities with captive biomedical engineering departments favor bundled installation and maintenance contracts. Integrated delivery networks in the United States pursue asset-light capacity models through third-party logistics partnerships.
- Imaging Centers:Independent diagnostic facilities prioritize per-scan rental agreements to minimize capital deployment and balance-sheet exposure. These operators drive demand for rapid-deployment mobile units serving suburban patient catchments.
- Research Institutions:Academic medical centers with specialized spectroscopy requirements demand high-field transport capabilities for 7 Tesla and above systems. Helium recovery infrastructure investment concentrates at these sites due to frequent magnet reconfiguration.
- Emergency Services:Pre-hospital stroke networks and disaster response agencies require autonomous mobile platforms with 72-hour cryogen endurance. Rural emergency services units in North America now specify rapid-deployment trailers as standard equipment.
Hospitals dominate installed base value; emergency services are climbing the fastest among end-user categories.
Technology:
Field strength and patient accessibility specifications determine transport complexity and routing constraints.
- Gradient Magnets:Rapid-switching coil assemblies for functional imaging impose vibration isolation requirements during movement. Research institutions in Germany specify gradient systems for advanced neuroimaging protocols.
- Superconducting Magnets:Niobium-titanium solenoids operating at 4 Kelvin with active shielding dominate diagnostic field strength above 1.5 Tesla. Cryogen-free closed-cycle architectures are collapsing helium dependency for long-haul transport.
- Open MRI:Permanent magnet or resistive designs with vertical field orientation permit claustrophobic patient accommodation. Lower field strength reduces shielding mass and eases trailer axle compliance.
- Closed MRI:Cylindrical bore configurations with superconducting solenoids achieve highest signal-to-noise ratios. Active shielding weight penalties restrict bridge clearance and routing options.
Superconducting magnets retain volume leadership; cryogen-free variants within this category are gaining share fastest.
Service Type:
Revenue recurrence and technical certification requirements separate high-margin recurring streams from transactional logistics.
- Installation:Site preparation, magnet positioning, and cryogen filling demand ISO 13485-certified technician teams. FDA 510(k) parallel pathway reviews for refurbished system relocation extend deployment schedules.
- Maintenance:Preventive service contracts with guaranteed uptime provisions generate superior margins through recurring revenue. OEM service divisions face displacement by third-party certified logistics providers.
- Transport Logistics:One-time magnet movement with DOT hazmat routing compliance and cryogen tanker coordination. DOT Pipeline and Hazardous Materials Safety Administration classifications force circuitous highway paths.
- Rental Services:Per-scan agreements with bundled technical support enable asset-light procurement for mid-sized health systems. These contracts concentrate in North American integrated delivery networks seeking balance-sheet flexibility.
Rental services command margin leadership; transport logistics represents the largest addressable volume pool.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital networks and emergency services departments concentrate procurement authority across four distinct national markets. Each geography exhibits unique regulatory constraints and infrastructure maturity patterns.
United States
Rural stroke triage networks and integrated delivery systems drive trailer deployment across the Great Plains and Mountain West. FDA Center for Devices and Radiological Health oversees interstate magnet certification, while DOT Pipeline and Hazardous Materials Safety Administration cryogen classifications force circuitous routing through Texas and Arizona corridor hubs.
Germany
University hospital networks lease mobile units to balance imaging capacity across satellite campuses in Bavaria and North Rhine-Westphalia. EMA harmonized transport guidelines reduce customs friction for cross-border equipment circulation between German and Dutch clinical sites. Berlin-Brandenburg academic medical centers anchor helium-recovery infrastructure investment.
Canada
Provincial health authorities in Ontario and Quebec contract mobile MRI services to address seasonal demand surges and remote community access gaps. Health Canada device licensing requirements parallel FDA frameworks but permit accelerated approval pathways for refurbished system relocation. Calgary and Edmonton clusters concentrate third-party logistics specialization.
Japan
Super-aging prefectures in rural Honshu deploy autonomous mobile platforms to maintain diagnostic access amid hospital consolidation. METI industrial standards govern cryostat safety certification for magnet movement between islands. Osaka-Kansai medical device manufacturers supply closed-cycle cryocooler technology reducing helium dependency.
Australia
Remote Indigenous health services and mining camp medical facilities contract trailer-based imaging across Western Australia and Queensland. TGA medical device regulations align with ISO 13485 quality management standards for installation and maintenance bundling. Perth and Brisbane logistics hubs coordinate intermodal containerized magnet movement.
MRI Transport Market Competitive Landscape
Channel-controlling players compete with product-specialist players across installation, maintenance, and transport logistics segments. Market structure tilts toward consolidation among OEM-affiliated service divisions, while independent operators fragment across regional niches. Three archetypes dominate: hospital logistics integrators bundling transport with capital equipment, cryogen infrastructure specialists capturing recurring helium recovery revenue, and patient-handling accessory fabricators protecting coil assemblies. Competitive moves center on ISO 13485 certification acquisition for installation bundling contracts and AI-assisted route optimization development for longer-haul cryogen endurance.
Among diversified hospital logistics operators, Stryker anchors the integrated delivery network channel through bundled service contracts. Magnetica occupies a position within cryogen infrastructure tiers, exemplifying helium-recovery system specialization. Newmatic Medical represents the patient-handling accessory archetype, fabricating transport frame integrations that protect coil assemblies. These three companies illustrate the strategic segmentation between capital equipment bundling, cryogen lifecycle management, and component-level protection systems.
| Leading Market Players |
|---|
| Biodex Medical Systems |
| Newmatic Medical |
| Magmedix |
| Stryker |
| Alstom |
| Magnetica |
| Patient Handling |
| Ergoline |
| Stand-Up MRI Systems |
| Others |
Supply & Pricing Matrix
The Texas-Arizona corridor's fuel and hazmat routing premiums concentrate pricing power among cryogen-certified logistics operators, compressing margins for standard freight providers while enabling premium tiering for DOT-compliant specialists serving rural stroke networks and university hospital leasing pools.
Pricing Analysis
Cost-plus contracts with helium indexation dominate long-haul magnet relocation agreements, tying transport fees to spot cryogen markets. Price differentiation hinges on ISO 13485 certification tier and bundled installation scope, with certified providers commanding substantial premiums over transactional logistics brokers. Pricing pressure intensifies as closed-cycle cryocooler technology collapses helium dependency, forcing traditional cryogen-reliant operators toward service bundling. Emergency services units exhibit highest price sensitivity due to constrained municipal budgets, while research institutions prioritize uptime guarantees over unit cost.
Supply Chain Analysis
Contract manufacturing for cryostat assemblies concentrates in Germany, Japan, and the United States, with Osaka-Kansai suppliers anchoring closed-cycle cryocooler production. The supply chain draws from niobium-titanium superconductor feedstock, liquid helium recovery infrastructure, and active shielding coil fabrications. Single-source vulnerability in helium refining—concentrated in Qatar and the United States—exposes transport operators to export quota disruptions. Distribution runs through OEM-affiliated service divisions and third-party ISO-certified logistics networks, with leasing intermediaries capturing recurring revenue streams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as cryogen-free superconducting architectures unlock rural deployment models previously uneconomical for mobile MRI capacity, with stroke triage protocol mandates accelerating penetration across underserved clinical catchments.
For Market Incumbents: Entrench position through captive helium-recovery infrastructure investment and backward integration into cryostat refurbishment cycles. OEM service divisions face displacement by certified third-party logistics providers; defensive consolidation through ISO 13485 certification acquisition for installation bundling contracts protects channel control. Capacity addition in German university hospital networks and North American integrated delivery systems reinforces recurring revenue capture. For New Entrants and Emerging Players: Build out AI-assisted route optimization capabilities targeting 72-hour autonomous cryogen endurance for long-haul magnet movements. Emergency services trailer deployment in rural United States districts represents the most penetrable segment, with per-scan rental agreements offering the clearest go-to-market angle against capital-purchasing inertia among mid-sized health systems. For Investors and Strategic Acquirers: Cryogen infrastructure specialists with closed-loop recapture technology and established DOT hazmat compliance protocols offer the strongest acquisition target profile. Long-term viability hinges on the technology transition window from helium-dependent to cryogen-free superconducting architectures. Watch helium spot price volatility as the inflection signal—sustained elevation accelerates closed-cycle adoption and compresses traditional logistics margins.| Strategic Initiative | Industry Significance |
|---|---|
| Helium Recovery Infrastructure Investment | Closed-loop recapture systems cut per-relocation costs and enable repeat transport economics for mid-sized health systems. |
| ISO 13485 Certification Acquisition | Quality management certification unlocks installation and maintenance bundling contracts from OEM service divisions. |
| AI-Assisted Route Optimization Development | Machine learning predicting cryogen boil-off against traffic patterns extends autonomous operation windows without replenishment. |
| University Hospital Satellite Leasing Partnerships | German academic medical center networks consolidate procurement through shared mobile fleets rotating between urban and rural sites. |
| Closed-Cycle Cryocooler Technology Integration | Cryogen-free architectures collapse dependency on liquid helium replenishment and standardize transport to flatbed freight. |
Research Methodology
The analysis maps mobile MRI trailer deployment, fixed magnet relocation, cryogen logistics, and rental service segments, each validated through biomedical engineering directors, hospital procurement committees, DOT hazmat compliance officers, and third-party logistics operators. Primary interviews with GPO contracts managers and helium supply specialists combined with secondary validation from FDA 510(k) filings, DOT PHMSA routing databases, EMA transport guideline harmonization documents, and hospital procurement databases. Bottom-up equipment movement volume estimates and top-down health system capital expenditure patterns were triangulated to anchor market sizing.
Assumptions held fixed include EMA guideline harmonization progress and closed-cycle cryocooler adoption curves, while helium spot price volatility and FDA parallel pathway review durations were stress-tested across scenarios. The projection horizon spans product type segmentation by fixed, mobile, trailer, and container modalities; end-user categories spanning hospitals, imaging centers, research institutions, and emergency services; and technology tiers from open permanent magnets to cryogen-free superconducting systems. CAGRs were derived from installed base replacement cycles and net new mobile deployment penetration rates, with rural stroke network mandate adoption and university hospital leasing contract velocity serving as key forecast inputs.
Stress conditions across helium export quota disruptions, DOT hazmat reclassification events, and FDA 510(k) review timeline extensions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions that could revise materially with regulatory or technological discontinuities. Cross-checking against health system capital expenditure surveys and GPO contract award databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Medical Linear Accelerators (MLA) Market
Medical Equipment
Embedded Disinfection Cabinet Market
Medical Equipment
X-Ray Generator Market
Medical Equipment
Hospital-at-Home Equipment Rental Market
Medical Equipment
Refurbished MRI Systems Market
Medical Equipment
Portable Steam Autoclave Market
Medical Equipment
Photorejuvenation Equipment Market
Medical Equipment
Europe Medical Carts Market
Medical Equipment
Medical Equipment Calibration Services Market
Medical Equipment
Global Hospital Equipment and Supplies Market
Medical Equipment
North America Medical Carts Market
Medical Equipment
Global Indirect Calorimeter Market
Medical Equipment
Global Stereotactic Radiosurgery (Gamma Knife) Market
Medical Equipment
Operating Light Market
Medical Equipment
Next Generation Centrifuge Market
Medical Equipment
Surgical Generators Market