
 ASEAN Telehealth Services Market | 2026-2036
ASEAN Telehealth Services Market Size, Share, and Industry Trends Forecast 2026-2036
ASEAN Telehealth Services Market Insights
Multi-source platform procurement is hardening as the dominant sourcing pattern across ASEAN health systems. Doctor Anywhere leverages its Singapore hub to anchor regional specialist access for Southeast Asian patients. Halodoc competes through hyperlocal pharmacy integration and on-demand diagnostics in Indonesian secondary cities. Alodokter sustains brand strength via content-driven patient acquisition and employer-sponsored telehealth contracts.
ASEAN telehealth services encompass real-time clinical consultation, asynchronous diagnostic review, and continuous physiological monitoring delivered through encrypted digital infrastructure with latency requirements below 150 milliseconds for video triage. These systems extend specialist reach into medically underserved provinces while reducing avoidable emergency transfers. Real-time consultation leads current revenue pools across the service type dimension, though remote monitoring captures the fastest expansion as chronic disease burdens deepen in Malaysia and Vietnam. Direct-to-consumer channels still dominate transaction volume, yet B2B partnerships with insurance companies and corporate clients concentrate margin pools through annual subscription structures.
Thailand's Medical Hub designation, Singapore's Health Sciences Authority telemedicine guidelines, and Vietnam's Ministry of Health circular on remote consultation standards collectively shape product registration pathways and cross-border data governance. The Health Insurance Portability and Accountability Act framework influences ASEAN platforms serving medical tourists from the United States, while ASEAN's Mutual Recognition Arrangements on telemedicine qualifications remain incomplete. Stakeholders must monitor which national regulator moves first to harmonize prescription authority across jurisdictions, as that decision will determine where regional platform headquarters consolidate clinical governance functions.
Market Dynamics
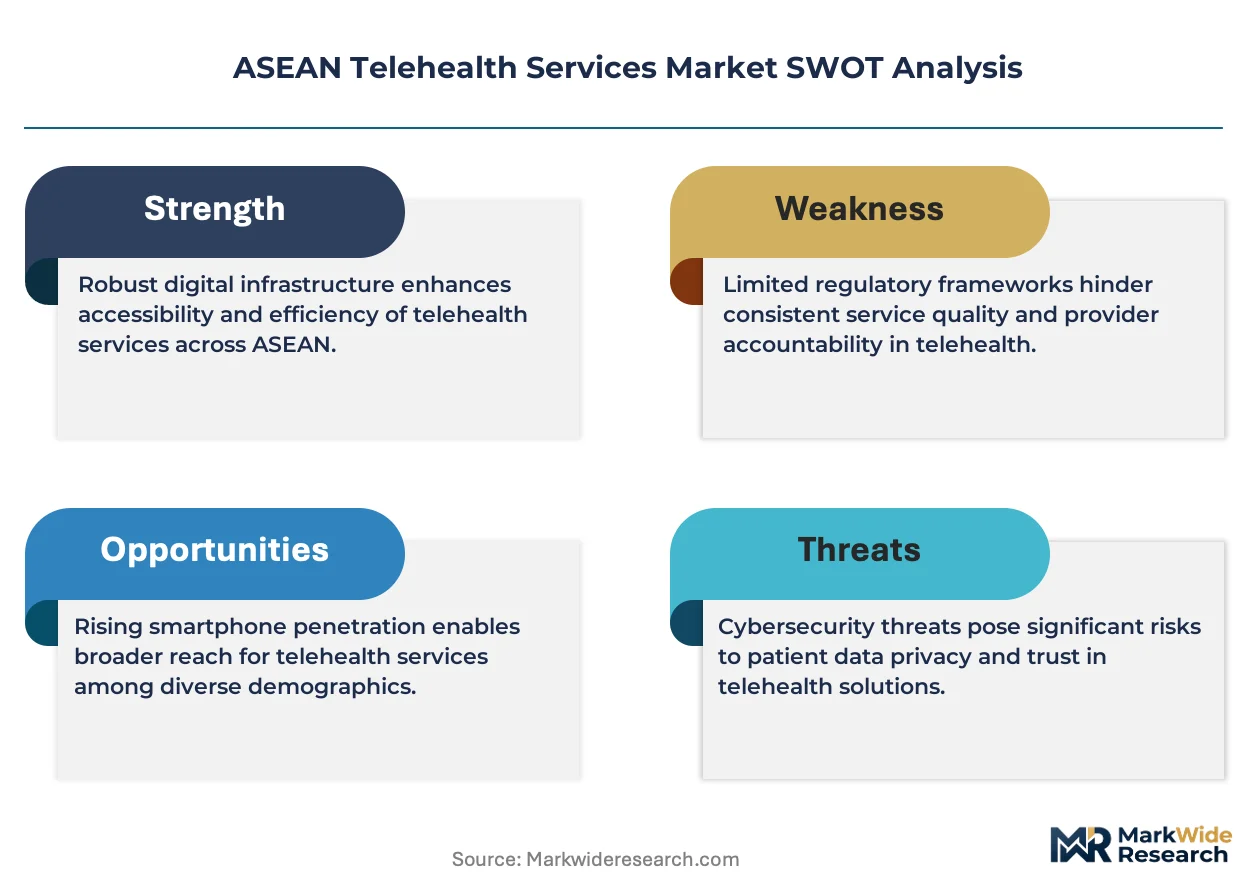
Cross-border data governance fragmentation is forcing ASEAN telehealth platforms to maintain redundant clinical governance infrastructure across multiple national jurisdictions rather than consolidating operations in single regulatory hubs.
Growth Catalysts
- Singapore's Health Sciences Authority telemedicine guidelines:These standards create exportable compliance templates that reduce registration friction for platforms expanding into neighboring markets.
- Chronic disease monitoring:Rising diabetes and cardiovascular burdens in Malaysia and Vietnam are pulling continuous physiological monitoring into mainstream reimbursement schemes.
- Metropolitan corridor demand:Patient flows connecting Bangkok, Ho Chi Minh City, and Singapore generate concentrated transaction volumes that justify specialist platform investments.
Market Restraints
- Incomplete Mutual Recognition Arrangements:ASEAN's unfinished framework for telemedicine qualifications forces platforms to duplicate physician credentialing across each national market.
- Latency infrastructure gaps:Rural provinces in Indonesia and the Philippines lack fiber backbone density to consistently meet sub-150 millisecond video triage requirements.
- Prescription authority fragmentation:Divergent national rules on remote prescribing create compliance complexity that limits cross-border service standardization.
Strategic Opportunities
- Vietnam's Ministry of Health circular on remote consultation standards:This regulatory clarity positions Vietnam as a potential early mover for regional clinical governance consolidation.
- Employer-sponsored telehealth contracts:Corporate wellness programs in Thailand and Singapore represent underpenetrated B2B channels with annual subscription margin profiles.
- AI-assisted diagnostic triage:Integration of machine learning with asynchronous diagnostic review is opening specialty access in Indonesian secondary cities without specialist density.
Industry Challenges
- Clinical governance talent scarcity:Platforms struggle to recruit physicians with dual competencies in specialty medicine and digital care protocol design.
- Legacy hospital EMR integration:Public health systems in the Philippines and Indonesia operate on fragmented electronic medical record architectures that resist API-based platform connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ASEAN Telehealth Services Market |
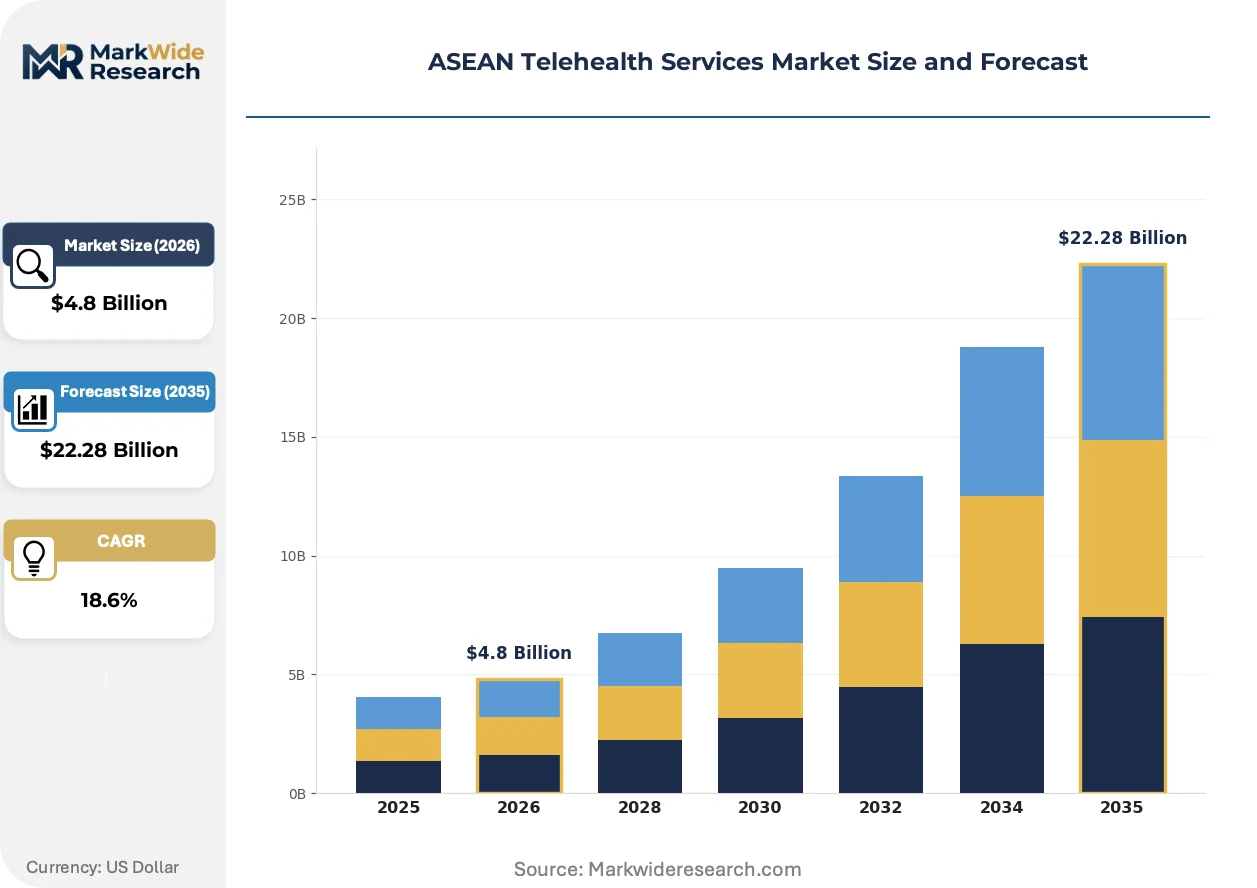
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.28 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Real-Time Consultation, Remote Monitoring, Mobile Health Applications, Teletherapy Delivery Model: Direct-to-Consumer, B2B Partnerships, Health System Integration, Free-Standing Clinics Technology: Video Conferencing, Messaging Platforms, Wearable Devices, AI Diagnostics End User: Patients, Healthcare Providers, Insurance Companies, Corporate Clients |
| Companies Covered | Doctor Anywhere, Halodoc, Alodokter, SeeYouDoc, Viettel, Good Doctor Technology, Doc2Us, DoctorOnCall, MyDoc, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ASEAN Telehealth Services Market Trends and Innovations
Platform architecture is pivoting from standalone consultation apps toward embedded health system infrastructure, with latency-sensitive video triage and AI-assisted diagnostic layers becoming core competitive differentiators rather than peripheral features.
AI-assisted diagnostic triage is automating preliminary symptom assessment and specialist routing decisions that previously required human nurse intake. Indonesian and Vietnamese hospital networks are deploying these systems at scale to manage specialist queue overflow. The technology is automating clinical workflow compression that reduces average time-to-diagnosis from days to hours for non-urgent cases.
Thailand's Medical Hub policy is reshaping cross-border service authorization by creating streamlined licensing pathways for foreign-registered telehealth providers serving medical tourists. The policy framework enables Singapore-based platforms to legally serve Thai patients without establishing domestic legal entities. Specialist telehealth segments targeting cosmetic and orthopedic consultation are restructuring their regulatory compliance stacks around this pathway.
Direct-to-consumer transaction models are yielding ground to B2B annual subscription structures as insurance companies and corporate clients consolidate purchasing power. Platform revenue concentration is rotating toward employer-sponsored contracts and payer partnerships in Bangkok and Singapore metropolitan zones. This shift is most visible in chronic disease management verticals where Malaysia's corporate wellness mandates create captive demand pools.
ASEAN Telehealth Services Market Segmentation
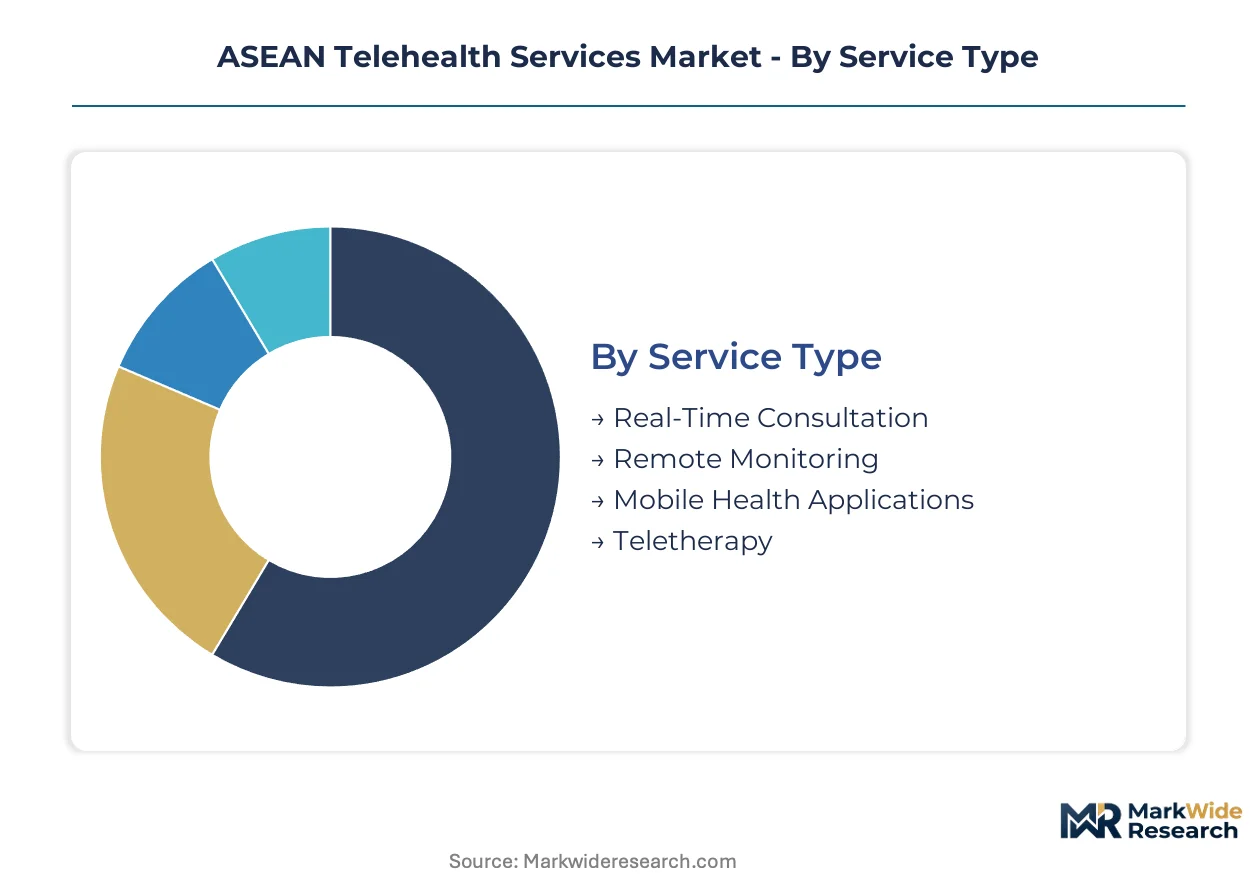
Segmentation in ASEAN telehealth reveals how platform economics diverge across service modalities and customer relationships. Each dimension exposes distinct margin structures, regulatory burdens, and infrastructure requirements that shape competitive positioning.
Service Type:
Volume concentrates in synchronous consultation, yet premium economics are migrating toward continuous care models.
- Real-Time Consultation:Synchronous video and audio clinical encounters delivered through encrypted platforms with sub-150 millisecond latency requirements. Demand clusters in metropolitan corridors connecting Bangkok, Ho Chi Minh City, and Singapore where specialist scarcity justifies premium pricing.
- Remote Monitoring:Continuous physiological tracking via connected devices for chronic disease management. Malaysia and Vietnam are pulling this segment into mainstream reimbursement as diabetes and cardiovascular burdens deepen, creating the steepest expansion trajectory across service types.
- Mobile Health Applications:Patient-facing software for appointment scheduling, medication adherence, and wellness tracking. Indonesian secondary cities drive adoption through pharmacy-integrated platforms.
- Teletherapy:Mental health counseling delivered via video, audio, or asynchronous messaging. Employer-sponsored contracts in Thailand and Singapore represent the primary revenue channel.
Today's leader: Real-Time Consultation. Tomorrow's challenger: Remote Monitoring.
Delivery Model:
Customer type determines contract structure, with annual subscriptions yielding superior unit economics against per-transaction models.
- Direct-to-Consumer:Individual patient payments for on-demand consultations. Transaction volume remains highest here, though margin compression intensifies as platforms compete for metropolitan user acquisition.
- B2B Partnerships:Contracts with insurance companies and corporate wellness programs. Bangkok and Singapore metropolitan zones concentrate purchasing power through annual subscription structures that lock in predictable revenue.
- Health System Integration:Embedded platform infrastructure within hospital networks. Rural Indonesian and Philippine hospital systems source specialty access through these arrangements rather than building physical departments.
- Free-Standing Clinics:Dedicated telehealth facilities with on-site diagnostic equipment. Thailand's Medical Hub policy enables foreign-registered providers to serve medical tourists through this model without domestic legal entities.
Margin pools are rotating from individual transactions toward institutional contracts with embedded renewal mechanisms.
Technology:
Infrastructure maturity varies sharply across modalities, with latency-sensitive applications requiring fiber density that rural provinces often lack.
- Video Conferencing:Real-time visual consultation with strict bandwidth and latency requirements. Metropolitan corridors justify specialist platform investments here, while Indonesian and Philippine rural provinces face connectivity constraints.
- Messaging Platforms:Asynchronous text-based consultation and care coordination. Pharmacy-integrated Indonesian platforms leverage this for hyperlocal service delivery with lower infrastructure demands.
- Wearable Devices:Connected sensors for continuous physiological monitoring. Malaysian corporate wellness mandates create captive demand pools for chronic disease applications.
- AI Diagnostics:Machine learning-assisted symptom assessment and specialist routing. Vietnamese hospital networks deploy these at scale to manage queue overflow without specialist density.
Platform architecture is pivoting toward embedded health system infrastructure rather than standalone applications.
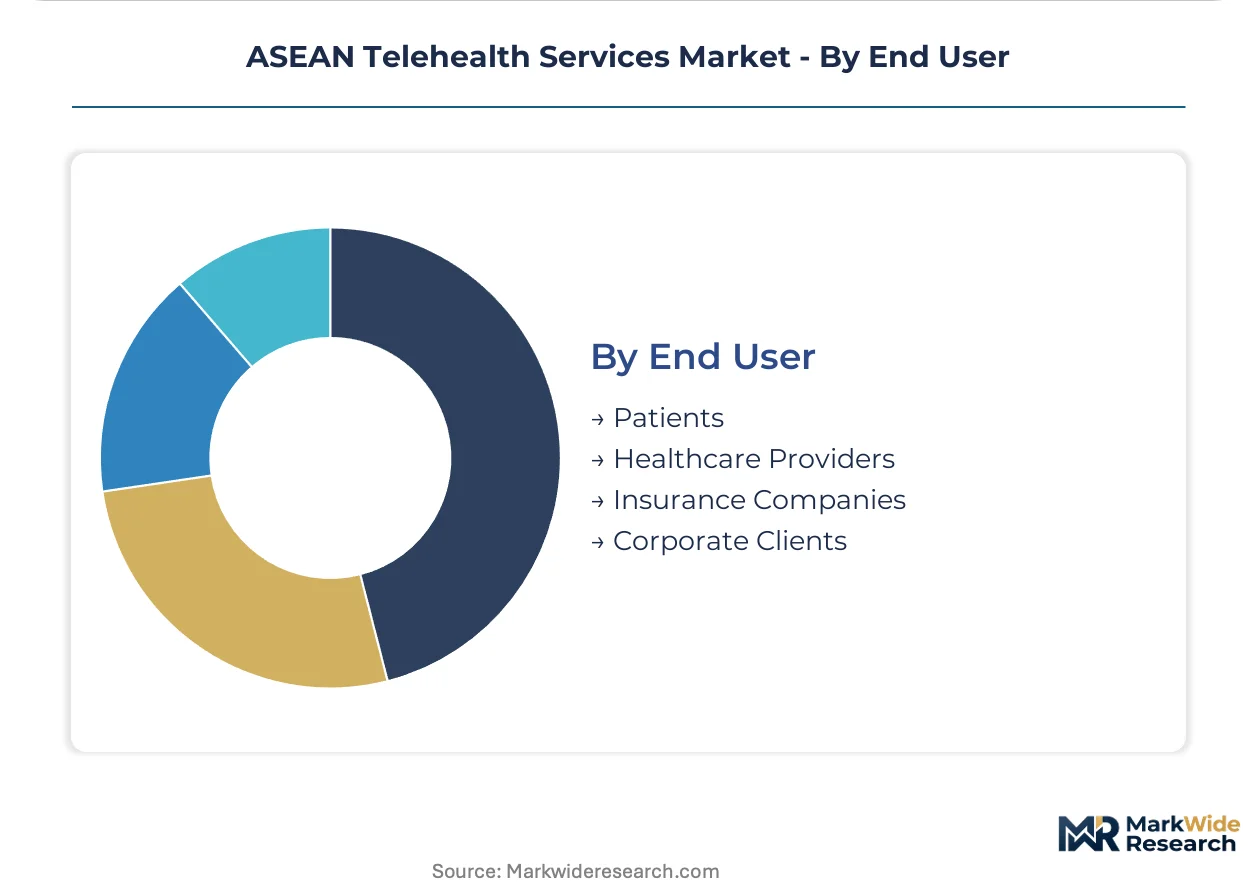
End User:
Purchasing sophistication varies dramatically, with institutional buyers consolidating volume against fragmented individual demand.
- Patients:Individual consumers seeking convenient access to care. Price sensitivity dominates this segment, with platforms competing on consultation fees and pharmacy integration.
- Healthcare Providers:Hospitals and clinics extending specialist reach into underserved provinces. Indonesian rural networks represent the most concentrated demand for platform-based specialty access.
- Insurance Companies:Payers integrating telehealth into benefit structures. Annual subscription negotiations in Singapore and Bangkok concentrate margin pools through volume commitments.
- Corporate Clients:Employers sponsoring wellness programs and occupational health services. Thailand's corporate wellness expansion and Singapore's employer mandates drive contract growth.
B2B channels are capturing margin concentration as institutional buyers consolidate purchasing power against fragmented consumer markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Bangkok-Ho Chi Minh City-Singapore metropolitan corridor anchors transaction volume concentration for ASEAN telehealth services. Platform investments cluster where specialist scarcity intersects with corporate purchasing power and fiber infrastructure density.
Singapore
Health Sciences Authority telemedicine guidelines create exportable compliance templates that reduce registration friction for platforms expanding into neighboring markets. The regulator's framework positions Singapore-based providers to serve cross-border patients under streamlined authorization pathways. Marina Bay and the One-North tech corridor concentrate regional headquarters functions for Doctor Anywhere and MyDoc.
Thailand
Medical Hub policy generates streamlined licensing for foreign-registered telehealth providers serving medical tourists without domestic legal entities. The Ministry of Public Health coordinates with tourism authorities to authorize cosmetic and orthopedic consultation platforms. Bangkok metropolitan zone contracts concentrate employer-sponsored wellness program demand from corporate clients.
Indonesia
Rural hospital networks in Java and Sulawesi source remote specialty consultations through platforms rather than building physical departments. Ministry of Health regulations on telemedicine licensing remain fragmented across provincial jurisdictions. Secondary cities Surabaya and Bandung drive pharmacy-integrated platform adoption through hyperlocal service delivery.
Vietnam
Ministry of Health circular on remote consultation standards creates regulatory clarity positioning Vietnam as potential early mover for regional clinical governance consolidation. Chronic disease monitoring pulls continuous physiological tracking into mainstream reimbursement schemes. Ho Chi Minh City anchors demand concentration connecting to Singapore and Bangkok corridor flows.
Philippines
Rural provinces lack fiber backbone density to consistently meet sub-150 millisecond video triage requirements for latency-sensitive applications. Department of Health telemedicine guidelines remain incomplete on cross-border prescription authority. Metro Manila concentrates platform transaction volume while Visayas and Mindanao rely on asynchronous messaging platforms.
ASEAN Telehealth Services Market Competitive Landscape
Established platforms occupy the standard tier; emerging entrants pursue AI-assisted diagnostic layers and embedded health system infrastructure. The vendor base separates into three maturity tiers: Singapore-anchored regional specialists, Indonesia-focused hyperlocal integrators, and Vietnam-Thailand corridor consolidators. Two strategic archetypes dominate competitive positioning: hub-and-spoke regional expanders and pharmacy-integrated national champions. Capacity expansion and B2B annual subscription contract capture represent the dominant competitive moves across the landscape.
Within the Singapore-based regional specialist tier, Doctor Anywhere and MyDoc exemplify hub-and-spoke expansion models leveraging regulatory exportability into neighboring markets. Among Indonesia-focused hyperlocal integrators, Halodoc occupies a position exemplifying pharmacy-embedded service delivery in secondary cities. These three companies represent distinct archetype anchors: regional compliance exporters, national pharmacy integrators, and metropolitan corridor consolidators. Platform differentiation increasingly concentrates on latency-sensitive video infrastructure and AI-assisted triage capabilities rather than standalone consultation access.
| Leading Market Players |
|---|
| Doctor Anywhere |
| Halodoc |
| Alodokter |
| SeeYouDoc |
| Viettel |
| Good Doctor Technology |
| Doc2Us |
| DoctorOnCall |
| MyDoc |
| Others |
Pricing and Supply Chain Analysis
Venture capital-rolled platforms with Singapore-domiciled headquarters impose pricing discipline through subscription lock-in while sourcing clinical governance talent across fragmented ASEAN regulatory jurisdictions. Their supply chain spreads fiber infrastructure deployment and physician credentialing across national markets, with procurement costs rising where latency requirements force redundant infrastructure.
Pricing Analysis
Input-cost pass-through from fiber backbone investments and dual-jurisdiction physician licensing flows into subscription tiering. Three-tier pricing structure across premium specialist access, standard primary care, and economy asynchronous messaging separates enterprise contracts from individual transactions. Cost compression in the direct-to-consumer tier intensifies because Halodoc and Alodokter compete on pharmacy integration subsidies. Employer-sponsored channels show least price sensitivity due to annual renewal mechanisms.
Supply Chain Analysis
Logistics and freight costs for connected medical devices concentrate supply chain vulnerability in Malaysian and Vietnamese distribution hubs serving chronic disease monitoring deployments. Hardware sourcing draws from China, South Korea, and Taiwan for wearable sensors and diagnostic peripherals. Single-source vulnerability sits with cloud infrastructure providers hosting encrypted video triage platforms. Distribution runs through hospital procurement committees in Jakarta and Manila alongside direct platform-to-patient channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ASEAN telehealth has entered late-cycle quality phase as corporate wellness mandates in Bangkok and Singapore shift procurement toward premium AI-assisted diagnostic specifications. Platforms must now defend margin pools through embedded health system integration rather than user acquisition scale.
For Market Incumbents: Anticipate margin compression from AI-native entrants by deepening clinical governance talent pools in Vietnam's regulatory clarity zone. Anchor fiber infrastructure investments in Ho Chi Minh City-Bangkok corridor nodes to defend latency advantages. Consolidate physician credentialing through Vietnam's early-mover regulatory framework before competing jurisdictions harmonize standards.
For New Entrants and Emerging Players: Begin with employer-sponsored teletherapy contracts in Thailand's corporate wellness expansion as the most penetrable white-space segment. Target secondary Indonesian cities for pharmacy-embedded asynchronous messaging where Halodoc's hyperlocal density remains incomplete. Pursue health system integration partnerships with rural Philippine hospital networks lacking specialty departments.
For Investors and Strategic Acquirers: Valuations sit cheapest among Indonesia-focused hyperlocal integrators with pharmacy density but limited B2B subscription penetration. Long-term viability hinges on regulatory exportability from Singapore or Vietnam hubs into fragmented ASEAN markets. Watch for which national regulator first harmonizes prescription authority across jurisdictions as the signal for clinical governance consolidation winners.
| Strategic Initiative | Industry Significance |
|---|---|
| AI Diagnostic Layer Integration | Vietnamese hospital networks deploy machine learning triage to manage specialist queue overflow without physician density. |
| Cross-Border Regulatory Harmonization | Thailand's Medical Hub policy enables Singapore platforms to serve medical tourists without domestic legal entities. |
| Corporate Wellness Contract Capture | Malaysia's employer mandates create captive demand pools for chronic disease management subscriptions. |
| Fiber Infrastructure Densification | Sub-150 millisecond latency requirements force redundant metropolitan corridor investments connecting Bangkok to Ho Chi Minh City. |
| Physician Credentialing Consolidation | Incomplete ASEAN Mutual Recognition Arrangements force duplication costs that Vietnam's regulatory clarity could resolve. |
Research Methodology
Coverage spans Southeast Asian metropolitan corridors and secondary cities, with primary inputs from each national market. The research combines interviews with telehealth platform executives, hospital procurement managers, and Health Sciences Authority regulatory leads with secondary validation from Ministry of Health circulars and corporate wellness contract disclosures. Sources include ASEAN telemedicine licensing databases, fiber infrastructure deployment filings, and employer-sponsored benefits audits. Bottom-up transaction modeling and top-down regulatory scenario analysis triangulate market sizing.
Granularity extends to service type, delivery model, technology infrastructure, and end-user purchasing behavior across the projection horizon. The analytical framework models real-time consultation, remote monitoring, mobile health applications, and teletherapy segments separately with distinct latency and reimbursement assumptions. CAGRs derive from physician supply constraints, chronic disease prevalence trajectories, and fiber penetration curves. Forecast inputs incorporate Health Sciences Authority guideline adoption rates and Vietnam Ministry of Health circular implementation timelines.
Several conditions sit outside the modeled scope, including unilateral prescription authority harmonization decisions and sovereign cloud infrastructure mandates. Forecasts reflect assumptions about regulatory exportability and corporate wellness mandate expansion. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telemedicine
Global Tele Intensive Care Unit Market
Telemedicine
Global Virtual Care Market
Telemedicine
Telestroke Services Market
Telemedicine
Global Telehealth Market
Telemedicine
Global Healthcare Virtual Assistants Market
Telemedicine
Remote Healthcare Market
Telemedicine
Global Online Therapy Services Market
Telemedicine
Europe Telemedicine Market
Telemedicine
Europe Telehealth Service Market
Telemedicine
Telehealth Software Market
Telemedicine
Telehealth Services Market
Telemedicine
India Telehealth Services Market
Telemedicine
Global Telemedicine Market
Telemedicine
In-Flight Telemedicine System Market
Telemedicine
North America Telemedicine Market
Telemedicine
Stroke Telemedicine Services Market