
 Global Vacuum Mixing Devices Market | 2026-2036
Global Vacuum Mixing Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Vacuum Mixing Devices Market Foresight
Hospital procurement consortiums is reconfiguring how vacuum mixing devices reach end users, with group purchasing organizations now dictating technical specifications and service terms. Stryker leverages its orthopedic implant ecosystem to bundle cement mixing systems with joint replacement kits. Zimmer Biomet sustains a parallel direct-sales model for high-volume orthopedic centers that require dedicated field support. Heraeus Holding anchors the dental segment through specialized distribution partnerships with European laboratory networks.
Vacuum mixing devices employ sealed chambers with sub-atmospheric pressure conditions to eliminate air entrapment during polymer, ceramic, or pharmaceutical paste preparation, typically operating between 0.05 and 0.8 bar absolute pressure to achieve homogeneous, void-free mixtures essential for structural integrity and dosing accuracy. High-speed vacuum mixers dominate orthopedic cement preparation where rapid polymerization windows demand aggressive deaeration cycles, while portable vacuum mixers are expanding fastest among mobile dental service units and field-based pharmaceutical quality labs. Digital control systems command premium positioning through programmable pressure profiles and data logging capabilities that satisfy FDA 21 CFR Part 11 traceability requirements.
FDA 510(k) premarket notification and EU MDR Class IIa classification shape device validation burdens, with the former demanding substantial equivalence demonstrations and the latter requiring updated clinical evidence and post-market surveillance systems. ISO 13485 quality management certification functions as a baseline market access credential for suppliers targeting regulated healthcare economies. Stakeholders must monitor evolving software-as-a-medical-device interpretations that could reclassify digitally controlled vacuum mixers under stricter cybersecurity and algorithm validation frameworks.
Market Dynamics
Orthopedic cement preparation protocols are standardizing around vacuum-assisted deaeration as joint replacement volumes climb and revision surgery rates intensify scrutiny over implant fixation quality. This procedural shift concentrates purchasing authority within hospital value analysis committees and group purchasing organizations.
Growth Catalysts
- FDA 510(k) pathway alignment:Substantial equivalence demonstrations for digital control systems are accelerating clearance timelines for next-generation vacuum mixers with integrated pressure logging.
- Dental laboratory expansion:Ceramic and composite material preparation in Germany, Japan, and Brazil is driving precision equipment procurement as aesthetic dentistry protocols tighten.
- EU MDR Class IIa classification:Updated clinical evidence requirements are filtering out marginal suppliers and consolidating procurement around validated manufacturers with robust post-market surveillance.
Market Restraints
- Stainless steel and medical-grade polymer input costs:Volatility in specialty material pricing compresses margin buffers for device manufacturers operating on fixed hospital contract terms.
- Validation burden concentration:FDA 21 CFR Part 11 compliance for software-as-a-medical-device interpretations demands cybersecurity infrastructure that favors established players with dedicated regulatory affairs functions.
- Manual mixing persistence:Cost-sensitive ambulatory surgical centers in emerging markets continue using non-vacuum methods for low-complexity procedures, capping addressable volume.
Strategic Opportunities
- Mobile dental service units:Portable vacuum mixer demand is expanding fastest among field-based quality labs serving rural populations in Brazil and India.
- Pharmaceutical paste preparation:API suspension homogeneity requirements are opening vacuum mixing applications in sterile manufacturing environments.
- ISO 13485 certification arbitrage:Suppliers achieving quality management credentials gain preferential access to regulated healthcare economies while competitors face exclusion.
Industry Challenges
- Biomedical engineering talent scarcity:Cross-functional expertise combining pneumatic systems, polymer chemistry, and regulatory documentation commands premium compensation and extends hiring cycles.
- Legacy device integration:Retrofitting digital control modules onto installed vacuum mixing bases requires hardware compatibility layers that delay upgrade revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Vacuum Mixing Devices Market |
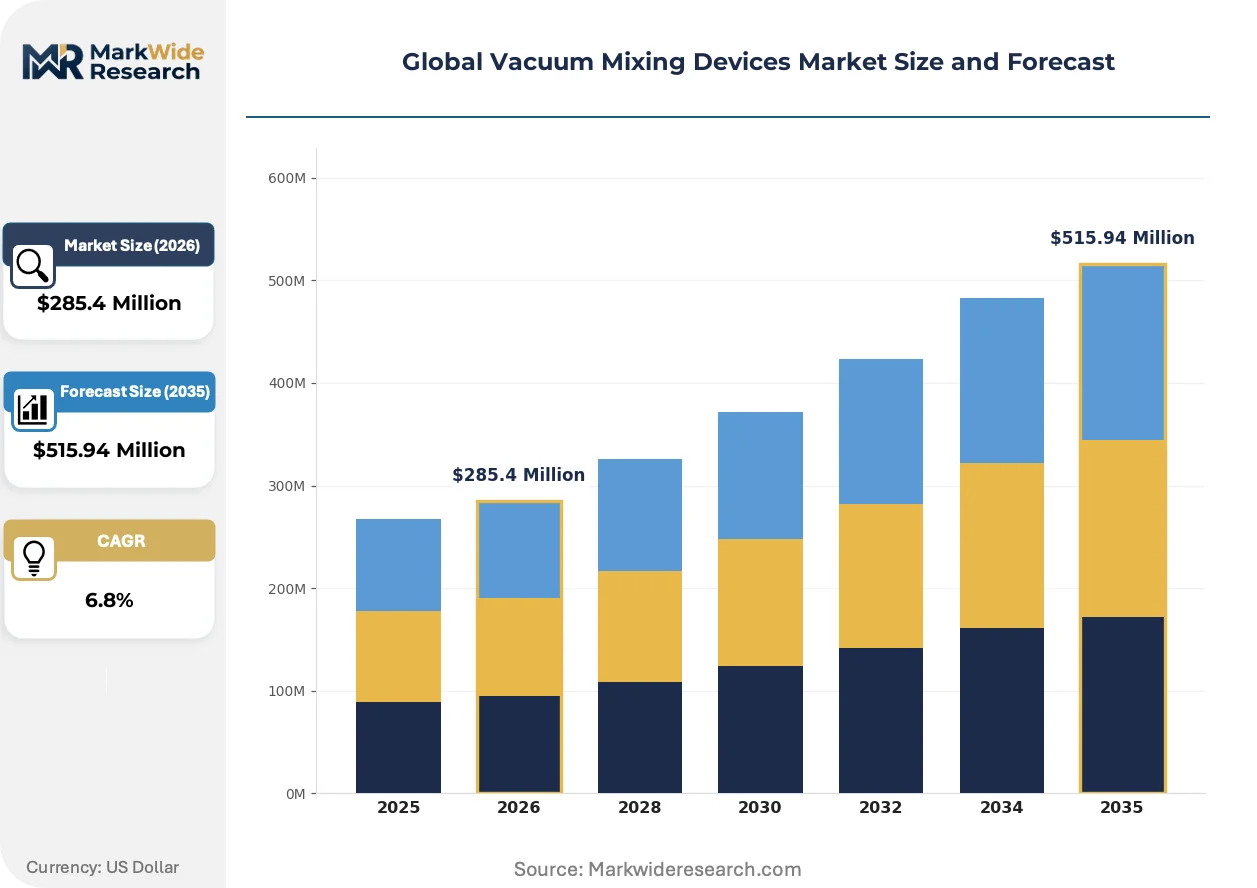
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $515.94 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Speed Vacuum Mixers, Low-Speed Vacuum Mixers, Dual Vacuum Mixers, Portable Vacuum Mixers, Bench-Top Vacuum Mixers Technology: Electromechanical, Pneumatic, Hydraulic, Digital Control Systems, Manual Assistance Application: Laboratory Testing, Dental Material Preparation, Pharmaceutical Production, Chemical Formulation, Food Processing End User: Research Laboratories, Dental Clinics, Pharmaceutical Manufacturers, Chemical Plants, Food Processing Units |
| Companies Covered | Stryker, Zimmer Biomet, Heraeus Holding, DJO Global, Summit Medical, OSARTIS GmbH, SIRIO DENTAL S.R.L., DENTALFARM SRL, Eurocem Srl, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Vacuum Mixing Devices Market Shifts & Advancements
Programmable pressure profiles and data traceability are redefining competitive differentiation as buyers prioritize audit-ready documentation over standalone mechanical performance. This shift elevates software architecture to parity with vacuum chamber engineering in vendor selection criteria.
Closed-loop pressure control is hybridizing conventional vacuum mixing with real-time sensor feedback, enabling adaptive deaeration cycles that adjust to material viscosity changes mid-process. High-volume orthopedic centers in the United States are piloting these systems to reduce cement preparation variability. The technology is compressing acceptable tolerance bands for void content and forcing recalibration of quality assurance protocols.
EU MDR post-market surveillance requirements are mandating systematic clinical follow-up data collection for Class IIa devices, extending validation obligations beyond initial clearance. Manufacturers must now maintain active implant registries or equivalent real-world evidence systems. Dental and orthopedic segments are responding by embedding unique device identifiers and automated batch logging into vacuum mixer firmware.
After-sales service unbundling is fragmenting traditional capital equipment contracts as buyers separate hardware procurement from maintenance and calibration agreements. Group purchasing organizations in Germany and the United States are driving this disaggregation to optimize lifetime cost models. Independent service organizations are capturing calibration revenue streams previously captive to original equipment manufacturers.
Global Vacuum Mixing Devices Market Segmentation
Vacuum mixing device procurement patterns diverge sharply across product configurations and end-use environments. Cycle time variability between high-throughput orthopedic cement preparation and intermittent dental laboratory workflows creates distinct replacement rhythms and service contract structures.
Product Type:
High-speed vacuum mixers turn over fastest in orthopedic settings where cement polymerization windows compress maintenance intervals, while bench-top units in research laboratories operate on decade-long depreciation schedules.
- High-Speed Vacuum Mixers:These systems operate at rotational speeds exceeding 1,500 RPM with aggressive deaeration cycles timed to bone cement working windows. Demand concentrates in United States orthopedic centers where joint replacement volumes strain preparation throughput.
- Portable Vacuum Mixers:Battery-powered units weighing under 8 kilograms enable field-based dental services and mobile pharmaceutical quality labs. Brazil's rural dental outreach programs and India's tier-2 city pharmaceutical inspectors drive procurement.
- Low-Speed Vacuum Mixers:Gentle agitation preserves shear-sensitive polymer structures in adhesive and coating formulations.
- Dual Vacuum Mixers:Parallel chamber configurations allow simultaneous preparation of contrasting material viscosities.
- Bench-Top Vacuum Mixers:Compact footprints suit academic research settings with intermittent usage patterns.
High-speed vacuum mixers anchor the volume base while portable vacuum mixers gain share at the steepest rate.
Technology:
Cost tier stratification separates electromechanical workhorses from digitally controlled premium systems, with pneumatic and hydraulic alternatives occupying mid-market niches defined by facility infrastructure constraints.
- Digital Control Systems:Programmable pressure profiles with integrated data logging satisfy FDA 21 CFR Part 11 traceability mandates. United States hospital value analysis committees prioritize these capabilities for orthopedic cement batch documentation.
- Electromechanical:Proven motor-driven vacuum pumps dominate installed bases where capital replacement cycles extend 7-10 years.
- Pneumatic:Compressed air systems eliminate electrical spark risks in solvent-heavy chemical formulation environments.
- Hydraulic:High-torque drive mechanisms handle extremely viscous pharmaceutical pastes and ceramic slurries.
- Manual Assistance:Hand-operated vacuum pumps persist in cost-constrained emerging market dental clinics.
Digital control systems command premium positioning while manual assistance configurations contract fastest as regulatory documentation requirements tighten.
Application:
Application-specific validation burdens create divergent margin profiles, with pharmaceutical production demanding sterile-grade documentation and food processing emphasizing cleanability certifications.
- Dental Material Preparation:Ceramic and composite mixing for crown, bridge, and veneer fabrication requires precise void elimination to prevent aesthetic defects. Germany's dental laboratory networks and Japan's aesthetic dentistry clinics prioritize equipment with sub-0.1% porosity guarantees.
- Pharmaceutical Production:API suspension homogeneity and sterile manufacturing compliance dominate specification sheets. FDA validation protocols and EU GMP Annex 1 requirements filter supplier pools to ISO 13485-certified manufacturers.
- Laboratory Testing:Research-grade flexibility with interchangeable vessel sizes suits materials science exploration.
- Chemical Formulation:Solvent-resistant seals and explosion-proof ratings address specialty coating and adhesive production.
- Food Processing:Hygienic design with CIP/SIP compatibility supports sauce, dough, and confectionery aeration control.
Dental material preparation anchors the volume base while pharmaceutical production applications expand most quickly as sterile manufacturing standards proliferate.
End User:
Customer type determines procurement authority concentration, with pharmaceutical manufacturers centralizing capital decisions and dental clinics fragmenting across individual practice purchases.
- Pharmaceutical Manufacturers:Integrated sterile manufacturing lines require vacuum mixing systems with validated cleaning protocols and batch record integration. United States and Germany facilities lead replacement cycles as legacy equipment reaches end-of-validated-life.
- Dental Clinics:Chairside and laboratory-adjacent preparation demands compact footprints with rapid cycle times. Brazil's expanding private dental networks and India's corporate clinic chains drive volume.
- Research Laboratories:University and government materials science facilities prioritize configurability over throughput.
- Chemical Plants:Industrial-scale production emphasizes durability and integration with continuous processing lines.
- Food Processing Units:Bakery and confectionery operations focus on aeration consistency and allergen segregation capabilities.
Pharmaceutical manufacturers anchor the volume base while dental clinics gain share at the steepest rate as private practice networks expand in emerging economies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container throughput connects German dental laboratory equipment exporters to Asian manufacturing hubs, while the Trans-Siberian Railway's cargo corridors link European vacuum mixing device suppliers with Chinese pharmaceutical production clusters.
United States
Joint replacement volume growth at Cleveland Clinic and Mayo Clinic campuses drives high-speed vacuum mixer procurement for orthopedic cement preparation. FDA 510(k) premarket notification requirements filter supplier pools to manufacturers with validated digital control systems. The Minneapolis-St. Paul medical device corridor concentrates production engineering talent for next-generation pressure logging integration.
Germany
Dental laboratory networks in Cologne and Stuttgart expand precision equipment procurement for ceramic crown fabrication. EU MDR Class IIa classification mandates updated clinical evidence and post-market surveillance systems for device manufacturers. The Rhine-Ruhr industrial belt hosts specialized distribution partnerships connecting vacuum mixer producers with European laboratory networks.
China
Domestic pharmaceutical manufacturers in Shanghai and Suzhou upgrade sterile production lines with vacuum-assisted API suspension systems. NMPA medical device registration requirements align with international quality management standards for imported equipment. The Yangtze River Delta medical technology cluster attracts joint ventures between local distributors and European device specialists.
Japan
Aesthetic dentistry clinics in Tokyo and Osaka prioritize sub-0.1% porosity guarantees for ceramic and composite material preparation. PMDA quality management inspections enforce documentation standards for imported dental equipment. The Nagoya medical device manufacturing zone supplies precision vacuum chamber components to domestic and export markets.
Brazil
Rural dental outreach programs in Minas Gerais and São Paulo states drive portable vacuum mixer demand for mobile service units. ANVISA medical device registration pathways standardize import documentation for European and North American suppliers. The Campinas medical technology corridor distributes field-based quality lab equipment to tier-2 city pharmaceutical inspectors.
Global Vacuum Mixing Devices Market Competitive Landscape
On the supply side, the industry is tiered between multinational orthopedic implant ecosystems and specialized dental equipment fabricators. Consolidated procurement authority within hospital value analysis committees and group purchasing organizations favors suppliers with bundled service capabilities. Two strategic archetypes dominate: implant manufacturers extending into cement preparation systems, and dedicated mixing equipment specialists serving laboratory networks. Competitive moves concentrate on strategic partnerships with distribution networks and portfolio diversification into portable configurations for emerging market access.
Among diversified orthopedic technology conglomerates, Stryker and Zimmer Biomet occupy positions where implant ecosystem integration anchors cement mixing system placement. Within the specialized dental segment, Heraeus Holding exemplifies the European laboratory network specialist archetype through its distribution-focused model. These three companies represent distinct competitive vectors: bundled orthopedic kits, direct high-volume center sales, and precision laboratory partnerships.
| Leading Market Players |
|---|
| Stryker |
| Zimmer Biomet |
| Heraeus Holding |
| DJO Global |
| Summit Medical |
| OSARTIS GmbH |
| SIRIO DENTAL S.R.L. |
| DENTALFARM SRL |
| Eurocem Srl |
| Others |
Supply & Pricing Matrix
Stainless steel and medical-grade polymer suppliers in Germany and Japan concentrate upstream input pricing power, anchoring margin pools with original equipment manufacturers who bundle digital control systems with orthopedic cement preparation hardware.
Pricing Analysis
Volume-discount tiering structures separate high-speed vacuum mixer procurement for United States orthopedic centers from portable unit purchases by Brazilian mobile dental services. Pricing stratifies across premium digital control tiers, ISO 13485-certified configurations, and manual-assistance economy levels. Cost compression in electromechanical segments intensifies as hospital group purchasing organizations consolidate contract negotiations. Ambulatory surgical centers in emerging markets exhibit highest price sensitivity, while pharmaceutical manufacturers prioritize FDA 21 CFR Part 11 traceability over unit cost.
Supply Chain Analysis
Extended payment terms from supply-chain finance facilities in the United States and Germany stabilize working capital for vacuum chamber fabricators serving hospital procurement consortiums. Component sourcing draws from precision machining clusters in Switzerland, medical-grade polymer extruders in the United States, and pneumatic system specialists in Japan. Single-source vulnerability concentrates in high-torque drive mechanisms for pharmaceutical paste applications. Distribution runs through specialized dental laboratory networks in Europe and orthopedic implant bundling agreements in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across mobile dental service units, field-based pharmaceutical quality labs, and tier-2 city outreach programs creates niche entry points as procurement authority decentralizes from centralized hospital value analysis committees.
For Market Incumbents: Insulate installed base revenue by embedding unique device identifiers and automated batch logging into vacuum mixer firmware ahead of EU MDR post-market surveillance mandates. Deepen backward integration into precision vacuum chamber component production to offset specialty material cost volatility from German and Japanese suppliers.
For New Entrants and Emerging Players: Portable vacuum mixer demand among rural dental outreach programs in Brazil and mobile pharmaceutical quality labs in India represents the most penetrable entry point. Target ISO 13485 certification arbitrage to bypass exclusion from regulated healthcare economies. Partner with independent service organizations capturing calibration revenue streams from disaggregated after-sales contracts.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with European laboratory network specialists holding distribution-focused models in Germany and dental equipment fabricators serving Japan's aesthetic dentistry clinics. Five-to-ten year viability hinges on software-as-a-medical-device reclassification risk for digitally controlled vacuum mixers. Monitor FDA cybersecurity guidance evolution for vacuum mixing device software validation as the inflection indicator for regulatory capital requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission for Digital Control Systems | Accelerates clearance timelines for next-generation vacuum mixers with integrated pressure logging capabilities. |
| CE Marking Pathway under EU MDR Class IIa | Filters supplier pools to validated manufacturers with robust post-market surveillance systems in European markets. |
| Hospital System Partnership for Bundled Procurement | Stryker and Zimmer Biomet leverage orthopedic implant ecosystems to anchor cement mixing system placement. |
| Software Companion Development for Data Traceability | Satisfies FDA 21 CFR Part 11 requirements that elevate software architecture to parity with vacuum chamber engineering. |
| Reimbursement Strategy for Revision Surgery Protocols | Aligns vacuum-assisted deaeration adoption with joint replacement volume growth at Cleveland Clinic and Mayo Clinic campuses. |
Research Methodology
Desk research of FDA 510(k) premarket notification databases, EU MDR technical documentation requirements, and orthopedic cement preparation protocol literature preceded structured interviews with hospital value analysis committee members, biomedical engineers, GPO contracts managers, and dental laboratory equipment procurement leads. Secondary validation drew from ISO 13485 certification registries, hospital procurement databases, and customs records for vacuum mixing device trade flows. Bottom-up demand modeling across product configurations triangulated with top-down market sizing from equipment manufacturer revenue disclosures.
Assumptions held joint replacement volume growth trajectories and EU MDR implementation timelines fixed across the analysis window, while pharmaceutical sterile manufacturing upgrade cycles and mobile dental service expansion rates varied by scenario. Segmentation dimensions spanned product type, control technology, application environment, and end-user procurement authority concentration. CAGRs derived from equipment replacement cycle analysis and penetration rate modeling for portable configurations. Forecast inputs incorporated cement polymerization window constraints and FDA software-as-a-medical-device interpretation evolution.
Practitioners should monitor stainless steel and medical-grade polymer input cost volatility, FDA cybersecurity guidance for medical device software, and EU MDR post-market surveillance enforcement intensity for early signals. Forecasts reflect these documented assumptions; macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Brain Mapping Instruments Market
Medical Equipment
Global Operating Table Mattresses Market
Medical Equipment
Global Countertop Platelet Incubator Market
Medical Equipment
Orthopedic Operating Tables Market
Medical Equipment
Medical Gas Cylinders Market
Medical Equipment
Global Portable Beds Market
Medical Equipment
Hemodialysis Equipment Market
Medical Equipment
PCR Plate Sealer Market
Medical Equipment
Global Medical Device Reprocessing Market
Medical Equipment
Global Cardiopulmonary Stress Testing Systems Market
Medical Equipment
Global Medical Vacuum System Market
Medical Equipment
Electron Beam Linear Accelerators Market
Medical Equipment
Medical X-Ray Generators Market
Medical Equipment
Europe Medical Device Reprocessing Market
Medical Equipment
Tissue Processing Systems Market
Medical Equipment
Global Intraoperative Radiation Therapy Market