
 Global Emergency Medical Equipment Market | 2026-2036
Global Emergency Medical Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Emergency Medical Equipment Market Foresight
ISO 13485 certification is reorganizing competitive dynamics for manufacturers seeking market access across major economies. Medtronic leverages its integrated supply chain to maintain defibrillator leadership across North American and European channels. Philips Healthcare differentiates through advanced monitoring platforms designed for mobile emergency deployment. Stryker Corporation anchors its position in resuscitation devices via sustained R&D investment in automated CPR technologies.
Emergency medical equipment encompasses life-support and diagnostic apparatus engineered for immediate intervention outside traditional clinical settings, typically incorporating battery-powered operation, ruggedized housing meeting IP ratings, and wireless telemetry for hospital handoff. Diagnostic devices and monitoring equipment command premium positioning due to software-integrated analytics and real-time data streaming capabilities. Ventilators represent the fastest-expanding product category as health systems prioritize respiratory readiness following pandemic-era supply vulnerabilities.
The FDA governs premarket notification pathways for emergency devices under 510(k) and PMA frameworks, while the EU MDR enforces stricter clinical evidence requirements and post-market surveillance obligations for CE-marked emergency equipment. Japan's PMDA maintains distinct quality management system inspections that create additional compliance layers for manufacturers targeting Asian hospital procurement channels. Stakeholders must weigh regulatory divergence against platform standardization when allocating product development resources across jurisdictions.
Market Dynamics
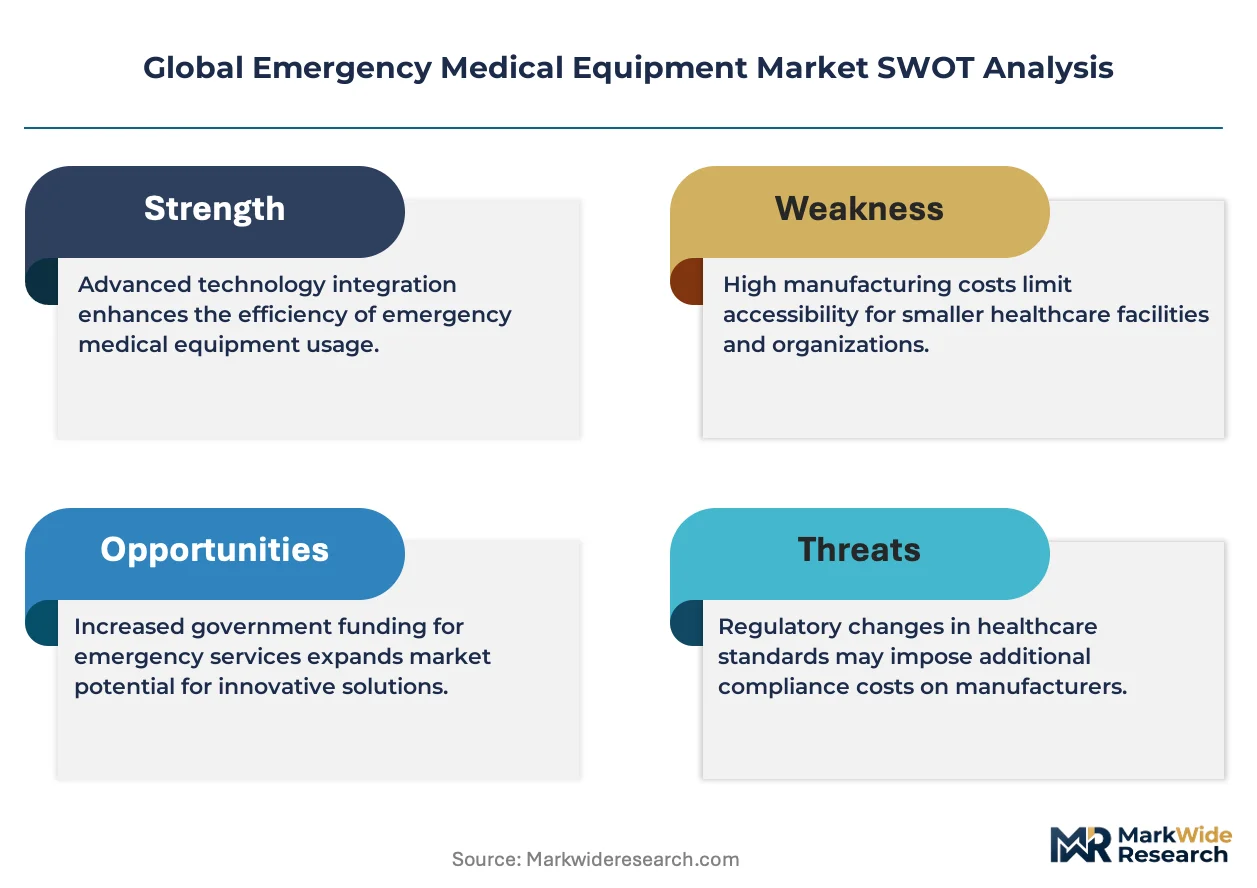
Pre-hospital care infrastructure modernization is compressing procurement cycles for portable life-support systems as health systems prioritize respiratory readiness and seamless hospital handoff capabilities. Ambulance fleets are replacing legacy equipment with ruggedized, telemetry-integrated platforms that meet stricter conformity requirements.
Growth Catalysts
- EU MDR compliance mandates:Stricter clinical evidence requirements for CE-marked emergency devices are filtering out marginal suppliers and consolidating procurement toward certified manufacturers with established quality management systems.
- Japan PMDA inspections:Additional compliance layers for Asian hospital procurement channels are accelerating investment in dual-certified production facilities serving both Japanese and export markets.
- Ventilator category expansion:Health system respiratory readiness programs are driving sustained demand for portable ventilation platforms with battery redundancy and wireless monitoring integration.
Market Restraints
- Semiconductor input volatility:Microcontroller and sensor chip supply concentration in East Asian foundries creates production scheduling uncertainty for device manufacturers with lean inventory policies.
- FDA PMA pathway duration:Premarket approval timelines for novel resuscitation technologies extend commercialization cycles, compressing effective patent protection windows for breakthrough devices.
- Disposable consumable substitution:Single-use circuit components and electrode pads face pricing pressure from third-party reprocessors, eroding OEM recurring revenue streams.
Strategic Opportunities
- German pre-hospital modernization:Federal state ambulance fleet renewal programs are creating concentrated demand for defibrillator-monitor combinations with integrated telemedicine connectivity.
- ISO 13485 platform standardization:Unified quality certification across jurisdictions enables manufacturers to amortize compliance costs across multiple regulatory markets simultaneously.
- AI-enhanced diagnostic convergence:Machine learning algorithms embedded in portable ECG and capnography devices are enabling real-time decision support for paramedic crews with limited physician oversight.
Industry Challenges
- Biomedical engineering talent scarcity:Specialized expertise in battery management systems and RF telemetry for medical-grade devices commands premium compensation, constraining R&D team scaling.
- Legacy EMS system integration:Municipal ambulance services operate heterogeneous device fleets with incompatible data protocols, complicating unified fleet management and training standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Emergency Medical Equipment Market |
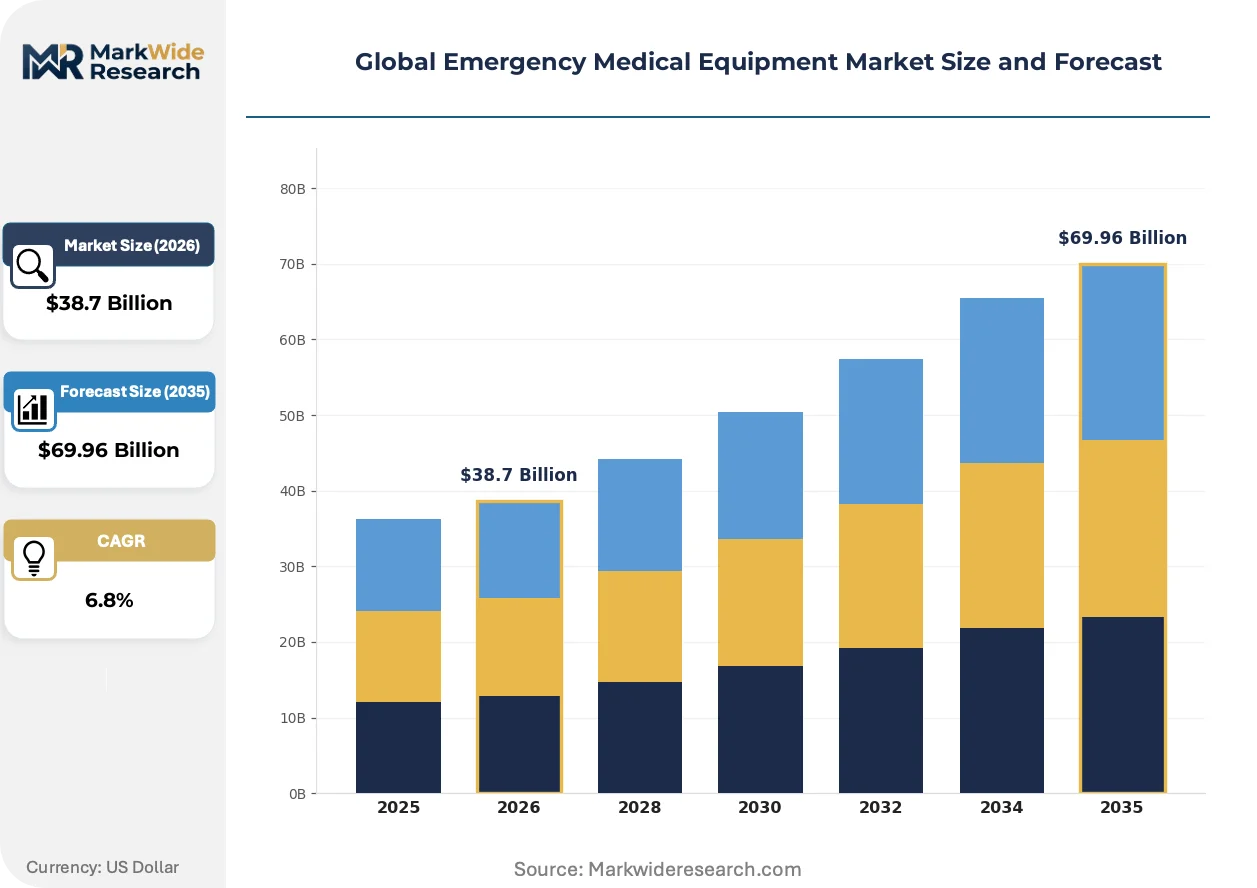
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
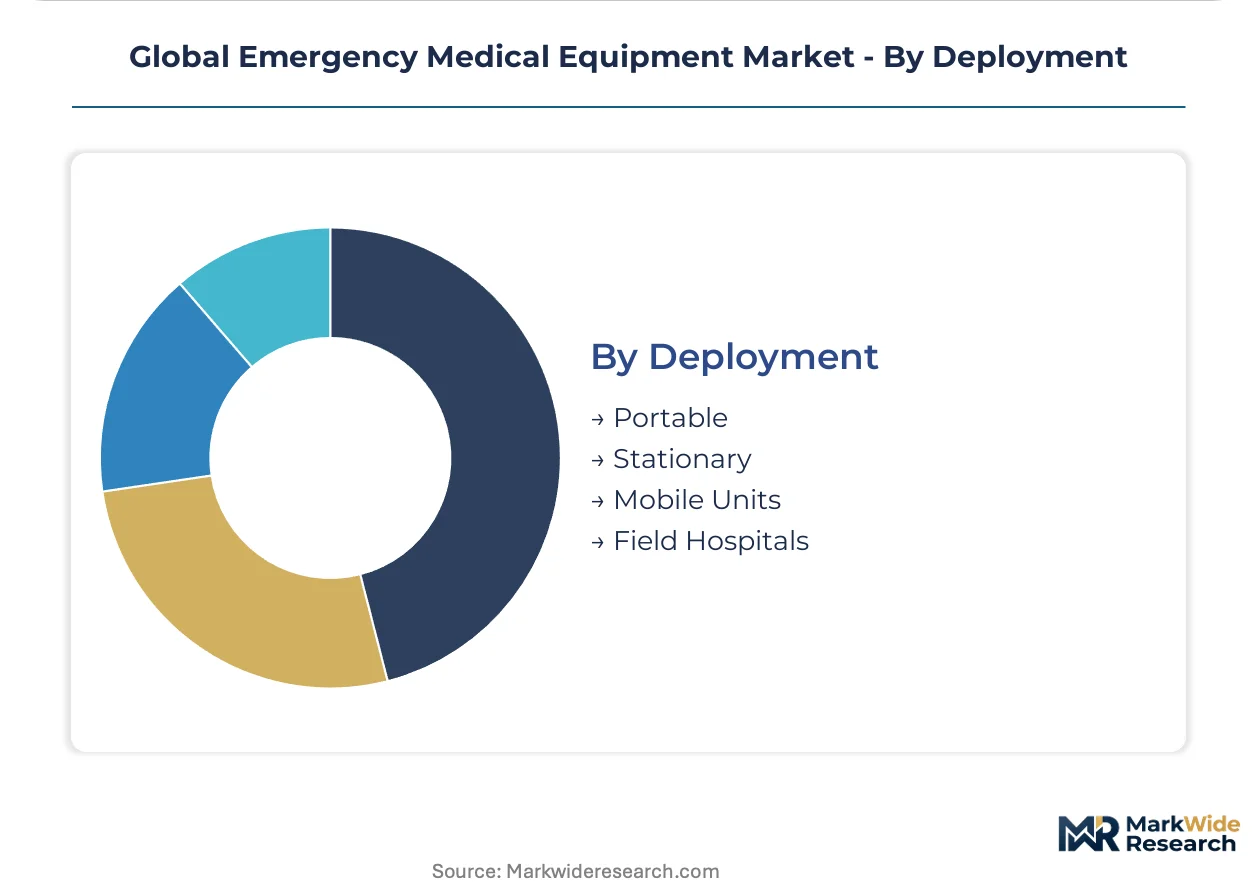
| Segmentation | Product Type: Defibrillators, Ventilators, Diagnostic Devices, Monitoring Equipment, Resuscitation Devices Application: Trauma Care, Cardiac Emergencies, Respiratory Support, Accident Response End User: Ambulance Services, Urgent Care Centers, Fire & Rescue Services, Military Medical Units Deployment: Portable, Stationary, Mobile Units, Field Hospitals |
| Companies Covered | Medtronic, GE Healthcare, Philips Healthcare, Stryker Corporation, Cardinal Health, 3M Company, Abbott Laboratories, Siemens Healthineers, Becton, Dickinson and Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Emergency Medical Equipment Market Shifts & Advancements
Software-defined functionality is displacing dedicated hardware modules across emergency device categories, enabling firmware-upgradable platforms that extend product lifecycles. Manufacturers are embedding predictive maintenance algorithms and remote diagnostic capabilities into core product architectures.
Modular patient monitoring architecture is decomposing traditional standalone devices into interoperable sensor hubs and display tablets. Air ambulance services and critical care transport teams are adopting these reconfigurable systems to reduce aircraft payload and simplify equipment sterilization protocols. This decomposition is compressing average selling prices for dedicated monitors while expanding attach rates for disposable sensors.
The EU MDR post-market surveillance obligations are mandating systematic clinical follow-up for CE-marked emergency equipment with higher risk classifications. Manufacturers must now maintain active vigilance systems capturing real-world performance data across distributed installed bases. Defibrillator and ventilator product lines face the steepest compliance cost increases as notified bodies expand audit scope for software validation and cybersecurity documentation.
Subscription-based service models are displacing outright equipment purchases among private ambulance operators and hospital-based EMS divisions. Predictable monthly fees covering device maintenance, consumable replenishment, and software updates align vendor incentives with uptime performance. This shift is most pronounced in United States municipal contracting, where capital budget constraints favor operational expenditure structures with guaranteed response time commitments.
Global Emergency Medical Equipment Market Segmentation
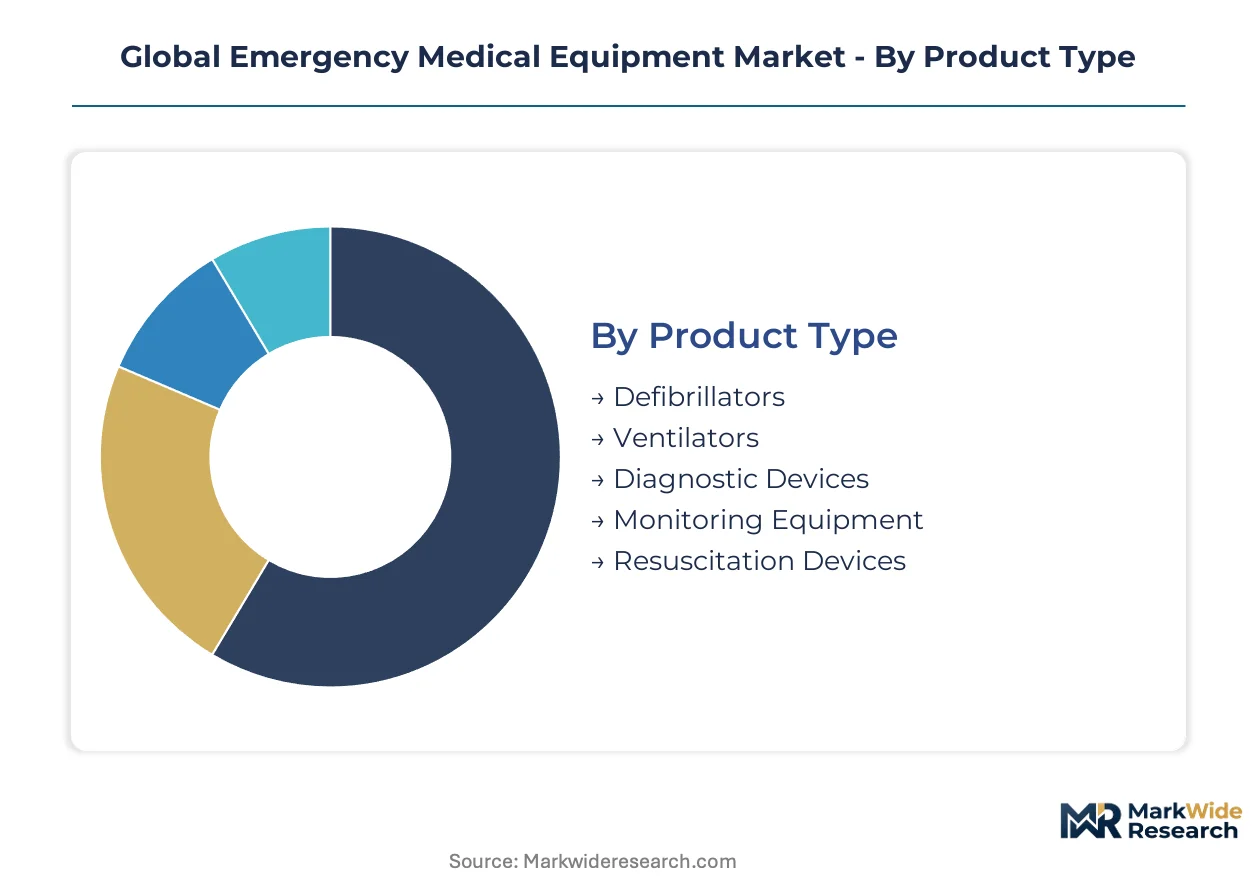
Regulatory frameworks fragment emergency medical equipment procurement across jurisdictions, creating distinct certification requirements that reshape how manufacturers configure product portfolios. ISO 13485 alignment and FDA PMA pathways force strategic choices about which segments warrant dedicated development investment versus platform standardization.
Product Type:
FDA 510(k) clearance timelines and EU MDR clinical evidence obligations concentrate competitive advantage among manufacturers with established quality management systems spanning multiple jurisdictions.
- Defibrillators:Automated external defibrillators incorporate biphasic waveform technology and voice-guided CPR coaching algorithms. Demand concentrates in German ambulance fleet modernization programs and United States municipal EMS contracting, where telemedicine connectivity mandates drive replacement cycles.
- Ventilators:Portable ventilation platforms integrate turbine-driven pneumatic systems with battery redundancy architectures for critical care transport. Health system respiratory readiness programs in Japan and the United States sustain procurement momentum following pandemic-era supply vulnerabilities.
- Diagnostic Devices:Portable ECG, ultrasound, and capnography units with embedded AI decision support.
- Monitoring Equipment:Multi-parameter patient monitors with wireless telemetry for hospital handoff.
- Resuscitation Devices:Automated CPR systems and airway management tools for mechanical chest compression.
Established volume favors defibrillators; emerging adoption favors ventilators.
Application:
Cost tier differentiation separates premium telemetry-integrated systems from basic life-support configurations across municipal, private, and military procurement channels.
- Trauma Care:Hemorrhage control devices, pelvic binders, and portable imaging for field stabilization. United States combat casualty care doctrine and NATO medical evacuation standards drive interoperability requirements.
- Cardiac Emergencies:Time-critical intervention systems including defibrillation, antiarrhythmic drug delivery, and 12-lead ECG transmission. Japanese fire department medical divisions and German emergency physician response vehicles anchor demand concentration.
- Respiratory Support:Emergency airway management and ventilation for acute respiratory failure.
- Accident Response:Extrication-compatible monitoring and trauma stabilization for vehicle collisions.
Trauma care commands premium pricing; cardiac emergencies drive highest unit velocity.
End User:
Customer type determines service model preference, with private operators favoring subscription structures and public agencies constrained by capital budget cycles.
- Ambulance Services:Ground and air medical transport fleets requiring ruggedized, telemetry-integrated platforms. United States municipal contracting shifts toward outcome-based service agreements with guaranteed response uptime.
- Urgent Care Centers:Fixed-site emergency departments with stationary diagnostic and monitoring infrastructure. Japanese hospital-based EMS divisions prioritize ISO 13485-certified devices with PMDA quality management system documentation.
- Fire & Rescue Services:First responder agencies with cross-trained personnel deploying basic life-support equipment.
- Military Medical Units:Deployable field hospitals and tactical combat casualty care systems.
Ambulance services dominate procurement volume; military medical units drive specifications for extreme environment durability.
Deployment:
Supply concentration in East Asian battery and sensor manufacturing shapes regional production strategies for portable versus stationary configurations.
- Portable:Battery-powered devices under 15 kilograms for single-responder carry. German emergency physician vehicles and United States critical care transport teams specify IP67-rated housings with 8-hour battery autonomy.
- Stationary:Fixed-installation equipment for emergency department resuscitation bays and urgent care procedure rooms. Japanese hospital procurement channels demand JIS-standard electrical safety compliance alongside PMDA device registration.
- Mobile Units:Vehicle-integrated systems with power conditioning and shock-mounted hardware.
- Field Hospitals:Deployable infrastructure for disaster response and military operations.
Portable configurations gain share fastest; stationary installations anchor replacement revenue stability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal ambulance fleet renewal programs in Germany are accelerating procurement of defibrillator-monitor combinations with telemedicine connectivity. Japan's PMDA quality management system inspections create additional compliance layers that favor dual-certified manufacturers. United States municipal EMS contracting shifts toward outcome-based service agreements with guaranteed response uptime commitments.
United States
Municipal EMS divisions are replacing legacy equipment with telemetry-integrated platforms under outcome-based service contracts. The FDA governs premarket notification pathways for emergency devices under 510(k) and PMA frameworks. Greater Boston anchors demand concentration for portable ventilation platforms with battery redundancy architectures.
Germany
Federal state ambulance fleet renewal programs are driving concentrated demand for defibrillator-monitor combinations. The EU Medical Device Regulation enforces stricter clinical evidence requirements and post-market surveillance obligations for CE-marked emergency equipment. Bavaria's emergency physician response vehicles specify IP67-rated housings with 8-hour battery autonomy.
Japan
Hospital-based EMS divisions prioritize ISO 13485-certified devices for respiratory readiness programs. The PMDA maintains distinct quality management system inspections that create additional compliance layers for Asian hospital procurement channels. Kanto region fire department medical divisions anchor demand for 12-lead ECG transmission systems.
United Kingdom
NHS ambulance trusts are modernizing pre-hospital care infrastructure with ruggedized, wireless-enabled monitoring platforms. The MHRA enforces UKCA marking requirements alongside continued CE recognition during transitional periods. London's air ambulance services adopt modular patient monitoring architecture to reduce aircraft payload.
India
Private ambulance operators are expanding fleets with basic life-support configurations for tier-2 city coverage. The CDSCO regulates medical device imports through registration and import license requirements. Maharashtra's municipal corporations are piloting subscription-based service models for device maintenance and consumable replenishment.
Global Emergency Medical Equipment Market Competitive Landscape
Player mix skews toward diversified medical technology conglomerates with established quality management systems spanning multiple jurisdictions. Market structure concentrates around manufacturers with integrated supply chains and dual-certified production facilities. Three archetypes dominate: integrated device conglomerates, specialized resuscitation technology developers, and diversified healthcare suppliers with emergency portfolios. Competitive moves center on M&A for telemetry capabilities and strategic partnerships for AI-enhanced diagnostic convergence.
Within the integrated device tier, Medtronic and Philips Healthcare exemplify manufacturers leveraging platform standardization across regulatory markets. Stryker Corporation occupies a position among specialized resuscitation technology developers with sustained investment in automated mechanical systems. These three entities represent the competitive anchor points against which mid-cap specialists and regional fabricators position their certification and pricing strategies.
| Leading Market Players |
|---|
| Medtronic |
| GE Healthcare |
| Philips Healthcare |
| Stryker Corporation |
| Cardinal Health |
| 3M Company |
| Abbott Laboratories |
| Siemens Healthineers |
| Becton, Dickinson and Company |
| Others |
Supply & Pricing Matrix
Outcome-based service contracts with guaranteed response uptime lock in multi-year supply commitments for telemetry-integrated platforms, giving certified manufacturers price visibility while binding ambulance operators to predictable operational expenditure structures across United States municipal markets and German federal state fleets.
Pricing Analysis
Certification level creates the primary spread between ISO 13485-certified premium tiers and basic utility-grade alternatives. Three-tier pricing structure across premium, standard, and economy levels separates FDA PMA-approved devices from 510(k)-cleared equivalents and unregistered gray-market imports. Cost compression in consumable electrodes and single-use circuits intensifies as third-party reprocessors capture aftermarket share. Private ambulance operators in India demonstrate highest price sensitivity, while Japanese hospital-based EMS divisions absorb premiums for PMDA-documented quality management systems.
Supply Chain Analysis
Inventory buffers for microcontroller and sensor chips stretch to six-month horizons as East Asian foundry concentration creates scheduling uncertainty for battery management systems and RF telemetry modules. Component sourcing draws from Taiwan, South Korea, and Japan for semiconductors, with battery cell production anchored in China and South Korea. Single-source vulnerability in advanced pulse oximetry sensors threatens production continuity for multi-parameter monitors. Distribution runs through authorized medical device distributors with field service capabilities, bypassing general industrial channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software subscription layers for predictive maintenance and remote diagnostics expand faster than hardware replacement cycles, transforming capital equipment vendors into recurring-revenue service providers with attached consumable replenishment contracts.
For Market Incumbents: Compound defensible positioning through backward integration into battery management system design and captive production of IP67-rated housings. Third-party reprocessors threaten electrode pad revenue streams; defend through embedded encryption that disables non-OEM consumables. Prioritize dual-certified production facilities serving both EU MDR and Japan PMDA channels to amortize compliance investment across regulatory markets. For New Entrants and Emerging Players: Aftermarket service coverage gaps in tier-2 Indian cities create entry points for subscription-based maintenance models with guaranteed uptime commitments. Target Maharashtra municipal pilot programs with basic life-support configurations priced below telemetry-integrated premiums. Partner with regional distributors possessing biomedical engineering field teams rather than building direct service infrastructure. For Investors and Strategic Acquirers: Specialized resuscitation technology developers with automated CPR patent portfolios and established ISO 13485 quality systems represent acquisition targets with regulatory moats. Long-term viability hinges on software-defined functionality roadmaps that extend hardware replacement cycles through firmware upgrades. Watch for EU MDR notified body audit scope expansion as an inflection indicator for compliance cost concentration among scaled manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR clinical evidence requirements filter marginal suppliers toward consolidated procurement. |
| Hospital System Partnership | Outcome-based contracts with guaranteed response uptime align vendor incentives with device performance. |
| Software Companion Development | AI-enhanced ECG decision support differentiates portable monitors for paramedic crews with limited physician oversight. |
| Reimbursement Strategy | Coding alignment for telemedicine-connected devices accelerates replacement cycles in United States municipal EMS. |
| Backward Integration | In-house battery management system production insulates against East Asian semiconductor foundry concentration. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across ambulance service procurement managers, biomedical engineering directors, GPO contracts managers, and regulatory affairs leads at device manufacturers. Secondary validation drew from FDA 510(k) and PMA filings, EU MDR notified body audit records, Japanese PMDA quality system inspection reports, and hospital procurement databases. Bottom-up installed base estimates triangulated against top-down health system expenditure tracking across the analysis window.
Across the projection horizon, analytical frameworks modeled volume and value trajectories by product type, application severity tier, end-user contracting structure, and deployment portability class. CAGRs derived from regression against pre-hospital care infrastructure investment cycles and regulatory compliance cost escalations. Forecast inputs incorporated ambulance fleet renewal schedules in Germany, respiratory readiness program budgets in Japan, and municipal EMS contracting shifts toward operational expenditure structures in the United States.
Forecasts assume regulatory continuity in FDA premarket notification frameworks, EU MDR post-market surveillance obligations, and Japan PMDA quality management system inspections; material policy shifts would require re-modeling. Semiconductor supply volatility and disposable consumable substitution rates represent specific risk factors that could revise trajectory assumptions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
North America Durable Medical Equipment Market
Medical Equipment
Operating Light Market
Medical Equipment
Cryogenic Freezers Market
Medical Equipment
Brazil Massage Equipment Market
Medical Equipment
Urodynamic Equipment Market
Medical Equipment
Global Mortuary Equipment Market
Medical Equipment
Sterilization Equipment Market
Medical Equipment
Durable Medical Equipment Market
Medical Equipment
Operating Table Market
Medical Equipment
Cryochambers Market
Medical Equipment
Asia-Pacific Medical Device Reprocessing Market
Medical Equipment
Chile Radiotherapy Market
Medical Equipment
Global Surgical Lights Market
Medical Equipment
Global Single-Arm Medical Pendant Market
Medical Equipment
Next Generation Centrifuge Market
Medical Equipment
Single-Coated Medical Tape Market