
 Global Hemodialysis Market | 2026-2036
Global Hemodialysis Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hemodialysis Market Analysis
Modularization of dialysis consumables into procedure-ready kits is repositioning how procurement teams evaluate total cost of ownership in the Global Hemodialysis Market. Fresenius Medical Care leverages backward integration into dialyzer membrane production to control input quality and margin structure. Baxter International anchors its competitive stance through peritoneal-to-hemodialysis crossover platforms that sustain hospital system loyalty. DaVita dominates the service layer, operating one of the largest networks of outpatient dialysis centers across multiple continents.
Hemodialysis is a renal replacement therapy that extracts metabolic waste products, excess fluid, and electrolytes from blood by circulating it through an extracorporeal circuit with a semipermeable dialyzer membrane, typically requiring blood flow rates of 200–500 mL/min and dialysate temperatures maintained at 36–37°C to prevent hemodynamic instability. The procedure serves patients with end-stage renal disease who have lost sufficient native kidney function to sustain life without mechanical intervention. Among product types, dialyzers command the deepest margin pools due to polymer science differentiation and repeat purchase frequency. Home care is the fastest-growing end-user channel as payors and patients push for alternatives to facility-based treatment. Portable dialysis technology remains nascent but attracts disproportionate R&D allocation because of its potential to unlock geographic access in underserved regions.
The FDA governs hemodialysis device safety through 510(k) and PMA pathways that dictate clinical evidence requirements for new membrane materials and machine software. EMA's MDR framework in Europe is forcing manufacturers to rebuild technical documentation and post-market surveillance systems for CE-marked dialyzers and bloodlines. Japan's PMDA maintains stringent quality audits that limit market entry to suppliers with demonstrated manufacturing consistency. Stakeholders must monitor how reimbursement reform in major markets alters the economics of home versus in-center treatment models.
Market Dynamics
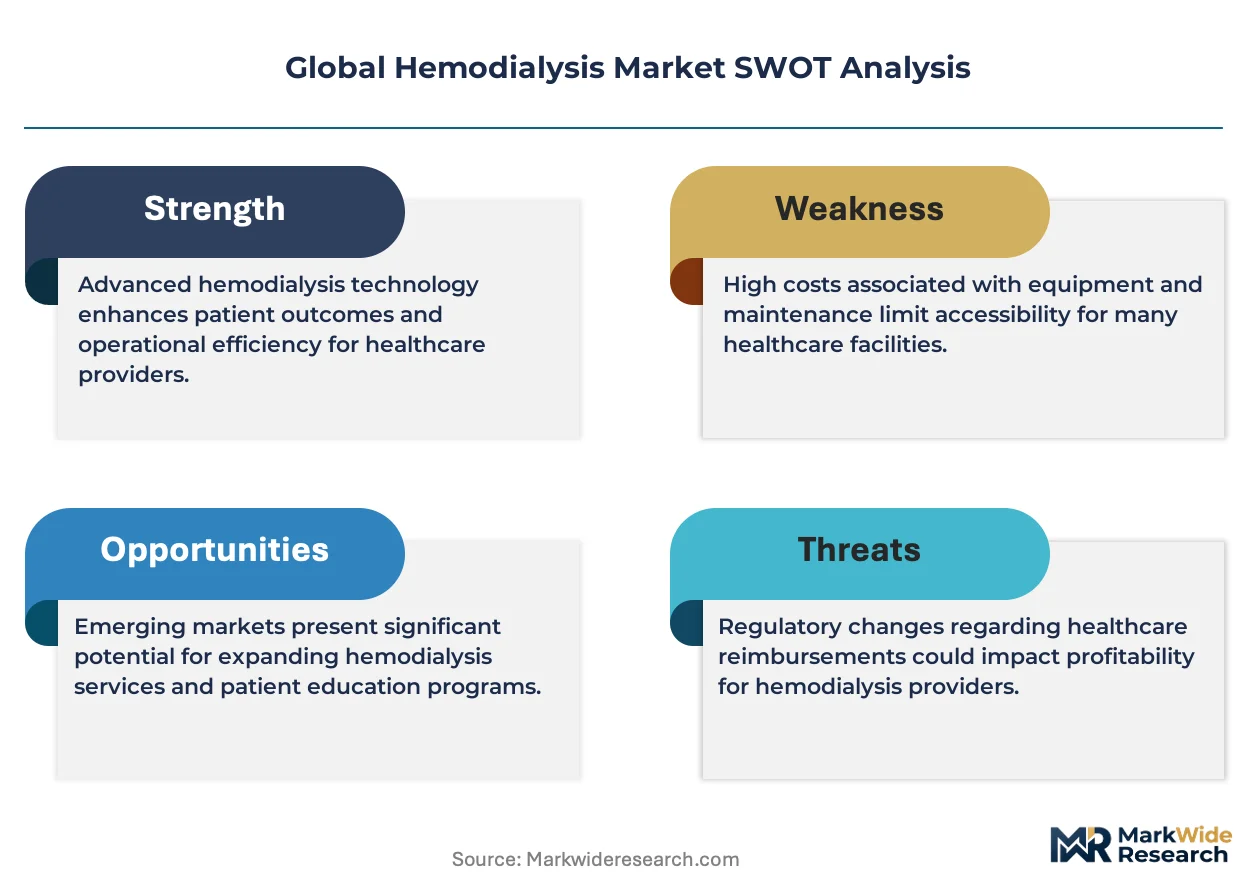
Home-based dialysis adoption is compressing the traditional facility-centered service model, forcing manufacturers to reengineer device portability and payors to recalibrate reimbursement structures around patient-managed care pathways.
Growth Catalysts
- Japan's PMDA quality audit framework:Stringent manufacturing consistency standards limit market entry to proven suppliers, creating competitive moats for established membrane producers and elevating quality benchmarks across the industry.
- Modular dialyzer kit formats:Procedure-ready consumable bundles reduce clinical setup time and inventory complexity, driving procurement preference among hospital systems seeking operational standardization.
- Germany's clinical service density:Concentrated manufacturing and treatment infrastructure around Fresenius Medical Care's operations generates knowledge spillovers and supplier clustering that accelerates product iteration cycles.
Market Restraints
- Polymer feedstock volatility:Specialized membrane polymers derive from petrochemical inputs whose price swings compress dialyzer margin structures unpredictably.
- FDA premarket pathway friction:Evolving 510(k) and PMA requirements for new membrane materials extend development timelines and elevate clinical evidence costs for device innovators.
- Peritoneal dialysis substitution:Baxter International's crossover platforms capture modality-switching patients, constraining hemodialysis volume growth in integrated health systems.
Strategic Opportunities
- Portable device white space:Miniaturized systems capable of operation without fixed infrastructure unlock geographic access in rural India and Southeast Asian markets lacking dialysis facility density.
- EMA MDR documentation services:Technical file reconstruction and post-market surveillance system rebuilding for CE-marked products creates service revenue streams adjacent to hardware sales.
- Home care channel expansion:Payor pressure for treatment flexibility in the United States and Western Europe is redirecting R&D investment toward patient-operable machine interfaces.
Industry Challenges
- Bioengineering talent scarcity:Specialized expertise in hemocompatible membrane surface modification commands premium compensation and constrains scale-up timelines for novel dialyzer programs.
- Legacy machine integration complexity:New consumable formats must maintain backward compatibility with installed base dialysis consoles, limiting design freedom and testing burden.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hemodialysis Market |
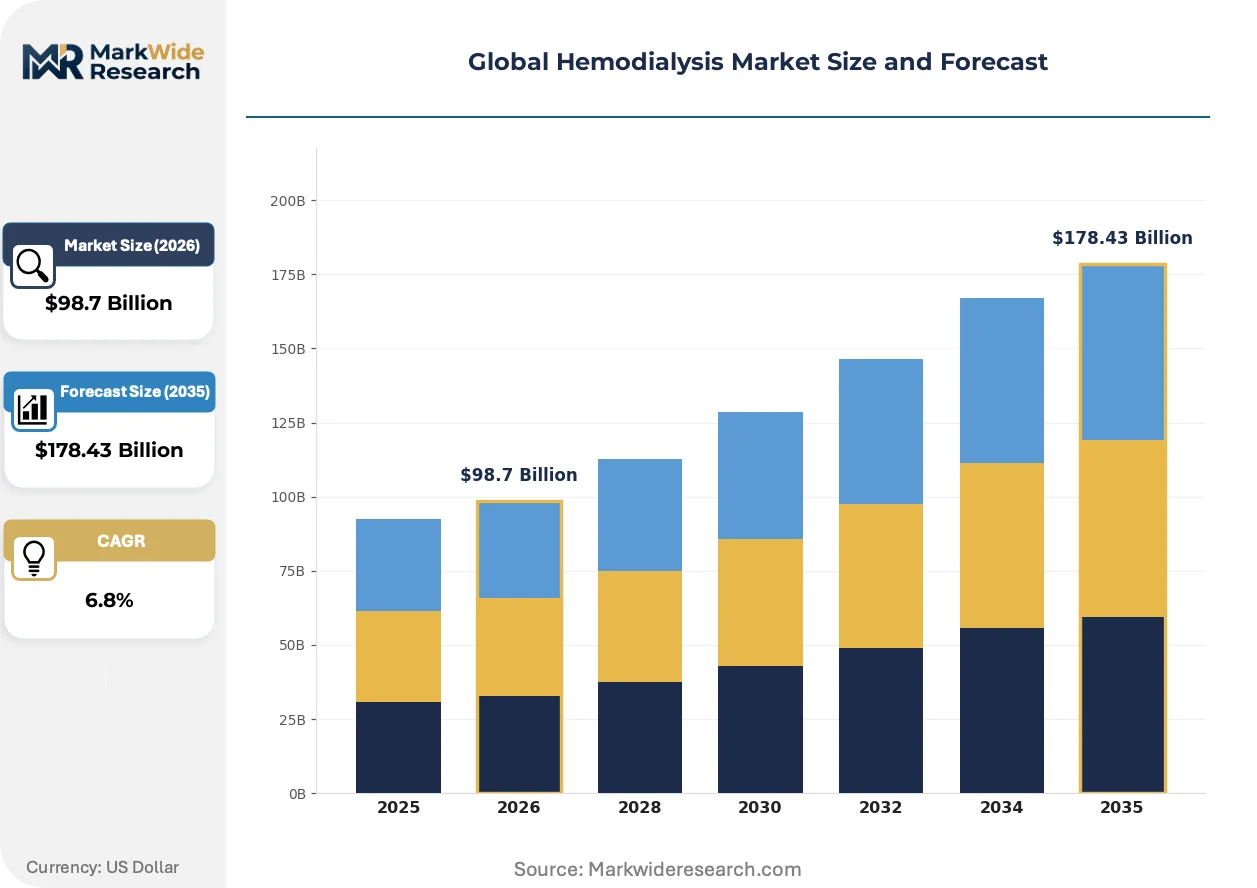
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $178.43 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hemodialysis Machines, Dialyzers, Blood Tubing, Catheters End User: Hospitals, Dialysis Centers, Home Care, Specialty Clinics Technology: Conventional Dialysis, Portable Dialysis, Online HDF, High-Flux Dialysis Application: Acute Kidney Injury, Chronic Kidney Disease, Uremia, Drug Overdose |
| Companies Covered | Fresenius Medical Care, Baxter International, DaVita, B. Braun Melsungen, Nipro Corporation, Nikkiso Co., Ltd., Asahi Kasei Medical, Medtronic, Becton, Dickinson and Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hemodialysis Market Emerging Trajectories
Device miniaturization and software-enabled remote monitoring are converging to enable patient-managed treatment outside clinical settings, fundamentally restructuring where care delivery occurs and who controls the therapeutic relationship.
High-flux synthetic membrane technology is consolidating clinical preference as polymer science advances enable superior middle-molecule clearance with reduced inflammatory response. Nephrology departments in tertiary hospitals are standardizing on these materials for routine care. The shift is compressing demand for cellulose-based alternatives and concentrating procurement volume among suppliers with captive polymer production capabilities.
Europe's MDR framework is forcing manufacturers to rebuild technical documentation and post-market surveillance systems for CE-marked dialyzers and bloodlines. The regulatory burden falls disproportionately on mid-tier suppliers lacking dedicated regulatory affairs infrastructure. German and Swiss manufacturers are responding by acquiring specialized compliance consultancies to accelerate certification timelines.
Hospital procurement teams are unbundling after-sales service contracts from equipment purchases, treating technical support as a separately negotiated spend category. This pattern disrupts traditional vendor lock-in strategies and compresses service margin pools. The United States exhibits the most advanced unbundling, with IDNs operating centralized biomedical engineering functions that reduce reliance on manufacturer field service.
Global Hemodialysis Market Segmentation
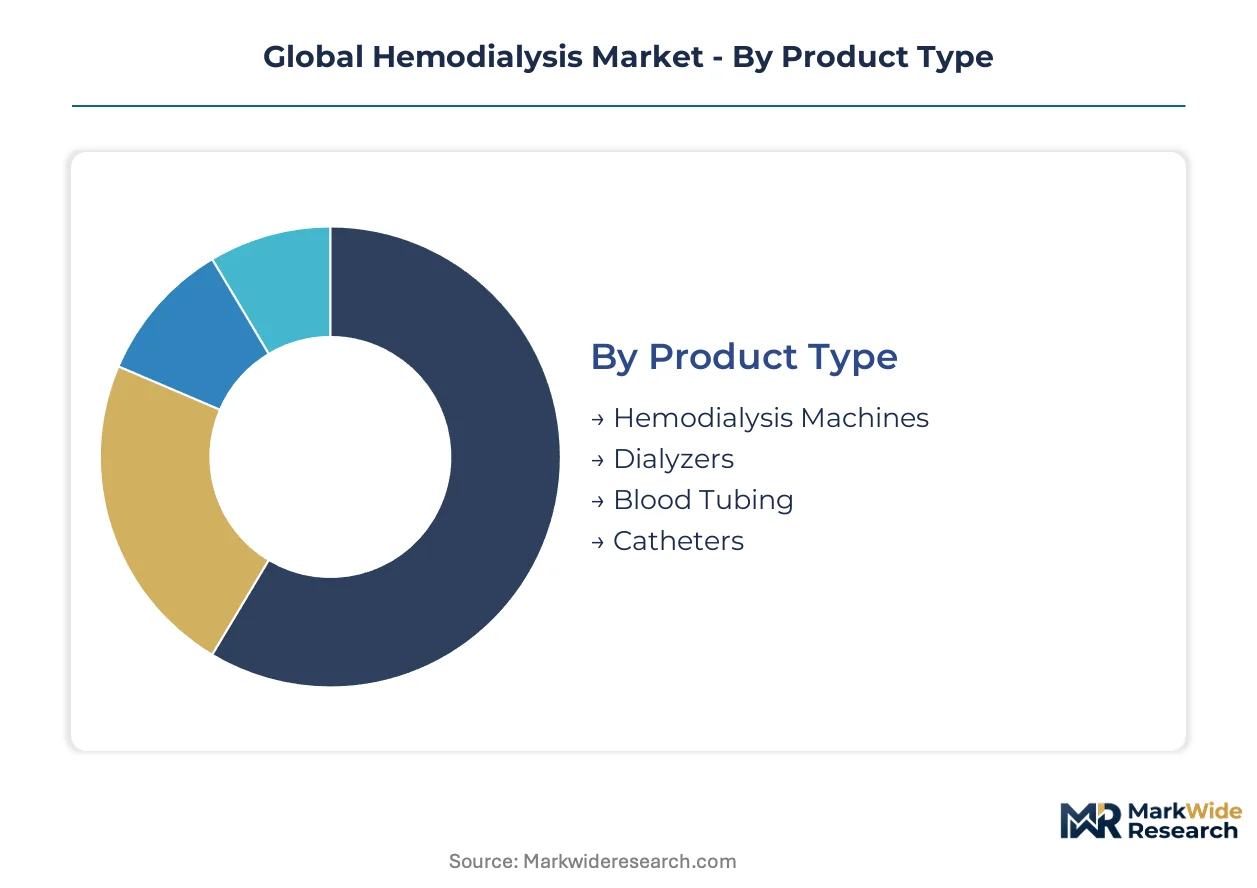
Hemodialysis market segmentation reveals divergent margin profiles across hardware, consumables, and service channels. Procurement patterns for capital equipment differ fundamentally from repeat-purchase consumable workflows, forcing suppliers to maintain dual commercial capabilities.
Product Type:
Volume concentrates in single-use consumables while premium pricing attaches to capital equipment with embedded software platforms.
- Dialyzers:Semi-permeable membrane cartridges manufactured from polysulfone or polyethersulfone polymers determine clearance efficiency and biocompatibility. German and Japanese hospital systems concentrate procurement volume here, driven by nephrology department demands for high-flux synthetic materials that reduce inflammatory response.
- Hemodialysis Machines:Console systems integrate blood pumps, dialysate delivery, and safety monitoring with software-controlled treatment protocols. Demand clusters in United States dialysis center networks seeking remote monitoring capabilities that reduce clinical staffing requirements per treatment station.
- Blood Tubing:Sterile PVC or silicone circuits transport blood between patient vascular access and dialyzer. FDA 510(k) pathway requirements govern material compliance for this high-volume repeat purchase category.
- Catheters:Vascular access devices including tunneled cuffed and non-tunneled variants serve patients without functional arteriovenous fistulas. Infection risk profiles drive material selection toward antimicrobial-coated configurations.
Today's leader: Dialyzers. Tomorrow's challenger: Hemodialysis Machines.
End User:
Customer type determines reimbursement pathway complexity and equipment specification requirements.
- Dialysis Centers:Outpatient facilities operate high-throughput treatment schedules with centralized technical support and bulk consumable procurement. Fresenius Medical Care and DaVita networks in the United States anchor volume concentration here, though facility saturation is redirecting capital toward home care alternatives.
- Home Care:Patient-operated or caregiver-assisted treatment outside clinical settings requires simplified machine interfaces and portable supply logistics. United States Medicare reimbursement reform and Western European payor pressure are accelerating channel expansion fastest.
- Hospitals:Acute inpatient settings demand flexible machines capable of intermittent hemodialysis and continuous renal replacement therapy modes. Tertiary centers in Germany and Japan concentrate procurement for complex multi-organ failure cases.
- Specialty Clinics:Nephrology-focused outpatient facilities offer personalized care models with lower patient-to-staff ratios than large dialysis organizations. Boutique operators in Switzerland and the United Arab Emirates pursue this positioning.
Channel concentration favors Dialysis Centers currently. Home Care exhibits the steepest expansion trajectory as payors recalibrate cost structures.
Technology:
Maturity curves separate established modalities from emerging platforms still seeking clinical evidence accumulation.
- High-Flux Dialysis:Synthetic membrane configurations with larger pore structures enable superior middle-molecule clearance compared to low-flux alternatives. Japanese PMDA quality audits and European nephrology guidelines are consolidating clinical preference around this modality.
- Portable Dialysis:Miniaturized systems designed for travel and non-clinical environments remain nascent but attract disproportionate R&D allocation. Rural India and Southeast Asian markets lacking facility infrastructure represent the primary geographic opportunity.
- Conventional Dialysis:Standard low-flux cellulose or synthetic membrane treatment remains prevalent in cost-constrained markets and legacy equipment installations. Backward compatibility requirements sustain this category despite clinical migration toward high-flux alternatives.
- Online HDF:Hemodiafiltration combines diffusive and convective clearance through high-volume ultrafiltration with sterile substitution fluid. European adoption leads United States penetration due to divergent reimbursement recognition of clinical benefits.
Clinical standardization favors High-Flux Dialysis. Portable Dialysis holds the highest uncaptured value potential pending miniaturization breakthroughs.
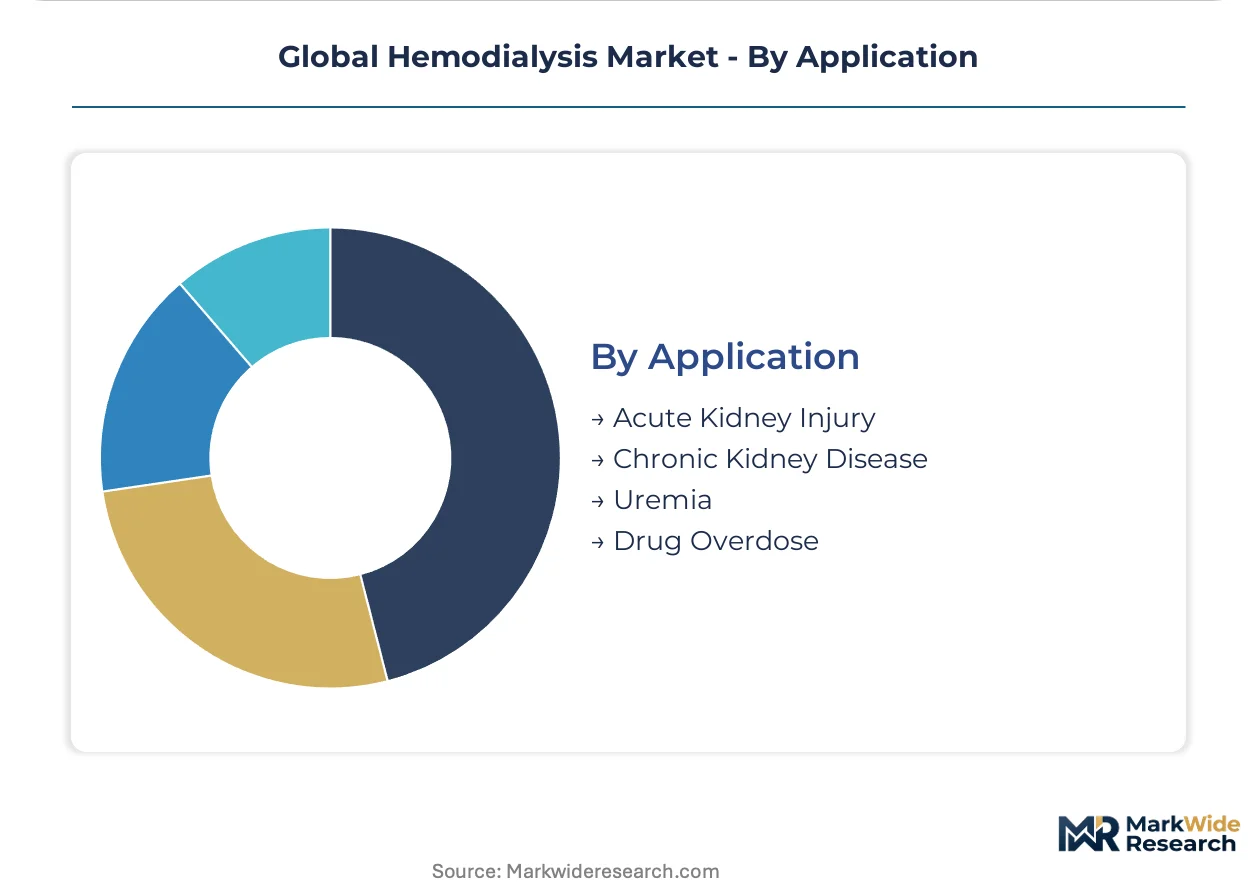
Application:
Disease acuity determines treatment setting, reimbursement category, and equipment specification intensity.
- Chronic Kidney Disease:End-stage renal disease requiring maintenance hemodialysis two to three times weekly represents the dominant volume pool. United States Medicare ESRD program and German statutory health insurance structures define reimbursement economics for this population.
- Acute Kidney Injury:Sudden renal function loss in hospitalized patients demands continuous or extended daily dialysis modalities. Intensive care units in tertiary hospitals concentrate demand for flexible acute treatment platforms.
- Uremia:Symptomatic toxin accumulation in advanced renal failure drives urgent dialysis initiation. Emergency departments and nephrology admission units manage this presentation category.
- Drug Overdose:Extracorporeal elimination of dialyzable toxins including lithium, salicylates, and certain antimicrobials requires specialized protocol adaptation. Poison control centers coordinate with hospital pharmacies on treatment decisions.
Volume dominance sits with Chronic Kidney Disease. Acute Kidney Injury commands premium pricing per treatment episode.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The hemodialysis industry traces its modern origins to Willem Kolff's rotating drum kidney developed in the Netherlands during World War II, with subsequent commercial scaling concentrated in German engineering clusters and Japanese precision manufacturing regions.
United States
Medicare's ESRD program coverage and DaVita's outpatient network density drive treatment volume concentration. FDA 510(k) and PMA pathways govern device approvals, extending timelines for membrane material innovations. The Southeast and Midwest corridor hosts dense dialysis center operations with integrated service infrastructure.
Germany
Fresenius Medical Care anchors manufacturing and clinical service clustering around Bad Homburg headquarters and Hesse production facilities. EMA MDR framework compliance requirements are forcing documentation rebuilds for CE-marked dialyzers. The Rhine-Main region generates knowledge spillovers accelerating product iteration cycles.
Japan
Aging demographics and high-flux membrane preference concentrate demand among tertiary nephrology departments. PMDA quality audit frameworks limit market entry to suppliers with demonstrated manufacturing consistency. Osaka and Tokyo medical device clusters host membrane surface modification expertise pools.
China
Expanding ESRD patient pools and government healthcare infrastructure investment are expanding treatment access. NMPA device registration pathways govern dialyzer and bloodline market entry. Yangtze River Delta manufacturing bases are scaling domestic membrane production capabilities.
India
Underpenetrated rural dialysis access and government dialysis program expansion are creating geographic white space. CDSCO medical device rules govern import and local manufacturing compliance. Maharashtra and Karnataka urban centers concentrate private dialysis chain operations.
Global Hemodialysis Market Vendor Landscape
The competitive structure tilts toward vertically integrated membrane producers with captive polymer science capabilities. Three to five conglomerates with diversified medical technology portfolios coexist alongside specialized dialysis service operators. Dominant archetypes include integrated device-consumable manufacturers, pure-play service network operators, and crossover modality platform developers. Capacity expansion in high-flux membrane production and strategic partnerships for portable device development represent the primary competitive moves reshaping positioning.
Among German-anchored integrated manufacturers, Fresenius Medical Care and B. Braun Melsungen occupy positions exemplifying backward integration into dialyzer membrane production. Baxter International represents the crossover modality archetype with peritoneal-to-hemodialysis platform capabilities. These three anchors demonstrate how geographic clustering around regulatory expertise and polymer science talent pools reinforces competitive moats.
| Leading Market Players |
|---|
| Fresenius Medical Care |
| Baxter International |
| DaVita |
| B. Braun Melsungen |
| Nipro Corporation |
| Nikkiso Co., Ltd. |
| Asahi Kasei Medical |
| Medtronic |
| Becton, Dickinson and Company |
| Others |
Supply Flow & Price Mechanics
High-flux synthetic membrane technology transition is compressing cost economics while concentrating supply power among polymer science leaders with captive production capabilities. Dialyzer manufacturers with backward integration into polysulfone and polyethersulfone resin production capture margin insulation against feedstock volatility, whereas non-integrated assemblers face pricing pressure from both raw material swings and procurement consolidation among large dialysis center networks.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs dialyzer and machine transactions, with FDA PMA certification and Japanese PMDA quality audit compliance serving as the primary price differentiation drivers. Cost compression in economy-grade consumables is intensifying because Chinese and Indian domestic manufacturers are scaling membrane production capacity. Hospital procurement committees exhibit the highest price sensitivity, while German and Japanese tertiary nephrology departments prioritize clinical performance metrics over unit cost.
Supply Chain Analysis
Reverse logistics for dialyzer refurbishment and hemodialysis machine remanufacturing remain underdeveloped, with most single-use consumables flowing to regulated medical waste streams rather than recovery programs. Manufacturing concentration clusters in Germany, Japan, and the United States, with specialized polymer production drawing from petrochemical feedstocks whose volatility transmits directly to membrane cost structures. Single-source vulnerability in high-purity polysulfone resin supply creates exposure to regional production disruptions. Distribution runs through hospital procurement systems, dialysis center networks, and specialized medical device distributors with cold-chain capabilities for temperature-sensitive bloodline products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Hemodialysis Market functions as a regulatory compounder where EMA MDR framework documentation requirements are accelerating consolidation among mid-tier suppliers lacking dedicated compliance infrastructure.
For Market Incumbents: Extend membrane production capacity in Germany and Japan to defend against Chinese domestic suppliers capturing cost-sensitive segments. Deepen software-enabled remote monitoring capabilities to lock in dialysis center network loyalty as hospital procurement teams unbundle service contracts from equipment purchases. Prioritize CE marking pathway investments to compress certification timelines under EMA MDR pressure.
For New Entrants and Emerging Players: Enter via portable dialysis device development targeting rural India and Southeast Asian markets lacking facility infrastructure density. Focus initial commercialization on home care channel partnerships with Western European payors recalibrating reimbursement toward patient-managed treatment. Pursue regulatory sandbox pathways in India's CDSCO framework to accelerate market entry before scaling to FDA or EMA jurisdictions.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier membrane assemblers without captive polymer production, presenting acquisition targets for vertical integration plays. Long-term viability over the projection horizon hinges on positioning for home care channel expansion and portable technology breakthroughs. Monitor FDA 510(k) pathway evolution for membrane materials as the signal indicating whether innovation timelines will compress or extend competitive moats.
| Strategic Initiative | Industry Significance |
|---|---|
| High-Flux Membrane Capacity Expansion | German and Japanese manufacturers with captive polymer production capture margin insulation against feedstock volatility. |
| CE Marking Pathway Investment | EMA MDR technical documentation rebuilds create competitive moats by excluding mid-tier suppliers lacking regulatory infrastructure. |
| Hospital System Partnership | Integrated delivery networks in the United States are unbundling service contracts, forcing vendors to renegotiate commercial terms. |
| Software Companion Development | Remote monitoring capabilities reduce clinical staffing requirements per treatment station, addressing labor cost pressure in dialysis centers. |
| Reimbursement Strategy | Medicare and Western European payor reform toward home-based treatment is redirecting R&D investment toward patient-operable interfaces. |
Methodological Framework
Direct dialogue with nephrology department heads, dialysis center operations directors, biomedical engineering managers, and GPO contracts managers grounded qualitative insights, supplemented by FDA 510(k) and PMA filings, EMA MDR submission databases, Japanese PMDA audit records, hospital procurement databases, and CMS Medicare reimbursement data. Bottom-up and top-down triangulation validated volume estimates across product type, end user, technology, and application segments.
Bottom-up modeling anchored in dialyzer production capacity, machine installation bases, and treatment episode frequency across chronic kidney disease and acute kidney injury populations, while top-down analysis cross-referenced against statutory health insurance expenditure patterns in Germany and Medicare ESRD program outlays in the United States. CAGRs were derived from regression analysis of historical procedure volumes and forward projection of ESRD incidence rates, payor policy shifts, and technology adoption curves for high-flux and portable modalities across the analysis window.
Inputs from regulatory filing databases and hospital procurement systems were available through the study window; gaps in real-time manufacturing capacity utilization data introduce uncertainty bands around supply-side forecasts. Practitioners should monitor FDA premarket pathway announcements, EMA MDR enforcement discretion periods, and Japanese PMDA audit schedule publications for early signals of competitive positioning shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nephrology
Nephrology Stents and Catheters Market
Nephrology
Late Stage Chronic Kidney Disease Therapeutics Market
Nephrology
Nephrotic Syndrome Market
Nephrology
Aldosterone-Renin Screening Market
Nephrology
Renal Artery Stenosis Treatment Market
Nephrology
Renal Cell Carcinoma Market
Nephrology
Dialysis Centers Market
Nephrology
US Dialysis Market
Nephrology
Hemodialysis Vascular Graft Market
Nephrology
Kidney Stone Extraction Balloon Market
Nephrology
Hemodialysis and Peritoneal Dialysis Market
Nephrology
ICU-Acquired Acute Kidney Treatment Market
Nephrology
Dialysis Service Market
Nephrology
Glomerulonephritis Treatment Market
Nephrology
Chronic Kidney Disease Market
Nephrology
Nephrosclerosis Treatment Market