
 Cell Washer Market | 2026-2036
Cell Washer Market Size, Share, and Industry Trends Forecast 2026-2036
Cell Washer Market Analytics
Multi-source procurement for precision centrifugation components is repositioning supply chain economics for cell washer OEMs. Thermo Fisher Scientific leverages its captive manufacturing network to control lead times on automated washing modules. Beckman Coulter anchors its position through deep specialization in high-throughput centrifugation platforms for clinical diagnostics. Miltenyi Biotec differentiates via magnetic bead integration that reduces manual handling steps in cell preparation workflows.
A cell washer is a laboratory instrument designed to remove unwanted media, buffers, or contaminants from cell suspensions through repeated centrifugation and resuspension cycles, typically operating at controlled speeds between 200 and 3,000 RPM with programmable wash protocols. Its primary purpose is to standardize cell preparation for downstream applications in immunology, cell therapy manufacturing, and protein analytical workflows. Automated cell washers command the dominant share of value given their integration with liquid handling robotics in GMP environments, while magnetic bead technology represents the fastest-expanding segment as cell therapy producers adopt closed-system processing. Semi-automated units retain relevance in academic settings where capital constraints limit full automation deployment.
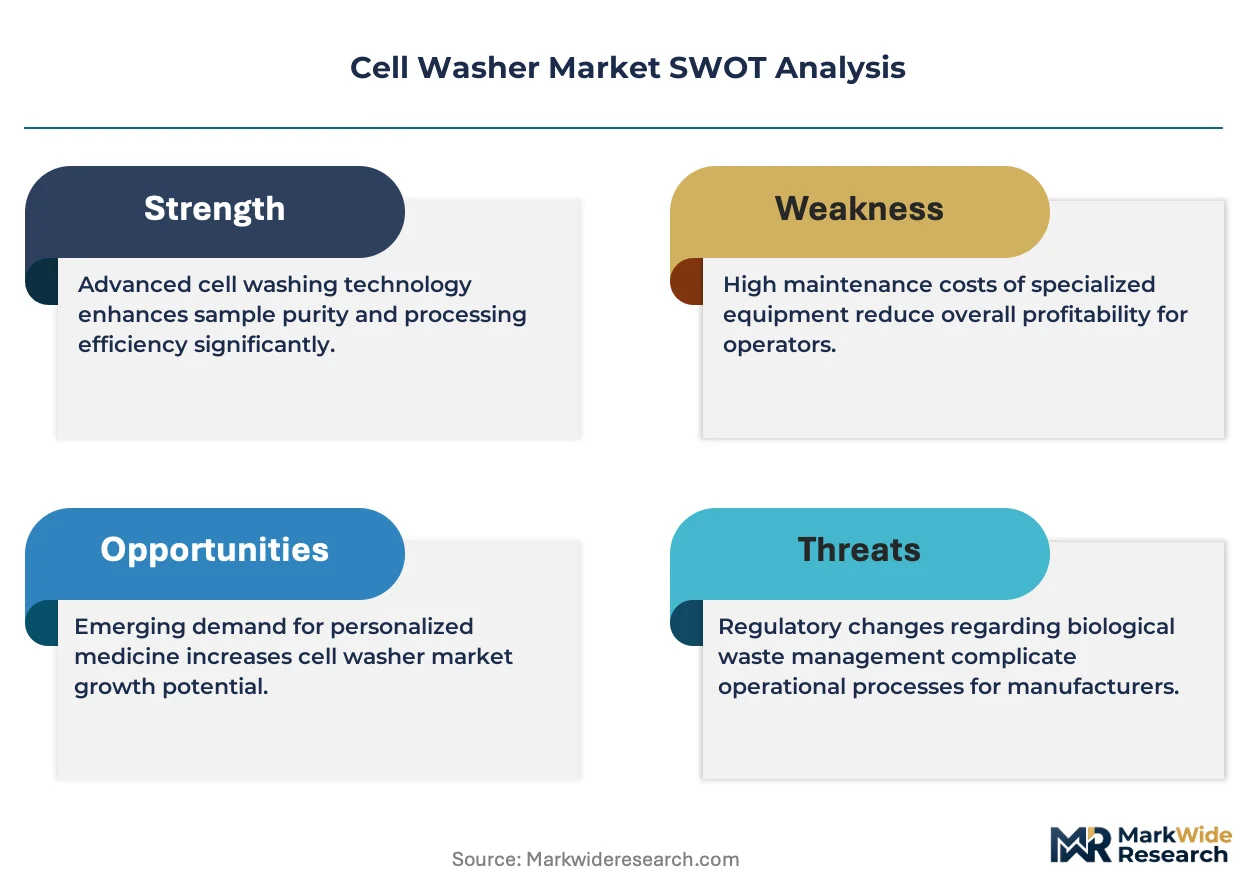
FDA 21 CFR Part 11 electronic records requirements and EU MDR conformity assessments shape validation documentation burdens for manufacturers seeking clinical laboratory placement. ISO 13485 quality management standards govern design controls for instruments entering diagnostic or therapeutic production settings. Stakeholders must monitor evolving GMP guidance for cell and gene therapy manufacturing as regulators tighten traceability requirements on washing step reproducibility.
Market Dynamics
Cell therapy manufacturing scale-up is compressing validation timelines and forcing instrument suppliers to pre-qualify equipment for GMP environments before purchase. FDA 21 CFR Part 11 compliance requirements now shape procurement checklists in clinical laboratories across Germany, the United States, and Japan.
Growth Catalysts
- Cell Therapy Manufacturing Expansion:Commercial-scale autologous and allogeneic cell production facilities require validated washing protocols. ISO 13485-certified instruments command preference in therapeutic manufacturing settings.
- FDA 21 CFR Part 11:Electronic records and signature requirements for clinical diagnostics create mandatory upgrade cycles. Laboratories replace legacy washers to achieve audit-ready documentation capabilities.
- Magnetic Bead Integration:Closed-system processing reduces contamination risk in cell therapy workflows. Automated bead separation protocols displace manual centrifugation steps in GMP cleanrooms.
Market Restraints
- Precision Centrifuge Component Concentration:German and Japanese suppliers dominate high-tolerance rotor manufacturing. OEMs face extended lead times for critical spare parts during supply disruptions.
- EU MDR Conformity Assessment Burden:Extended validation timelines for Class I medical devices delay market entry. Small manufacturers struggle with notified body capacity constraints.
- Capital Intensity of Full Automation:Academic and small clinical laboratories lack budget for integrated liquid handling systems. Semi-automated units retain share in price-sensitive segments.
Strategic Opportunities
- India Biopharma Manufacturing:CDSCO regulatory alignment with ICH standards attracts contract manufacturing investment. Local production incentives under PLI scheme support domestic instrument assembly.
- Point-of-Care Cell Processing:Decentralized manufacturing models require compact, validated washers. Regional cell therapy centers in the United States seek footprint-optimized equipment.
- ISO 20387 Biobanking Standards:Quality requirements for biological resource centers create replacement demand. Biobanks in Japan and Germany upgrade washing protocols for sample integrity.
Industry Challenges
- GMP Validation Specialist Shortage:Cell therapy facilities compete for qualified commissioning and qualification personnel. Equipment suppliers must embed validation support into service contracts.
- Legacy System Integration Complexity:Existing laboratory information management systems require custom middleware for automated washer connectivity. Hospitals delay upgrades due to IT resource constraints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cell Washer Market |
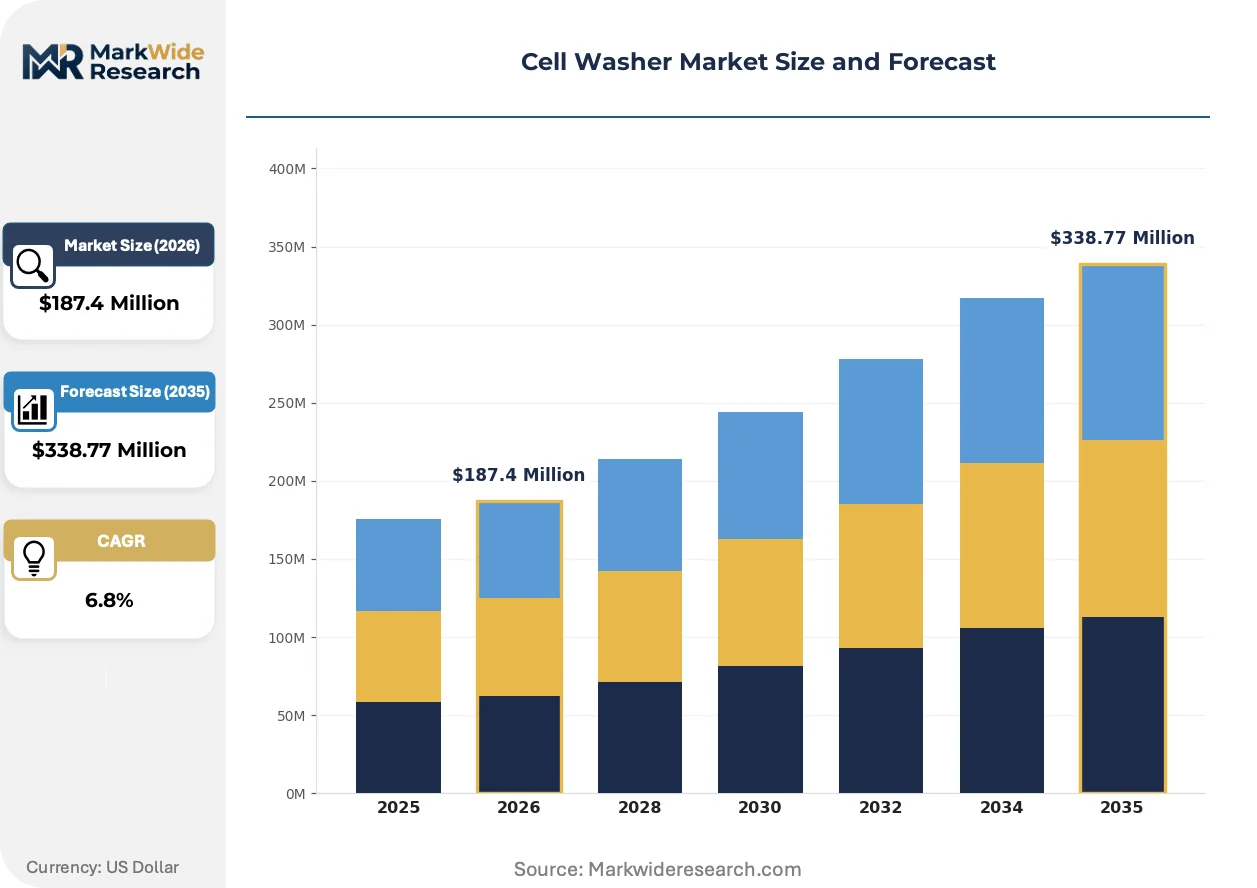
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Cell Washers, Manual Cell Washers, Semi-Automated Cell Washers, Multi-Parameter Cell Washers Technology: Filtration Technology, Centrifugation Technology, Membrane Separation, Magnetic Bead Technology End User: Clinical Laboratories, Research Institutions, Pharmaceutical Companies, Biotechnology Firms Application: Cell Isolation, Protein Purification, Cell Culture, Immunology Testing |
| Companies Covered | Thermo Fisher Scientific Inc., Beckman Coulter Inc., Miltenyi Biotec GmbH, Sartorius AG, Bio-Rad Laboratories, Inc., Sysmex Corporation, Danaher Corporation, Eppendorf AG, Andreas Hettich GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cell Washer Market Evolving Landscape
Automation architectures are fragmenting as cell therapy producers demand configurable washing protocols rather than fixed-program instruments. Regulatory convergence between diagnostic and therapeutic applications is compressing development cycles for multi-purpose equipment.
Single-use rotor assemblies and disposable fluid paths are modularizing equipment design for cell therapy manufacturing. CAR-T producers in the United States and Germany adopt swappable components to eliminate cross-contamination risks between patient batches. This architecture reduces changeover downtime and enables parallel processing lines within shared cleanroom footprints.
EU MDR Annex I general safety and performance requirements are tightening documentation standards for instruments entering clinical diagnostic workflows. Manufacturers must demonstrate traceability for software updates and calibration procedures. High-throughput clinical laboratories in France and the Netherlands prioritize pre-validated washers to accelerate compliance timelines.
Consolidated procurement through group purchasing organizations is concentrating buyer power among multi-hospital systems. Academic medical centers in Japan negotiate enterprise-wide service agreements spanning installation, validation, and preventive maintenance. This bundling compresses margins for standalone equipment sales while expanding recurring revenue pools for integrated suppliers.
Cell Washer Market Segmentation
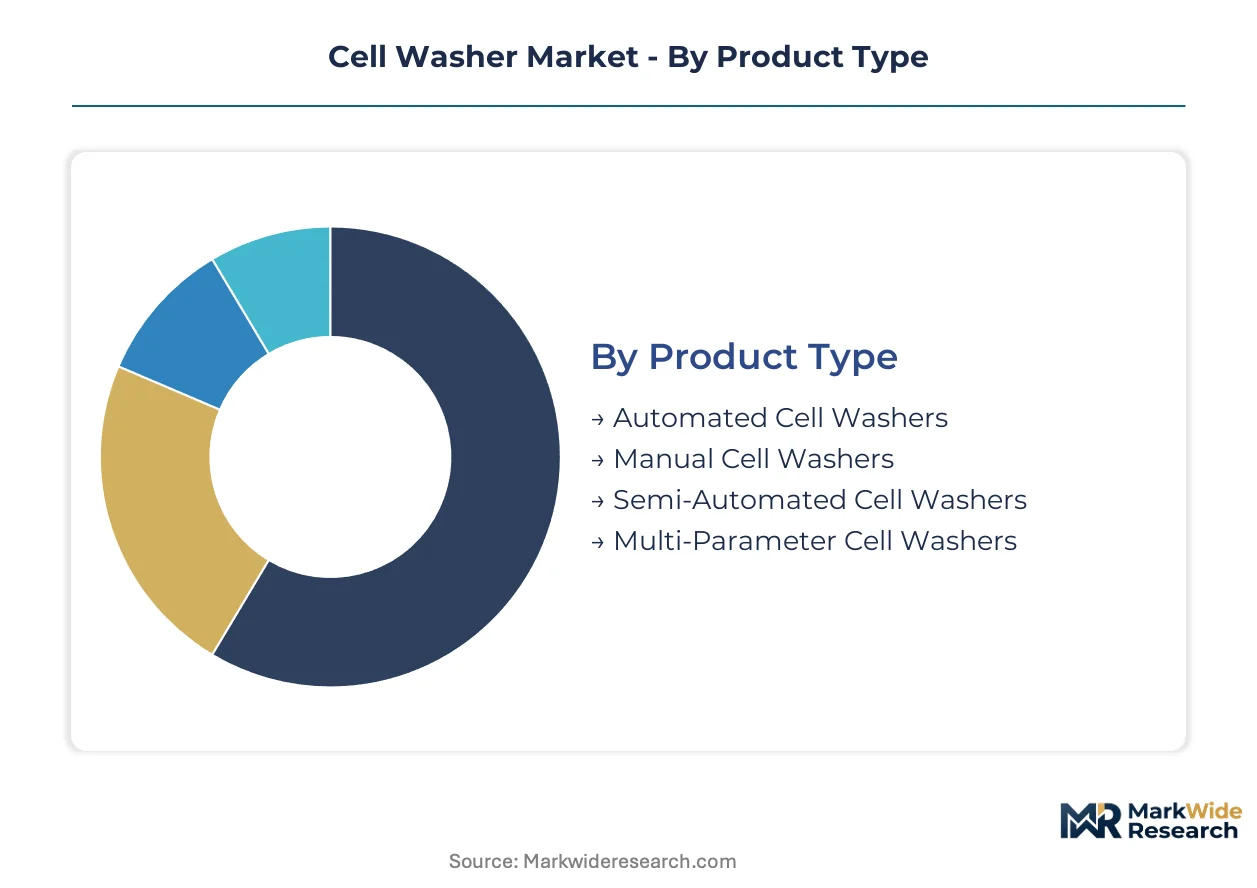
Segmentation in the cell washer market reflects divergent validation requirements across therapeutic manufacturing and diagnostic workflows. Equipment specifications vary sharply between GMP-compliant cell therapy facilities and academic research settings with limited capital budgets.
Product Type:
Supply concentration in precision centrifugation subassemblies favors manufacturers with captive component production or long-term supplier partnerships in Germany and Japan.
- Automated Cell Washers:Fully programmable instruments integrate with liquid handling robotics and LIMS platforms for electronic records compliance. Cell therapy manufacturers in the United States and Germany specify these units for GMP environments where batch traceability is mandatory.
- Semi-Automated Cell Washers:Partial automation reduces operator handling while retaining manual intervention points for protocol flexibility. Academic medical centers and mid-sized clinical laboratories deploy these units where capital constraints limit full automation investment.
- Manual Cell Washers:Benchtop centrifugation units with basic speed control serve resource-constrained settings.
- Multi-Parameter Cell Washers:Configurable platforms support diverse cell types through swappable rotor assemblies and programmable wash cycles.
Automated cell washers absorb the bulk of installed capacity in therapeutic manufacturing; multi-parameter units are expanding most quickly as facilities seek protocol flexibility.
Technology:
Cost tier differentiation separates premium magnetic bead systems from standard centrifugation platforms, with filtration occupying a mid-range position for specific contamination removal applications.
- Magnetic Bead Technology:Closed-system processing eliminates open centrifugation steps, reducing contamination risk in cell therapy cleanrooms. CAR-T producers in Germany and the United States adopt this technology to meet FDA guidance on aseptic processing.
- Centrifugation Technology:Differential sedimentation remains the dominant washing mechanism, operating at controlled speeds between 200 and 3,000 RPM with programmable acceleration profiles.
- Filtration Technology:Tangential flow and dead-end filtration remove soluble contaminants without pelleting cells.
- Membrane Separation:Selective permeability enables buffer exchange while retaining target cell populations.
Centrifugation technology retains the largest installed base; magnetic bead systems are gaining share fastest in cell therapy manufacturing.
End User:
Customer type determines procurement authority, with pharmaceutical companies consolidating purchases through enterprise agreements while research institutions negotiate individual unit sales.
- Clinical Laboratories:High-throughput diagnostic facilities require FDA 21 CFR Part 11-compliant washers with electronic signature capabilities. Hospital networks in Japan and the United States prioritize pre-validated equipment to accelerate compliance timelines.
- Pharmaceutical Companies:Commercial-scale cell therapy producers demand ISO 13485-certified instruments with comprehensive IQ/OQ/PQ documentation packages.
- Research Institutions:University laboratories and basic research centers balance performance specifications against grant-funded capital constraints.
- Biotechnology Firms:Emerging cell therapy developers seek scalable platforms that transition from process development to GMP manufacturing.
Clinical laboratories command the largest equipment volume; pharmaceutical companies are driving the steepest expansion trajectory as cell therapy manufacturing scales.
Application:
Application maturity varies, with cell isolation representing an established workflow while cell therapy manufacturing creates novel validation requirements for washing step reproducibility.
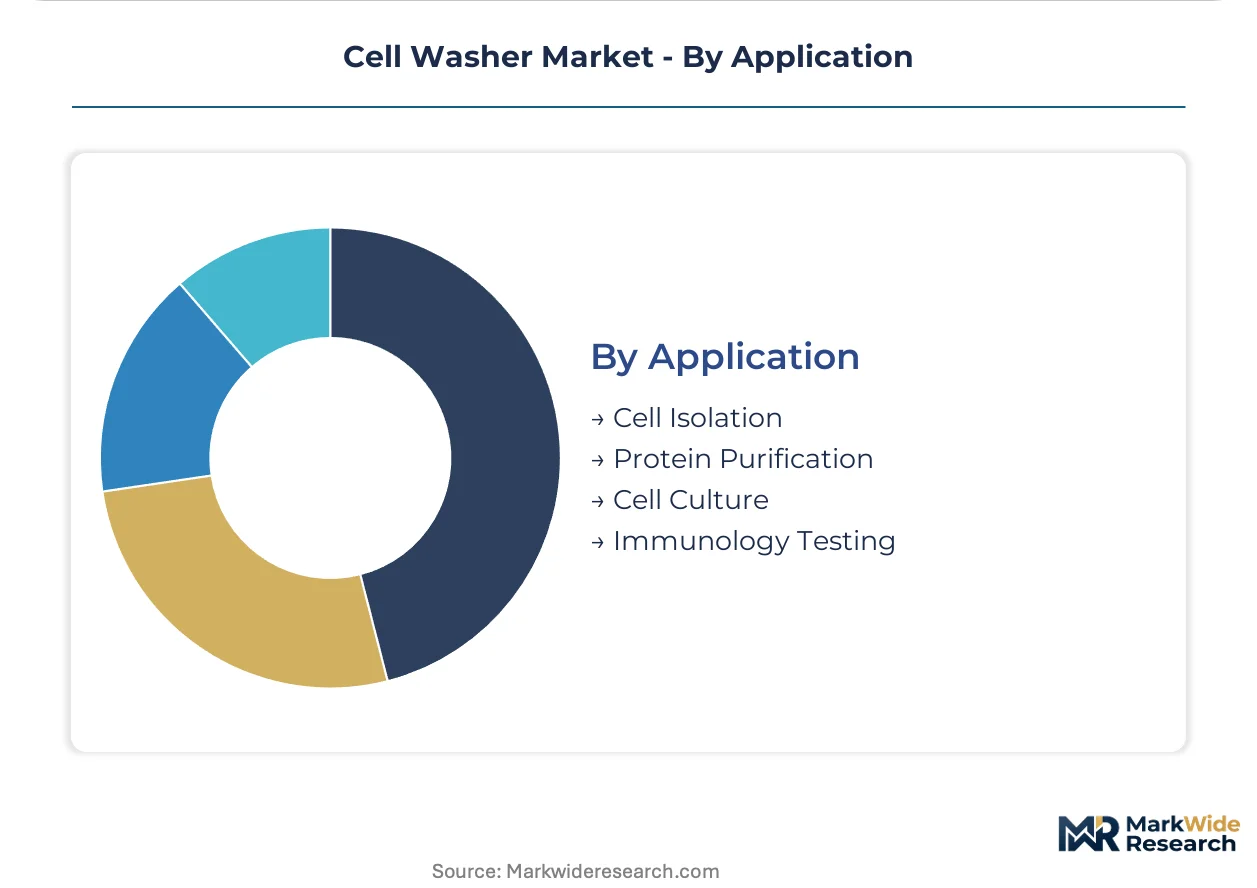
- Cell Isolation:Separation of target populations from complex mixtures requires controlled washing to remove debris and unbound reagents. Immunology laboratories in Germany and the United States standardize these protocols for diagnostic assay reproducibility.
- Cell Culture:Media exchange and contaminant removal support expansion of primary and immortalized cell lines.
- Protein Purification:Buffer exchange and tag removal workflows utilize washing steps downstream of cell lysis.
- Immunology Testing:Standardized cell preparation ensures consistent assay performance in diagnostic and research settings.
Cell isolation accounts for the majority of installed washer capacity; cell culture applications are climbing the fastest as regenerative medicine production expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision centrifuge rotor manufacturing concentrates in German and Japanese industrial clusters, anchoring supply-side capabilities for cell washer OEMs serving therapeutic manufacturing and diagnostic laboratories worldwide.
United States
Commercial-scale CAR-T production facilities in Boston and San Francisco drive demand for FDA 21 CFR Part 11-compliant washers with electronic records capabilities. The FDA's tightening GMP guidance for cell and gene therapy manufacturing accelerates validation documentation requirements. Massachusetts and California biopharma clusters command premium pricing for pre-qualified GMP equipment.
Germany
High-tolerance rotor fabrication from Baden-Württemberg and Bavaria suppliers shapes OEM sourcing strategies for precision centrifugation components. EU MDR conformity assessments extend validation timelines for Class I medical devices entering clinical diagnostic workflows. The Rhine-Main and Munich metropolitan areas concentrate cell therapy manufacturing investment from global pharmaceutical firms.
Japan
PMDA quality standards for regenerative medicine products drive ISO 13485-certified instrument procurement from Tokyo and Osaka-based clinical laboratories. METI industrial policy supports domestic bioprocessing equipment manufacturing through targeted R&D subsidies. The Kanto and Kansai regions host dense clusters of academic medical centers negotiating enterprise-wide service agreements.
India
CDSCO regulatory alignment with ICH standards attracts contract manufacturing investment for cell therapy production facilities in Maharashtra and Telangana. PLI scheme production incentives support domestic instrument assembly capabilities for price-sensitive research institutions. Hyderabad and Mumbai biotech corridors emerge as regional hubs for process development and analytical services.
United Kingdom
MHRA post-Brexit regulatory autonomy creates parallel compliance pathways for washers entering diagnostic and therapeutic applications. London and Cambridge life science clusters demand configurable platforms transitioning from research to GMP manufacturing. The Golden Triangle concentrates procurement authority among consolidated academic medical center networks.
Cell Washer Market Competitive Landscape
Strategic partnerships dominate the current landscape as instrument suppliers embed validation support and service capabilities into long-term contracts. The vendor base stratifies across three tiers: integrated life science conglomerates with captive component manufacturing, specialized centrifugation equipment manufacturers with deep protocol expertise, and emerging platform developers targeting closed-system cell therapy workflows. Two competitive moves define current positioning: vertical integration into precision rotor production to secure supply continuity, and geographic expansion through localized service networks to reduce validation deployment timelines.
Among diversified life science conglomerates, Thermo Fisher Scientific Inc. and Danaher Corporation exemplify scale-driven archetypes with extensive captive manufacturing networks. Beckman Coulter Inc. and Miltenyi Biotec GmbH occupy specialist positions, with the latter representing magnetic bead integration capabilities. German fabrication heritage anchors Andreas Hettich GmbH & Co. KG within precision centrifugation equipment manufacturing. These named entities collectively illustrate how competitive positioning fragments across integration depth, technological specialization, and regional service density rather than concentrating around单一 dominance.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Beckman Coulter Inc. |
| Miltenyi Biotec GmbH |
| Sartorius AG |
| Bio-Rad Laboratories, Inc. |
| Sysmex Corporation |
| Danaher Corporation |
| Eppendorf AG |
| Andreas Hettich GmbH & Co. KG |
| Others |
Value Network & Pricing Analysis
Magnetic bead technology adoption in cell therapy cleanrooms is compressing equipment cost structures while simultaneously concentrating procurement leverage among GMP-certified buyers in Germany, the United States, and Japan. This dual shift tightens margins for standard centrifugation platforms while elevating pricing power for suppliers with validated closed-system architectures.
Pricing Analysis
Warranty and preventive maintenance bundling separates premium-tier suppliers from unbundled equipment vendors in competitive tenders. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 13485 certification status and GMP validation documentation depth. Price differentiation hinges on electronic records compliance and geographic service density. Cost compression in semi-automated segments is intensifying because academic buyers prioritize capital expenditure minimization over total cost of ownership. Research institutions exhibit highest price sensitivity; commercial cell therapy manufacturers prioritize qualification speed over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle demand from multi-hospital systems and pharmaceutical conglomerates, while distributor networks serve fragmented academic accounts. Precision rotor fabrication concentrates in Germany and Japan, with secondary machining capabilities in the United States. Supply chains draw from specialized steel alloys, ceramic bearings, and rare-earth magnetic materials. Single-source vulnerability in high-tolerance spindle manufacturing creates procurement risk during demand surges. Distribution runs through authorized service organizations with embedded validation engineers for GMP deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision centrifugation component scarcity props pricing power for OEMs with captive manufacturing or long-term supplier partnerships. Capacity constraints in validated rotor production limit competitive entry.
For Market Incumbents: Hedge against magnetic bead technology displacement by deepening protocol expertise in automated washing workflows. Secure multi-year supply agreements with Baden-Württemberg and Bavaria rotor fabricators to defend against lead time volatility. Invest in embedded validation service capabilities to differentiate from emerging platform developers competing on equipment cost alone. For New Entrants and Emerging Players: Contract research organizations represent the most penetrable channel partner type for establishing initial reference accounts. Target India-based biopharma manufacturing facilities seeking CDSCO-aligned equipment at price points below established GMP suppliers. Pursue point-of-care cell processing applications where footprint constraints and decentralized deployment models favor compact system architectures over incumbent bulk equipment. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by diversified life science conglomerates seeking centrifugation protocol expertise. Long-term viability favors platforms with magnetic bead integration capabilities and closed-system processing architectures. Monitor FDA GMP guidance evolution for cell and gene therapy manufacturing as the critical inflection signal for validation service demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| GMP Validation Service Expansion | Embedded IQ/OQ/PQ support accelerates procurement decisions from FDA-regulated cell therapy facilities. |
| Magnetic Bead Platform Integration | Closed-system processing architectures meet FDA aseptic processing guidance for CAR-T manufacturing workflows. |
| Precision Rotor Manufacturing Partnership | Long-term supply agreements with German and Japanese fabricators secure component continuity during demand spikes. |
| Regional Service Network Localization | India-based assembly and validation capabilities reduce deployment timelines for CDSCO-aligned biopharma customers. |
| Single-Use Component Modularization | Swappable rotor assemblies enable parallel processing lines within shared cleanroom footprints for batch efficiency. |
Research Methodology
Document review covered FDA 21 CFR Part 11 guidance documents, EU MDR technical documentation requirements, and ISO 13485 quality management standards, complemented by interviews with cell therapy manufacturing directors, clinical laboratory managers, GMP validation specialists, and biomedical equipment procurement leads. Secondary sources included SEC filings from listed life science conglomerates, CDSCO regulatory circulars, METI industrial policy white papers, and hospital group purchasing organization contract databases. Bottom-up equipment installation estimates triangulated against top-down market size assessments.
Historical shipment data cross-referenced against panel input from OEM sales executives and distributor channel managers established baseline trajectories. Segmentation modeling spanned automation level, technology type, end-user category, and application workflow across the projection horizon. CAGRs derived from weighted average of equipment replacement cycles, manufacturing capacity expansion announcements, and regulatory compliance upgrade timelines. Forecast inputs incorporated cell therapy clinical trial advancement rates and biobank infrastructure investment patterns.
Caveats apply where FDA GMP guidance revisions, EU MDR notified body capacity constraints, or precision component supply disruptions could materially shift the outlook. Forecasts reflect documented assumptions regarding therapeutic manufacturing scale-up trajectories and diagnostic laboratory automation adoption curves. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Europe Medical Device Reprocessing Market
Medical Equipment
Bench-Top Dental Autoclaves Market
Medical Equipment
Asia-Pacific Medical Device Cleaning Market
Medical Equipment
Hemodialysis Equipment Market
Medical Equipment
Medical Physics Market
Medical Equipment
Animal Operating Table Market
Medical Equipment
Medical Gas Equipment Market
Medical Equipment
Durable Medical Equipment Market
Medical Equipment
US Durable Medical Equipment Market
Medical Equipment
Dual Energy X-Ray Absorptiometry (Dexa) Equipment Market
Medical Equipment
Electrophysiology Equipment and Recording Systems Market
Medical Equipment
North America Nuclear Medicine Equipment Market
Medical Equipment
Global Indirect Calorimeter Market
Medical Equipment
Hybrid Operating Room Market
Medical Equipment
Cryochambers Market
Medical Equipment
North America Radiotherapy Market