
 Global Optometry Equipment Market | 2026-2036
Global Optometry Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Optometry Equipment Market Foresight
The EU MDR is pivoting the cost-of-entry calculus for optometry device manufacturers toward extensive clinical validation and quality management system overhauls. Carl Zeiss Meditec AG leverages its vertically integrated optics heritage to absorb these compliance burdens without margin erosion. EssilorLuxottica anchors its competitive stance through channel control spanning lens manufacturing and retail distribution networks. Topcon Corporation differentiates via sustained R&D intensity in fundus imaging and refractive diagnostics.
Optometry equipment encompasses diagnostic and refractive instruments engineered to measure visual acuity, ocular health parameters, and refractive errors with precision thresholds typically reaching 0.12 diopter resolution in modern autorefractors. These devices serve primary vision correction workflows, disease screening protocols, and surgical planning sequences across clinical and commercial settings. Optical Coherence Tomography systems command the deepest margin pools due to their capital intensity and recurrent software upgrade cycles. Autorefractors and lensmeters represent mature, high-volume categories where manufacturing scale determines unit economics. Visual Field Analyzers are gaining share fastest among the technology segments as glaucoma screening protocols expand into primary care settings.
FDA 510(k) pathways and EU MDR conformity assessments shape product development timelines and market access sequencing for manufacturers targeting both jurisdictions. ISO 13485 quality system certification operates as a baseline procurement filter across hospital and clinic purchasing committees. China's NMPA device registration requirements add a third compliance layer for firms seeking access to that country's expanding ophthalmology clinic base. Stakeholders must monitor how regulatory divergence between FDA's predicate-based system and EU MDR's stricter clinical evidence demands will fragment product portfolio strategies and regional launch priorities.
Market Dynamics
The EU MDR clinical evidence requirements are compressing product development timelines while simultaneously elevating the capital threshold for market entry, forcing manufacturers to restructure validation protocols and quality management systems around sustained clinical data generation rather than predicate equivalence.
Growth Catalysts
- EU MDR implementation:Stricter conformity assessment procedures are filtering out marginal competitors and consolidating procurement decisions toward certified manufacturers with established quality systems.
- Primary care integration:Glaucoma screening protocols are expanding beyond ophthalmology clinics into general practitioner workflows, creating pull for portable diagnostic instruments.
- Software-as-a-service models:Recurrent revenue from OCT system upgrades and AI-powered diagnostic algorithms is transforming capital equipment economics toward predictable subscription streams.
Market Restraints
- Precision optics supply concentration:German and Japanese optical component suppliers control critical lens grinding and coating capabilities, exposing downstream manufacturers to single-source dependencies.
- EU MDR notification body capacity:Bottlenecked conformity assessment timelines are delaying product launches by 12-18 months regardless of technical readiness.
- Smartphone-based refraction apps:Consumer-grade vision screening tools are capturing low-acuity diagnostic occasions that previously required professional equipment.
Strategic Opportunities
- India's ophthalmology clinic expansion:Tier-2 and tier-3 cities are developing diagnostic infrastructure faster than multinational distribution networks can penetrate, creating white space for localized assembly and service models.
- Telemedicine reimbursement codes:Remote diagnostic interpretations are gaining coverage under US Medicare and private payer frameworks, enabling equipment deployment without co-located specialist presence.
- AI-integrated fundus imaging:Machine learning algorithms for diabetic retinopathy detection are creating new purchase justifications for primary care settings previously outside the optometry equipment addressable market.
Industry Challenges
- ISO 13485 auditor scarcity:Qualified quality management system assessors are concentrated among a handful of certification bodies, creating backlog risks for manufacturers pursuing multi-jurisdictional compliance.
- Legacy EMR integration:Hospital information systems and practice management software use incompatible data standards, forcing device manufacturers to maintain multiple interface configurations per customer.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Optometry Equipment Market |
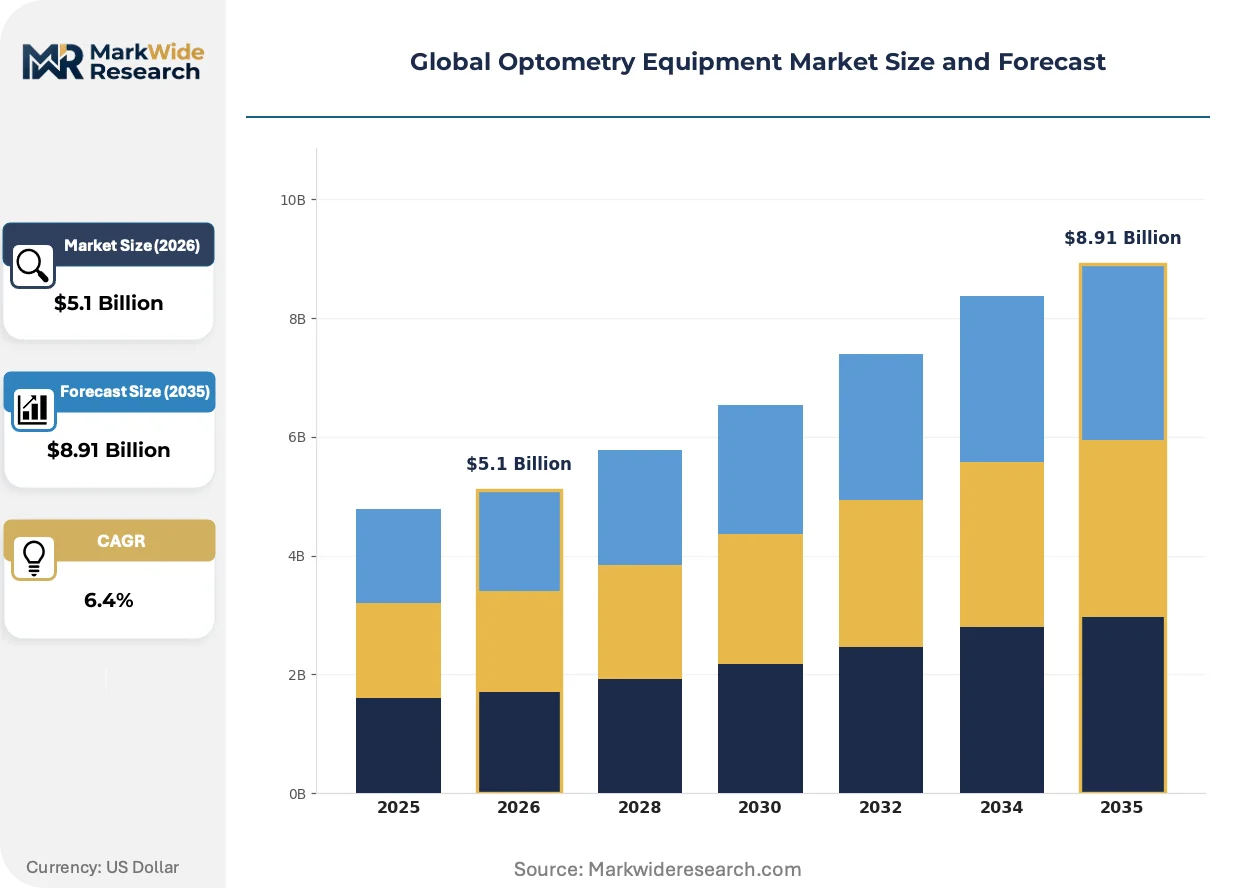
| Market Size in 2026 | $5.1 Billion |
| Market Size in 2035 | $8.91 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Autorefractors, Lensmeters, Ophthalmoscopes, Phoropters Technology: Optical Coherence Tomography, Non-Contact Tonometry, Fundus Photography, Visual Field Analyzers End User: Ophthalmology Clinics, Hospitals, Optical Retail Stores, Research Institutions Application: Vision Testing, Diagnosis, Treatment Monitoring, Patient Education |
| Companies Covered | Carl Zeiss Meditec AG, EssilorLuxottica, Alcon, Topcon Corporation, Bausch Health Companies Inc, Canon Inc., Haag-Streit Holding AG, Nidek Co., Ltd., Heidelberg Engineering, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Optometry Equipment Market Shifts & Advancements
Optometry equipment is undergoing convergence between optical hardware and computational diagnostics, with artificial intelligence algorithms now embedded directly into capture devices rather than residing on separate analysis workstations.
Swept-source OCT technology is electrifying posterior segment imaging by replacing time-domain acquisition with wavelength-tuned laser sources that capture volumetric retinal data at speeds exceeding 100,000 A-scans per second. Academic medical centers and high-volume retina practices are adopting these systems to compress examination duration while expanding the diagnostic information captured per patient encounter. The technology is electrifying competitive dynamics by rendering previous spectral-domain platforms obsolete in premium segments while creating aftermarket service vulnerability for installed base migrations.
EU MDR post-market surveillance requirements are mandating systematic clinical follow-up data collection across device lifecycles, transforming quality management from document-centric compliance to active patient outcome monitoring. Manufacturers must now maintain vigilance systems capable of detecting rare adverse events that predicate-based approval previously obscured. High-risk Class III devices including implantable contact lenses and certain laser platforms face the steepest documentation burdens, with notified bodies demanding prospective registry data rather than retrospective chart reviews.
Hospital purchasing committees are consolidating vendor relationships through single-source agreements that bundle diagnostic equipment, consumables, and extended service contracts into multi-year commitments. Independent ophthalmology practices and smaller clinic chains are responding through group purchasing organizations that aggregate procurement volume to secure pricing parity with integrated delivery networks. This concentration is most pronounced in Germany's statutory health insurance reimbursement environment, where equipment financing decisions increasingly flow through centralized hospital procurement rather than individual physician preference.
Global Optometry Equipment Market Segmentation
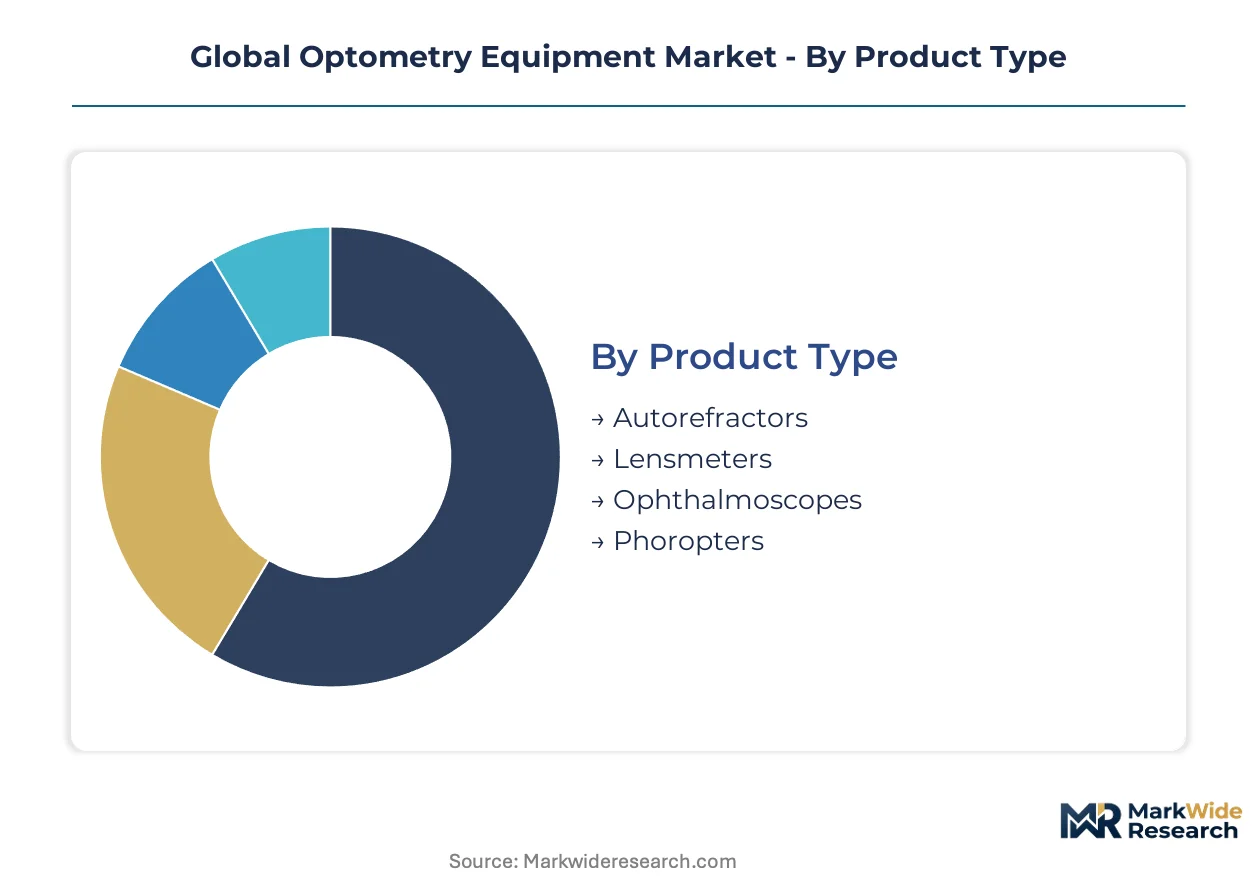
Optometry equipment segmentation reveals how diagnostic workflows fragment across clinical settings and technical specifications. Understanding these divisions exposes where procurement budgets concentrate and which technology transitions reshape competitive positioning.
Product Type:
Equipment categories stratify by measurement precision requirements and capital intensity thresholds.
- Autorefractors:Automated devices measure refractive errors using infrared light and wavefront analysis, delivering objective prescriptions within seconds. Demand clusters in high-throughput optical retail chains across Germany and Japan where patient volume justifies automation investment.
- Lensmeters:Instruments verify lens power, axis orientation, and prism correction through optical bench configurations. Procurement concentrates among independent opticians in India's tier-2 cities seeking quality assurance for locally sourced lenses.
- Ophthalmoscopes:Direct and indirect illumination systems enable retinal examination through undilated pupils.
- Phoropters:Refractive testing assemblies combine multiple lens powers for subjective visual acuity determination.
Autorefractors lead on scale; phoropters lead on momentum as digital refraction systems displace manual configurations.
Technology:
Diagnostic platforms differentiate by imaging depth, acquisition speed, and software integration capabilities.
- Optical Coherence Tomography:Interferometric imaging captures cross-sectional retinal anatomy at micron-scale resolution. Hospital purchasing committees in the United States prioritize spectral-domain and swept-source platforms for glaucoma and macular degeneration protocols.
- Visual Field Analyzers:Perimetry systems map functional vision loss through automated stimulus presentation. Primary care networks across the United Kingdom deploy compact units for community-based glaucoma screening expansion.
- Fundus Photography:Digital capture systems document retinal pathology for remote consultation and longitudinal tracking.
- Non-Contact Tonometry:Air-puff devices measure intraocular pressure without corneal anesthesia.
OCT commands the deepest margins; visual field analyzers are gaining share fastest among primary care integration.
End User:
Customer segments diverge by reimbursement structure, patient volume, and equipment financing mechanisms.
- Ophthalmology Clinics:Specialized practices demand multi-modal diagnostic suites combining anterior and posterior segment capabilities. Private clinic chains in South Korea invest heavily for competitive differentiation in refractive surgery candidacy assessment.
- Hospitals:Integrated delivery networks negotiate enterprise agreements bundling service contracts and software licenses. Academic medical centers in Switzerland prioritize research-compatible platforms with open data architectures.
- Optical Retail Stores:Commercial vision correction providers seek compact, patient-facing devices for in-store prescription verification.
- Research Institutions:Universities and clinical trial organizations require calibrated instrumentation for investigational protocols.
Hospitals dominate procurement volume; ophthalmology clinics show the steepest expansion trajectory in emerging markets.
Application:
Clinical use cases determine performance specifications and regulatory classification pathways.
- Vision Testing:Routine refractive assessment drives the highest equipment utilization rates. School screening programs across Brazil create sustained demand for portable autorefractors and visual acuity charts.
- Diagnosis:Pathology detection requires FDA 510(k) or EU MDR clearance with clinical validation datasets. Diabetic retinopathy screening initiatives in Saudi Arabia fund fundus camera deployment into primary health centers.
- Treatment Monitoring:Longitudinal disease management necessitates interoperable data systems for trend analysis.
- Patient Education:Visualization tools support informed consent and treatment adherence through anatomical illustration.
Vision testing anchors installed base; diagnosis applications are climbing the fastest as screening protocols expand beyond specialist settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision optics engineers and Japanese imaging scientists anchor the industry's geographic talent distribution, concentrating advanced manufacturing capabilities in specific industrial corridors while regulatory divergence between FDA and EU MDR compliance pathways fragments product launch sequencing across jurisdictions.
United States
Medicare reimbursement expansion for remote diagnostic interpretations drives demand for telemedicine-compatible fundus cameras and visual field systems. FDA 510(k) predicate-based pathways accelerate clearance timelines compared to EU counterparts, though post-market surveillance requirements are tightening. Hospital purchasing committees in the Cleveland Clinic and Mayo Clinic networks negotiate enterprise agreements bundling service contracts across multi-state ophthalmology groups.
Germany
Statutory health insurance reimbursement frameworks centralize equipment procurement through hospital purchasing cooperatives rather than individual physician decisions. EU MDR notified body assessments from TÜV SÜD and BSI impose 12-18 month conformity delays regardless of technical readiness. Jena and Oberkochen host vertically integrated optics clusters where lens grinding, coating, and precision assembly capabilities concentrate within 50-kilometer radii.
Japan
Aging demographics compress examination duration requirements, accelerating swept-source OCT adoption in high-volume retina practices. PMDA device registration maintains alignment with FDA technical standards while adding Japan-specific clinical trial obligations. Nagoya and Tokyo metropolitan areas concentrate domestic manufacturing for export-oriented fundus camera and autorefractor production.
China
Private ophthalmology clinic chains in Shanghai and Beijing expand diagnostic suites faster than multinational distribution networks can penetrate tier-2 cities. NMPA device registration requirements add compliance layers distinct from FDA and EU pathways, favoring domestic assemblers with localized regulatory expertise. Yangtze River Delta manufacturing zones develop indigenous optical component capabilities to reduce German and Japanese supply dependencies.
India
Tier-2 and tier-3 city clinic expansion outpaces established distribution infrastructure, creating white space for localized assembly and service models. CDSCO medical device rules increasingly align with IMDRF standards, though state-level procurement variations complicate national rollout strategies. Maharashtra and Gujarat host emerging precision optics workshops serving domestic lensmeter and portable autorefractor demand.
Global Optometry Equipment Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across technology tiers, with consolidated procurement decisions favoring vendors bundling hardware, software, and extended service commitments. The vendor base stratifies into three archetypes: vertically integrated optics heritage firms, channel-dominant eyewear conglomerates, and R&D-intensive imaging specialists. Competitive positioning hinges on backward integration into precision optical components and forward integration into software-as-a-service diagnostic algorithms.
Within the heritage optics tier, Carl Zeiss Meditec AG and Haag-Streit Holding AG exemplify German precision manufacturing traditions extending across medical and industrial applications. Topcon Corporation and Nidek Co., Ltd. occupy positions among Japanese imaging specialists concentrating sustained R&D investment in fundus diagnostics. EssilorLuxottica represents channel-integrated conglomerates leveraging retail network control to anchor equipment placement decisions.
| Leading Market Players |
|---|
| Carl Zeiss Meditec AG |
| EssilorLuxottica |
| Alcon |
| Topcon Corporation |
| Bausch Health Companies Inc |
| Canon Inc. |
| Haag-Streit Holding AG |
| Nidek Co., Ltd. |
| Heidelberg Engineering |
| Others |
Supply & Pricing Matrix
Family-owned precision optics specialists in Jena and Oberkochen anchor supply-side discipline through captive lens grinding capabilities, while their pricing power over spectral-domain OCT modules constrains margin compression for downstream device assemblers lacking backward integration into German optical component production.
Pricing Analysis
Bundled service contracts dominate premium OCT system transactions, while unbundled per-unit pricing persists in high-volume autorefractor and lensmeter categories. Three-tier pricing structure across premium, standard, and economy levels separates research-grade swept-source platforms from clinical spectral-domain systems and entry-level manual phoropters. Cost compression in standard-tier devices is intensifying because Chinese assemblers are absorbing EU MDR compliance burdens to capture emerging market share. Optical retail chains exhibit the highest price sensitivity, whereas academic medical centers prioritize performance specifications over unit economics.
Supply Chain Analysis
Precision optics workforce scarcity in Thuringia and Baden-Württemberg constrains expansion of German lens grinding capacity, forcing Japanese manufacturers to compete for the same specialized engineering talent pools. Supply concentration in Germany, Japan, and emerging Chinese Yangtze River Delta zones draws from proprietary glass formulations, precision motion control systems, and infrared detector arrays. Single-source vulnerability runs through German suppliers controlling aspheric lens coating technologies. Distribution runs through multinational device OEMs with direct hospital sales forces and regional distributor networks serving independent optometry practices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR conformity assessment bottlenecks in Germany create a twelve-to-eighteen-month regulatory arbitrage window against FDA 510(k) clearance timelines in the United States, rewarding manufacturers with dual-jurisdiction compliance infrastructure.
For Market Incumbents: Deepen software-as-a-service integration to lock in recurring revenue streams and defend against smartphone-based refraction apps capturing low-acuity diagnostic occasions. Prioritize EU MDR notified body pre-submission engagements to compress assessment timelines, while expanding captive optical component production in Jena to insulate margins from German supply concentration. For New Entrants and Emerging Players: Begin with India's tier-2 ophthalmology clinic expansion, where diagnostic infrastructure growth outpaces multinational distribution penetration and localized assembly models can undercut landed cost structures. Target portable visual field analyzers for primary care glaucoma screening protocols, leveraging telemedicine reimbursement expansion as the primary go-to-market pathway. For Investors and Strategic Acquirers: Eyewear conglomerates with retail channel control are the most active acquirer in this space, seeking diagnostic equipment capabilities to anchor in-store prescription workflows. Five-to-ten year viability hinges on AI-integrated imaging software assets rather than hardware manufacturing scale. Monitor FDA breakthrough device designations for fundus imaging algorithms as the signal for platform consolidation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Notified Body Pre-Submission | BSI and TÜV SÜD engagement compresses conformity assessment delays for Class IIb diagnostic platforms. |
| Swept-Source OCT Platform Migration | Academic medical centers in Switzerland and South Korea accelerate replacement of spectral-domain installed bases. |
| AI Fundus Imaging Software Companion | Machine learning algorithms for diabetic retinopathy detection expand addressable market into primary care settings. |
| India Localized Assembly Partnership | Maharashtra and Gujarat precision optics workshops reduce landed costs for tier-2 city clinic penetration. |
| Telemedicine Reimbursement Strategy | Medicare remote diagnostic interpretation codes enable equipment deployment without co-located specialist presence. |
Research Methodology
Direct dialogue with hospital purchasing committee chairs, ophthalmology clinic managing directors, biomedical engineers, and GPO contracts managers grounded qualitative findings in procurement decision dynamics. Secondary validation drew from FDA 510(k) filings, EU MDR notified body assessment databases, CMS Medicare reimbursement schedules, and hospital equipment procurement records. Bottom-up unit demand modeling and top-down market sizing triangulated volume estimates across the analysis window.
Segmentation-level CAGRs emerged from regression analysis against ophthalmology clinic expansion rates, statutory health insurance reimbursement trajectories, and technology substitution curves for swept-source versus spectral-domain OCT platforms. The model incorporated product type splits across autorefractors, lensmeters, OCT systems, and visual field analyzers; technology tiers spanning time-domain, spectral-domain, and swept-source imaging; end-user categories including hospitals, ophthalmology clinics, and optical retail chains; and application workflows from vision testing through treatment monitoring.
Several conditions sit outside the modeled scope, including sudden EU MDR notified body capacity collapses, breakthrough smartphone refraction accuracy improvements, and major ophthalmology clinic chain bankruptcies. Practitioners should monitor FDA breakthrough device designations for AI diagnostic algorithms and EU MDR transition deadline extensions for early signals of forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Dialysis Equipment Market
Medical Equipment
Medical Oxygen Concentrators and Oxygen Cylinders Market
Medical Equipment
Medical Device and Equipment Tags Market
Medical Equipment
Blood Banking Equipment Market
Medical Equipment
Global Medical Vacuum System Market
Medical Equipment
Water Bath Market
Medical Equipment
Medical Carts and Workstations Market
Medical Equipment
Medical Ultrasonic Baths Market
Medical Equipment
Medical Cart Battery Market
Medical Equipment
Global Bone Densitometer Market
Medical Equipment
Clinical Microscopes Market
Medical Equipment
Proton and Ion Beam Therapy Dosimetry and QA Test Equipment Market
Medical Equipment
Global Microtome Market
Medical Equipment
Apheresis Equipment Market
Medical Equipment
Global Oxygen Flow Meters Market
Medical Equipment
Contact Type Liquid Handling Workstation Market