
 Global Surgical Table Market | 2026-2036
Global Surgical Table Market Size, Share, and Industry Trends Forecast 2026-2036
Global Surgical Table Market Foresight
The capital-intensity divergence between integrated manufacturers and assembly-dependent competitors is rotating competitive advantage toward firms with in-house actuator production and precision machining capabilities. Stryker leverages its vertically integrated supply chain for powered adjustment systems across North American hospital networks. GETINGE anchors its position through sustained R&D investment in imaging-compatible table architectures that reduce intraoperative repositioning.
A surgical table is a height-adjustable, articulating patient support platform engineered from stainless steel and radiolucent composites, designed to maintain stable patient positioning during invasive procedures while accommodating anesthesia equipment and C-arm imaging systems. Electric tables with motorized adjustment and integrated load sensing now dominate procurement specifications in tertiary hospitals, whereas manual and hydraulic variants retain share in cost-constrained surgical centers and emerging-market facilities where infrastructure budgets limit electrification. Imaging integration technology commands premium positioning as hybrid operating rooms expand, while anti-microbial coating applications are becoming baseline requirements rather than differentiators across European and North American tenders.
The FDA's 510(k) clearance framework and the EU MDR's stricter clinical evidence requirements for Class II medical devices are extending product development timelines and elevating compliance costs for table manufacturers seeking transatlantic market access. ISO 13485 quality management certification and IEC 60601 electrical safety standards function as non-negotiable gatekeepers for procurement eligibility in OECD healthcare systems. Stakeholders must monitor how reimbursement shifts toward outpatient surgical settings reshape volume allocation between hospital-based and ambulatory table deployments.
Market Dynamics
Hybrid operating room construction is compressing replacement cycles for legacy surgical platforms as hospitals prioritize imaging-compatible patient positioning systems over standard general surgery tables.
Growth Catalysts
- Motorized Adjustment Systems:Ambulatory surgical centers in the United States are specifying powered tables for outpatient orthopedic and ophthalmic procedures as procedure volumes migrate from inpatient settings.
- EU MDR Certification Requirements:Stricter clinical evidence mandates for Class II medical devices are filtering out marginal competitors and concentrating procurement among certified manufacturers with established quality systems.
- Germany Hospital Modernization:Federal infrastructure programs are accelerating replacement of tables exceeding fifteen years of service life in university hospitals and municipal surgical departments.
Market Restraints
- Stainless Steel Input Volatility:Surgical table chassis fabrication depends on medical-grade stainless steel pricing, which fluctuates with nickel and chromium commodity markets and compresses margin predictability for assembly-dependent manufacturers.
- Actuator Supply Concentration:Precision linear actuator production clusters in Germany and Japan, creating single-source vulnerability for table manufacturers without captive motor production.
- Manual Table Substitution:Cost-constrained surgical centers in emerging markets retain hydraulic and manual positioning platforms where electrification infrastructure is unreliable or capital budgets are restricted.
Strategic Opportunities
- India Ambulatory Expansion:Corporate hospital chains in Mumbai and Delhi are building day-surgery centers requiring compact motorized tables with rapid turnaround capabilities.
- Anti-Microbial Coating Mandates:French and Italian tender specifications are elevating copper-ion and silver-nanoparticle surface treatments from optional to required, creating premium tier differentiation for compliant manufacturers.
- Cloud-Connected Load Sensing:Integration of real-time patient weight distribution monitoring with hospital information systems is creating recurring software revenue streams alongside hardware sales.
Industry Challenges
- ISO 13485 Certification Timeline:New market entrants face eighteen-to-twenty-four month quality management system audits before achieving procurement eligibility in OECD healthcare systems.
- Electromechanical Integration Complexity:Surgical tables must simultaneously satisfy IEC 60601 electrical safety, electromagnetic compatibility, and imaging equipment interference standards, extending engineering validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Surgical Table Market |
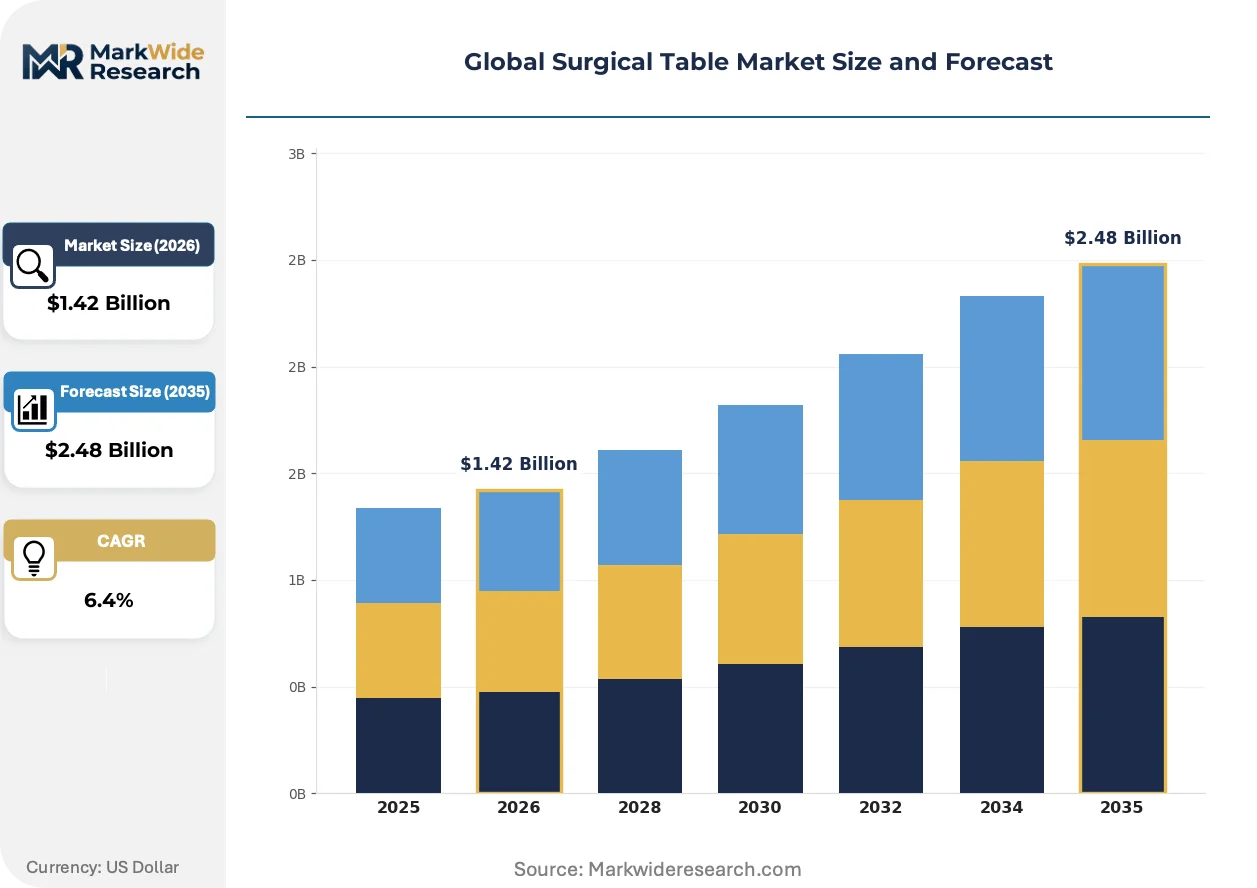
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.48 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric, Manual, Hydraulic, Radiolucent Application: Neurosurgery, Orthopedic Procedures, Cardiac Surgery, General Surgery End User: Hospitals, Surgical Centers, Ambulatory Clinics, Specialty Clinics Technology: Imaging Integration, Motorized Adjustment, Anti-microbial Coating, Load Sensing |
| Companies Covered | STERIS Healthcare, GETINGE, Stryker, Baxter, MIZUHO OSI, Trumpf Medical, Skytron, ALVO Medical, Hill-Rom, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Surgical Table Market Shifts & Advancements
Radiolucent carbon fiber composites are displacing traditional metal tabletops as C-arm imaging penetration deepens across cardiovascular and spinal surgery suites.
Carbon fiber tabletop technology is miniaturizing. These lattice-reinforced structures permit uninterrupted fluoroscopy during spinal instrumentation and endovascular procedures. Tertiary hospitals in Switzerland and the Netherlands are specifying full-carbon surfaces in hybrid OR tenders. The technology is miniaturizing component thickness while maintaining load-bearing capacity, compressing the performance gap between imaging tables and general surgery platforms.
EU MDR's post-market surveillance requirements are extending clinical follow-up obligations for powered positioning devices. Manufacturers must now maintain systematic complaint databases and periodic safety update reports across the product lifecycle. German and Swedish notified bodies are prioritizing audits for surgical table manufacturers with legacy hydraulic systems seeking recertification.
Leasing arrangements are displacing capital purchase models for surgical tables in United States health systems. Hospital networks in Texas and Florida are bundling table procurement with preventive maintenance and software upgrade clauses through third-party equipment finance providers. This shift transfers obsolescence risk from clinical facilities to manufacturers and compresses average contract durations from ten-year ownership to five-year refresh cycles.
Global Surgical Table Market Segmentation
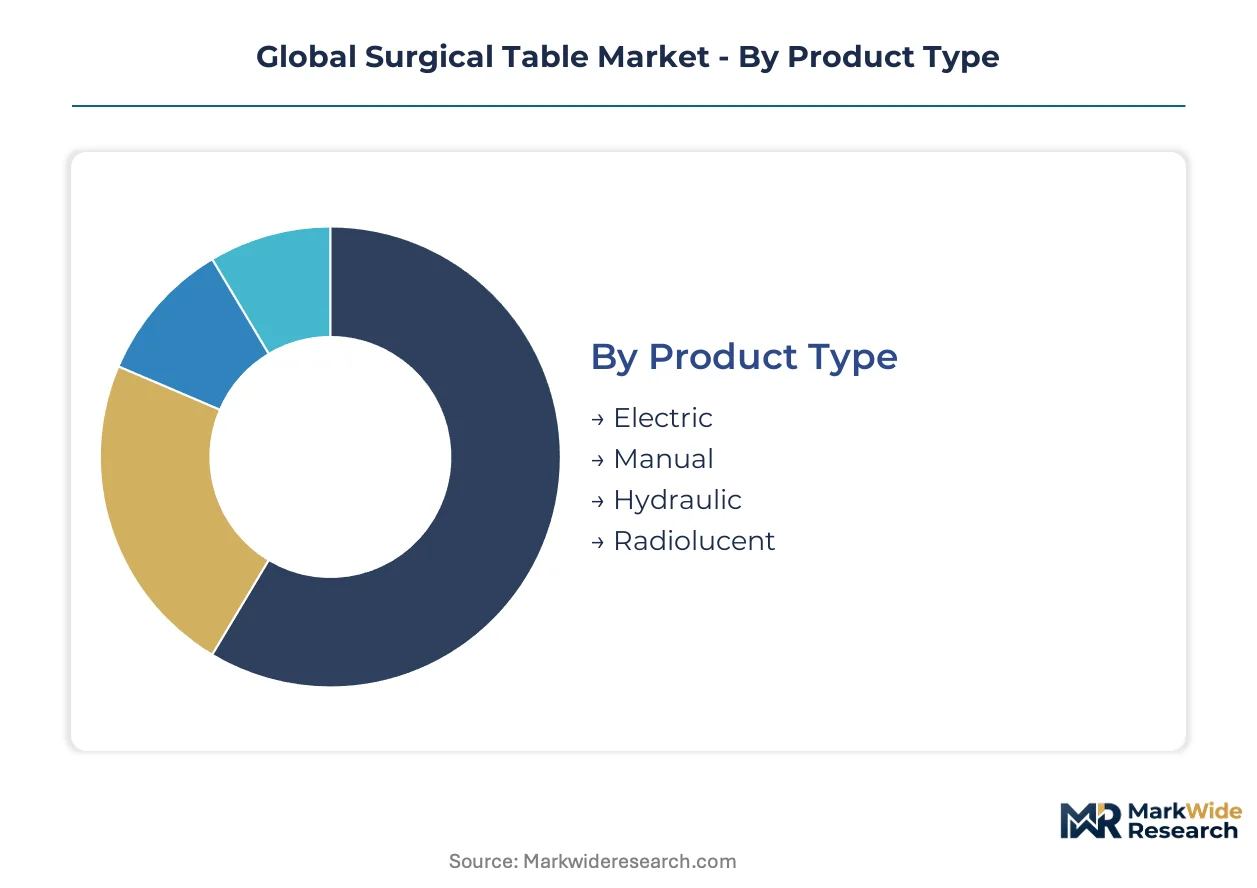
Surgical table procurement diverges sharply across facility types and procedure requirements. Substitution pressures from manual alternatives and imaging table convergence reshape competitive dynamics within each segment category.
Product Type:
Manual positioning platforms exert persistent substitution pressure on powered systems where electrification infrastructure remains unreliable or capital budgets face compression.
- Electric:Motorized height adjustment and articulation powered by precision linear actuators with integrated load sensing. Tertiary hospitals in Germany and the United States specify electric platforms for hybrid operating rooms where C-arm compatibility is mandatory.
- Radiolucent:Carbon fiber composite tabletops engineered for uninterrupted fluoroscopy during spinal instrumentation and endovascular procedures. Swiss and Dutch university hospitals are specifying full-carbon surfaces in hybrid OR tenders as imaging penetration deepens.
- Manual:Mechanical crank or hydraulic lift systems requiring physical adjustment by surgical staff. Retains procurement share in cost-constrained surgical centers across India and Southeast Asia where infrastructure budgets limit electrification.
- Hydraulic:Fluid-powered positioning systems offering intermediate automation without electrical components. Municipal surgical departments in Eastern Europe retain hydraulic platforms where maintenance capabilities favor mechanical over electromechanical systems.
Electric platforms retain volume leadership; radiolucent configurations hold the steepest expansion curve.
Application:
Procedure-specific positioning requirements concentrate procurement specifications around imaging compatibility and patient stability demands.
- Orthopedic Procedures:Traction-capable tables with radiolucent extensions for intraoperative imaging during joint replacement and fracture fixation. Ambulatory surgical centers in Texas and Florida are specifying motorized orthopedic platforms as outpatient volumes climb.
- Cardiac Surgery:Sternotomy positioning with integrated cardiac compression and perfusion equipment mounting. German university hospitals prioritize cardiac-compatible tables in federal infrastructure modernization programs.
- Neurosurgery:Precision head fixation and skull clamp integration with three-axis positioning. Requires sub-millimeter stability tolerances during intracranial procedures.
- General Surgery:Versatile abdominal positioning with Trendelenburg and reverse-Trendelenburg capability. Standard specification for municipal surgical departments with mixed procedure portfolios.
General surgery retains volume leadership; orthopedic applications are expanding most quickly.
End User:
Capital allocation patterns and reimbursement structures differentiate procurement behavior across facility ownership models.
- Hospitals:Integrated health systems with ten-to-fifteen-year replacement cycles and preventive maintenance contracts. University hospitals in Germany and the United States dominate premium electric and radiolucent procurement.
- Surgical Centers:Focused-procedure facilities requiring rapid turnaround and compact footprints. Corporate hospital chains in Mumbai and Delhi are building day-surgery centers with motorized table specifications.
- Ambulatory Clinics:Office-based surgical suites with limited space and lower procedure volumes. Manual and hydraulic platforms retain share where electrification infrastructure is constrained.
- Specialty Clinics:Single-discipline facilities such as ophthalmology or pain management suites. Compact motorized tables with procedure-specific positioning accessories.
Hospitals retain volume leadership; surgical centers are gaining share fastest.
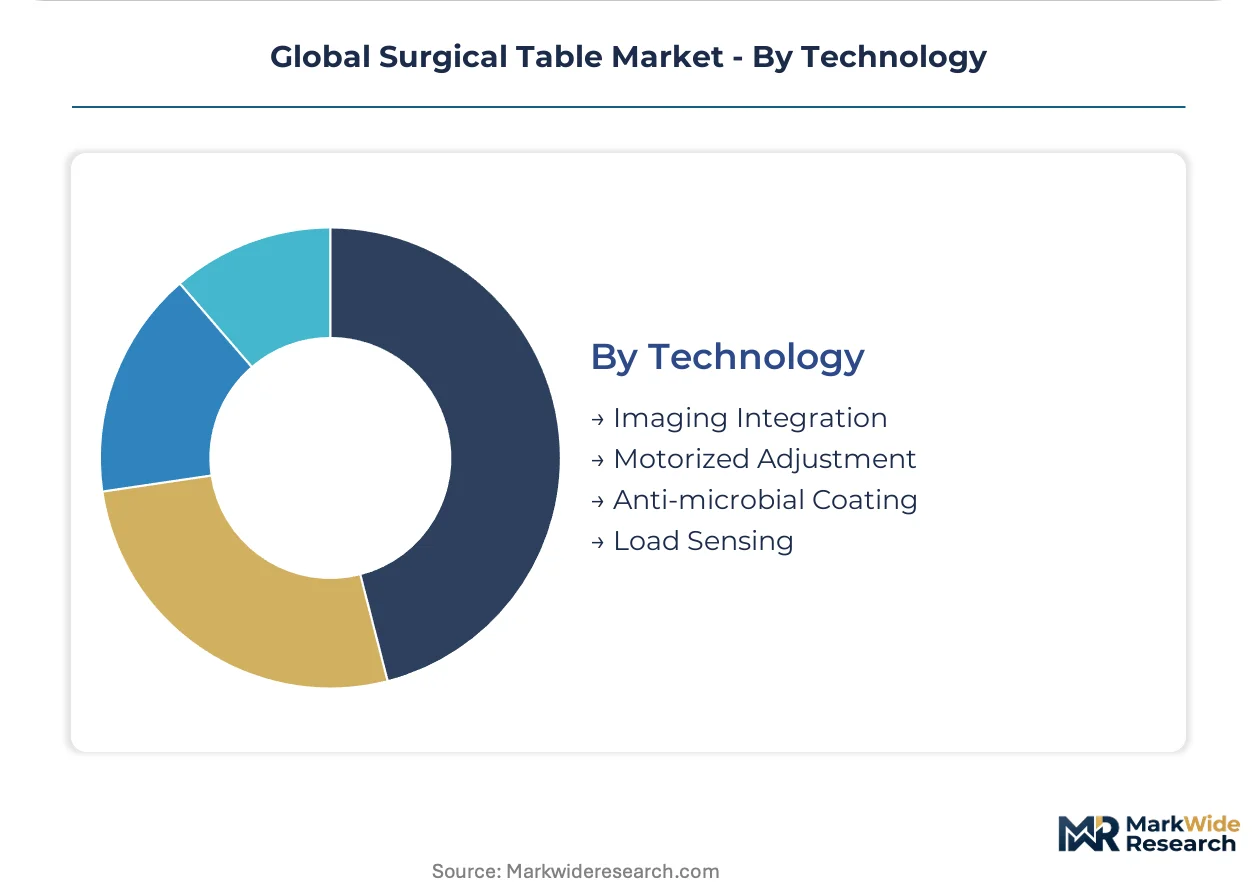
Technology:
Regulatory mandates and clinical workflow integration are elevating certain technologies from optional to required specifications.
- Imaging Integration:C-arm compatibility with carbon fiber tabletops and artifact-free fluoroscopy. Hybrid OR construction in Switzerland and the Netherlands is compressing replacement cycles for non-compatible legacy platforms.
- Anti-microbial Coating:Copper-ion and silver-nanoparticle surface treatments for infection control. French and Italian tender specifications are elevating these from optional to required.
- Motorized Adjustment:Electric actuation for height, tilt, and lateral positioning with programmable presets. Standard specification for ambulatory surgical centers in the United States.
- Load Sensing:Real-time patient weight distribution monitoring with hospital information system integration. Cloud-connected variants are creating recurring software revenue streams alongside hardware sales.
Motorized adjustment retains volume leadership; imaging integration commands the steepest premium trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium surgical table pricing in Switzerland and the Netherlands commands 40-50% above equivalent specifications in India, where municipal procurement budgets compress electrification rates and extend hydraulic platform lifecycles.
United States
Texas and Florida hospital networks are bundling table procurement with preventive maintenance through third-party equipment finance providers. FDA 510(k) clearance timelines extend development cycles for powered positioning systems. Ambulatory surgical centers in Dallas and Houston specify motorized orthopedic platforms as outpatient volumes climb.
Germany
Federal infrastructure programs accelerate replacement of tables exceeding fifteen years of service life in university hospitals. EU MDR stricter clinical evidence mandates filter out marginal competitors and concentrate procurement among certified manufacturers. Bavarian and North Rhine-Westphalian municipal surgical departments prioritize imaging-compatible platforms in hybrid OR construction.
Switzerland
Tertiary hospitals specify full-carbon radiolucent tabletops in hybrid OR tenders as C-arm imaging penetration deepens across cardiovascular suites. Swissmedic prioritizes audits for manufacturers with legacy hydraulic systems seeking recertification under tightened surveillance requirements. Zurich and Basel university hospitals command premium positioning for imaging integration technology.
India
Corporate hospital chains in Mumbai and Delhi build day-surgery centers requiring compact motorized tables with rapid turnaround capabilities. CDSCO medical device regulations elevate quality management requirements for imported powered positioning equipment. Maharashtra and Karnataka state health procurement favors manual and hydraulic variants where electrification infrastructure remains constrained.
Japan
Precision linear actuator production clusters create supply concentration for table manufacturers without captive motor production. PMDA quality standards function as procurement gatekeepers for OECD healthcare system eligibility. Tokyo and Osaka metropolitan hospital networks emphasize electromechanical integration compliance in tender specifications.
Global Surgical Table Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the surgical table market. The vendor base separates into three tiers: integrated manufacturers with in-house actuator production, imaging-compatible specialists with sustained R&D investment, and assembly-dependent competitors vulnerable to stainless steel input volatility. Strategic moves concentrate on backward integration into precision machining capabilities and geographic expansion through equipment finance partnerships.
Among diversified medical technology conglomerates, Stryker and GETINGE exemplify contrasting archetypes. Stryker occupies a position emphasizing vertically integrated supply chains for powered adjustment systems. GETINGE anchors the imaging-compatible specialist tier through sustained architecture development. Baxter and Hill-Rom sit within the hospital equipment diversification segment. Trumpf Medical represents German precision engineering concentration. MIZUHO OSI exemplifies Japanese actuator supply integration. Skytron and ALVO Medical occupy mid-scale specialist positions. STERIS Healthcare represents sterilization-to-positioning portfolio breadth.
| Leading Market Players |
|---|
| STERIS Healthcare |
| GETINGE |
| Stryker |
| Baxter |
| MIZUHO OSI |
| Trumpf Medical |
| Skytron |
| ALVO Medical |
| Hill-Rom |
| Others |
Supply & Pricing Matrix
Carbon fiber composite tabletops displacing stainless steel surfaces in hybrid operating rooms simultaneously concentrate procurement among German and Japanese precision manufacturers while compressing margin predictability for assembly-dependent competitors without captive composite fabrication. This material substitution elevates pricing power for integrated producers controlling radiolucent component supply while pressuring mid-tier vendors exposed to nickel and chromium commodity volatility.
Pricing Analysis
Configured-to-order pricing for imaging-compatible surgical tables with integrated C-arm positioning commands substantial premiums over standard general surgery platforms. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and after-sales service bundling, with EU MDR-certified electric platforms from German manufacturers holding the least price-sensitive position among university hospital buyers. Cost compression in manual and hydraulic tiers intensifies because municipal procurement in India and Eastern Europe prioritizes capital expenditure minimization over lifecycle cost optimization. Ambulatory surgical centers in Texas and Florida exhibit moderate price sensitivity, balancing rapid turnaround specifications against equipment finance bundling preferences.
Supply Chain Analysis
Strategic stockpiling of medical-grade stainless steel and precision linear actuators dominates inventory strategy among integrated surgical table manufacturers facing eighteen-month procurement cycles for critical electromechanical components. Component fabrication clusters in Germany, Japan, and Switzerland for precision actuators and radiolucent composites, with chassis assembly distributed across Poland, Mexico, and China for cost-optimized tiers. Raw material dependencies rest on nickel-chromium alloy pricing, carbon fiber prepreg supply, and rare-earth magnet availability for motor assemblies. Single-source vulnerability in German and Japanese actuator production creates structural risk for assembly-dependent competitors without backward integration into precision machining. Distribution runs through hospital group purchasing organizations in the United States, federal procurement frameworks in Germany, and corporate hospital chains in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among integrated hospital networks and ambulatory surgical center chains, with ten-hospital-system contracts displacing individual facility procurement and compressing vendor margins through volume aggregation.
For Market Incumbents: Shield premium positioning by accelerating backward integration into carbon fiber composite tabletop production and precision actuator manufacturing, eliminating single-source exposure to German and Japanese component suppliers. Deepen hospital system partnerships through preventive maintenance bundling and software upgrade subscriptions that transfer obsolescence risk from clinical buyers. Defensive certification investment in EU MDR quality management systems filters out marginal competitors and protects procurement eligibility in OECD healthcare systems.
For New Entrants and Emerging Players: Anchor in India's corporate day-surgery center expansion, where motorized table demand outpaces established vendor presence and CDSCO regulatory pathways remain less congested than FDA or EU MDR routes. Target compact orthopedic platforms with rapid turnaround specifications for Mumbai and Delhi ambulatory chains, where infrastructure constraints favor electrification over manual alternatives. Pursue equipment finance partnerships as the primary go-to-market angle, bundling hardware procurement with maintenance contracts to match incumbent service offerings.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed hospital equipment distributors holding fragmented surgical table portfolios across European municipal procurement channels. Five-to-ten year viability hinges on regulatory certification durability and imaging integration technology refresh cycles rather than commodity manufacturing scale. Monitor EU MDR recertification timelines for legacy hydraulic system manufacturers as an inflection indicator for consolidation opportunity, with German and Swedish notified body audit backlogs signaling distressed asset availability.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Investment | Quality system audits by German notified bodies protect procurement eligibility in European university hospitals. |
| Backward Integration into Actuator Production | In-house precision linear motor manufacturing eliminates single-source dependency on Japanese component suppliers. |
| Cloud-Connected Load Sensing Development | Real-time patient weight monitoring integration with hospital information systems creates recurring software revenue streams. |
| Equipment Finance Partnership Expansion | Third-party leasing bundling in Texas and Florida transfers obsolescence risk and compresses replacement cycles. |
| Anti-Microbial Coating Compliance | Copper-ion surface treatment certification satisfies French and Italian tender mandates elevating infection control specifications. |
Research Methodology
Desk research of FDA 510(k) clearance databases, EU MDR notified body audit records, and hospital procurement contract filings preceded structured interviews with biomedical engineers, hospital purchasing committee chairs, GPO contracts managers, and surgical equipment distributors. Primary fieldwork with German university hospital procurement departments and Texas ambulatory surgical center administrators validated secondary data on replacement cycle timing and imaging integration specifications. Bottom-up surgical table shipment estimates by product configuration triangulated against top-down healthcare capital expenditure forecasts from OECD health system budget disclosures.
Variance decomposition across the projection horizon isolates volume drivers by facility type, procedure migration patterns, and regulatory certification phase-ins without assuming uniform adoption curves. Segmentation modeling incorporates product type, application specialty, end-user facility ownership, and technology tier dimensions alongside regional reimbursement structure differentiation. CAGRs derive from fitted logistic adoption curves for motorized platforms and linear replacement assumptions for legacy manual systems, with hybrid operating room construction permitting procedure-specific demand elasticity estimation.
Material uncertainties — nickel-chromium commodity volatility, EU MDR audit timeline extensions, and ambulatory reimbursement policy shifts — sit outside the modeled envelope. Forecasts reflect assumptions of stable OECD healthcare capital allocation and continued outpatient procedure migration. Revision becomes warranted when federal infrastructure program funding in Germany or equipment finance availability in the United States crosses threshold disruptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Global Refrigerated Incubators Market
Medical Equipment
Medical Equipment Management Software Market
Medical Equipment
Durable Medical Equipment Market
Medical Equipment
Bone Densitometer Systems Market
Medical Equipment
Urodynamic Equipment and Consumables Market
Medical Equipment
Radiotherapy Motion Management Market
Medical Equipment
Medical Suction Units Market
Medical Equipment
Fluoroscopy Equipment Market
Medical Equipment
Animal Operating Table Market
Medical Equipment
Marijuana Drying and Curing Equipment Market
Medical Equipment
Blood Banking Equipment Market
Medical Equipment
Portable Steam Autoclave Market
Medical Equipment
Global Embryo Incubator Market
Medical Equipment
Tanning Units Market
Medical Equipment
Global Indirect Calorimeter Market
Medical Equipment
Contact Type Liquid Handling Workstation Market