
 US Hospital Consumables Market | 2026-2036
US Hospital Consumables Market Size, Share, and Industry Trends Forecast 2026-2036
US Hospital Consumables Market Insights
Buyer concentration among integrated delivery networks is expanding as hospital systems consolidate purchasing decisions across multi-state footprints. Cardinal Health leverages national distribution infrastructure to serve these consolidated accounts. Medline Industries, Inc. anchors private-label consumables programs for GPO-affiliated hospitals. Owens & Minor competes through specialized logistics services tailored to just-in-time operating room supply chains.
Hospital consumables encompass single-use and limited-use medical products including syringes, catheters, surgical drapes, gloves, and wound dressings, typically manufactured from medical-grade polymers, nonwoven fabrics, or latex alternatives under sterile conditions. These items prevent cross-contamination, reduce healthcare-associated infections, and eliminate reprocessing costs in acute care settings. Surgical supplies represent the most mature segment with established margin pools, while diagnostic kits are capturing accelerated demand from point-of-care testing expansion in emergency departments. Wholesale distributors remain the dominant channel for bulk hospital procurement, though direct sales relationships are deepening with large multi-hospital systems seeking contract pricing leverage.
FDA 510(k) clearance requirements and EPA sterilization emission standards govern product entry and manufacturing protocols for domestic suppliers. OSHA bloodborne pathogen regulations and Joint Commission accreditation standards further shape product specifications and hospital purchasing criteria. Stakeholders must monitor CMS reimbursement shifts toward outpatient settings and evaluate how site-of-care migration reshapes consumable volume patterns across acute versus non-acute channels.
Market Dynamics
Hospital system consolidation into integrated delivery networks is compressing procurement cycles and forcing distributors to restructure contract frameworks around multi-year, multi-site agreements rather than facility-level purchasing.
Growth Catalysts
- CMS outpatient reimbursement migration:Ambulatory surgical centers in Texas and Florida are scaling sterile consumable inventories to capture shifting procedural volumes from inpatient settings.
- Joint Commission infection control mandates:Acute care hospitals are replacing reusable instruments with single-use alternatives to satisfy accreditation audits and reduce liability exposure.
- Polymer sterilization advances:Gamma-stable thermoplastic formulations are expanding the range of devices that can transition from metal reprocessing to disposable polymer construction.
Market Restraints
- Petrochemical feedstock volatility:Medical-grade polypropylene and polystyrene resin costs fluctuate with crude oil benchmarks, squeezing margin predictability for molded consumables.
- Domestic sterilization capacity concentration:Ethylene oxide sterilization services cluster in Illinois and Georgia, creating geographic chokepoints for national distribution.
- Reusable instrument reprocessing:Central sterile departments in cost-constrained hospitals extend instrument life cycles, delaying conversion to single-use alternatives.
Strategic Opportunities
- Rural hospital supply deserts:Critical access hospitals in Montana and Wyoming lack distributor density, creating openings for regional logistics specialists with cold-chain capabilities.
- California surgical kit customization:Large health systems in Los Angeles and San Francisco are demanding procedure-specific tray configurations rather than standard off-the-shelf packs.
- FDA 510(k) streamlined pathways:Predicate device expansion for low-risk consumables is shortening clearance timelines for domestic manufacturers targeting OR supply contracts.
Industry Challenges
- Sterile packaging engineering talent:Medical device manufacturers compete with food and pharmaceutical sectors for polymer scientists specializing in barrier film design.
- ERP integration with hospital inventory systems:Distributors must build API connections to Epic and Cerner platforms to enable automated reorder triggers and consignment tracking.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Hospital Consumables Market |
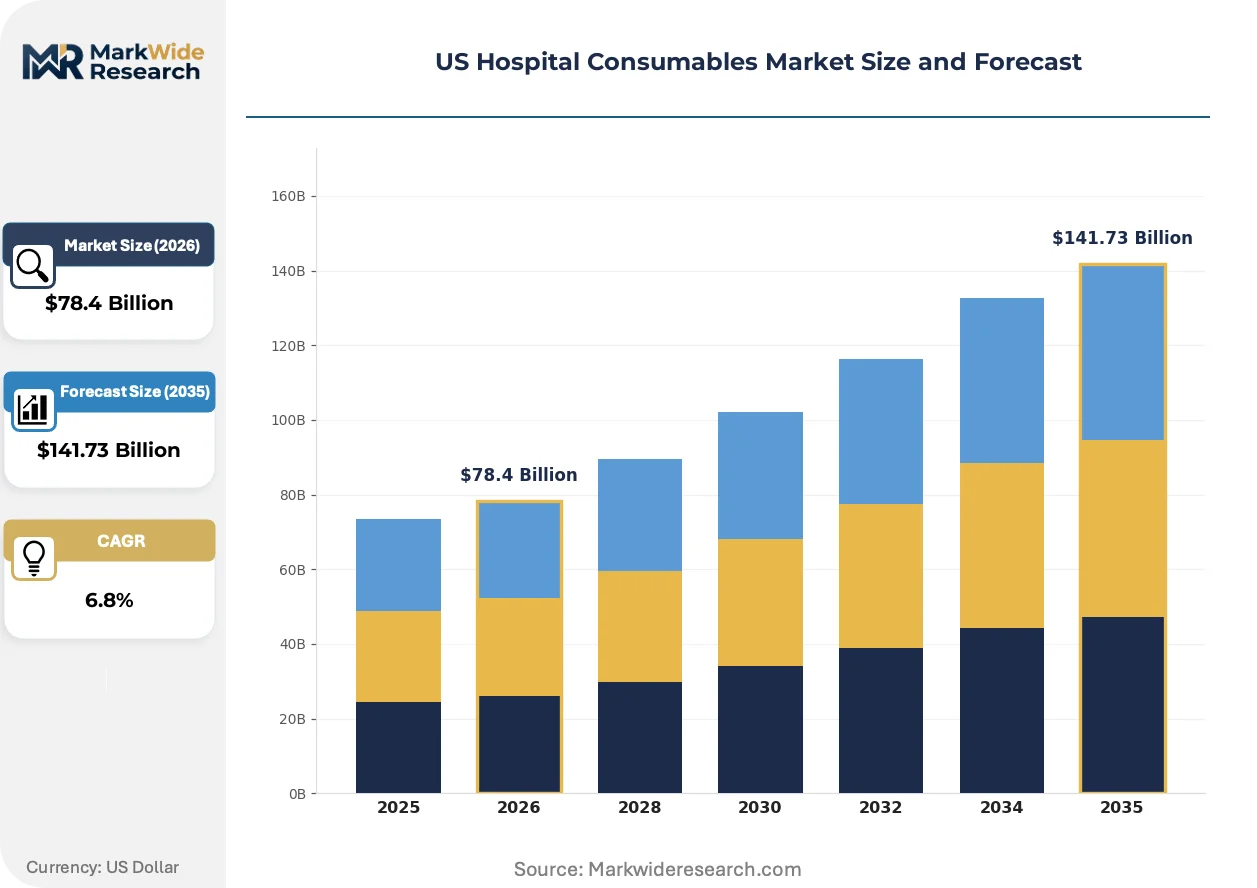
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $141.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
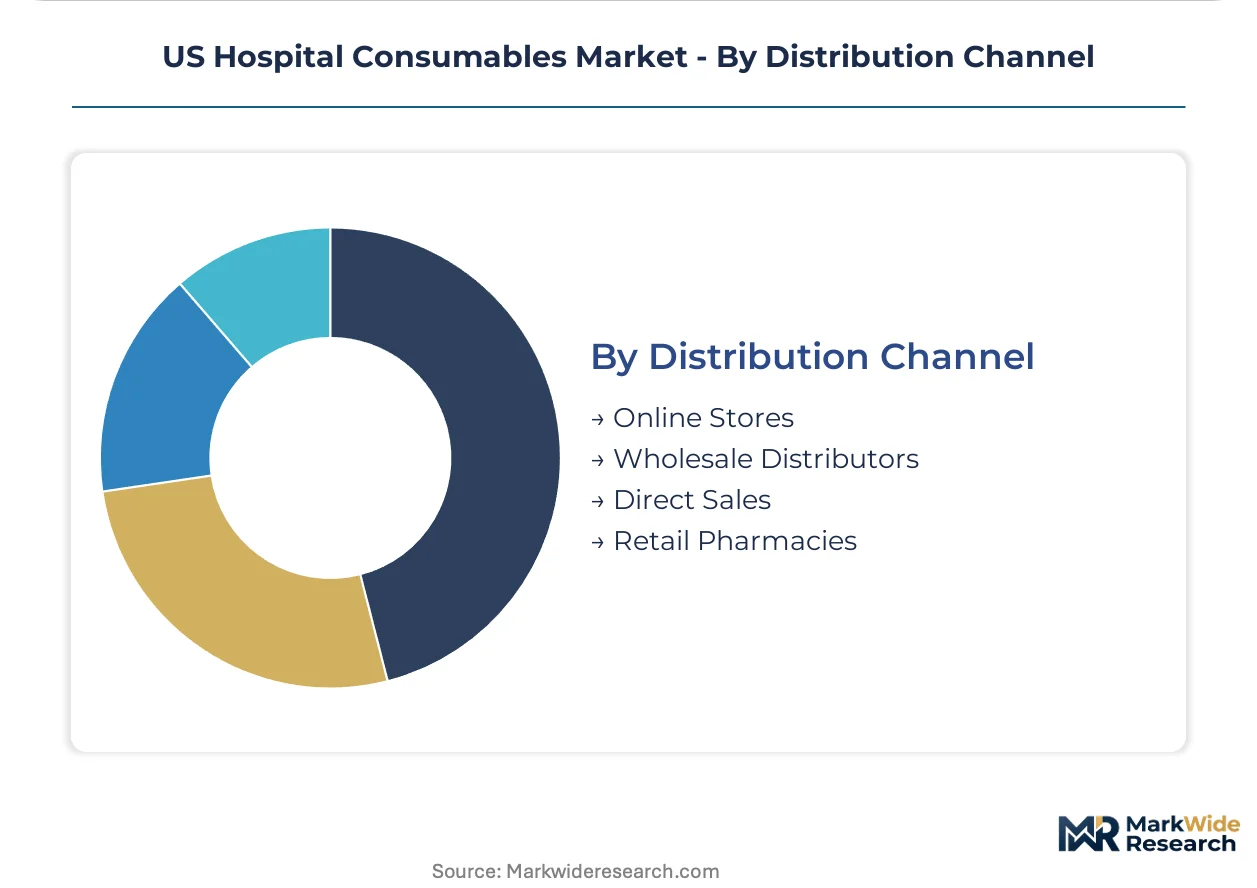
| Segmentation | Product Type: Surgical Supplies, Wound Care, Diagnostic Kits, Infusion Sets End User: Clinics, Surgical Centers, Rehabilitation Facilities, Emergency Departments Application: Patient Care, Diagnostics, Surgical Procedures, Emergency Treatment Distribution Channel: Online Stores, Wholesale Distributors, Direct Sales, Retail Pharmacies |
| Companies Covered | B. Braun Melsungen, 3M, McKesson Medical-Surgical Inc., Henry Schein Inc., Terumo Medical Corporation, Medline Industries, Inc., Owens & Minor, Smith+Nephew, Cardinal Health, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Hospital Consumables Market Trends and Innovations
Smart packaging technologies and polymer material science are converging to transform how hospitals track, deploy, and dispose of single-use medical supplies across acute and ambulatory settings.
Radio-frequency identification tags embedded in sterile barrier packaging are integrating with hospital inventory management systems to enable real-time location tracking and expiration monitoring. Large integrated delivery networks in California and Texas are mandating RFID-enabled consumables for high-value implant kits and cardiac catheterization supplies. This technology is integrating forward logistics with reverse logistics, allowing distributors to automate consignment replenishment and capture usage data for demand forecasting.
EPA sterilization emission standards are forcing ethylene oxide facilities to install catalytic oxidizer systems and relocate away from dense population centers. Medical device manufacturers dependent on contract sterilization services are diversifying across gamma, electron beam, and nitrogen dioxide alternatives to reduce regulatory risk. The surgical suture and wound closure segment faces the most acute requalification burden as facilities scramble to validate alternative sterilization modalities without compromising packaging integrity.
Hospital materials management departments are consolidating vendor relationships to reduce invoice complexity and standardize product specifications across merged entities. Multi-hospital systems in Florida are awarding exclusive distribution contracts to single-source partners willing to embed staff for inventory optimization. This concentration is most visible in cardiovascular and orthopedic service lines, where standardized physician preference cards are replacing individualized supply requests.
US Hospital Consumables Market Segmentation
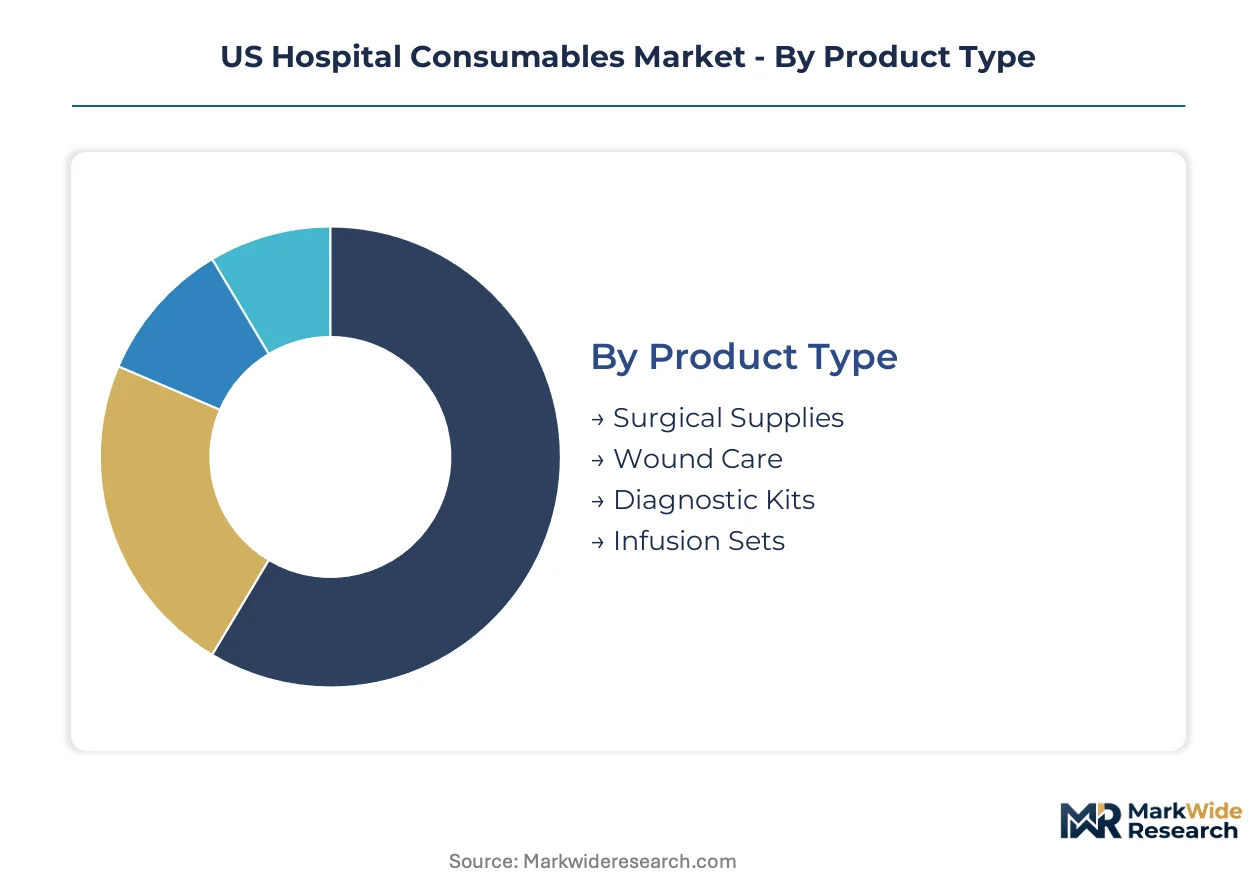
Hospital consumables segmentation reveals how procurement decisions fragment across clinical workflows, regulatory requirements, and supply chain configurations. Understanding these divides exposes where contract consolidation creates leverage and where specialty distribution retains pricing power.
Product Type:
Customization intensity varies sharply across this category, with procedure-specific configurations commanding premium positioning against commoditized alternatives.
- Surgical Supplies:Encompass sterile drapes, gowns, gloves, and instrument kits manufactured from spunbond-meltblown-spunbond polypropylene laminates. Demand concentrates in cardiovascular and orthopedic service lines within Texas and Florida hospital systems where standardized physician preference cards are replacing individualized supply requests.
- Wound Care:Includes advanced dressings, negative pressure therapy accessories, and antimicrobial gauze constructed from hydrocolloid, alginate, or silver-impregnated materials. California integrated delivery networks are driving specification consolidation toward evidence-based protocols that reduce SKU complexity across merged entities.
- Diagnostic Kits:Point-of-care testing consumables for glucose, cardiac markers, and infectious disease screening.
- Infusion Sets:IV administration tubing, needleless connectors, and smart pump-compatible sets.
Most installed capacity flows through Surgical Supplies. Expansion is steepest in Diagnostic Kits.
End User:
Volume concentration tilts toward facilities with highest procedural throughput and most complex supply chain requirements.
- Surgical Centers:Ambulatory facilities in Texas and Florida are scaling sterile consumable inventories to capture CMS outpatient reimbursement migration. These sites demand compact, procedure-specific kits that minimize sterile field contamination risk while reducing materials management labor.
- Emergency Departments:Level I trauma centers require rapid-access configurations for hemorrhage control, airway management, and resuscitation supplies. Point-of-care testing expansion is accelerating diagnostic kit consumption in these settings.
- Clinics:Primary and specialty outpatient sites with limited storage capacity.
- Rehabilitation Facilities:Post-acute settings with wound care and infusion therapy requirements.
Procurement volume aggregates at Surgical Centers. Margin expansion is most pronounced in Emergency Departments.
Application:
Clinical use case determines sterility grade, traceability requirements, and disposal classification across the product spectrum.
- Surgical Procedures:Operating room consumables must satisfy Joint Commission infection control mandates and FDA 510(k) clearance pathways. Gamma-stable thermoplastic formulations are expanding the range of devices transitioning from metal reprocessing to disposable polymer construction in these settings.
- Patient Care:General ward supplies including basic wound dressings, hygiene products, and mobility aids. Cost-constrained hospitals extend instrument life cycles here, delaying conversion to single-use alternatives.
- Diagnostics:Laboratory and point-of-care testing consumables.
- Emergency Treatment:Rapid-deployment supplies for trauma and critical care interventions.
Regulatory scrutiny intensifies around Surgical Procedures. Technology substitution is advancing fastest in Patient Care.
Distribution Channel:
Channel selection reflects hospital system scale, ERP integration maturity, and consignment inventory preferences.
- Wholesale Distributors:Cardinal Health and similar national operators leverage distribution infrastructure to serve consolidated integrated delivery networks across multi-state footprints. These relationships center on multi-year, multi-site agreements with automated reorder triggers via Epic and Cerner platform integration.
- Direct Sales:Large multi-hospital systems in Los Angeles and San Francisco are demanding procedure-specific tray configurations and embedding distributor staff for inventory optimization. This channel deepens contract pricing leverage for high-volume accounts.
- Online Stores:E-procurement platforms for standardized, low-acuity supplies.
- Retail Pharmacies:Limited role in acute care replenishment, primarily serving discharge prescription and home care transitions.
Transaction volume concentrates through Wholesale Distributors. Relationship investment is climbing fastest in Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and Japan both maintain sophisticated hospital supply ecosystems, yet the United States dominates absolute procurement volume through its fragmented but high-spending acute care infrastructure. Regional variation within the US reflects divergent reimbursement models, state-level Medicaid expansion decisions, and the geographic clustering of integrated delivery networks.
Texas
Ambulatory surgical centers in Dallas-Fort Worth and Houston are expanding sterile consumable inventories to capture CMS outpatient reimbursement migration. The Texas Medical Center complex drives concentrated demand for cardiovascular and orthopedic procedure kits. San Antonio's military health system anchors federal procurement contracts for trauma supplies.
California
Los Angeles and San Francisco integrated delivery networks are mandating procedure-specific surgical tray configurations rather than standard off-the-shelf packs. Kaiser Permanente's vertical integration shapes procurement standardization across Northern and Southern California markets. FDA 510(k) predicate device expansion accelerates clearance timelines for domestic manufacturers targeting these health systems.
Florida
Jacksonville and Tampa hospital systems are awarding exclusive distribution contracts to single-source partners willing to embed staff for inventory optimization. The state's aging demographic profile elevates demand for wound care and infusion therapy consumables. Joint Commission infection control mandates drive replacement of reusable instruments with single-use alternatives in Miami-Dade acute care facilities.
Illinois
Chicago's central sterile departments in cost-constrained safety-net hospitals extend instrument life cycles, delaying conversion to disposable alternatives. The state hosts concentrated ethylene oxide sterilization capacity, creating geographic chokepoints for national distribution. Northwestern Medicine's multi-hospital network compresses procurement cycles through consolidated purchasing decisions.
Pennsylvania
Philadelphia and Pittsburgh health systems compete for cardiovascular service line volume, driving differentiated consumable specifications. UPMC's regional dominance enables contract pricing leverage with wholesale distributors. The state's rural hospital supply deserts in central Appalachian counties create openings for regional logistics specialists with cold-chain capabilities.
US Hospital Consumables Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base organizes around three strategic archetypes: national distributors leveraging infrastructure scale, private-label manufacturers anchoring GPO-affiliated programs, and specialized logistics operators serving just-in-time operating room supply chains. Consolidation pressure from integrated delivery networks forces multi-year, multi-site contract restructuring. Capacity expansion in alternative sterilization modalities and ERP integration with Epic and Cerner platforms represent dominant competitive moves.
Among diversified health care conglomerates, 3M and Cardinal Health exemplify scale-driven positioning across multiple consumable categories. 3M occupies a position within the advanced materials tier through its spunbond-meltblown-spunbond polypropylene laminate technologies. Cardinal Health anchors the national distribution vector, serving consolidated accounts across multi-state footprints. Medline Industries, Inc. sits within the private-label specialist tier, embedding staff for inventory optimization at large multi-hospital systems.
| Leading Market Players |
|---|
| B. Braun Melsungen |
| 3M |
| McKesson Medical-Surgical Inc. |
| Henry Schein Inc. |
| Terumo Medical Corporation |
| Medline Industries, Inc. |
| Owens & Minor |
| Smith+Nephew |
| Cardinal Health |
| Others |
Pricing and Supply Chain Analysis
Polypropylene resin futures on the CME Group cascade through medical-grade polymer supply chains into three distinct pricing tiers for hospital consumables. Spot volatility in petrochemical feedstocks compresses margin predictability for molded syringes and instrument kits, forcing distributors to renegotiate annual contracts with integrated delivery networks.
Pricing Analysis
Capacity additions in Illinois and Georgia sterilization corridors are reshaping price floors for ethylene oxide-dependent product categories. Three-tier pricing structure across premium gamma-sterilized, standard EtO-processed, and economy non-critical tiers reflects certification grade and sterility assurance level. Pricing pressure stems from GPO consolidation in Texas and Florida, where multi-hospital systems extract volume discounts exceeding historical benchmarks. Critical access hospitals in rural Montana and Wyoming exhibit highest price sensitivity, while Los Angeles integrated delivery networks prioritize supply assurance over unit cost.
Supply Chain Analysis
Domestic-content mandates under the Buy American Act are reshaping sourcing patterns for federal hospital procurement. Medical-grade polymer production concentrates in Texas, Louisiana, and Ohio, with nonwoven fabric conversion anchored in South Carolina and North Carolina. Raw material dependencies rest on propylene monomer from Gulf Coast petrochemical complexes and spunbond-meltblown-spunbond laminates from domestic textile converters. Single-source vulnerability pervades ethylene oxide sterilization, where Illinois and Georgia facilities process the majority of national surgical kit volume. Distribution runs through Cardinal Health and McKesson wholesale networks with embedded inventory management at large health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through polymer sterilization technology substitution, where gamma-stable thermoplastic formulations displace metal reprocessing costs and command premium positioning.
For Market Incumbents: Hedge ethylene oxide regulatory exposure by diversifying sterilization modality partnerships across electron beam and nitrogen dioxide providers in Nevada and Arizona. Secure backward integration into medical-grade polypropylene compounding to defend margin position against resin price volatility. Embed clinical supply chain staff at Florida hospital systems to lock in exclusive distribution contracts before GPO consolidation completes.
For New Entrants and Emerging Players: Rural critical access hospitals in Wyoming and Montana present underserved buyer archetypes lacking distributor density and cold-chain capabilities. Target procedure-specific surgical kit customization for California integrated delivery networks demanding physician preference card standardization. Pursue FDA 510(k) streamlined pathways for low-risk consumables to accelerate OR supply contract penetration.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized logistics operators possessing Epic and Cerner ERP integration capabilities. Five-to-ten year viability favors regional distributors with sterile packaging engineering talent and alternative sterilization validation expertise. Monitor CMS outpatient reimbursement migration rates as the inflection signal for ambulatory surgical center consumable volume shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Alternative Sterilization Capacity Buildout | Electron beam and nitrogen dioxide investments reduce EPA regulatory risk exposure for surgical suture manufacturers. |
| ERP Platform Integration | API connections to Epic and Cerner enable automated consignment replenishment and usage data capture. |
| Procedure-Specific Kit Customization | California health system demands for standardized physician preference cards replace off-the-shelf surgical packs. |
| Private-Label GPO Program Expansion | Medline Industries anchors multi-year contracts with integrated delivery networks seeking invoice complexity reduction. |
| Rural Cold-Chain Logistics Investment | Montana and Wyoming critical access hospitals lack distributor density for temperature-sensitive consumables. |
Research Methodology
Direct dialogue with hospital purchasing committee chairs, GPO contracts managers, biomedical engineers, and sterile processing department directors grounded qualitative findings. Secondary validation drew from FDA 510(k) clearance databases, CMS Medicare cost report filings, GPO contract award notices, and hospital procurement system disclosures. Bottom-up demand modeling across product type, end user, and application segments triangulated against top-down distributor revenue attribution.
Segment-level volume and value trajectories emerged from procedure volume projections, site-of-care migration patterns, and sterilization capacity utilization modeling across the analysis window. CAGRs derived from regression analysis of historical procurement data against Joint Commission accreditation trends and polymer feedstock price indices. Forecast inputs incorporated ambulatory surgical center expansion timelines, FDA predicate device expansion rates, and integrated delivery network consolidation velocity.
Underlying measurement precision varies by segment; surgical supplies and wound care carry tighter precision than emerging diagnostic kit categories. Forecasts embed assumptions regarding CMS reimbursement stability, EPA sterilization emission enforcement consistency, and petrochemical feedstock price correlation persistence. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Australia Hospital Supplies Market
Medical Supplies
Steam Sterilizer Bag Market
Medical Supplies
Forensic Swabs Market
Medical Supplies
Compression Socks Market
Medical Supplies
Europe Ostomy Drainage Bags Market
Medical Supplies
Continuous Ambulatory Peritoneal Dialysis Bags Market
Medical Supplies
GCC Syringes and Needles Market
Medical Supplies
Face Mask Market
Medical Supplies
Global Nasal Aspirator Market
Medical Supplies
Disposable Masks Market
Medical Supplies
Global Enema Bags Market
Medical Supplies
External Nasal Dilator and Nasal Strip Market
Medical Supplies
Diagnostic Vials Market
Medical Supplies
Disposable Hospital Gowns Market
Medical Supplies
Cosmetic Pipette Market
Medical Supplies
Plastic Bandages Market