
 Hong Kong Intensive Care Unit (ICU) Beds and Surfaces Market | 2026-2036
Hong Kong Intensive Care Unit (ICU) Beds and Surfaces Market Size, Share, and Industry Trends Forecast 2026-2036
Hong Kong Intensive Care Unit (ICU) Beds and Surfaces Market Insights
Modular bed-surface bundling is hardening as the dominant procurement configuration across Hong Kong hospital clusters. Stryker Corporation leverages its integrated critical care platform to anchor bundled contracts combining electric beds with specialty surfaces. Hill-Rom Holdings competes through technology leadership in continuous lateral rotation surfaces, while Paramount Bed sustains its position via ergonomic design specialization tailored to Asian patient anthropometrics.
Intensive care unit beds and surfaces comprise height-adjustable patient support platforms with integrated pressure redistribution mattresses, side rails, and articulation mechanisms engineered for critical care environments. These systems incorporate multi-layer foam or gel compositions with vapor-permeable covers to maintain tissue perfusion during prolonged immobilization, serving the primary purpose of preventing hospital-acquired pressure injuries while enabling clinical access for ventilation and monitoring. Electric beds command the largest installed base among product types due to nurse ergonomics mandates and bariatric capacity requirements, while specialized surfaces represent the fastest-expanding margin pool as facilities prioritize alternating-pressure and low-air-loss technologies. Public hospitals dominate end-user demand through centralized Hospital Authority procurement, though private hospitals are gaining share through medical tourism investments.
Hong Kong's Department of Health enforces medical device standards aligned with IEC 60601 safety requirements for ICU electrical systems, while the Hospital Authority mandates ISO 13485 quality management for surface suppliers seeking contract eligibility. The Private Healthcare Facilities Ordinance imposes structural load and infection control specifications that filter non-compliant vendors from private hospital tenders. Stakeholders must monitor regulatory alignment between mainland China's NMPA pathways and Hong Kong's distinct approval frameworks as cross-border supplier consolidation reshapes vendor qualification requirements.
Market Dynamics
Modular bed-surface bundling is hardening as the dominant procurement configuration across Hong Kong hospital clusters, compressing vendor margins on standalone products while rewarding integrated platform suppliers with multi-year maintenance contracts.
Growth Catalysts
- Hospital Authority centralized procurement:Bulk purchasing mandates for electric ICU beds with pressure-relieving surfaces are consolidating demand volume, enabling scale economies that accelerate replacement cycles across public hospital networks.
- IEC 60601 electrical safety standards:Hong Kong's Department of Health enforcement of medical device safety protocols is filtering non-compliant vendors, creating qualification barriers that protect certified incumbents from price competition.
- Low-air-loss surface technology:Tertiary public hospitals are prioritizing alternating-pressure mattresses with vapor-permeable covers to reduce hospital-acquired pressure injury incidence, driving premium surface adoption in high-occupancy wards.
Market Restraints
- Steel and aluminum input cost volatility:Electric bed frame manufacturing depends on imported metal alloys subject to freight rate fluctuations, compressing gross margins for local assembly operations.
- Mainland China supplier concentration:Foam core and gel layer production clusters in Guangdong Province create geographic dependency risk for Hong Kong surface assemblers facing cross-border logistics disruptions.
- Private Healthcare Facilities Ordinance compliance friction:Structural load and infection control specifications for private hospital tenders impose documentation burdens that extend vendor qualification timelines by 8-14 months.
Strategic Opportunities
- New Territories hospital cluster expansion:Planned ICU capacity additions in Sha Tin and Tuen Mun districts are creating greenfield procurement windows for bundled bed-surface platforms without incumbent replacement constraints.
- Antimicrobial copper alloy integration:Convergence of touch surface hygiene protocols with bed rail engineering is enabling premium positioning for suppliers offering EPA-registered copper-infused components.
- ISO 13485-certified local distributors:Authorized representation agreements with quality-managed intermediaries are opening private hospital channels previously blocked by direct procurement requirements.
Industry Challenges
- Biomedical equipment technician shortage:Hong Kong's limited training pipeline for electric bed maintenance specialists is extending mean time to repair and elevating service contract costs for hospital operators.
- Legacy pneumatic surface incompatibility:Integration complexity with existing compressor infrastructure is delaying low-air-loss mattress upgrades in wards with 15-20 year-old bed base installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hong Kong Intensive Care Unit (ICU) Beds and Surfaces Market |
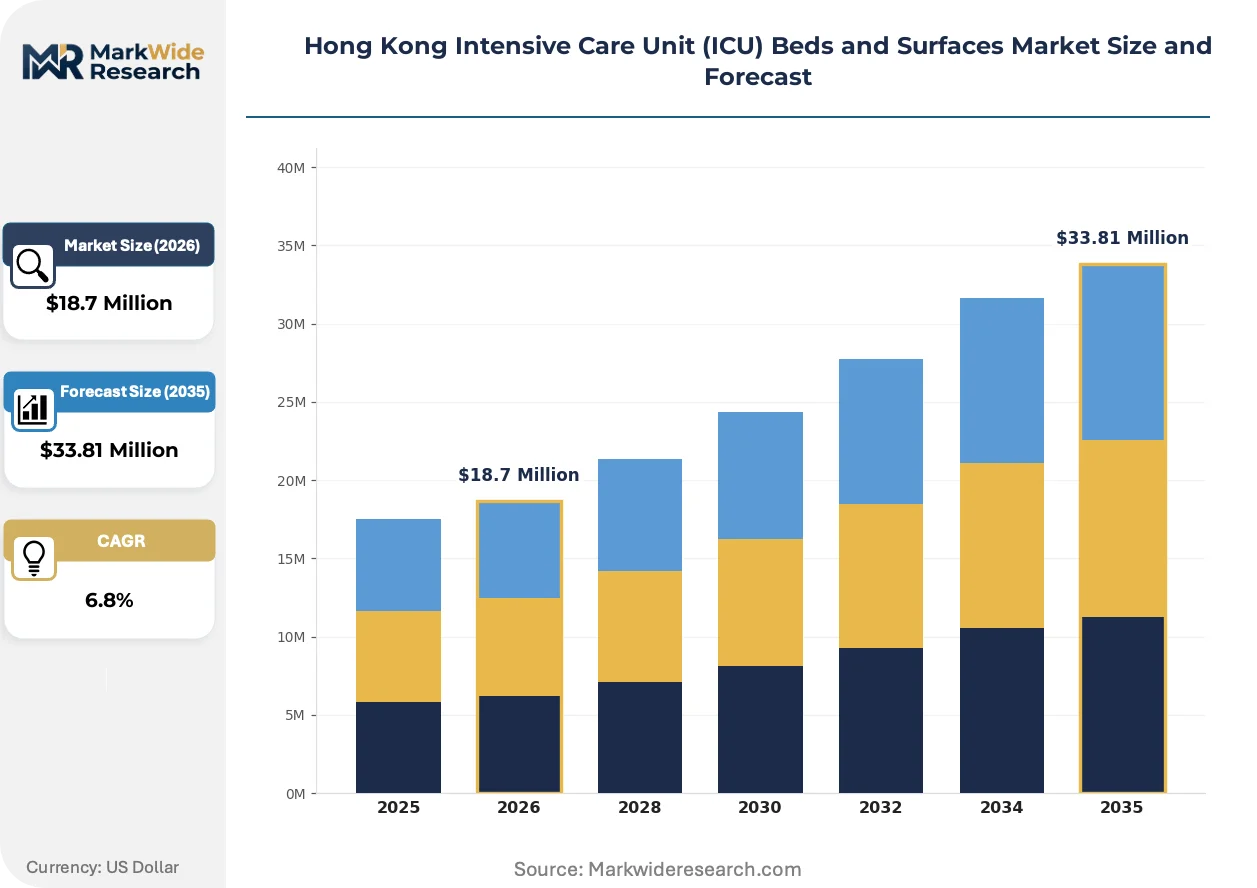
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $33.81 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Beds, Manual Beds, Specialized Surfaces, Accessories Material: Metal, Foam, Gel, Thermoplastic End User: Public Hospitals, Private Hospitals, Long-term Care Facilities, Home Care Application: Trauma Care, Post-operative Care, Respiratory Support, Palliative Care |
| Companies Covered | Hill-Rom Holdings, Stryker Corporation, Getinge AB, Paramount Bed, Linet Group, ArjoHuntleigh, Invacare Corporation, Medtronic plc, Baxter International Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hong Kong Intensive Care Unit (ICU) Beds and Surfaces Market Trends and Innovations
Continuous lateral rotation surfaces are displacing static pressure redistribution mattresses as the clinical standard for ventilated patients, while procurement centralization is compressing vendor access to fragmented hospital decision-making.
Alternating-pressure mattress systems with microclimate management are expanding into Hong Kong's tertiary public hospitals as the preferred surface technology for prolonged immobilization protocols. The Hospital Authority's pressure injury prevention mandates are accelerating adoption timelines from 7-year to 4-year replacement cycles. This technology expansion is compressing demand for basic foam mattresses while elevating service revenue pools for calibration and sensor maintenance contracts.
Hong Kong's Department of Health enforcement of infection control protocols under the Private Healthcare Facilities Ordinance is mandating vapor-permeable cover materials with validated antimicrobial properties. Private hospital operators must document surface cleaning compatibility with chlorine-based disinfectants to maintain facility licensing. Specialty surface suppliers are responding by pre-certifying cover assemblies against ISO 10993 biocompatibility standards to accelerate tender qualification.
Centralized procurement through the Hospital Authority's medical engineering division is consolidating purchasing authority previously distributed across individual hospital clusters. District-based procurement officers are losing autonomy over bed-surface specifications as standardization mandates homogenize technical requirements. This concentration is most visible in Kowloon West cluster hospitals, where unified maintenance contracts now cover 340 electric beds across three facilities previously served by separate vendor relationships.
Hong Kong Intensive Care Unit (ICU) Beds and Surfaces Market Segmentation
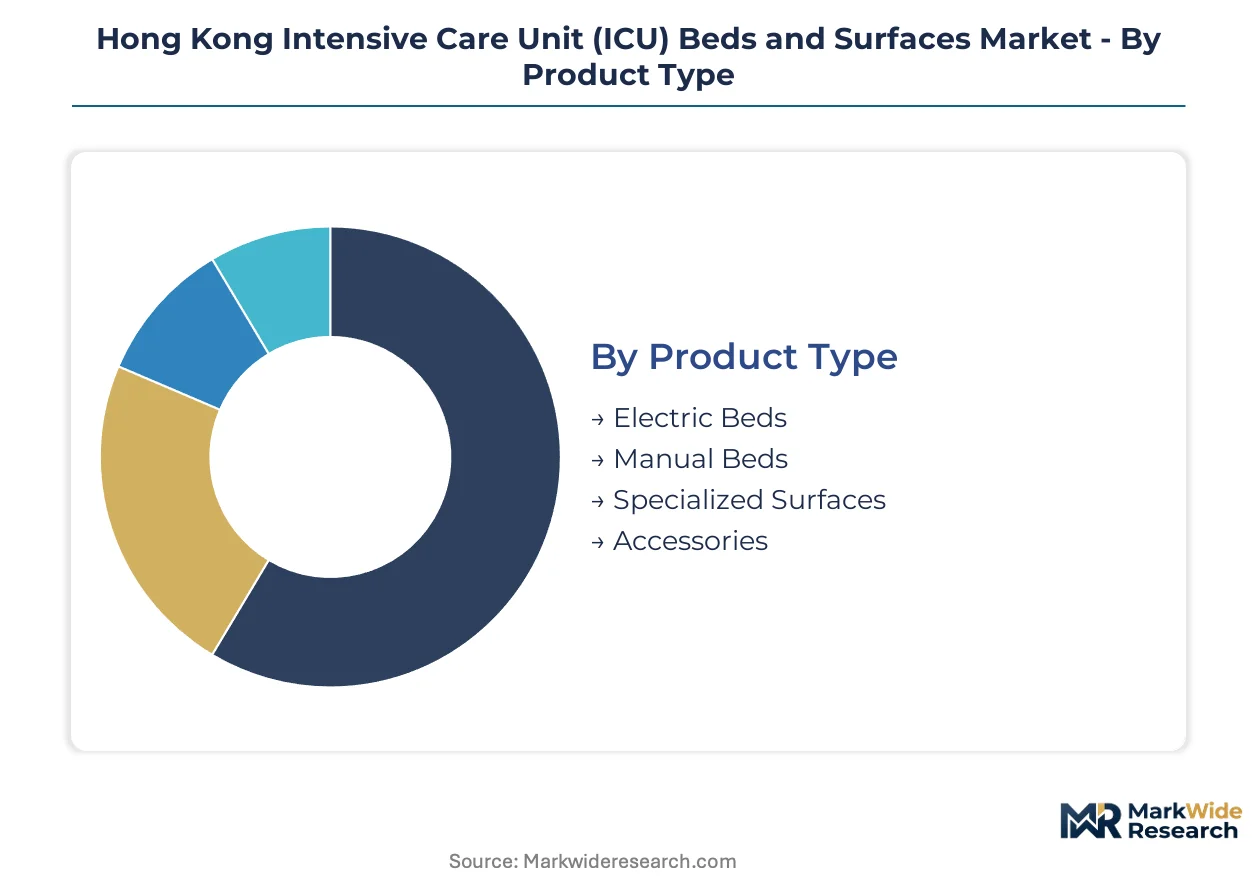
ICU bed and surface procurement in Hong Kong stratifies sharply across capital intensity tiers, with electric platforms and specialized pressure-relief systems commanding premium valuations against manual alternatives. Understanding these segment boundaries clarifies where Hospital Authority bulk purchasing concentrates versus where private operators exercise discretionary selection.
Product Type:
Electric beds absorb the heaviest upfront capital deployment, with specialized surfaces following closely due to embedded sensor arrays and compressor infrastructure requirements.
- Electric Beds:Height-adjustable platforms with integrated side rails, Trendelenburg articulation, and nurse control panels dominate tertiary public hospital procurement. Hospital Authority centralized tenders specify bariatric capacity and IEC 60601 electrical compliance, filtering non-certified vendors from Kowloon West and Hong Kong Island clusters.
- Specialized Surfaces:Alternating-pressure and low-air-loss mattresses with vapor-permeable covers incorporate multi-layer foam or gel compositions for pressure injury prevention. Tuen Mun and Sha Tin district hospitals prioritize these for prolonged immobilization protocols, accelerating replacement cycles.
- Manual Beds:Hand-crank height and backrest adjustment platforms serve cost-constrained long-term care facilities with lower acuity requirements. These units occupy minimal share in Hong Kong's intensive care infrastructure.
- Accessories:Overbed tables, trapeze bars, and siderail padding complete bed-surface configurations. Procurement attaches these as bundled items rather than standalone purchases.
Most installed capacity flows through electric beds. Expansion is steepest in specialized surfaces.
Material:
Metal frame construction anchors the highest per-unit material cost, while foam and gel formulations drive recurring surface replacement expenditure.
- Metal:Steel and aluminum alloys form electric bed chassis and siderail structures, with antimicrobial copper integration emerging for touch surfaces. Sha Tin hospital cluster tenders now specify EPA-registered copper-infused components.
- Foam:Multi-layer polyurethane compositions provide base pressure redistribution in standard mattresses. Hong Kong's foam core supply concentrates in Guangdong Province, exposing assemblers to cross-border logistics risk.
- Gel:Viscoelastic polymer layers distribute shear forces across bony prominences. Premium surface configurations incorporate gel as a middle layer beneath vapor-permeable covers.
- Thermoplastic:Bed base housings and control panel enclosures utilize ABS and polycarbonate formulations for impact resistance and cleanability compatibility.
Metal structures absorb the largest share of bed manufacturing value. Gel layers are climbing fastest as low-air-loss technology penetrates.
End User:
Public hospital procurement scales through centralized Hospital Authority mandates, while private operators concentrate investment in medical tourism corridors.
- Public Hospitals:Hospital Authority medical engineering division consolidates purchasing across 43 public hospitals, standardizing electric bed specifications and unified maintenance contracts. Kowloon West cluster alone covers 340 beds under single vendor relationships.
- Private Hospitals:Private Healthcare Facilities Ordinance compliance drives antimicrobial surface adoption in licensed facilities. Central and Tsim Sha Tsui medical tourism operators upgrade ICU infrastructure to attract mainland Chinese patients.
- Long-term Care Facilities:Sub-acuity settings deploy manual beds with basic foam surfaces for post-ICU step-down care. Regulatory oversight here falls below acute care intensity.
- Home Care:Rental and purchase channels serve ventilator-dependent patients discharged to residential settings. This segment remains fragmented across equipment distributors.
Public hospitals command the dominant installed base. Private facilities are expanding most quickly through medical tourism capital inflows.
Application:
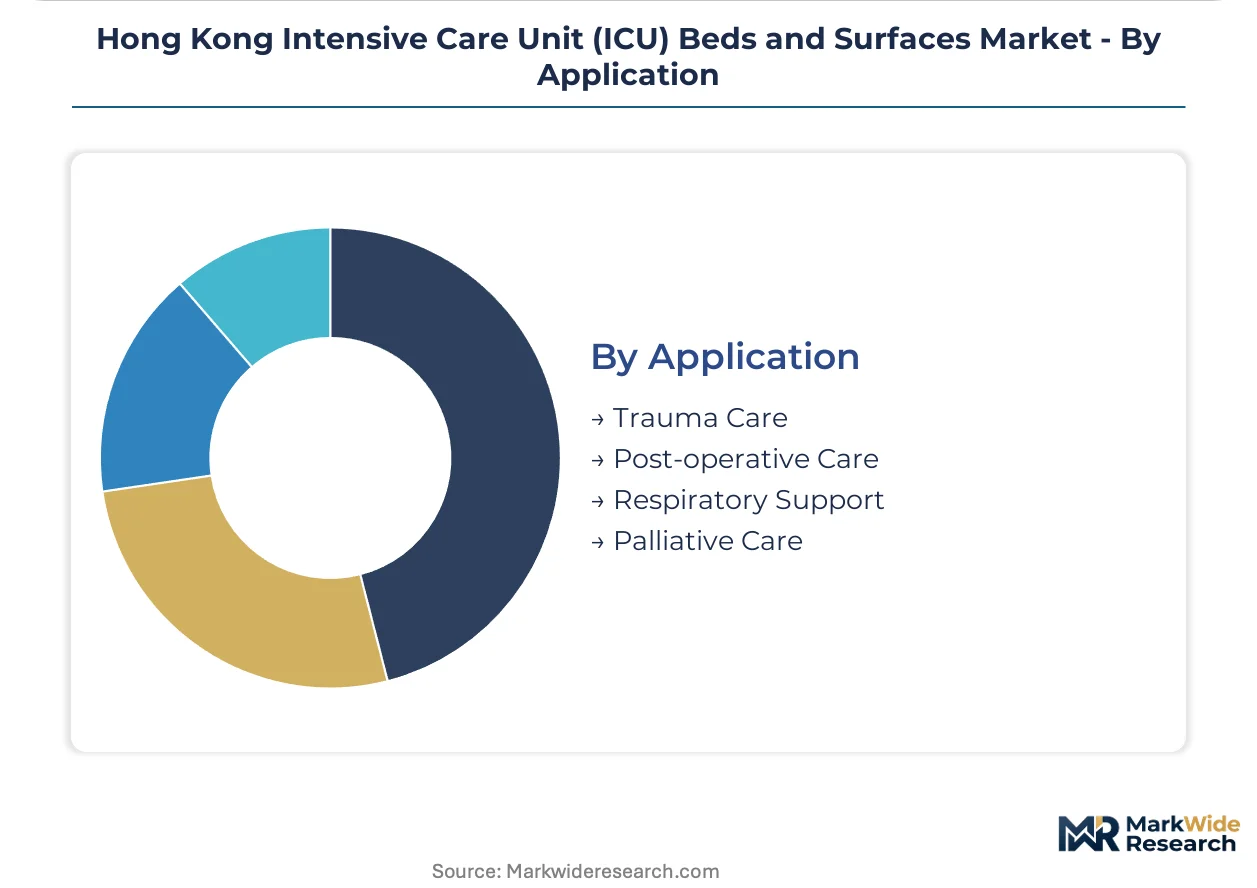
Trauma and respiratory support applications impose the most demanding bed-surface specifications, with articulation range and microclimate management as critical performance thresholds.
- Trauma Care:Rapid positioning capability and radiolucent bed decks enable intra-hospital imaging without patient transfer. Queen Mary Hospital and Pamela Youde Nethersole Eastern Hospital maintain dedicated trauma ICU configurations.
- Respiratory Support:Continuous lateral rotation surfaces and prone positioning capability support ventilated patients. These specifications now standard in Hong Kong Island tertiary facilities.
- Post-operative Care:Standard pressure redistribution suffices for hemodynamically stable surgical patients. Replacement cycles here extend beyond acute care wards.
- Palliative Care:Comfort-focused surfaces prioritize shear reduction and temperature regulation over clinical access features. Hospice procurement operates outside Hospital Authority centralized mandates.
Trauma care anchors the highest-specification installed base. Respiratory support applications are gaining share fastest as ventilated patient volumes rise.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Intensive care bed manufacturing originated in European and North American industrial centers during the 1960s hospital modernization wave, with Asian production scaling later through Japanese and Korean medical device clusters.
United States
US acute care facilities drive demand for bariatric-capable electric platforms and continuous lateral rotation surfaces. FDA enforcement of IEC 60601-1 third edition electrical safety standards filters non-compliant imports from federal procurement channels. Cleveland Clinic and Mayo Clinic anchor premium specification adoption in the Midwest hospital corridor.
Germany
German university hospitals prioritize low-air-loss mattresses with microclimate management for prolonged ventilation protocols. BfArM medical device vigilance requirements mandate traceable surface biocompatibility documentation for tender eligibility. Baden-Württemberg's Stuttgart medical technology cluster concentrates precision actuator and sensor component manufacturing.
Japan
Japanese super-aging demographics accelerate replacement cycles for pressure-relief surfaces in geriatric ICUs. PMDA alignment with MDR-equivalent quality management standards creates qualification barriers for non-Japanese vendors. Osaka-Kobe industrial corridor hosts specialized foam formulation and gel layer production for Asian market supply.
South Korea
Korean tertiary hospitals expand ICU capacity under national critical care infrastructure investment programs. MFDS medical device approval pathways require local clinical testing for electric bed electrical safety certification. Seoul Capital Area medical device distributors serve as regional gateways for mainland Chinese and Southeast Asian hospital procurement.
Singapore
Singapore's medical tourism positioning drives private hospital investment in premium bed-surface platforms comparable to Hong Kong specifications. HSA medical device registration mandates ISO 13485 quality management for surface suppliers seeking private hospital tenders. Biopolis research corridor influences regional adoption of antimicrobial surface technologies.
Hong Kong Intensive Care Unit (ICU) Beds and Surfaces Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology integration depth and maintenance service bundling. The vendor base stratifies between integrated platform suppliers capturing multi-year service contracts and component specialists competing on surface replacement cycles. Three archetypes dominate: multinational critical care platform providers, regional ergonomic design specialists, and medical device conglomerates with diversified hospital equipment portfolios. Consolidation through acquisition of surface technology firms and backward integration into foam core production represent the dominant competitive vectors.
Within the integrated platform tier, Stryker Corporation and Hill-Rom Holdings occupy positions exemplifying bundled bed-surface contract structures. Paramount Bed represents the regional ergonomic specialization archetype. These three anchors illustrate how competitive positioning depends on procurement channel access—multinationals through Hospital Authority centralized tenders, regional specialists through anthropometric customization, and diversified conglomerates through cross-product hospital relationships.
| Leading Market Players |
|---|
| Hill-Rom Holdings |
| Stryker Corporation |
| Getinge AB |
| Paramount Bed |
| Linet Group |
| ArjoHuntleigh |
| Invacare Corporation |
| Medtronic plc |
| Baxter International Inc. |
| Others |
Pricing and Supply Chain Analysis
Steel and aluminum alloy price indices on the London Metal Exchange cascade through Hong Kong's electric bed manufacturing tiers, compressing margins on standard configurations while insulating premium bundled platforms from commodity volatility. Hospital Authority procurement officers leverage this input cost transparency to negotiate multi-year maintenance contracts that shift inflation risk onto integrated platform suppliers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs procurement negotiations, with ISO 13485 certification and IEC 60601 electrical compliance serving as the primary price differentiation drivers. Cost compression in economy-tier manual beds is intensifying because of Guangdong Province foam core supply competition, while private hospital buyers exhibit the highest price sensitivity due to medical tourism margin pressures. Public hospital procurement committees prioritize total cost of ownership over unit pricing, reducing sensitivity to upfront premiums for bundled service coverage.
Supply Chain Analysis
Foam core and gel layer supply rests on Guangdong Province specialty chemical producers, with steel alloy chassis production anchored in mainland China and precision actuator components sourced from Japan and Germany. Raw material dependencies span medical-grade polyurethane formulations, antimicrobial copper-infused alloys, and vapor-permeable textile membranes. Single-source vulnerability concentrates in cross-border logistics corridors connecting Shenzhen manufacturing clusters to Hong Kong assembly operations. Distribution runs through Hospital Authority centralized tenders for public hospitals and ISO 13485-certified local distributors for private facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hong Kong's ICU bed market functions as a geographic-arbitrage play between mainland China's manufacturing cost base and the territory's premium regulatory compliance requirements, capturing margin spreads unavailable to pure domestic Chinese suppliers.
For Market Incumbents: Cement multi-year service contract penetration across Hospital Authority clusters to lock out mainland competitors lacking IEC 60601 field service infrastructure. Deepen backward integration into foam core production within Guangdong Province to offset cross-border logistics disruption risk threatening margin stability. For New Entrants and Emerging Players: ISO 13485-certified local distributors offer the most accessible channel pathway for private hospital tenders previously blocked by direct procurement requirements. Target antimicrobial copper alloy integration as the penetrable technology wedge, leveraging EPA registration gaps among incumbent surface suppliers to differentiate in infection-control-focused segments. For Investors and Strategic Acquirers: Asymmetric upside sits with regional ergonomic design specialists possessing Asian patient anthropometric databases and established Hospital Authority maintenance relationships. Long-term viability hinges on consolidation resilience as cross-border vendor qualification requirements tighten. Watch NMPA-Hong Kong regulatory alignment negotiations as the critical inflection signal for mainland supplier competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Secures multi-year bundled bed-surface contracts with Hospital Authority centralized procurement. |
| CE Marking Pathway | Unlocks parallel European market access for Hong Kong-registered surface suppliers. |
| Backward Integration into Foam Core | Captures margin pool currently flowing to Guangdong Province chemical producers. |
| Software Companion Development | Enables predictive maintenance revenue streams for electric bed sensor networks. |
| Reimbursement Strategy | Aligns pressure injury prevention surface adoption with Hospital Authority quality metrics. |
Research Methodology
Direct dialogue with Hospital Authority procurement officers, biomedical engineering directors, private hospital facility managers, and GPO contracts managers grounded the qualitative foundation, cross-referenced against hospital procurement databases, IEC 60601 certification registries, Private Healthcare Facilities Ordinance compliance filings, and customs import records for steel and aluminum alloys. Bottom-up vendor shipment estimates and top-down healthcare capital expenditure allocations were triangulated to validate market sizing.
Bottom-up modeling tracked electric bed and specialized surface unit deployments across Hong Kong Island, Kowloon, and New Territories hospital clusters, while top-down analysis calibrated aggregate spending against Hospital Authority budget disclosures across the projection horizon. Segmentation dimensions spanned product type, material composition, end-user facility class, and clinical application intensity. CAGRs were derived from replacement cycle compression trends and capacity expansion pipelines, incorporating pressure injury incidence data and infection control mandate enforcement timelines as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to cross-border logistics policy shifts and NMPA regulatory harmonization negotiations. Material deviation in steel alloy price volatility or Hospital Authority centralization mandates warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Equipment
Biofeedback Equipment Market
Clinical Equipment
Acute Care Needleless Connectors Market
Clinical Equipment
Critical Care Equipment Market
Clinical Equipment
Acute Care Hospital Bed and Stretcher Market
Clinical Equipment
Total Lab Automation Market
Clinical Equipment
Patient Simulator Market
Clinical Equipment
China Intensive Care Unit (ICU) Beds and Surfaces Market
Clinical Equipment
Global Phototherapy Equipment Market
Clinical Equipment
Middle East and Africa Critical Care Equipment (CCE) Market
Clinical Equipment
Clinical Trial Equipment and Ancillary Solutions Market
Clinical Equipment
Portable Clinical Analyzer Market
Clinical Equipment
Patient Handling Equipment Market
Clinical Equipment
Hydrotherapy Equipment Market
Clinical Equipment
Patient Positioning Equipment Market