
 Global Cardiopulmonary Stress Testing Systems Market | 2026-2036
Global Cardiopulmonary Stress Testing Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cardiopulmonary Stress Testing Systems Market Intelligence
The EU Medical Device Regulation is decoupling market access from legacy CE certifications, forcing manufacturers to rebuild clinical dossiers. GE Healthcare leverages its installed base of metabolic carts to sustain service revenue across European hospital networks. Koninklijke Philips N.V. anchors its position through integrated ECG-spirometry platforms that dominate North American academic medical centers. COSMED Srl specializes in portable breath-by-breath systems that compete on precision in sports medicine and pulmonary rehabilitation settings.
Cardiopulmonary stress testing systems comprise integrated diagnostic platforms that measure cardiac, ventilatory, and metabolic responses to controlled exercise or pharmacological provocation, typically quantifying parameters such as VO2 max, anaerobic threshold, and respiratory exchange ratio through breath-by-breath gas analysis. These systems serve primarily to stratify cardiovascular risk, quantify functional capacity, and guide therapeutic decisions in heart failure, coronary artery disease, and chronic obstructive pulmonary disease. Treadmill stress test configurations retain the largest installed base due to familiarity among cardiologists and established procedural protocols, while metabolic analysis technology captures expanding margin pools as hospitals seek to consolidate multiple physiological measurements into single-platform workflows. Cycle ergometer systems represent the fastest-growing product configuration in pulmonary and rehabilitation settings where seated positioning optimizes ventilatory mechanics assessment.
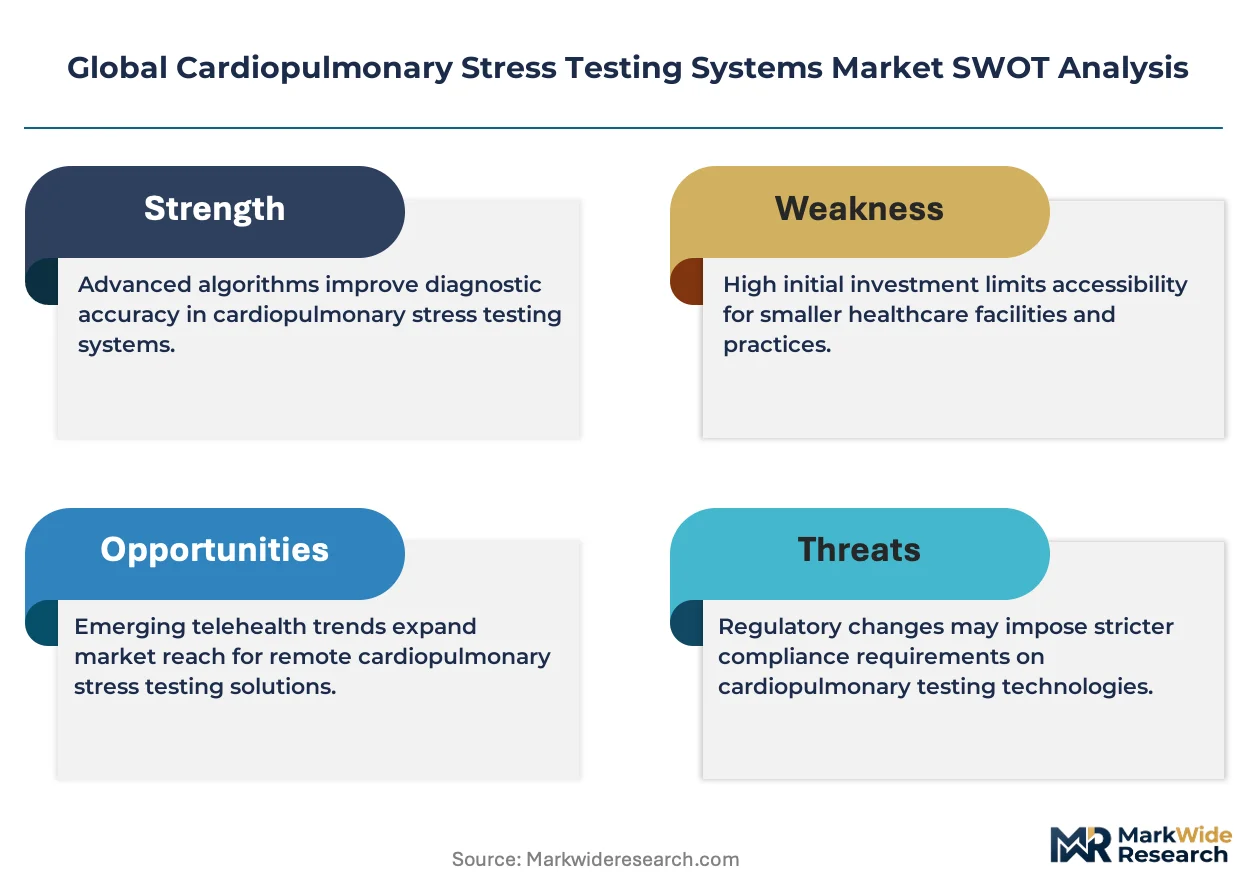
FDA 510(k) premarket notification and EU MDR conformity assessment shape product development timelines and clinical evidence requirements for manufacturers seeking commercial access in the United States and European Union. Japan's PMDA enforces stringent electrical safety and software validation standards that filter market entrants and elevate quality benchmarks across the Asia-Pacific supply base. ISO 13485 quality management and IEC 60601-1 third-edition safety standards provide the foundational compliance architecture that regulators in Germany, France, and Switzerland reference during national approvals. Stakeholders must monitor how evolving MDR notified body capacity constraints and FDA breakthrough device designations redistribute competitive advantage between established multinationals and agile specialized manufacturers.
Market Dynamics
EU MDR recertification deadlines are compressing product development cycles and forcing manufacturers to rebuild clinical evidence dossiers from legacy CE-marked platforms, redistributing competitive advantage toward firms with established notified body relationships and deeper regulatory affairs capabilities.
Growth Catalysts
- Integrated metabolic analysis platforms:Hospitals in Germany and Japan are consolidating multiple physiological measurements into single-workflow systems to reduce capital expenditure and staff training burdens.
- FDA 510(k) pathway modernization:Streamlined premarket notification processes for software-as-medical-device components are accelerating iterative updates to breath-by-breath analysis algorithms.
- Aging demographic clusters:Cardiology clinics across the United States are replacing decade-old treadmill configurations to meet rising diagnostic volumes from Medicare-eligible populations.
Market Restraints
- Notified body capacity constraints:EU MDR implementation bottlenecks are extending conformity assessment timelines to 18-24 months for Class IIa diagnostic platforms.
- Cycle ergometer supply concentration:Precision electromagnetic braking systems rely on a narrow supplier base concentrated in Switzerland and northern Italy.
- Pharmacological stress agent substitution:Dobutamine and regadenoson protocols face displacement from coronary CT angiography in intermediate-risk patient stratification.
Strategic Opportunities
- Home-based pulmonary rehabilitation:Portable telemetry systems with cellular connectivity are penetrating post-acute care settings in Australia where reimbursement codes now cover remote monitoring.
- AI-ECG integration:Machine learning algorithms for real-time arrhythmia detection during exercise are converging with traditional gas exchange analysis to create premium diagnostic bundles.
- Sports medicine expansion:Olympic training centers and professional football clubs in Brazil are adopting precision breath-by-breath systems for athlete performance optimization.
Industry Challenges
- Clinical engineering talent scarcity:Hospitals struggle to recruit technicians proficient in both respiratory physiology and embedded software troubleshooting for integrated metabolic carts.
- Legacy system interoperability:DICOM and HL7 FHIR integration with hospital information systems requires costly middleware development for multi-vendor environments.
- ISO 13485 audit backlogs:Quality management recertification delays are freezing product registrations in multiple Asia-Pacific markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cardiopulmonary Stress Testing Systems Market |
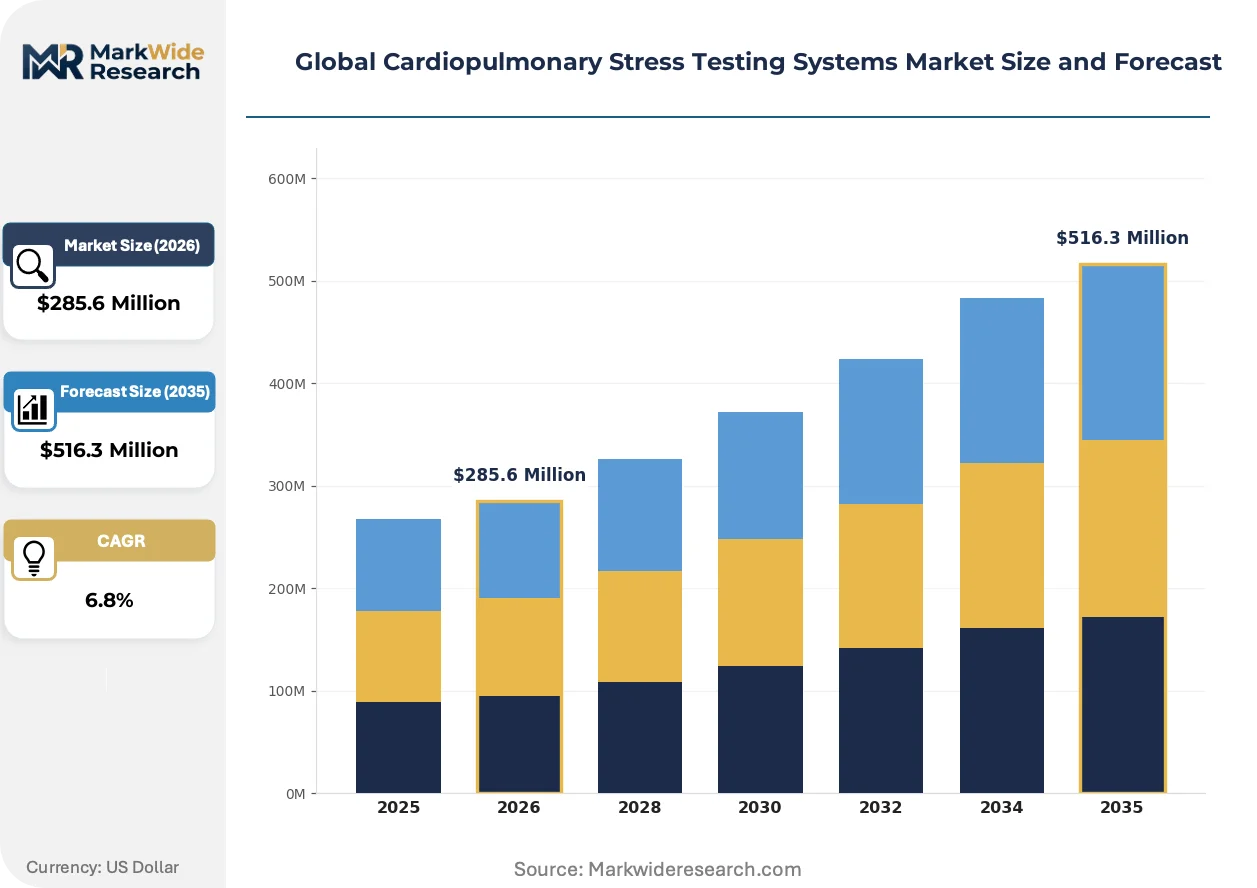
| Market Size in 2026 | $285.6 Million |
| Market Size in 2035 | $516.3 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Treadmill Stress Test, Cycle Ergometer, Exercise Stress Test, Pharmacological Stress Test Technology: Electrocardiography, Spirometry, Metabolic Analysis, Pulse Oximetry, Blood Pressure Monitoring Application: Cardiac Disease Diagnosis, Pulmonary Evaluation, Functional Capacity Assessment, Rehabilitation Monitoring End User: Cardiology Clinics, Pulmonary Centers, Rehabilitation Facilities, Sports Medicine Clinics |
| Companies Covered | GE Healthcare, Koninklijke Philips N.V., MGC Diagnostics Corporation, COSMED Srl, Nihon Kohden Corporation, Schiller AG, Vyaire Medical Inc., Spacelabs Healthcare, SunTech Medical, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cardiopulmonary Stress Testing Systems Market Strategic Shifts & Innovations
Breath-by-breath gas analysis technology is electrifying competitive positioning as manufacturers race to embed real-time metabolic computation into compact, wearable-adjacent form factors.
Wireless capnography and oxygen uptake sensors are electrifying the traditional tethered laboratory model. Academic medical centers in the United States are piloting Bluetooth-enabled metabolic carts that untether patients from fixed analyzer positions. This architecture is electrifying demand for cloud-native data platforms that synchronize ventilatory measurements with electronic health record workflows.
Japan's PMDA has tightened electrical safety and software validation standards for devices incorporating artificial intelligence components. Manufacturers must now submit standalone algorithm performance dossiers alongside hardware submissions. Cycle ergometer systems with embedded arrhythmia detection are most affected, with several firms establishing Tokyo-based regulatory affairs subsidiaries to manage iterative validation protocols.
After-sales service unbundling is fragmenting traditional equipment procurement patterns. German hospital networks now separate hardware acquisition from preventive maintenance contracts, issuing multi-vendor service tenders to independent clinical engineering firms. This behavior compresses manufacturer service margins while elevating third-party calibration and certification providers in the Rhineland and Bavaria clusters.
Global Cardiopulmonary Stress Testing Systems Market Segmentation
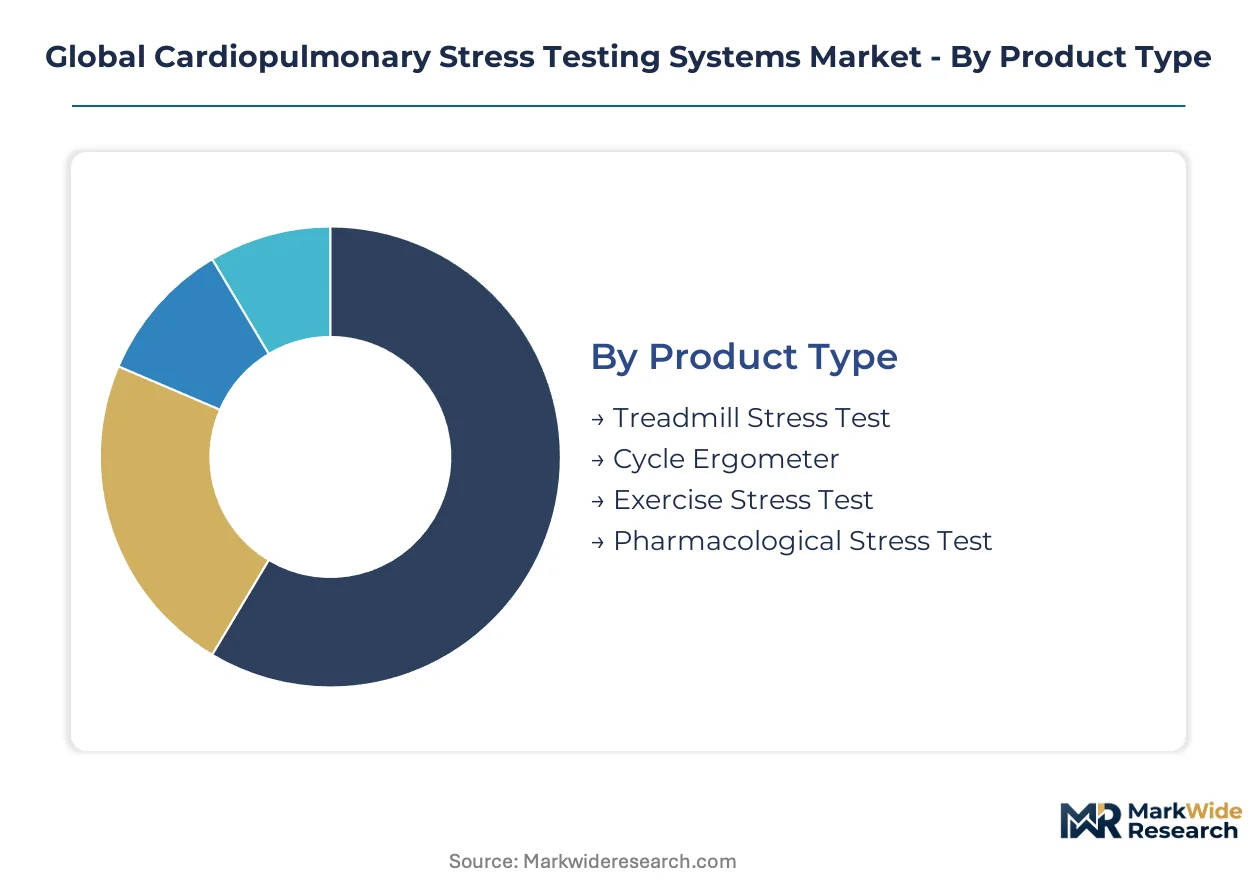
Segmentation in cardiopulmonary stress testing systems reveals how regulatory pathways and clinical use cases fragment procurement priorities across hospital networks. Manufacturers must align product configurations with specific certification burdens and end-user workflows to capture replacement cycles and new installations.
Product Type:
FDA 510(k) clearance timelines vary substantially across mechanical configurations, with treadmill-based systems facing shorter review cycles than novel ergometer designs. EU MDR Class IIa conformity assessments impose equivalent clinical evidence standards regardless of exercise modality.
- Treadmill Stress Test:Belt-driven motorized platforms with adjustable speed and incline protocols dominate cardiology department installations. Demand concentrates in United States academic medical centers where established procedural familiarity reduces staff retraining costs. Medicare reimbursement stability supports replacement of decade-old units.
- Cycle Ergometer:Seated electromagnetic braking systems optimize ventilatory mechanics assessment in pulmonary rehabilitation settings. German hospital networks favor these configurations for heart failure patient cohorts where supine positioning compromises respiratory measurement accuracy. Precision braking component supply from Swiss and Italian vendors creates procurement lead time variability.
- Exercise Stress Test:Integrated platforms combining ECG acquisition with automated blood pressure monitoring serve high-throughput diagnostic clinics. Compact footprints suit Japanese urban hospital spatial constraints.
- Pharmacological Stress Test:Dobutamine and regadenoson protocols without exercise components face displacement from coronary CT angiography in intermediate-risk stratification workflows.
Treadmill Stress Test sits at the top of the volume ranking, with Cycle Ergometer climbing the fastest.
Technology:
Cost tier stratification separates premium multi-parameter integrated platforms from single-modality point solutions. Hospitals consolidate capital expenditure around systems capturing simultaneous cardiac, ventilatory, and metabolic signals.
- Electrocardiography:Twelve-lead acquisition with real-time ST-segment analysis forms the diagnostic backbone of all major platform configurations. Demand clusters in United States cardiology clinics where malpractice liability drives continuous monitoring redundancy.
- Spirometry:Flow-volume loop generation with bronchodilator response assessment integrates with exercise protocols for comprehensive pulmonary evaluation. German pneumology departments specify these modules for COPD staging compliance with national disease management guidelines.
- Metabolic Analysis:Breath-by-breath oxygen uptake and carbon dioxide output quantification commands premium pricing. Japanese Olympic training centers and professional sports facilities drive precision requirements for VO2 max determination.
- Pulse Oximetry:Peripheral oxygen saturation monitoring provides safety surveillance during maximal exercise protocols. Standard inclusion even in base system configurations.
- Blood Pressure Monitoring:Automated cuff systems with exercise-tolerant algorithms complete cardiovascular risk stratification datasets. Rehabilitation facilities prioritize non-invasive continuous monitoring to reduce patient risk.
Electrocardiography commands the largest installed base, with Metabolic Analysis gaining share fastest.
Application:
Customer type differentiation separates acute diagnostic workflows from longitudinal monitoring programs. Reimbursement coding stability varies across clinical indications, directing hospital capital allocation.
- Cardiac Disease Diagnosis:Ischemia detection and arrhythmia provocation under controlled exercise stress represents the original clinical indication for these platforms. United States hospital outpatient departments maintain the highest procedure volumes.
- Pulmonary Evaluation:Ventilatory limitation assessment and exercise-induced bronchospasm identification drive configuration requirements. German pulmonary centers specify combined spirometry-ergometer systems for interstitial lung disease protocols.
- Functional Capacity Assessment:Pre-operative risk stratification and disability determination utilize standardized metabolic endpoints. Japanese cardiac rehabilitation programs mandate these measurements for post-myocardial infarction patient clearance.
- Rehabilitation Monitoring:Serial testing to quantify therapeutic response guides exercise prescription adjustments. Australian remote monitoring reimbursement codes now cover telemetry-enabled home-based systems.
Cardiac Disease Diagnosis retains the largest procedure volume, with Rehabilitation Monitoring expanding most quickly.
End User:
Geographic concentration of specialized clinical expertise determines regional demand patterns. Urban academic centers drive technology adoption ahead of community practice settings.
- Cardiology Clinics:Outpatient diagnostic facilities with high procedure throughput prioritize system reliability and rapid patient turnaround. United States Medicare-eligible population growth sustains replacement demand.
- Pulmonary Centers:Specialized respiratory disease units require precise ventilatory mechanics assessment capabilities. German pneumology networks specify advanced metabolic analysis modules for rare disease research protocols.
- Rehabilitation Facilities:Post-acute care settings emphasize patient safety monitoring and progressive exercise tolerance testing. Australian reimbursement innovation supports remote telemetry adoption.
- Sports Medicine Clinics:Performance optimization and return-to-play clearance drive precision requirements. Brazilian Olympic training centers and professional football clubs import European and Japanese equipment standards.
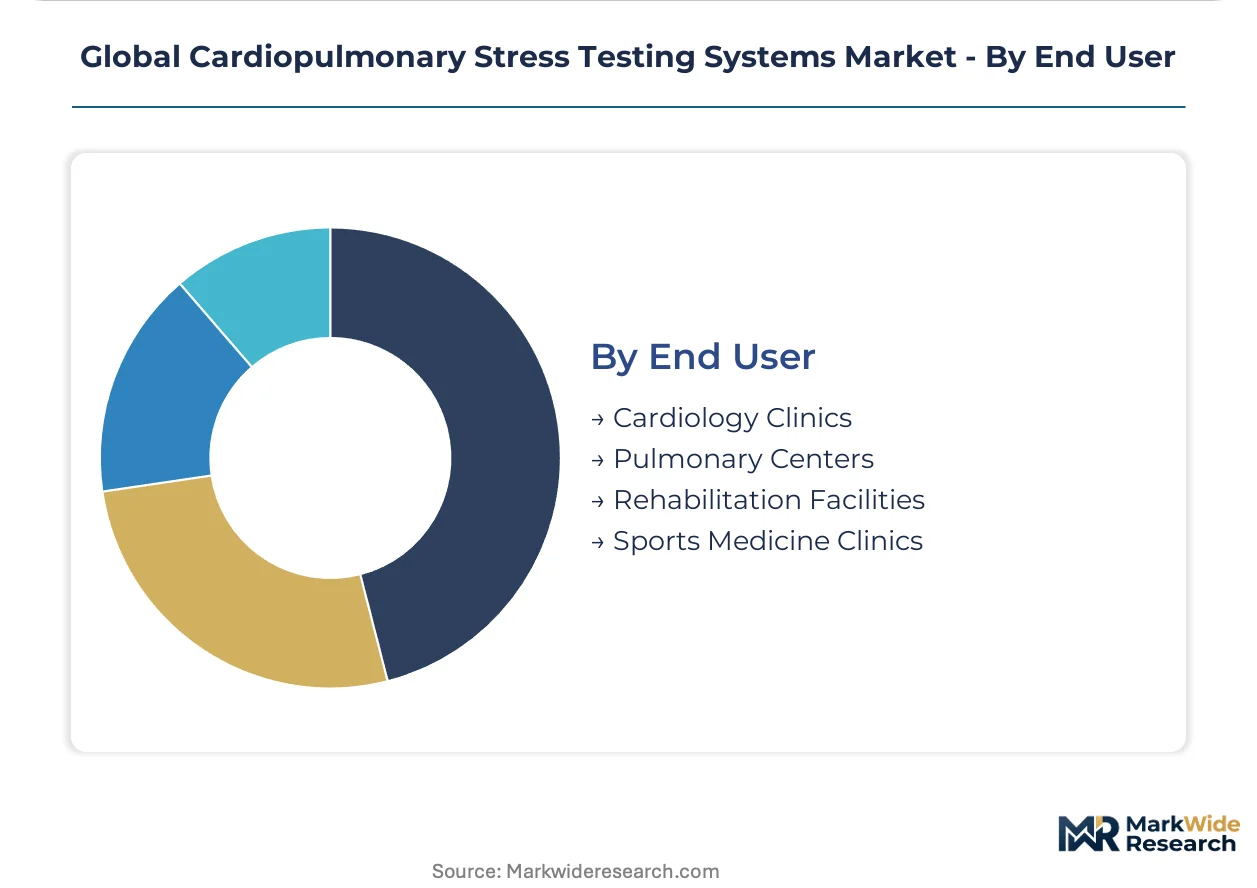
Cardiology Clinics maintain the dominant installed base, with Sports Medicine Clinics showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cardiac electrophysiologists and pulmonary specialists cluster in metropolitan hospital networks across the United States, Germany, and Japan, anchoring replacement demand for integrated metabolic analysis platforms. These workforce concentrations align with stable reimbursement frameworks and aging patient demographics.
United States
Medicare-eligible population expansion drives cardiology clinic equipment refresh cycles in urban outpatient centers. The FDA 510(k) pathway shapes product development timelines for breath-by-breath algorithm updates. Academic medical centers in Boston and New York pilot wireless telemetry configurations that untether patients from fixed analyzer positions.
Germany
Hospital networks in North Rhine-Westphalia consolidate capital expenditure around single-workflow systems capturing simultaneous cardiac and ventilatory signals. The EU MDR recertification deadline compresses development cycles for legacy CE-marked platforms. Pulmonary centers in Bavaria specify advanced metabolic analysis modules for interstitial lung disease protocols.
Japan
PMDA electrical safety and software validation standards filter market entrants and elevate quality benchmarks across Asia-Pacific supply chains. Olympic training centers in Tokyo drive precision requirements for VO2 max determination. Cardiac rehabilitation programs in Osaka mandate standardized metabolic measurements for post-myocardial infarction patient clearance.
Australia
Remote monitoring reimbursement codes now cover telemetry-enabled home-based pulmonary rehabilitation systems in post-acute care settings. The TGA references ISO 13485 quality management standards during device registration reviews. Clinical engineering firms in New South Wales capture multi-vendor preventive maintenance contracts unbundled from hardware procurement.
Brazil
Professional football clubs and Olympic training centers in São Paulo import European and Japanese equipment standards for athlete performance optimization. ANVISA enforcement of medical device quality standards accelerates formal registration pathways for imported diagnostic platforms. Sports medicine clinics in Rio de Janeiro adopt precision breath-by-breath systems for return-to-play clearance protocols.
Global Cardiopulmonary Stress Testing Systems Market Key Industry Players
The competitive structure tilts toward diversified multinationals with established notified body relationships and regulatory affairs capabilities. Tiered specialization separates premium integrated platform manufacturers from point-solution specialists. Three archetypes dominate: full-system integrators leveraging installed base service revenue, precision component specialists competing on measurement accuracy, and regional fabricators capturing price-sensitive procurement. Competitive moves concentrate on M&A for regulatory dossier access and strategic partnerships for algorithm development.
Among diversified health technology conglomerates, GE Healthcare and Koninklijke Philips N.V. exemplify the full-system integrator archetype with positions across hospital network procurement channels. COSMED Srl occupies a specialist position representing precision breath-by-breath measurement capabilities. These three entities anchor the competitive landscape across divergent customer segments from academic medical centers to sports medicine facilities.
| Leading Market Players |
|---|
| GE Healthcare |
| Koninklijke Philips N.V. |
| MGC Diagnostics Corporation |
| COSMED Srl |
| Nihon Kohden Corporation |
| Schiller AG |
| Vyaire Medical Inc. |
| Spacelabs Healthcare |
| SunTech Medical, Inc. |
| Others |
Cost & Logistics Intelligence
Captive production of precision electromagnetic braking components in Switzerland and northern Italy anchors supply security for premium cycle ergometer manufacturers while simultaneously insulating tier-one suppliers from commodity pricing volatility. This vertical control over critical motion-control subsystems enables incumbent device makers to sustain margin pools even as hospital procurement teams unbundle hardware acquisition from service contracts across German and North American networks.
Pricing Analysis
The bundled-versus-unbundled service split now defines competitive positioning across major hospital networks. Three-tier pricing structure across premium, standard, and economy levels separates integrated metabolic carts with full algorithm suites from basic ECG-stress configurations and refurbished legacy installations. Price differentiation rests on FDA 510(k) clearance tier and ISO 13485 certification depth rather than hardware specifications alone. Cost compression in the standard tier is intensifying because German hospital networks now issue multi-vendor preventive maintenance tenders separately from capital equipment procurement. Community cardiology clinics exhibit highest price sensitivity due to Medicare reimbursement lag, while academic medical centers prioritize measurement precision over acquisition cost.
Supply Chain Analysis
Regional distribution centers in the Netherlands and Singapore orchestrate hub-and-spoke patterns for Asia-Pacific and European hospital network fulfillment. Precision manufacturing concentrates in Switzerland, Germany, and Japan where electromagnetic braking systems, gas analysis sensors, and embedded software modules originate. Component sourcing draws from Taiwanese semiconductor foundries for signal processing chips and specialized Italian machine shops for ergometer frame fabrication. Single-source vulnerability persists for breath-by-breath gas analyzers where two European suppliers control proprietary optical sensing technology. Distribution runs through manufacturer-direct clinical engineering teams for premium installations and third-party medical device distributors for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Cardiopulmonary Stress Testing Systems Market functions as a stable compounder where aging demographic clusters across developed economies generate predictable replacement cycles and reimbursement stability.
For Market Incumbents: Cement notified body relationships ahead of EU MDR recertification waves to secure conformity assessment capacity for legacy platform transitions. Deepen backward integration into electromagnetic braking component production to reduce exposure to Swiss and Italian supplier concentration. Prioritize software-as-medical-device certification investment to capture iterative algorithm update revenue streams threatened by FDA 510(k) pathway modernization. For New Entrants and Emerging Players: The price-point gap between premium integrated metabolic carts and economy treadmill configurations creates white-space opportunity for mid-tier entrants offering modular upgrade pathways. Target Australian rehabilitation facilities where remote monitoring reimbursement codes now cover telemetry-enabled home-based systems. Pursue sports medicine clinics in Brazil as the most penetrable geography given ANVISA enforcement gaps and import-dependent equipment standards. Deploy direct-to-clinic digital sales channels to bypass established distributor relationships controlling North American hospital procurement. For Investors and Strategic Acquirers: Roll-up economics work for precision component specialists because EU MDR clinical evidence requirements favor acquirers with existing notified body dossiers over de novo entrants. Long-term viability centers on five-to-ten year windows where metabolic analysis technology captures expanding margin pools within consolidated hospital workflows. Acquisition target archetype: breath-by-breath gas analysis specialists with proprietary optical sensing patents and established PMDA validation protocols. Monitor FDA breakthrough device designation velocity as inflection indicator for algorithm-centric competitive disruption.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Recertification Pathway | Rebuilds clinical evidence dossiers for legacy CE-marked platforms ahead of notified body deadline compression. |
| Software-as-Medical-Device Certification | Enables iterative breath-by-breath algorithm updates through streamlined FDA 510(k) premarket notification. |
| Hospital System Partnership | Secures multi-year preventive maintenance contracts unbundled from hardware procurement in German networks. |
| Reimbursement Strategy Development | Captures remote monitoring revenue streams through Australian telemetry-enabled pulmonary rehabilitation coverage. |
| Precision Component Acquisition | Consolidates electromagnetic braking supply security against Swiss and northern Italian vendor concentration. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to construct demand estimates for integrated metabolic analysis platforms. Primary engagement encompassed cardiology department heads, hospital biomedical engineers, GPO contracts managers, and regulatory affairs directors at notified bodies. Secondary validation drew from FDA 510(k) premarket notification databases, EU MDR conformity assessment records, CMS Medicare procedure volume reports, and hospital procurement database aggregators. Bottom-up installation tracking and top-down reimbursement flow analysis triangulated market sizing across treadmill, ergometer, and pharmacological stress test configurations.
Segment-weighting approaches distributed value and volume projections across product type, technology module, clinical application, and end-user facility categories. The analytical framework modeled replacement cycles, new installation demand, and technology upgrade pathways across the projection horizon. CAGRs derived from fitted growth curves incorporating aging demographic trajectories, reimbursement stability indices, and regulatory pathway friction coefficients. Industry-specific forecast inputs included PMDA software validation timeline data and EU notified body capacity utilization rates.
Caveats apply where FDA 510(k) review timeline extensions or EU MDR notified body capacity collapse could materially shift the outlook for new platform commercialization. Forecasts reflect documented assumptions regarding reimbursement code stability and electromagnetic component supply continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Tissue Processing Systems Market
Medical Equipment
PMMA Healthcare Market
Medical Equipment
Fluoroscopy Equipment Market
Medical Equipment
Tissue Culture Incubator Market
Medical Equipment
Medical Oxygen Cylinders Market
Medical Equipment
Medical Oxygen Concentrators and Oxygen Cylinders Market
Medical Equipment
ECG Equipment and Management Systems Market
Medical Equipment
Embedded Disinfection Cabinet Market
Medical Equipment
Asia-Pacific Medical Carts Market
Medical Equipment
Medical Physics Market
Medical Equipment
Medical Cart Battery Market
Medical Equipment
Mercury Thermometer Market
Medical Equipment
Faecal Extraction System Market
Medical Equipment
US ECG Equipment Market
Medical Equipment
Global Portable Beds Market
Medical Equipment
Medical Fluid Bags Market