
 Global Kidney Dialysis Equipment and Supplies Market | 2026-2036
Global Kidney Dialysis Equipment and Supplies Market Size, Share, and Industry Trends Forecast 2026-2036
Global Kidney Dialysis Equipment and Supplies Market Foresight
Project finance and equipment leasing programs are reshaping competitive dynamics in renal care, lowering capital barriers for independent dialysis centers and ambulatory surgical centers. Fresenius Medical Care leverages captive financing arms to anchor long-term supply contracts across clinic networks. Baxter International sustains R&D intensity in automated peritoneal dialysis systems. DaVita Inc. competes through scale advantages in outpatient service delivery.
Kidney dialysis equipment and supplies encompass hemodialysis machines, dialyzers, blood tubing sets, concentrates, and peritoneal dialysis solutions engineered with biocompatible membranes and ultrapure water systems to filter metabolic waste from patients with compromised renal function. Hemodialysis machines dominate installed base value while portable devices represent the fastest-expanding technology segment as manufacturers miniaturize pumps and improve battery efficiency. End-stage renal disease applications command the largest patient volume share, though pediatric dialysis commands premium pricing due to specialized consumable requirements.
FDA premarket notification pathways and EU MDR conformity assessments govern device approval timelines and clinical evidence standards for manufacturers seeking market access. Japan's PMDA maintains distinct quality management system requirements that extend certification cycles for foreign suppliers. Stakeholders must monitor reimbursement rate negotiations between public health systems and dialysis providers, as these directly determine equipment refresh cycles and home therapy expansion feasibility.
Market Dynamics
EU MDR conformity assessment timelines and battery miniaturization advances are compressing certification cycles while expanding portable device feasibility for home-based renal therapy.
Growth Catalysts
- Japan's PMDA pathway streamlining:Quality management system harmonization accelerates foreign manufacturer market entry for automated peritoneal dialysis systems.
- Home healthcare channel expansion:Ambulatory surgical centers and independent dialysis clinics deploy portable hemodialysis machines to reduce patient travel burden.
- Biocompatible membrane R&D:Synthetic polymer advances in dialyzer construction reduce inflammatory response rates and extend treatment session intervals.
Market Restraints
- Ultrapure water system infrastructure costs:Capital intensity for water purification installations constrains clinic expansion in rural United States markets.
- EU MDR clinical evidence requirements:Extended certification timelines delay product launches for dialyzer and blood tubing set manufacturers.
- Peritoneal dialysis solution supply concentration:Limited sterile manufacturing capacity in Western Europe creates vulnerability to batch contamination events.
Strategic Opportunities
- Pediatric dialysis specialization:Underserved neonatal and adolescent segments command premium pricing for scaled consumables and specialized equipment interfaces.
- India's dialysis infrastructure buildout:Public-private partnerships under national health mission frameworks expand addressable patient populations beyond metropolitan centers.
- Remote monitoring convergence:Integration of IoT sensors with cloud-based clinical dashboards enables predictive maintenance and real-time treatment parameter adjustment.
Industry Challenges
- Bioengineered membrane workforce scarcity:Specialized polymer chemistry and hemocompatibility expertise shortages delay R&D pipeline advancement.
- Legacy hemodialysis machine integration complexity:Retrofitting clinic networks with connectivity modules for data interoperability demands substantial technical support capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Kidney Dialysis Equipment and Supplies Market |
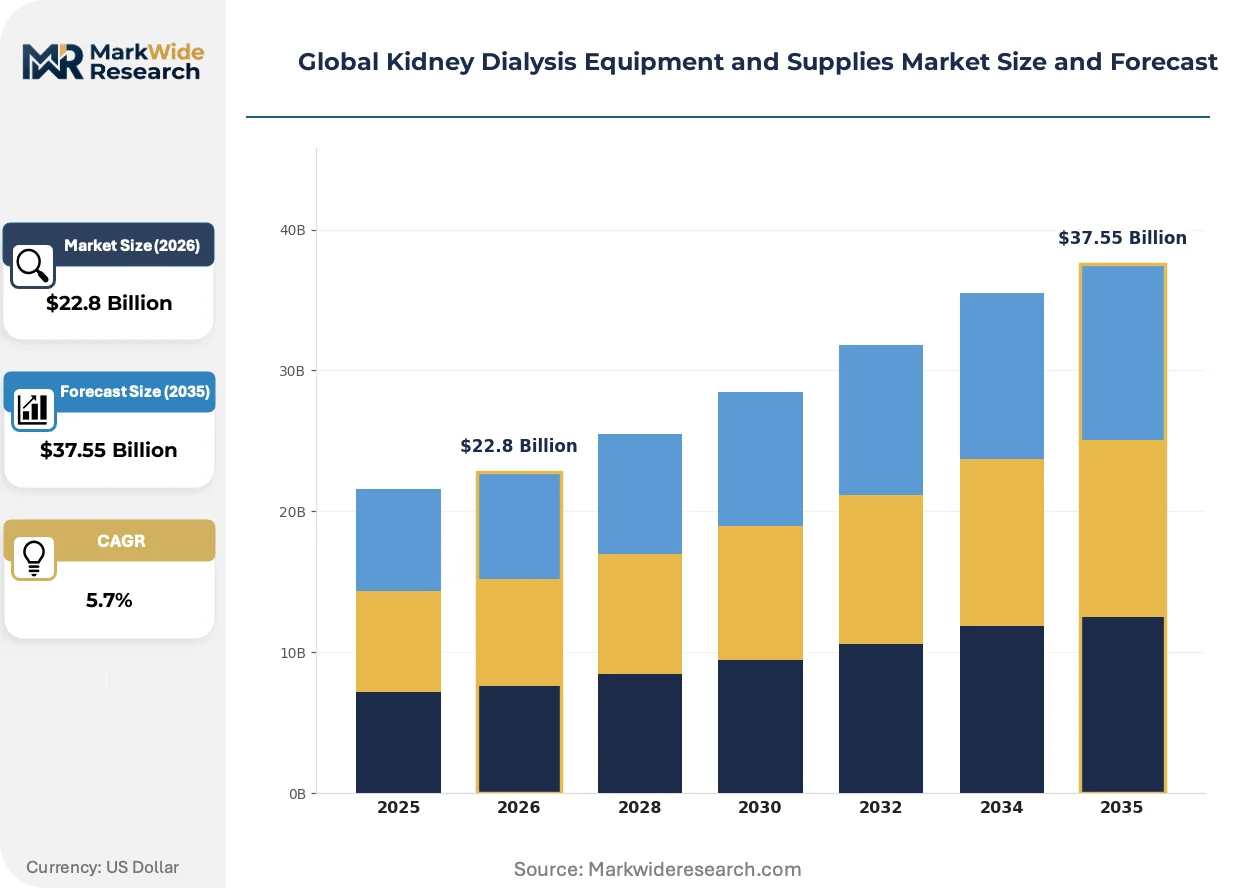
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $37.55 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dialyzers, Hemodialysis Machines, Peritoneal Dialysis Solutions, Blood Tubing Sets, Dialysis Concentrates Technology: Membrane Filtration, Ultrapure Water Systems, Automated Peritoneal Dialysis, Portable Devices, Continuous Renal Replacement Therapy Application: Chronic Kidney Disease, Acute Kidney Injury, End-Stage Renal Disease, Pediatric Dialysis, Geriatric Therapy End User: Dialysis Centers, Specialty Clinics, Ambulatory Surgical Centers, Home Healthcare Providers, Rehabilitation Facilities |
| Companies Covered | Fresenius Medical Care, Baxter International, DaVita Inc., Nipro Corporation, B. Braun Melsungen, Nikkiso Co., Ltd., Asahi Kasei Corporation, Medtronic plc, Toray Medical Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Kidney Dialysis Equipment and Supplies Market Shifts & Advancements
Device miniaturization, regulatory harmonization pressures, and care site decentralization are restructuring how renal replacement therapy reaches end-stage renal disease patients across developed and emerging markets.
Portable hemodialysis systems is migrating from hospital-based treatment toward home and ambulatory deployment. Patients with end-stage renal disease in Germany and Japan adopt battery-powered devices for overnight therapy sessions. This technology shift compresses clinic infrastructure requirements while demanding new training protocols for home healthcare providers.
EU MDR post-market surveillance obligations intensify clinical follow-up documentation for dialyzer manufacturers. The regulation mandates periodic safety update reports and vigilance system integration that extend compliance staffing needs. High-risk device classifications in France and Germany drive consolidation among smaller suppliers unable to sustain regulatory affairs capabilities.
Subscription-based equipment leasing displaces capital purchase models among independent dialysis center operators in the United States. Financing arms of major suppliers bundle maintenance, consumables, and technology refresh cycles into per-treatment fee structures. This procurement evolution concentrates vendor relationships and locks in long-term supply contracts across clinic networks.
Global Kidney Dialysis Equipment and Supplies Market Segmentation
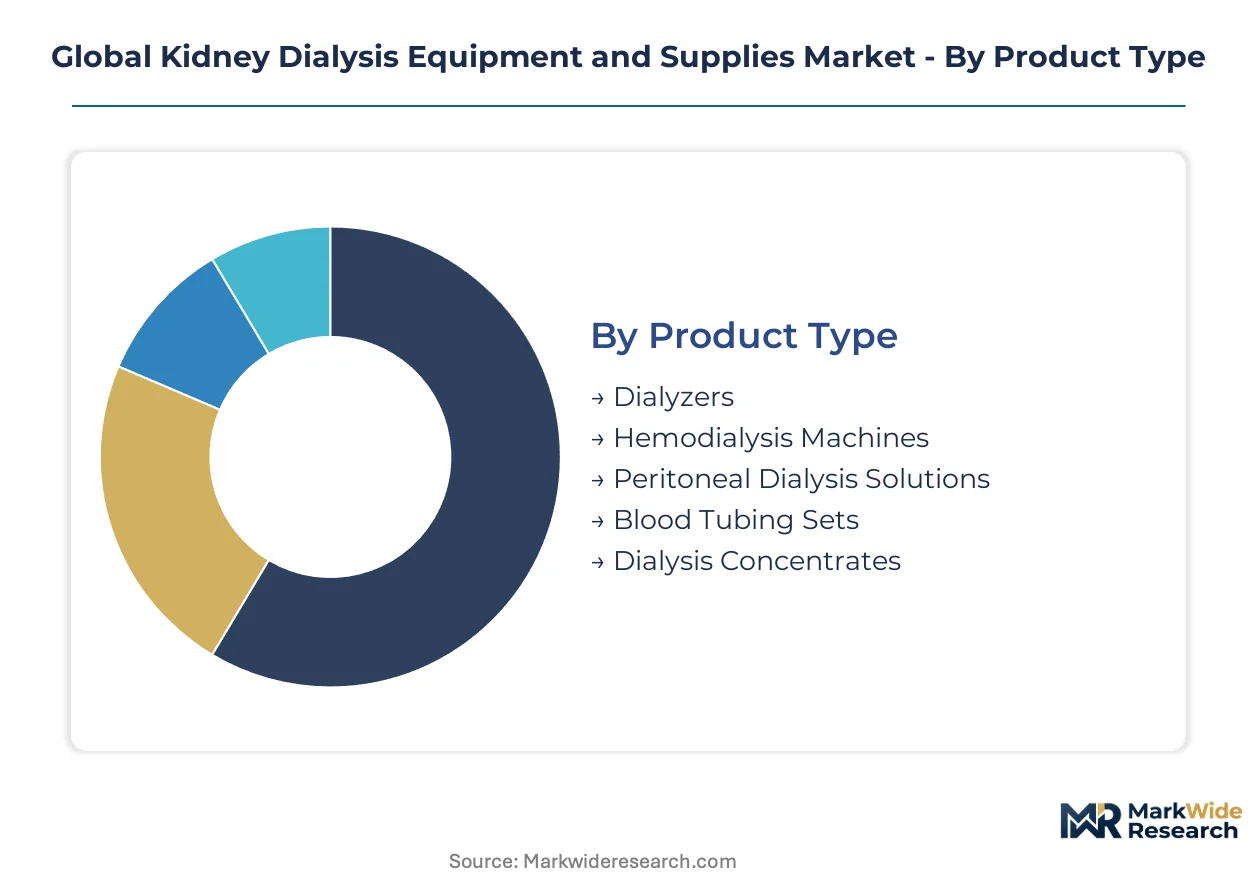
Segmentation in renal replacement therapy reveals divergent equipment lifecycles and margin structures across treatment modalities. Understanding these patterns enables suppliers to align R&D investment with replacement demand timing and reimbursement rate trajectories.
Product Type:
Consumable segments turn over in months while capital equipment cycles span years, creating fundamentally different revenue recognition profiles and customer relationship architectures.
- Dialyzers:Single-use hollow-fiber devices with synthetic polymer membranes engineered for biocompatibility and toxin clearance efficiency. Demand concentrates in high-volume dialysis centers across Germany and Japan where session frequency drives replacement rates and membrane material specifications determine reimbursement tiering.
- Hemodialysis Machines:Electromechanical systems integrating blood pumps, heparin delivery modules, and conductivity monitors for controlled extracorporeal filtration. Replacement demand clusters in United States outpatient networks where equipment leasing programs accelerate refresh cycles and connectivity upgrades.
- Peritoneal Dialysis Solutions:Sterile glucose-based or icodextrin fluids for intraperitoneal toxin exchange.
- Blood Tubing Sets:Single-use extracorporeal circuits with arterial and venous lines.
- Dialysis Concentrates:Acid and bicarbonate formulations for dialysate preparation.
Hemodialysis machines dominate installed base. Dialyzers are where expansion concentrates.
Technology:
Technology segmentation separates mature platforms with established reimbursement codes from emerging modalities requiring clinical evidence investment and regulatory pathway navigation.
- Membrane Filtration:Diffusion and convection-based separation using polysulfone, polyethersulfone, or cellulose triacetate membranes with defined molecular weight cutoffs. Deployment concentrates in European dialysis networks where EU MDR biocompatibility documentation requirements favor suppliers with established polymer chemistry capabilities.
- Portable Devices:Miniaturized battery-powered systems enabling home-based hemodialysis with reduced water infrastructure requirements. Adoption concentrates in Japanese and German home healthcare channels where aging demographics and caregiver shortages drive ambulatory treatment models.
- Ultrapure Water Systems:Reverse osmosis and ultrafiltration infrastructure for dialysate preparation.
- Automated Peritoneal Dialysis:Cyclers managing nocturnal exchange regimens.
- Continuous Renal Replacement Therapy:Slow continuous filtration for hemodynamically unstable patients.
Membrane filtration anchors current revenue. Portable devices are climbing the fastest.
Application:
Application segments stratify by clinical acuity, treatment duration, and patient age-specific interface requirements that dictate equipment specification and consumable pricing power.
- End-Stage Renal Disease:Maintenance dialysis for irreversible kidney function loss requiring sustained thrice-weekly hemodialysis or daily peritoneal therapy. Patient volumes concentrate in United States Medicare-funded programs where bundled reimbursement rates compress provider margins and extend equipment utilization periods.
- Pediatric Dialysis:Scaled equipment and consumables for neonatal through adolescent patients with specialized blood volume management and vascular access requirements. Demand clusters in tertiary referral centers across Germany and Japan where low patient incidence supports premium pricing for adapted device interfaces.
- Chronic Kidney Disease:Pre-dialysis management and education.
- Acute Kidney Injury:Temporary renal support in critical care settings.
- Geriatric Therapy:Age-adjusted treatment protocols for comorbid elderly patients.
End-stage renal disease commands patient volume. Pediatric dialysis holds pricing power.
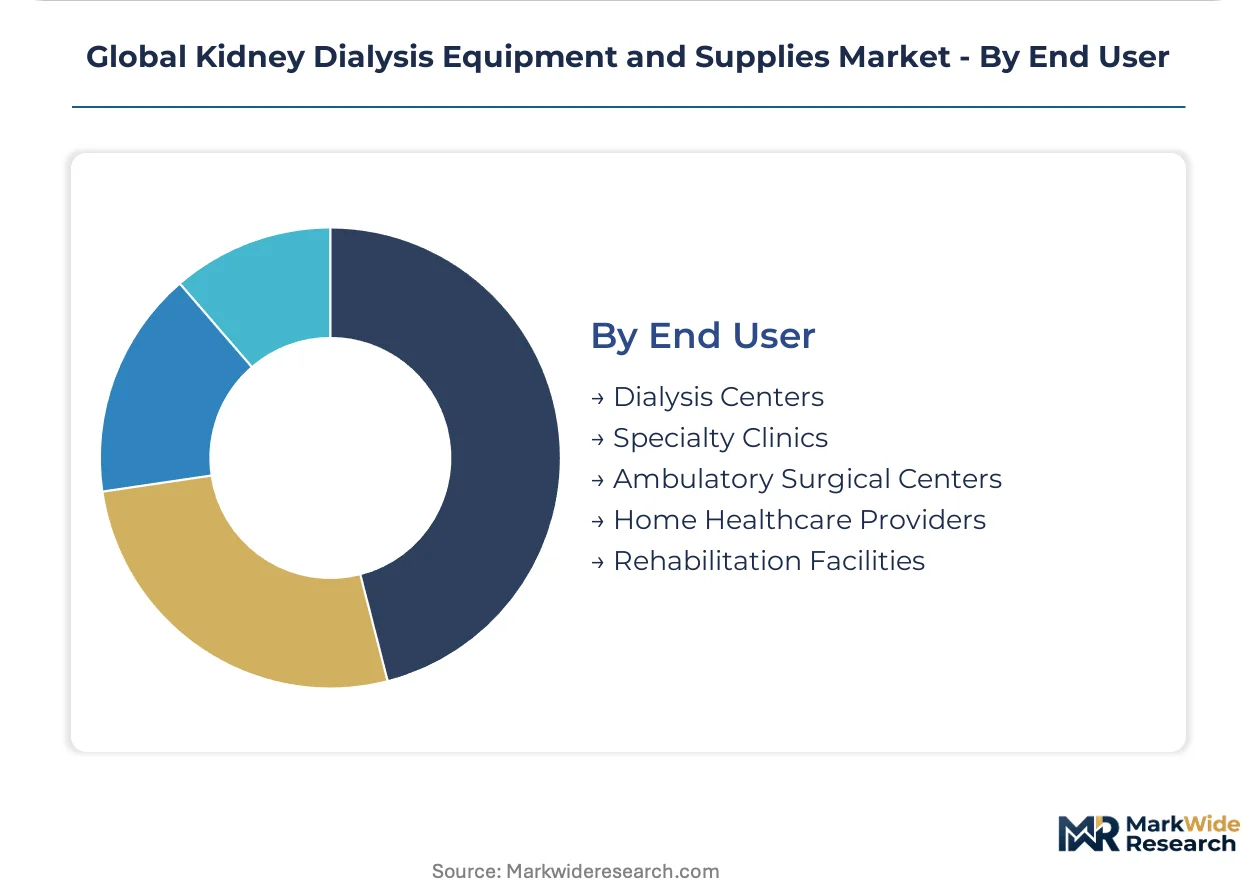
End User:
End-user segmentation tracks the decentralization of renal care from hospital campuses toward community-based and residential settings with divergent capital intensity and staffing models.
- Dialysis Centers:Dedicated outpatient facilities with centralized water purification, multiple treatment stations, and specialized nursing staff. Equipment procurement concentrates in United States networks where scale economies and group purchasing organizations concentrate vendor relationships.
- Home Healthcare Providers:Organizations training and supporting patients in peritoneal dialysis or home hemodialysis with remote monitoring capabilities. Expansion concentrates in German and Japanese markets where reimbursement supports home therapy infrastructure and patient self-management education.
- Specialty Clinics:Hospital-affiliated or independent nephrology practices.
- Ambulatory Surgical Centers:Same-day procedure facilities with limited dialysis capability.
- Rehabilitation Facilities:Post-acute care settings with transitional dialysis support.
Dialysis centers anchor equipment shipments. Home healthcare providers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment trade flows concentrate in dialysis machine exports from Germany and Japan against concentrate and consumable imports into India and Brazil. The United States runs a substantial deficit in dialyzer membranes while maintaining surplus in water purification systems. Regulatory divergence between FDA, EU MDR, and Japan's PMDA shapes cross-border certification strategies.
United States
Medicare bundled reimbursement sustains the world's largest hemodialysis patient population, driving equipment refresh cycles in outpatient networks. FDA 510(k) premarket notification governs machine approvals with clinical evidence requirements tightening for high-risk device classifications. Dialysis center concentration clusters in Texas, Florida, and California where independent clinic operators deploy subscription-based leasing models.
Germany
Aging demographics and universal health coverage sustain per-capita dialysis treatment rates among Europe's highest. EU MDR conformity assessment timelines extend certification cycles for dialyzer manufacturers seeking CE marking renewal. Industrial concentration in Baden-Württemberg and North Rhine-Westphalia hosts membrane polymer chemistry specialists supplying hollow-fiber production lines.
Japan
Home healthcare reimbursement supports automated peritoneal dialysis adoption rates exceeding Western markets. PMDA quality management system harmonization accelerates foreign manufacturer entry for portable device categories. Manufacturing clusters in Kansai and Chubu regions produce dialyzers and blood tubing sets for domestic consumption and Asian export.
India
Public-private partnerships under the National Health Mission expand dialysis infrastructure beyond metropolitan centers into tier-2 cities. CDSCO medical device registration requirements strengthen post-market surveillance obligations for imported equipment. Industrial corridors in Gujarat and Maharashtra attract concentrate manufacturing investments to reduce import dependency.
Brazil
Universal health system coverage expansion drives public procurement volume for hemodialysis machines in Southeast and Northeast regions. ANVISA medical device regulations align with Mercosur technical standards while maintaining distinct in-country testing requirements. São Paulo state anchors equipment import distribution networks serving the Mercosur trade bloc.
Global Kidney Dialysis Equipment and Supplies Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in membrane and polymer supply. Market structure consolidates around vertically integrated manufacturers with captive financing arms and long-term service contracts. Three archetypes dominate: full-service platform vendors bundling equipment and consumables, membrane chemistry specialists licensing polymer formulations, and regional assemblers serving price-sensitive procurement channels. Competitive moves center on equipment leasing program expansion and backward integration into dialyzer membrane production.
Among diversified healthcare conglomerates, Fresenius Medical Care and Baxter International occupy positions exemplifying platform integration archetypes, while DaVita Inc. represents service-scale competitive positioning. These entities anchor distinct strategic vectors: captive financing and supply contract bundling, automated therapy system development, and outpatient network density respectively. Specialist manufacturers including Nipro Corporation, B. Braun Melsungen, and Asahi Kasei Corporation sit within component and materials tiers, supplying membranes, tubing sets, and concentrate formulations to integrated platform vendors and independent clinic operators.
| Leading Market Players |
|---|
| Fresenius Medical Care |
| Baxter International |
| DaVita Inc. |
| Nipro Corporation |
| B. Braun Melsungen |
| Nikkiso Co., Ltd. |
| Asahi Kasei Corporation |
| Medtronic plc |
| Toray Medical Co., Ltd. |
| Others |
Supply & Pricing Matrix
Rotterdam-Antwerp freight corridors govern landed cost differentials for dialyzer membrane imports, compressing margins for European clinic operators while amplifying price separation between premium synthetic polymer grades and standard cellulose alternatives. This logistics architecture concentrates procurement leverage among integrated platform vendors with captive manufacturing in Germany and Japan.
Pricing Analysis
Industrial OEM buyers anchor subscription-based equipment leasing structures that bundle maintenance, consumables, and technology refresh cycles into per-treatment fee arrangements. Price differentiation rests on FDA clearance tier and membrane biocompatibility certification, with premium synthetic polymer dialyzers commanding substantial markups over standard cellulose alternatives. Cost compression in economy-tier consumables is intensifying because of group purchasing organization concentration among United States dialysis networks. Independent clinic operators exhibit highest price sensitivity, while integrated health systems with captive financing arms demonstrate lowest sensitivity due to long-term contract lock-in.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculus for blood tubing set manufacturers dependent on medical-grade PVC resin imports. Manufacturing gravity centers on Germany, Japan, and the United States for hemodialysis machines, while membrane polymer chemistry specialists cluster in Baden-Württemberg and Kansai regions. Raw material dependencies include polysulfone resins, medical-grade silicones, and ultrapure water treatment membranes. Single-source vulnerability pervades sterile peritoneal dialysis solution manufacturing in Western Europe. Distribution runs through integrated platform vendor direct sales forces and group purchasing organization contracts with hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against bioartificial kidney implant development programs that threaten to displace maintenance dialysis modalities over extended time horizons. Incumbents must navigate this existential technology transition while extracting maximum value from installed base equipment.
For Market Incumbents: Entrench service-scale advantages through backward integration into dialyzer membrane production, securing captive supply of synthetic polymer formulations against supply concentration risks. Deepen hospital system partnership density in United States Medicare-funded networks to lock in long-term consumable offtake before reimbursement rate compression accelerates equipment refresh cycles.
For New Entrants and Emerging Players: Establish a beachhead in pediatric dialysis specialization where scaled consumable requirements and premium pricing power offset low patient volumes. Target tertiary referral centers in Germany and Japan with adapted device interfaces for neonatal through adolescent patients, leveraging regulatory pathway expertise to navigate PMDA and EU MDR quality management system requirements.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors membrane chemistry specialists with established polymer formulation capabilities and regulatory documentation libraries. Long-term viability hinges on differentiation defensibility against platform integrators with captive financing arms. Watch automated peritoneal dialysis system adoption rates in Japanese home healthcare channels as inflection indicator for ambulatory treatment model viability.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR conformity assessment timelines compress competitive windows for dialyzer manufacturers seeking market access. |
| Hospital System Partnership | GPO contract concentration in United States outpatient networks locks in multi-year consumable supply relationships. |
| Software Companion Development | IoT sensor integration with cloud-based clinical dashboards enables predictive maintenance and real-time parameter adjustment. |
| Reimbursement Strategy | Medicare bundled rate negotiations directly determine equipment refresh feasibility and home therapy expansion economics. |
| Backward Integration | In-house membrane polymer production secures supply continuity against sterile manufacturing capacity constraints in Western Europe. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with nephrologists, biomedical engineers, hospital purchasing committee members, GPO contracts managers, and dialysis center operations directors. Secondary validation drew from FDA 510(k) premarket notification databases, EU MDR conformity assessment records, CMS Medicare reimbursement filings, and hospital procurement contract disclosures. Bottom-up patient volume modeling and top-down equipment shipment triangulation anchored market sizing across the analysis window.
Calibration against historical equipment replacement cycles and reimbursement rate trajectories informed projection methodology. Segmentation dimensions spanned treatment modality, technology platform, patient age category, and care site configuration. CAGRs were derived from installed base evolution and consumable throughput assumptions, with specific weighting for portable device adoption curves and home healthcare channel expansion rates.
Sensitivities concentrate around EU MDR certification timeline extensions, Medicare bundled rate renegotiation outcomes, and bioartificial kidney clinical trial advancement. Forecasts reflect documented assumptions regarding patient population growth, equipment lifespan parameters, and reimbursement stability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Global Intraoperative Radiation Therapy Market
Medical Equipment
Irradiation Apparatus Market
Medical Equipment
South Africa Radiotherapy Market
Medical Equipment
Minor Surgical Lights Market
Medical Equipment
MRI Transport Market
Medical Equipment
Auditory Brainstem Response Analyzers Market
Medical Equipment
Global Capnography Equipment Market
Medical Equipment
US Medical Carts Market
Medical Equipment
Dial Thermometers Market
Medical Equipment
Europe Nuclear Medicine Equipment Market
Medical Equipment
Terminal Sterilization Market
Medical Equipment
Global Surgical Table Market
Medical Equipment
Global Medical Refrigerators Market
Medical Equipment
Medical Oxygen Cylinders Market
Medical Equipment
Intensive Care Unit (ICU) Equipment Market
Medical Equipment
Surgical Generators Market