
 Tattoo Removal Patch Market | 2026-2036
Tattoo Removal Patch Market Size, Share, and Industry Trends Forecast 2026-2036
Tattoo Removal Patch Market Analytics
Micro-needle array technology is tilting toward dissolvable hyaluronic acid matrices that release tattoo-degrading agents past the stratum corneum without thermal damage. Alma Lasers Ltd. leverages its clinic-installed base to cross-sell complementary patch protocols. Cynosure, Inc. anchors its position through R&D intensity in fractional delivery systems. LUTRONIC Corporation specializes in bridging laser and patch modalities for hybrid treatment workflows.
A tattoo removal patch is a transdermal or topical delivery system engineered with active permeation enhancers—typically salicylic acid derivatives, alpha-hydroxy acids, or enzymatic breakdown agents—designed to fragment dermal ink particles for lymphatic clearance without ablative intervention. The transdermal delivery mode commands the deepest margin pools due to extended-release kinetics and higher per-unit pricing, while topical formulations occupy volume leadership through salon and home-user channels. Patches within the product type taxonomy are recording the fastest trajectory as manufacturers optimize adhesion chemistry for multi-day wear on contoured body surfaces. Dermatologists as an end-user segment concentrate purchasing power through protocol-driven repeat applications, whereas home users fragment across direct-to-consumer brands with weaker retention profiles.
FDA Center for Devices and Radiological Health oversight of combination drug-device patches, coupled with EU MDR requirements for clinical evidence on active substance delivery, elevates barriers for new entrants lacking regulatory infrastructure. ISO 10993 biocompatibility testing and REACH compliance for skin-contact adhesives further shape formulation choices and supplier qualification timelines. Stakeholders must monitor evolving FDA classification determinations on enzymatic tattoo removal patches as the boundary between cosmetic and medical device claims narrows.
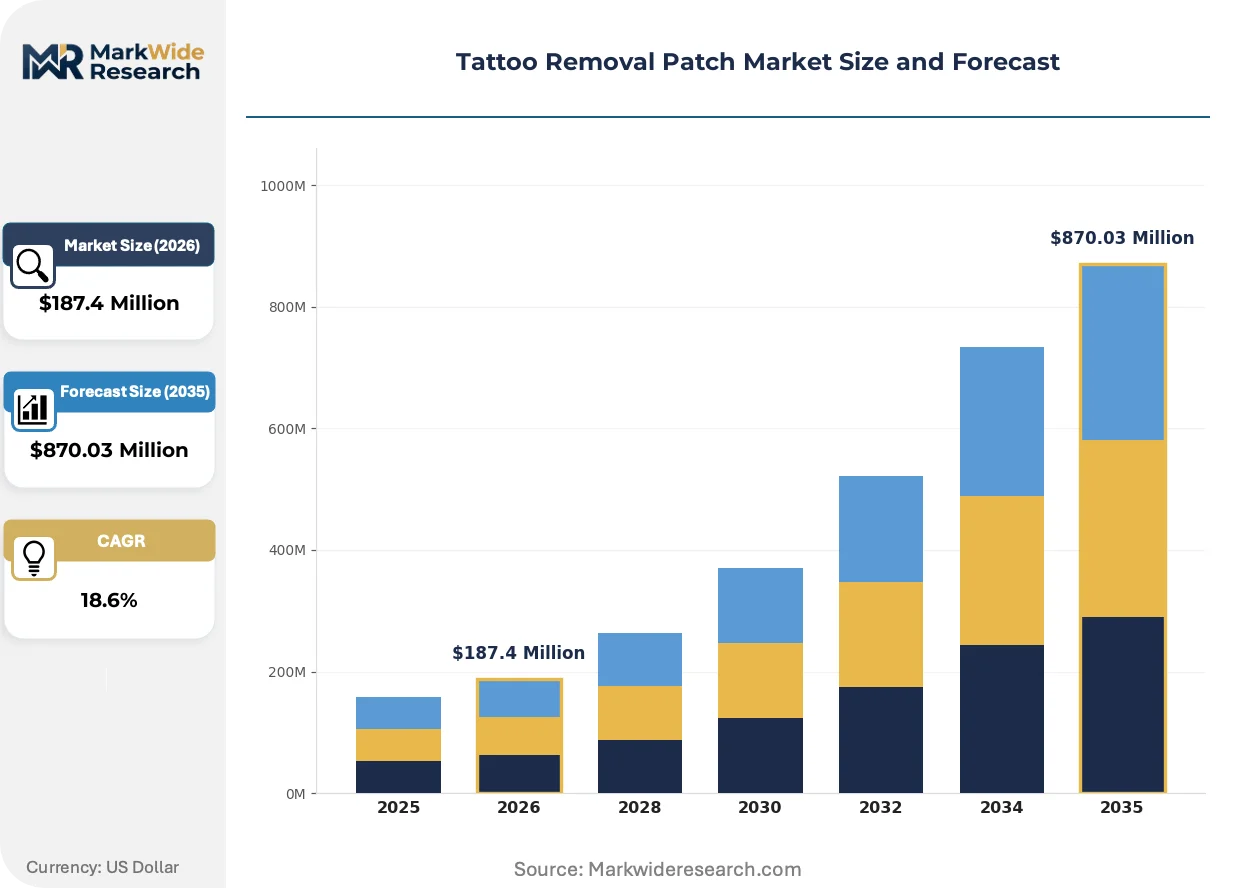
Market Dynamics
Micro-needle dissolution chemistry is collapsing the barrier between clinic-grade and home-use tattoo removal, forcing manufacturers to recalibrate formulation potency against adhesion durability for unsupervised wear.
Growth Catalysts
- FDA cosmetic-device boundary tightening:The FDA Center for Devices and Radiological Health's evolving classification guidance for enzymatic patches is accelerating clinical validation investments by established manufacturers.
- Salon channel expansion:Med-spa operators in Seoul and Los Angeles are integrating patch protocols into membership-based aesthetic programs, creating recurring revenue streams.
- Hyaluronic acid matrix advances:Dissolvable micro-needle arrays now achieve 72-hour controlled release of tattoo-degrading enzymes past the stratum corneum.
Market Restraints
- Biocompatibility testing costs:ISO 10993 cytotoxicity and sensitization studies for novel adhesive chemistries add 14-18 months to product development timelines.
- Active ingredient supply concentration:Pharmaceutical-grade alpha-hydroxy acid derivatives for dermal penetration depend on a narrow supplier base concentrated in Germany and Switzerland.
- Laser substitution persistence:Q-switched Nd:YAG systems retain preference for multicolor tattoos where patch enzymatic action remains chromatically limited.
Strategic Opportunities
- EU MDR clinical evidence pathways:Manufacturers with existing biocompatibility dossiers can leverage CE marking for active substance delivery devices to access 27 member state markets.
- Direct-to-consumer subscription models:Home-user channels in California and South Korea are testing multi-patch regimen deliveries with tele-dermatology oversight.
- Hybrid protocol positioning:Dermatology clinics are bundling patch pre-treatment with fractional laser finishing, creating service differentiation against standalone modalities.
Industry Challenges
- Formulation stability expertise:Enzyme preservation in adhesive matrices across temperature variations requires bioprocess engineering talent scarce outside established pharmaceutical hubs.
- Claims substantiation timelines:EU MDR requirements for clinical evidence on lymphatic clearance rates extend certification cycles beyond typical venture capital horizons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tattoo Removal Patch Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $870.03 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Creams, Gels, Patches, Kits Delivery Mode: Transdermal, Topical, Oral, Injection End User: Clinics, Salons, Home Users, Dermatologists Application: Cosmetic, Medical, Aesthetic, Others |
| Companies Covered | Cutera, Inc., Syneron Medical Ltd., Alma Lasers Ltd., LUTRONIC Corporation, Quanta System S.p.A., Lumenis Ltd., Fotona d.o.o., Sciton, Inc., Cynosure, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tattoo Removal Patch Market Evolving Landscape
Dissolvable micro-needle chemistry is collapsing the historical separation between professional and consumer-grade tattoo removal, while regulatory classification debates in Washington and Brussels reshape competitive entry costs.
Biodegradable hyaluronic acid micro-arrays are collapsing the efficacy gap between transdermal patches and ablative lasers. Dermatology clinics in Tokyo and Los Angeles are adopting these arrays for patient cohorts with thermal sensitivity or darker skin phototypes. The technology is collapsing price premiums previously commanded by fractional delivery systems, compressing per-treatment revenue for standalone laser operators.
The EU MDR's tightened clinical evidence requirements for active dermal delivery devices are elevating documentation burdens for enzymatic tattoo removal patches. Manufacturers must now submit lymphatic clearance kinetic data alongside biocompatibility assessments. Transdermal patch categories face the steepest compliance gradients, with notified bodies in Germany and the Netherlands extending review timelines for novel adhesive formulations.
Subscription-based patch regimens are displacing single-unit retail purchases in direct-to-consumer channels. Tele-dermatology platforms in South Korea are bundling patch shipments with remote progress monitoring, capturing patient cohorts distant from specialist clinics. This model concentrates most visibly in Seoul's medical aesthetics corridor, where digital-native competitors are eroding traditional clinic referral networks.
Tattoo Removal Patch Market Segmentation
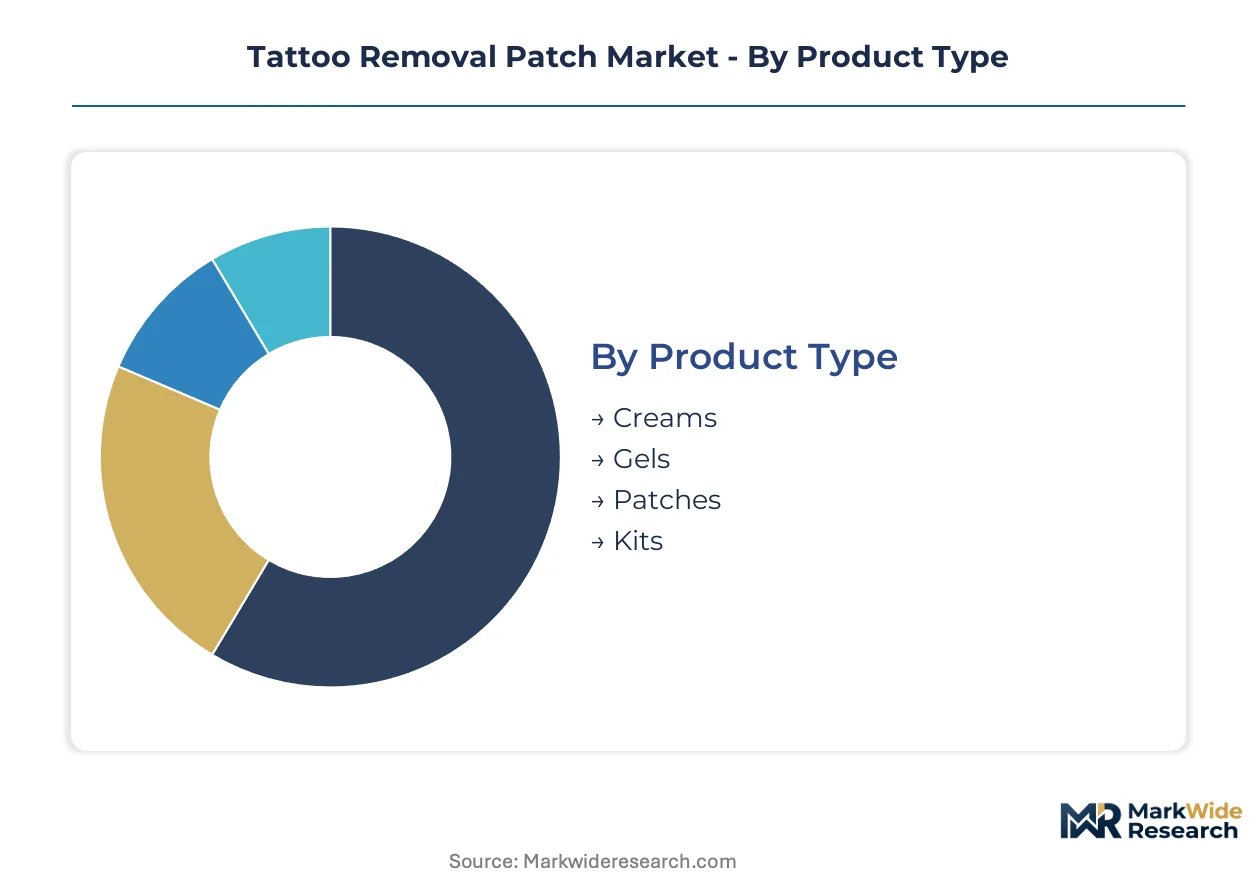
Segmentation in the tattoo removal patch market reveals divergent margin structures across delivery technologies and purchasing contexts. Product form factors and end-user settings determine regulatory pathways, pricing power, and repeat purchase velocity.
Product Type:
Cost tier differentiation separates professional-grade formulations from mass-market alternatives, with adhesion chemistry and active ingredient concentration driving per-unit economics.
- Patches:Dissolvable micro-needle arrays and extended-wear adhesive matrices command premium positioning through controlled-release kinetics. Dermatology clinics in Seoul and Los Angeles are expanding patch protocols for patients seeking alternatives to thermal ablation, with multi-day wear formulations reducing clinic visit frequency.
- Creams:Topical emulsions with alpha-hydroxy acid derivatives occupy volume leadership through salon and direct-to-consumer channels. Lower per-unit pricing and weaker retention profiles characterize this segment, though California's med-spa operators are bundling cream pre-treatment into membership programs.
- Gels:Semi-occlusive formulations with salicylic acid penetration enhancers target home users seeking visible results without prescription requirements.
- Kits:Multi-product regimens combining patches, creams, and post-treatment soothers capture subscription revenue through tele-dermatology platforms.
Patches command the established base. The steepest expansion runs through kits as subscription models displace single-unit retail.
Delivery Mode:
Application depth determines lymphatic clearance efficiency and regulatory classification intensity across jurisdictions.
- Transdermal:Active permeation past the stratum corneum via dissolvable micro-needles or chemical enhancers achieves deeper ink fragmentation. EU MDR clinical evidence requirements for active substance delivery elevate barriers, with notified bodies in Germany and the Netherlands extending review timelines for novel formulations.
- Topical:Surface-level application without barrier disruption avoids device classification in most jurisdictions. Salon channels in Seoul and Los Angeles favor topical protocols for walk-in clientele, though efficacy limitations against dermal ink persist.
- Oral:Systemic enzyme delivery remains investigational, with lymphatic targeting challenges limiting commercial penetration.
- Injection:Intradermal delivery of tattoo-degrading agents requires clinical administration and faces heightened FDA Center for Devices and Radiological Health scrutiny for combination product claims.
Transdermal systems concentrate purchasing power among dermatologists. Topical formulations are gaining share fastest in unsupervised home-use contexts.
End User:
Customer type shapes procurement scale, protocol adherence, and price sensitivity across treatment settings.
- Dermatologists:Protocol-driven repeat applications with clinical oversight generate the highest per-patient lifetime value. South Korea's medical aesthetics corridor concentrates specialist purchasing power, with practitioners bundling patch pre-treatment with fractional laser finishing.
- Home Users:Fragmented demand across direct-to-consumer brands exhibits weaker retention and higher price elasticity. California's cosmetic dermatology hubs see digital-native competitors eroding traditional clinic referrals through tele-dermatology bundling.
- Clinics:Multi-specialty aesthetic practices balance patch protocols against laser-installed bases, with Alma Lasers Ltd. and Cynosure, Inc. leveraging equipment relationships for cross-selling.
- Salons:Med-spa operators in Los Angeles integrate patch protocols into membership-based programs, creating recurring revenue streams with lower clinical oversight requirements.
Dermatologists anchor the revenue base. Home users are expanding most quickly as micro-needle dissolution chemistry collapses the clinic-grade barrier.
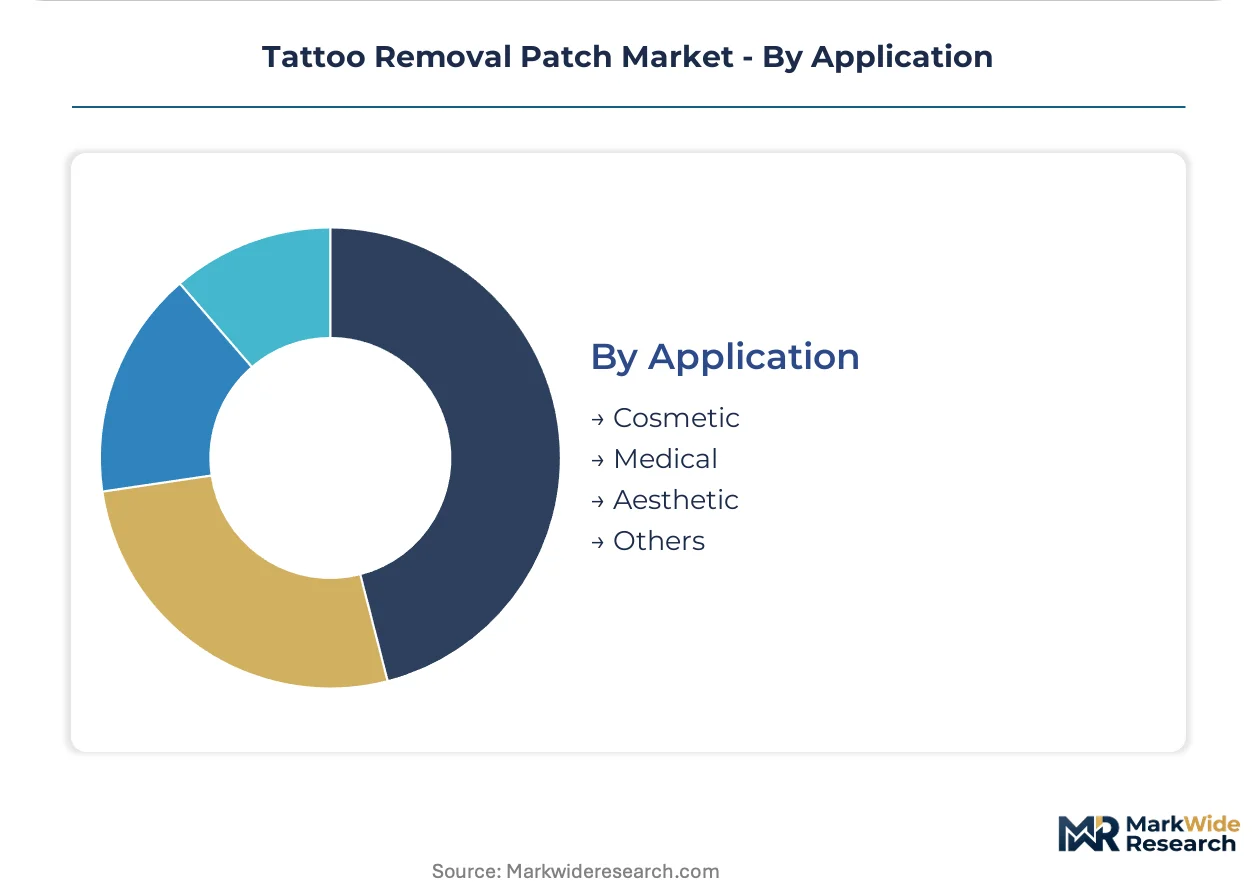
Application:
Use case context determines claims substantiation burden and reimbursement potential across regulatory environments.
- Cosmetic:Elective tattoo removal for aesthetic preference dominates volume, with FDA cosmetic labeling requirements tightening as enzymatic action claims blur the device boundary.
- Medical:Traumatic tattoo clearance and radiation marker removal command institutional purchasing through hospital dermatology departments, with ISO 10993 biocompatibility testing mandatory for adhesive matrices.
- Aesthetic:Preventive fading for tattoo modification or cover-up preparation bridges cosmetic and medical classifications, with EU MDR active dermal delivery device rules elevating documentation requirements.
- Others:Forensic and military identification removal represent niche demand with specialized procurement channels.
Cosmetic applications hold the installed base. Medical indications are climbing the fastest as hospital systems seek non-ablative alternatives for compromised skin.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for pharmaceutical-grade alpha-hydroxy acid derivatives concentrates supply risk in Germany and Switzerland, while patch manufacturers in South Korea and the United States drive formulation innovation for export markets.
United States
FDA Center for Devices and Radiological Health oversight of combination drug-device patches shapes compliance investments by domestic manufacturers. California's cosmetic dermatology hubs in Los Angeles and San Diego anchor demand for clinic-grade dissolvable micro-needle arrays. Med-spa operators in Beverly Hills integrate patch protocols into membership-based aesthetic programs.
South Korea
MFDS classification guidance for active dermal delivery devices accelerates clinical validation timelines for Seoul-based manufacturers. The medical aesthetics corridor spanning Gangnam and Apgujeong concentrates specialist purchasing power for protocol-driven repeat applications. Tele-dermatology platforms bundle patch shipments with remote progress monitoring for home users.
Germany
EU MDR notified bodies in Germany extend review timelines for novel adhesive formulations seeking CE marking. Pharmaceutical-grade chemical suppliers in Basel-adjacent regions anchor the active ingredient supply base for enzymatic patches. Frankfurt and Munich dermatology clinics adopt hybrid protocols bundling patch pre-treatment with fractional laser finishing.
Japan
PMDA consultation pathways for cosmetic-device boundary products shape registration strategies for transdermal delivery innovators. METI funding for bioprocess engineering talent supports enzyme preservation research in Osaka pharmaceutical clusters. Tokyo dermatology practices lead adoption of hyaluronic acid micro-arrays for patients with thermal sensitivity.
United Kingdom
MHRA post-Brexit recognition of EU MDR clinical evidence maintains market access for CE-marked patches while diverging classification debates create uncertainty. London Harley Street clinics concentrate private demand for premium transdermal formulations. Manchester and Birmingham med-spa chains test subscription-based patch regimens for price-sensitive segments.
Tattoo Removal Patch Market Competitive Landscape
On the supply side, the industry is consolidating around laser equipment incumbents with clinic-installed bases and emerging patch specialists with bioprocess engineering capabilities. Three strategic archetypes dominate: established aesthetic device manufacturers cross-selling complementary protocols, pharmaceutical-adjacent formulators with enzymatic preservation expertise, and direct-to-consumer brands leveraging tele-dermatology platforms. Capacity expansion in dissolvable micro-needle manufacturing and strategic partnerships between laser operators and patch formulators represent the dominant competitive vectors.
Among aesthetic device incumbents, Alma Lasers Ltd., Cynosure, Inc., and LUTRONIC Corporation exemplify the cross-selling archetype, leveraging existing clinic relationships to introduce patch protocols alongside installed laser bases. These companies occupy positions bridging thermal and non-thermal modalities, with their geographic footprints reflecting historical laser market penetration in Seoul, Los Angeles, and Tokyo dermatology networks.
| Leading Market Players |
|---|
| Cutera, Inc. |
| Syneron Medical Ltd. |
| Alma Lasers Ltd. |
| LUTRONIC Corporation |
| Quanta System S.p.A. |
| Lumenis Ltd. |
| Fotona d.o.o. |
| Sciton, Inc. |
| Cynosure, Inc. |
| Others |
Value Network & Pricing Analysis
Basel-adjacent pharmaceutical clusters in Switzerland and southwestern Germany concentrate active ingredient production for enzymatic tattoo removal patches, with their capacity utilization rates directly transmitting into downstream margin pressure for formulators lacking long-term offtake agreements.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the tattoo removal patch market. Price differentiation separates FDA-cleared transdermal devices from cosmetic-grade topical alternatives, with certification tier and volume scale as the primary drivers. Cost compression in the standard tier is intensifying because Korean and Chinese manufacturers are expanding dissolvable micro-needle capacity. Home users exhibit the highest price sensitivity, while dermatology clinics purchasing through GPO contracts demonstrate the lowest.
Supply Chain Analysis
Contract manufacturing for dissolvable micro-needle arrays concentrates among specialized pharmaceutical CDMOs in South Korea, Germany, and Japan. Raw material dependencies include pharmaceutical-grade hyaluronic acid, alpha-hydroxy acid derivatives, and enzymatic active agents. Single-source vulnerability runs through the narrow supplier base for dermal penetration enhancers concentrated in Basel-adjacent regions. Distribution runs through dermatology clinic networks, med-spa chains, and direct-to-consumer tele-dermatology platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating among dermatology GPOs and tele-dermatology platforms, with procurement scale shifting toward subscription-based patch regimens that fragment demand across fewer intermediaries.
For Market Incumbents: Entrench clinic relationships through backward integration into dissolvable micro-needle manufacturing capacity in South Korea or Germany. Secure ISO 10993 biocompatibility dossiers ahead of EU MDR clinical evidence requirements to extend certification lead times for emerging competitors. The threat of direct-to-consumer brands eroding referral networks demands channel control through exclusive med-spa partnerships. For New Entrants and Emerging Players: California's inland markets and secondary Japanese cities beyond Tokyo represent geographic underpenetration with weaker incumbent laser-installed bases. Target home-user segments in price-sensitive regions with tele-dermatology-bundled subscription models. A go-to-market angle through salon channel partnerships avoids the capital intensity of clinical trial investments required for dermatologist adoption. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because FDA and EU MDR classification tightening elevates barriers for capital-constrained entrants. Acquisition targets should display existing biocompatibility testing infrastructure and notified body relationships in Germany or the Netherlands. The signal to watch is MFDS guidance evolution in South Korea, where accelerated clinical validation pathways may compress competitive moats.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR clinical evidence requirements for active dermal delivery devices elevate documentation burdens for transdermal patch categories. |
| Backward Integration | In-house production of dissolvable hyaluronic acid micro-arrays reduces dependency on Basel-adjacent pharmaceutical suppliers. |
| Hospital System Partnership | Institutional procurement for medical tattoo removal indications creates non-ablative alternatives for compromised skin phototypes. |
| Direct-to-Consumer Launch | Tele-dermatology platforms in Seoul and Los Angeles bundle patch shipments with remote progress monitoring. |
| Reimbursement Strategy | Medical indication coding for traumatic tattoo clearance opens hospital dermatology department purchasing channels. |
Research Methodology
Initial hypotheses were tested against primary input from dermatology clinic operators, biomedical engineers, GPO contracts managers, and regulatory affairs leads, and refined through secondary validation against FDA 510(k) filings, EU MDR notified body documentation, ClinicalTrials.gov entries, and MFDS registration databases. Bottom-up patient volume estimates by treatment setting were triangulated against top-down manufacturer capacity disclosures.
Demand-supply balance modeling across the analysis window incorporated product type segmentation by patches, creams, gels, and kits; delivery mode by transdermal, topical, oral, and injection; and end-user categories spanning dermatologists, home users, clinics, and salons. CAGRs were derived from iterative reconciliation of procedure volume projections and per-treatment pricing trajectories. Industry-specific inputs included ISO 10993 biocompatibility testing timelines and EU MDR notified body review duration assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive moves by direct-to-consumer tele-dermatology platforms or laser equipment manufacturers into patch formulating would shift outcomes. Quarterly review of MFDS classification guidance evolution, FDA Center for Devices and Radiological Health enforcement patterns, and CE marking backlog durations at German and Dutch notified bodies is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Aesthetics
Europe Medical Aesthetic Devices Market
Medical Aesthetics
Photoelectric Medical Beauty Equipment Market
Medical Aesthetics
Japan Laser Hair Removal Market
Medical Aesthetics
Oculoplastic Surgery Market
Medical Aesthetics
Facial Injectables Market
Medical Aesthetics
Germany Facial Aesthetics Market
Medical Aesthetics
France Hair Transplant Market
Medical Aesthetics
Cosmetic Threads Market
Medical Aesthetics
Global Medical Aesthetic Devices Market
Medical Aesthetics
Korea Medical Aesthetics Market
Medical Aesthetics
Italy Hair Transplant Market
Medical Aesthetics
China Hair Transplant Market
Medical Aesthetics
Facial Injector Market
Medical Aesthetics
China Laser Hair Removal Market
Medical Aesthetics
India Hair Transplant Market
Medical Aesthetics
North America Laser Tattoo and Striae Removal Market