
 Radiotherapy Motion Management Market | 2026-2036
Radiotherapy Motion Management Market Size, Share, and Industry Trends Forecast 2026-2036
Radiotherapy Motion Management Market Outlook
Cancer treatment centers is reorganizing procurement priorities around real-time motion compensation during fractionated radiotherapy. Varian Medical Systems leverages its Calypso electromagnetic tracking legacy to anchor hospital loyalty across North American proton centers. Elekta AB competes through Unity MR-linac integration, while Accuray Incorporated specializes in robotic CyberKnife platforms that dominate intracranial and lung lesion workflows.
Radiotherapy motion management encompasses hardware and software systems that detect, predict, and compensate for patient movement during external beam delivery, typically achieving spatial tracking precision below one millimeter through optical, electromagnetic, or ultrasound modalities. The primary purpose is preserving tumor dose conformity while sparing adjacent healthy tissue during treatments spanning multiple fractions. Surface tracking systems lead product category revenue due to their non-contact deployment speed and compatibility with conventional linacs, whereas motion management software represents the fastest-expanding margin pool as vendors bundle AI-driven predictive algorithms into multi-year service contracts. Optical systems dominate technology adoption in breast and lung applications where infrared reflectance tracking of chest wall motion enables gated beam delivery without implanted fiducials.
FDA 510(k) premarket notification requirements shape product development cycles for electromagnetic and optical tracking devices, while CE marking under the EU MDR imposes clinical evidence standards that filter smaller vendors from European hospital tenders. ISO 13485 quality management certification operates as a baseline qualification for contract manufacturing partnerships across Japanese and German supply chains. Stakeholders must monitor reimbursement coding shifts for adaptive radiotherapy procedures, as CMS and national health technology assessment bodies increasingly predicate coverage on demonstrated motion management documentation.
Market Dynamics
Proton therapy center construction in the United States, Germany, and Japan is compressing installation timelines for integrated motion management systems, forcing vendors to pre-certify electromagnetic and optical tracking modules before facility commissioning rather than retrofitting post-installation.
Growth Catalysts
- EU MDR Clinical Evidence Standards:CE marking requirements under the Medical Device Regulation are filtering marginal competitors from European tenders, consolidating procurement decisions around vendors with established electromagnetic tracking portfolios and streamlining hospital vendor qualification processes.
- MR-Linac Installation Momentum:Unity and other magnetic resonance-linear accelerator platforms are mandating real-time surface tracking compatibility, creating hardware pull-through for optical and infrared motion detection systems across Nordic and Central European cancer centers.
- FDA 510(k) Pathway Efficiency:The premarket notification framework for electromagnetic tracking devices enables faster commercialization cycles than premarket approval routes, accelerating product iteration for respiratory gating algorithms and predictive motion compensation software.
Market Restraints
- Silicon Detector Supply Concentration:Infrared camera arrays and CMOS sensors for optical tracking systems depend on concentrated East Asian semiconductor foundry capacity, exposing hardware vendors to allocation volatility and extended lead times for high-resolution imaging components.
- Electromagnetic Field Interference Limitations:Calypso-style beacon tracking encounters signal degradation in magnetic resonance environments, restricting deployment to conventional linac installations and excluding the fastest-growing MR-linac segment without substantial hardware redesign.
- EU MDR Technical Documentation Burden:Clinical performance data requirements for Class IIa and IIb motion management devices impose documentation costs that disproportionately burden mid-tier vendors, reducing competitive diversity in German and French hospital procurement.
Strategic Opportunities
- India Cancer Center Expansion:The country's PLI scheme for medical device manufacturing and CDSCO regulatory harmonization efforts create entry pathways for surface tracking vendors willing to localize production and establish service networks in Mumbai and Delhi oncology clusters.
- AI-Driven Predictive Algorithms:Machine learning models trained on longitudinal patient respiratory patterns enable anticipatory beam gating, converging motion detection hardware with adaptive radiotherapy software to capture multi-year service contract value.
- Japan Proton Center Buildout:METI funding for particle therapy facilities and PMDA accelerated review pathways for breakthrough medical devices position Japanese installations as priority targets for integrated motion management system bundling.
Industry Challenges
- ISO 13485 Certification Timelines:Quality management system audits for contract manufacturing partnerships in German and Japanese supply chains extend vendor onboarding by 12-18 months, compressing product launch windows against competitor first-mover advantages.
- Legacy Linac Integration Complexity:Surface tracking retrofits on decade-old Varian and Elekta accelerators require custom mounting hardware and software interface development, fragmenting engineering resources across heterogeneous installed base configurations.
- Reimbursement Documentation Burden:CMS and national health technology assessment bodies increasingly predicate adaptive radiotherapy coverage on demonstrated motion management documentation, forcing treatment centers to invest in staff training for tracking system operation and data archiving protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Radiotherapy Motion Management Market |
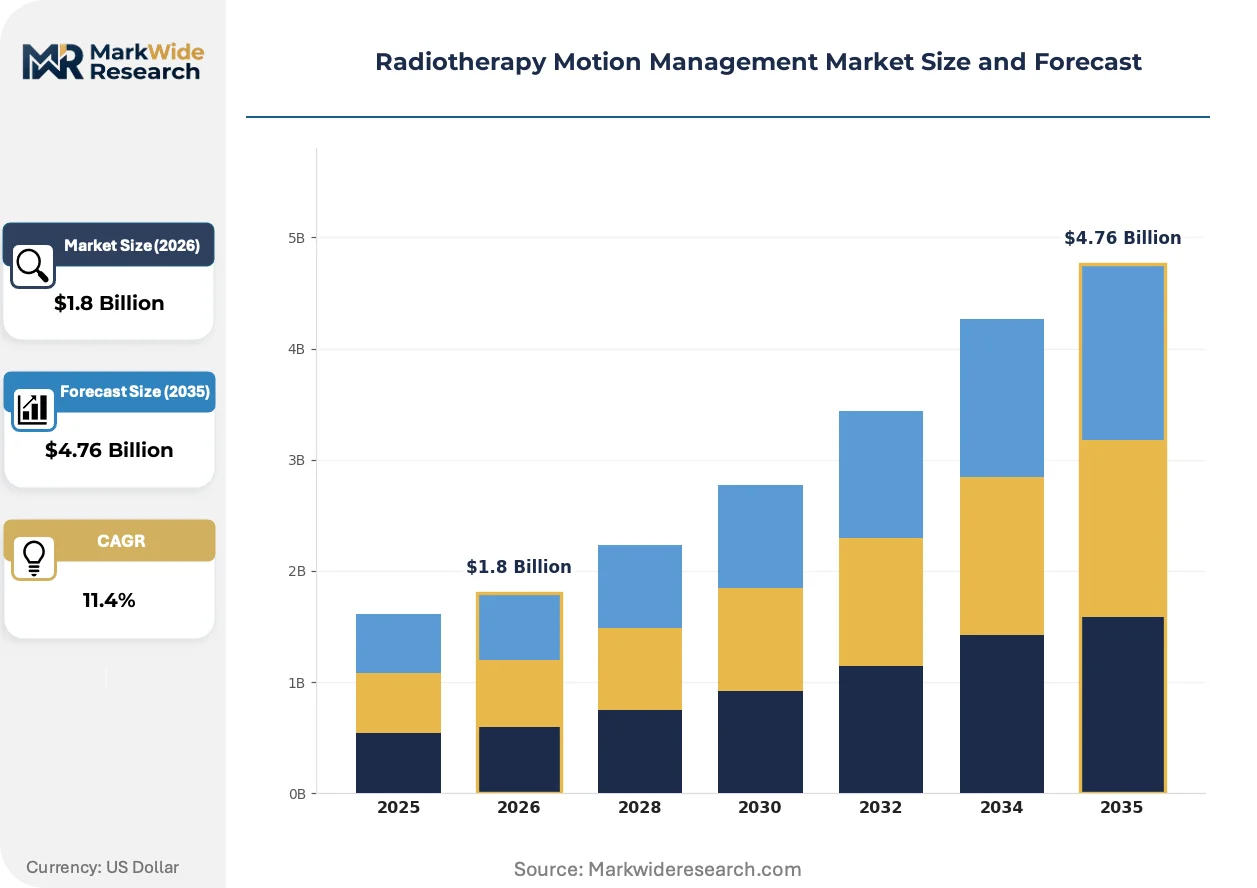
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surface Tracking Systems, Respiratory Gating Devices, Imaging Systems, Motion Management Software End User: Hospitals, Cancer Treatment Centers, Research Institutions, Academic Centers Technology: Optical Systems, Electromagnetic Systems, Ultrasound Systems, Infrared Systems Application: Breast Cancer, Lung Cancer, Prostate Cancer, Head & Neck Cancer |
| Companies Covered | Varian Medical Systems, Elekta AB, Accuray Incorporated, Promis Electro-Optics, Siemens Healthineers, ViewRay Technologies, IBA Worldwide, CIVCO Medical Solutions, GE Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Radiotherapy Motion Management Market Strategic Shifts
Artificial intelligence is compressing the latency between motion detection and beam modulation, enabling predictive rather than reactive gating algorithms that anticipate patient respiratory displacement before it occurs.
Deep learning respiratory prediction models are supplanting threshold-based gating protocols in lung and upper-abdominal treatments. Academic medical centers in the United States and Germany are piloting these systems for hypofractionated regimens where margin reduction carries amplified clinical consequence. The technology is compressing planning target volume margins by 2-3 millimeters, enabling dose escalation trials that were previously precluded by motion uncertainty.
FDA 510(k) clearance pathways for software-as-medical-device motion prediction algorithms are tightening evidentiary standards for locked versus adaptive algorithm architectures. Vendors must now submit performance validation across diverse patient populations and respiratory pathologies, extending pre-submission timelines but reducing post-market surveillance risk. Electromagnetic tracking vendors with predicate device portfolios navigate this transition more efficiently than optical-only competitors lacking legacy 510(k) foundations.
Hospital procurement committees are unbundling motion management hardware from multi-year linac service contracts, creating standalone evaluation criteria for surface tracking and electromagnetic systems. Nordic and Benelux cancer centers lead this transition, establishing separate technical specifications for tracking precision, integration latency, and vendor training obligations. The shift exposes pure-play motion management specialists to direct competition against integrated linac manufacturers previously protected by bundling economics.
Radiotherapy Motion Management Market Segmentation
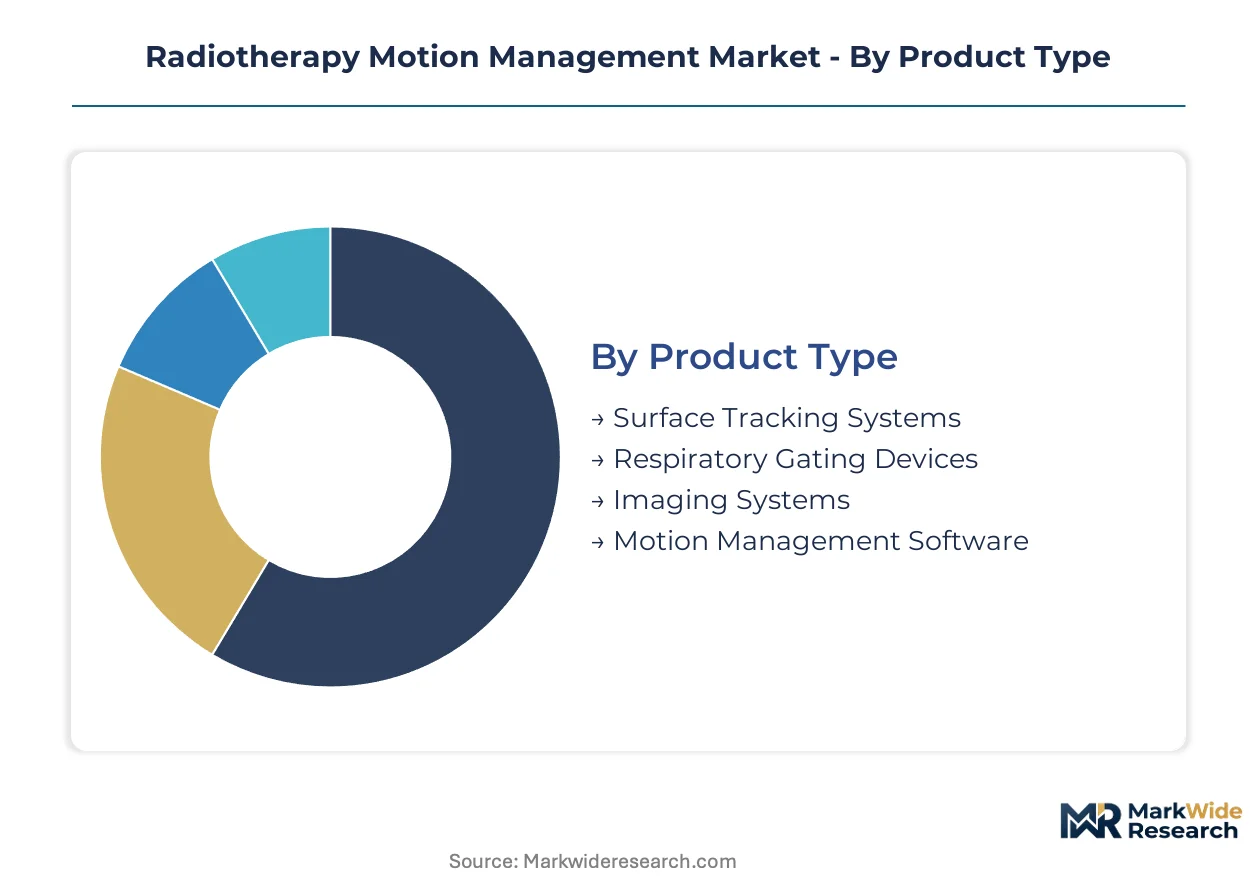
Segmentation in radiotherapy motion management reveals distinct procurement patterns across hardware categories and clinical settings. Treatment centers prioritize non-contact optical solutions for throughput efficiency while academic institutions drive software adoption for research protocols. Understanding these divides clarifies where vendors must localize service networks versus standardize global platforms.
Product Type:
Surface tracking systems and respiratory gating devices anchor domestic hospital procurement in the United States and Germany, whereas motion management software travels across borders through cloud-based licensing agreements with minimal physical infrastructure.
- Surface Tracking Systems:Non-contact infrared and optical arrays monitor patient chest wall or abdominal displacement without implanted fiducials. Demand clusters in breast and lung treatment workflows at high-volume cancer centers in Texas and Bavaria where fractionated schedules demand rapid patient turnover.
- Respiratory Gating Devices:Hardware-software combinations synchronize beam delivery to specific respiratory phases using external bellows or internal tracking. Japanese proton centers in Hyogo and Chiba specify these for moving tumor treatments where dose sparing of healthy tissue carries regulatory scrutiny under PMDA guidelines.
- Imaging Systems:Integrated fluoroscopic or CBCT modules for intra-fraction verification.
- Motion Management Software:AI-driven predictive algorithms and gating control interfaces.
Surface tracking commands the established base. The steepest expansion runs through motion management software.
End User:
Cost tier stratification separates capital-intensive hardware purchasers from software subscribers, with research institutions occupying a hybrid position that demands both.
- Hospitals:Integrated health systems with proton therapy investments in Florida, Pennsylvania, and Baden-Württemberg. These facilities bundle motion management into multi-year linac service contracts, prioritizing vendor consolidation over best-of-breed tracking precision.
- Cancer Treatment Centers:Dedicated oncology facilities with standalone radiation departments. Centers in Delhi and Mumbai under India's PLI scheme for medical devices are emerging as price-sensitive adopters of surface tracking retrofits on refurbished linacs.
- Research Institutions:National laboratories and clinical trial networks.
- Academic Centers:University-affiliated hospitals with residency programs.
Hospitals anchor procurement volume. Academic centers generate the steepest software licensing growth.
Technology:
Application specificity drives technology selection, with breast and abdominal treatments favoring optical modalities while pelvic applications retain electromagnetic legacy installations.
- Optical Systems:Camera-based surface imaging using structured light or passive stereo vision. These dominate new installations at MR-linac sites in Sweden and the Netherlands where electromagnetic interference excludes beacon-based alternatives under EMA clinical evidence standards.
- Electromagnetic Systems:Implanted or surface beacon tracking with AC magnetic field detection. Proton centers in the United States retain these for established lung workflows despite MR-linac incompatibility, protecting installed base investments.
- Ultrasound Systems:Real-time organ boundary visualization for prostate and liver targets.
- Infrared Systems:Reflective marker tracking for respiratory motion quantification.
Optical systems claim the fastest share gain. Electromagnetic systems defend the legacy installed base.
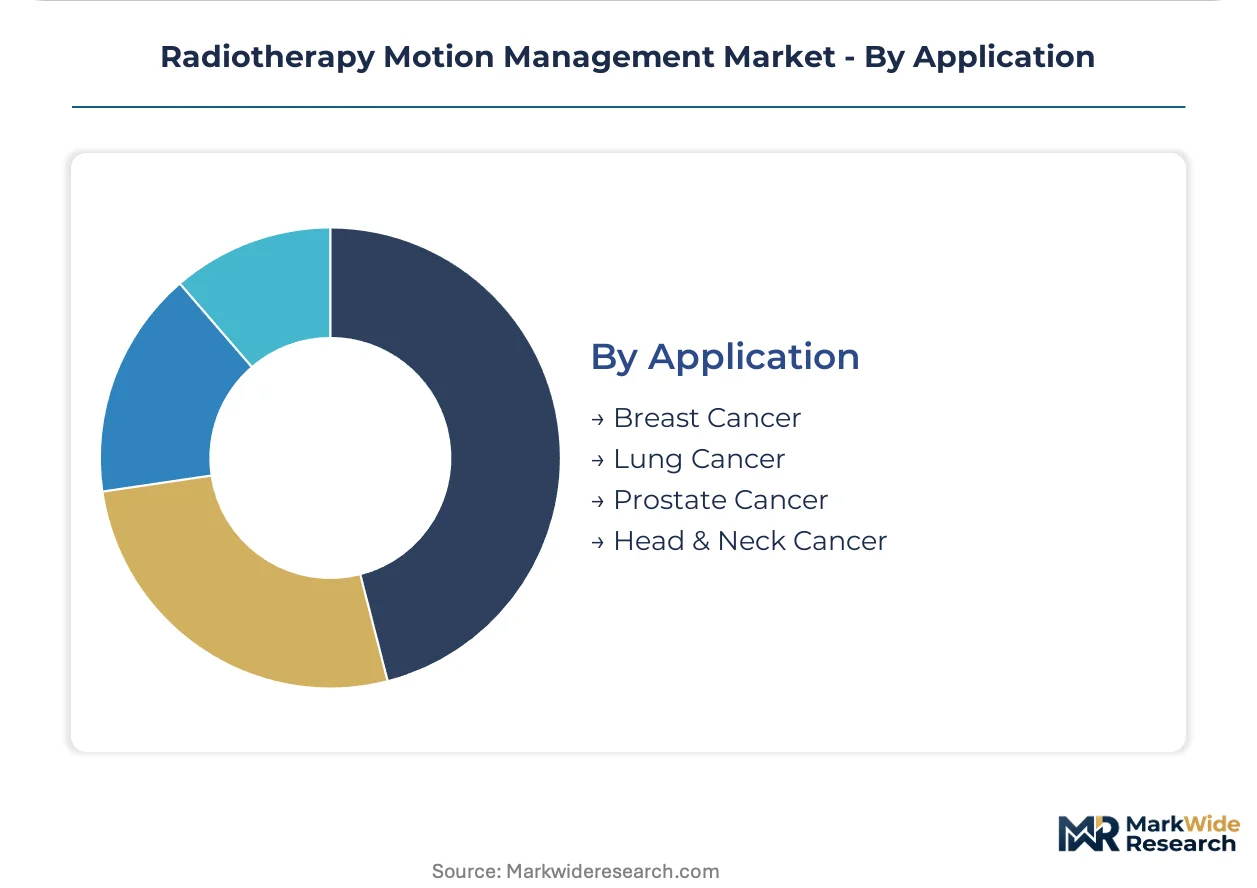
Application:
Volume concentration in lung and breast cases shapes vendor R&D allocation, while prostate and head & neck applications demand specialized tracking precision that commands premium pricing.
- Breast Cancer:Surface tracking enables supine positioning with continuous chest wall monitoring. German breast centers in Munich and Hamburg specify sub-millimeter optical precision for hypofractionated partial breast irradiation protocols.
- Lung Cancer:Respiratory gating and tumor tracking for moving targets. Stereotactic body radiation therapy programs in Arizona and Colorado drive demand for predictive algorithms that anticipate tumor displacement before beam delivery.
- Prostate Cancer:Ultrasound or electromagnetic tracking for intrafraction motion.
- Head & Neck Cancer:Rigid immobilization with optical position verification.
Lung cancer applications concentrate the highest technology investment. Breast cancer workflows deliver the broadest installed base expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and Japanese manufacturers export precision tracking hardware to proton therapy centers across the United States, establishing a trade corridor that concentrates high-value motion management system flows between these three markets.
United States
Proton therapy construction in Florida, Pennsylvania, and Texas drives hardware procurement for respiratory gating systems. FDA 510(k) premarket notification pathways accelerate commercialization timelines for electromagnetic tracking devices. The MD Anderson Cancer Center in Houston and Mayo Clinic in Rochester anchor demand for integrated surface tracking modules.
Germany
Breast cancer centers in Munich and Hamburg specify sub-millimeter optical precision for hypofractionated protocols. CE marking under EU MDR imposes clinical evidence standards that filter smaller vendors from hospital tenders. The Bavarian oncology cluster around Heidelberg and Tübingen leads MR-linac installations requiring compatible motion detection systems.
Japan
METI funding for particle therapy facilities in Hyogo and Chiba compresses installation timelines for electromagnetic tracking modules. PMDA accelerated review pathways for breakthrough medical devices position Japanese installations as priority targets for integrated system bundling. The National Cancer Center in Tokyo anchors research-driven demand for predictive motion compensation software.
India
The PLI scheme for medical device manufacturing and CDSCO regulatory harmonization create entry pathways for surface tracking vendors. Cancer treatment centers in Delhi and Mumbai emerge as price-sensitive adopters of retrofits on refurbished linacs. The Tata Memorial Hospital in Mumbai anchors procurement volume for optical tracking systems in the subcontinent.
Sweden
Unity MR-linac installations at Karolinska University Hospital mandate real-time surface tracking compatibility. EMA clinical evidence standards under EU MDR exclude electromagnetic beacon systems from magnetic resonance environments. The Stockholm oncology cluster drives Nordic adoption of camera-based optical modalities for lung and breast workflows.
Radiotherapy Motion Management Market Competitive Environment
Player mix skews toward integrated radiation therapy system manufacturers with embedded motion management portfolios, creating a concentrated structure where vendor consolidation outpaces pure-play specialist survival. Three archetypes dominate: linac-integrated platform vendors with captive tracking modules, proton therapy specialists with electromagnetic legacy installations, and optical hardware pure-plays serving MR-linac retrofit demand. Competitive moves center on pre-certification partnerships with proton center construction consortia and unbundling of tracking hardware from multi-year service contracts.
Within the integrated platform tier, Varian Medical Systems and Elekta AB occupy positions anchored by linac installed base control, while Accuray Incorporated exemplifies the robotic delivery specialist archetype with CyberKnife platform integration. These three companies represent the dominant competitive anchors, with Varian leveraging electromagnetic tracking heritage, Elekta driving MR-linac convergence, and Accuray defending intracranial and lung lesion specialization.
| Leading Market Players |
|---|
| Varian Medical Systems |
| Elekta AB |
| Accuray Incorporated |
| Promis Electro-Optics |
| Siemens Healthineers |
| ViewRay Technologies |
| IBA Worldwide |
| CIVCO Medical Solutions |
| GE Healthcare |
| Others |
Value Chain & Pricing Dynamics
Fourteen-to-eighteen-month lead times for CMOS sensor arrays concentrate pricing power among East Asian foundry partners, while proton therapy centers in Texas and Bavaria absorb premium markups for electromagnetic tracking modules bundled into facility commissioning contracts.
Pricing Analysis
Next-generation AI-driven predictive software commands subscription premiums threefold above legacy threshold-based gating systems, while prior-generation optical arrays face commoditization in Indian refurbishment markets. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared electromagnetic systems from CE-marked optical alternatives and unbranded surface tracking retrofits. Cost compression in economy-tier hardware intensifies because CDSCO harmonization invites price-sensitive Indian cancer centers. Academic medical centers in Germany and Japan exhibit lowest price sensitivity due to research grant funding, whereas standalone cancer treatment centers in Delhi and Mumbai prioritize capital expenditure minimization.
Supply Chain Analysis
Strategic stockpiling of infrared camera arrays and silicon photomultipliers distinguishes proton center construction consortia from just-in-time procurement patterns at conventional linac retrofit sites. Component sourcing centers on Taiwan and South Korea for CMOS sensors, Germany for precision optical assemblies, and Japan for electromagnetic beacon manufacturing. Raw material dependencies span rare-earth magnets for field generation, high-purity germanium for detector substrates, and specialized polymers for patient interface surfaces. Single-source vulnerability concentrates in East Asian semiconductor foundry capacity. Distribution runs through authorized service networks anchored by Varian and Elekta field engineering teams, with spare parts logistics coordinated from regional hubs in Houston, Heidelberg, and Tokyo.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as hospital procurement committees unbundle motion management hardware from multi-year linac service contracts, creating standalone evaluation criteria that favor specialized optical vendors over integrated platform manufacturers.
For Market Incumbents: Secure electromagnetic tracking installed base loyalty through predictive algorithm upgrades that extend service contract duration, while accelerating optical system certification for MR-linac compatibility to counter Elekta's Unity integration threat. Backward integration into CMOS sensor sourcing mitigates East Asian foundry allocation volatility that disrupts hardware delivery timelines. For New Entrants and Emerging Players: FDA 510(k) pre-submission pathways for software-as-medical-device motion prediction algorithms offer fastest regulatory clearance velocity, enabling entry through AI-driven respiratory gating modules that retrofit legacy Varian and Elekta linacs. Target price-sensitive cancer treatment centers in India's Delhi and Mumbai clusters with localized surface tracking production under PLI scheme incentives, leveraging cloud-based software licensing to minimize physical infrastructure investment. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because procurement unbundling exposes pure-play motion management specialists to acquisition by integrated linac manufacturers seeking optical capabilities for MR-linac convergence. Acquisition target archetype: optical hardware vendors with established EMA clinical evidence packages and Nordic hospital reference sites. Signal to watch: CMS reimbursement coding shifts that predicate adaptive radiotherapy coverage on demonstrated motion management documentation, accelerating replacement demand at academic medical centers.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR clinical evidence requirements filter marginal competitors from German and French hospital tenders. |
| Hospital System Partnership | Proton center construction consortia in Florida and Texas demand pre-certified tracking modules before commissioning. |
| Software Companion Development | AI-driven predictive algorithms bundled into multi-year service contracts capture recurring revenue from academic centers. |
| Reimbursement Strategy | CMS documentation requirements for adaptive radiotherapy coverage force treatment center investment in tracking infrastructure. |
| Geographic Expansion | CDSCO regulatory harmonization and PLI scheme incentives enable surface tracking localization in Mumbai oncology clusters. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with radiation oncology department heads, proton center construction project managers, biomedical engineers at academic medical centers, and GPO contracts managers at integrated health systems. Secondary validation drew from FDA 510(k) premarket notification databases, EMA clinical evidence documentation for EU MDR compliance, hospital procurement records from German and Japanese cancer centers, and CMS reimbursement coding bulletins. Bottom-up triangulation of installed base counts and replacement cycles converged with top-down expenditure estimates from national health technology assessment bodies.
Across the analysis window, the forecasting framework modeled volume and value trajectories through segmentation by product type, technology modality, application site, and end-user category, with regional regulatory cluster as an additional dimension. CAGRs were derived from logistic diffusion curves fitted to proton therapy and MR-linac installation pipelines, cross-referenced with replacement demand from legacy electromagnetic tracking depreciation schedules. Industry-specific inputs included PMDA accelerated review pathway utilization rates and PLI scheme medical device manufacturing incentive uptake in India.
Decision-makers should treat outputs as directional under assumptions of continued FDA 510(k) pathway efficiency and stable East Asian semiconductor foundry capacity; material deviation would warrant model refresh. Revision becomes warranted when EU MDR technical documentation requirements or CMS reimbursement coding shifts cross implementation thresholds that alter vendor competitive positioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Durable Medical Equipment Rental Market
Medical Equipment
Surgical Lighting System Market
Medical Equipment
Biomedical Refrigerators and Freezers Market
Medical Equipment
Medical Device and Equipment Tags Market
Medical Equipment
Medical Equipment Rental Market
Medical Equipment
Global Hospital Equipment and Supplies Market
Medical Equipment
Autopsy Saw Market
Medical Equipment
Medical Air Sterilizer Market
Medical Equipment
Medical Filter Market
Medical Equipment
Minor Surgical Lights Market
Medical Equipment
Autopsy Equipment Market
Medical Equipment
Medical Oxygen Concentrators and Oxygen Cylinders Market
Medical Equipment
Global Emergency Medical Equipment Market
Medical Equipment
Medical Gas Equipment Market
Medical Equipment
Mercury Thermometer Market
Medical Equipment
Global Surgical Lights Market