
 Global Medical Refrigerators Market | 2026-2036
Global Medical Refrigerators Market Size, Share, and Industry Trends Forecast 2026-2036
Global Medical Refrigerators Market Outlook
Research facilities and specialized biobanks is redrawing demand patterns that hospitals once dominated. Thermo Fisher Scientific Inc. leverages its laboratory channel dominance to control high-specification bio-storage installations across North America. Haier Biomedical anchors volume production of pharmacy-grade units through manufacturing scale in Asia. Vestfrost Solutions specializes in ultra-low temperature chest configurations for European blood bank networks.
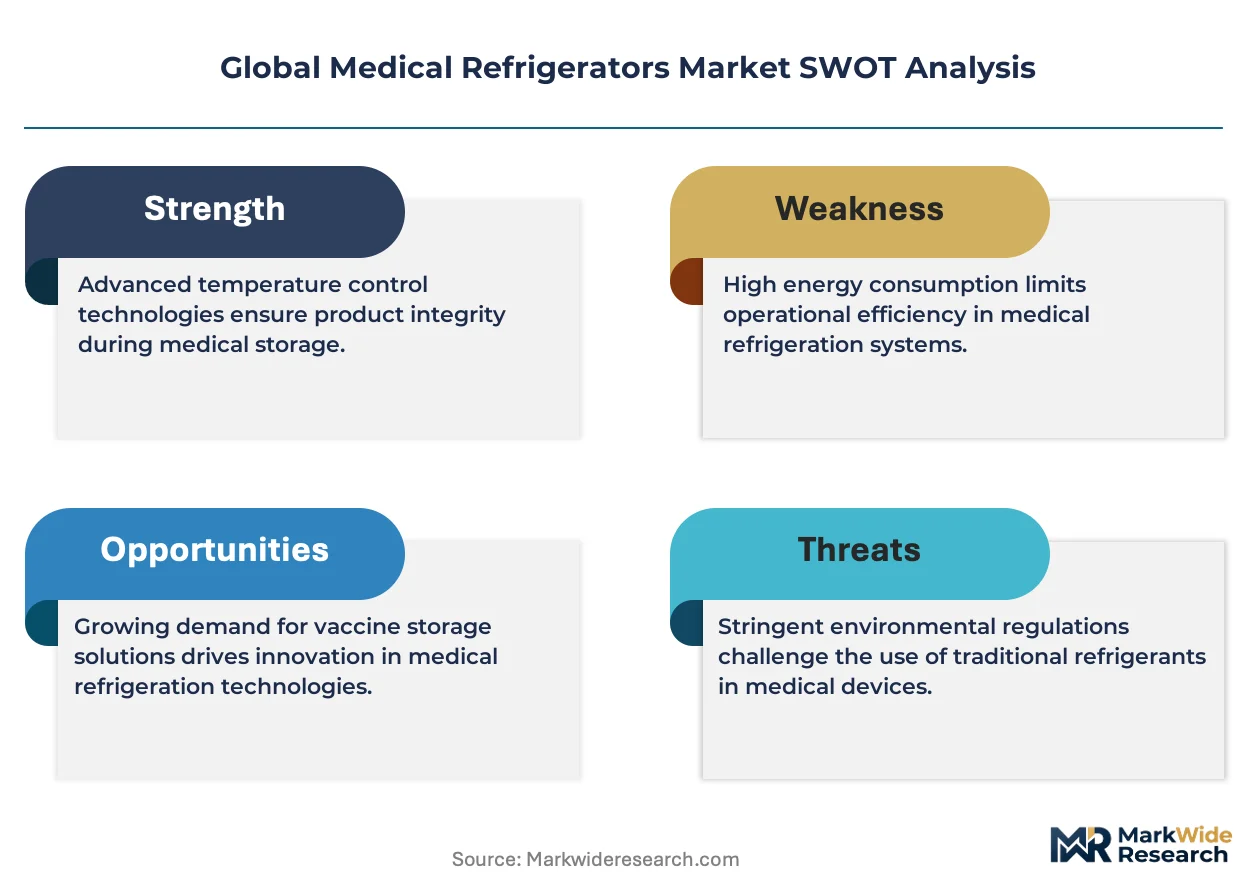
Medical refrigerators are precision thermal management cabinets engineered to maintain temperature ranges between 2°C and 8°C for pharmaceuticals, or -40°C to -86°C for biological specimens, using compressor-driven vapor compression cycles with redundant cooling circuits and continuous digital monitoring. Their primary purpose is to preserve potency of temperature-sensitive medical products from manufacture through point of administration. The upright product category leads installed base due to floor-space efficiency in clinical settings, while portable technology represents the fastest-expanding segment as field vaccination campaigns and mobile health programs multiply. Pharmacy end users command premium pricing because regulatory compliance burdens and alarm redundancy requirements exceed those of standard clinical storage.
FDA validation protocols, EMA Good Distribution Practice guidelines, and WHO Performance Quality and Safety standards collectively mandate temperature mapping, 24/7 alarm systems, and documented calibration cycles that elevate product specifications and barrier new entrants. The EU MDR and forthcoming EPA refrigerant phase-down rules will force compressor redesigns and natural refrigerant transitions. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and compliance gaps.
Market Dynamics
Biopharmaceutical cold chain logistics is redrawing procurement priorities among hospital systems and research facilities. The FDA and EMA have tightened temperature validation requirements for vaccine distribution networks.
Growth Catalysts
- Centralized immunization programs:National vaccination drives in the United States, Germany, and China are accelerating unit volume demand for pharmacy-grade cold storage infrastructure.
- EMA Good Distribution Practice guidelines:Temperature mapping mandates and 24/7 alarm system requirements are elevating product specifications across European distribution networks.
- Biobank expansions:Research facilities and specialized biobanks are displacing hospitals as the dominant demand source for ultra-low temperature configurations.
Market Restraints
- Compressor component concentration:Supply of precision cooling compressors concentrates among Asian manufacturing clusters, creating vulnerability for Western OEMs.
- Natural refrigerant transition costs:The EPA refrigerant phase-down rules are forcing costly redesigns of vapor compression cycles before economies of scale emerge.
- Copper and aluminum price volatility:Raw material swings for heat exchanger components are compressing margins on mid-tier product lines.
Strategic Opportunities
- Mobile health program expansion:Field vaccination campaigns across sub-Saharan Africa and Southeast Asia are creating demand for portable battery-powered refrigeration units.
- WHO Performance Quality and Safety standards:Pre-qualification pathways for emerging market tenders are opening procurement channels for certified manufacturers.
- IoT-enabled predictive maintenance:Convergence of cloud telemetry and compressor diagnostics is enabling outcome-based service contracts for hospital networks.
Industry Challenges
- Thermal validation engineer scarcity:Qualified technicians for temperature mapping and calibration documentation are in short supply across clinical settings.
- Legacy system integration friction:Hospital IT departments struggle to connect new digital monitoring platforms with existing building management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Medical Refrigerators Market |
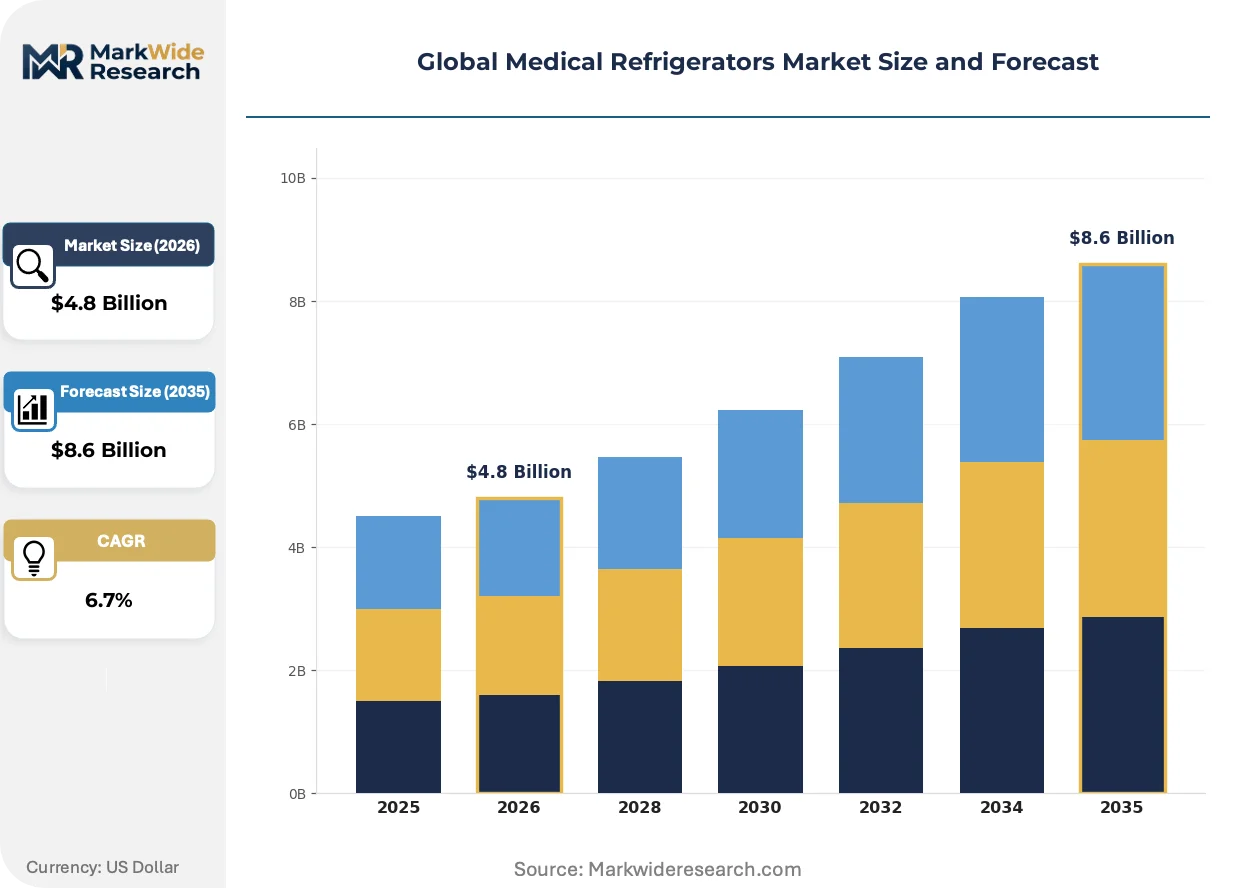
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Upright, Chest, Bio-Storage, Pharmacy End User: Hospitals, Clinics, Laboratories, Research Facilities Technology: Static, Dynamic, Dual Temperature, Portable Application: Vaccine Storage, Blood Banks, Biological Samples, Pharmaceuticals |
| Companies Covered | Helmer Scientific Inc., Vestfrost Solutions, Thermo Fisher Scientific Inc., Godrej & Boyce Manufacturing Co Ltd., Standex International Corporation, PHC Holdings Corporation, Blue Star Limited, Follett LLC, Haier Biomedical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Medical Refrigerators Market Strategic Shifts
Precision thermal management is undergoing a technology refresh as regulatory validation requirements harden and end-use applications fragment. Three developments are reshaping competitive positioning.
Solid-state thermoelectric cooling is displacing conventional compressor-driven systems in portable field units. Military medical corps and disaster response agencies are adopting these lighter configurations for vaccine transport. The technology is displacing mechanical refrigeration in applications below 50-liter capacity where weight and vibration tolerance matter more than energy efficiency.
The EU F-Gas Regulation is accelerating natural refrigerant adoption across European manufacturing. Hydrocarbon and carbon dioxide-based systems now dominate new product development for blood bank networks. German and French hospital procurement tenders are beginning to disqualify synthetic refrigerant platforms, compressing the viable product portfolio for suppliers serving these markets.
Research facilities are unbundling equipment purchase from validation services, treating compliance documentation as a separate procurement category. Biobank operators now contract third-party thermal mapping specialists rather than relying on OEM-provided certification. This shift is most pronounced in the United States, where research institutions maintain dedicated cold chain compliance departments with independent vendor relationships.
Global Medical Refrigerators Market Segmentation
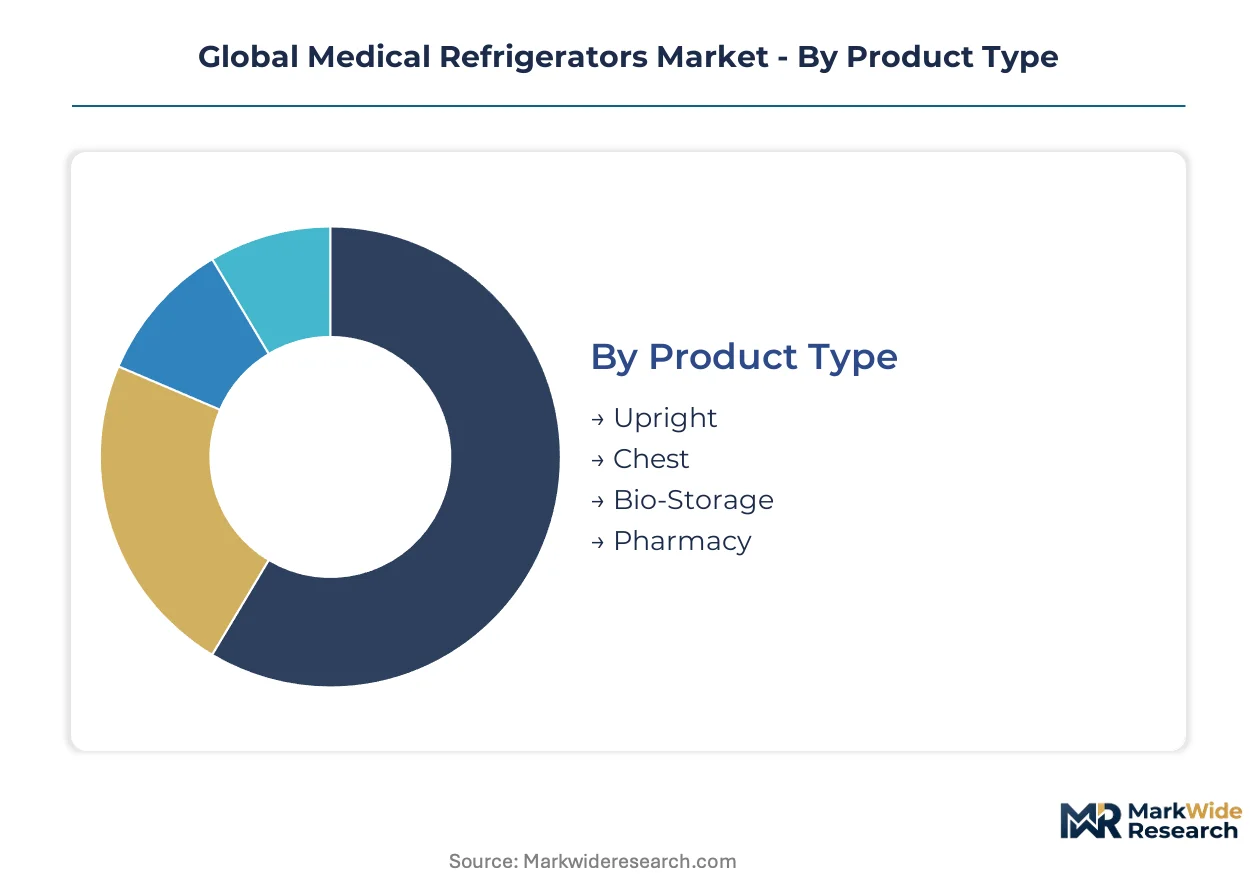
Temperature precision requirements fragment procurement specifications across clinical, research, and field deployment contexts. Substitution pressures vary sharply by segment—portable units face thermoelectric alternatives while pharmacy-grade cabinets compete on validation service bundling.
Product Type:
Portable configurations confront the most acute substitution threat from solid-state thermoelectric cooling in military and disaster response applications.
- Upright:Vertical cabinet designs maximize floor-space efficiency in crowded hospital pharmacies and clinical corridors. Demand concentrates in the United States and Germany where centralized immunization programs require high-density storage footprints.
- Chest:Horizontal ultra-low temperature configurations dominate blood bank networks and biobank installations across European hospital systems. EMA temperature mapping mandates favor these units for their thermal stability during power fluctuations.
- Bio-Storage:Specialized -86°C configurations with redundant cooling circuits serve research facilities preserving cellular materials and genetic specimens.
- Pharmacy:2°C to 8°C precision cabinets with 24/7 alarm systems and documented calibration cycles meet FDA validation protocols for vaccine distribution.
Upright configurations anchor the volume base while portable technology gains share at the steepest rate.
End User:
Cost tier stratification separates premium-specification research installations from standardized clinical procurement.
- Research Facilities:Ultra-low temperature demand centers on biobank expansions in China and specialized cryogenic storage for genomic research. These end users unbundle equipment purchase from third-party thermal mapping services.
- Hospitals:Pharmacy departments and blood banks drive replacement cycles for compressor-driven units with natural refrigerant transitions forced by EPA phase-down rules.
- Laboratories:Clinical diagnostic settings require dual-temperature flexibility for reagent storage and specimen processing workflows.
- Clinics:Smaller-scale 2°C to 8°C units serve point-of-care vaccination sites with simplified alarm systems and reduced compliance documentation burdens.
Hospitals anchor the volume base while research facilities gain share at the steepest rate.
Technology:
Application context determines whether static simplicity or dynamic precision takes procurement priority.
- Dynamic:Forced-air circulation systems maintain uniform temperature distribution for vaccine storage applications. WHO Performance Quality and Safety standards favor these configurations for national immunization tenders in sub-Saharan Africa.
- Portable:Battery-powered and solar-compatible units enable field vaccination campaigns across Southeast Asia. Solid-state thermoelectric alternatives displace compressor systems below 50-liter capacity where weight and vibration tolerance matter.
- Static:Gravity-driven cooling suffices for blood bank plasma storage with minimal door-opening frequency.
- Dual Temperature:Separate compartments for frozen and refrigerated storage serve laboratory workflows with mixed specimen requirements.
Dynamic systems anchor the volume base while portable configurations expand most quickly.
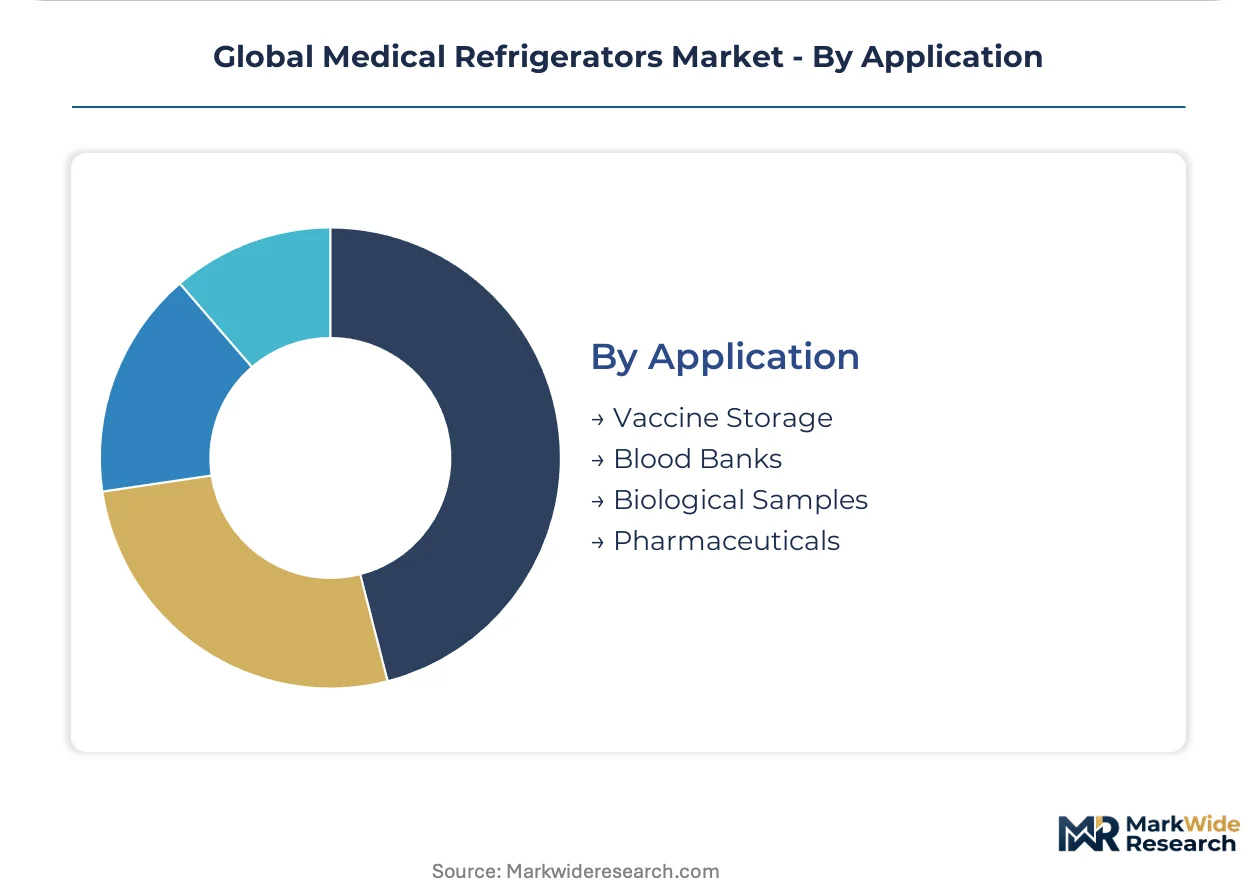
Application:
Margin structures diverge between regulated pharmaceutical storage and research specimen preservation.
- Vaccine Storage:2°C to 8°C precision with continuous digital monitoring supports national immunization programs. FDA and EMA validation requirements elevate product specifications and barrier new entrants.
- Biological Samples:Ultra-low temperature preservation for cellular materials and genetic specimens drives demand in Chinese biobank expansions and North American research institutions.
- Blood Banks:Plasma and erythrocyte storage configurations dominate European procurement with EU F-Gas Regulation accelerating natural refrigerant adoption.
- Pharmaceuticals:General drug storage applications in hospital pharmacies face pricing pressure from mid-tier product lines.
Vaccine storage anchors the volume base while biological sample applications climb the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Compressor manufacturing clusters in China, South Korea, and Japan supply precision cooling components to Western OEMs assembling finished units in Germany and the United States. This geographic split between component origin and final assembly shapes procurement lead times and regulatory compliance pathways across major demand centers.
United States
Hospital pharmacy networks and biobank expansions at the National Institutes of Health drive demand for ultra-low temperature configurations. FDA validation protocols for vaccine distribution mandate 24/7 alarm systems and documented calibration cycles that elevate product specifications. The Research Triangle Park in North Carolina concentrates cold chain compliance expertise serving academic medical centers.
Germany
Blood bank networks and centralized immunization programs sustain replacement cycles for pharmacy-grade units. EU F-Gas Regulation accelerates natural refrigerant adoption, disqualifying synthetic refrigerant platforms from hospital procurement tenders. The Baden-Württemberg industrial corridor hosts engineering specialists developing hydrocarbon-based compressor systems.
China
National biobank expansions and genomic research initiatives propel demand for -86°C bio-storage configurations. NMPA medical device registration requirements and dual carbon goals pressure manufacturers toward energy-efficient natural refrigerant transitions. The Yangtze River Delta manufacturing belt concentrates volume production of compressor components serving domestic and export markets.
India
Universal Immunization Programme scale-up and cold chain infrastructure investments create procurement volume for 2°C to 8°C portable units. CDSCO medical device regulations and PLI scheme incentives attract domestic assembly investment. The Pune-Ahmedabad industrial corridor emerges as a fabrication hub for solar-compatible field refrigeration systems.
Japan
Academic research institutions and pharmaceutical quality control laboratories sustain premium demand for precision thermal management. PMDA pharmaceutical manufacturing guidelines and METI energy efficiency standards shape product development priorities. The Kansai region around Osaka maintains specialized engineering capacity for ultra-low temperature cascade cooling systems.
Global Medical Refrigerators Market Competitive Environment
Concentration sits with diversified laboratory equipment conglomerates and specialized cold chain fabricators serving distinct end-use tiers. The vendor base spans three strategic archetypes: precision laboratory equipment providers with channel dominance in research settings, volume manufacturers leveraging Asian production scale for standardized clinical units, and regional specialists capturing blood bank and field deployment niches. Competitive dynamics revolve around M&A activity consolidating validation service capabilities and capacity expansion into natural refrigerant platform manufacturing.
Among laboratory equipment conglomerates, Thermo Fisher Scientific Inc. and PHC Holdings Corporation exemplify the precision-tier archetype with established research facility relationships. Haier Biomedical anchors the volume-manufacturing segment with Chinese production scale serving hospital pharmacy procurement globally. Vestfrost Solutions occupies a specialist position within European cold chain networks. These three patterns—conglomerate precision, Asian volume scale, and regional specialization—structure competitive positioning across temperature ranges and compliance requirements.
| Leading Market Players |
|---|
| Helmer Scientific Inc. |
| Vestfrost Solutions |
| Thermo Fisher Scientific Inc. |
| Godrej & Boyce Manufacturing Co Ltd. |
| Standex International Corporation |
| PHC Holdings Corporation |
| Blue Star Limited |
| Follett LLC |
| Haier Biomedical |
| Others |
Value Chain & Pricing Dynamics
FDA validation protocols and EMA Good Distribution Practice guidelines gate both supplier qualification and price differentiation simultaneously, compressing margins for uncertified fabricators while elevating premiums for compliant manufacturers serving hospital pharmacy networks and biobank installations.
Pricing Analysis
FDA and EMA temperature mapping mandates dictate the pricing tier structure across the medical refrigerator landscape. Three-tier pricing separates premium validation-bundled configurations from standard pharmacy-grade units from economy clinical cabinets without redundant cooling circuits. Price differentiation rests on certification grade and after-sales service bundling, with research facilities commanding the highest premiums for third-party thermal mapping documentation. Cost compression in mid-tier product lines is intensifying because copper and aluminum price volatility for heat exchanger components squeezes fabricator margins. Clinics and point-of-care vaccination sites exhibit the greatest price sensitivity, while biobank operators prioritize compliance documentation over unit cost.
Supply Chain Analysis
Container availability fluctuations on Asia-Europe trade lanes and port congestion at Shanghai and Rotterdam disrupt inbound logistics for precision cooling compressors and electronic control modules. Manufacturing gravity centers on China, South Korea, and Japan for compressor components, with final assembly concentrating in Germany and the United States for proximity to hospital procurement channels. Raw material dependencies span copper and aluminum for heat exchangers, rare earth elements for compressor motors, and specialized insulation foams. Single-source vulnerability concentrates in Asian precision cooling compressor fabrication, exposing Western OEMs to geopolitical friction and logistics chokepoints. Distribution runs through laboratory equipment distributors, GPO contracts with hospital systems, and direct tenders with national immunization programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The medical refrigerator market functions as a regulatory moat business where FDA and EMA validation entrenchment creates prohibitive switching costs for hospital pharmacy networks and research facilities.
For Market Incumbents: Compound defensive positioning by deepening captive supply of natural refrigerant compressor platforms ahead of EPA phase-down deadlines, and acquiring third-party thermal mapping specialists to capture unbundled validation services demand from biobank operators. Thermoelectric portable alternatives threaten compressor-driven field units below 50-liter capacity, demanding R&D investment in hybrid cooling architectures. For New Entrants and Emerging Players: Lead with solar-compatible portable configurations targeting sub-Saharan African and Southeast Asian field vaccination campaigns where WHO Performance Quality and Safety pre-qualification opens procurement channels underserved by incumbent laboratory equipment conglomerates. Mobile health programs represent the most penetrable demand pocket, with battery-powered units enabling outcome-based service contracts as the preferred go-to-market angle. For Investors and Strategic Acquirers: The EPA refrigerant phase-down and EU F-Gas Regulation reshapes the acquisition landscape toward natural refrigerant engineering capabilities and validation service bundling. Long-term viability favors manufacturers with backward integration into compressor platforms and established hospital GPO relationships. Acquisition target archetypes include regional cold chain specialists with blood bank network penetration and thermoelectric cooling engineering shops. The signal to watch is German and French hospital procurement tender language disqualifying synthetic refrigerant platforms, indicating accelerated portfolio obsolescence for legacy manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Natural Refrigerant Platform Transition | EPA phase-down rules and EU F-Gas Regulation force compressor redesigns before economies of scale emerge. |
| Validation Service Unbundling | Biobank operators now contract third-party thermal mapping specialists rather than OEM-provided certification. |
| Portable Battery-Powered Expansion | Field vaccination campaigns across sub-Saharan Africa create demand for solar-compatible thermoelectric units. |
| IoT Predictive Maintenance Integration | Cloud telemetry convergence enables outcome-based service contracts with hospital pharmacy networks. |
| WHO Pre-Qualification Pathway | Performance Quality and Safety certification opens procurement channels for emerging market tenders. |
Study Parameters
The analysis maps upright, chest, portable, and bio-storage product configurations, each validated through procurement managers at hospital pharmacy networks, biomedical engineers at research facilities, cold chain compliance officers at biobank operators, and aftermarket service heads at laboratory equipment distributors. Primary fieldwork combined structured interviews with secondary validation against FDA 483 inspection observations, EMA Good Distribution Practice guidance documents, WHO Performance Quality and Safety pre-qualification databases, and hospital GPO contract disclosures. Bottom-up unit shipment modeling triangulated against top-down addressable market sizing across temperature range, end-use, and geographic demand clusters.
Consistency checks validated volume and value outputs against external benchmarks including customs trade data for compressor component flows, hospital capital expenditure surveys from academic medical centers, and national immunization program cold chain investment disclosures. The analytical framework modeled product type, end user, technology, and application dimensions across the projection horizon, with CAGRs derived from segment-specific demand elasticity and replacement cycle analysis. Industry-specific forecast inputs incorporated EPA refrigerant phase-down implementation timelines and EU MDR device registration pathway durations.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement of temperature validation protocols or accelerated natural refrigerant transitions would require recalibration. Forecasts reflect documented assumptions regarding hospital capital expenditure continuity, biobank expansion funding, and compressor component supply chain stability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
US ECG Equipment Market
Medical Equipment
Europe Medical Equipment Maintenance Market
Medical Equipment
Asia-Pacific Medical Carts Market
Medical Equipment
Benchtop Platelet Agitator Market
Medical Equipment
Global Hospital Equipment and Supplies Market
Medical Equipment
Medical Whirlpool Market
Medical Equipment
Histology Embedding System Market
Medical Equipment
Medical Filter Market
Medical Equipment
Global Plasma Sterilizers Market
Medical Equipment
Cath Lab Market
Medical Equipment
Global Optometry Equipment Market
Medical Equipment
North America Nuclear Medicine Equipment Market
Medical Equipment
X-Ray Generator Market
Medical Equipment
Urodynamic Equipment Market
Medical Equipment
Podiatry Equipment Market
Medical Equipment
Contact Lens Inspection Equipment Market