
 Helicopter MRO Market | 2026-2036
Helicopter MRO Market Size, Share, and Industry Trends Forecast 2026-2036
Helicopter MRO Market Intelligence
Aftermarket service revenue is rewriting competitive economics across the Helicopter MRO landscape. Lufthansa Technik leverages its European network to dominate engine overhaul contracts for medium and heavy twin-engine platforms. Air France Industries KLM Engineering & Maintenance anchors its position through integrated airframe and component capabilities across offshore and SAR operator fleets. Sikorsky competes by extending proprietary military support agreements into government contractor maintenance programs.
Helicopter MRO encompasses the inspection, repair, overhaul, and modification of rotary-wing aircraft systems to sustain airworthiness and operational availability, typically involving turbine engine hot-section refurbishment at defined flight-hour intervals and dynamic component replacement based on fatigue-life tracking. Engine overhaul commands the deepest margin pools due to specialized tooling and proprietary technical data requirements, while component repair segments attract growing investment as operators pursue unit-cost reduction through part-life extension programs. Military services represent a structurally distinct demand channel characterized by long-term performance-based logistics contracts and sovereign fleet prioritization.
The FAA mandates compliance with 14 CFR Part 43 and 145 standards for repair station certification, while EASA enforces Part 145 and continuing airworthiness management organization requirements across European-registered fleets. Military operators face additional country-specific technical airworthiness authority oversight that fragments procurement and limits cross-border maintenance sourcing flexibility. Stakeholders must monitor how digital airworthiness record-keeping mandates and predictive maintenance platform integration reshape technician skill requirements and capital deployment priorities.
Market Dynamics
Performance-based logistics contracts are compressing traditional time-and-material billing models across military and offshore operator segments. Sovereign fleet operators now demand guaranteed availability metrics rather than discrete overhaul events.
Growth Catalysts
- Offshore Oil & Gas Fleet Utilization:North Sea and Gulf of Mexico operators are extending flight-hour programs on heavy-lift platforms, triggering accelerated engine hot-section refurbishment cycles at defined intervals.
- EASA Continuing Airworthiness Mandates:Updated Part 145 requirements for component traceability are forcing non-compliant repair stations into upgrade investments, consolidating demand toward certified providers.
- Dynamic Component Life Tracking:Fatigue-life monitoring systems embedded in main rotor hubs and transmissions are enabling predictive replacement scheduling, expanding addressable maintenance events.
Market Restraints
- Specialized Tooling Concentration:OEM-controlled proprietary fixtures for turbine engine overhauls limit independent repair station entry, particularly for latest-generation turboshaft models.
- Technician Certification Bottlenecks:FAA Part 65 Airframe and Powerplant license holders with rotary-wing endorsements remain scarce relative to fixed-wing peers, constraining labor supply elasticity.
- Raw Material Volatility:Nickel-based superalloy pricing fluctuations directly impact engine component repair economics, compressing margin predictability for independent shops.
Strategic Opportunities
- India Defense Modernization:Indigenous helicopter fleet expansion under the country's Make-in-India framework creates demand for localized heavy maintenance infrastructure and technical training partnerships.
- Predictive Maintenance Platform Integration:Convergence of IoT sensor networks with AI-driven failure prediction models enables remote condition monitoring, opening subscription-based revenue streams for MRO providers.
- Emergency Medical Services Fleet Renewal:Aging single-engine air ambulance platforms in the United States approach mandatory retirement thresholds, driving replacement-induced component demand.
Industry Challenges
- Digital Airworthiness Record-Keeping Compliance:FAA and EASA mandates for electronic maintenance logs require legacy repair stations to retrain technicians and retool documentation workflows.
- Cross-Border Military Sourcing Restrictions:Country-specific technical airworthiness authority oversight fragments procurement, limiting maintenance sourcing flexibility for multinational defense contractors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Helicopter MRO Market |
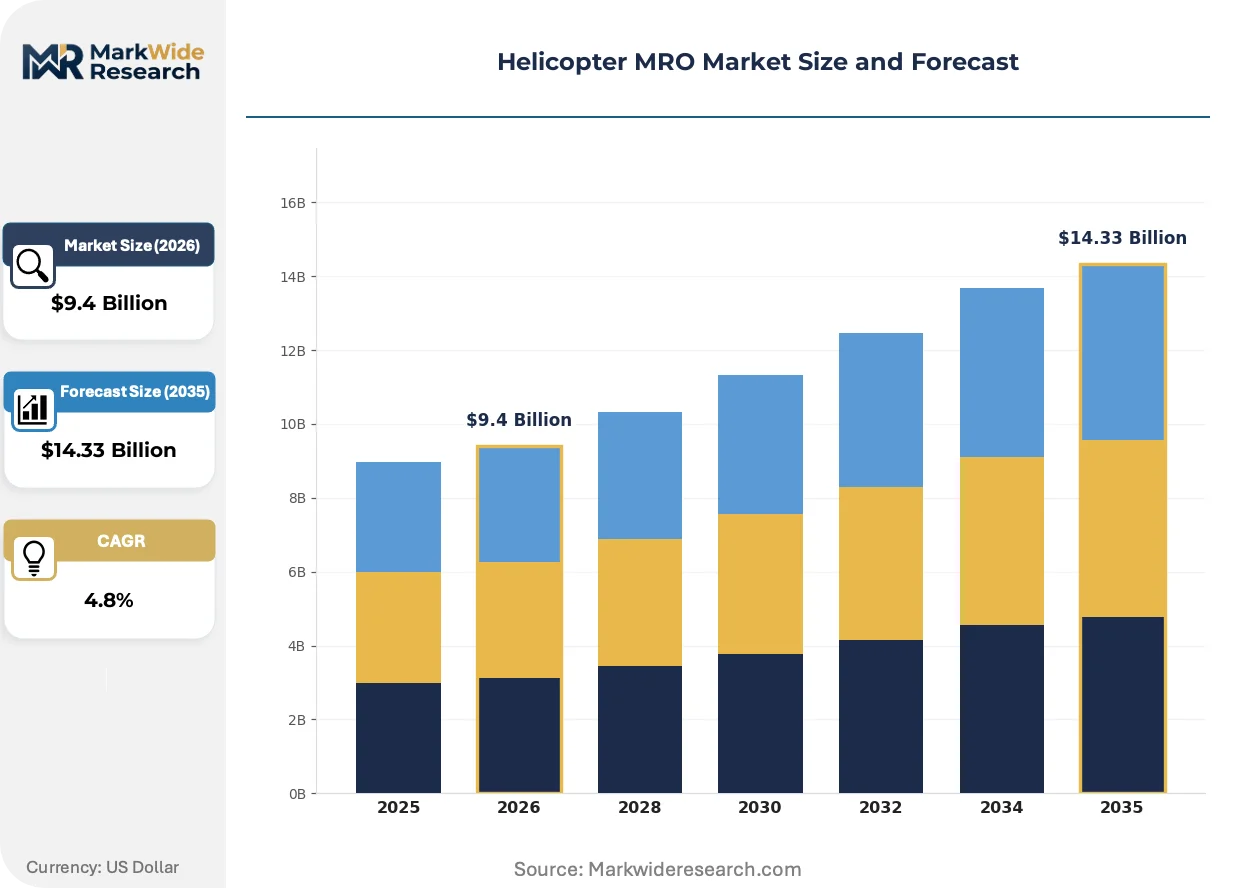
| Market Size in 2026 | $9.4 Billion |
| Market Size in 2035 | $14.33 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Airframe Maintenance, Engine Overhaul, Component Repair, Modifications End User: Commercial Operators, Military Services, Government Agencies, Private Owners Technology: Traditionally Operated, Advanced Avionics, UAV Integration, Maintenance Management Systems Deployment Model: Onsite Maintenance, Offsite Repair, Scheduled Inspections, Emergency Services |
| Companies Covered | Delta TechOps, Air France Industries KLM Engineering & Maintenance, Lufthansa Technik, MTU Maintenance, SR Technics, ST Engineering Aerospace, HAECO Group, Sikorsky, AAR Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Helicopter MRO Market Strategic Shifts & Innovations
Digital thread technologies are collapsing the information gap between flight operations and maintenance planning. Real-time data flows now determine inventory positioning and technician dispatch priorities.
Health and Usage Monitoring Systems is digitizing component degradation tracking across main rotor systems and turbine engines. Offshore operators in the North Sea are deploying these platforms fleet-wide. The technology is digitizing maintenance scheduling from calendar-based to condition-based intervals, compressing unnecessary removal events.
EASA's updated Part 145 requirements for continuing airworthiness management organizations are tightening component traceability standards. Repair stations must now demonstrate electronic parts pedigree documentation. European-registered offshore and search-and-rescue fleets are absorbing compliance costs through consolidated supplier relationships.
Power-by-the-hour contracts are displacing transactional overhaul procurement among medium-twin operators. Fixed-cost-per-flight-hour agreements now cover engine, dynamic component, and airframe elements. This model concentrates most visibly in United Kingdom and Norwegian offshore oil and gas segments.
Helicopter MRO Market Segmentation
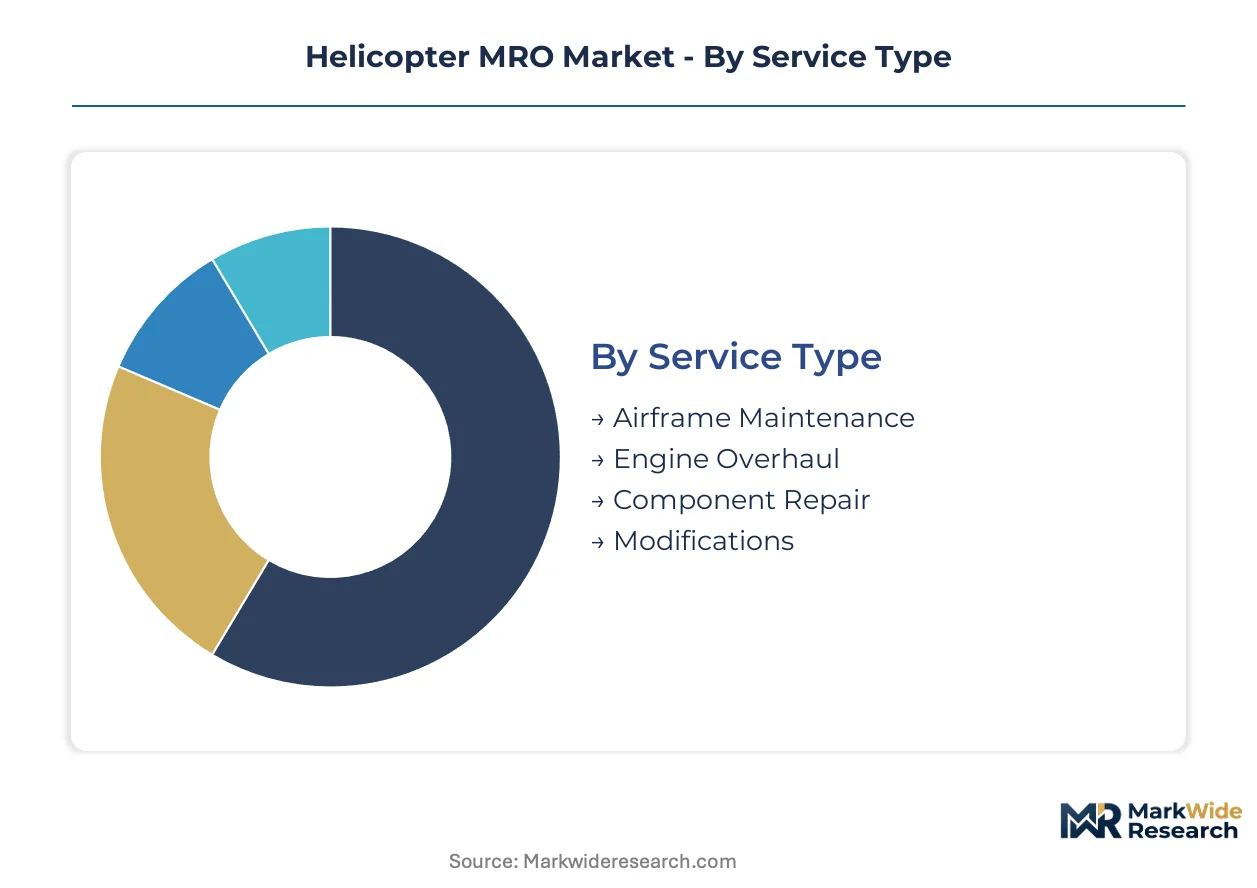
Helicopter MRO providers configure service portfolios around distinct operational rhythms. Fleet operators select service tiers based on utilization intensity, regulatory jurisdiction, and asset ownership structure.
Service Type:
Maintenance intensity varies across airframe age, engine cycles, and component fatigue accumulation.
- Airframe Maintenance:Structural inspections and corrosion control programs sustain airworthiness across aluminum and composite fuselage assemblies. Offshore oil and gas operators in the United Kingdom and Norway drive heavy demand for salt-environment protection treatments and periodic reskinning.
- Engine Overhaul:Hot-section refurbishment of turboshaft powerplants requires proprietary tooling and OEM technical data access. FAA Part 145 repair stations dominate this segment in the United States due to concentrated military and emergency medical services fleet density.
- Component Repair:Dynamic system refurbishment extends service life for main rotor hubs, gearboxes, and flight controls.
- Modifications:Avionics upgrades and mission equipment reconfigurations adapt platforms to evolving operational requirements.
The dominant share belongs to Engine Overhaul, while Component Repair is closing the gap fastest.
End User:
Procurement patterns diverge sharply between sovereign fleet operators and commercial asset managers.
- Commercial Operators:Offshore transport, emergency medical services, and utility contractors purchase maintenance through power-by-the-hour contracts or transactional event billing. Gulf of Mexico helicopter operators favor guaranteed availability agreements that transfer utilization risk to MRO providers.
- Military Services:Performance-based logistics contracts lock in multi-year maintenance commitments with sovereign technical airworthiness oversight. United States Army and Navy rotary-wing programs concentrate overhaul volume at domestic military depots and approved contractor facilities.
- Government Agencies:Search-and-rescue and law enforcement fleets balance budget constraints with regulatory compliance mandates.
- Private Owners:Individual aircraft operators rely on scheduled inspections at certified repair stations with limited in-house technical capability.
Commercial Operators command the largest contract value, with Military Services expanding most quickly through fleet modernization programs.
Technology:
Digital integration depth determines maintenance scheduling precision and parts traceability compliance.
- Traditionally Operated:Analog flight instruments and mechanical control systems persist in legacy light-single platforms. Private owners and small commercial operators in the United States sustain demand for conventional inspection protocols.
- Advanced Avionics:Glass cockpit configurations and integrated flight management systems require specialized diagnostic equipment. EASA Part 145 mandates for electronic maintenance records accelerate upgrade investments across European-registered fleets.
- UAV Integration:Unmanned rotary-wing platforms introduce novel airworthiness certification pathways and component lifing methodologies.
- Maintenance Management Systems:Predictive analytics platforms consolidate Health and Usage Monitoring System data for condition-based intervention scheduling.
Advanced Avionics captures the majority of current upgrade expenditure, though Maintenance Management Systems is gaining share fastest through fleet-wide platform deployments.
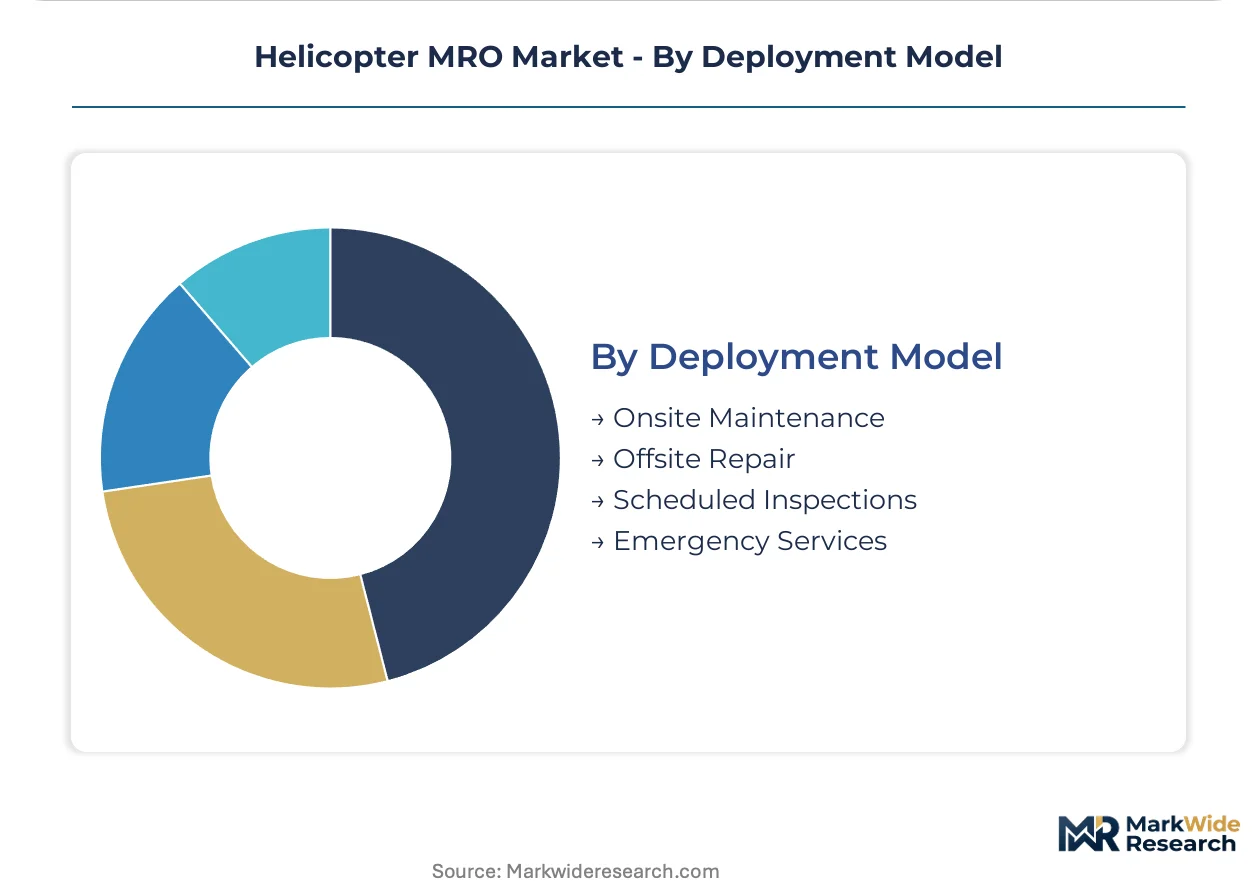
Deployment Model:
Physical proximity to operating bases shapes cost structure and response capability.
- Onsite Maintenance:Dedicated personnel and equipment positioned at operator facilities enable rapid turnaround for high-utilization fleets. North Sea offshore operators maintain captive maintenance crews at heliport installations to minimize aircraft downtime.
- Offsite Repair:Centralized overhaul facilities achieve economies of scale on complex engine and component work. Lufthansa Technik and Air France Industries KLM Engineering & Maintenance anchor European offsite capacity for medium and heavy twin-engine platforms.
- Scheduled Inspections:Calendar and flight-hour-based maintenance events follow manufacturer-defined airworthiness limitation schedules.
- Emergency Services:AOG response teams deploy specialized technicians and replacement components to restore operational status.
Offsite Repair holds the dominant position, while Onsite Maintenance is climbing the fastest as operators prioritize availability guarantees.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MRO capacity concentrates where helicopter utilization intensity intersects with regulatory stringency. Repair station density follows offshore oil platforms, military basing patterns, and emergency medical services corridors across five dominant national markets.
United States
FAA Part 145 repair stations cluster around Gulf of Mexico offshore corridors and military rotorcraft hubs. The Army and Navy sustain heavy overhaul volume through performance-based logistics contracts at domestic depots. Dallas-Fort Worth anchors the largest concentration of independent engine overhaul capacity.
Germany
Lufthansa Technik leverages Hamburg and Frankfurt maintenance bases to capture European medium-twin engine contracts. EASA Part 145 continuing airworthiness mandates drive consolidation toward certified providers with electronic traceability systems. Bavaria hosts specialized component repair facilities serving Alpine rescue and police aviation fleets.
United Kingdom
North Sea offshore operators demand guaranteed availability agreements from Aberdeen-based maintenance crews. The Civil Aviation Authority enforces stringent component life-tracking documentation for SAR and oil transport fleets. Somerset and Cornwall house airframe specialists focused on salt-environment corrosion programs.
France
Air France Industries KLM Engineering & Maintenance anchors European heavy maintenance through Paris-Charles de Gaulle infrastructure. EASA mandates for electronic maintenance records accelerate platform upgrades across offshore and EMS operator fleets. Marseille hosts Mediterranean-focused dynamic component specialists.
Singapore
ST Engineering Aerospace positions Changi-based facilities to capture Asia-Pacific offshore and military aftermarket demand. The Civil Aviation Authority of Singapore aligns certification standards with EASA and FAA reciprocity agreements. Seletar Aerospace Park concentrates regional component repair and engine overhaul investment.
Helicopter MRO Market Key Industry Players
Full-service airline-affiliated MROs and independent specialists split the market along capability depth and customer access vectors. Consolidation favors providers with proprietary technical data licenses and captive fleet relationships. Two archetypes dominate: integrated aviation groups leveraging passenger airline infrastructure, and OEM-captive services extending military support agreements. Competitive moves center on power-by-the-hour contract expansion and predictive maintenance platform integration.
Among integrated aviation groups, Air France Industries KLM Engineering & Maintenance and Lufthansa Technik occupy positions defined by European network density and engine overhaul specialization. Sikorsky represents the OEM-captive archetype, anchoring military aftermarket channels through sovereign fleet support programs. These three exemplify how technical data access and long-term service agreements create defensive positioning against independent repair station competition.
| Leading Market Players |
|---|
| Delta TechOps |
| Air France Industries KLM Engineering & Maintenance |
| Lufthansa Technik |
| MTU Maintenance |
| SR Technics |
| ST Engineering Aerospace |
| HAECO Group |
| Sikorsky |
| AAR Corporation |
| Others |
Cost & Logistics Intelligence
Dallas-Fort Worth anchors the densest concentration of FAA Part 145 repair stations in North America, concentrating engine overhaul capacity that feeds pricing power downstream to military and EMS fleet operators. This geographic clustering shapes contract economics across the Helicopter MRO landscape.
Pricing Analysis
FAA Part 145 certification dictates the pricing tier structure across the Helicopter MRO market, separating authorized repair stations from uncertified competitors. Three-tier pricing structure across premium, standard, and economy levels reflects OEM technical data access, with engine overhaul commanding premium positioning due to proprietary tooling requirements. Cost compression in component repair segments is intensifying because operators pursue part-life extension programs. Commercial offshore operators exhibit highest price sensitivity, while military services demonstrate lowest sensitivity under performance-based logistics frameworks.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for nickel-based superalloy feedstocks critical to turbine engine component manufacturing. The Helicopter MRO supply chain draws from Germany, Singapore, and the United States for specialized tooling and replacement parts. Raw material dependencies center on cobalt, titanium alloys, and precision-machined castings. Single-source vulnerability persists for OEM-controlled proprietary fixtures. Distribution runs through authorized dealer networks and direct military procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technician certification scarcity defines competitive moats in this market, with FAA Part 65 Airframe and Powerplant license holders bearing rotary-wing endorsements remaining structurally scarce relative to fixed-wing peers.
For Market Incumbents: Build proprietary technical data licensing moats by securing exclusive OEM maintenance agreements for latest-generation turboshaft platforms. Expand predictive maintenance platform integration to capture subscription revenue streams. Counter independent repair station competition through guaranteed availability contracts that transfer utilization risk from offshore operators.
For New Entrants and Emerging Players: Pursue India defense modernization opportunities under the Make-in-India framework, where localized heavy maintenance infrastructure demand outstrips certified supply. Target emergency medical services fleet renewal in the United States as aging single-engine platforms approach mandatory retirement thresholds. Establish technical training partnerships with sovereign fleet operators as the primary go-to-market mechanism.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors repair stations with integrated Health and Usage Monitoring System capabilities and electronic airworthiness documentation compliance. Long-term viability rests on digital thread integration depth rather than legacy calendar-based maintenance scheduling. Acquisition target archetype: mid-size European Part 145 providers with offshore oil and gas fleet relationships. Monitor EASA continuing airworthiness mandate enforcement velocity as the inflection indicator for consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Integration | Converges IoT sensor networks with AI-driven failure prediction for condition-based scheduling across North Sea offshore fleets. |
| Technical Training Partnership Expansion | Addresses FAA Part 65 certification bottlenecks through structured apprenticeship programs with community aviation colleges. |
| Electronic Traceability System Deployment | Satisfies EASA Part 145 component pedigree documentation mandates for European-registered SAR and oil transport operators. |
| Power-by-the-Hour Contract Scaling | Displaces transactional overhaul procurement among United Kingdom and Norwegian medium-twin offshore operators. |
| OEM Technical Data Licensing Acquisition | Secures proprietary maintenance protocols for latest-generation turboshaft engines that independent stations cannot access. |
Research Approach
Operator-level perspectives from fleet maintenance directors, FAA Part 145 repair station managers, military logistics procurement officers, and offshore oil and gas aviation supervisors anchored the qualitative base. Primary interviews combined with secondary validation from FAA airworthiness directives, EASA continuing airworthiness management organization filings, offshore operator fleet utilization reports, and military performance-based logistics contract disclosures. Bottom-up service demand modeling and top-down market sizing triangulated volume estimates.
Scenario-bracketing framed the analytical approach across the projection horizon, with segmentation dimensions spanning service type, end user procurement pattern, technology integration depth, and deployment model proximity. CAGRs derived from flight-hour accumulation curves, fleet age profiles, and regulatory compliance cycle frequencies. Industry-specific forecast inputs incorporated Health and Usage Monitoring System adoption trajectories and power-by-the-hour contract penetration rates.
Macroeconomic conditions sit as an overlay; deviation in nickel-based superalloy pricing, sovereign defense budget allocations, or offshore oil and gas capital expenditure cycles would shift the trajectory. Forecasts reflect documented assumptions about technician certification pipeline recovery and regulatory mandate implementation schedules. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Maintenance and MRO Solutions
Digital Aerospace MRO Market
Aircraft Maintenance and MRO Solutions
Asia-Pacific Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Storage, Preservation and Reactivation Services Market
Aircraft Maintenance and MRO Solutions
Aviation MRO Software Market
Aircraft Maintenance and MRO Solutions
Aviation Maintenance Training Market
Aircraft Maintenance and MRO Solutions
Aviation Maintenance Repair and Overhaul MRO Software Market
Aircraft Maintenance and MRO Solutions
Commercial Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Autoclave Market
Aircraft Maintenance and MRO Solutions
Southeast Asia Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Aviation Maintenance Software Market
Aircraft Maintenance and MRO Solutions
Digital MRO Market
Aircraft Maintenance and MRO Solutions
Middle-East and Africa Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Colombia Commercial Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Gas Turbine MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Line Maintenance Market
Aircraft Maintenance and MRO Solutions
Africa Aircraft Windshield Wiper and Washer System Market