
 Africa Aircraft Windshield Wiper and Washer System Market | 2026-2036
Africa Aircraft Windshield Wiper and Washer System Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Aircraft Windshield Wiper and Washer System Market Analytics
Buyer concentration across Africa's commercial aviation sector is pivoting toward national flag carriers and expanding low-cost operators in East and West Africa. Safran S.A. leverages its established supply relationships with Airbus and Boeing platforms serving African operators. Eaton Corporation anchors aftermarket distribution through regional logistics partnerships in Johannesburg and Lagos. Honeywell International Inc. competes on integrated avionics-visibility system bundles that reduce airline procurement complexity.
Africa aircraft windshield wiper and washer systems comprise electromechanical and hydraulic actuation assemblies, typically fabricated from corrosion-resistant aluminum alloys and fluoropolymer-coated rubber elements, designed to maintain pilot optical clarity during precipitation, dust, and insect contamination events across tropical and desert operating environments. Electric wiper systems now lead product type demand as operators phase out hydraulic architectures to reduce weight and maintenance burden. The aftermarket installation segment captures expanding margin pools as Africa's in-service fleet ages and local MRO capabilities mature.
South Africa's Civil Aviation Authority, Nigeria's NCAA, and Kenya's KCAA enforce airworthiness standards aligned with ICAO Annex 8 that mandate functional visibility system certification for continued operational approval. These regulators shape demand by requiring OEM-traceable components and documented maintenance histories that filter out non-certified suppliers. Stakeholders must monitor harmonization between national aviation authorities and EASA-equivalent standards as African Union Single African Air Transport Market implementation advances.
Market Dynamics
Electric actuation architectures are displacing hydraulic wiper systems across African commercial fleets as operators prioritize weight reduction and simplified maintenance protocols in tropical operating conditions. This technology transition concentrates procurement decisions around integrated avionics bundles rather than standalone visibility components.
Growth Catalysts
- ICAO Annex 8 Alignment:Kenya's KCAA and Nigeria's NCAA mandate functional visibility system certification for operational approval, forcing fleet upgrades among aging domestic carriers.
- East African Fleet Expansion:Ethiopian Airlines and RwandAir are adding narrow-body aircraft with factory-installed electric wiper architectures, creating pull-through demand for compatible aftermarket components.
- Fluoropolymer-Coated Rubber Elements:These corrosion-resistant materials extend service intervals in dust-heavy Sahel operations, reducing total cost of ownership for Nigerian and Malian operators.
Market Restraints
- Aluminum Alloy Input Volatility:Electromechanical wiper arm fabrication depends on aerospace-grade aluminum pricing, which fluctuates with LME spot markets and African import tariff regimes.
- OEM Supply Concentration:Certified wiper system manufacturing concentrates in European and North American facilities, exposing African MROs to extended lead times and currency conversion risk.
- Hydraulic System Lock-In:Legacy Boeing 737 Classic fleets operated by several African carriers retain hydraulic wiper architectures, fragmenting spare parts demand across incompatible technical standards.
Strategic Opportunities
- Johannesburg MRO Hub Development:South Africa's maturing maintenance capabilities create regional distribution nodes for wiper blade and motor assemblies serving sub-Saharan operators.
- Sensor-Wiper Convergence:Integration of rain detection sensors with automatic wiper actuation enables premium retrofit packages for executive aircraft based in Lagos and Nairobi.
- African Union SAATM Implementation:Harmonized airworthiness standards across 35 signatory states streamline certification pathways for visibility system suppliers entering new national markets.
Industry Challenges
- Aerospace Electrician Skill Scarcity:Conversion to electric wiper systems demands technicians trained in avionics troubleshooting, a capability gap acute in secondary African MRO facilities.
- EASA-Equivalent Certification Timelines:National aviation authorities in Ghana and Tanzania lack delegated authority for rapid parts approval, delaying aftermarket product introductions by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Aircraft Windshield Wiper and Washer System Market |
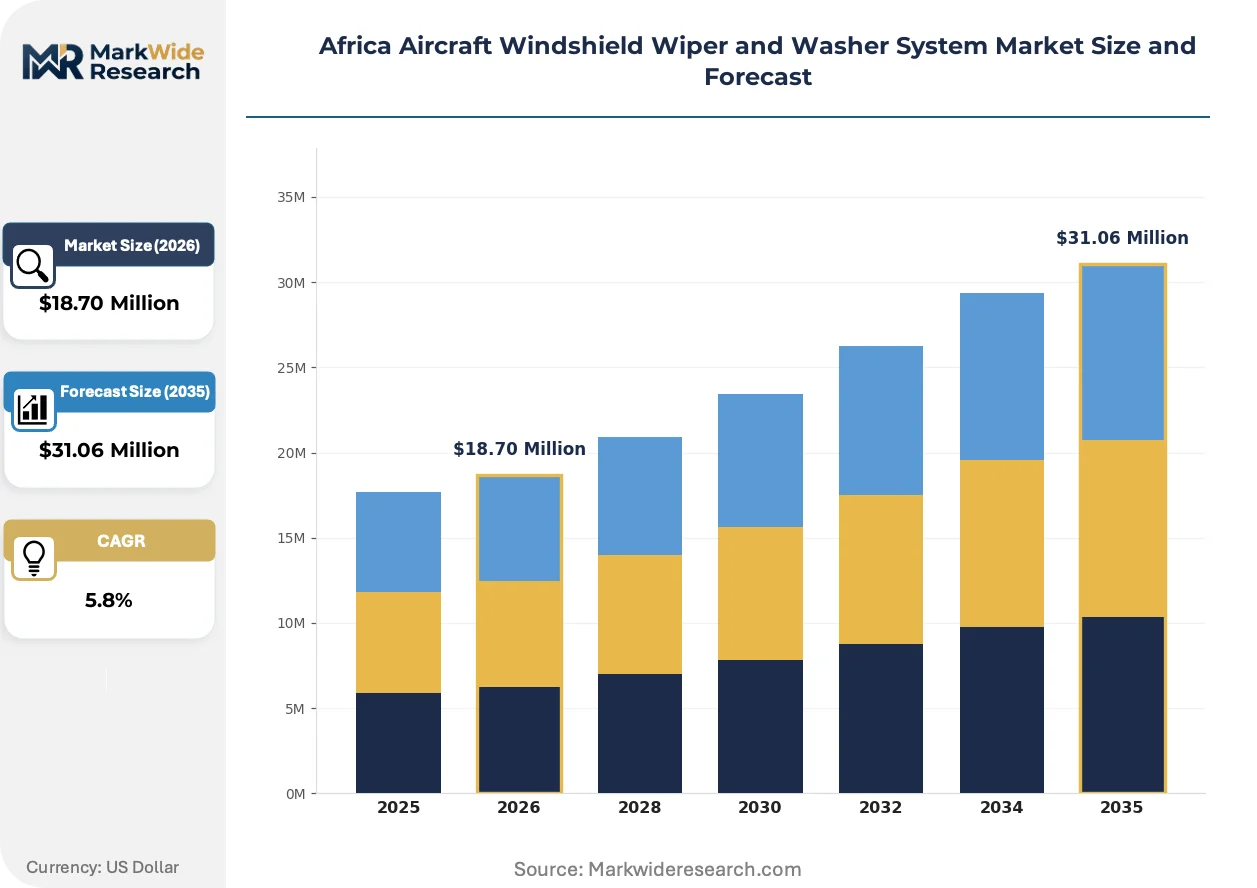
| Market Size in 2026 | $18.70 Million |
| Market Size in 2035 | $31.06 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional Wipers, Electric Wipers, Hydraulic Wipers, Washer Pumps End User: Commercial Aviation, Military Aviation, General Aviation, Private Jets Installation Type: OEM, Aftermarket, Retrofit, Remanufactured System Type: Single Wiper System, Dual Wiper System, Integrated Wash System, Standalone Wash System |
| Companies Covered | RTX Corp., Moog Inc., Safran S.A., PPG Industries, Liebherr Aerospace, Eaton Corporation, Raytheon Technologies, Aerosystems S.r.l., Honeywell International Inc., Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Aircraft Windshield Wiper and Washer System Market Evolving Landscape
Visibility system engineering is pivoting toward predictive maintenance integration and modular component architectures that reduce aircraft-on-ground downtime. These shifts compress traditional procurement cycles and elevate software-enabled diagnostic capabilities alongside mechanical hardware.
Brushless DC motor technology is rewriting electromechanical wiper performance standards. These motors eliminate brush wear failures common in legacy designs. Ethiopian Airlines and Kenya Airways are specifying brushless architectures in new fleet procurement. This specification shift is rewriting supplier qualification criteria toward electronics expertise rather than pure mechanical fabrication.
South Africa's Civil Aviation Authority has tightened airworthiness directive enforcement on flight deck equipment traceability. This policy requires documented maintenance histories and OEM-traceable components for continued operational approval. Low-cost carriers operating mixed fleets face compliance cost pressure. Nigerian domestic operators are responding by consolidating visibility system procurement through approved distributor networks in Lagos.
Airlines are unbundling visibility system maintenance from full airframe service contracts. This pattern separates component-level MRO decisions from airframe heavy maintenance scheduling. Independent MRO providers in Johannesburg and Nairobi are capturing these disaggregated service relationships. East African carriers show the strongest unbundling momentum as they build internal technical capabilities.
Africa Aircraft Windshield Wiper and Washer System Market Segmentation
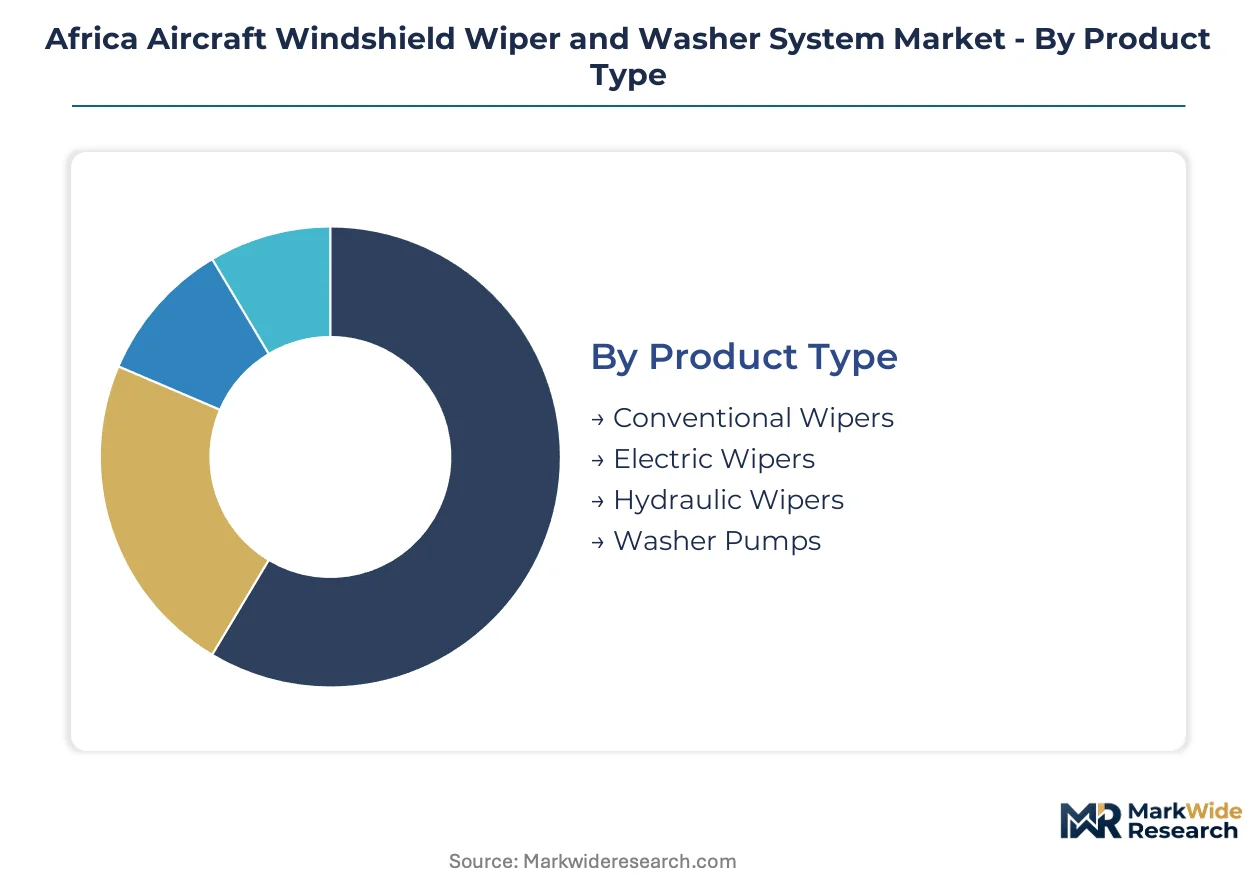
Segmentation in Africa's aircraft windshield wiper and washer system market reveals how procurement priorities diverge across fleet types, regulatory exposure, and technical upgrade cycles. Understanding these fault lines exposes where margin pools concentrate and which technology transitions reshape supplier relationships.
Product Type:
Buyer differentiation across product categories hinges on maintenance burden tolerance and fleet modernization timelines rather than upfront cost sensitivity alone.
- Conventional Wipers:Mechanical linkage systems with rubber blades remain specified for legacy turboprop fleets serving remote airstrips. Operators in Mali and Chad favor these units for field-repairability where MRO infrastructure is sparse.
- Electric Wipers:Brushless DC motor architectures eliminate brush wear failures and reduce weight versus hydraulic alternatives. Ethiopian Airlines and Kenya Airways are specifying these in narrow-body procurement, pulling aftermarket demand toward compatible spares.
- Hydraulic Wipers:Legacy Boeing 737 Classic fleets operated by Nigerian domestic carriers retain these systems, fragmenting spare parts demand across incompatible technical standards and extended lead times from European OEM facilities.
- Washer Pumps:Compact fluid delivery units with corrosion-resistant housings address dust-heavy Sahel operations; fluoropolymer-coated internals extend service intervals for Malian operators.
Volume sits with Conventional Wipers; growth tilts toward Electric Wipers.
End User:
End-use segmentation tracks directly to regulatory scrutiny intensity and fleet renewal capital availability.
- Commercial Aviation:National flag carriers and low-cost operators face ICAO Annex 8 alignment mandates from Kenya's KCAA and Nigeria's NCAA. Fleet expansion at RwandAir and Ethiopian Airlines generates factory-installed demand for integrated visibility systems.
- Military Aviation:Defense procurement channels emphasize supply security and domestic content requirements over unit economics. South African military specifications influence regional tender structures.
- General Aviation:Charter operators and flight schools prioritize total cost of ownership in high-cycle training environments. Nairobi and Lagos-based operators show strongest unbundling of visibility maintenance from airframe contracts.
- Private Jets:Executive aircraft based in Lagos and Nairobi drive premium retrofit demand for sensor-integrated automatic actuation systems.
Commercial Aviation commands current procurement volume; General Aviation climbs fastest as training fleet expansion accelerates.
Installation Type:
Installation channel selection reflects fleet age distribution and the maturity of local technical capabilities.
- OEM:Factory-installed systems on new Airbus and Boeing deliveries to Ethiopian Airlines and RwandAir establish baseline specifications that constrain aftermarket alternatives.
- Aftermarket:Independent MRO providers in Johannesburg and Nairobi capture disaggregated service relationships as East African carriers build internal technical capabilities.
- Retrofit:Electric architecture conversions for aging hydraulic-equipped fleets demand avionics-trained technicians, a capability gap acute in secondary African facilities.
- Remanufactured:Cost-sensitive domestic operators in Nigeria consolidate procurement through approved distributor networks to satisfy South Africa's tightened airworthiness directive enforcement on component traceability.
Aftermarket channels dominate transaction volume; Retrofit activity expands most quickly as electric conversion programs accelerate.
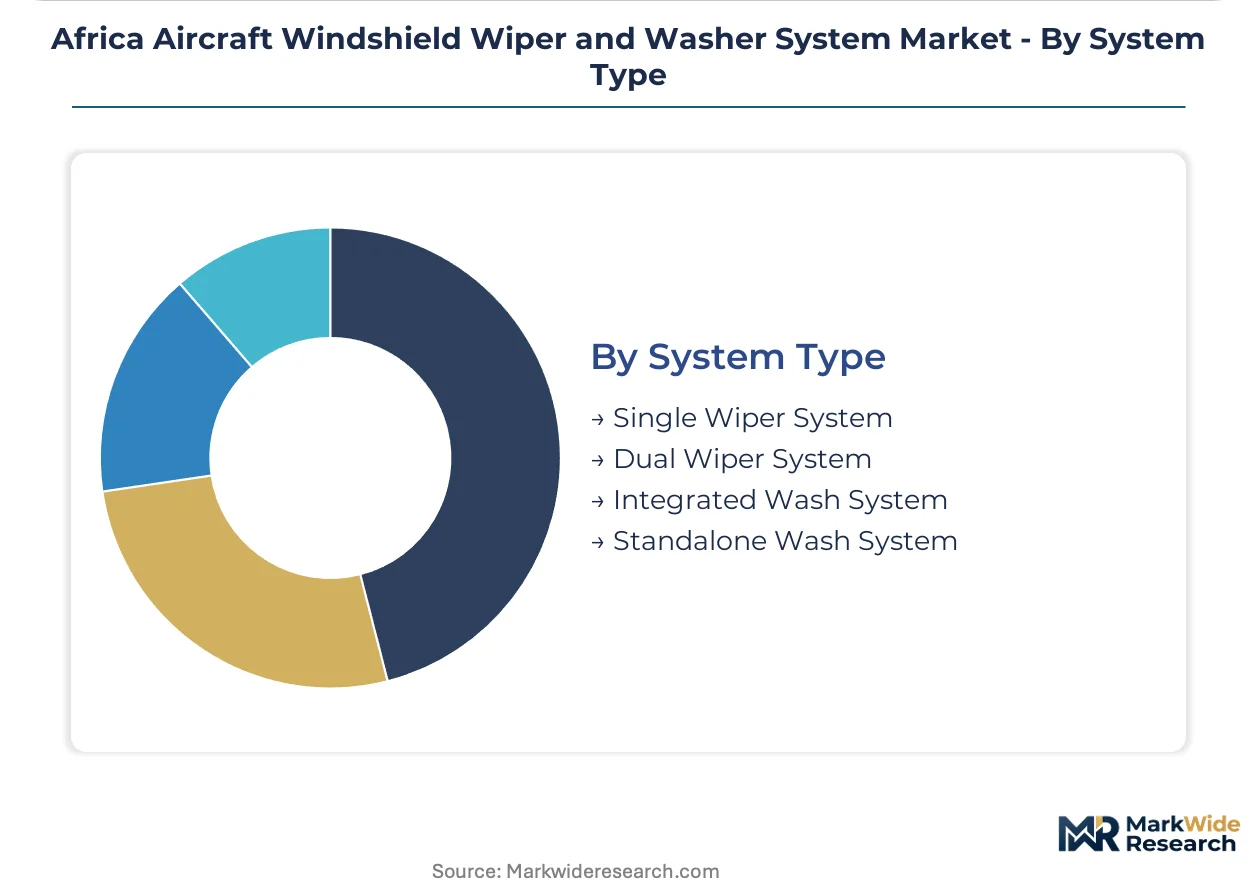
System Type:
System architecture preferences diverge by aircraft category and operational environment severity.
- Single Wiper System:Specified for regional turboprops and light jets where weight minimization outweighs redundancy requirements. Dust-heavy Sahel operations stress blade durability.
- Dual Wiper System:Redundant configurations on narrow-body commercial jets address continued airworthiness requirements under Kenya's KCAA and Nigeria's NCAA mandates.
- Integrated Wash System:Combined fluid delivery and wiper actuation reduces procurement complexity for airlines specifying Honeywell avionics-visibility bundles.
- Standalone Wash System:Modular architectures enable component-level replacement in Johannesburg MRO hubs serving sub-Saharan operators with mixed fleet types.
Dual Wiper Systems anchor installed base volume; Integrated Wash Systems gain share fastest as avionics bundling reshapes procurement patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aluminum alloy feedstock availability and aerospace-grade rubber compound processing anchor manufacturing economics across African aviation supply chains. Corrosion-resistant material specifications from South Africa's Civil Aviation Authority cascade through sub-Saharan procurement networks. Local MRO capability development in Johannesburg and Lagos reshapes distribution topology for visibility system components.
South Africa
Johannesburg anchors sub-Saharan aftermarket distribution with maturing MRO capabilities serving mixed fleet operators. The Civil Aviation Authority enforces stringent airworthiness directives on flight deck equipment traceability that filter non-certified suppliers from approved procurement channels. Cape Town-based technical training facilities address aerospace electrician skill scarcity for electric wiper system conversions.
Nigeria
Lagos concentrates domestic airline procurement as low-cost carriers expand narrow-body fleets requiring modern visibility systems. The NCAA mandates functional visibility system certification aligned with ICAO Annex 8 standards, forcing fleet upgrades among aging operators. Approved distributor networks in Lagos consolidate procurement to satisfy component traceability requirements.
Ethiopia
Addis Ababa drives factory-installed demand through Ethiopian Airlines' narrow-body expansion with electric wiper architectures. The country's national aviation regulator enforces continued airworthiness standards that shape aftermarket spare parts specifications. Bole International Airport's maintenance facilities pull compatible components through regional logistics partnerships.
Kenya
Nairobi hosts expanding general aviation training fleets that prioritize total cost of ownership in high-cycle environments. The KCAA mandates functional visibility system certification for operational approval, accelerating electric architecture retrofits. Jomo Kenyatta International Airport's technical capabilities capture disaggregated visibility maintenance contracts from East African carriers.
Rwanda
Kigali supports RwandAir's fleet modernization with factory-installed integrated visibility systems on new aircraft deliveries. National aviation authorities align with EASA-equivalent standards under African Union SAATM harmonization initiatives. Bugesera International Airport development creates infrastructure for regional MRO service expansion.
Africa Aircraft Windshield Wiper and Washer System Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue sensor-integration and predictive maintenance adjacencies. The supplier base concentrates around electromechanical system specialists and integrated avionics bundlers serving African flag carriers. Three archetypes dominate: legacy aerospace conglomerates with broad platform coverage, regional distribution specialists anchoring aftermarket logistics, and avionics-integrated solution providers reducing procurement complexity. Competitive positioning hardens through strategic partnerships with Johannesburg and Lagos MRO hubs, plus technology licensing arrangements that accelerate electric architecture penetration.
Among diversified aerospace conglomerates, Safran S.A. and Eaton Corporation exemplify established supply relationship archetypes with African operators. Honeywell International Inc. occupies the integrated systems tier, bundling visibility components with broader avionics portfolios. These three anchors represent distinct competitive vectors: platform-certified component supply, aftermarket distribution network control, and procurement complexity reduction through system integration.
| Leading Market Players |
|---|
| RTX Corp. |
| Moog Inc. |
| Safran S.A. |
| PPG Industries |
| Liebherr Aerospace |
| Eaton Corporation |
| Raytheon Technologies |
| Aerosystems S.r.l. |
| Honeywell International Inc. |
| Others |
Value Network & Pricing Analysis
East African flag carriers and Nigerian low-cost operators concentrate procurement volumes, anchoring contract-based long-term offtake pricing with tiered structures tied to certification grade and volume scale. This buyer consolidation enables OEMs to enforce premium pricing on ICAO Annex 8-compliant traceable components while squeezing margin on standard-tier parts through approved distributor networks.
Pricing Analysis
Factory-installed systems on new Airbus and Boeing deliveries to Ethiopian Airlines and RwandAir command premium margins, while aftermarket channels compete on total cost of ownership for aging hydraulic-equipped fleets. Three-tier pricing structure across premium, standard, and economy levels separates OEM-traceable certified components from approved distributor parts and gray-market alternatives. Cost compression in the standard tier intensifies as Nigerian domestic operators consolidate procurement through Lagos networks to satisfy South Africa's tightened airworthiness directive enforcement. General aviation training fleets in Nairobi show highest price sensitivity due to high-cycle operating economics, whereas executive aircraft operators in Lagos prioritize performance over unit cost.
Supply Chain Analysis
Aerospace electrician scarcity in Johannesburg and Nairobi constrains regional MRO capacity expansion for electric wiper system conversions. Certified manufacturing concentrates in Germany, France, and the United States, drawing from aerospace-grade aluminum alloy feedstocks and fluoropolymer-coated rubber compounds. Single-source vulnerability persists for brushless DC motor controllers sourced from European electronics specialists. Distribution runs through Johannesburg and Lagos logistics partnerships serving sub-Saharan operators with mixed fleet types.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
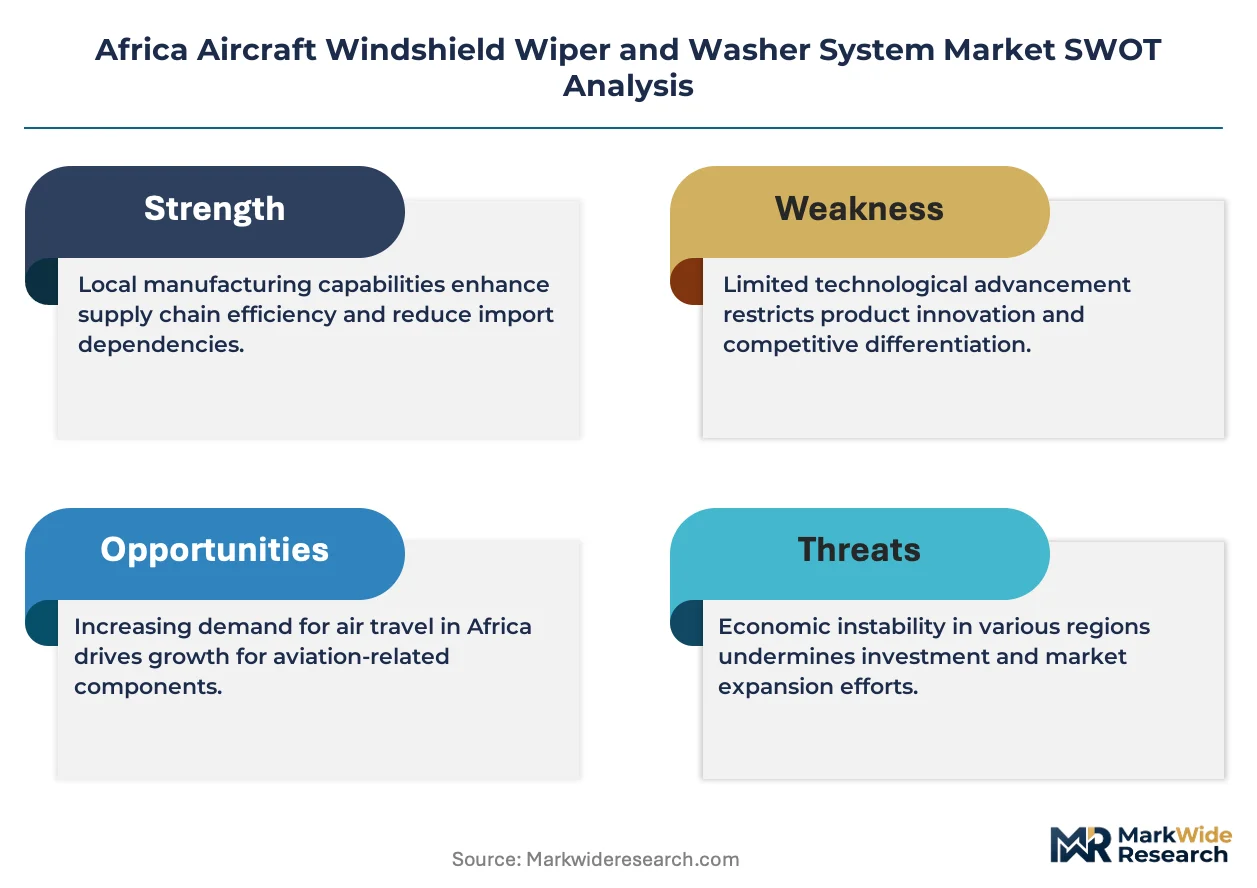
This market is becoming a vertical-integration race as suppliers pursue backward integration into corrosion-resistant material processing to secure fluoropolymer-coated rubber supply against African import tariff volatility.
For Market Incumbents: Hedge against electric architecture commoditization by locking exclusive supply relationships with Ethiopian Airlines and Kenya Airways for brushless DC motor platforms. Secure Johannesburg MRO hub partnerships to anchor aftermarket distribution control before independent providers capture disaggregated service relationships from East African carriers building internal technical capabilities. For New Entrants and Emerging Players: Secondary African MRO facilities in Ghana and Tanzania present the most penetrable white-space target, where EASA-equivalent certification timeline delays create 12-18 month supply gaps for aftermarket components. Enter through technology licensing arrangements with established European OEMs that accelerate electric architecture penetration without requiring full certification investment. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap electromechanical specialists with existing ICAO Annex 8 certification in South Africa, where Johannesburg's maturing MRO capabilities create regional distribution leverage. Long-term viability hinges on sensor-wiper convergence and predictive maintenance integration capabilities. Watch for African Union SAATM harmonization implementation as the inflection signal that streamlines certification pathways across 35 signatory states.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluoropolymer Processing | Captive supply of corrosion-resistant rubber compounds insulates against African import tariff regimes. |
| Johannesburg MRO Hub Partnership | Regional distribution node captures aftermarket margin pools from aging sub-Saharan fleets. |
| Sensor-Wiper Convergence Development | Premium retrofit packages for Lagos and Nairobi executive aircraft command pricing power. |
| ICAO Annex 8 Certification Investment | Traceability compliance unlocks approved procurement channels with Nigerian and Kenyan flag carriers. |
| Technology Licensing Arrangement | Accelerated electric architecture penetration without full EASA-equivalent certification burden. |
Research Methodology
Multi-period observation of fleet renewal timelines and regulatory harmonization progress anchored the trend analysis, supplemented by interviews with MRO operations directors, airline procurement managers, aviation authority certification leads, and aftermarket distributor principals. Secondary validation drew from ICAO safety management documentation, EASA airworthiness directive databases, African Union SAATM implementation reports, and national civil aviation authority regulatory filings. Bottom-up triangulation across installation channel volumes and top-down reconciliation against fleet size projections established market sizing boundaries.
Segment-weighting across product type, end user, installation channel, and system architecture dimensions shaped the analytical framework across the projection horizon. CAGRs were derived from elasticity modeling against fleet expansion schedules and replacement cycle assumptions. Industry-specific forecast inputs included Ethiopian Airlines and RwandAir narrow-body delivery schedules, plus South African Civil Aviation Authority enforcement intensity indices.
Revisions become necessary when African Union SAATM harmonization stalls, aluminum alloy LME spot volatility exceeds historical bands, or brushless DC motor supply concentration triggers extended lead times. Forecasts reflect documented assumptions on regulatory alignment and input cost trajectories. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Maintenance and MRO Solutions
Nigeria Aircraft Maintenance Repair and Overhaul Market
Aircraft Maintenance and MRO Solutions
Aircraft Tire Balancer Market
Aircraft Maintenance and MRO Solutions
Aircraft Maintenance Market
Aircraft Maintenance and MRO Solutions
Aircraft Recycling Market
Aircraft Maintenance and MRO Solutions
Aircraft Towing Equipment Market
Aircraft Maintenance and MRO Solutions
Europe Aircraft Engine MRO Market
Aircraft Maintenance and MRO Solutions
Latin America Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Global Aircraft Heavy Maintenance Visits Market
Aircraft Maintenance and MRO Solutions
Aircraft Exterior Strip and Repaint Services Market
Aircraft Maintenance and MRO Solutions
Airplane Pushback Tug Market
Aircraft Maintenance and MRO Solutions
North America Aerospace Maintenance Chemical Market
Aircraft Maintenance and MRO Solutions
Aircraft Landing Gear Repair and Overhaul Market
Aircraft Maintenance and MRO Solutions
MRO Software Market
Aircraft Maintenance and MRO Solutions
Africa Aviation MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Line Maintenance Market
Aircraft Maintenance and MRO Solutions
North America Aircraft Engine MRO Market