
 Aviation Maintenance Software Market | 2026-2036
Aviation Maintenance Software Market Size, Share, and Industry Trends Forecast 2026-2036
Aviation Maintenance Software Market Insights
EASA Part 145 and FAA Part 145 certification cycles for maintenance software vendors is collapsing from a multi-year barrier to a baseline qualifier. Veryon leverages its cloud-native architecture to compete for mid-size airline contracts across North America. Lufthansa Technik anchors the European MRO segment through captive software development tied to its Hamburg and Munich facilities. Ramco Systems extends its presence in Asia-Pacific through mobile-first maintenance platforms designed for line maintenance crews.
Aviation maintenance software comprises integrated digital systems that manage aircraft airworthiness records, track component life limits, schedule preventive maintenance intervals, and generate regulatory compliance documentation for civil aviation authorities. These platforms serve the primary commercial purpose of eliminating paper-based logbooks while ensuring traceability across tens of thousands of serialized aircraft parts per fleet. Cloud-based deployment now leads solution type adoption as carriers abandon capital-intensive on-premise infrastructure, while predictive maintenance modules represent the fastest-expanding solution category as operators integrate sensor data from connected aircraft. Compliance tracking functions command premium pricing due to the liability exposure associated with audit failures.
FAA Part 43 repair station rules, EASA Part 145 maintenance organization approvals, and ICAO Annex 6 standards collectively mandate digital record retention periods exceeding the operational life of airframes, which forces software procurement regardless of airline profitability cycles. The EU AI Act introduces emerging compliance obligations for predictive maintenance algorithms that automate go/no-go dispatch decisions. Stakeholders must monitor whether regulators will require algorithmic transparency in defect prediction models as machine learning displaces rule-based threshold monitoring.
Market Dynamics
Cloud-native architecture is decomposing the legacy on-premise software stack that dominated aviation maintenance for three decades, forcing vendors to rebuild certification-compliant platforms for distributed deployment while carriers abandon capital-intensive infrastructure commitments.
Growth Catalysts
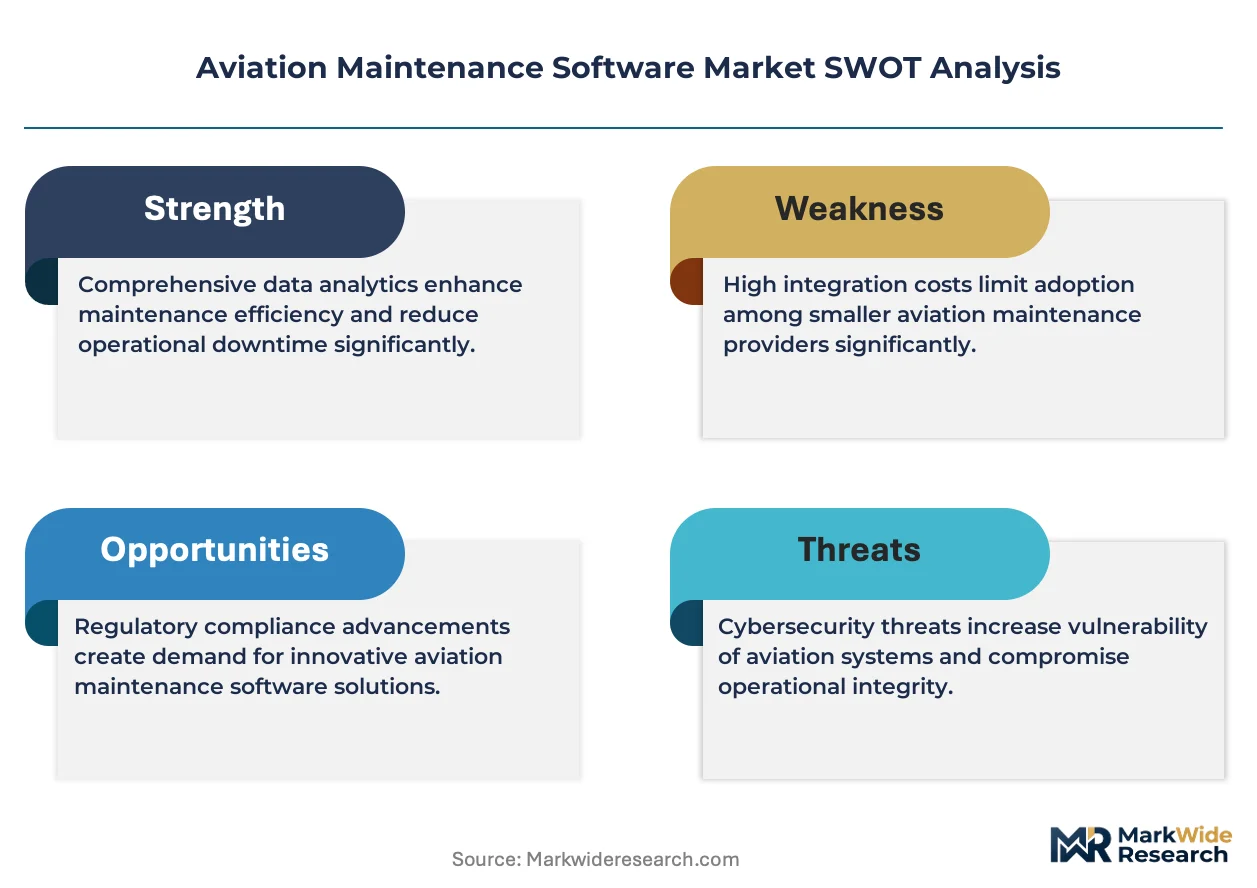
- FAA Part 145 and EASA Part 145 tightening:Certification cycles now demand digital audit trails for every maintenance action, compelling repair stations to replace paper-based systems regardless of fleet age or profitability.
- Predictive maintenance modules:Connected aircraft sensor streams enable algorithmic defect prediction, compressing unscheduled downtime intervals and justifying software procurement through operational cost avoidance.
- Legacy carrier fleet modernization:United States-based airlines with aging Boeing and Airbus fleets require extensive MRO software upgrades to manage component life limits across tens of thousands of serialized parts.
Market Restraints
- Certification timeline friction:FAA and EASA software validation cycles extend 18-24 months, freezing vendor R&D roadmaps and delaying revenue recognition for new platform releases.
- Data sovereignty requirements:China's GB standards and Russia's localization mandates fragment cloud deployment architectures, forcing redundant infrastructure investments for multi-national carriers.
- Rule-based threshold monitoring:Established maintenance protocols resist machine learning displacement, creating adoption drag among risk-averse MRO operations.
Strategic Opportunities
- EU AI Act algorithmic transparency mandates:Predictive maintenance vendors who pre-build explainable defect models gain first-mover advantage as regulators scrutinize automated go/no-go dispatch decisions.
- Line maintenance mobility gaps:Mobile-first platforms for tarmac crews remain underdeveloped relative to hangar-based systems, opening white space for purpose-built crew applications.
- India DGCA compliance digitization:Rapid fleet expansion among low-cost carriers creates demand for cost-effective, cloud-deployed maintenance record systems aligned with Indian regulatory frameworks.
Industry Challenges
- Aviation software engineering talent scarcity:Dual expertise in airworthiness regulations and modern cloud architecture commands premium compensation, constraining vendor scaling velocity.
- Legacy system integration complexity:Decades of accumulated proprietary data formats in incumbent platforms resist standardized API migration, extending implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aviation Maintenance Software Market |
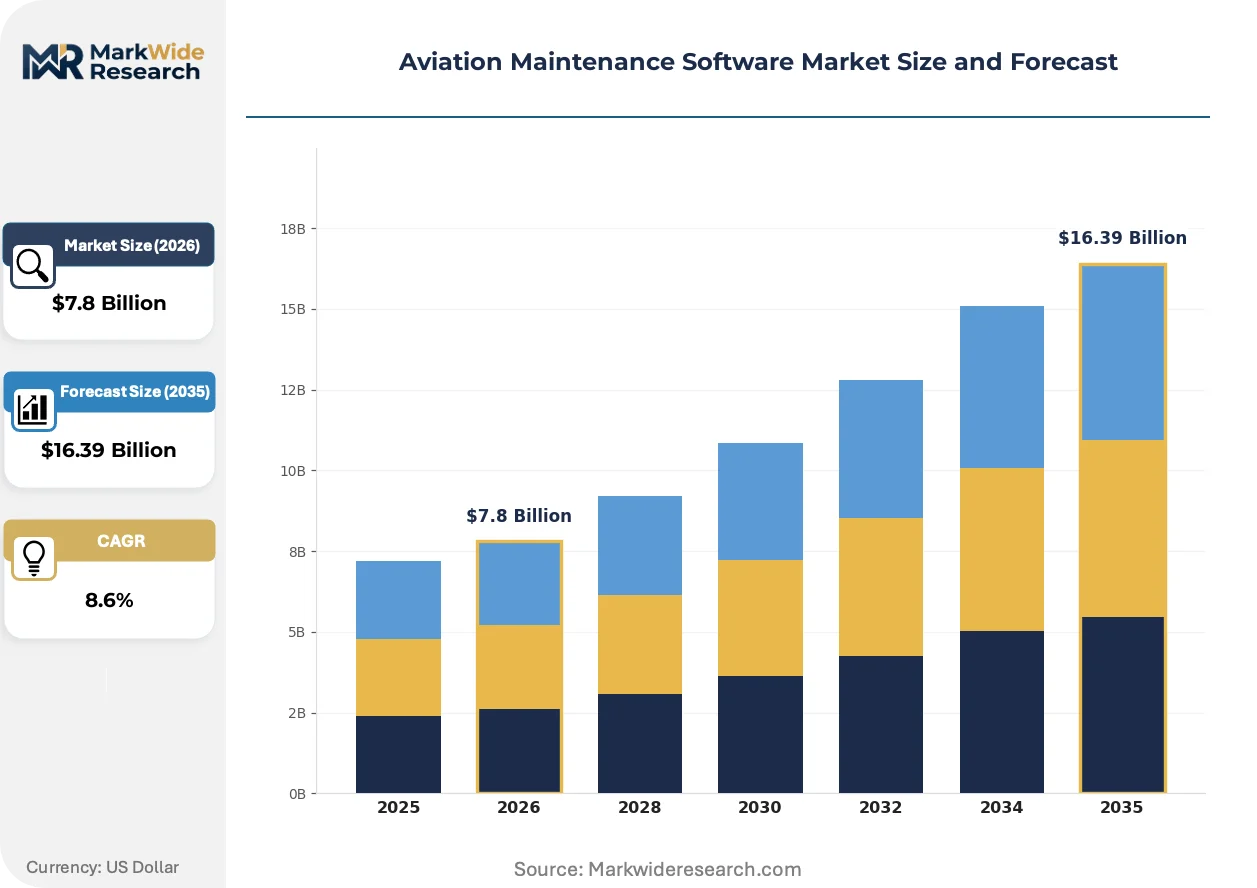
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $16.39 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Private Cloud Solution Type: Predictive Maintenance, Fleet Management, Inventory Management, Compliance Tracking, Workflow Automation Application: Aircraft Maintenance Tracking, Parts Management, Service Scheduling, Defect Reporting, Maintenance Analytics End User: Airlines, MRO Providers, Aircraft Manufacturers, Aviation Regulators, Airport Operators |
| Companies Covered | Veryon, Lufthansa Technik, CAMP Systems International, Ramco Systems, IFS AB, AeroSoft Systems, ATP Inc., Rusada, Jet Support Services, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aviation Maintenance Software Market Trends and Innovations
Sensor fusion and edge computing architectures are actively restructuring how maintenance data flows from aircraft to decision systems, compressing the latency between defect detection and dispatch authorization.
Digital twin technology is decomposing traditional scheduled maintenance intervals into condition-based interventions. Full-fleet operators at Delta and American Airlines deploy physics-based component models that simulate degradation trajectories in real time. This capability collapses the economic justification for calendar-driven overhaul contracts.
The EU AI Act introduces mandatory documentation standards for machine learning systems that automate safety-critical maintenance decisions. European MRO providers must now maintain algorithmic version histories and training data provenance equivalent to physical part traceability. German and French repair stations are investing in MLOps infrastructure to satisfy audit requirements before enforcement deadlines.
Airline procurement teams now unbundle software licensing from implementation services, treating maintenance platforms as composable API layers rather than monolithic enterprise contracts. Low-cost carriers in Southeast Asia lead this shift, selecting best-of-breed modules for inventory, scheduling, and compliance rather than integrated suites. This pattern fragments vendor account control and accelerates switching cycles.
Aviation Maintenance Software Market Segmentation
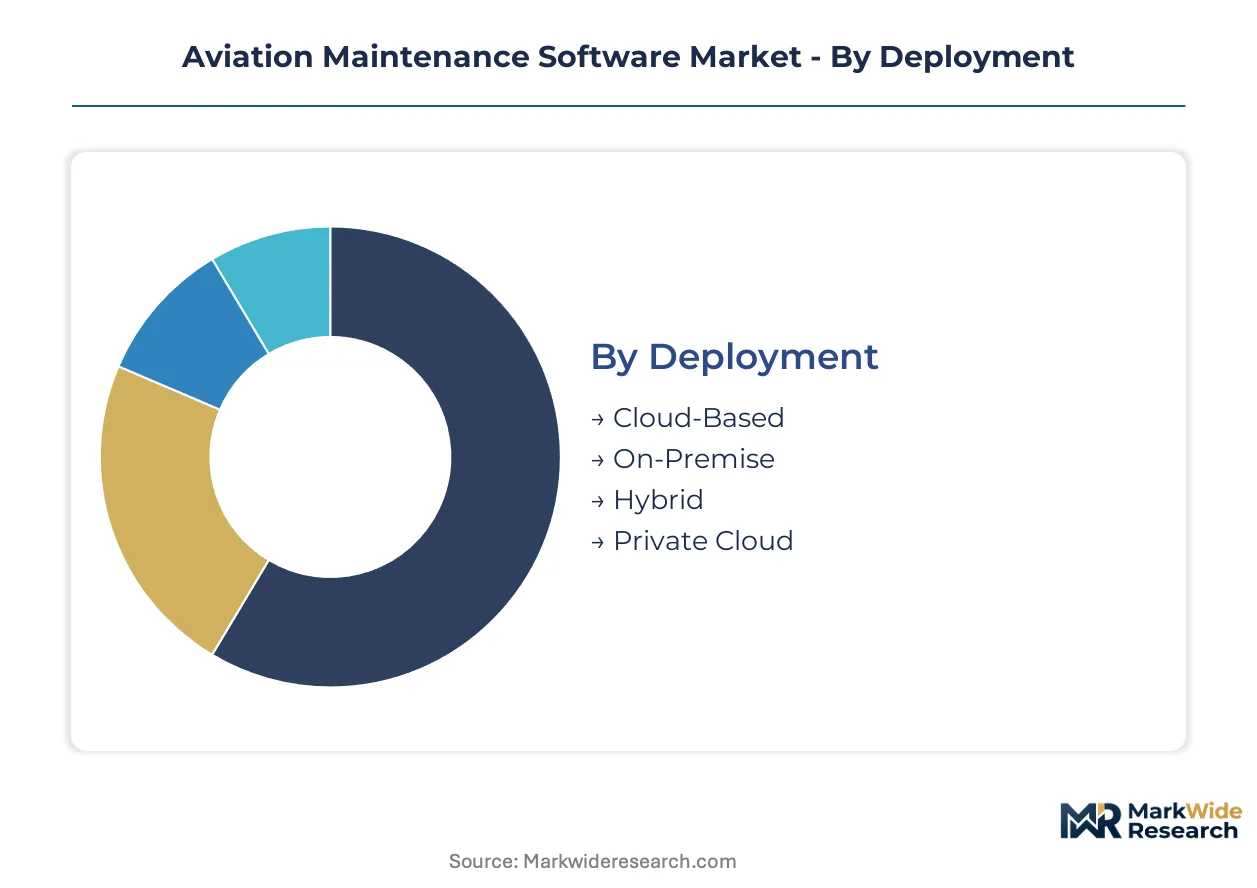
Segmentation in aviation maintenance software reveals how procurement priorities diverge between capital-constrained low-cost carriers and legacy network operators with decades of technical debt. Deployment architecture and solution type choices directly determine compliance audit readiness and integration complexity with existing fleet management systems.
Deployment:
Substitution pressure from cloud-native platforms is collapsing the economic case for on-premise infrastructure among mid-size carriers seeking to eliminate data center capital commitments.
- Cloud-Based:Multi-tenant SaaS architectures enable rapid FAA Part 145 certification updates without carrier IT intervention. United States-based regional airlines prioritize this model to avoid technical staffing overhead in secondary hubs.
- On-Premise:Legacy installations persist where air-gapped security protocols or classified military contracts mandate physical infrastructure control. Defense contractors and certain national flag carriers maintain these deployments despite higher total cost of ownership.
- Hybrid:Split architectures isolate sensitive airworthiness data on-premise while pushing analytics workloads to public cloud. European MRO providers favor this approach to satisfy EASA data residency requirements without sacrificing computational scale.
- Private Cloud:Single-tenant dedicated environments serve carriers with stringent latency requirements for real-time predictive maintenance. Major network airlines in Germany and France deploy these for connected aircraft sensor ingestion.
Cloud-Based deployments anchor the volume base while Hybrid configurations gain share at the steepest rate as regulators clarify cross-border data flow permissions.
Solution Type:
Cost tier stratification separates premium-priced compliance modules from commoditized workflow tools where vendor differentiation erodes fastest.
- Predictive Maintenance:Machine learning models process engine vibration, oil debris, and thermal sensor streams to forecast component failures before threshold breaches. Airlines with connected Boeing 787 and Airbus A350 fleets drive concentrated demand for these algorithmic dispatch tools.
- Fleet Management:Integrated platforms consolidate aircraft status, maintenance history, and regulatory documentation across mixed-type fleets. Large network carriers in the United States require these systems to manage thousands of airframes through centralized operations centers.
- Inventory Management:Serialized part tracking with automated life limit calculations reduces AOG (aircraft on ground) events from missing components. MRO providers in Singapore and Dubai leverage these tools for high-velocity rotable part pools.
- Compliance Tracking:Audit trail generation for FAA, EASA, and ICAO mandates commands sustained premium pricing due to liability exposure. Repair stations treat this as non-discretionary procurement regardless of fleet profitability cycles.
- Workflow Automation:Digital task card routing and electronic sign-off accelerate line maintenance turnaround times. Low-cost carriers in Southeast Asia adopt these modules to maximize aircraft utilization rates.
Compliance Tracking generates the highest margin pool while Predictive Maintenance expands most quickly as sensor-equipped fleets proliferate.
Application:
Customer type divergence separates hangar-based heavy maintenance from tarmac line operations with radically different mobility and latency requirements.
- Aircraft Maintenance Tracking:Centralized airworthiness record systems manage component installation history across multiple owners and lease transitions. Lessors and asset managers in Ireland and the Cayman Islands require these capabilities for portfolio-wide visibility.
- Parts Management:Procurement and logistics modules optimize spare part positioning across distributed warehouse networks. MRO providers with regional hub strategies in Texas and Ohio concentrate demand for inventory optimization algorithms.
- Service Scheduling:Hangar slot allocation and manpower planning tools coordinate complex C-check and D-check interventions. Major maintenance facilities in Hamburg and Singapore depend on these systems for throughput maximization.
- Defect Reporting:Mobile-enabled discrepancy capture accelerates pilot and mechanic communication for airworthiness decisions. Line maintenance crews at hub airports in Atlanta and Dallas-Fort Worth drive adoption of tablet-optimized interfaces.
- Maintenance Analytics:Fleet-wide reliability trending and cost-per-flight-hour analysis inform long-term fleet planning. Network airline engineering departments in Chicago and London use these tools for retirement and acquisition timing.
Aircraft Maintenance Tracking provides the foundational data layer while Defect Reporting climbs fastest as mobile-first design priorities reshape crew application procurement.
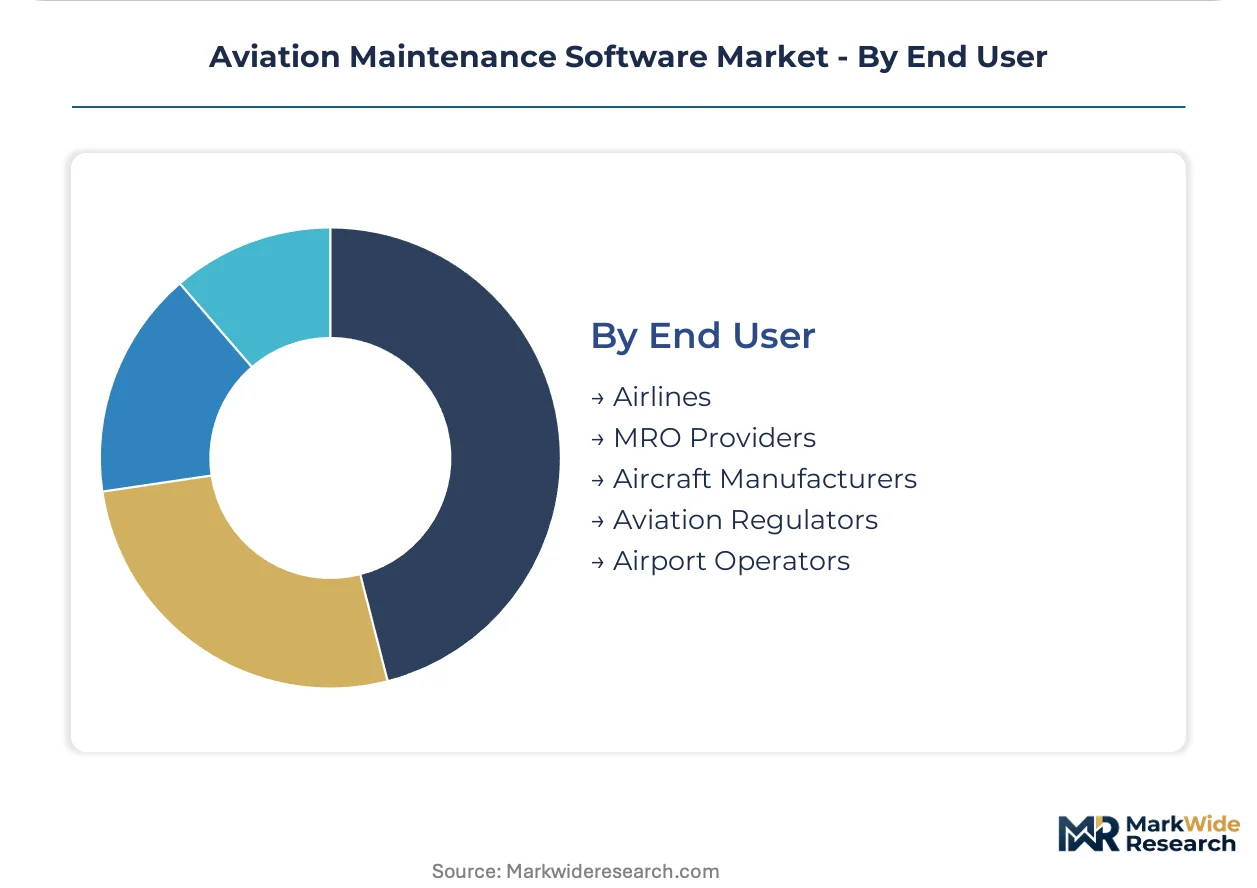
End User:
Supply concentration among MRO providers creates pricing leverage distinct from fragmented airline procurement patterns.
- Airlines:In-house engineering organizations select platforms balancing direct operating cost visibility with regulatory audit support. United States legacy carriers and European network airlines represent the largest procurement volume.
- MRO Providers:Independent repair stations and OEM-affiliated service operations require multi-tenant architectures serving diverse airline customers. Lufthansa Technik, ST Engineering, and AAR Corp anchor demand in this segment.
- Aircraft Manufacturers:OEMs deploy maintenance software for in-service support and aftermarket service contract fulfillment. Boeing and Airbus integrate these capabilities with their digital services portfolios.
- Aviation Regulators:Civil aviation authorities utilize audit and oversight modules for surveillance of certificated repair stations. The FAA and EASA maintain specialized inspection tracking systems.
- Airport Operators:Ground handling and line maintenance coordination tools manage third-party service provider relationships. Hub airports in Denver and Munich procure these for common-use facility management.
MRO Providers command the deepest platform customization requirements while Airlines drive standardization push for API interoperability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FAA Part 145 and EASA Part 145 certification tightening is reshaping procurement patterns across major aviation hubs, with carriers prioritizing cloud-native platforms that accelerate regulatory audit readiness.
United States
Legacy carriers with aging Boeing and Airbus fleets drive concentrated demand for component life limit tracking across tens of thousands of serialized parts. FAA Part 43 and Part 145 rules mandate digital audit trails for every maintenance action, compelling repair station software upgrades. Dallas-Fort Worth and Atlanta anchor the largest line maintenance crew deployments, with mobile-first defect reporting tools seeing rapid adoption at hub airports.
Germany
Lufthansa Technik's captive software development at Hamburg and Munich facilities anchors European MRO platform supply. The EU AI Act introduces algorithmic transparency mandates for predictive maintenance systems, forcing German repair stations to invest in MLOps infrastructure before enforcement deadlines. Bavaria and North Rhine-Westphalia concentrate the deepest platform customization requirements for multi-tenant architectures.
Singapore
High-velocity rotable part pools at Changi-based MRO providers generate concentrated demand for inventory management modules with automated life limit calculations. The Civil Aviation Authority of Singapore aligns with ICAO Annex 6 standards for digital record retention exceeding airframe operational life. Seletar Aerospace Park hosts the densest cluster of third-party maintenance facilities adopting cloud-deployed compliance tracking systems.
India
Rapid fleet expansion among low-cost carriers creates demand for cost-effective, cloud-deployed maintenance record systems aligned with DGCA digitization initiatives. Ramco Systems extends its Asia-Pacific presence through mobile-first platforms designed specifically for line maintenance crews. Bangalore and Hyderabad anchor the fastest-growing engineering centers where aviation software talent scarcity commands premium compensation.
United Arab Emirates
Dubai-based MRO providers leverage strategic geographic positioning between European and Asian traffic flows to justify predictive maintenance module investments for connected aircraft fleets. The General Civil Aviation Authority mandates digital documentation standards equivalent to EASA Part 145 requirements. Dubai South and Al Maktoum International Airport concentrate the region's deepest hangar slot allocation and manpower planning tool deployments.
Aviation Maintenance Software Market Competitive Landscape
Player mix skews toward specialized aviation software vendors and airline-affiliated technology units rather than horizontal enterprise platforms. Market structure exhibits moderate consolidation around vendors with dual expertise in airworthiness regulations and cloud architecture. Two strategic archetypes dominate: legacy platform vendors managing decades of proprietary data formats, and cloud-native entrants exploiting distributed deployment advantages. Competitive moves center on certification acceleration partnerships and API interoperability investments that reduce carrier switching costs.
Among North American and European specialists, Veryon, Lufthansa Technik, and Ramco Systems occupy distinct positioning vectors. Veryon exemplifies the cloud-native archetype competing for mid-size airline contracts through rapid FAA Part 145 certification update cycles. Lufthansa Technik represents the captive airline-affiliated model, with Hamburg-based development tied directly to heavy maintenance facility operations. Ramco Systems anchors the Asia-Pacific expansion pattern, with India-originated mobile-first platforms designed for tarmac crew workflows. These three illustrate how geographic origin and organizational structure shape competitive differentiation in a market where regulatory compliance serves as the primary barrier to entry.
| Leading Market Players |
|---|
| Veryon |
| Lufthansa Technik |
| CAMP Systems International |
| Ramco Systems |
| IFS AB |
| AeroSoft Systems |
| ATP Inc. |
| Rusada |
| Jet Support Services |
| Others |
Pricing and Supply Chain Analysis
Eighteen-to-twenty-four-month FAA and EASA software validation cycles concentrate pricing power among incumbent vendors with existing certification pipelines, while carriers absorbing extended implementation timelines face compressed negotiation leverage against cloud-native entrants offering faster deployment paths.
Pricing Analysis
Certification level creates the primary spread between premium compliance-tracking modules and commoditized workflow tools. SaaS-tiered subscription models dominate, with FAA Part 145 and EASA Part 145 audit-grade functionality commanding sustained premiums due to liability exposure from audit failures. Price differentiation rests on regulatory-grade documentation capabilities versus basic task routing. Cost compression in workflow automation is intensifying because low-cost carriers unbundle integrated suites into best-of-breed API layers. Regional airlines in the United States exhibit highest price sensitivity, while MRO providers treat compliance modules as non-discretionary procurement.
Supply Chain Analysis
Just-in-time certification update delivery through multi-tenant SaaS architectures is displacing strategic stockpiling of on-premise infrastructure among mid-size carriers. Software engineering talent concentrates in the United States, Germany, and India, with Bangalore and Hyderabad anchoring the fastest-growing engineering centers. Platform development draws from specialized aviation regulatory expertise, cloud architecture competency, and connected aircraft sensor integration capabilities. Single-source vulnerability in FAA-validated code bases creates concentration risk for carriers dependent on incumbent vendors. Distribution runs through direct enterprise sales to airline engineering departments and MRO procurement teams, supplemented by OEM aftermarket service channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aviation maintenance software functions as a service-attach opportunity where predictive maintenance algorithm subscriptions and compliance audit support contracts expand faster than core platform licensing, embedding vendors deeper into carrier operational workflows.
For Market Incumbents: Fortify certification pipeline advantages by accelerating FAA Part 145 update cycles through pre-validated cloud-native architectures, countering cloud-native entrants exploiting distributed deployment speed. Deepen upstream control over aviation software engineering talent pools through captive development centers in India and Germany, constraining competitor scaling velocity.
For New Entrants and Emerging Players: Anchor in line maintenance mobility gaps where tablet-optimized defect reporting tools remain underdeveloped relative to hangar-based systems. Target India's DGCA digitization initiatives as the most penetrable regulatory environment, deploying cost-effective cloud-deployed maintenance record systems for rapid fleet expansion among low-cost carriers. Pursue API-first go-to-market positioning that enables carrier unbundling of integrated suites.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because FAA and EASA certification timelines create durable moats around validated platforms regardless of technological disruption. Acquisition candidates with dual expertise in airworthiness regulations and modern cloud architecture command scarcity premiums. Watch EU AI Act algorithmic transparency enforcement deadlines as inflection indicators for predictive maintenance vendor consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API interoperability investments reduce carrier switching costs and accelerate SaaS-tiered subscription adoption among unbundling low-cost carriers. |
| Strategic Partnership | Certification acceleration partnerships with FAA and EASA validation authorities compress 18-24 month software approval timelines. |
| Acquisition of Specialist Firm | Aviation software engineering talent scarcity makes MLOps infrastructure specialists targets for predictive maintenance capability expansion. |
| Geographic Expansion | India DGCA alignment and Southeast Asia mobile-first crew workflows open white space beyond saturated North American and European markets. |
| Product Launch | Explainable defect prediction models gain first-mover advantage as EU AI Act mandates algorithmic transparency for automated dispatch decisions. |
Research Methodology
The analysis maps cloud-native deployment architectures, predictive maintenance modules, compliance tracking functions, and mobile-first crew applications, each validated through airline engineering directors, MRO procurement leads, regulatory affairs specialists at FAA and EASA, and aviation software platform engineers. Primary interview insights triangulate against FAA Part 145 certification databases, EASA maintenance organization approval records, SEC filings from publicly traded MRO providers, and customs data on aviation software imports. Bottom-up carrier procurement pattern analysis reconciles with top-down market sizing across deployment models and solution types.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. Segmentation dimensions modeled include deployment architecture, solution type, application workflow, and end-user procurement pattern. CAGRs derive from carrier fleet expansion trajectories, connected aircraft sensor penetration curves, and regulatory digitization mandates. Forecast inputs incorporate MRO provider capacity buildouts at Hamburg, Singapore, and Dubai facilities, plus low-cost carrier fleet growth in India and Southeast Asia.
Material uncertainties — FAA and EASA certification timeline extensions, EU AI Act enforcement severity, aviation software engineering wage inflation, and data sovereignty fragmentation — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory digitization continuity and cloud migration velocity among legacy carriers. Revision becomes warranted when connected aircraft sensor deployment thresholds cross predictive maintenance algorithmic dispatch adoption inflection points.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Maintenance and MRO Solutions
On-Premises MRO Software Market
Aircraft Maintenance and MRO Solutions
GCC Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Cabin Reconfiguration and Retrofit MRO Services Market
Aircraft Maintenance and MRO Solutions
Military Aircraft Maintenance, Repair and Overhaul Market
Aircraft Maintenance and MRO Solutions
Africa Aircraft Windshield Wiper and Washer System Market
Aircraft Maintenance and MRO Solutions
Global Aircraft Heavy Maintenance Visits Market
Aircraft Maintenance and MRO Solutions
Aviation Asset Management Market
Aircraft Maintenance and MRO Solutions
Distributed Electric Propulsion System MRO Services Market
Aircraft Maintenance and MRO Solutions
Aircraft Vacuum Cleaners Market
Aircraft Maintenance and MRO Solutions
Aviation Test Equipment Market
Aircraft Maintenance and MRO Solutions
Aircraft Weighing Scales Market
Aircraft Maintenance and MRO Solutions
Airline Maintenance Software Market
Aircraft Maintenance and MRO Solutions
Commercial Aircraft Landing Gear MRO Market
Aircraft Maintenance and MRO Solutions
Military Aviation Maintenance, Repair, and Overhaul Market
Aircraft Maintenance and MRO Solutions
Latin America Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
MRO Software Market