
 Gas Turbine MRO Market | 2026-2036
Gas Turbine MRO Market Size, Share, and Industry Trends Forecast 2026-2036
Gas Turbine MRO Market Analysis
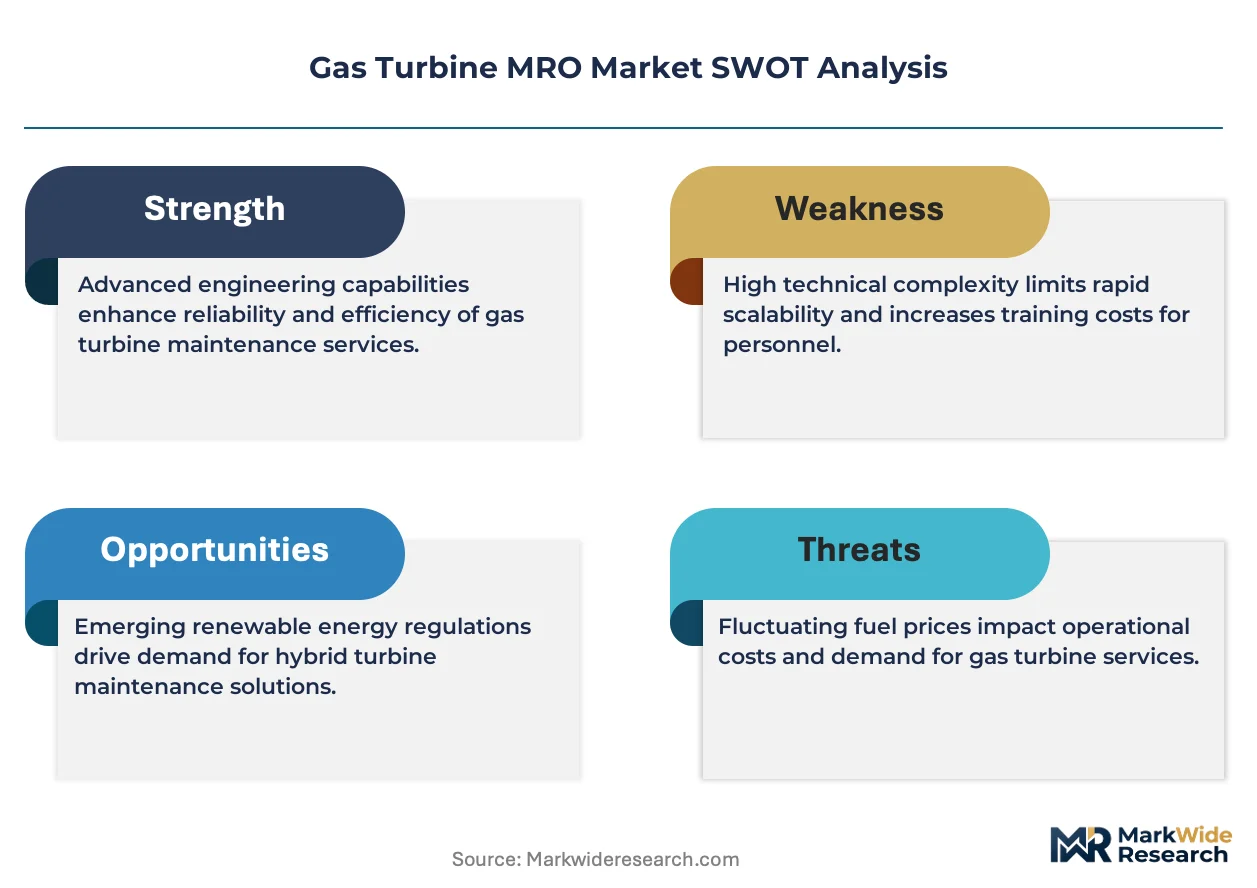
The EU F-Gas Regulation is decoupling overhaul demand from simple replacement cycles by mandating lower-emission combustion hardware retrofits. GE Vernova leverages its OEM-installed base across North American combined-cycle plants to secure long-term service agreements. Siemens Energy anchors European demand through regional service hubs that specialize in hydrogen-ready turbine conversions. Mitsubishi Power competes in Asia-Pacific markets with advanced coating technologies that extend hot-gas-path component life.
Gas turbine MRO encompasses inspection, refurbishment, and replacement of rotating and stationary components in axial-flow turbines operating at inlet temperatures exceeding 1,200°C and rotational speeds above 3,000 RPM. The activity restores thermal efficiency, emissions compliance, and mechanical reliability in power generation and industrial drive applications. Engine services commands the largest value pool due to the capital intensity of rotor and combustor overhauls, while predictive maintenance represents the fastest-expanding technology segment as operators deploy sensor networks to reduce unplanned outages. Component repair retains margin concentration in specialized coating and welding shops that hold proprietary metallurgical processes.
EPA enforces emissions standards that compel utilities to adopt dry low-NOx combustors during major overhauls, while the EU F-Gas Regulation restricts fluorinated greenhouse gas use in turbine cooling systems. ISO 3977 provides performance testing protocols that MRO providers must satisfy for warranty retention. Stakeholders should monitor hydrogen blending mandates and their implications for combustion system redesign requirements.
Market Dynamics
Life-extension economics for aging combined-cycle fleets are overriding traditional replacement cycles, as EPA emissions compliance costs and hydrogen-readiness retrofits compress payback thresholds for new-unit procurement.
Growth Catalysts
- EPA dry low-NOx mandates:Major overhaul windows now require combustion hardware replacement, expanding the addressable serviceable market for hot-gas-path component providers.
- Hydrogen blending pilots:European utilities under EU Green Deal timelines are commissioning turbine conversions ahead of 2030 infrastructure targets, creating forward-loaded MRO demand.
- Predictive maintenance sensor deployment:Power generators are retrofitting axial-flow units with real-time vibration monitoring, compressing inspection intervals and increasing shop-visit frequency.
Market Restraints
- Superalloy supply concentration:Vacuum-melted nickel-based casting feedstock remains captive to a narrow supplier base in the United States and Germany, exposing overhaul schedules to raw-material volatility.
- Specialized welding labor scarcity:TIG and plasma-transferred-arc repair technicians require ASME Section IX certification that takes 18-24 months to credential, constraining shop throughput expansion.
- EU F-Gas refrigerant phase-down:Cooling system overhauls face extended parts-lead times as turbine OEMs redesign heat exchangers for lower-global-warming-potential working fluids.
Strategic Opportunities
- India CEA grid modernization:National thermal fleet efficiency mandates are opening first-mover positions for hot-section refurbishment specialists in Gujarat and Maharashtra utility corridors.
- Digital twin integration:Convergence of finite-element thermal modeling with operational sensor streams enables remote remaining-life assessment, unbundling predictive services from OEM captive agreements.
- Industrial cogeneration revival:Refinery and petrochemical operators in Texas and Louisiana are repowering with aeroderivative units, creating non-utility demand for modular fast-track overhaul programs.
Industry Challenges
- ASME PTC-22 test-cell certification delays:Third-party MRO providers face 6-9 month queue times for witnessed performance testing, compressing warranty-validated turnaround commitments.
- Legacy control system integration:Hydrogen-capable combustion retrofits require synchronization with existing Mark VI and Ovation distributed control architectures, extending commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gas Turbine MRO Market |
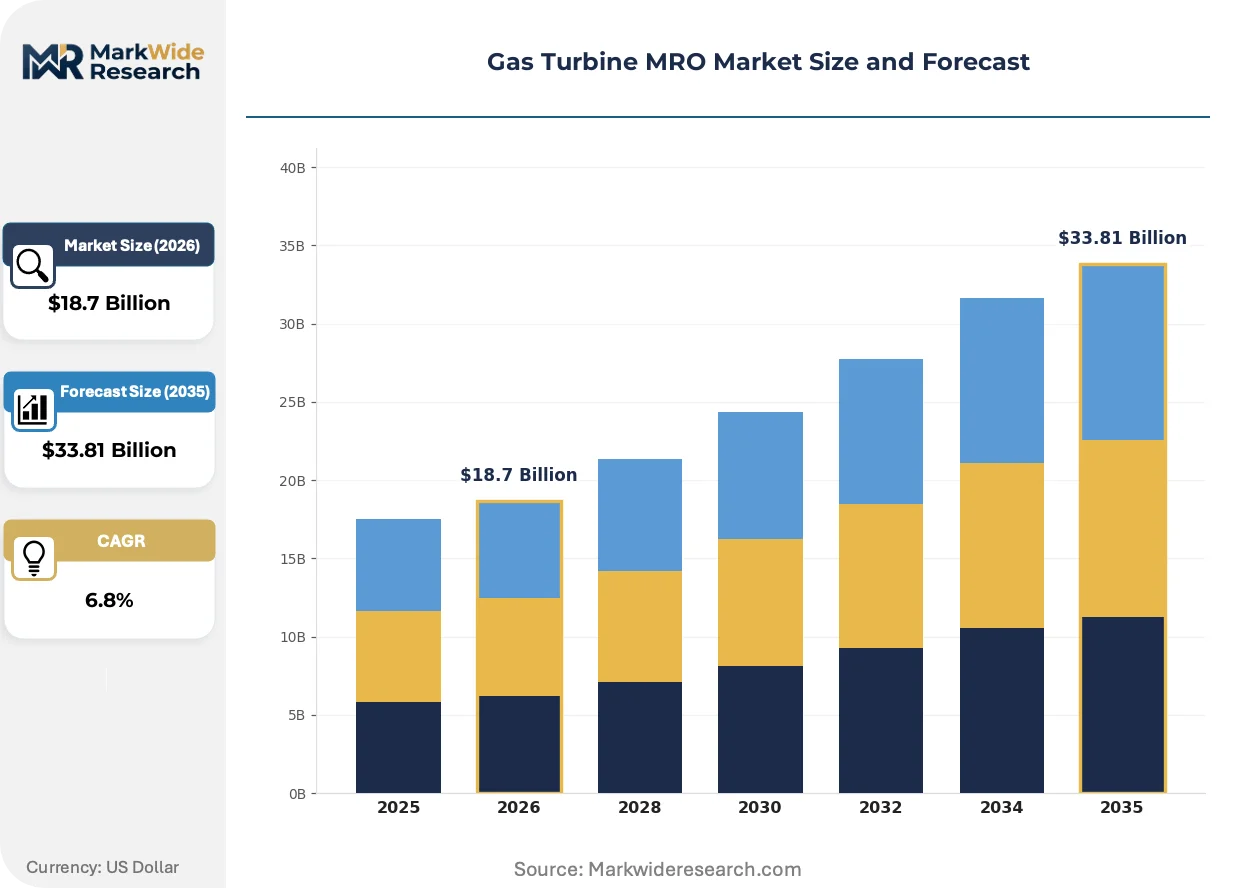
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Maintenance Type: Routine Maintenance, Overhaul, Repair, Replacement Service Type: Engine Services, Component Repair, Modification Services, Field Services End User: Aerospace, Marine, Industrial, Power Generation Technology: Digital Diagnostics, Predictive Maintenance, Turbine Upgrade, Condition Monitoring |
| Companies Covered | Solar Turbines, Turbine Ops, GE Vernova, Shanghai Electric, Baker Hughes, Siemens Energy, EthosEnergy, Ansaldo Energia, Mitsubishi Power, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gas Turbine MRO Market Emerging Trajectories
Digital instrumentation and additive repair processes are compressing traditional overhaul economics while regulatory hydrogen mandates force combustion architecture redesigns ahead of infrastructure availability.
Directed-energy-deposition cladding using cobalt-chrome powders is modularizing blade repair workflows by enabling in-situ restoration of eroded airfoil profiles without full rotor disassembly. Independent service providers in the Gulf Coast corridor are adopting these cells to capture turn-time-sensitive utility contracts. The technology is modularizing the traditional three-zone shop layout into cellular manufacturing configurations that reduce floor-space requirements.
EPA's 2023 reconsideration of particulate matter standards is tightening stack-emission thresholds for simple-cycle peaking units, forcing combustion-system redesigns during hot-section overhauls. Utilities in California and Texas are pre-positioning dry low-NOx hardware orders to secure fabrication slots ahead of compliance deadlines. The regulation is accelerating demand for staged-combustor retrofits that were previously deferred to end-of-life replacement cycles.
Long-term service agreement unbundling is fragmenting procurement authority as independent power producers separate predictive analytics subscriptions from parts-and-labor coverage. Merchant generators in ERCOT and PJM territories are negotiating à la carte hot-gas-path inspections while retaining in-house rotor balancing capabilities. This disaggregation is most visible among 200-400 MW combined-cycle operators seeking to minimize fixed-cost exposure during merchant price volatility.
Gas Turbine MRO Market Segmentation
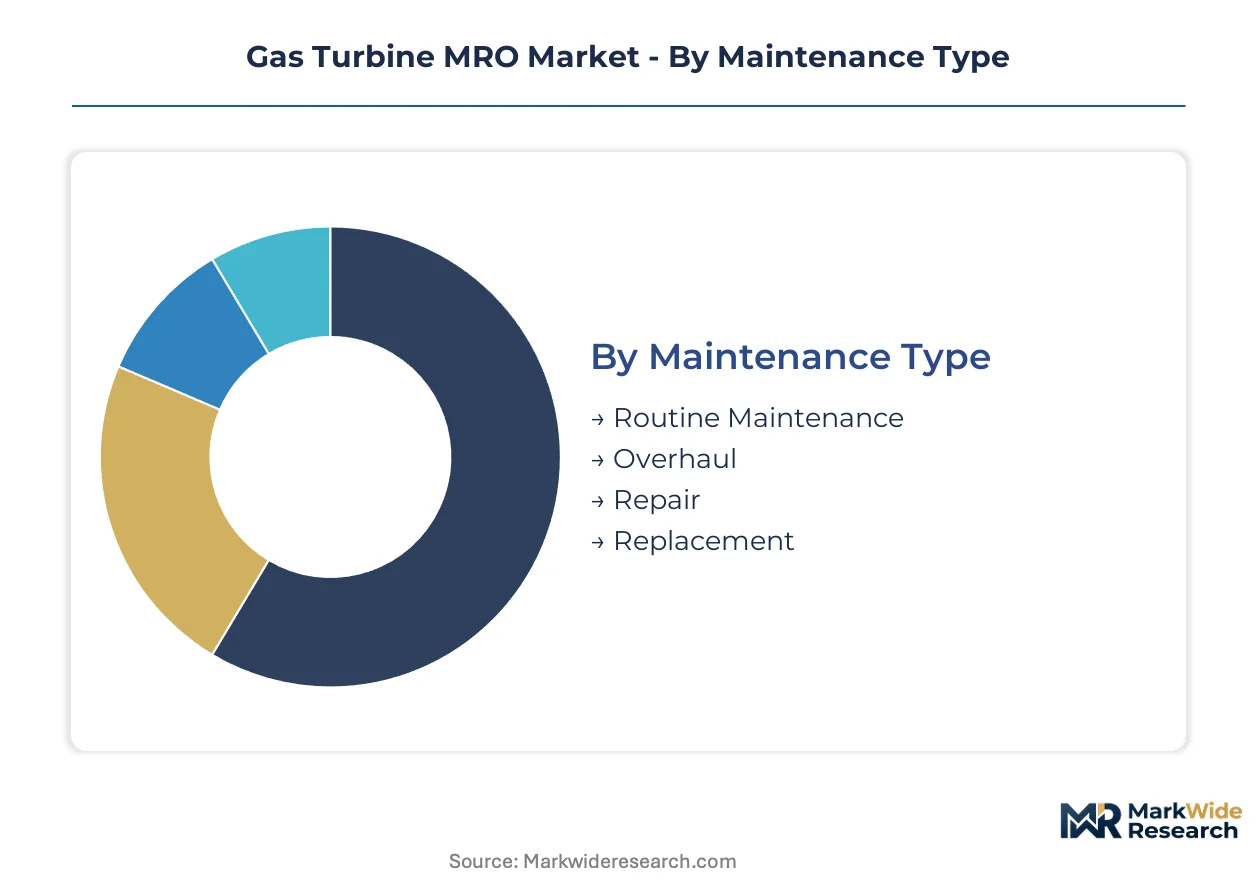
Gas turbine MRO procurement splits sharply between scheduled life-extension programs and unplanned failure response, with each maintenance category demanding distinct technical capabilities and turnaround commitments. Service providers must align shop-floor configuration and technician certification to the specific thermal-cycle demands of each segment.
Maintenance Type:
Volume-heavy routine work dominates shop throughput, while overhaul and replacement cycles concentrate margin in specialized hot-section capabilities.
- Overhaul:Complete disassembly, inspection, and restoration of rotor assemblies, combustors, and hot-gas-path components to OEM performance specifications. Demand concentrates in United States utility corridors—particularly Texas and California—where EPA dry low-NOx mandates force hardware replacement during major outage windows.
- Repair:Restoration of damaged airfoils, seals, and casings through welding, coating, and machining processes without full unit replacement. Texas refinery and petrochemical operators drive non-utility demand for modular fast-track repair programs that minimize production downtime.
- Routine Maintenance:Scheduled inspection, cleaning, and minor part replacement at prescribed operating-hour intervals.
- Replacement:Substitution of life-limited components including blades, vanes, and combustor baskets that exceed creep or fatigue thresholds.
Mature deployment sits with Routine Maintenance. Newer deployment is concentrated in Overhaul cycles driven by emissions compliance retrofit requirements.
Service Type:
Margin capture diverges between capital-intensive engine services and high-velocity component repair shops that exploit proprietary metallurgical processes.
- Engine Services:Integrated rotor balancing, combustion system redesign, and performance testing in witnessed test-cell facilities. United States combined-cycle operators under FERC-regulated reliability standards anchor demand for warranty-validated turnaround commitments.
- Component Repair:Specialized restoration of turbine blades, vanes, and transition pieces through directed-energy-deposition cladding and plasma-transferred-arc welding. Independent Gulf Coast providers capture turn-time-sensitive contracts through cellular manufacturing configurations.
- Field Services:On-site inspection, borescope examination, and minor repair without unit removal.
- Modification Services:Combustion hardware retrofits for hydrogen blending and emissions compliance.
Revenue concentration favors Engine Services. Fastest capability expansion is occurring in Component Repair through additive manufacturing adoption.
End User:
Application-specific thermal cycling patterns and duty-cycle intensity shape procurement authority and service-level requirements across user categories.
- Power Generation:Utility and independent power producer fleets operating combined-cycle and simple-cycle plants for baseload and peaking duty. United States merchant generators in ERCOT and PJM territories drive demand for unbundled predictive analytics and à la carte hot-gas-path inspections.
- Industrial:Refinery, petrochemical, and manufacturing facilities employing aeroderivative and heavy-frame turbines for mechanical drive and cogeneration. Texas and Louisiana operators repowering with aeroderivative units create demand for modular overhaul programs.
- Aerospace:Maintenance of aviation gas turbine engines for commercial and military aircraft.
- Marine:Overhaul of propulsion and auxiliary turbines for naval and commercial vessels.
Procurement sophistication is highest in Power Generation. Industrial applications are gaining share fastest through cogeneration revival and refinery repowering cycles.
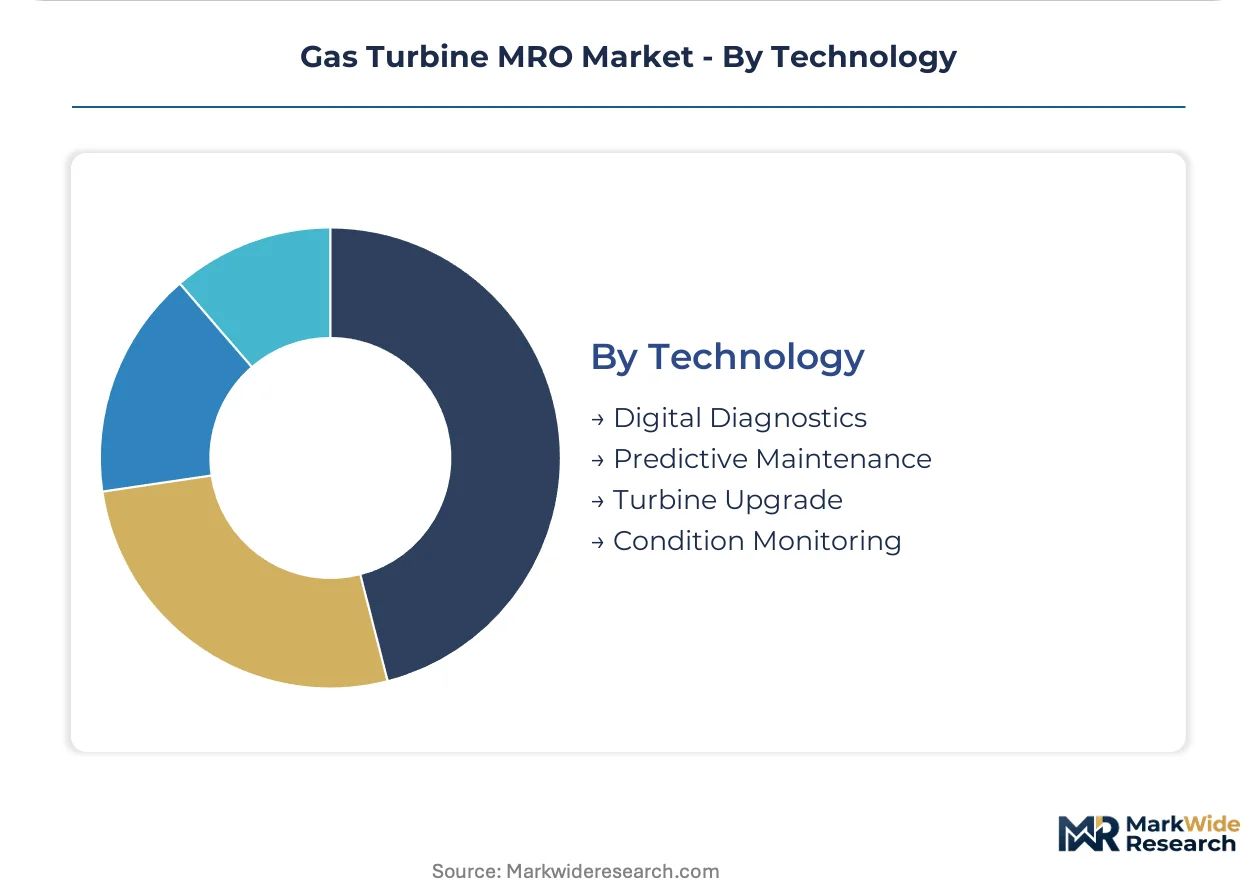
Technology:
Digital capability deployment separates OEM-captive service agreements from independent provider competition in remote diagnostics and remaining-life assessment.
- Predictive Maintenance:Sensor networks and machine-learning algorithms that forecast component degradation and optimize inspection timing. United States utilities retrofitting axial-flow units with real-time vibration monitoring compress inspection intervals and increase shop-visit frequency.
- Digital Diagnostics:Remote monitoring platforms that aggregate operational data for performance trending and anomaly detection. Convergence with finite-element thermal modeling enables independent providers to unbundle predictive services from OEM captive agreements.
- Condition Monitoring:Continuous measurement of vibration, temperature, and pressure parameters for operational safety.
- Turbine Upgrade:Hardware and software modifications that enhance output, efficiency, or fuel flexibility.
Installed base penetration is deepest in Condition Monitoring. Steepest expansion trajectory belongs to Predictive Maintenance as sensor deployment costs decline and analytics capabilities mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Houston anchors the largest concentration of gas turbine MRO activity worldwide, hosting specialized welding shops and coating facilities that serve utility and petrochemical operators across the Gulf Coast corridor. Regional demand patterns diverge sharply between emissions-driven overhaul cycles in North America and hydrogen-readiness retrofits across European industrial clusters.
United States
Texas and California utility corridors generate sustained demand for hot-gas-path component replacement and dry low-NOx combustor retrofits. EPA enforcement of particulate matter standards compels staged-combustor upgrades during major outage windows. Houston-Galveston and Los Angeles-Long Beach harbor industrial zones concentrate independent service providers with ASME-certified test cells.
Germany
Ruhr industrial basin utilities and chemical operators commission hydrogen-ready turbine conversions ahead of EU Green Deal infrastructure targets. EU F-Gas Regulation restricts fluorinated greenhouse gas use in cooling system overhauls, forcing heat exchanger redesigns. Mannheim and Düsseldorf host regional service hubs specializing in combined-cycle plant life extension.
China
Yangtze River Delta power generators deploy predictive maintenance sensor networks across aging coal-gasification and combined-cycle fleets. National dual carbon goals accelerate efficiency mandates for thermal plant retrofits. Shanghai and Jiangsu province concentrate domestic MRO capacity for heavy-frame turbine overhauls.
India
Gujarat and Maharashtra utility corridors open first-mover positions for hot-section refurbishment specialists under CEA grid modernization mandates. National thermal fleet efficiency targets compress payback thresholds for life-extension programs over new-unit procurement. Mumbai and Ahmedabad industrial zones anchor emerging independent service provider networks.
Japan
Kansai and Chubu regional utilities invest in axial-flow turbine sensor deployment for condition monitoring and remaining-life assessment. METI hydrogen blending pilots create forward-loaded demand for combustion system modifications. Osaka and Nagoya host specialized coating shops serving domestic combined-cycle operators.
Gas Turbine MRO Market Vendor Landscape
Premium-margin players sit above commodity-margin players across proprietary metallurgical process ownership and ASME certification depth. The vendor base stratifies between OEM-captive service arms with long-term agreement portfolios and independent specialists competing on turnaround velocity. Three archetypes dominate: full-service engine overhaul providers, component repair specialists with additive manufacturing capabilities, and field services operators deploying predictive analytics platforms. Capacity expansion and strategic technology licensing represent the dominant competitive vectors as independents seek to unbundle services from OEM captive agreements.
Within the OEM-captive tier, GE Vernova and Siemens Energy exemplify integrated service providers leveraging installed base access for long-term agreement retention. Among Asia-Pacific-based specialists, Mitsubishi Power and Shanghai Electric occupy positions emphasizing regional hub strategies and coating technology differentiation. EthosEnergy represents the independent specialist archetype competing on modular repair workflows and cellular manufacturing configurations.
| Leading Market Players |
|---|
| Solar Turbines |
| Turbine Ops |
| GE Vernova |
| Shanghai Electric |
| Baker Hughes |
| Siemens Energy |
| EthosEnergy |
| Ansaldo Energia |
| Mitsubishi Power |
| Others |
Supply Flow & Price Mechanics
Captive backward integration into vacuum-melted superalloy feedstock anchors pricing power for OEM-captive service arms while exposing independent providers to raw-material volatility and compressed margins. ASME-certified test-cell capacity in Houston and Mannheim concentrates premium-tier pricing authority, with EPA dry low-NOx retrofit mandates forcing utilities to absorb pass-through costs for combustion hardware during major outage windows.
Pricing Analysis
Uptime-guarantee contracts anchor value-based pricing for engine services, with premium tiers capturing warranty-validated turnaround commitments and economy tiers accepting longer lead times without performance guarantees. Price differentiation separates ASME PTC-22 certified providers from uncertified competitors, with ISO 3977 compliance commanding material premiums. Cost compression in component repair intensifies as Gulf Coast independents adopt directed-energy-deposition cells to capture turn-time-sensitive utility contracts. Merchant generators in ERCOT territories exhibit highest price sensitivity, while FERC-regulated utilities prioritize reliability over unit economics.
Supply Chain Analysis
Superalloy feedstock rests on vacuum-melted nickel-based casting capacity concentrated in the United States and Germany, with cobalt-chrome powder supply anchored in specialty chemical producers serving directed-energy-deposition repair cells. TIG and plasma-transferred-arc welding consumables, precision-machined blade forgings, and ceramic thermal barrier coatings constitute critical input dependencies. Single-source vulnerability in ASME Section IX certified technician pools constrains shop throughput expansion. Distribution runs through regional service hubs in Houston, Mannheim, and Shanghai that coordinate just-in-time parts logistics with utility outage scheduling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA emissions enforcement and EU F-Gas Regulation create a cost-of-compliance barrier that consolidates margin in certified incumbents while raising capital thresholds for new entrants. The regulatory moat deepens as hydrogen-readiness retrofits demand synchronized control system expertise.
For Market Incumbents: Acquire ASME-certified test-cell capacity in underserved utility corridors to preempt independent challengers. Consolidate regional welding shops with proprietary coating processes to defend against additive manufacturing disruptors. Backward integration into superalloy feedstock buffers margin compression from raw-material volatility. For New Entrants and Emerging Players: The premium-to-economy price gap in predictive analytics subscriptions offers white-space entry for independent digital twin platforms unbundled from OEM captive agreements. Target industrial cogeneration operators in Texas and Louisiana with modular fast-track repair programs. Lead with cellular manufacturing configurations that compress turnaround commitments below incumbent benchmarks. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to OEM service arms seeking regional hub expansion. Long-term viability favors providers with hydrogen-capable combustion retrofit capabilities and ISO 3977 certification depth. Watch EPA particulate matter standard reconsiderations as inflection triggers for accelerated hardware replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen-Ready Combustion Retrofit | EU Green Deal timelines force turbine conversions ahead of infrastructure availability. |
| Directed-Energy-Deposition Cell Deployment | Gulf Coast independents modularize blade repair workflows without full rotor disassembly. |
| Predictive Maintenance Platform Launch | Sensor networks compress inspection intervals and increase shop-visit frequency. |
| ASME PTC-22 Test-Cell Certification | Third-party providers face extended queues for warranty-validated performance testing. |
| Long-Term Service Agreement Unbundling | Merchant generators separate analytics subscriptions from parts-and-labor coverage. |
Methodological Framework
Independent corroboration across utility planning officers, IPP project developers, EPC contractors, and aftermarket service heads underwrites the qualitative findings. Primary interviews with maintenance directors at combined-cycle operators and procurement leads at refinery cogeneration facilities combined with secondary validation from EIA capacity data, FERC reliability filings, and IEA power sector reports. Bottom-up segmentation modeling triangulates against top-down market sizing from customs trade flows in superalloy castings and welding consumables.
Rate-of-change decomposition separates volume effects from price-mix shifts across the analysis window. Segmentation dimensions include maintenance type, service category, end-user application, and technology deployment. CAGRs derive from installed base retirement curves, emissions compliance retrofit schedules, and hydrogen blending infrastructure timelines. Forecast inputs incorporate EPA enforcement intensity projections and EU F-Gas Regulation phase-down schedules for fluorinated refrigerants.
Inputs from utility outage databases and OEM service agreement disclosures were available through the study window; gaps in independent shop financials introduce uncertainty bands around margin distribution estimates. Forecasts reflect assumptions on regulatory enforcement consistency and superalloy supply elasticity. A small set of triggers—hydrogen blending mandate acceleration, ASME certification rule changes, and superalloy export restrictions—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Maintenance and MRO Solutions
Helicopter MRO Market
Aircraft Maintenance and MRO Solutions
Middle-East Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Weight Scale Market
Aircraft Maintenance and MRO Solutions
Frame Alignment Systems Market
Aircraft Maintenance and MRO Solutions
North America Aircraft Engine MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Component MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Washing Systems Market
Aircraft Maintenance and MRO Solutions
Global Degaussing System Market
Aircraft Maintenance and MRO Solutions
Aviation Asset Management Market
Aircraft Maintenance and MRO Solutions
Aircraft Landing Gear Repair and Overhaul Market
Aircraft Maintenance and MRO Solutions
MRO Protective Coatings Market
Aircraft Maintenance and MRO Solutions
GCC Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Digital Aerospace MRO Market
Aircraft Maintenance and MRO Solutions
Africa Aviation MRO Market
Aircraft Maintenance and MRO Solutions
Aviation Maintenance Repair and Overhaul MRO Software Market
Aircraft Maintenance and MRO Solutions
Business Jet Mro Market