
 Aviation MRO Software Market | 2026-2036
Aviation MRO Software Market Size, Share, and Industry Trends Forecast 2026-2036
Aviation MRO Software Market Analysis
Subscription-based fleet analytics is broadening what aviation MRO software vendors monetize beyond perpetual licenses. IBS Software leverages cloud-native architecture to anchor long-term contracts with Asia-Pacific carriers. Ramco Systems competes through mobile-first maintenance workflows that reduce aircraft downtime. Oracle Corporation dominates enterprise-grade deployments by extending its ERP backbone into aviation-specific compliance modules.
Aviation MRO software encompasses digital platforms that schedule, track, and document aircraft maintenance, repair, and overhaul activities through modules integrating work order management, parts traceability, and regulatory compliance reporting. These systems typically interface with airframe OEM data standards and ATA chapter coding to ensure technical documentation interoperability across operator and third-party maintenance networks. Cloud-based deployment leads adoption among mid-sized carriers seeking lower capital overhead, while artificial intelligence integration represents the fastest-expanding technology layer as predictive algorithms reduce unscheduled component removals. Maintenance software remains the most mature product category with established vendor consolidation, whereas inventory management modules command premium pricing through real-time parts availability optimization.
The FAA mandates digital record-keeping under Part 121 and Part 135 rules, while EASA's continuing airworthiness management organization framework drives software standardization across European operators. China's CAAC enforces localized data residency requirements that shape vendor hosting architectures for carriers serving domestic routes. Stakeholders must weigh regulatory divergence against platform consolidation as jurisdictions tighten cybersecurity and audit trail specifications.
Market Dynamics
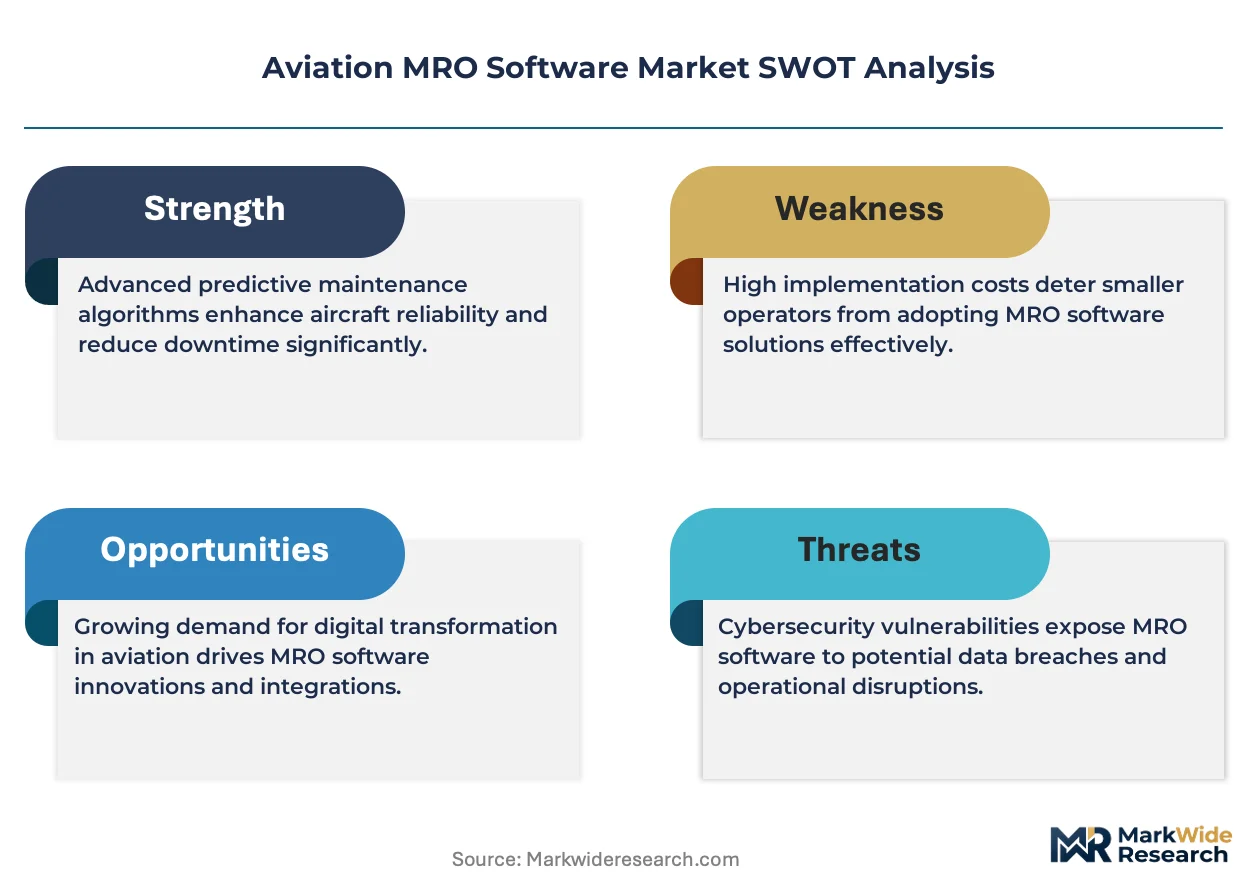
Cloud migration is compressing the sales cycle for aviation MRO software vendors as carriers abandon on-premise infrastructure to meet FAA predictive maintenance mandates and reduce IT overhead. This structural shift favors platform providers with native multi-tenant architectures over legacy client-server systems.
Growth Catalysts
- Part 121 Digital Mandates:FAA enforcement of predictive maintenance record-keeping for scheduled carriers is forcing replacement of paper-based systems with integrated compliance platforms.
- Fleet Complexity:Mixed-generation aircraft portfolios spanning narrow-body and wide-body types require software capable of managing divergent OEM data standards and maintenance intervals.
- Asia-Pacific Capacity Expansion:Low-cost carriers in Indonesia, Vietnam, and the Philippines are procuring cloud-native MRO suites to support rapid fleet growth without capital-intensive infrastructure.
Market Restraints
- Data Residency Requirements:China's CAAC localized hosting rules fragment vendor architectures and inflate operational costs for carriers with cross-border operations.
- Legacy System Entrenchment:Major US network carriers carry decades of customized maintenance databases that resist modular replacement without multimillion-dollar migration projects.
- Cybersecurity Certification Delays:EASA's evolving audit trail specifications for continuing airworthiness management organizations extend sales cycles by 8-14 months.
Strategic Opportunities
- AI-Layer Integration:Predictive algorithms trained on component failure patterns represent unmonetized white space beyond core maintenance scheduling functionality.
- Third-Party MRO Penetration:Independent repair stations in Poland, Turkey, and Mexico lack enterprise-grade software and present mid-market entry points.
- Inventory Network Effects:Real-time parts availability optimization across operator pools creates platform stickiness distinct from transactional license sales.
Industry Challenges
- Aviation Software Talent Scarcity:Developers with simultaneous expertise in ATA chapter coding, airworthiness regulations, and modern cloud architecture command premium compensation that strains vendor margins.
- OEM Data Standard Fragmentation:Airbus, Boeing, and Embraer maintain proprietary technical documentation formats that force costly adapter development for interoperability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aviation MRO Software Market |
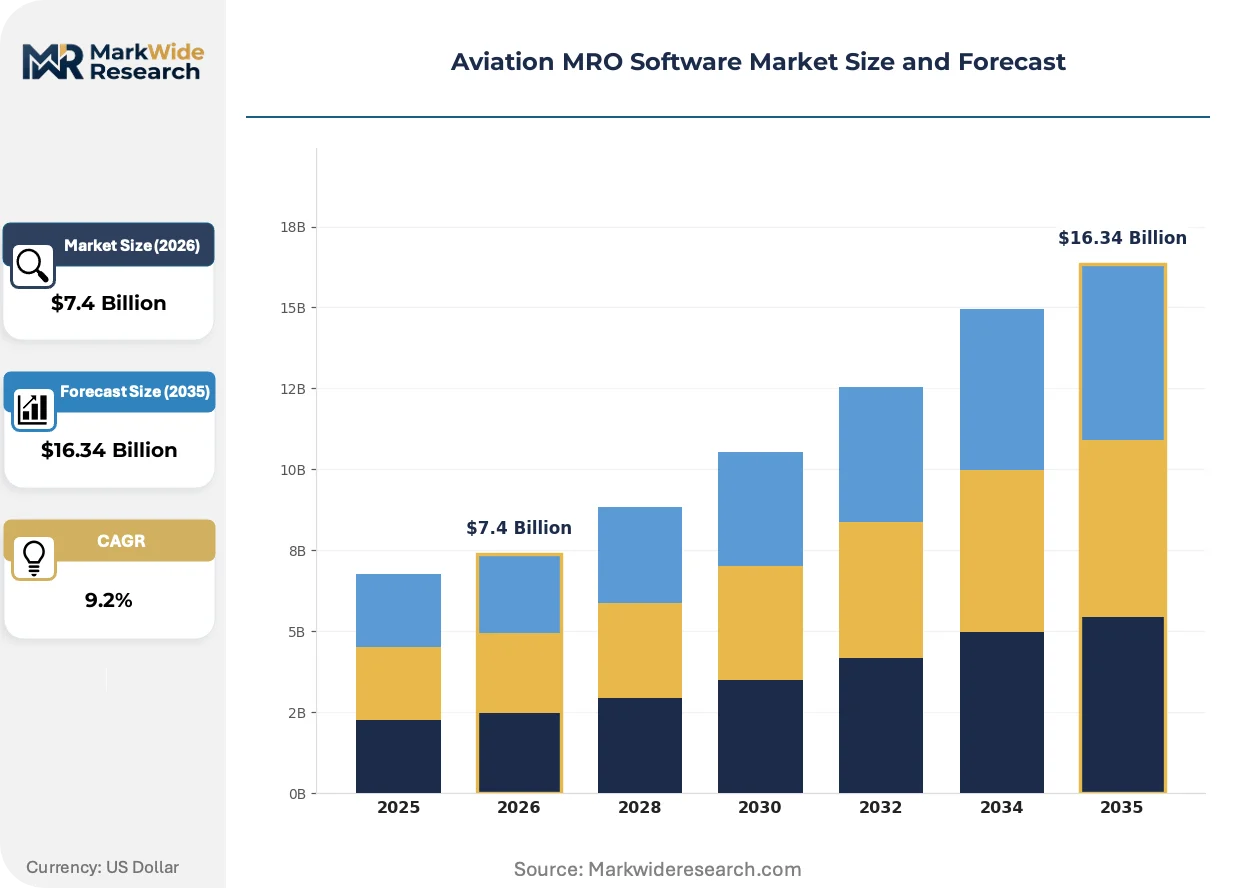
| Market Size in 2026 | $7.4 Billion |
| Market Size in 2035 | $16.34 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Maintenance Software, Inspection Systems, Inventory Management, Document Control End User: Commercial Airlines, Business Aviation, Military Operators, Maintenance Providers Deployment: On-Premise, Cloud-Based, Hybrid, Web-Based Technology: Artificial Intelligence, IoT Solutions, Data Analytics, Mobile Applications |
| Companies Covered | IBS Software, Lufthansa Technik AG, Ramco Systems, Oracle Corporation, General Electric Company, IFS AB, Flatirons Solutions, SAP SE, Swiss Aviation Software, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aviation MRO Software Market Emerging Trajectories
Artificial intelligence is penetrating maintenance workflows through predictive component monitoring, while regulatory pressure accelerates consolidation around integrated compliance suites. Procurement patterns favor vendors demonstrating cross-fleet data harmonization capabilities.
Digital twin technology is rewriting how airlines model aircraft system degradation. Carriers with mixed Airbus and Boeing fleets are deploying physics-based simulations to compress troubleshooting time for intermittent faults. This capability is rewriting competitive positioning by enabling differentiated service-level agreements tied to mean-time-to-repair metrics rather than software feature checklists.
EASA's continuing airworthiness management organization framework is tightening software standardization requirements across European operators. The regulation mandates centralized technical record repositories accessible to national aviation authorities during spot audits. Part 135 operators in Germany and France are responding by consolidating previously fragmented point solutions into unified platforms to reduce compliance documentation labor.
Subscription-based fleet analytics are displacing perpetual license structures among mid-sized carriers seeking operational expenditure treatment for IT investments. Third-party MRO providers in Southeast Asia are adopting usage-based pricing models that scale with flight hour volume. This shift is most visible in Indonesia, where rapid fleet expansion makes capital-intensive on-premise deployments economically unworkable for emerging low-cost carriers.
Aviation MRO Software Market Segmentation
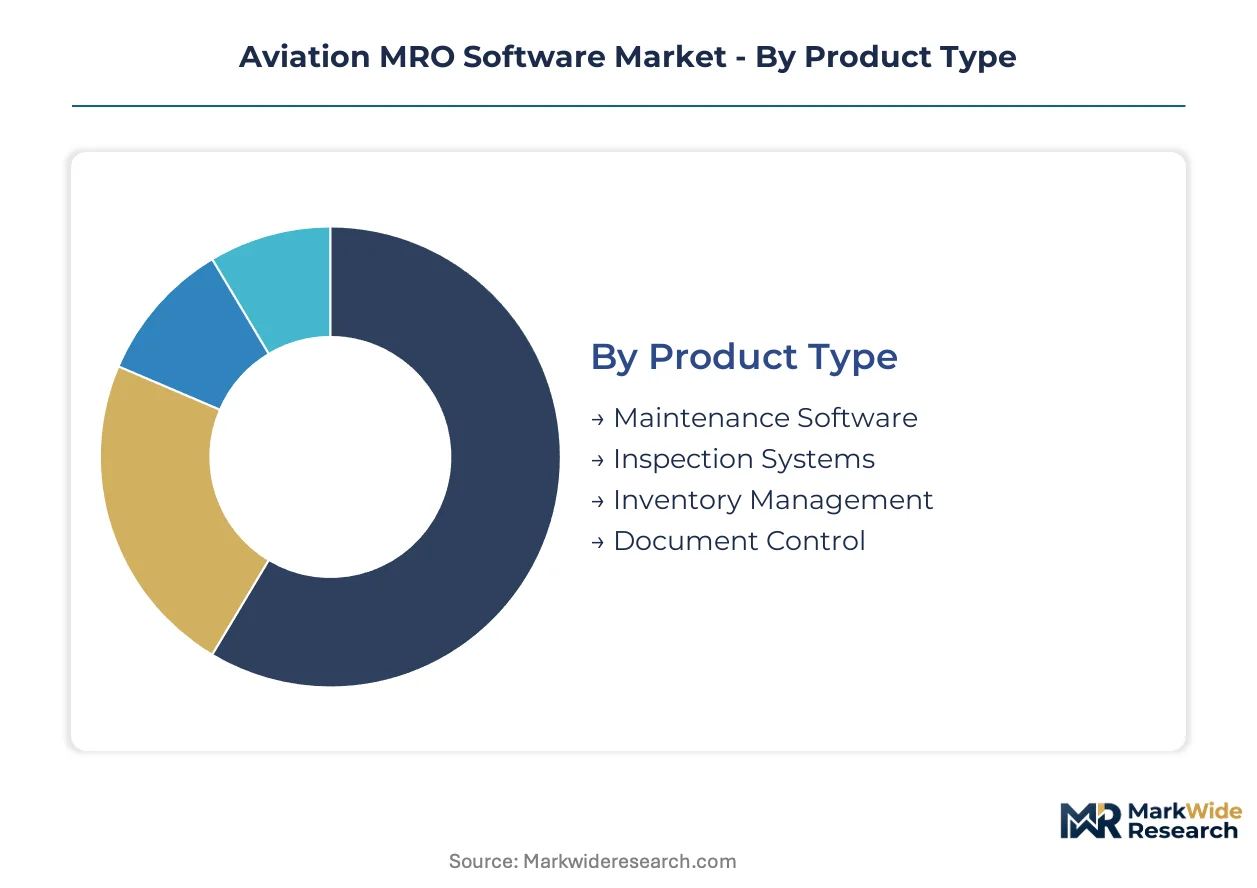
Aviation MRO software vendors configure product architectures around operator scale, regulatory jurisdiction, and fleet complexity. Segmentation decisions determine whether carriers absorb platform costs as capital expenditure or operational expenditure, reshaping contract structures and vendor profitability.
Product Type:
Standardization dominates maintenance scheduling modules while inspection systems require heavy customization to airframe-specific technical documentation formats.
- Maintenance Software:Core modules manage work order generation, labor tracking, and component life monitoring against OEM maintenance planning documents. Demand concentrates among Part 121 operators in the United States replacing legacy client-server systems to meet FAA predictive maintenance mandates.
- Inventory Management:Real-time parts availability engines optimize stock levels across distributed warehouse networks using ATA chapter classification for traceability. Carriers with mixed Airbus-Boeing fleets in Germany and France prioritize these modules to reduce aircraft-on-ground incidents from component shortages.
- Inspection Systems:Digital checklists with photographic evidence capture streamline airworthiness directive compliance.
- Document Control:Centralized technical record repositories satisfy EASA continuing airworthiness management organization audit requirements.
Most installed capacity flows through Maintenance Software. Expansion is steepest in Inventory Management.
End User:
Procurement authority varies sharply across operator categories, with military contracts favoring on-premise security architectures and commercial carriers accepting multi-tenant cloud terms.
- Commercial Airlines:Scheduled carriers operating under Part 121 rules drive demand for integrated compliance suites spanning maintenance, inventory, and regulatory reporting. Network carriers in the United States consolidate vendor relationships around platforms demonstrating cross-fleet data harmonization.
- Maintenance Providers:Independent repair stations in Poland, Turkey, and Mexico lack enterprise-grade software and represent mid-market entry points for cloud-native vendors. Third-party MROs price contracts competitively by reducing overhead through usage-based software licensing.
- Business Aviation:Fractional ownership operators and corporate flight departments prioritize mobile-first workflows for dispersed maintenance teams.
- Military Operators:Defense aviation commands segmented security certifications and air-gapped deployment architectures.
Commercial Airlines command the largest share of vendor revenue. Maintenance Providers are gaining share fastest as outsourcing accelerates.
Deployment:
Capital expenditure constraints among emerging carriers are compressing sales cycles for cloud-native architectures while legacy operators amortize on-premise investments.
- Cloud-Based:Multi-tenant platforms eliminate infrastructure ownership and enable subscription pricing aligned with flight hour volumes. Low-cost carriers in Indonesia, Vietnam, and the Philippines adopt these deployments to support rapid fleet growth without data center construction.
- On-Premise:Single-tenant installations persist among major US network carriers carrying decades of customized maintenance databases resistant to modular replacement without multimillion-dollar migration projects.
- Hybrid:Split architectures isolate sensitive airworthiness data on-premise while pushing analytics workloads to cloud infrastructure.
- Web-Based:Browser-accessible thin clients serve third-party MROs requiring rapid deployment across multiple customer sites.
Cloud-Based deployments now dominate new procurement decisions. Hybrid architectures are expanding most quickly among carriers with cross-border operations facing data residency requirements.
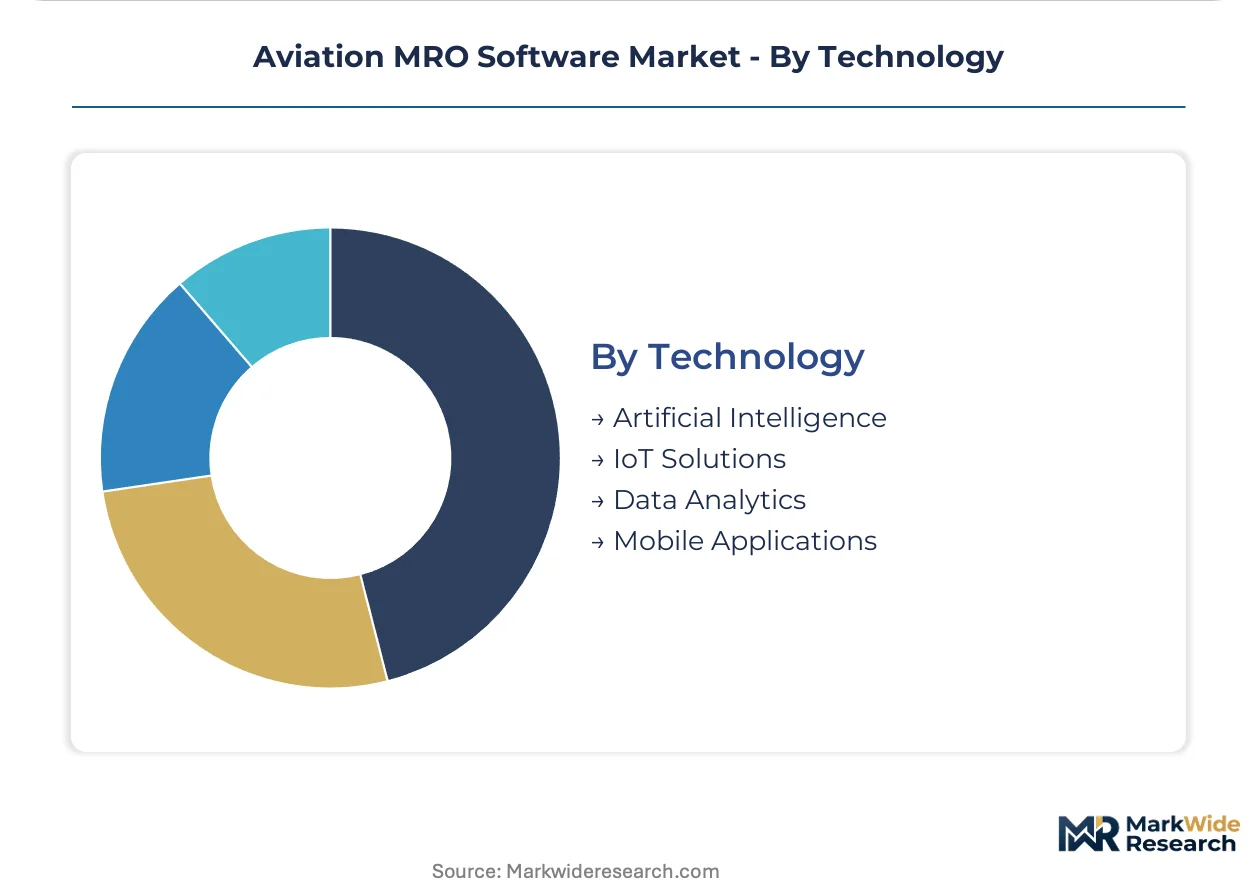
Technology:
Artificial intelligence integration commands premium pricing while mobile applications face commoditization across vendor portfolios.
- Artificial Intelligence:Predictive algorithms trained on component failure patterns reduce unscheduled removals by identifying degradation signatures before functional failure. Carriers with mixed-generation fleets deploy these tools to optimize maintenance interval planning.
- IoT Solutions:Sensor networks on aircraft systems stream operational parameters to ground-based analytics platforms for real-time health monitoring. Engine OEMs in the United States and France drive standardization of data formats for these feeds.
- Data Analytics:Fleet-wide benchmarking tools compare reliability metrics across operator networks to identify systemic issues.
- Mobile Applications:Technician-facing apps with offline synchronization support line maintenance activities at remote stations.
Data Analytics layers claim the broadest installed base. Artificial Intelligence represents the steepest expansion trajectory as predictive maintenance mandates tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States carriers consolidate vendor relationships around integrated suites while Indonesia's low-cost carriers adopt cloud-native platforms to bypass infrastructure investments. Regulatory divergence between FAA predictive maintenance mandates and China's data residency requirements fragments vendor architectures across major aviation markets.
United States
Major network carriers replace legacy client-server systems with FAA-compliant predictive maintenance platforms. Part 121 operators face enforcement pressure to digitize record-keeping for scheduled maintenance activities. Dallas-Fort Worth and Atlanta anchor concentrated procurement decisions as American Airlines and Delta Air Lines consolidate multi-year vendor contracts.
Germany
Lufthansa Technik drives demand for continuing airworthiness management organization-compliant document control modules. EASA mandates centralized technical record repositories accessible during spot audits. Hamburg and Frankfurt concentrate software procurement authority among integrated airline-MRO groups serving mixed Airbus-Boeing fleets.
China
Domestic carriers serving internal routes absorb elevated operational costs from CAAC-mandated localized data hosting. The national aviation regulator enforces data residency rules that fragment cloud architectures for cross-border operators. Beijing and Shanghai house procurement decisions for state-owned carriers expanding narrow-body fleets.
Indonesia
Rapid fleet expansion among low-cost carriers makes capital-intensive on-premise deployments economically unworkable. Garuda Indonesia and Lion Air Group prioritize subscription pricing aligned with flight hour volumes. Jakarta concentrates vendor selection authority as carriers procure cloud-native suites without data center construction.
United Kingdom
British Airways and Virgin Atlantic drive demand for cross-fleet data harmonization capabilities spanning mixed-generation aircraft. The Civil Aviation Authority enforces audit trail specifications that extend procurement cycles for compliance modules. London Heathrow and Gatwick anchor maintenance software decisions among legacy carriers with decades of customized databases.
Aviation MRO Software Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with enterprise software vendors capturing premium-tier airline contracts while niche providers penetrate third-party MRO stations. The vendor base concentrates around three strategic archetypes: cloud-native platform specialists, ERP-extended aviation modules, and legacy maintenance system modernizers. Consolidation favors multi-tenant architectures over client-server legacy systems. Competitive moves center on AI-layer integration and inventory network effects that create platform stickiness.
Within the cloud-native tier, IBS Software and Ramco Systems exemplify architectures designed for rapid deployment across Asia-Pacific carriers. Oracle Corporation occupies a position among ERP-anchored vendors extending financial system backbones into aviation-specific compliance modules. Lufthansa Technik represents the integrated airline-MRO archetype, leveraging captive maintenance expertise to inform software development priorities.
| Leading Market Players |
|---|
| IBS Software |
| Lufthansa Technik AG |
| Ramco Systems |
| Oracle Corporation |
| General Electric Company |
| IFS AB |
| Flatirons Solutions |
| SAP SE |
| Swiss Aviation Software |
| Others |
Supply Flow & Price Mechanics
Part 121 carriers consolidating vendor relationships around integrated compliance suites are compressing procurement timelines and forcing software vendors to absorb customization costs into subscription pricing. This buyer concentration shifts pricing power toward network carriers in the United States while elevating operational leverage for cloud-native platform providers with multi-tenant architectures.
Pricing Analysis
Capacity additions in Indonesia and Vietnam are reshaping price floors for cloud-native MRO suites as low-cost carriers negotiate usage-based contracts tied to flight hour volumes. SaaS-tiered subscription models dominate new procurement, with price differentiation anchored in AI-layer integration depth and EASA compliance certification levels. Pricing pressure stems from rapid carrier consolidation in Southeast Asia. Regional low-cost carriers exhibit highest price sensitivity, while major US network carriers prioritize total cost of ownership over license fees.
Supply Chain Analysis
Dual-sourcing requirements from Part 121 operators mandate multi-vendor qualification for critical maintenance modules, fragmenting procurement across IBS Software, Ramco Systems, and Oracle Corporation deployments. Software development concentrates in India, Ireland, and the United States, with cloud infrastructure dependencies drawing from Amazon Web Services, Microsoft Azure, and Google Cloud regions. Supply chain risk centers on CAAC-mandated data residency rules that force localized hosting architectures. Distribution runs through direct enterprise sales teams and aviation-specific systems integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as FAA predictive maintenance mandates and EASA continuing airworthiness requirements elevate procurement specifications toward integrated compliance platforms over point solutions.
For Market Incumbents: To counter margin compression from cloud-native entrants in Asia-Pacific, anchor long-term contracts through AI-layer integration and inventory network effects that create platform stickiness. Prioritize backward integration into aviation-specific data analytics capabilities. Defend enterprise tier relationships by extending ERP backbone modules into predictive maintenance workflows. For New Entrants and Emerging Players: The price-point gap between premium Oracle-anchored deployments and economy-tier legacy modernizations opens white space in Poland, Turkey, and Mexico independent repair stations. Target third-party MRO providers lacking enterprise-grade software through mobile-first maintenance workflows. Penetrate via usage-based pricing models that scale with flight hour volume without capital-intensive infrastructure requirements. For Investors and Strategic Acquirers: Asymmetric upside sits with cloud-native platform specialists demonstrating cross-fleet data harmonization capabilities and Asia-Pacific carrier penetration. Long-term viability favors vendors with native multi-tenant architectures over legacy client-server modernizers. Watch AI-layer monetization rates as the inflection indicator for platform differentiation sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Layer Integration | Predictive algorithms trained on component failure patterns command premium subscription tiers from Part 121 operators. |
| Platform Consolidation | Unified compliance suites reduce EASA audit documentation labor for German and French continuing airworthiness management organizations. |
| Geographic Expansion | Cloud-native deployments in Indonesia bypass data center construction for Lion Air Group rapid fleet growth. |
| Strategic Partnership | Systems integrator alliances accelerate FAA-compliant implementations at American Airlines and Delta Air Lines hubs. |
| Acquisition of Specialist Firm | Mobile-first maintenance workflow specialists extend reach into business aviation fractional ownership operators. |
Methodological Framework
Direct dialogue with aviation software procurement officers, airline maintenance directors, third-party MRO operations managers, and regulatory compliance leads grounded the qualitative foundation. Secondary validation drew from FAA Part 121 enforcement guidance, EASA continuing airworthiness management organization specifications, CAAC data residency directives, SEC 10-K filings from Oracle and SAP, and aviation trade association deployment surveys. Bottom-up carrier-by-carrier procurement analysis triangulated against top-down vendor revenue segmentation across deployment models and technology layers.
Market size and growth trajectory outputs reflect econometric modeling across product type, end user category, deployment architecture, and technology integration depth dimensions throughout the projection horizon. CAGRs derive from regression analysis against fleet expansion forecasts, regulatory mandate implementation timelines, and cloud migration adoption curves. Industry-specific inputs include Part 121 operator digital compliance deadlines, Asia-Pacific low-cost carrier fleet growth rates, and AI predictive maintenance module attach rates.
The model assumes a particular technology adoption path; alternative pathways for artificial intelligence integration would alter the outlook if regulatory mandates accelerate or carrier consolidation patterns shift. Deviation in FAA enforcement intensity or EASA audit trail specification evolution would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Maintenance and MRO Solutions
Aircraft Recycling Market
Aircraft Maintenance and MRO Solutions
Aircraft Engine Hoists Market
Aircraft Maintenance and MRO Solutions
Regional Turboprop Engine MRO Services Market
Aircraft Maintenance and MRO Solutions
Airplane Pushback Tug Market
Aircraft Maintenance and MRO Solutions
Gas Turbine MRO Market
Aircraft Maintenance and MRO Solutions
Commercial Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Maintenance Market
Aircraft Maintenance and MRO Solutions
US Aviation MRO Software Market
Aircraft Maintenance and MRO Solutions
Middle-East and Africa Aircraft Engine MRO Market
Aircraft Maintenance and MRO Solutions
Europe Aircraft Engine MRO Market
Aircraft Maintenance and MRO Solutions
United States Airframe MRO Market
Aircraft Maintenance and MRO Solutions
Europe Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Global Aircraft Heavy Maintenance Visits Market
Aircraft Maintenance and MRO Solutions
Latin America Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Distributed Electric Propulsion System MRO Services Market
Aircraft Maintenance and MRO Solutions
Middle-East and Africa Aircraft MRO Market