
 Aircraft Storage, Preservation and Reactivation Services Market | 2026-2036
Aircraft Storage, Preservation and Reactivation Services Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Storage, Preservation and Reactivation Services Market Insights
Digital twin integration is narrowing the gap between predictive analytics and physical aircraft preservation workflows. TARMAC Aerosave leverages its multi-site European footprint to sustain competitive positioning across short-term and long-term service tiers. Ascent Aviation Services anchors its market presence through specialized military and commercial reactivation capabilities in the southwestern United States.
Aircraft storage, preservation and reactivation services encompass the systematic mothballing, environmental protection, and return-to-service preparation of temporarily idle airframes, typically requiring humidity control below 40% relative humidity, corrosion-inhibiting compound application, and periodic engine rotation to preserve mechanical integrity. These services exist to maintain airworthiness certification continuity and protect asset residual value during operational pauses. The service type dimension shows long-term preservation commanding the deepest margin pools due to specialized labor and material intensity, while reactivation services are expanding fastest as post-pandemic fleet normalization accelerates. Within end users, leasing firms represent a structurally growing segment because lessor portfolio management demands frequent transition-state aircraft handling.
The FAA governs U.S. storage standards through specific airworthiness directives for prolonged parking, while EASA's Part-M regulations shape European preservation protocols and documentation requirements. Military fleet operators face additional compliance layers from national defense aviation authorities that mandate classified-system protection during idle periods. Stakeholders must monitor how evolving corrosion-control technology standards and shifting airline fleet strategy will reshape capacity planning and service specialization requirements.
Market Dynamics
The FAA's tightening airworthiness directive framework for prolonged aircraft parking is forcing storage providers to upgrade facility monitoring systems and documentation protocols, compressing margins for operators lacking capital reserves.
Growth Catalysts
- Cyclical Fleet Adjustments:Commercial airlines facing demand volatility are expanding professional preservation contracts to maintain airworthiness certification continuity during operational pauses. Leasing firms now represent structurally growing demand as portfolio transitions accelerate.
- EASA Part-M Documentation Requirements:European preservation protocols mandate enhanced record-keeping for corrosion-control interventions, creating pull-through demand for integrated digital logging systems alongside physical storage services.
- Desert Climate Concentration:Facility expansion in Arizona and California leverages arid conditions that naturally suppress humidity below critical thresholds, reducing active climate control energy costs for long-term preservation contracts.
Market Restraints
- Specialized Labor Scarcity:Certified airframe preservation technicians command premium wages, and training pipelines remain thin, constraining capacity expansion for long-term service tiers requiring intensive material application.
- Input Cost Volatility:Corrosion-inhibiting compounds and specialized humidity control equipment face supply chain concentration risks, with key chemical suppliers concentrated in Germany and Japan.
- Regulatory Friction:Military fleet operators face additional compliance layers from national defense aviation authorities mandating classified-system protection, creating documentation barriers that civilian providers cannot easily cross.
Strategic Opportunities
- Digital Twin Convergence:Predictive analytics platforms are hybridizing with physical preservation workflows, enabling remote airframe condition monitoring that reduces manual inspection frequency and opens subscription revenue streams.
- Reactivation Service Expansion:Post-pandemic fleet normalization is accelerating return-to-service preparation demand, with shorter cycle times and higher labor intensity than storage operations.
- India Aviation Growth:The country's expanding leased aircraft fleet and humid coastal climate create structural need for professional preservation infrastructure currently served by ad hoc arrangements.
Industry Challenges
- Certification Timeline Compression:FAA airworthiness directive compliance for reactivated aircraft requires compressed documentation review periods, straining quality assurance staffing during demand surges.
- Legacy System Integration:Established storage facilities operate paper-based record systems that resist digitization, complicating the shift to predictive maintenance platforms demanded by lessor clients.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Storage, Preservation and Reactivation Services Market |
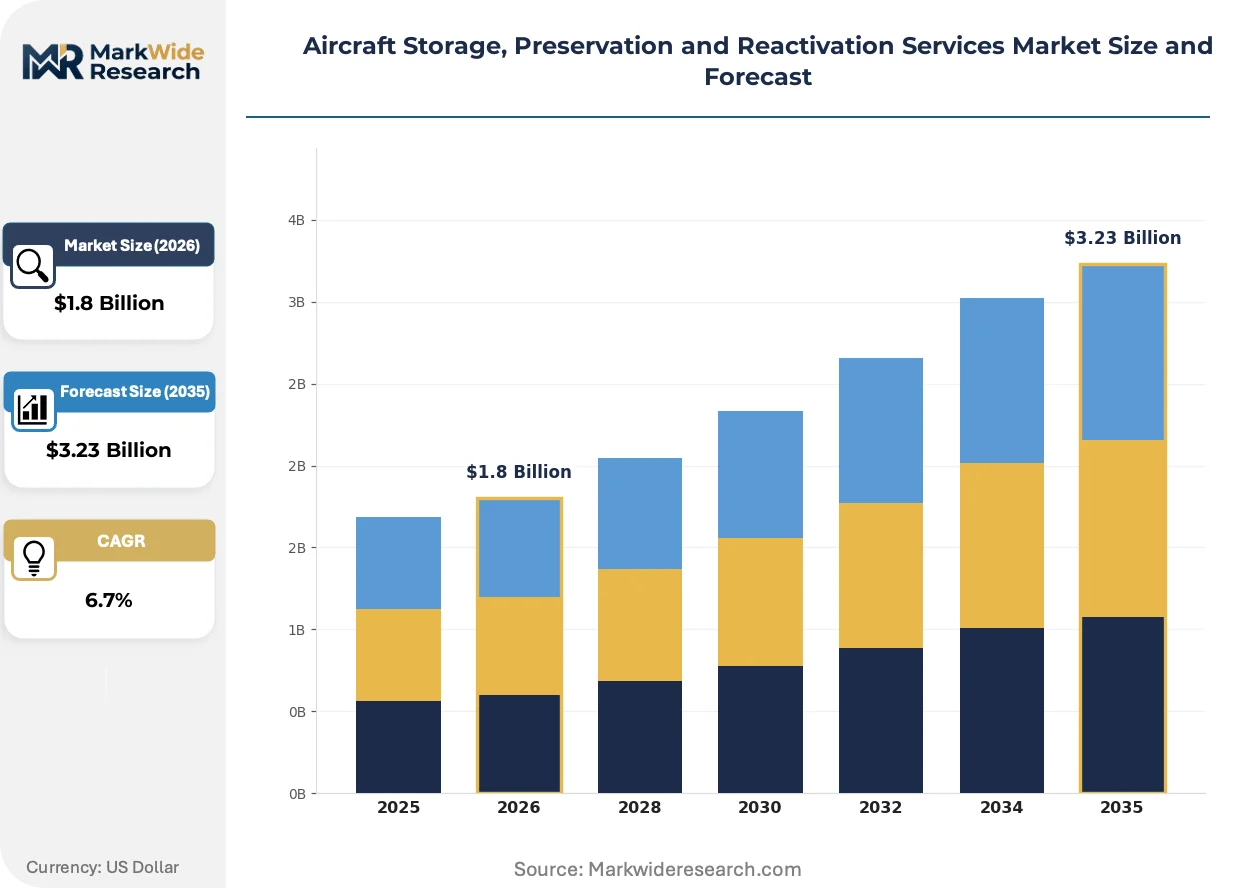
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Short-Term Storage, Long-Term Preservation, Reactivation, Maintenance Support, Dehumidification, Cleaning End User: Commercial Airlines, Cargo Operators, Leasing Firms, Military Fleet Operators, Private Jet Owners, Charter Services Application: Fleet Optimization, Seasonal Demand Management, Regulatory Compliance, Asset Life Extension, Emergency Backup, Repair Preparation Technology: Corrosion Control, Protective Coatings, Climate-Controlled Hangars, Monitoring Systems, Automated Preservation, Engine Preservation |
| Companies Covered | TARMAC Aerosave, Ascent Aviation Services, Asia Pacific Aircraft Storage, ecube, Vallair, AAR, Jet Aviation, FL Technics, AMROS Global, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Storage, Preservation and Reactivation Services Market Trends and Innovations
Digital infrastructure is reshaping how preservation providers demonstrate airworthiness continuity to regulators and asset owners, compressing the gap between physical intervention and data-driven verification.
Environmental sensor networks are hybridizing with blockchain-based documentation systems to create immutable humidity and corrosion treatment records. Major lessors now mandate such verification layers before accepting returned aircraft, displacing traditional paper logbooks. This convergence is compressing liability exposure for storage providers while raising capital requirements for facility upgrades.
REACH chemical authorization protocols in Europe are restricting traditional corrosion-inhibiting compound formulations, forcing reformulation investments and supplier qualification changes. The industrial consequence extends preservation cycle times as new compounds undergo extended compatibility testing. Military and commercial segments in Germany and France face the tightest compliance windows, accelerating partnerships with specialty chemical firms.
Leasing firms are unbundling preservation services from lease agreements and sourcing directly through preferred provider networks, displacing airline-controlled procurement. This disintermediation concentrates buying power with fewer decision-makers and compresses pricing leverage for regional storage operators. The shift is most visible across Dublin and Singapore, where major lessor headquarters drive contract standardization.
Aircraft Storage, Preservation and Reactivation Services Market Segmentation
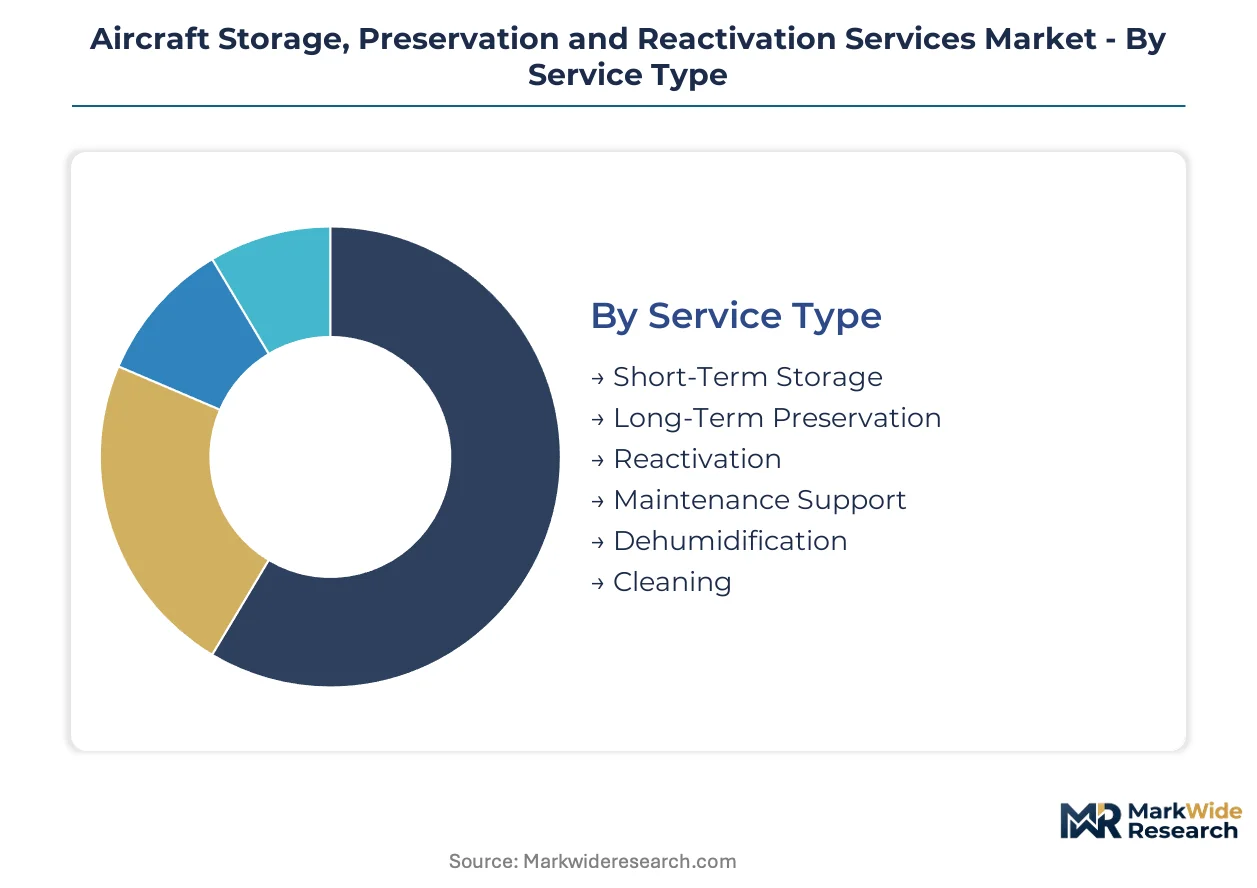
Service differentiation in aircraft preservation hinges on cycle-time economics. Short-turnaround reactivation commands premium labor rates, while multi-year preservation contracts amortize facility costs across extended durations. Understanding segment velocity helps providers align staffing and capital deployment with revenue recognition patterns.
Service Type:
Cycle times range from 72-hour reactivation sprints to decade-long preservation holds, creating divergent working capital intensity across the service portfolio.
- Short-Term Storage:Temporary parking solutions spanning 30 to 180 days with minimal intervention requirements. Arizona desert facilities dominate this segment due to natural humidity suppression that reduces active climate control costs during brief idle periods.
- Long-Term Preservation:Multi-year mothballing requiring corrosion-inhibiting compound application, engine preservation protocols, and periodic mechanical rotation. Leasing firms in Dublin and Singapore drive structural demand as portfolio transitions accelerate, though specialized technician scarcity constrains capacity expansion.
- Reactivation:Return-to-service preparation including FAA airworthiness directive compliance documentation and compressed quality assurance review. Post-pandemic fleet normalization has steepened demand curves for this labor-intensive segment.
- Maintenance Support:Ongoing airframe servicing during storage periods to preserve certification continuity. Demand concentrates among military fleet operators facing national defense aviation authority mandates.
- Dehumidification:Active humidity control systems maintaining sub-40% relative humidity thresholds. Energy costs vary dramatically between arid southwestern United States facilities and humid coastal alternatives.
- Cleaning:Exterior wash and interior preparation services preceding storage or reactivation. This entry-level service tier faces pricing pressure from airline in-house capabilities.
Long-term preservation anchors the volume base while reactivation gains share at the steepest rate.
End User:
Procurement authority is shifting from airline operations teams to lessor asset managers, reshaping contract structures and technical specification requirements.
- Commercial Airlines:Cyclical fleet adjustment programs drive demand volatility as carriers park aircraft during demand troughs. United States legacy carriers favor multi-year preservation contracts that maintain airworthiness certification continuity without crew retention costs.
- Leasing Firms:Portfolio transition management requires frequent handling of aircraft between lessees. Dublin and Singapore headquarters now mandate blockchain-based documentation systems before accepting returned aircraft.
- Cargo Operators:Seasonal freight pattern variations create predictable storage demand cycles. E-commerce logistics expansion in India generates new preservation requirements for converted freighter fleets.
- Military Fleet Operators:Classified-system protection mandates during idle periods create compliance barriers civilian providers struggle to cross. National defense aviation authorities impose documentation layers beyond FAA or EASA requirements.
- Private Jet Owners:Individual asset preservation with personalized service expectations. This fragmented segment resists standardization and prefers boutique facility relationships.
- Charter Services:Irregular utilization patterns requiring flexible short-term storage arrangements. Regional operators in California and Florida dominate this price-sensitive category.
Commercial airlines contribute the largest revenue pool while leasing firms expand their procurement share most aggressively.
Application:
Margin profiles diverge sharply between compliance-mandated applications and discretionary optimization programs.
- Fleet Optimization:Strategic capacity reduction during demand downturns. United States network carriers deployed this approach extensively during post-pandemic restructuring.
- Seasonal Demand Management:Predictable cyclical parking aligned with tourism or freight patterns. European leisure carriers in Spain and Greece drive Mediterranean concentration.
- Regulatory Compliance:Mandatory preservation during airworthiness directive remediation or certification gaps. FAA tightening of prolonged parking standards has elevated service intensity requirements.
- Asset Life Extension:Preservation preceding heavy maintenance or freighter conversion decisions. Cargo operators in Germany and the Netherlands favor this application for aging widebody fleets.
- Emergency Backup:Contingency storage for operational disruption scenarios. Military and government fleet operators maintain these arrangements for surge readiness.
- Repair Preparation:Pre-maintenance preservation protecting airframes awaiting hangar availability. Supply chain constraints on MRO slots have lengthened these holding periods.
Regulatory compliance commands the deepest margins while fleet optimization shows the most cyclical volatility.
Technology:
Digital infrastructure investments are separating technology-forward providers from legacy facility operators.
- Corrosion Control:Chemical compound application and monitoring protocols. REACH authorization restrictions in Europe are forcing reformulation investments and extended compatibility testing cycles.
- Protective Coatings:Specialized barrier applications for engine intakes, exhausts, and flight control surfaces. Japanese chemical suppliers concentrate supply for aerospace-grade formulations.
- Climate-Controlled Hangars:Active environmental management infrastructure. Arid climate facilities in Arizona achieve natural humidity suppression that coastal competitors must replicate through energy-intensive systems.
- Monitoring Systems:Sensor networks tracking humidity, temperature, and airframe condition. Major lessors now require these verification layers before accepting returned aircraft.
- Automated Preservation:Robotic application systems for corrosion inhibitors and protective films. Capital requirements limit deployment to high-volume facilities.
- Engine Preservation:Specialized protocols including desiccant installation, periodic rotation, and run-up procedures. Military specifications exceed commercial standards for classified powerplant protection.
Climate-controlled hangars represent the largest installed base while monitoring systems attract the fastest capital deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Leasing firms headquartered in Dublin and Singapore concentrate procurement authority for preservation contracts, while desert climate facilities in the southwestern United States absorb the deepest volume of long-term storage demand. Military fleet operators in Israel and France impose classified-system protection mandates that civilian providers struggle to satisfy.
United States
Legacy network carriers facing cyclical fleet adjustments drive structural demand for multi-year preservation contracts that maintain FAA airworthiness certification continuity. The FAA's tightening airworthiness directive framework for prolonged parking forces facility upgrades across Arizona and California desert sites. Marana Pinal Airpark and Victorville Southern California Logistics Airport anchor North American long-term storage capacity with natural humidity suppression below critical thresholds.
Germany
Cargo operators managing aging widebody freighter fleets generate preservation demand preceding heavy maintenance or conversion decisions. REACH chemical authorization protocols restrict traditional corrosion-inhibiting compound formulations, forcing reformulation investments and extended compatibility testing cycles. Frankfurt and Hamburg industrial clusters concentrate MRO-adjacent storage infrastructure serving Central European leasing firm portfolios.
France
Military fleet operators impose national defense aviation authority mandates for classified-system protection during idle periods, creating compliance barriers civilian providers cannot easily cross. EASA Part-M documentation requirements shape European preservation protocols and corrosion-control intervention record-keeping. Tarbes-Lourdes-Pyrénées Airport hosts TARMAC Aerosave's multi-site operations serving short-term and long-term service tiers across the continent.
India
Expanding leased aircraft fleets and humid coastal climates create structural need for professional preservation infrastructure currently served by ad hoc arrangements. The Directorate General of Civil Aviation (DGCA) maintains airworthiness oversight for parked aircraft without equivalent FAA-style prolonged parking directives. Mumbai and Delhi aviation clusters face capacity constraints as e-commerce logistics expansion generates new preservation requirements for converted freighter fleets.
Singapore
Major lessor headquarters drive contract standardization and mandate blockchain-based documentation systems before accepting returned aircraft. The Civil Aviation Authority of Singapore (CAAS) aligns with EASA-influenced preservation protocols for regional fleet management. Seletar Aerospace Park concentrates Asia-Pacific leasing firm procurement authority, displacing airline-controlled preservation sourcing.
Aircraft Storage, Preservation and Reactivation Services Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a market structure that concentrates around desert climate facility operators and European multi-site networks. Tiered competitive positioning separates scale-driven preservation providers from boutique military-specialist operators. Strategic archetypes include full-service desert facility operators, European multi-site preservation networks, and military-cleared reactivation specialists. Dominant competitive moves encompass facility monitoring system upgrades to satisfy tightening FAA documentation requirements and strategic partnerships with specialty chemical firms navigating REACH reformulation mandates.
Within the full-service preservation tier, TARMAC Aerosave leverages its European multi-site footprint to sustain positioning across service tiers, while Ascent Aviation Services anchors market presence through southwestern United States military and commercial capabilities. Asia Pacific Aircraft Storage occupies a position serving regional humid climate demand, and AAR exemplifies the diversified aviation services conglomerate archetype with integrated MRO-adjacent storage offerings.
| Leading Market Players |
|---|
| TARMAC Aerosave |
| Ascent Aviation Services |
| Asia Pacific Aircraft Storage |
| ecube |
| Vallair |
| AAR |
| Jet Aviation |
| FL Technics |
| AMROS Global |
| Others |
Pricing and Supply Chain Analysis
German and Japanese chemical suppliers concentrate corrosion-inhibiting compound production, anchoring margin pools in long-term preservation contracts where material costs dominate operational economics. This upstream concentration forces downstream providers to absorb price volatility or pass through via indexation clauses, reshaping contract structures across Arizona desert facilities and European multi-site networks.
Pricing Analysis
Cost-plus contracts with labor and chemical indexation dominate long-term preservation agreements, particularly for leasing firm portfolios requiring multi-year airworthiness continuity. Price differentiation rests on technician certification tiers and digital documentation capabilities, with FAA-compliant providers commanding premiums over baseline storage operators. Pricing pressure intensifies as REACH-mandated compound reformulations extend compatibility testing cycles. Regional charter services in California and Florida exhibit highest price sensitivity, while Dublin-headquartered lessors prioritize verification systems over rate minimization.
Supply Chain Analysis
Upstream feedstock supply for corrosion inhibitors concentrates in Germany, Japan, and specialized U.S. Gulf Coast chemical processors, creating geographic vulnerability to REACH authorization delays and trans-Pacific logistics constraints. Key inputs span aerospace-grade desiccants, humidity control equipment, and proprietary compound formulations. Single-source vulnerability runs through Japanese suppliers of protective coating polymers. Distribution feeds from manufacturer-direct relationships into facility-level procurement at Arizona and California desert sites, with European networks maintaining regional chemical blending partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across service tiers and geographic coverage creates niche opportunities as lessor procurement authority disintermediates airline-controlled sourcing. Digital documentation mandates and military compliance barriers prevent pure commoditization, preserving margin pools for differentiated positioning.
For Market Incumbents: Entrench positioning through backward integration into corrosion compound formulation partnerships, particularly for REACH-compliant European operations. Expand monitoring system deployment across Arizona and California facilities to capture lessor-mandated verification revenue. Counter emerging military-cleared specialists by accelerating FAA documentation protocol investments that compress reactivation cycle times. For New Entrants and Emerging Players: Establish a beachhead in India's humid coastal preservation infrastructure, where leased fleet expansion outpaces professional facility supply. Target cargo operator seasonal demand management in Mediterranean leisure carrier hubs as the most penetrable application segment. Lead with climate-controlled hangar construction partnerships rather than competing on reactivation labor intensity. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European multi-site preservation networks facing REACH compliance capital calls. Five-to-ten year viability hinges on digital twin integration capabilities separating legacy facility operators from technology-forward competitors. Monitor FAA airworthiness directive tightening velocity as the signal for reactivation service demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Platform Deployment | Enables remote airframe condition monitoring that reduces manual inspection frequency for lessor clients. |
| REACH-Compliant Compound Partnership | Secures reformulated corrosion inhibitor supply chains for European preservation contract continuity. |
| Military Clearance Acquisition | Opens classified-system protection contracts with French and Israeli defense aviation authorities. |
| Desert Climate Facility Expansion | Leverages Arizona and California humidity suppression to reduce active climate control energy costs. |
| Blockchain Documentation Integration | Satisfies Dublin and Singapore lessor mandates for immutable humidity and treatment records. |
Research Methodology
Two parallel data streams informed the analysis: primary engagement with preservation facility operators, leasing firm asset managers, and FAA compliance officers; and secondary validation through EASA Part-M regulatory filings, FAA airworthiness directive archives, and customs records tracking corrosion compound import flows. Bottom-up triangulation against top-down facility capacity estimates anchored volume and value projections.
Forecast inputs considered service type velocity, end-user procurement authority shifts, and technology adoption curves across the projection horizon. Segmentation dimensions spanned preservation duration tiers, end-user regulatory exposure, and digital infrastructure maturity. CAGRs derived from facility utilization rates, contract pricing trajectories, and capital deployment patterns observed across Arizona desert sites and European multi-site networks.
Sensitivities concentrate around FAA directive implementation timelines, REACH chemical authorization delays, and lessor documentation mandate adoption rates. Cross-checking against FAA aircraft registration and parking duration databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Maintenance and MRO Solutions
Africa Aviation MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Line Maintenance Market
Aircraft Maintenance and MRO Solutions
Airline Maintenance Software Market
Aircraft Maintenance and MRO Solutions
MRO Protective Coatings Market
Aircraft Maintenance and MRO Solutions
Digital Aerospace MRO Market
Aircraft Maintenance and MRO Solutions
Middle-East Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Distributed Electric Propulsion System MRO Services Market
Aircraft Maintenance and MRO Solutions
Air Transport MRO Market
Aircraft Maintenance and MRO Solutions
North America Aerospace Maintenance Chemical Market
Aircraft Maintenance and MRO Solutions
Aircraft Weighing Scales Market
Aircraft Maintenance and MRO Solutions
Aircraft Recycling Market
Aircraft Maintenance and MRO Solutions
On-Premises MRO Software Market
Aircraft Maintenance and MRO Solutions
Global Aircraft Engine MRO Market
Aircraft Maintenance and MRO Solutions
MRO Software Market
Aircraft Maintenance and MRO Solutions
Aircraft Buffing Wheel Market
Aircraft Maintenance and MRO Solutions
Asia-Pacific Aircraft MRO Market