
 Southeast Asia Aircraft MRO Market | 2026-2036
Southeast Asia Aircraft MRO Market Size, Share, and Industry Trends Forecast 2026-2036
Southeast Asia Aircraft MRO Market Analytics
Indonesian third-party MRO providers is repositioning to capture narrow-body overhaul volume as Garuda Indonesia and Lion Air expand leased fleets. GMF AeroAsia leverages its Jakarta facility to anchor engine overhaul capacity for CFM56 and LEAP powerplants. ST Engineering Aerospace sustains multi-site operations across Singapore and Vietnam, competing on integrated airframe-component service bundles. SIA Engineering Company differentiates through predictive analytics partnerships, positioning its digital platform as a regional maintenance planning standard.
Southeast Asia Aircraft MRO encompasses the inspection, repair, overhaul, and modification of airframes, engines, and components to maintain airworthiness compliance under ICAO Annex 8 standards, typically requiring C-check intervals at 3,000-6,000 flight hours and engine shop visits at 15,000-25,000 cycles. Engine Overhaul commands the largest value share due to module replacement costs and specialized tooling requirements, while Line Maintenance generates the highest transaction frequency driven by daily transit checks at hub airports. Component Repair concentrates margin pools in avionics and landing gear subsystems where OEM technical data licensing creates supply-side barriers.
CAAS in Singapore and CAAM in Malaysia enforce EASA-aligned Part 145 maintenance organization approvals, while Indonesia's DGCA implements ICAO-compliant airworthiness directives that shape foreign MRO market access requirements. The EU AI Act's emerging classification of predictive maintenance algorithms as high-risk AI systems will force Southeast Asian MROs serving EU-registered lessors to recertify diagnostic software workflows. Stakeholders must monitor regulatory divergence between ASEAN national aviation authorities as bilateral recognition agreements determine cross-border maintenance outsourcing eligibility.
Market Dynamics
Leased narrow-body fleet expansion across Indonesia and Vietnam is compressing maintenance turnaround windows, forcing third-party MRO providers to reconfigure hangar scheduling systems and workforce deployment models around higher-frequency C-check cycles.
Growth Catalysts
- EASA-aligned Part 145 standards:CAAS Singapore and CAAM Malaysia adoption tightens documentation requirements, elevating compliant providers above uncertified competitors in lessor qualification processes.
- CFM56/LEAP engine density:Narrow-body fleet concentration in the Jakarta-Surabaya corridor generates predictable shop visit demand for module replacement and life-limited part management.
- Low-cost carrier utilization rates:Indonesian and Vietnamese budget airlines push airframe cycles above OEM baseline assumptions, accelerating wear-component replacement schedules.
Market Restraints
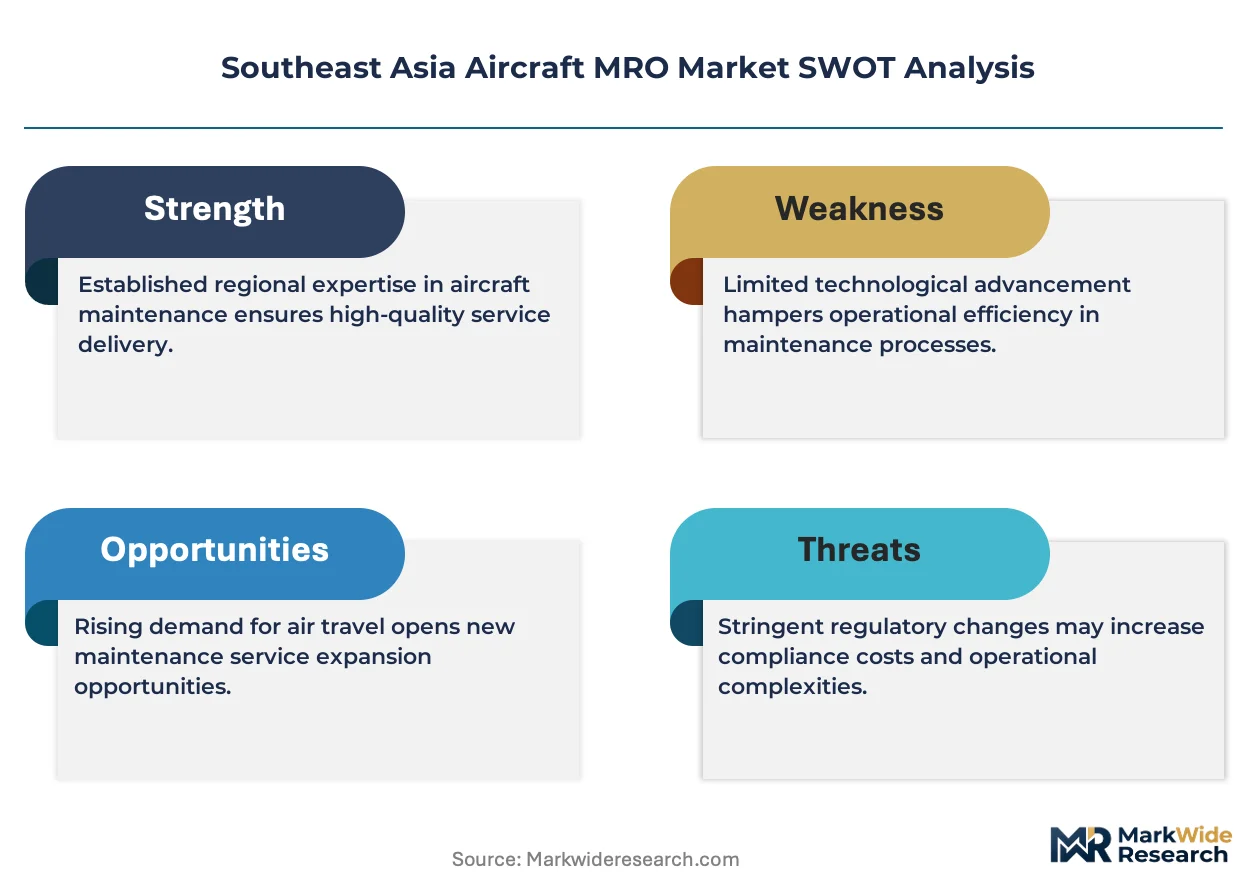
- OEM technical data licensing:Airbus and Boeing proprietary repair schemes restrict independent MRO access to structural composite repair instructions, limiting component repair margin capture.
- Specialized tooling capital intensity:Engine overhaul cell configuration requires multi-million dollar investment in borescope inspection rigs and blade grinding equipment, concentrating capability at established facilities.
- Skilled technician pipeline constraints:Indonesian DGCA-licensed airframe and powerplant mechanics face competing demand from Middle Eastern carriers offering tax-free compensation packages.
Strategic Opportunities
- Vietnamese MRO infrastructure gaps:Noi Bai and Tan Son Nhat airport capacity constraints create first-mover advantage for greenfield heavy maintenance facilities serving narrow-body lessors.
- Predictive maintenance algorithm deployment:EU AI Act high-risk classification requirements will force diagnostic software recertification, favoring MROs with established data science partnerships.
- Component repair specialization:Landing gear and avionics subsystems offer margin concentration where OEM licensing barriers limit competitive entry.
Industry Challenges
- Airworthiness directive compliance velocity:Indonesian DGCA and Singapore CAAS issue overlapping mandatory inspection bulletins, requiring fleet management systems to reconcile divergent implementation timelines.
- Legacy paper record digitization:Historical maintenance logbooks from pre-2010 aircraft transfers resist automated ingestion, forcing manual transcription for blockchain-traceable lessor handbacks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Southeast Asia Aircraft MRO Market |
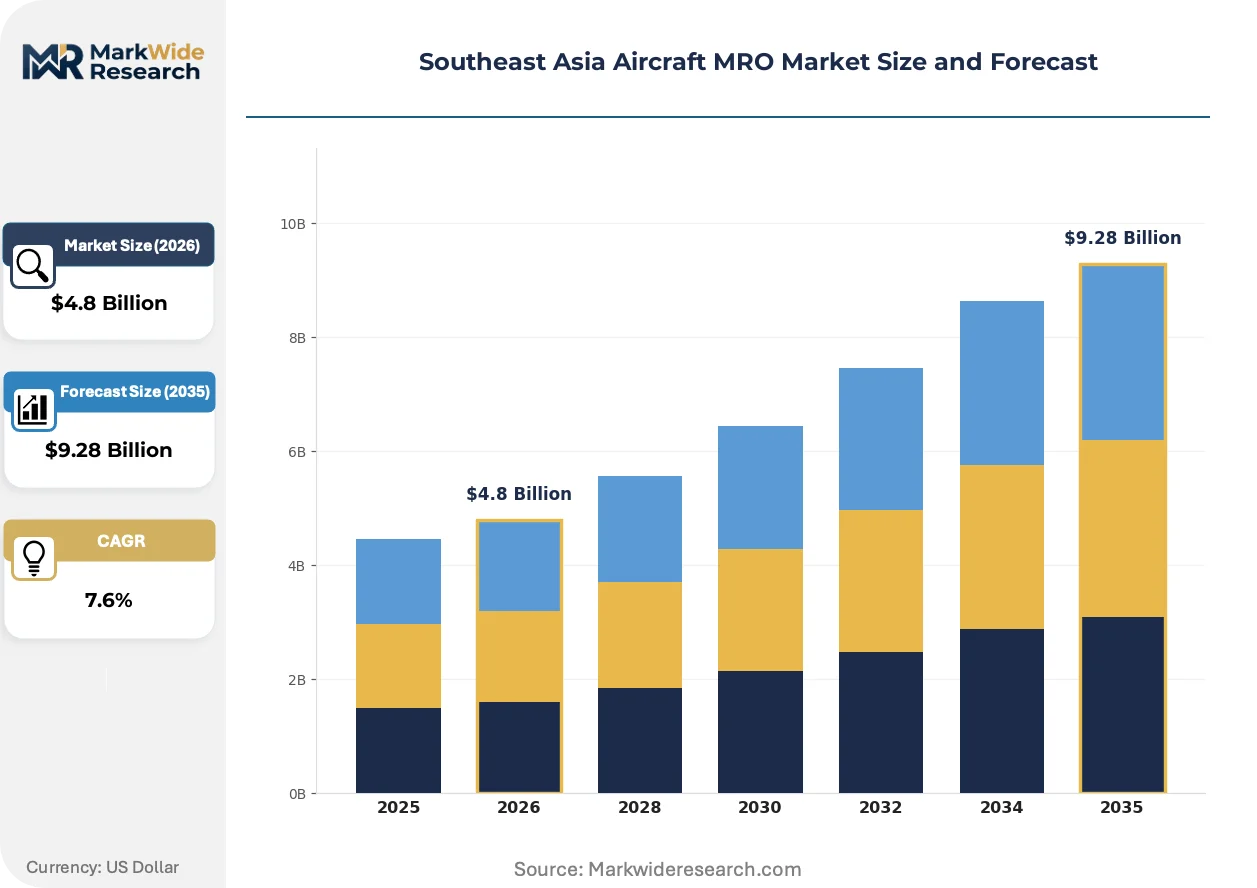
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Airframe Maintenance, Engine Overhaul, Component Repair, Line Maintenance Aircraft Type: Commercial Jets, Regional Aircraft, Cargo Planes, Helicopters End User: Airline Operators, Government Agencies, Charter Services, MRO Providers Technology: AI Maintenance Tools, Predictive Analytics, IoT Sensors, Modular Systems |
| Companies Covered | Sepang Aircraft Engineering, Aplus, GMF AeroAsia, Asia Digital Engineering, VAECO, ST Engineering Aerospace, Thai Airways Technical, SR Technics Malaysia, SIA Engineering Company, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Southeast Asia Aircraft MRO Market Evolving Landscape
Digital thread technologies are compressing maintenance planning cycles across Southeast Asian hub operations, replacing reactive scheduling with continuous airworthiness monitoring that anticipates component degradation before failure thresholds.
Electrified ground support equipment is electrifying apron operations at Changi and Kuala Lumpur International, replacing diesel-powered tugs and air conditioning carts with battery-electric alternatives. Ground handling contractors at Singapore Airlines and AirAsia hubs face CAAS-mandated emissions reduction timelines that accelerate fleet conversion. This infrastructure shift is electrifying line maintenance cost structures, forcing MROs to recalculate energy pricing into turnaround bids.
EU AI Act high-risk system classification is tightening algorithm governance requirements for predictive maintenance platforms serving EU-registered lessors. Southeast Asian MROs deploying machine learning for engine health monitoring must now document training data provenance and human oversight protocols. Malaysian CAAM and Singapore CAAS are evaluating reciprocal recognition frameworks that would streamline cross-border software certification.
Power-by-the-hour contracts are displacing traditional time-and-material billing among Indonesian and Vietnamese low-cost carriers seeking to cap maintenance cost volatility. Lessors including AerCap and SMBC Aviation Capital now require bundled airframe-engine-component coverage as a condition of lease placement. This procurement compression is visible most acutely in Jakarta, where Garuda Maintenance Facility and third-party competitors restructure service menus around fixed-rate availability guarantees.
Southeast Asia Aircraft MRO Market Segmentation
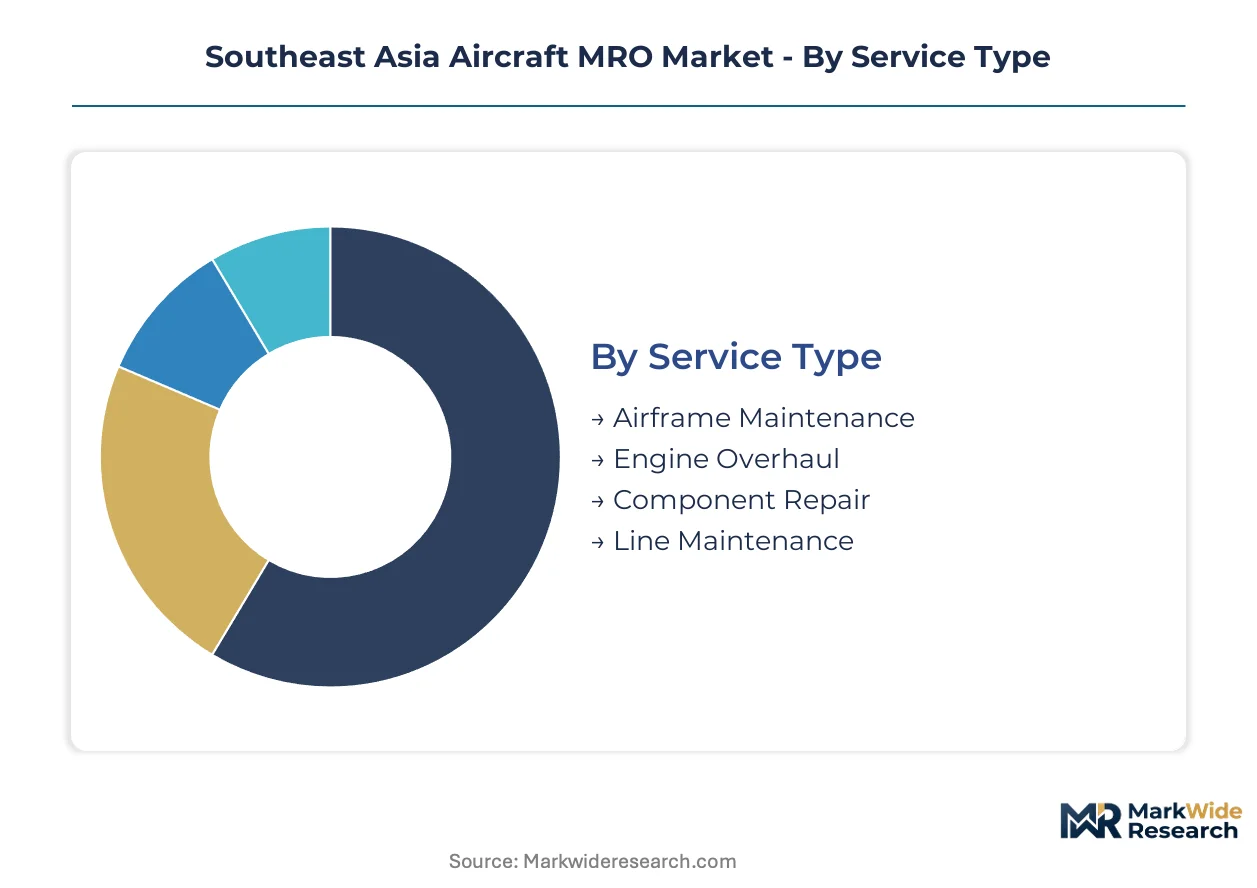
Segmentation reveals how maintenance value pools concentrate across service tiers, aircraft platforms, and technology interfaces in Southeast Asia's fragmented regulatory landscape. Each axis exposes distinct margin structures and capability barriers that determine competitive positioning for third-party providers and airline-captive facilities alike.
Service Type:
Technical complexity and capital intensity separate line maintenance from heavy overhaul, with specialized tooling requirements creating tiered entry barriers across the service spectrum.
- Engine Overhaul:Module replacement and life-limited part management demand borescope inspection rigs and blade grinding equipment costing several million dollars per cell. CFM56 and LEAP powerplant density in Indonesia's Jakarta-Surabaya corridor generates predictable shop visit demand from Lion Air and Garuda Indonesia leased fleets.
- Line Maintenance:Daily transit checks and turnaround inspections at Changi, Soekarno-Hatta, and Tan Son Nhat airports produce the highest transaction frequency with compressed scheduling windows. Low-cost carrier utilization rates above OEM baseline assumptions accelerate wear-component replacement cycles across narrow-body fleets.
- Airframe Maintenance:C-check intervals at 3,000-6,000 flight hours require hangar slots and structural repair stations compliant with EASA-aligned Part 145 standards.
- Component Repair:Avionics and landing gear subsystems concentrate margin pools where OEM technical data licensing restricts independent provider access.
Engine Overhaul leads on scale; Line Maintenance leads on momentum.
Aircraft Type:
Operational intensity and lease structure variation across platform categories determine maintenance procurement patterns and third-party service penetration.
- Commercial Jets:Narrow-body fleet expansion across Indonesia and Vietnam compresses turnaround windows, forcing hangar reconfiguration around higher-frequency C-check cycles. Power-by-the-hour contracts now dominate procurement among budget carriers seeking fixed-rate availability guarantees.
- Regional Aircraft:Turboprop operations serving secondary Indonesian and Philippine island routes generate distributed maintenance demand outside primary hub infrastructure. ATR and Bombardier fleets require specialized propeller and landing gear capabilities absent from many third-party facilities.
- Cargo Planes:Freighter conversion programs and e-commerce-driven night operations create distinct airworthiness documentation requirements under ICAO Annex 8.
- Helicopters:Offshore oil and gas support in Malaysian and Indonesian waters drives rotorcraft MRO demand with specialized component traceability protocols.
Commercial Jets command the largest value pool; Regional Aircraft show the steepest expansion trajectory as connectivity programs penetrate secondary markets.
End User:
Procurement sophistication and regulatory compliance burden diverge sharply between airline-captive operations and outsourced service relationships.
- Airline Operators:Garuda Indonesia and Lion Air captive facilities compete with third-party providers for narrow-body overhaul volume, while Singapore Airlines subsidiaries leverage predictive analytics partnerships. Power-by-the-hour contract adoption is displacing traditional time-and-material billing among cost-sensitive carriers.
- MRO Providers:ST Engineering Aerospace and GMF AeroAsia compete on integrated airframe-component bundles, with EASA-aligned Part 145 approvals from CAAS and CAAM serving as lessor qualification filters. Independent providers face OEM technical data licensing barriers in structural composite repair.
- Government Agencies:Military and coast guard fleets operate under separate airworthiness frameworks with classified maintenance documentation requirements.
- Charter Services:Business aviation and VIP transport demand flexible scheduling with premium turnaround guarantees at secondary airports.
Airline Operators anchor procurement volume; MRO Providers capture the fastest share gains as outsourcing accelerates.
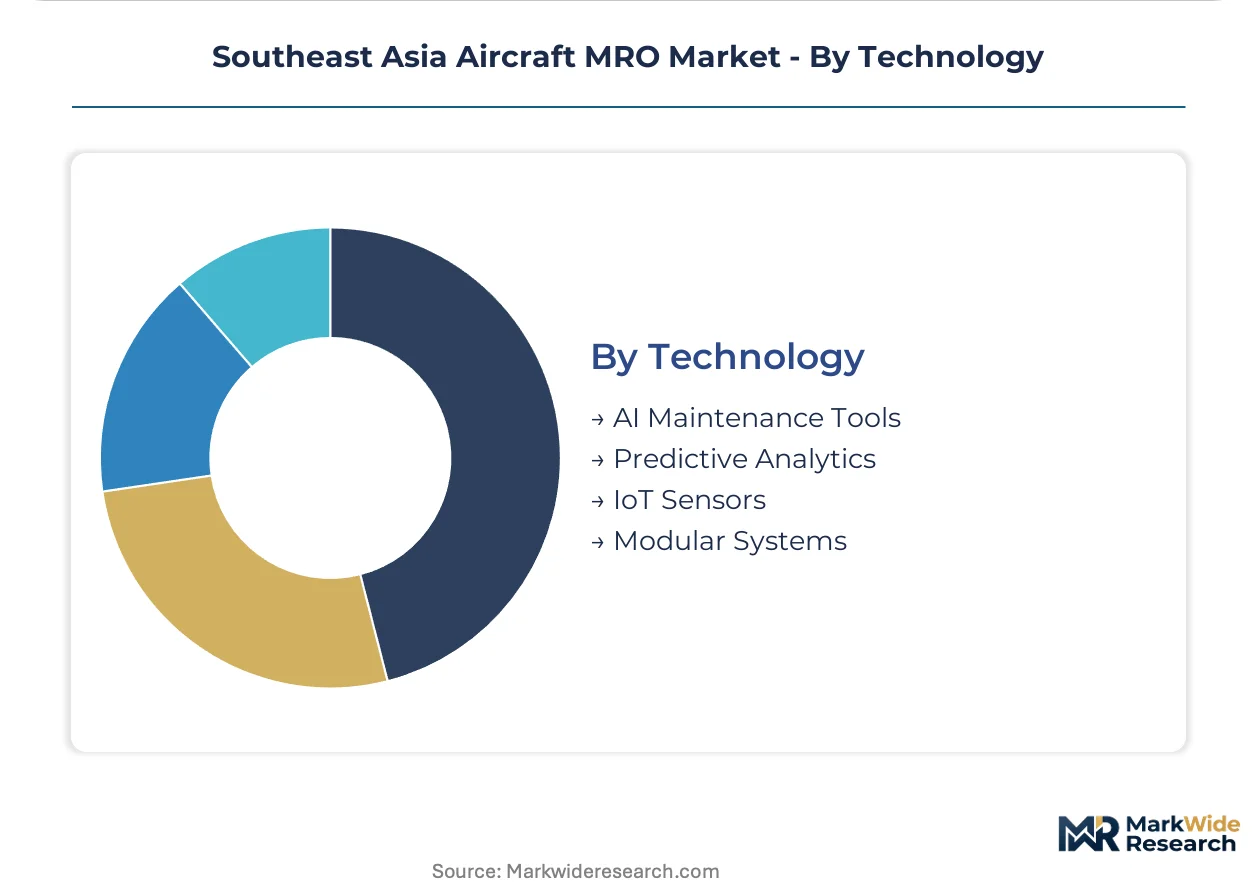
Technology:
Digital infrastructure investment separates predictive-capable facilities from reactive maintenance operations, with regulatory compliance emerging as a competitive differentiator.
- Predictive Analytics:Machine learning platforms for engine health monitoring now require documented training data provenance and human oversight protocols under EU AI Act high-risk system classification. SIA Engineering Company positions its digital platform as a regional maintenance planning standard through data science partnerships.
- IoT Sensors:Continuous airworthiness monitoring systems compress maintenance planning cycles by anticipating component degradation before failure thresholds. Sensor deployment on CFM56 and LEAP powerplants generates real-time performance data streams for fleet management optimization.
- AI Maintenance Tools:Diagnostic software recertification requirements favor MROs with established algorithm governance frameworks serving EU-registered lessors.
- Modular Systems:Swappable component architectures reduce aircraft-on-ground time but require expanded spare parts pools and logistics coordination.
Predictive Analytics leads on technology investment intensity; IoT Sensors gain traction fastest as hardware deployment costs decline.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost differentials between Singapore's CAAS and Indonesia's DGCA are redirecting narrow-body overhaul volume toward Jakarta-Surabaya corridor facilities. EASA-aligned Part 145 compliance costs in Singapore and Malaysia concentrate premium engine work at established hubs while pushing line maintenance toward lower-cost Indonesian operations.
Indonesia
Lion Air and Garuda Indonesia leased fleet expansions drive narrow-body C-check demand at Soekarno-Hatta International Airport. DGCA enforces ICAO-compliant airworthiness directives with documentation standards tightening for lessor handback compliance. GMF AeroAsia anchors engine overhaul capacity for CFM56 and LEAP powerplants from its Jakarta facility.
Singapore
Changi Airport's transit traffic generates highest-frequency line maintenance transactions with compressed turnaround windows. CAAS Part 145 approvals serve as lessor qualification filters elevating compliant providers above regional competitors. SIA Engineering Company positions predictive analytics partnerships from its digital platform hub at Seletar Aerospace Park.
Malaysia
CAAM adoption of EASA-aligned maintenance organization approvals tightens documentation requirements for foreign MRO market access. Sepang Aircraft Engineering and SR Technics Malaysia compete on integrated airframe-component service bundles at Kuala Lumpur International Airport. Low-cost carrier utilization rates from AirAsia operations accelerate wear-component replacement schedules.
Vietnam
Noi Bai and Tan Son Nhat airport capacity constraints create infrastructure gaps for heavy maintenance facilities serving narrow-body lessors. VAECO captures domestic carrier volume while foreign providers pursue greenfield expansion approvals. Power-by-the-hour contract adoption among VietJet and Bamboo Airways restructures procurement toward fixed-rate availability guarantees.
Thailand
Thai Airways Technical maintains captive operations at Suvarnabhumi Airport with selective third-party commercialization of excess hangar capacity. Aplus and regional competitors target ASEAN cross-border maintenance outsourcing eligibility through bilateral recognition frameworks. Tourism recovery patterns reshape fleet utilization assumptions for maintenance planning cycles.
Southeast Asia Aircraft MRO Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue digital platform differentiation and predictive analytics integration. The market structures around three capability tiers: airline-captive facilities with guaranteed volume, independent third-party providers competing on EASA-aligned certification, and technology-forward operators investing in AI-enabled diagnostics. Competitive positioning hinges on Part 145 approval breadth, engine overhaul cell configuration, and lessor relationship depth. Dominant moves include hangar capacity expansion at Indonesian hubs and strategic data science partnerships for predictive maintenance algorithm deployment.
Within the airline-captive tier, GMF AeroAsia and Thai Airways Technical anchor narrow-body overhaul volume through fleet-integrated operations. ST Engineering Aerospace exemplifies the multi-site independent model with cross-border facility networks spanning Singapore and Vietnam. SIA Engineering Company occupies the technology-forward position, representing predictive analytics specialization serving EU-registered lessor compliance requirements under emerging AI Act governance frameworks.
| Leading Market Players |
|---|
| Sepang Aircraft Engineering |
| Aplus |
| GMF AeroAsia |
| Asia Digital Engineering |
| VAECO |
| ST Engineering Aerospace |
| Thai Airways Technical |
| SR Technics Malaysia |
| SIA Engineering Company |
| Others |
Value Network & Pricing Analysis
Sovereign-backed airline-captive facilities and private-equity-rolled-up third-party specialists anchor Southeast Asia's MRO supply base, concentrating pricing power at established hubs while compressing margins at independent providers competing for lessor qualification. This ownership fragmentation creates tiered procurement leverage, with EASA-aligned Part 145 certification serving as the primary filter for premium pricing access.
Pricing Analysis
Distributor margin capture in component repair subsystems concentrates value at avionics and landing gear specialists holding OEM technical data licenses. Power-by-the-hour contracts now dominate procurement among Indonesian and Vietnamese low-cost carriers, displacing transactional time-and-material billing with fixed-rate availability guarantees. Pricing pressure stems from leased fleet operators demanding bundled airframe-engine-component coverage as a lease placement condition. Charter services and business aviation segments exhibit lowest price sensitivity, prioritizing turnaround speed over unit cost.
Supply Chain Analysis
Regional distribution centers at Changi, Soekarno-Hatta, and Kuala Lumpur International anchor hub-and-spoke patterns for life-limited parts and replacement modules. Singapore, Malaysia, and Indonesia concentrate specialized tooling fabrication and borescope inspection equipment supply. The chain draws from aerospace-grade alloy suppliers in Japan and Germany, composite material specialists in the United States, and precision machining clusters in South Korea. Single-source vulnerability in CFM56 and LEAP engine module supply creates exposure to OEM production scheduling. Distribution runs through lessor-approved logistics networks with blockchain-traceable documentation for handback compliance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Southeast Asia's aircraft MRO market compounds steadily as narrow-body fleet utilization rates across Indonesia and Vietnam permanently elevate maintenance cycle frequency above OEM baseline assumptions.
For Market Incumbents: Deploy predictive analytics partnerships to differentiate diagnostic platforms ahead of EU AI Act high-risk system recertification requirements. Expand hangar capacity at Jakarta-Surabaya corridor facilities to capture narrow-body C-check volume from Lion Air and Garuda Indonesia leased fleet expansions. Consolidate component repair specialization in landing gear and avionics subsystems where OEM technical data licensing limits competitive entry. For New Entrants and Emerging Players: Digital-first maintenance planning platforms offer entry leverage into Vietnamese MRO infrastructure gaps at Noi Bai and Tan Son Nhat airports. Target greenfield heavy maintenance facility development serving narrow-body lessors seeking alternatives to capacity-constrained incumbent hubs. Pursue CAAM Malaysia Part 145 approval pathways to access EASA-aligned certification credibility in cross-border outsourcing arrangements. For Investors and Strategic Acquirers: Valuations sit cheapest among independent third-party providers lacking predictive analytics capabilities but holding established lessor relationships and hangar infrastructure. The five-to-ten-year viability window favors operators with demonstrated EU-registered lessor compliance and data science partnerships. Monitor CAAS-Singapore and CAAM-Malaysia bilateral recognition framework negotiations as signal for cross-border maintenance outsourcing eligibility expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Deployment | EU AI Act high-risk classification forces diagnostic software recertification favoring established data science partnerships. |
| Greenfield Heavy Maintenance Facility Development | Vietnamese infrastructure gaps at Noi Bai and Tan Son Nhat create first-mover advantage for narrow-body lessor servicing. |
| EASA-Aligned Part 145 Certification Investment | CAAS Singapore and CAAM Malaysia approvals serve as lessor qualification filters elevating compliant providers above competitors. |
| Component Repair Specialization | Landing gear and avionics subsystems concentrate margins where OEM technical data licensing restricts independent provider access. |
| Power-by-the-Hour Contract Restructuring | Indonesian and Vietnamese low-cost carriers now demand fixed-rate availability guarantees displacing transactional billing. |
Research Methodology
Bottom-up airline operator and MRO provider modeling reconciled against top-down fleet utilization and regulatory filing tracking forms the analytical core of this study. Primary interviews with maintenance planning executives, DGCA-licensed airframe and powerplant mechanics, lessor technical asset managers, and CAAS compliance officers combined with secondary validation from ICAO Annex 8 documentation, EASA Part 145 approval registries, and airline fleet expansion disclosures. Triangulation across these sources ensures segmentation integrity across service type, aircraft platform, and technology interface dimensions.
The input-output matrix framing connects CFM56 and LEAP engine shop visit frequency assumptions to narrow-body fleet density projections across the analysis window. Segmentation modeling spans service tier complexity, aircraft operational intensity, procurement sophistication, and digital infrastructure maturity. CAGRs derive from reconciling bottom-up maintenance event frequency against top-down fleet expansion trajectories. Industry-specific forecast inputs include power-by-the-hour contract penetration rates and EASA-aligned regulatory adoption timelines.
The model holds under stable bilateral recognition agreements between ASEAN national aviation authorities; deviation in EU AI Act implementation velocity or DGCA documentation standard tightening would shift predictive maintenance platform investment returns. Forecasts reflect stated assumptions on fleet utilization rates and lessor qualification criteria evolution. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Maintenance and MRO Solutions
Aircraft Exterior Strip and Repaint Services Market
Aircraft Maintenance and MRO Solutions
North America Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Tire Balancer Market
Aircraft Maintenance and MRO Solutions
Digital Aerospace MRO Market
Aircraft Maintenance and MRO Solutions
Gas Turbine MRO Market
Aircraft Maintenance and MRO Solutions
Global Aircraft Engine MRO Market
Aircraft Maintenance and MRO Solutions
Aviation Maintenance Repair and Overhaul MRO Software Market
Aircraft Maintenance and MRO Solutions
Latin America Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Regional Turboprop Engine MRO Services Market
Aircraft Maintenance and MRO Solutions
Africa Aviation MRO Market
Aircraft Maintenance and MRO Solutions
Military Aircraft Maintenance, Repair and Overhaul Market
Aircraft Maintenance and MRO Solutions
Helicopter MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Wheel Bead Breakers Market
Aircraft Maintenance and MRO Solutions
Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Military Aviation Repair Solutions Market
Aircraft Maintenance and MRO Solutions
Aircraft Weighing Scales Market