
 Aviation Maintenance Training Market | 2026-2036
Aviation Maintenance Training Market Size, Share, and Industry Trends Forecast 2026-2036
Aviation Maintenance Training Market Analysis
Subscription-based digital learning platforms is broadening what training providers sell beyond traditional classroom hours. CAE leverages its simulation technology leadership to anchor recurring revenue from airline partners seeking type-specific maintenance certification. Lufthansa Technical Training competes through its integrated training and MRO service bundling across European carrier networks.
Aviation maintenance training encompasses the structured instruction, competency assessment, and certification preparation required for technicians to perform airframe, powerplant, and avionics repairs under regulatory supervision. Programs blend theoretical coursework on turbine engine thermodynamics and composite material properties with hands-on practicum using full-motion flight simulators and actual aircraft components. Simulation-based delivery commands premium positioning as airlines prioritize reduced downtime and risk-mitigated skill transfer for next-generation aircraft platforms. E-learning modules targeting recurrent regulatory certification represent the fastest-expanding segment, though instructor-led programs retain margin concentration for initial type-rating and specialized troubleshooting credentials.
FAA Part 147 curriculum standards and EASA Part 66 licensing requirements shape training content, duration, and facility accreditation across the United States and European Union member states. The FAA mandates specific instructional hours and practical experience thresholds that directly determine program architecture and enrollment capacity. Stakeholders must monitor evolving battery-electric and hydrogen propulsion certification pathways as these technologies force curriculum redesign and instructor requalification cycles.
Market Dynamics
Fleet modernization cycles and propulsion technology transitions are compressing curriculum refresh timelines for aviation maintenance training providers, forcing simultaneous investment in simulation infrastructure and instructor requalification.
Growth Catalysts
- Next-generation aircraft penetration:Airlines operating Boeing 787 and Airbus A350 platforms require type-specific composite repair and avionics troubleshooting credentials, expanding enrollment in advanced simulation programs.
- EASA Part 66 mandate expansion:The European Union's recurrent certification requirements for licensed aircraft maintenance engineers sustain steady demand for refresher modules and examination services.
- Battery-electric propulsion pilots:Regional carriers testing hybrid-electric commuter aircraft are commissioning specialized high-voltage systems training ahead of regulatory framework finalization.
Market Restraints
- Simulator hardware cost inflation:Full-motion flight training devices with maintenance-specific fault insertion capabilities require capital outlays exceeding fifteen million dollars per unit, constraining program expansion at mid-tier institutions.
- Certified instructor scarcity:The pipeline of technicians holding both airframe credentials and instructional qualifications has tightened across Germany, France, and the United Kingdom.
- FAA Part 147 accreditation timelines:New training facility approvals average eighteen to twenty-four months, limiting supply responsiveness to regional demand surges.
Strategic Opportunities
- India domestic aviation expansion:The Directorate General of Civil Aviation's projected technician shortage creates openings for joint venture training centers near Bengaluru and Hyderabad maintenance clusters.
- Hydrogen propulsion pre-certification:Cryogenic fuel system handling protocols for zero-emission aircraft represent uncaptured curriculum territory ahead of EASA rulemaking.
- Micro-credential stacking:Modular digital badges for specific component systems enable subscription revenue models and employer-customized learning pathways.
Industry Challenges
- Curriculum-hardware synchronization:Training providers must align simulation scenarios with proprietary aircraft health monitoring systems whose architectures vary by manufacturer and remain commercially sensitive.
- Multi-jurisdiction instructor licensing:Cross-border training delivery requires instructors to hold separate FAA, EASA, and national aviation authority certifications, complicating staffing flexibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aviation Maintenance Training Market |
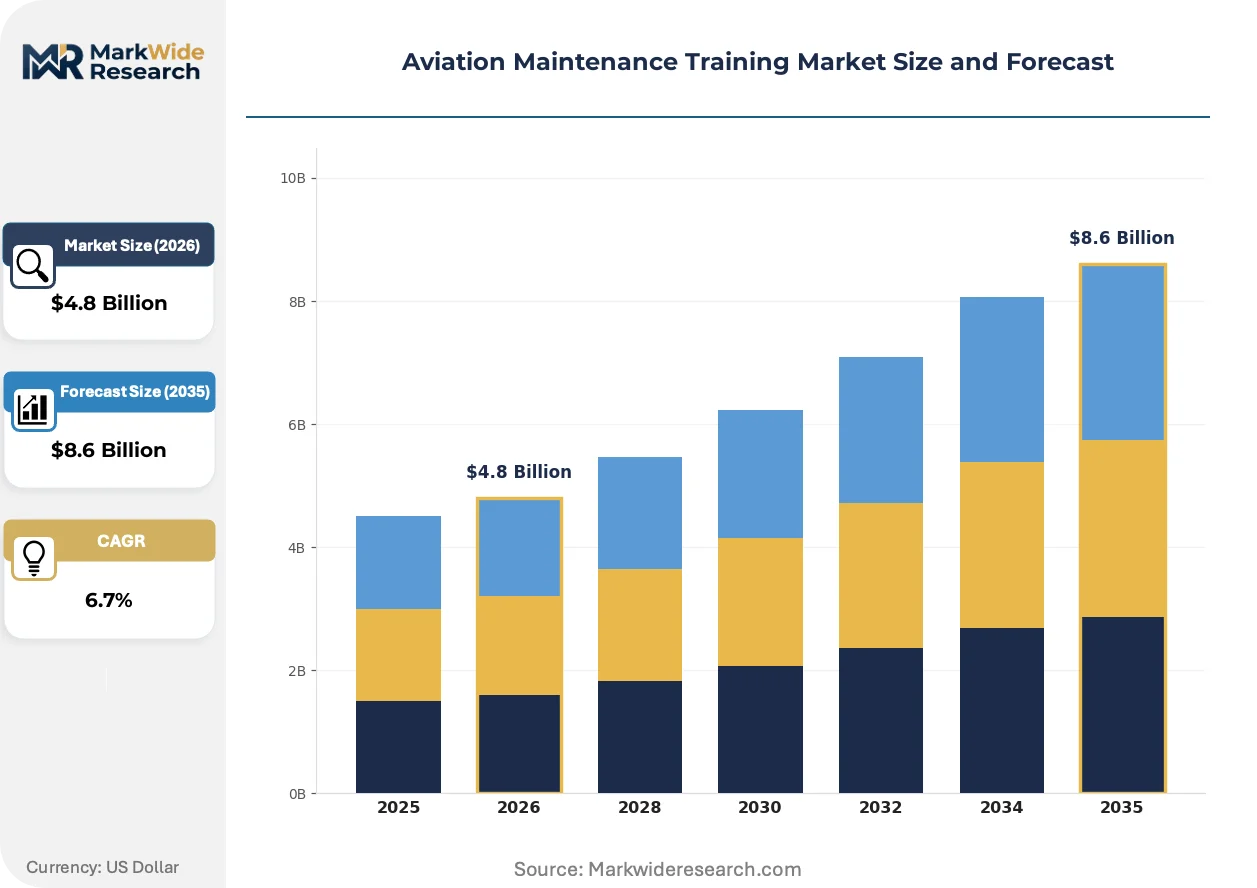
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Training Type: Classroom, Online, Hybrid, On-the-job Certification Level: Basic, Advanced, Specialized, Regulatory Delivery Method: Instructor-led, E-learning, Simulation-based, Self-paced Target Audience: Aviation Technicians, Engineers, Students, Professionals |
| Companies Covered | Hillsboro Aero Academy, Pan Am International Flight Academy, Aviation Institute of Maintenance, ST Engineering Aerospace, FL Technics, FEAM Aero, CAE, Lufthansa Technical Training, Diamond Aircraft Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aviation Maintenance Training Market Emerging Trajectories
Digital twin architectures and immersive reality systems are absorbing capital allocation previously directed toward physical training aircraft, compressing the cost-per-competency metric while expanding scenario complexity.
Extended reality headsets with haptic feedback gloves are absorbing tactile skill transfer for engine component removal and installation sequences. Major European MRO operators have deployed these systems for initial troubleshooting certification, reducing live aircraft access requirements by half. The technology is absorbing training hours previously reserved for hangar-based practicum, enabling faster cohort throughput without airframe availability constraints.
CSRD disclosure requirements are mandating documented training outcomes for maintenance workforce sustainability metrics. European airline sustainability reports must now quantify technician certification rates and competency retention, elevating training program visibility to board-level procurement decisions. MRO providers in the Netherlands and Scandinavia are responding with integrated learning management systems that automate compliance documentation.
Airline technical operations departments are consolidating vendor relationships around full-service training partners capable of delivering type-rating, recurrent, and specialized troubleshooting through unified platforms. This concentration is displacing fragmented procurement across multiple single-service providers. The shift is most pronounced among low-cost carriers in Spain and Ireland seeking operational simplicity and volume pricing leverage.
Aviation Maintenance Training Market Segmentation
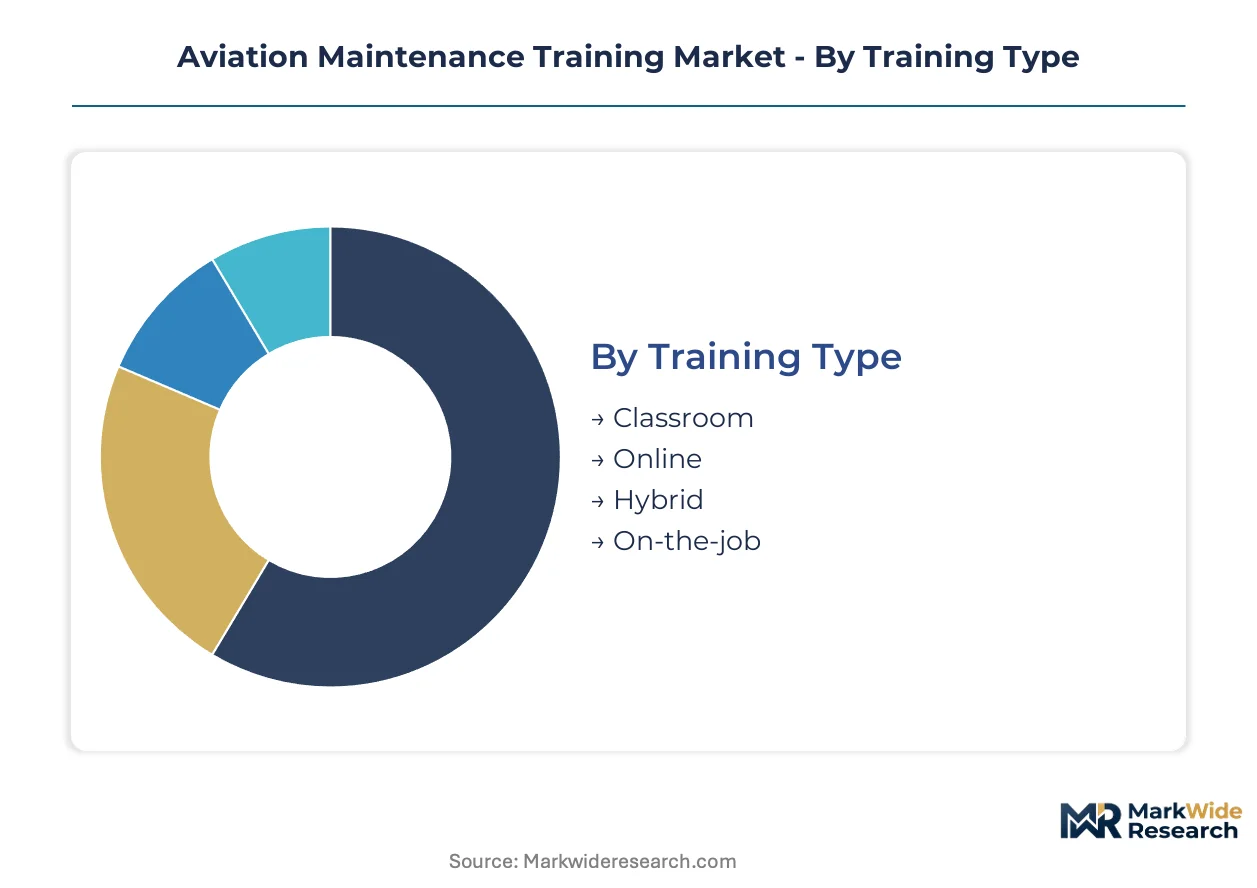
Segmentation in aviation maintenance training reveals how regulatory complexity and technology diffusion reshape procurement patterns across stakeholder groups. Training providers calibrate curriculum architecture, pricing tiers, and delivery infrastructure against distinct competency requirements and certification pathways.
Training Type:
Technology integration intensity varies sharply across instructional modalities, with capital deployment and margin structure diverging accordingly.
- Classroom:Instructor-facilitated group instruction in dedicated training facilities emphasizes theoretical foundations in airframe systems and turbine thermodynamics. Demand concentrates at FAA Part 147-accredited schools in Florida and Texas serving domestic airline technician pipelines, constrained by physical capacity limits and eighteen-month accreditation timelines for new facilities.
- Online:Asynchronous digital modules deliver regulatory refresher content and theoretical coursework through cloud-based learning management systems. European carriers under EASA Part 66 recurrent mandates in Germany and France are expanding enrollment fastest, driven by CSRD disclosure requirements mandating documented training outcomes for workforce sustainability metrics.
- Hybrid:Blended curricula combine virtual theoretical instruction with scheduled hands-on practicum sessions. Regional MRO clusters in Arizona leverage this format to balance cost efficiency with practical competency verification.
- On-the-job:Supervised workplace instruction pairs apprentices with certified technicians during live maintenance operations. Airlines in India deploy this approach to address DGCA-projected technician shortages near Bengaluru maintenance hubs.
Mature deployment sits with Classroom programs at established Part 147 institutions. Newer deployment is concentrated in Online modules responding to recurrent certification automation.
Certification Level:
Credential tier determines curriculum duration, examination rigor, and instructor qualification thresholds.
- Basic:Entry-level airframe and powerplant fundamentals prepare candidates for initial FAA or EASA mechanic certification. Community college programs in Texas anchor volume here.
- Advanced:Type-specific ratings for Boeing 787 composite repair and Airbus A350 avionics troubleshooting command premium positioning. Airlines in Ireland and Spain prioritize these credentials for fleet modernization, with simulation-based delivery absorbing capital previously directed toward physical training aircraft.
- Specialized:Narrow competencies in high-voltage battery-electric systems and cryogenic hydrogen handling address emerging propulsion technologies. Regional carriers in Scandinavia commission this training ahead of EASA rulemaking finalization.
- Regulatory:Recurrent examination services and compliance documentation modules sustain steady demand. EASA Part 66 mandate expansion across European Union member states accelerates enrollment in automated refresher platforms.
Revenue concentration weights toward Advanced credentials for type-rating procurement. Steepest expansion trajectory belongs to Specialized tiers addressing propulsion technology transitions.
Delivery Method:
Capital intensity and scalability trade-offs differentiate procurement preferences across airline technical operations departments.
- Instructor-led:Synchronous facilitation by certified aviation maintenance instructors supports complex troubleshooting scenarios and examination preparation. Premium margins concentrate here for initial certification pathways.
- E-learning:Self-directed digital content with automated assessment enables subscription revenue models and employer-customized learning pathways. Low-cost carriers in Spain consolidate vendor relationships around unified platforms delivering this format.
- Simulation-based:Full-motion flight training devices with fault insertion capabilities replicate next-generation aircraft systems for risk-mitigated skill transfer. Hardware costs exceeding fifteen million dollars per unit constrain expansion at mid-tier institutions.
- Self-paced:Modular micro-credentials allow technicians to stack digital badges for specific component systems. Netherlands-based MRO operators deploy integrated learning management systems automating compliance documentation for this format.
Procurement gravity centers on Simulation-based delivery for type-specific troubleshooting. Volume scaling favors E-learning for recurrent regulatory modules.
Target Audience:
Career stage and employer type shape curriculum customization and pricing elasticity.
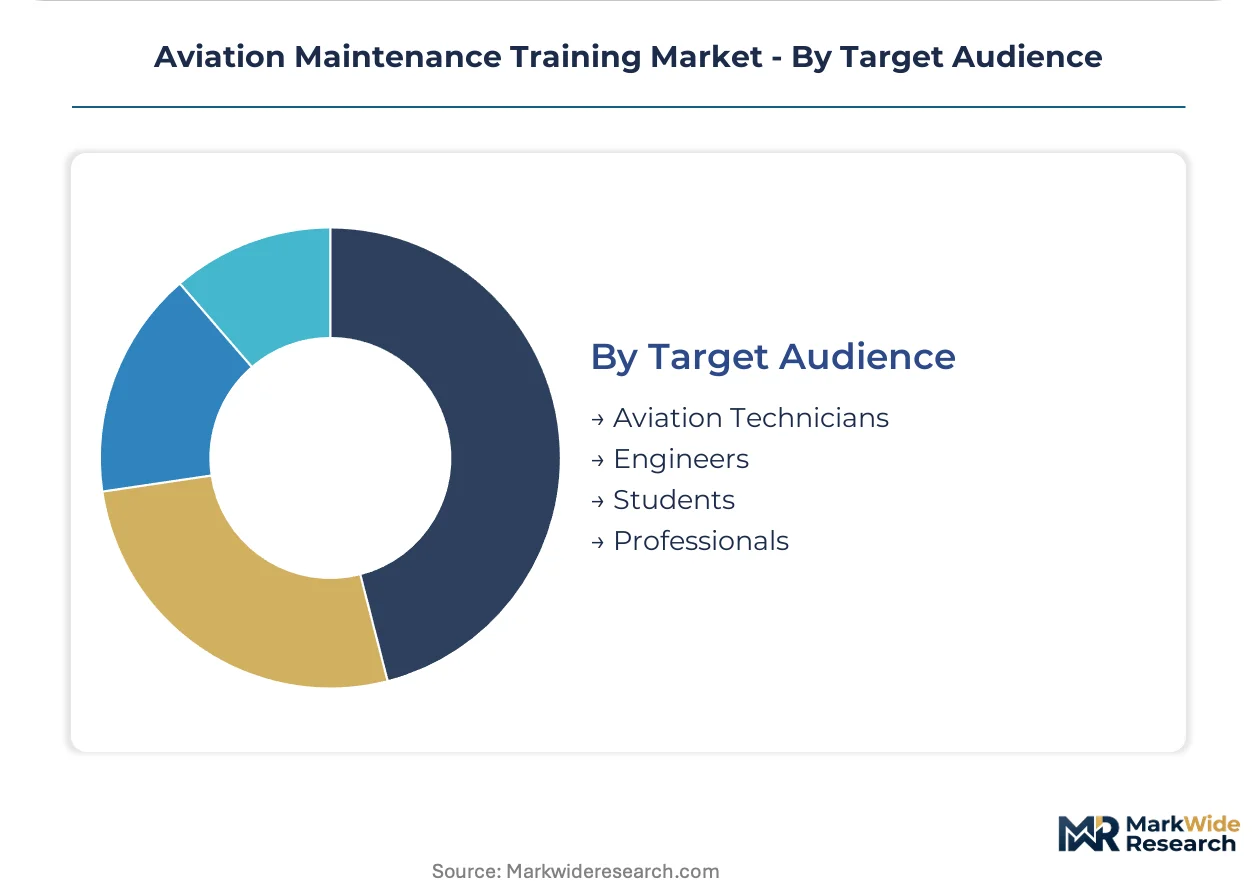
- Aviation Technicians:Licensed mechanics seeking recurrent certification or type-specific advancement represent core demand. FAA and EASA regulatory mandates directly determine enrollment patterns.
- Engineers:Design and systems integration specialists require advanced propulsion and avionics troubleshooting credentials. Battery-electric and hydrogen propulsion pilots in regional carrier networks drive emerging demand.
- Students:Pre-employment candidates at Part 147 schools and university aviation programs form the pipeline for technician labor markets. Enrollment correlates with fleet modernization cycles and projected retirements.
- Professionals:Cross-industry personnel transitioning into aviation maintenance require accelerated foundational programs. India's domestic aviation expansion creates openings for joint venture training centers serving this cohort.
Established volume resides with Aviation Technicians under recurrent mandates. Fastest audience expansion is concentrated in Engineers addressing propulsion technology transitions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Florida anchors global aviation maintenance training infrastructure, with Miami and Orlando metropolitan clusters hosting FAA Part 147-accredited schools that feed technician pipelines for domestic and international carriers. Fleet modernization programs at American Airlines and Delta Air Lines sustain enrollment in composite repair and avionics simulation curricula.
United States
Texas and Arizona training hubs absorb capital from airline technical operations departments consolidating vendor relationships around full-service partners. FAA Part 147 accreditation timelines averaging eighteen to twenty-four months constrain new facility expansion despite technician shortage projections. Dallas-Fort Worth and Phoenix maintenance corridors concentrate hybrid delivery programs blending virtual instruction with hands-on practicum.
Germany
EASA Part 66 recurrent certification mandates sustain steady demand for refresher modules and examination services across Lufthansa Group and Eurowings maintenance networks. The country's national aviation regulator enforces licensing requirements that directly determine program architecture and instructor qualification thresholds. Hamburg and Munich MRO clusters deploy integrated learning management systems automating CSRD compliance documentation for workforce sustainability metrics.
United Kingdom
Certified instructor scarcity has tightened across England and Scotland as technicians holding both airframe credentials and instructional qualifications retire. The Civil Aviation Authority maintains alignment with EASA standards post-Brexit while preserving grandfathered certification pathways. London Gatwick and Manchester maintenance bases commission specialized troubleshooting credentials for next-generation Airbus A350 and Boeing 787 platforms.
India
The Directorate General of Civil Aviation projects acute technician shortages as domestic aviation expansion accelerates fleet induction. Joint venture training centers near Bengaluru and Hyderabad maintenance clusters address pipeline gaps through on-the-job apprenticeship models pairing candidates with certified technicians. Regional carriers testing hybrid-electric commuter aircraft are commissioning high-voltage systems training ahead of regulatory framework finalization.
France
Air France-KLM technical operations prioritize type-specific simulation programs for composite repair certification on new-generation aircraft. The country's national aviation regulator enforces EASA Part 66 standards while coordinating with industry on battery-electric propulsion curriculum pre-certification. Toulouse and Paris-Charles de Gaulle maintenance zones concentrate advanced troubleshooting instruction for avionics systems integration.
Aviation Maintenance Training Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across a market structure that concentrates premium positioning among simulation technology specialists and fragments commodity instruction among regional flight schools. Three archetypes dominate: integrated airline-affiliated academies bundling training with MRO services, independent Part 147 schools serving domestic technician pipelines, and technology vendors licensing digital platforms to carrier technical operations departments. Competitive moves center on strategic partnerships for curriculum co-development and geographic expansion through joint venture training centers near emerging maintenance clusters.
Within the integrated airline-affiliated tier, Lufthansa Technical Training and CAE exemplify full-service positioning that spans type-rating, recurrent, and specialized troubleshooting through unified platforms. Aviation Institute of Maintenance represents the independent Part 147 school archetype with concentrated presence in Florida and Texas training corridors. FEAM Aero occupies a position among MRO-integrated operators delivering on-the-job instruction alongside live maintenance operations. These three anchors illustrate how vendor consolidation around comprehensive training partners displaces fragmented procurement across single-service providers, particularly among low-cost carriers seeking operational simplicity and volume pricing leverage.
| Leading Market Players |
|---|
| Hillsboro Aero Academy |
| Pan Am International Flight Academy |
| Aviation Institute of Maintenance |
| ST Engineering Aerospace |
| FL Technics |
| FEAM Aero |
| CAE |
| Lufthansa Technical Training |
| Diamond Aircraft Industries |
| Others |
Supply Flow & Price Mechanics
Airline technical operations departments consolidating vendor relationships around full-service training partners are forcing supply-side specialization and compressing margins for fragmented single-service providers. This procurement concentration reshapes how training providers price bundled curricula and source simulation hardware.
Pricing Analysis
Margin tightening in simulation-based delivery reflects hardware cost inflation exceeding fifteen million dollars per full-motion training unit. Pricing stratifies across premium type-rating credentials, standard recurrent certification modules, and economy-tier theoretical coursework. Cost compression in classroom instruction intensifies as mid-tier institutions compete for FAA Part 147-accredited enrollment. Low-cost carriers in Spain and Ireland exhibit highest price sensitivity, while legacy network carriers prioritize capability breadth over unit economics.
Supply Chain Analysis
Domestic-content mandates in India's aviation sector are reshaping instructor sourcing and curriculum localization for joint venture training centers near Bengaluru. Hardware supply concentrates in the United States, Germany, and Canada for full-motion flight training devices. Component dependencies span motion platform actuators, visual display systems, and proprietary fault insertion software. Single-source vulnerability in simulator manufacturer networks creates concentration risk. Distribution runs through direct airline technical operations procurement and MRO-integrated training bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where FAA Part 147 accreditation timelines averaging eighteen to twenty-four months erect barrier-to-entry moats protecting established training providers.
For Market Incumbents: To counter certified instructor scarcity across Germany, France, and the United Kingdom, incumbents should deepen captive supply of instructional talent through accelerated credential pathways and cross-border licensing reciprocity agreements. Consolidation of simulation infrastructure through shared-service partnerships with regional MRO clusters defends margin position against capital-constrained entrants. For New Entrants and Emerging Players: Regional carriers testing battery-electric and hydrogen propulsion pilots represent an underserved buyer archetype requiring specialized high-voltage and cryogenic systems training ahead of EASA rulemaking finalization. White-space concentration sits with micro-credential stacking for modular digital badges. Joint venture structures with established Part 147 schools accelerate market access without full accreditation burden. For Investors and Strategic Acquirers: The window for entry favors technology vendors licensing immersive reality platforms to carrier technical operations departments seeking reduced live aircraft access. Long-term viability hinges on curriculum-hardware synchronization capabilities across proprietary aircraft health monitoring architectures. Watch for EASA rulemaking finalization on zero-emission propulsion as inflection indicator for specialized training demand.| Strategic Initiative | Industry Significance |
|---|---|
| Simulation Infrastructure Partnership | CAE and Lufthansa Technical Training anchor recurring revenue through shared motion platform networks. |
| Curriculum Co-Development Agreement | Airline-MRO collaborations align troubleshooting scenarios with proprietary Boeing 787 health monitoring architectures. |
| Joint Venture Training Center | DGCA-aligned facilities near Hyderabad address India's projected technician shortage through localized instruction. |
| Digital Platform Licensing | Cloud-based learning management systems automate CSRD compliance documentation for European carrier sustainability reporting. |
| Micro-Credential Stack Development | Modular digital badges enable subscription revenue models and employer-customized learning pathways for component-specific competencies. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs combining primary interviews with training provider executives, airline technical operations directors, MRO procurement leads, and civil aviation authority certification officers. FAA Part 147 accreditation databases, EASA Part 66 examination statistics, and DGCA workforce projections supplied validation benchmarks. Bottom-up enrollment modeling and top-down market sizing triangulated volume estimates.
Data-stream reconciliation across training type, certification level, delivery method, and target audience segmentation generated consistent value projections across the analysis window. CAGRs derived from fleet modernization cycle correlation with technician pipeline requirements, incorporating simulator hardware deployment rates and instructor qualification throughput constraints.
Revisions become necessary when battery-electric or hydrogen propulsion certification pathways accelerate ahead of modeled timelines, or when FAA Part 147 accreditation timelines compress materially. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Maintenance and MRO Solutions
Wide-Body Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Digital MRO Market
Aircraft Maintenance and MRO Solutions
GCC Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Wheel Bead Breakers Market
Aircraft Maintenance and MRO Solutions
Regional Turboprop Engine MRO Services Market
Aircraft Maintenance and MRO Solutions
Global Aircraft Refurbishing Market
Aircraft Maintenance and MRO Solutions
Asia-Pacific Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Latin America Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
United States Airframe MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Component MRO Market
Aircraft Maintenance and MRO Solutions
MRO Software Market
Aircraft Maintenance and MRO Solutions
Aircraft Weighing Scales Market
Aircraft Maintenance and MRO Solutions
Aircraft Maintenance Market
Aircraft Maintenance and MRO Solutions
Global Aircraft Engine MRO Market
Aircraft Maintenance and MRO Solutions
Global Aircraft Heavy Maintenance Visits Market
Aircraft Maintenance and MRO Solutions
Distributed Electric Propulsion System MRO Services Market