
 Global Electronic Flight Bag Market | 2026-2036
Global Electronic Flight Bag Market Size, Share, and Industry Trends Forecast 2026-2036
Global Electronic Flight Bag Market Foresight
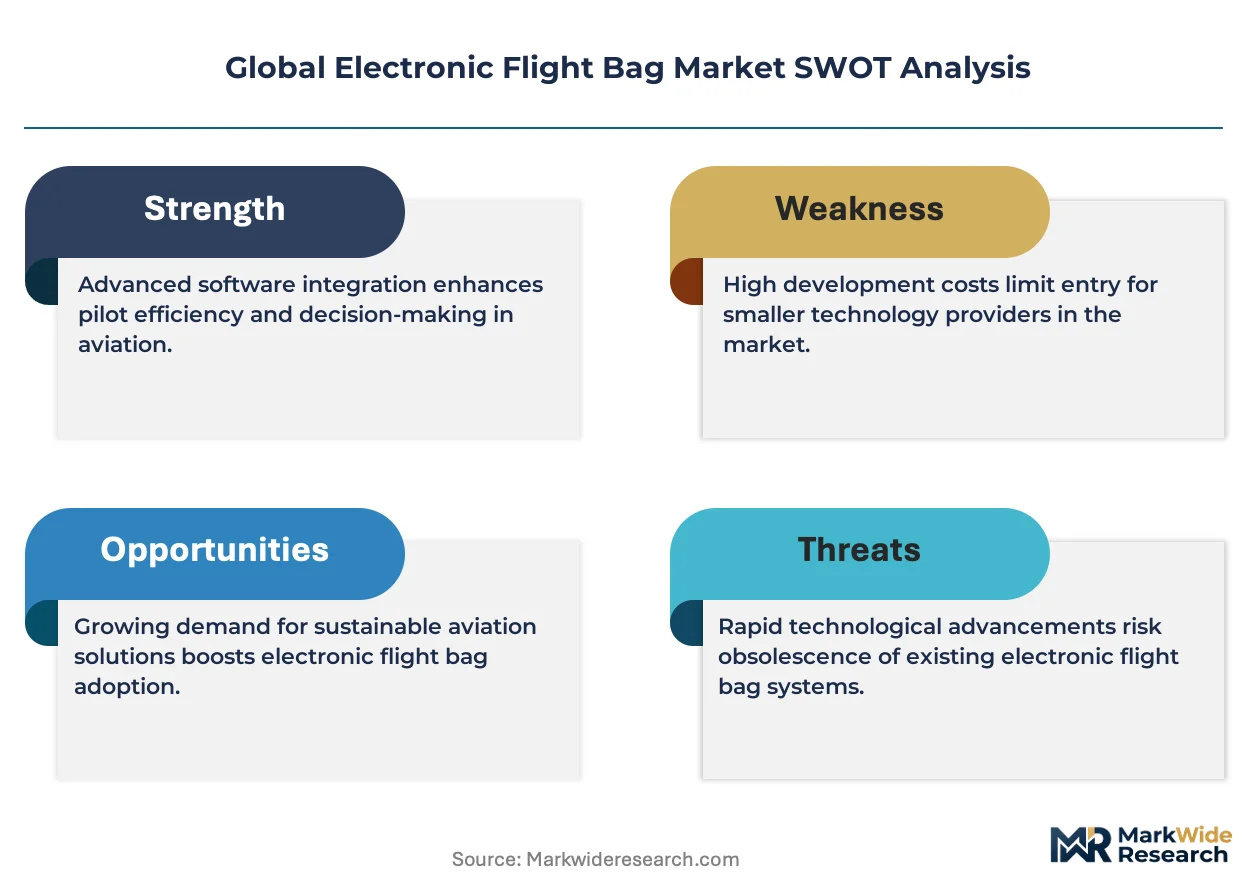
Commercial airlines is rotating toward integrated EFB solutions as charter operators and cargo carriers lag in fleet-wide deployment. Honeywell International Inc. leverages its avionics heritage to dominate integrated hardware-software bundles for Boeing and Airbus platforms. Thales Group anchors European supply chains through cockpit display integration and certified connectivity modules. Collins Aerospace competes via its deep position in retrofit programs for legacy aircraft types.
An electronic flight bag comprises certified computing hardware, navigation databases, performance calculation software, and document management systems that replace traditional paper charts and manuals in aircraft cockpits. These systems must meet DO-178C software assurance and DO-254 hardware certification standards while operating across temperature ranges from minus 40 to plus 70 degrees Celsius. Software and integrated solutions command the strongest margin pools as airlines prioritize subscription-based updates over one-time hardware purchases. Cloud-based platforms represent the fastest-growing deployment category, though onboard systems retain the largest installed base due to regulatory latency in approving full connectivity dependency.
The FAA mandates EFB operational authorization under AC 120-76, while EASA enforces comparable certification through AMC 20-25, and China's CAAC aligns with its own airworthiness directives for electronic documentation. These frameworks shape demand by determining which hardware classes require supplemental type certificates versus simple operational approvals. Stakeholders must monitor the divergence between cloud-native architectures and legacy onboard certification pathways as regulators reassess connectivity risk models.
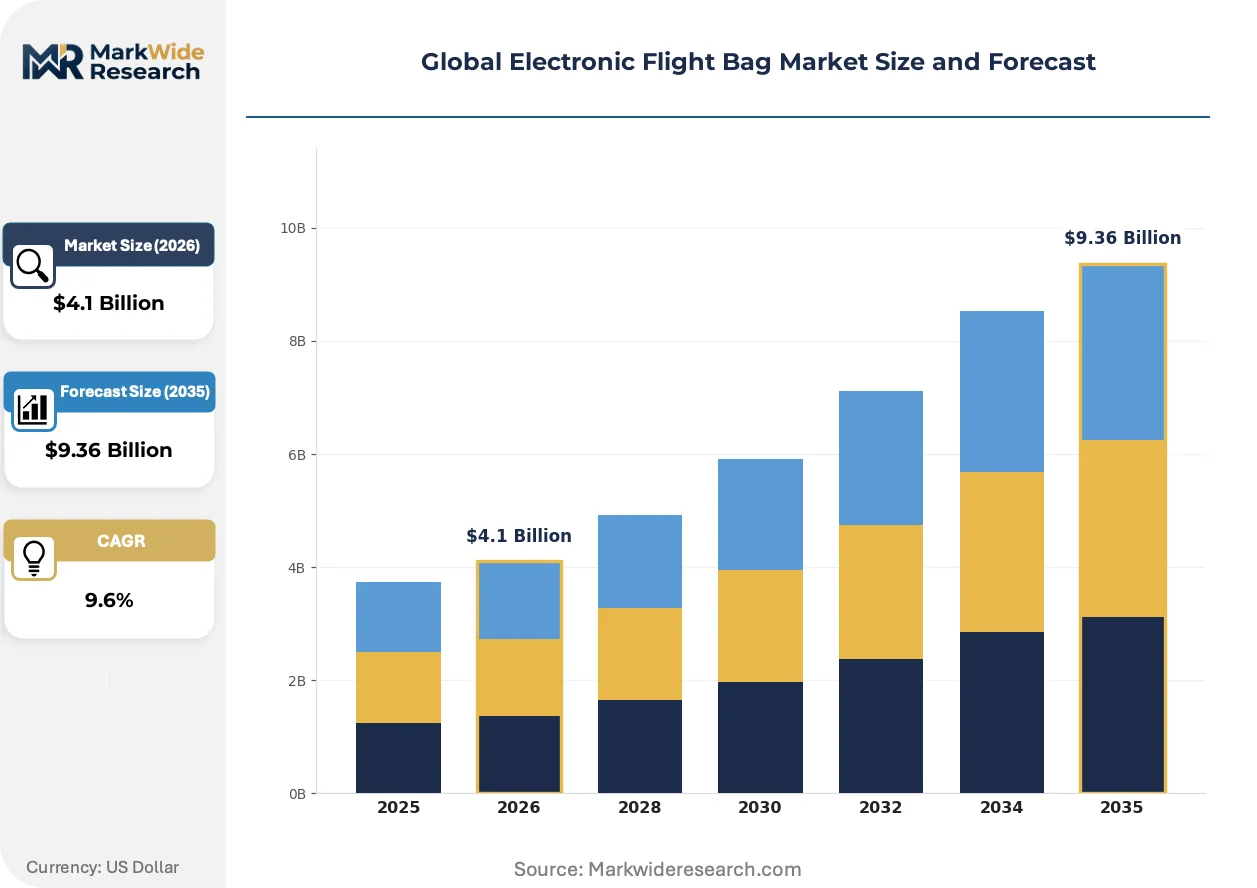
Market Dynamics
Fleet modernization mandates from the FAA and EASA are compressing hardware replacement cycles while cloud-native architectures create parallel certification pathways that split vendor investment priorities.
Growth Catalysts
- Paperless Cockpit Mandates:FAA AC 120-76 and EASA AMC 20-25 operational authorizations eliminate manual chart workflows across commercial fleets.
- Narrow-Body Fleet Expansion:Low-cost carriers in India and Southeast Asia are retrofitting legacy Boeing 737 and Airbus A320 platforms with portable EFB hardware.
- Performance Software Subscriptions:Airlines favor recurring navigation database and calculation tool licenses over capital-intensive hardware refreshes.
Market Restraints
- DO-178C Certification Costs:Software assurance testing for safety-critical flight applications consumes 18-24 month development timelines.
- Avionics Supply Concentration:Certified display and processor modules depend on a concentrated base of aerospace-grade semiconductor foundries in Germany and the United States.
- Connectivity Latency Risks:Full cloud dependency remains blocked by regulator skepticism toward satellite link reliability in polar and oceanic routes.
Strategic Opportunities
- Cargo Carrier Underpenetration:Freighter operators at FedEx and DHL maintain paper-based dispatch workflows ripe for Class 2 EFB conversion.
- China CAAC Alignment:Harmonization with FAA and EASA certification standards opens domestic Chinese airline procurement to foreign hardware-software bundles.
- AI-Assisted Flight Planning:Machine learning route optimization converges with real-time weather data feeds to create premium subscription tiers.
Industry Challenges
- DO-254 Hardware Verification:Complex programmable logic device certification for custom graphics processors strains engineering teams.
- Legacy Aircraft Integration:Retrofit cabling and power distribution modifications for 1990s-era Boeing 757 and 767 cockpits extend deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Electronic Flight Bag Market |
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $9.36 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardware, Software, Integrated Solutions, Mobile Apps Deployment: Onboard Systems, Portable Devices, Cloud-Based Platforms, Hybrid Solutions Application: Pilot Interface, Flight Planning, Aircraft Maintenance, Crew Communication End User: Commercial Airlines, Charter Operators, Cargo Carriers, Military Aviation |
| Companies Covered | Honeywell International Inc., Thales Group, The Boeing Company, Collins Aerospace, Teledyne Technologies Incorporated, Lufthansa Systems, Raytheon Technologies Corporation, CMC Electronics, Astronautics Corporation of America, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Electronic Flight Bag Market Shifts & Advancements
Real-time data architectures are bifurcating the installed base between connected tablets and hardened embedded systems, forcing suppliers to maintain dual development tracks.
Cloud-based EFB platforms are fragmenting the traditional hardware-software bundle. These systems offload performance calculations and document libraries to ground servers, reducing onboard storage requirements. Regional carriers and charter operators adopt them fastest due to lower upfront capital needs. The shift compresses margins for dedicated avionics hardware manufacturers while elevating software vendors.
EASA's evolving guidance on connectivity risk models is tightening operational approval standards for tablet-based solutions. The regulator now demands redundant data paths and offline fallback capabilities for oceanic operations. Wide-body operators on trans-Pacific routes face the steepest compliance adjustments, accelerating investment in hybrid architectures that cache critical data locally.
Airline technical procurement departments are consolidating vendor relationships around integrated lifecycle service contracts. Single-source accountability for hardware, software updates, and regulatory compliance is displacing fragmented multi-vendor arrangements. This concentration is most pronounced among United States legacy carriers managing mixed Boeing-Airbus fleets.
Global Electronic Flight Bag Market Segmentation
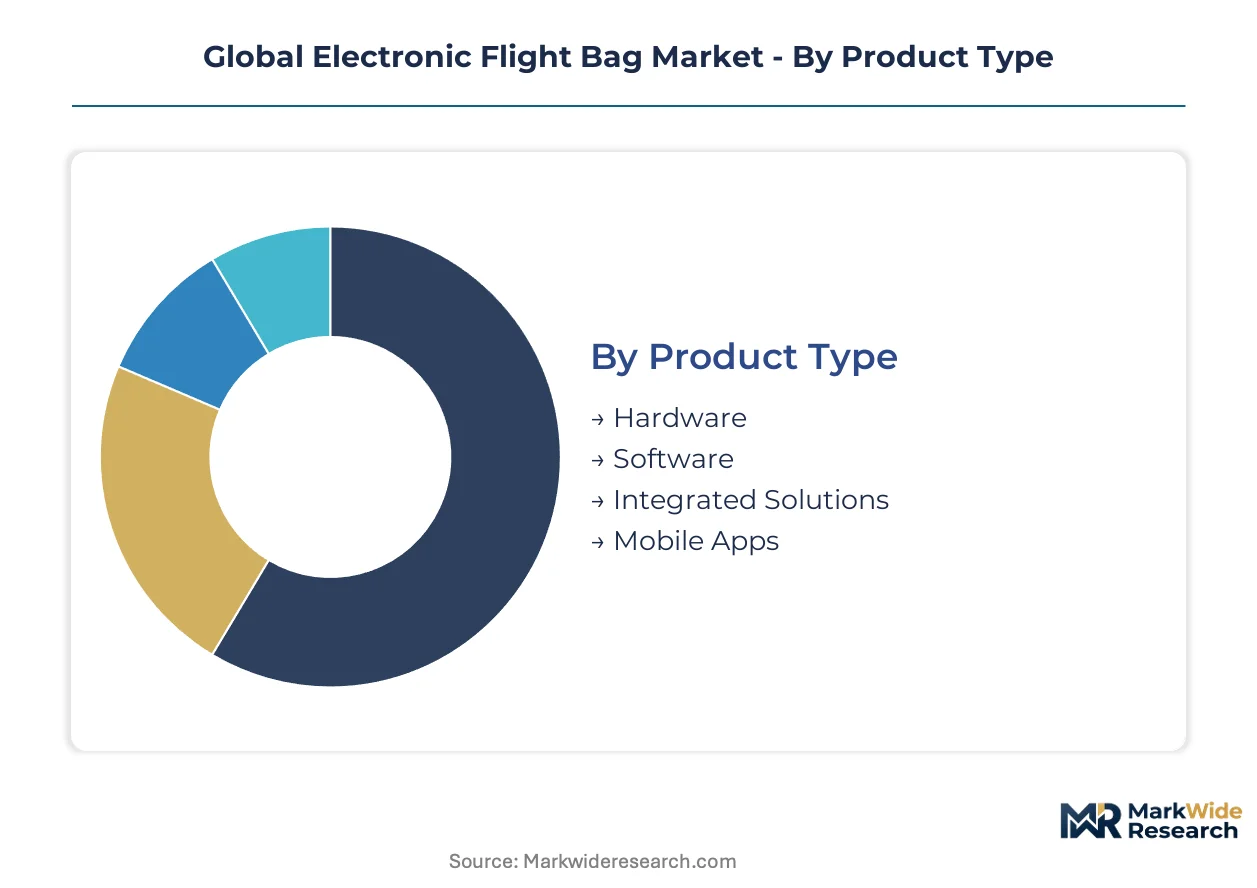
EFB procurement patterns diverge sharply between hardware-centric retrofit programs and software-subscription models. Airlines select segments based on fleet age, regulatory jurisdiction, and whether they prioritize capital expenditure control or operational flexibility.
Product Type:
Hardware shipments flow through avionics distributors and OEM retrofit channels, while software and integrated solutions reach airlines via direct enterprise sales and recurring subscription platforms.
- Hardware:Certified computing platforms include ruggedized tablets, mountable displays, and processor units meeting DO-254 standards. Demand concentrates in the United States and Germany as carriers retrofit narrow-body fleets ahead of FAA and EASA paperless deadlines. Hardware procurement faces compressed margins as airlines extend replacement cycles.
- Software:Navigation databases, performance calculation engines, and document management systems operate under DO-178C assurance protocols. German carriers and Chinese airlines prioritize subscription-based performance tools to minimize upfront capital deployment. Recurring revenue models dominate procurement negotiations.
- Integrated Solutions:Bundled hardware-software packages with unified certification support.
- Mobile Apps:Lightweight pilot-facing applications for document access and basic calculations.
By volume, Hardware leads. By growth pace, Software is ahead.
Deployment:
Cost tiers separate this category: onboard systems command premium pricing for certified avionics integration, while portable and cloud-based options reduce entry barriers for regional operators.
- Onboard Systems:Permanently installed EFB architectures with dedicated cockpit displays and aircraft power distribution. United States legacy carriers deploying across Boeing and Airbus wide-body fleets drive demand, constrained by STC acquisition timelines and wiring modification costs.
- Cloud-Based Platforms:Ground-server-dependent architectures offloading storage and processing to terrestrial data centers. Charter operators in India and Southeast Asia adopt these fastest due to minimal capital requirements and rapid deployment. EASA connectivity risk assessments create compliance friction for oceanic routes.
- Portable Devices:Removable tablet-based systems for temporary cockpit use.
- Hybrid Solutions:Architectures combining local data caching with intermittent cloud synchronization.
By installed base, Onboard Systems dominate. By expansion trajectory, Cloud-Based Platforms are climbing the fastest.
Application:
Customer type determines segment selection: flight planning tools serve airline operations centers, while pilot interface solutions target individual flight deck users with distinct procurement workflows.
- Flight Planning:Route optimization, fuel calculation, and dispatch release generation tools. Chinese airlines and German cargo carriers invest heavily as CAAC alignment with international standards accelerates software procurement. Real-time weather integration and AI-assisted routing create premium subscription tiers.
- Pilot Interface:Electronic chart display, checklist management, and NOTAM presentation systems. United States commercial airlines standardize these across narrow-body and wide-body fleets under FAA AC 120-76 operational authorizations. Display certification and human factors testing extend development timelines.
- Aircraft Maintenance:Technical logbook digitization and defect reporting tools for ground crews.
- Crew Communication:Messaging and briefing distribution platforms connecting flight deck with cabin and ground personnel.
By operational penetration, Pilot Interface leads. By investment growth, Flight Planning is gaining share fastest.
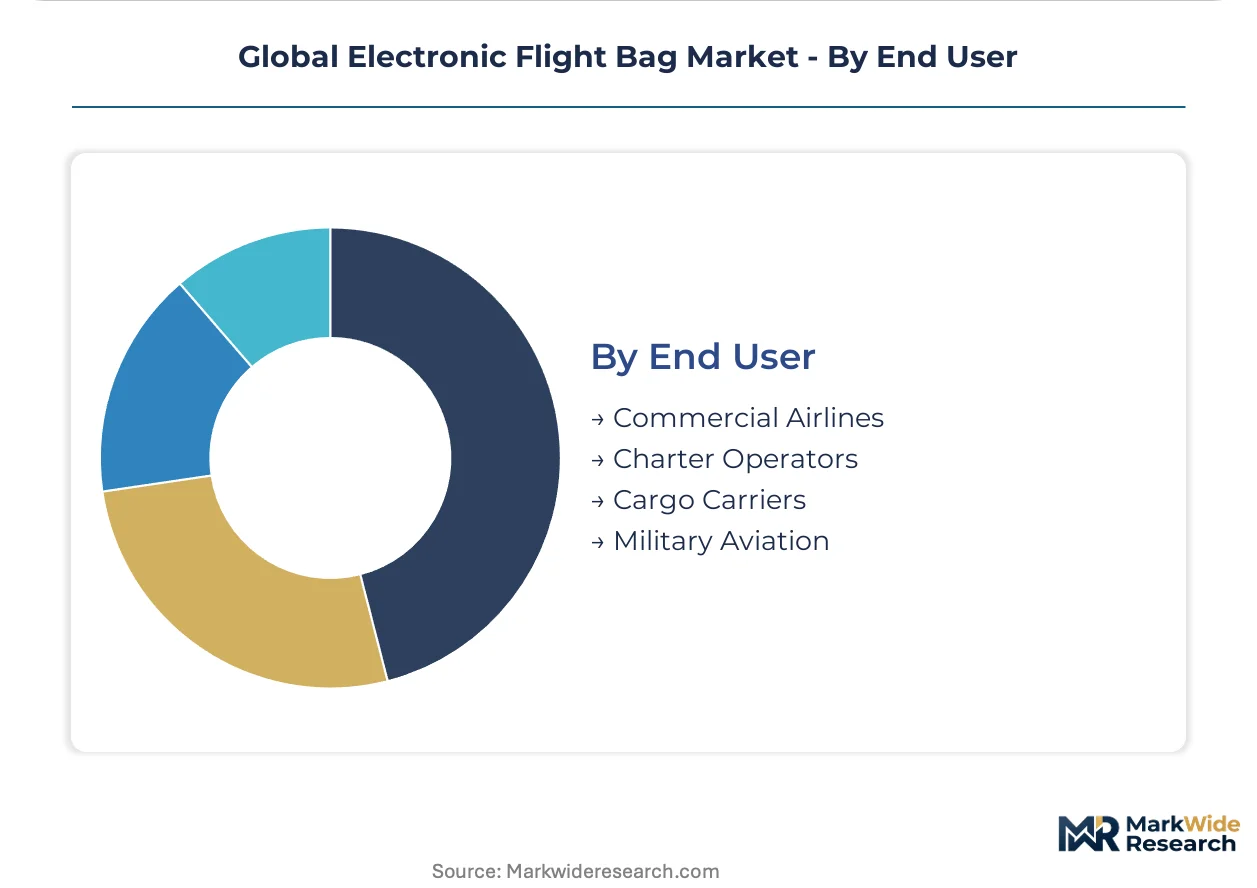
End User:
Maturity stages separate this category: commercial airlines operate at full fleet deployment, while cargo carriers and charter operators remain in early adoption phases with substantial runway for conversion.
- Commercial Airlines:Full-fleet EFB deployment across narrow-body, wide-body, and regional aircraft types. United States and German carriers lead procurement volume, driven by FAA and EASA paperless cockpit mandates. Vendor consolidation around integrated lifecycle contracts characterizes procurement patterns.
- Cargo Carriers:Freighter operators at FedEx, DHL, and similar fleets maintaining paper-based dispatch workflows. Underpenetration creates conversion opportunity as Class 2 EFB hardware enables phased retrofit without full avionics replacement.
- Charter Operators:Fragmented fleet structures and variable route profiles complicate standardization.
- Military Aviation:Specialized security and interoperability requirements distinct from civil certification pathways.
By current deployment scale, Commercial Airlines dominate. By untapped conversion potential, Cargo Carriers present the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FAA's Next Generation Air Transportation System infrastructure anchors United States demand for certified cockpit computing platforms. Satellite ground stations across the continental grid enable real-time data synchronization for connected EFB architectures.
United States
Legacy carriers retrofit narrow-body and wide-body fleets under FAA AC 120-76 operational authorization deadlines. The FAA mandates supplemental type certificates for Class 3 installed systems while permitting operational approval for portable Class 1 and 2 devices. Dallas-Fort Worth and Seattle aerospace clusters concentrate avionics integration facilities serving mixed Boeing-Airbus fleets.
Germany
Lufthansa Group and cargo operators drive procurement of integrated hardware-software bundles for performance calculation tools. EASA AMC 20-25 certification requirements shape vendor selection toward DO-178C compliant navigation databases. Hamburg and Munich host cockpit display integration facilities linking European supply chains to Airbus final assembly lines.
China
Domestic airlines accelerate fleet-wide EFB deployment as CAAC aligns airworthiness directives with FAA and EASA standards. The Civil Aviation Administration of China issues type certificates for foreign-certified hardware-software bundles entering procurement pipelines. Beijing and Shanghai aerospace districts concentrate retrofit programs for Boeing 737 and Airbus A320 platforms operated by Air China and China Eastern.
India
Low-cost carriers retrofit legacy narrow-body fleets with portable EFB hardware to minimize capital deployment. The Directorate General of Civil Aviation operational circulars permit tablet-based solutions for domestic route networks. Mumbai and Bangalore maintenance facilities specialize in rapid deployment programs for IndiGo and SpiceJet aircraft.
United Kingdom
British Airways and Virgin Atlantic standardize pilot interface systems across long-haul wide-body operations. The UK Civil Aviation Authority enforces EASA-aligned operational approvals with additional scrutiny for connectivity-dependent oceanic routes. London Heathrow and Gatwick anchor technical procurement departments consolidating vendor relationships around integrated lifecycle contracts.
Global Electronic Flight Bag Market Competitive Landscape
Concentration sits with integrated avionics suppliers possessing DO-254 hardware certification and DO-178C software assurance capabilities. The vendor base stratifies between full-stack platform providers and specialized software vendors. Three archetypes dominate: aerospace conglomerates with cockpit heritage, airline-affiliated technology divisions, and independent avionics specialists. Competitive moves center on unified certification support and retrofit program execution for legacy aircraft types.
Within the integrated platform tier, Honeywell International Inc. and Thales Group exemplify full-stack positioning through bundled hardware-software offerings. Collins Aerospace anchors the retrofit-specialist archetype with concentrated presence in legacy aircraft modification programs. Lufthansa Systems represents the airline-affiliated technology division model, leveraging operator-side operational knowledge to inform product development priorities.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Thales Group |
| The Boeing Company |
| Collins Aerospace |
| Teledyne Technologies Incorporated |
| Lufthansa Systems |
| Raytheon Technologies Corporation |
| CMC Electronics |
| Astronautics Corporation of America |
| Others |
Supply & Pricing Matrix
Cloud-native software architectures displacing dedicated avionics hardware are redrawing procurement geography toward subscription-based vendors while compressing margins for traditional equipment manufacturers locked into DO-254 certification cycles.
Pricing Analysis
Volume-discount tiering structures separate narrow-body fleet commitments above fifty aircraft from smaller charter operator deployments. Airlines negotiating enterprise-wide performance software subscriptions extract steeper discounts than cargo carriers purchasing portable Class 2 hardware in tranches below ten units. Price differentiation hinges on DO-178C certification grade and after-sales service bundling, with integrated lifecycle contracts commanding premiums over fragmented multi-vendor arrangements. Cost compression in hardware tiers is intensifying because airlines extend replacement cycles and favor recurring navigation database licenses over capital-intensive processor refreshes. Regional operators in India exhibit highest price sensitivity, while United States legacy carriers managing mixed Boeing-Airbus fleets prioritize unified certification support over unit cost minimization.
Supply Chain Analysis
DO-254-compliant semiconductor foundry concentration in Germany and the United States anchors processor and graphics module availability for certified avionics systems. Aerospace-grade programmable logic devices and ruggedized display panels draw from concentrated fabrication facilities in Bavaria and Texas, with secondary sourcing from Japanese specialty foundries. Single-source vulnerability in custom graphics processor supply creates exposure when EASA tightens operational approval standards demanding redundant data paths. Distribution runs through avionics distributors and OEM retrofit channels for hardware, while software and integrated solutions reach airlines via direct enterprise sales and recurring subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Electronic Flight Bag market functions as a service-attach opportunity where performance software subscriptions and integrated lifecycle contracts expand faster than hardware shipments, rewarding vendors that anchor customer relationships around recurring revenue rather than one-time equipment sales.
For Market Incumbents: Compound defensive positioning by deepening backward integration into DO-254-certified semiconductor sourcing and acquiring specialized navigation database providers to control subscription renewal flows. Lock in narrow-body fleet retrofit programs ahead of FAA AC 120-76 deadlines to forestall portable hardware competitors from establishing footholds with low-cost carriers. For New Entrants and Emerging Players: EASA AMC 20-25 fast-track certification for tablet-based solutions opens entry pathways for software-native vendors lacking avionics heritage. Target cargo carrier Class 2 EFB conversion at FedEx and DHL networks where paper-based dispatch workflows persist, and lead with AI-assisted flight planning modules that create premium subscription tiers distinct from incumbent performance tools. For Investors and Strategic Acquirers: Capital is best deployed toward software-native EFB platforms with established airline subscription bases and clear paths to DO-178C certification, rather than hardware-dependent vendors facing margin compression. Monitor EASA connectivity risk model evolution as the inflection signal determining whether hybrid architectures or full cloud-native solutions capture wide-body operator procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Lifecycle Service Contracts | Single-source accountability for Honeywell and Thales displaces fragmented multi-vendor arrangements at United States legacy carriers. |
| DO-178C Certification Investment | Eighteen-month software assurance timelines create defensive moats against unqualified entrants in safety-critical flight applications. |
| AI-Assisted Flight Planning Development | Machine learning route optimization converges with real-time weather data feeds to capture premium subscription tiers from Chinese airlines. |
| Cargo Carrier Retrofit Program | Class 2 EFB hardware conversion at FedEx and DHL networks unlocks underpenetrated freighter operator demand without full avionics replacement. |
| CAAC Harmonization Alignment | Foreign-certified hardware-software bundles entering procurement pipelines at Air China and China Eastern accelerate market access. |
Research Methodology
Cross-validation between primary interviews with airline technical procurement directors, avionics integration engineers, and regulatory compliance officers and secondary sources including FAA AC 120-76 guidance documents, EASA AMC 20-25 certification databases, and CAAC airworthiness directive filings anchors the qualitative findings. Bottom-up triangulation of fleet deployment data from United States, German, and Chinese carriers with top-down macroeconomic indicators shapes market sizing.
Sensitivity analysis around narrow-body fleet expansion rates and cloud adoption curves tests forecast robustness across the projection horizon. Segmentation dimensions modeled include product type, deployment architecture, application function, and end-user category, with CAGRs derived from regression analysis against historical EFB procurement patterns and projected airline fleet modernization schedules. Industry-specific inputs incorporate DO-178C certification timeline assumptions and satellite connectivity reliability benchmarks for oceanic operations.
Underlying assumptions cover FAA and EASA paperless cockpit mandate adherence timelines, with deviation risk concentrated in CAAC regulatory harmonization pace and aerospace-grade semiconductor foundry capacity constraints. Practitioners should keep alternative scenarios live as EASA connectivity risk assessments and polar route satellite link reliability data evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Attack Helicopter Market
Aircraft
Southeast Asia Aviation Market
Aircraft
Global Ultralight and Light Aircraft Market
Aircraft
Middle-East Aviation Market
Aircraft
Amphibious Aircraft Market
Aircraft
Heavy-Lift Helicopter Market
Aircraft
Military Transport Aircraft Market
Aircraft
Global Aircraft Tugs Market
Aircraft
Aircraft Oxygen System Market
Aircraft
Water Bomber Market
Aircraft
Middle East and Africa Military Helicopters Market
Aircraft
Latin America Business Jet Market
Aircraft
Asia-Pacific Aircraft Manufacturing Market
Aircraft
Commercial Aircraft Lighting Market
Aircraft
Onboard Oxygen Generating System (OBOGS) Market
Aircraft
Aircraft Aerostructures Market