
 Digital MRO Market | 2026-2036
Digital MRO Market Size, Share, and Industry Trends Forecast 2026-2036
Digital MRO Market Analysis
The EU Green Deal's emissions reduction mandates for aviation is repositioning maintenance strategies toward condition-based interventions that minimize material waste and fuel burn. Lufthansa Technik anchors European digital MRO services through its AVIATAR platform, which integrates fleet analytics with predictive algorithms. Honeywell International Inc. leverages its Forge software suite to compete across energy and aerospace verticals with real-time asset monitoring. IBM extends its Watson IoT capabilities into aviation partnerships, occupying a niche in cognitive maintenance diagnostics for complex turbine systems.
Digital MRO encompasses software platforms, cloud infrastructure, and data analytics tools that digitize maintenance, repair, and overhaul workflows for capital-intensive equipment. These systems typically integrate sensor data streams, digital twin simulations, and AR-guided technician interfaces to compress turnaround times and extend component life cycles. Cloud Platforms represent the fastest-expanding product type as operators migrate legacy on-premise systems to scalable architectures that reduce IT overhead. Within end-user verticals, Aerospace dominates current spending due to regulatory pressure for continuous airworthiness documentation, while Energy is emerging as the highest-margin segment where offshore asset monitoring commands premium pricing for uptime guarantees.
The FAA's airworthiness directive digitization requirements and EASA's Part-M continuing airworthiness regulations are mandating electronic record-keeping that accelerates platform adoption across regulated fleets. India's DGCA has aligned with ICAO standards to require digital maintenance logs for commercial operators, opening procurement pathways for SaaS-based compliance tools. Stakeholders must monitor how emerging cybersecurity frameworks for operational technology reshape vendor qualification criteria and platform architecture decisions.
Market Dynamics
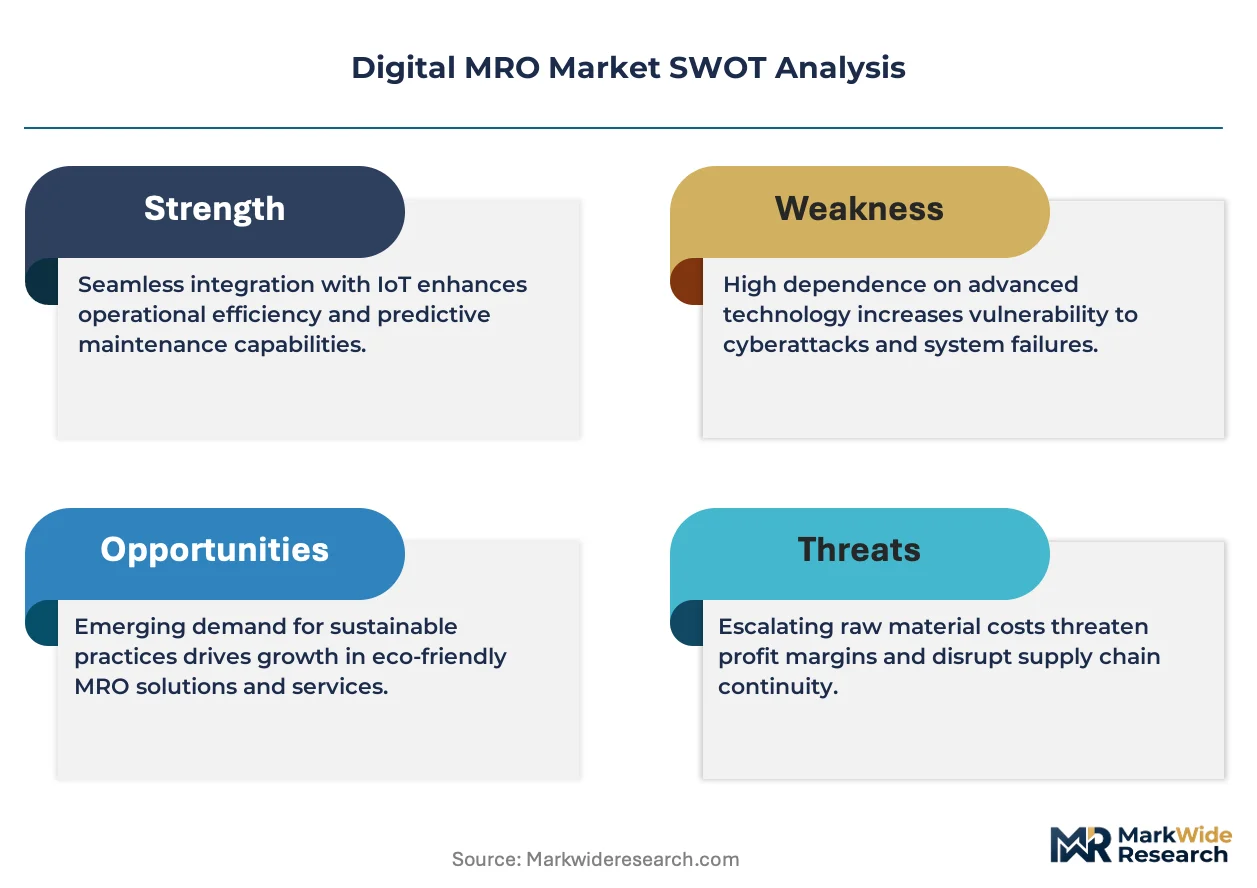
Machine learning architectures are compressing maintenance cycles from calendar-based overhauls to condition-driven interventions, forcing legacy ERP systems into obsolescence and redrawing vendor qualification criteria across regulated fleets.
Growth Catalysts
- FAA Airworthiness Directive Digitization:Mandated electronic record-keeping for continuous airworthiness documentation accelerates platform procurement among US commercial operators and regional carriers.
- Cloud Infrastructure Migration:Scalable architectures reduce IT overhead for MRO providers managing sensor data streams from distributed asset fleets.
- Germany:Lufthansa Technik's AVIATAR platform anchors Europe's largest aviation MRO cluster, concentrating predictive algorithm development and technician training programs.
Market Restraints
- Legacy System Integration Costs:Proprietary data formats in incumbent maintenance software create friction during platform migration, extending implementation timelines.
- Offshore Asset Monitoring Concentration:Premium uptime guarantees for energy sector deployments concentrate in North Sea and Gulf of Mexico regions, limiting addressable market expansion.
- Cybersecurity Framework Gaps:Operational technology security standards remain immature, creating vendor qualification uncertainty for critical infrastructure operators.
Strategic Opportunities
- India DGCA Digital Log Mandate:Aligned ICAO standards open procurement pathways for SaaS-based compliance tools among commercial operators in South Asia.
- Digital Twin Convergence:Integration of sensor data streams with AR-guided technician interfaces compresses turnaround times for component overhaul workflows.
- Energy Sector Premium Pricing:Offshore wind and oil platform monitoring commands margin expansion through uptime guarantee contracts distinct from aviation rate structures.
Industry Challenges
- Technician Skill Transformation:Predictive maintenance algorithms require workforce retraining from mechanical overhaul expertise to data interpretation and anomaly detection.
- Multi-Regulatory Compliance:Operators must simultaneously satisfy FAA, EASA Part-M, and emerging DGCA digital log requirements, fragmenting platform certification pathways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital MRO Market |
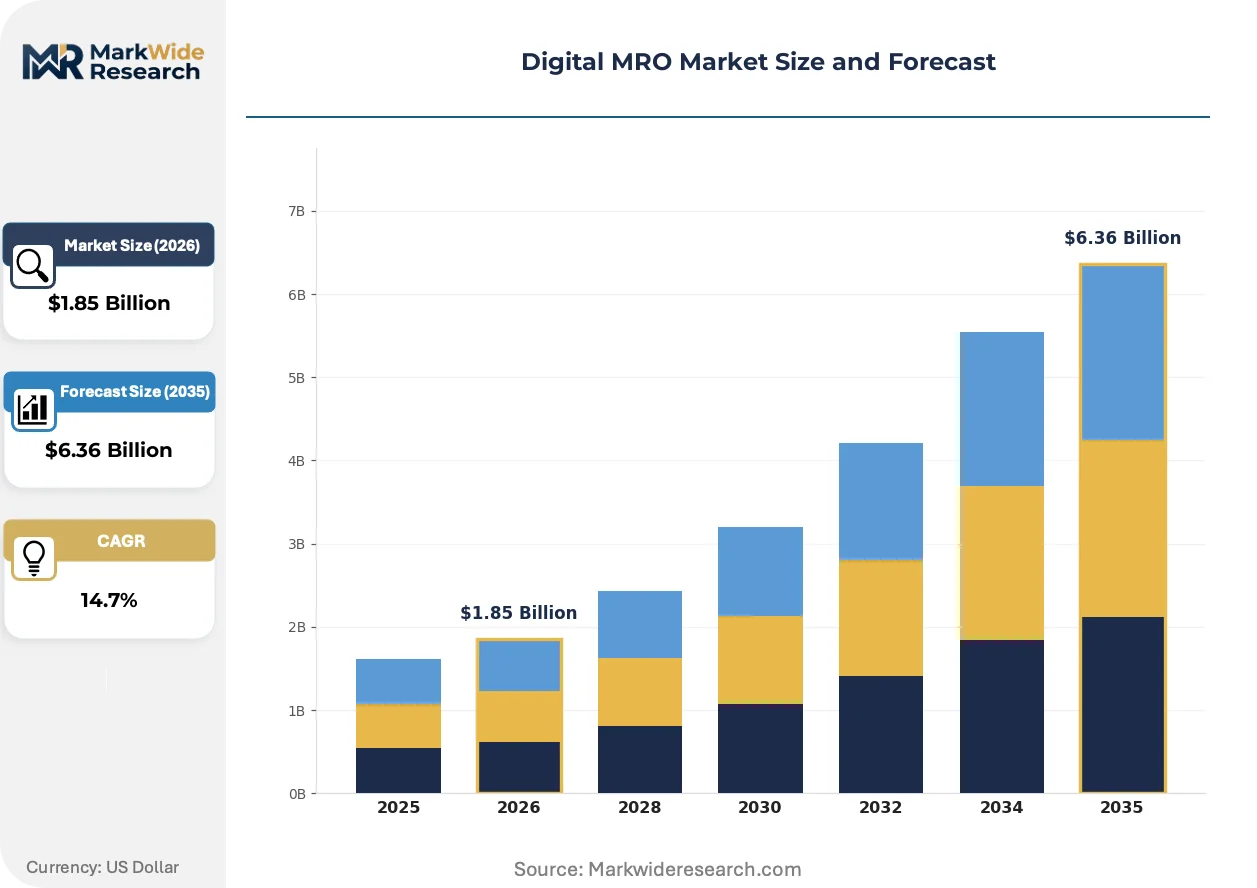
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $6.36 Billion |
| CAGR (2026 – 2036) | 14.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software Solutions, Cloud Platforms, Data Analytics Tools, Mobile Applications End User: Aerospace, Energy, Manufacturing, Automotive Deployment: On-Premise, Cloud-Based, Hybrid, SaaS Service Type: Consulting, Implementation, Support, Training |
| Companies Covered | Rusada Limited, Lufthansa Technik AG, International Business Machines Corporation, Honeywell International Inc., General Electric Company, IFS AB, The Boeing Company, AAR Corp., Ramco Systems Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital MRO Market Emerging Trajectories
Digital MRO platforms are converging three distinct capability layers—sensor ingestion, simulation modeling, and augmented reality interfaces—into unified workflow architectures that compress technician decision cycles.
Digital twin simulations are integrating real-time sensor feeds with historical failure databases to generate component-specific degradation curves. Aerospace operators in Germany and the United States are deploying these models at fleet-wide scale, replacing scheduled teardowns with condition-triggered interventions. The technology is integrating predictive algorithms directly into maintenance planning systems, collapsing the lag between anomaly detection and work order generation.
EASA's Part-M continuing airworthiness regulations now mandate electronic record interoperability across member states, forcing platform vendors to adopt standardized data exchange protocols. This industrial consequence accelerates consolidation among regional MRO software providers unable to achieve certification. Aviation fleets operating across Germany, France, and Italy face the most complex compliance burden, driving preference toward established vendors with existing regulatory relationships.
Airline procurement teams are unbundling maintenance software from bundled OEM service contracts, creating direct vendor relationships with specialized analytics providers. This channel disruption fragments the historical dominance of engine manufacturers in digital tool provision. The shift is most visible among North American carriers expanding independent fleet management programs to reduce unplanned downtime exposure.
Digital MRO Market Segmentation
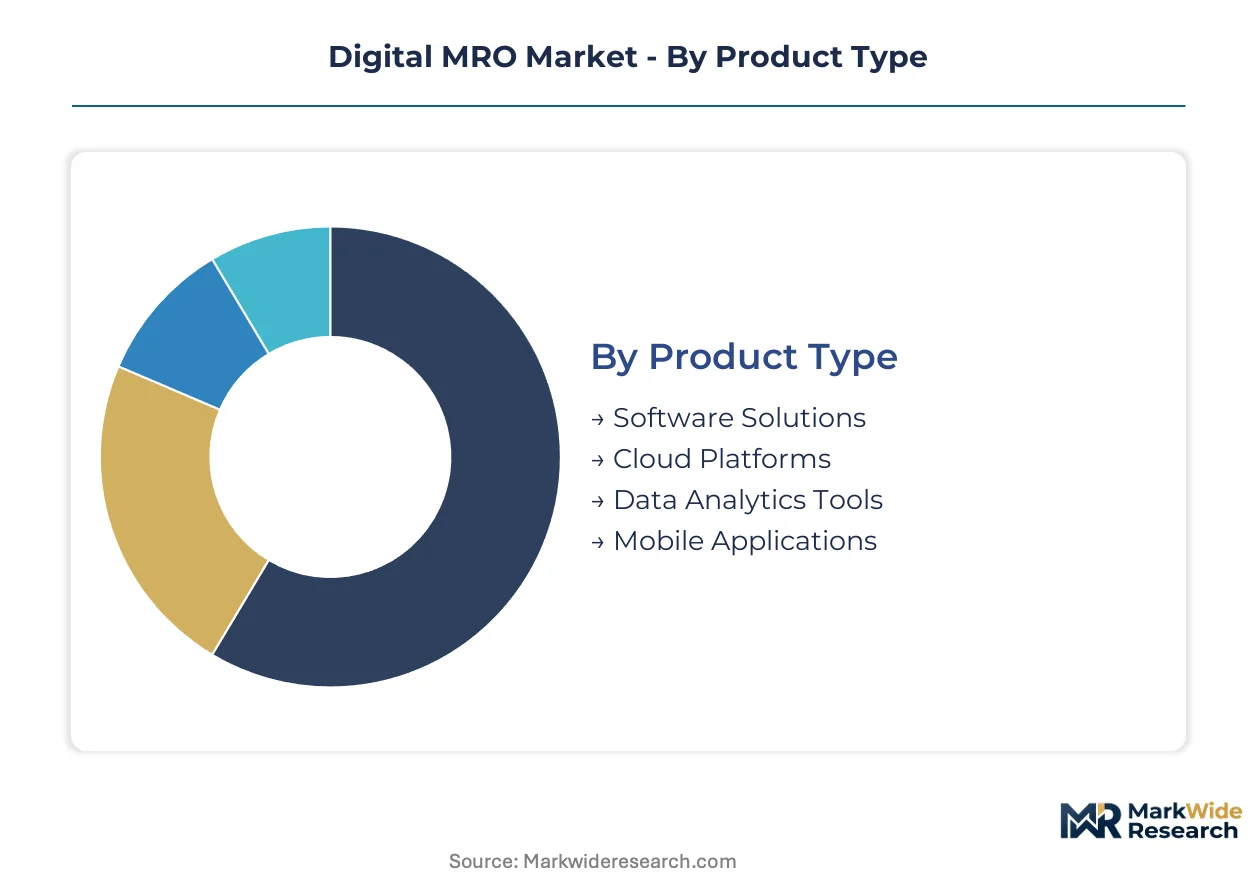
Segmentation reveals how digital MRO procurement diverges across asset-intensive industries. Each dimension exposes distinct vendor qualification criteria, pricing architectures, and integration complexity that shape platform selection decisions.
Product Type:
Upgrade cycles vary dramatically by product layer, with infrastructure migrations outpacing application refreshes.
- Software Solutions:Legacy ERP modules and point maintenance applications require extensive API reconfiguration to ingest sensor streams. Aerospace operators in Germany and the United States are unbundling these tools from OEM service contracts to establish direct vendor relationships with specialized analytics providers.
- Cloud Platforms:Scalable architectures hosting digital twin simulations and predictive algorithm workloads reduce IT overhead for distributed asset fleets. Demand concentrates among North American energy operators managing offshore monitoring infrastructure where uptime guarantees command premium pricing.
- Data Analytics Tools:Machine learning pipelines processing historical failure databases and real-time degradation signals.
- Mobile Applications:AR-guided technician interfaces compressing turnaround times for component overhaul workflows.
Volume placements concentrate in Software Solutions; the faster expansion belongs to Cloud Platforms.
End User:
Margin structures and procurement authority differ sharply across verticals, with regulated industries demanding certified compliance modules.
- Aerospace:Continuous airworthiness documentation mandates under FAA and EASA regulations drive spending on electronic record-keeping platforms. Fleet operators require interoperability across member states, forcing standardized data exchange protocols.
- Energy:Offshore wind and oil platform monitoring commands the highest margins through uptime guarantee contracts distinct from aviation rate structures. North Sea and Gulf of Mexico deployments concentrate premium service provision.
- Manufacturing:Condition-based maintenance minimizing material waste aligns with EU Green Deal emissions reduction mandates.
- Automotive:Predictive algorithms replacing calendar-based overhaul schedules for capital-intensive production equipment.
Revenue concentration sits with Aerospace; margin expansion is steepest in Energy.
Deployment:
Architecture decisions hinge on data sovereignty requirements and legacy system entanglement.
- On-Premise:Proprietary data formats in incumbent maintenance software create migration friction, extending implementation timelines for critical infrastructure operators.
- Cloud-Based:Scalable sensor data ingestion architectures reducing IT overhead for MRO providers managing distributed asset fleets.
- Hybrid:Split workloads preserving sensitive failure databases on-site while leveraging cloud compute for simulation modeling.
- SaaS:India's DGCA digital log mandate opens procurement pathways for compliance-focused subscription tools among South Asian commercial operators.
Legacy installations dominate current infrastructure; SaaS is climbing the fastest.
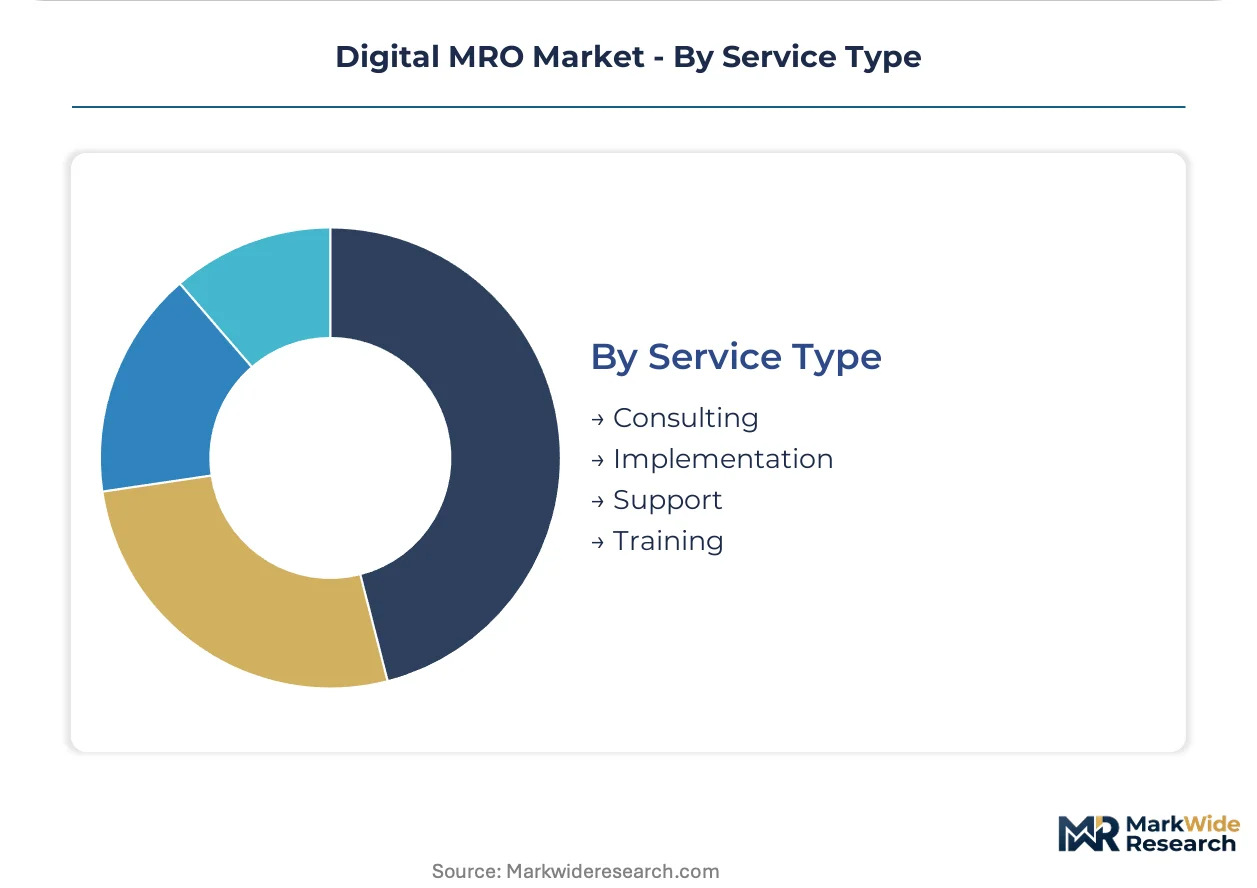
Service Type:
Vendor revenue mix shifts toward recurring support as platform complexity outpaces customer technical capacity.
- Consulting:Workforce transformation programs retraining technicians from mechanical overhaul expertise to data interpretation and anomaly detection.
- Implementation:Integration services resolving proprietary data format conflicts during platform migration.
- Support:Continuous algorithm tuning and regulatory compliance updates for multi-jurisdiction fleet operators.
- Training:Technician certification programs for AR-guided interfaces and predictive maintenance toolchains.
Project-based revenue concentrates in Implementation; recurring support is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hamburg anchors European digital MRO development through Lufthansa Technik's AVIATAR platform, while North American carriers expand independent fleet management programs to compress unplanned downtime.
United States
Domestic airlines are unbundling maintenance software from OEM service contracts to establish direct vendor relationships with specialized analytics providers. FAA airworthiness directive digitization mandates accelerate platform procurement among commercial operators and regional carriers. Dallas-Fort Worth and Seattle-Tacoma aerospace clusters concentrate predictive algorithm deployment across legacy and next-generation fleets.
Germany
EU Green Deal emissions reduction mandates reposition maintenance strategies toward condition-based interventions that minimize material waste and fuel burn. EASA Part-M continuing airworthiness regulations mandate electronic record interoperability across member states. The Hamburg-Munich corridor anchors Europe's largest aviation MRO cluster, concentrating technician training programs and digital twin simulation development.
India
DGCA alignment with ICAO standards requires digital maintenance logs for commercial operators, opening procurement pathways for SaaS-based compliance tools. The country's national aviation regulator has accelerated platform adoption timelines across domestic carriers. Bangalore and Hyderabad technology corridors concentrate cloud infrastructure development for distributed asset monitoring.
United Kingdom
Offshore wind and North Sea oil platform monitoring commands premium pricing for uptime guarantees distinct from aviation rate structures. The country's energy regulator has tightened operational technology security standards for critical infrastructure operators. Aberdeen and London energy finance clusters concentrate margin expansion through guarantee-based service contracts.
Japan
Manufacturing operators deploy predictive algorithms to replace calendar-based overhaul schedules for capital-intensive production equipment. METI industrial digitization programs accelerate sensor data stream integration into legacy ERP systems. Nagoya and Osaka industrial corridors concentrate condition-based maintenance adoption among automotive and machinery producers.
Digital MRO Market Vendor Landscape
Premium-margin players sit above commodity-margin players across compliance certification depth and regulatory relationship tenure. The vendor base organizes into three tiers: OEM-affiliated service providers with bundled software contracts, independent analytics specialists with direct airline relationships, and cloud infrastructure vendors hosting simulation workloads. Two competitive moves dominate: strategic partnerships between aerospace operators and specialized analytics providers, and geographic expansion into India's DGCA-mandated compliance market.
Among Germany-based service providers, Lufthansa Technik AG exemplifies the OEM-affiliated archetype through its AVIATAR platform integration. International Business Machines Corporation and Honeywell International Inc. occupy positions as cross-vertical technology vendors extending IoT and software capabilities into aviation partnerships. These three anchors represent distinct strategic postures: European MRO cluster concentration, cognitive diagnostics specialization, and multi-industry platform leverage.
| Leading Market Players |
|---|
| Rusada Limited |
| Lufthansa Technik AG |
| International Business Machines Corporation |
| Honeywell International Inc. |
| General Electric Company |
| IFS AB |
| The Boeing Company |
| AAR Corp. |
| Ramco Systems Corporation |
| Others |
Supply Flow & Price Mechanics
Backward integration into cloud infrastructure and proprietary algorithm development anchors pricing power for established platform vendors while locking out regional software providers lacking comparable capital depth. Lufthansa Technik's AVIATAR platform exemplifies this pattern, where captive control over digital twin simulation workloads supports premium positioning against unbundled analytics specialists competing on SaaS subscription rates.
Pricing Analysis
Uptime guarantee contracts anchor value-based pricing for energy sector deployments, where offshore wind and oil platform monitoring commands premiums distinct from aviation rate structures. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification depth and regulatory relationship tenure, with FAA and EASA Part-M compliance modules carrying substantial markups. Cost compression in standard-tier SaaS offerings is intensifying because India's DGCA mandate has attracted multiple entrants pursuing volume scale. Regional carriers and emerging market operators exhibit highest price sensitivity, while North American energy majors prioritize performance guarantees over unit economics.
Supply Chain Analysis
Freight and data sovereignty costs concentrate platform development in Germany, the United States, and India, where regulatory proximity reduces compliance friction for aviation clients. Cloud compute capacity draws from hyperscaler infrastructure anchored in North Virginia, Frankfurt, and Mumbai regions, while specialized sensor hardware sources from Japan and South Korea. Single-source vulnerability in legacy ERP data format conversion creates implementation bottlenecks extending project timelines. Distribution runs through direct vendor relationships with airline procurement teams, bypassing historical OEM service contract bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform engineering capacity scarcity props pricing power for vendors with existing regulatory certifications, constraining supply response to demand acceleration from DGCA-mandated compliance markets.
For Market Incumbents: Cement regulatory relationship advantages through accelerated EASA Part-M interoperability certification and FAA airworthiness directive digitization pre-qualification. Deepen vertical control over algorithm training datasets to defend against cloud-native entrants lacking historical failure database access. Channel control through direct airline procurement relationships remains the critical defensive lever against OEM-affiliated service providers. For New Entrants and Emerging Players: Independent MRO analytics specialists represent the most penetrable channel partner type for SaaS-based compliance tools targeting India's DGCA-mandated market. White-space concentration sits with mid-tier energy operators in the North Sea and Gulf of Mexico regions underserved by aviation-focused incumbents. Geographic expansion into South Asian commercial carriers offers lowest competitive density against established European and North American vendors. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by cloud infrastructure hyperscalers seeking aviation vertical penetration or OEM-affiliated service providers filling analytics capability gaps. Long-term viability favors vendors with multi-jurisdiction regulatory certifications and proprietary digital twin simulation assets. Watch for cybersecurity framework maturation in operational technology as inflection signal reshaping vendor qualification criteria and platform architecture investment requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Certification Acceleration | EASA Part-M and FAA digitization pre-qualification locks in procurement preference among multi-jurisdiction fleet operators. |
| Cloud Infrastructure Partnership | Hyperscaler alliances reduce IT overhead for distributed asset monitoring while scaling predictive algorithm workloads. |
| Digital Twin Convergence | Integration of sensor ingestion with AR-guided interfaces compresses technician decision cycles for component overhaul. |
| Geographic Expansion into India | DGCA-mandated digital logs open procurement pathways for SaaS compliance tools among South Asian commercial carriers. |
| Workforce Transformation Programs | Technician retraining from mechanical expertise to data interpretation addresses skill gaps constraining platform adoption. |
Methodological Framework
Document review covered EASA regulatory filings, FAA airworthiness directive databases, and hyperscaler capex disclosures, complemented by interviews with fleet maintenance directors, MRO procurement officers, platform engineers, and regulatory compliance leads. Secondary validation drew from airline annual reports, DGCA circulars, and cloud infrastructure provider technical documentation. Bottom-up segment sizing triangulated against top-down market envelope analysis.
Historical trend analysis cross-referenced against expert panel input across product type, deployment model, and end-user vertical dimensions. The analytical framework modeled software solutions, cloud platforms, data analytics tools, and mobile applications across on-premise, cloud-based, hybrid, and SaaS architectures throughout the forecast period. Aerospace, energy, manufacturing, and automotive verticals shaped demand segmentation. CAGRs derived from algorithmic curve fitting against disclosed platform procurement timelines and regulatory mandate effective dates.
Caveats apply where cybersecurity framework maturation for operational technology or legacy system integration cost overruns could materially shift the outlook. Forecasts reflect assumptions regarding regulatory alignment pace and cloud migration timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Maintenance and MRO Solutions
Gas Turbine MRO Market
Aircraft Maintenance and MRO Solutions
Europe Aircraft Engine MRO Market
Aircraft Maintenance and MRO Solutions
Global Aerospace Maintenance Chemical Market
Aircraft Maintenance and MRO Solutions
United States Airframe MRO Market
Aircraft Maintenance and MRO Solutions
Regional Turboprop Engine MRO Services Market
Aircraft Maintenance and MRO Solutions
Aviation Asset Management Market
Aircraft Maintenance and MRO Solutions
Aerospace and Defense MRO Market
Aircraft Maintenance and MRO Solutions
Asia-Pacific Aircraft Engine MRO Market
Aircraft Maintenance and MRO Solutions
Narrowbody Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Line Maintenance Market
Aircraft Maintenance and MRO Solutions
Middle-East and Africa Aircraft Engine MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Storage, Preservation and Reactivation Services Market
Aircraft Maintenance and MRO Solutions
Middle-East Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
On-Premises MRO Software Market
Aircraft Maintenance and MRO Solutions
Europe Aircraft MRO Market