
 Global Aircraft Windows and Windshields Market | 2026-2036
Global Aircraft Windows and Windshields Market Size, Share, and Industry Trends Forecast 2026-2036
Global Aircraft Windows and Windshields Market Intelligence
The historical separation between airline-captive Maintenance Repair Organizations and third-party maintenance providers is collapsing, creating new procurement dynamics. PPG Industries, Inc. leverages its material science expertise to supply both original equipment manufacturer and aftermarket channels. GKN Aerospace sustains its market position through deep integration with commercial airliner production lines. Saint-Gobain Aerospace differentiates with its specialized windshield and canopy solutions for military and business jet applications.
Aircraft windows and windshields are multi-layered transparent structures engineered to withstand extreme pressure differentials and bird strikes, often incorporating acrylic or polycarbonate plies. Their primary purpose is to provide clear visibility for pilots and passengers while ensuring cabin structural integrity. Polycarbonate materials lead in applications requiring high impact resistance, such as for military aircraft and helicopters. The commercial airliners segment constitutes the largest application by volume, driven by constant replacement cycles in the global fleet.
Product certification is governed by stringent airworthiness authorities, including the FAA in the United States and the European Union Aviation Safety Agency. These bodies mandate rigorous testing for impact resistance, optical clarity, and material durability, directly shaping design and manufacturing protocols. Future profitability for stakeholders is linked to their ability to navigate complex certification pathways for new materials while managing aftermarket supply chain logistics.
Market Dynamics
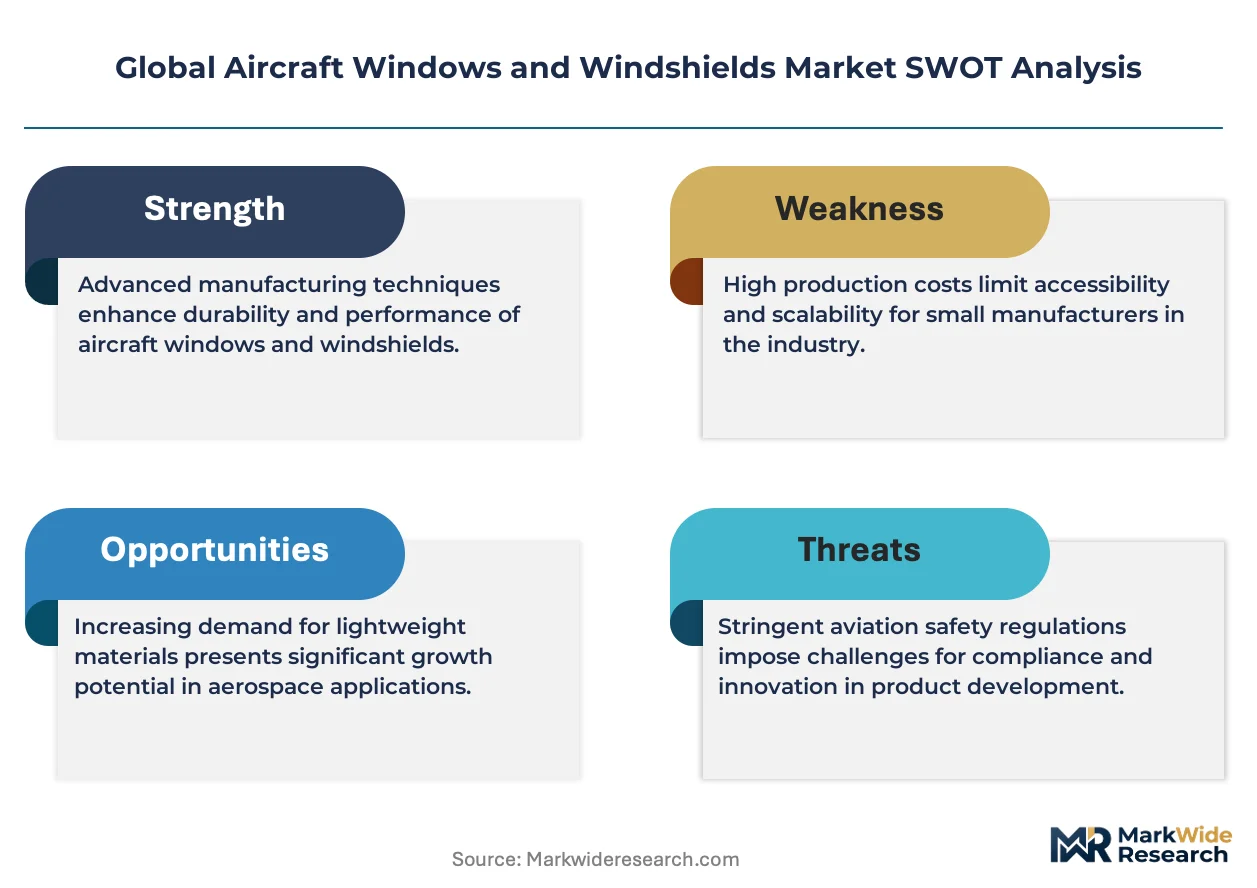
The central dynamic shaping the aircraft windows and windshields market is the tension between the slow, rigorous certification process for new materials and the urgent aftermarket demand for cost-effective, readily available replacement parts for existing global fleets.
Growth Catalysts
- Advanced Composites:The development and airworthiness certification of lightweight, multi-layered composite laminates incorporating polycarbonate and advanced acrylics are enabling stronger, more impact-resistant transparencies for new aircraft programs.
- Business Aviation Expansion:Demand from the business and private jet sector, particularly for larger cabin windows and advanced cockpit windshields with integrated systems, provides a high-margin growth avenue for manufacturers.
- Fleet Modernization:Airlines in fast-growing aviation markets, such as India and across Southeast Asia, are expanding and modernizing their fleets, creating a consistent order book for both line-fit and initial provisioning spares.
Market Restraints
- Certification Timelines:The stringent and lengthy certification pathways mandated by airworthiness authorities like the FAA and EASA for any new material or significant design modification can delay market entry for innovations by several years.
- Raw Material Costs:Volatility in the price of specialized raw materials, particularly aerospace-grade polycarbonate and cast acrylic sheet, directly impacts manufacturer margins and can lead to price increases for end-users.
- Manufacturing Concentration:Production of high-performance transparencies is concentrated in established aerospace manufacturing clusters in the United States and France, creating supply chain vulnerabilities and logistical complexities.
Strategic Opportunities
- Smart Glass Integration:The development of electronically dimmable windows (EDWs) offers a significant opportunity to enhance passenger experience and improve cabin thermal management, with strong interest from premium commercial airlines.
- Urban Air Mobility:The emerging Urban Air Mobility (UAM) vehicle segment requires novel, lightweight, and bird-strike-resistant canopies and windows, creating an entirely new application area for specialized transparency solutions.
- MRO in the Middle East:Establishing MRO and repair capabilities in the Middle East presents a major opportunity to serve the large, modern fleets of Gulf carriers, reducing turnaround times and shipping costs for high-turnover components.
Industry Challenges
- Skilled Labor Scarcity:A shortage of technicians with the specialized skills required for the precise installation, polishing, and repair of advanced composite transparencies poses a significant operational challenge for MRO providers.
- Systems Integration Complexity:Embedding de-icing, de-fogging, and heads-up display (HUD) systems into windshields without compromising optical clarity or structural integrity is a persistent engineering and manufacturing challenge.
- Material Compliance:Adhering to evolving chemical regulations, such as the EU's REACH framework, requires constant reformulation and recertification of coatings, sealants, and interlayer materials used in window assemblies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Aircraft Windows and Windshields Market |
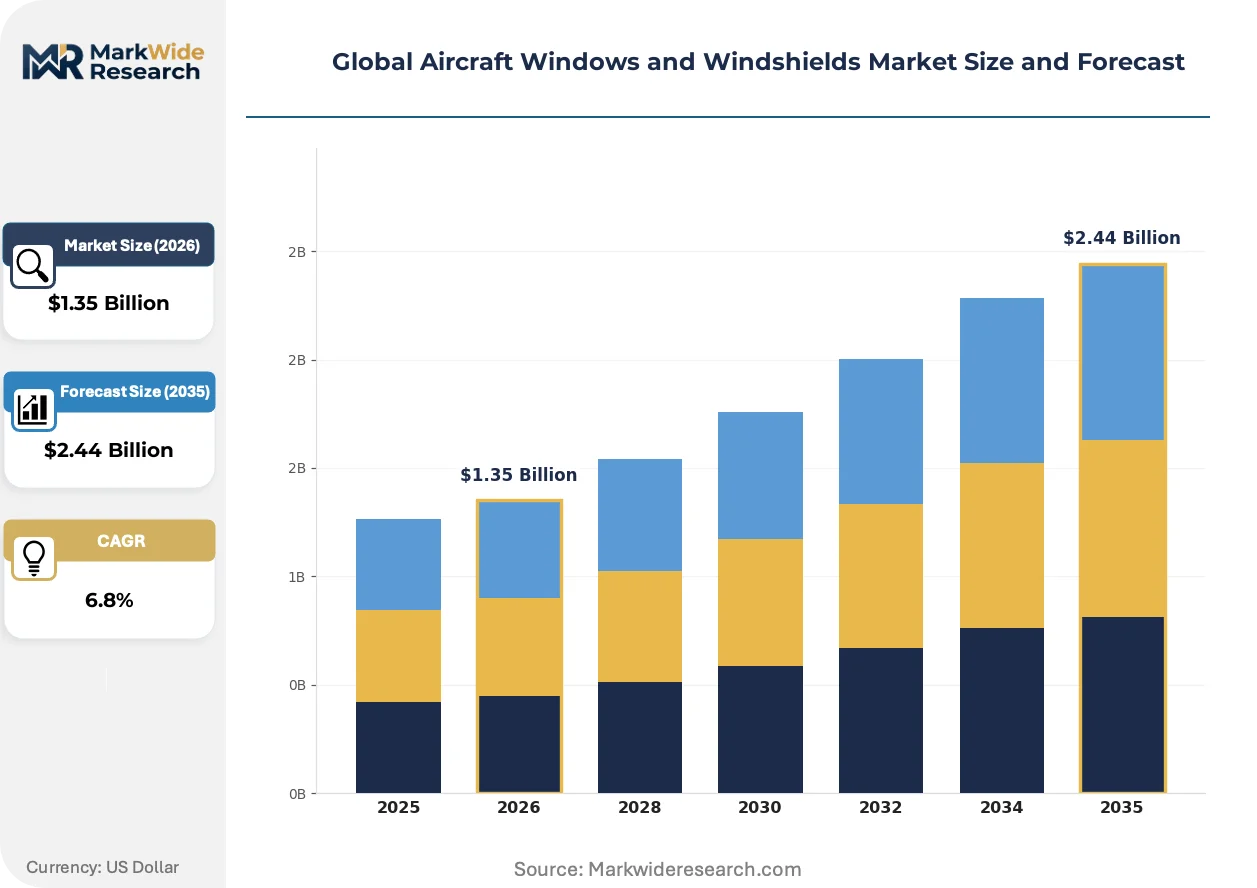
| Market Size in 2026 | $1.35 Billion |
| Market Size in 2035 | $2.44 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Windows, Operable Windows, Windshields, Cabin Windows, Canopy Windows Material Type: Acrylic, Polycarbonate, Laminated Glass, Tempered Glass, Composite Laminates Application: Commercial Airliners, Business Jets, Military Aircraft, Helicopters, Unmanned Aerial Vehicles End User: Aircraft Manufacturers, Maintenance Repair Organizations, Airlines, Defense Forces, Charter Operators |
| Companies Covered | PPG Industries, Inc., GKN Aerospace, Saint-Gobain Aerospace, Gentex Corporation, The NORDAM Group LLC, Lee Aerospace, Control Logistics Inc., Llamas Plastics Inc., LP Aero Plastics Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Aircraft Windows and Windshields Market Strategic Shifts & Innovations
Material science advancements are running parallel to shifts in aftermarket service models. This creates a dual track of innovation, with one focused on next-generation airframe performance and the other on optimizing the lifecycle cost of the existing global fleet.
Polycarbonate composite laminates offer superior impact strength and weight reduction over traditional glass-acrylic constructions. Military aircraft and business jet programs are the primary adopters, driven by stringent performance and survivability requirements. This advanced material composition is displacing heavier, less resilient multi-ply glass designs in forward-fit applications where structural performance is paramount.
The European Union Aviation Safety Agency (EASA) is placing greater emphasis on the sustainability and circularity of aircraft components. This regulatory pressure encourages research into recyclable thermoplastics and bio-based adhesives for window and windshield assemblies. The commercial airliner segment is most affected due to its high volume of replacement parts, compelling suppliers to investigate more environmentally responsible manufacturing processes.
A consolidation among third-party Maintenance, Repair, and Overhaul (MRO) organizations is altering how airlines procure aftermarket transparencies. Large MRO networks increasingly use their purchasing power to secure direct, high-volume supply contracts from manufacturers, bypassing traditional distribution channels. This pattern is most visible in the mature aviation markets of North America and Europe, which have a substantial and predictable demand for replacement windows.
Global Aircraft Windows and Windshields Market Segmentation
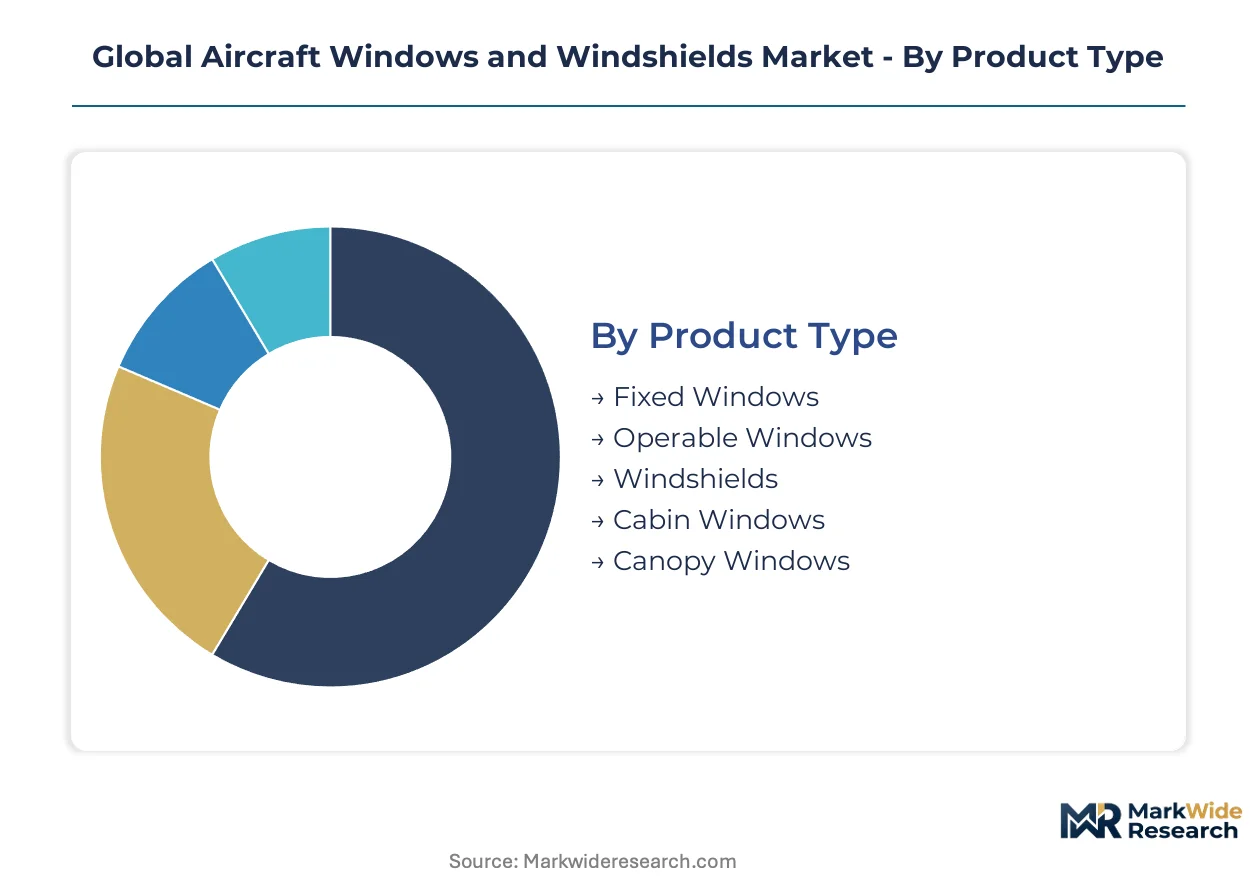
The Global Aircraft Windows and Windshields market segments according to distinct product types, material compositions, application areas, and end-user profiles. Understanding these divisions is crucial for manufacturers to align product development with specific performance requirements and for suppliers to optimize their distribution strategies across varied demand centers.
Product Type:
Segments within product type face varying degrees of material substitution, influencing design innovation and material choices for transparencies.
- Windshields:Multi-layered transparent structures for flight deck visibility, engineered to withstand extreme pressure differentials, bird strikes, and thermal cycling. Demand concentrates in new commercial airliner programs and business jets requiring advanced optical clarity and integrated heating systems.
- Cabin Windows:Transparent panels providing passenger visibility and maintaining cabin structural integrity, often incorporating acrylic or polycarbonate plies. Consistent replacement cycles in the global commercial fleet drive demand, particularly in expanding aviation markets like India and Southeast Asia.
- Fixed Windows:Non-opening transparent panels, primarily utilized in passenger cabins for structural integrity and light transmission.
- Operable Windows:Windows designed to open, typically found in smaller aircraft or emergency exits, offering ventilation or egress capabilities.
- Canopy Windows:Specialized transparent enclosures for military aircraft and helicopters, providing pilots with wide-angle visibility and ballistic protection.
Windshields anchor the volume base while Cabin Windows gain share at the steepest rate due to fleet expansion in high-growth regions.
Material Type:
Material type segmentation highlights the diverse performance requirements across aircraft applications, from high-impact resistance to optical clarity and weight reduction.
- Polycarbonate:A thermoplastic polymer offering superior impact resistance and lightweight properties, crucial for military aircraft and helicopter transparencies. Demand is pronounced in applications requiring enhanced survivability against bird strikes and ballistic threats.
- Composite Laminates:Multi-layered structures combining various materials like polycarbonate and advanced acrylics, providing enhanced strength-to-weight ratios. New aircraft programs seeking lighter and stronger transparencies drive adoption, particularly in business jet and military sectors.
- Acrylic:Transparent plastic used for cabin windows and some windshields, valued for its optical clarity and ease of forming.
- Laminated Glass:Multiple layers of glass bonded with interlayers, offering strength and shatter resistance for critical windshield applications.
- Tempered Glass:Heat-treated glass with increased strength, used in specific window applications where thermal and mechanical resistance are important.
Material innovation is concentrating on advanced solutions, with composite laminates seeing significant development for next-generation aircraft designs.
Application:
Application segments delineate distinct customer-specific requirements, influencing design specifications and certification pathways for aircraft transparencies.
- Commercial Airliners:The largest application segment by volume, driven by the sheer number of aircraft and constant replacement cycles for cabin windows and windshields. Stringent airworthiness regulations by bodies like the FAA and EASA necessitate durable, high-performance transparencies.
- Business Jets:A high-margin segment demanding larger cabin windows and advanced cockpit windshields, often incorporating integrated systems like heating and electronically dimmable features. Customization and premium aesthetics are significant considerations for manufacturers.
- Military Aircraft:Requires highly durable and impact-resistant transparencies, including specialized canopies and windshields for combat and surveillance platforms.
- Helicopters:Utilizes polycarbonate plies for high impact resistance, particularly for bubble windows and cockpit transparencies in demanding operational environments.
- Unmanned Aerial Vehicles:An emerging application for lightweight, robust transparencies, crucial for sensor integration and aerodynamic efficiency in diverse operational roles.
Growth in the global fleet underpins demand across mature segments like commercial airliners and emerging areas such as unmanned aerial vehicles.
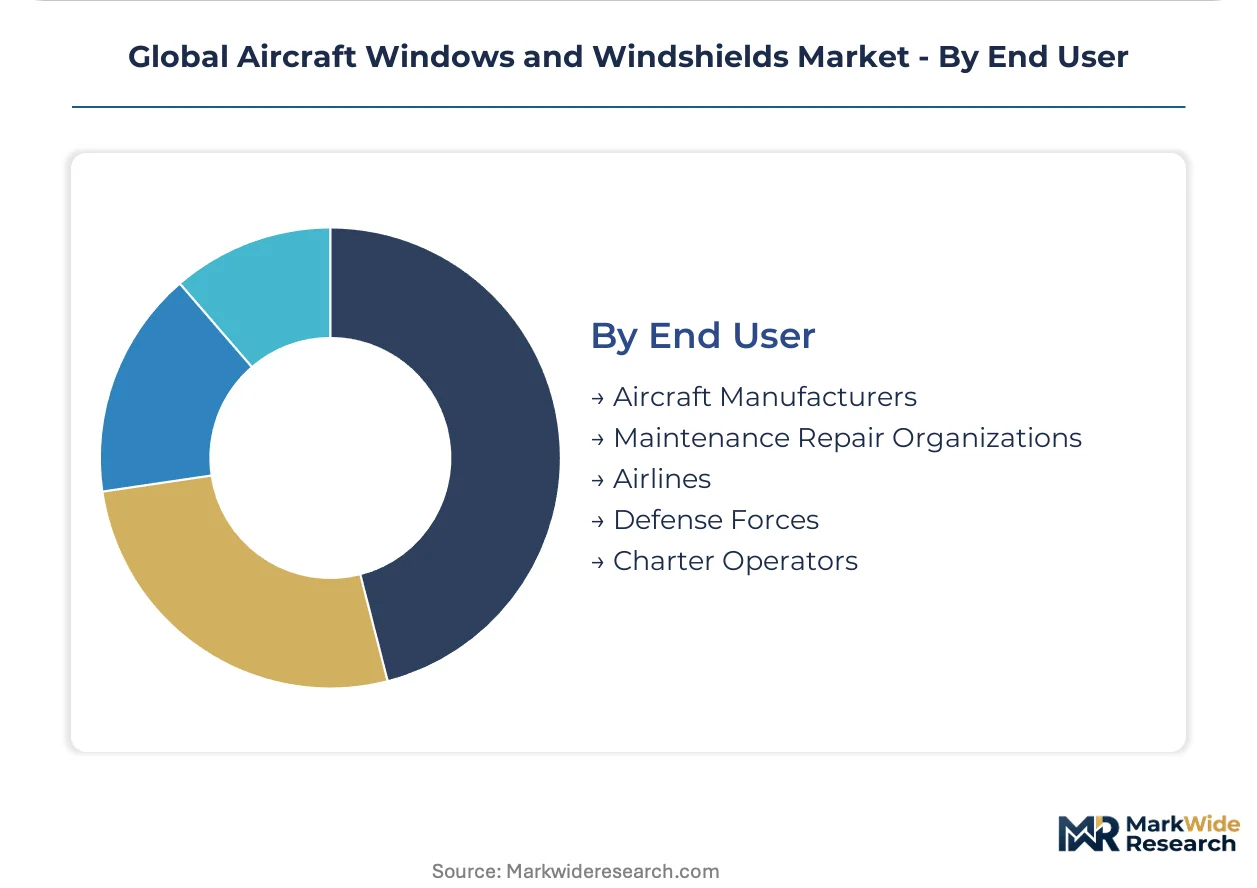
End User:
End-user categories reflect distinct procurement dynamics, ranging from large-volume original equipment supply to specialized aftermarket service contracts.
- Aircraft Manufacturers:These entities procure transparencies for new aircraft production and initial provisioning spares, requiring rigorous quality control and seamless integration with airframe designs. Long-term supply agreements are common for major programs.
- Maintenance Repair Organizations:MROs provide aftermarket replacement and repair services for existing fleets, sourcing transparencies to meet operational demands and reduce aircraft downtime. Consolidation among third-party MROs influences purchasing power.
- Airlines:Directly procure transparencies for their fleet maintenance, often through MROs or direct contracts with manufacturers for specific parts.
- Defense Forces:Acquire specialized, high-performance transparencies for military aircraft, prioritizing impact resistance and survivability for operational readiness.
- Charter Operators:Purchase transparencies for their smaller, often business jet fleets, emphasizing quick turnaround times and access to specialized parts.
The evolution of aftermarket service models is reshaping supply relationships, particularly between MROs and direct manufacturers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global aerospace manufacturing infrastructure, particularly in established clusters, underwrites the demand for aircraft windows and windshields. Manufacturing capabilities and regulatory frameworks significantly influence market dynamics across different regions. Procurement patterns for both original equipment and aftermarket parts vary by geography, reflecting fleet age and MRO network maturity.
United States
Demand for advanced cockpit windshields and business jet cabin windows drives the market in the United States. The Federal Aviation Administration (FAA) mandates rigorous certification for all transparencies, shaping design and material choices. Aerospace manufacturing hubs in Wichita, Kansas, and Seattle, Washington, concentrate production and MRO activities for both commercial and general aviation.
France
Commercial airliner production lines and military aircraft programs sustain a significant portion of the French market. The European Union Aviation Safety Agency (EASA) enforces strict airworthiness standards for all aircraft components, including windows and windshields. Toulouse, a major aerospace center, serves as a focal point for both manufacturing and aftermarket support for large commercial fleets.
India
Fleet modernization initiatives and expanding commercial aviation markets generate consistent demand for cabin windows and replacement parts in India. The Directorate General of Civil Aviation (DGCA) oversees airworthiness requirements and maintenance protocols for the country's rapidly growing fleet. Bengaluru and Hyderabad are emerging as key MRO and aerospace component manufacturing centers, attracting investment.
China
New aircraft programs and the expansion of domestic airlines contribute to the market for aircraft transparencies in China. The Civil Aviation Administration of China (CAAC) regulates the design, production, and maintenance of all aircraft within its jurisdiction. Major aerospace industrial parks in Xi'an and Shanghai are developing capabilities for both original equipment and aftermarket supply.
Global Aircraft Windows and Windshields Market Key Industry Players
Concentration sits with large, vertically integrated material science companies and specialized aerospace component manufacturers. The market structure exhibits a tiered approach, with a few dominant players supplying both OEM and MRO channels. Strategic partnerships and continuous investment in advanced material research are common competitive moves within this sector.
Within the material science and integrated solutions tier, PPG Industries, Inc. leverages its extensive expertise to serve a broad customer base. GKN Aerospace exemplifies a leading position through deep integration with major commercial airliner production lines. Saint-Gobain Aerospace occupies a specialized niche, anchoring its market presence with advanced windshield and canopy solutions for military and business jet applications.
| Leading Market Players |
|---|
| PPG Industries, Inc. |
| GKN Aerospace |
| Saint-Gobain Aerospace |
| Gentex Corporation |
| The NORDAM Group LLC |
| Lee Aerospace |
| Control Logistics Inc. |
| Llamas Plastics Inc. |
| LP Aero Plastics Inc. |
| Others |
Cost & Logistics Intelligence
Long-term supply agreements, common in the aerospace industry, lock in both supply access and price visibility for aircraft windows and windshields. These contracts stabilize procurement for manufacturers and MROs, mitigating raw material cost fluctuations.
Pricing Analysis
Volume-based pricing structures dominate procurement for aircraft transparencies, reflecting the scale of commercial airliner fleets. Price differentiation stems from rigorous FAA and EASA certification levels, customization for business jets, and bundled after-sales service. Pricing softness reflects intense competition for aftermarket MRO contracts and volatile raw material costs. Airlines exhibit high price sensitivity for replacement cabin windows, while military and business jet operators prioritize performance and rapid availability.
Supply Chain Analysis
Maintaining optimal inventory levels and managing lead times is critical for aircraft window and windshield suppliers, given the lengthy certification process. Geographic supply concentration centers on established aerospace manufacturing clusters in the United States and France. The industry relies on specialized aerospace-grade polycarbonate and cast acrylic sheet. Manufacturing concentration creates single-source vulnerability for certain high-performance components. Distribution runs through direct channels to aircraft manufacturers and increasingly through consolidated MRO networks for aftermarket parts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is experiencing a significant buyer power shift, driven by the consolidation of third-party Maintenance, Repair, and Overhaul (MRO) organizations. These larger MRO networks exert greater purchasing influence over transparency suppliers.
For Market Incumbents: Fortify core OEM relationships through joint material development programs, particularly for advanced composite laminates. Expand MRO capabilities in high-growth regions like the Middle East to counter emerging regional suppliers. The threat of new material certification delays necessitates continuous R&D investment in next-generation polycarbonate and acrylic formulations. Control over aftermarket distribution channels remains a critical lever.
For New Entrants and Emerging Players: A focused certification fast-track for specific material applications, such as lightweight canopies for Urban Air Mobility (UAM) vehicles, presents a viable entry point. Target the specialized military and business jet segments with high-impact polycarbonate solutions. Emphasize rapid prototyping and agile manufacturing processes to differentiate from established players. Go-to-market via direct partnerships with smaller airframe manufacturers or specialized MROs.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialized MRO providers with established long-term service contracts for commercial fleets. Long-term viability depends on exposure to fleet modernization cycles in Asia and the integration of smart glass technologies. Target acquisition archetypes include niche material science firms developing sustainable thermoplastics or MROs with strong regional presence. The signal to watch is the pace of EASA and FAA approvals for new transparency materials.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Secures long-term supply for new aircraft programs and reduces lead times for critical components. |
| R&D Investment | Enhances product performance for military aircraft and business jet applications. |
| MRO Network Expansion | Improves aftermarket service delivery for Gulf carriers and reduces logistical costs. |
| Strategic Partnership | Captures premium segment demand from commercial airlines for electronically dimmable windows. |
| Certification Pathway Development | Addresses regulatory pressure for circularity in commercial airliner components. |
Research Approach
Findings reconcile primary fieldwork against secondary review of regulatory filings, industry reports, and company financial statements. This involved in-depth interviews with aerospace component manufacturers, MRO executives, airline procurement managers, and material science experts. Secondary validation included data from the FAA, EASA, and ICAO, alongside academic research. A bottom-up approach estimated market size from granular segment data, cross-referenced with top-down industry aggregates.
Segmentation dimensions modeled include product type, material composition, application, and end-user profile, with a specific focus on regional fleet modernization rates. The analytical framework projects market trajectories over the projection horizon. Compound Annual Growth Rates were derived from historical trends and expert projections. Key forecast inputs included new aircraft delivery schedules and aircraft retirement rates.
Underlying assumptions cover stable geopolitical conditions and consistent regulatory enforcement, with deviation risk concentrated in raw material supply disruptions and unforeseen airworthiness authority mandates. These forecasts reflect current market conditions and anticipated industry developments. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft and Aerospace Components
Helicopter Blades Market
Aircraft and Aerospace Components
South America Rotor Blade Market
Aircraft and Aerospace Components
Aerospace Parts Manufacturing Market
Aircraft and Aerospace Components
Composite Flap Track Fairing Systems for Drag Reduction Market
Aircraft and Aerospace Components
Europe Aerospace and Defense Market
Aircraft and Aerospace Components
Aircraft Brackets Market
Aircraft and Aerospace Components
Solenoid Valves in Aerospace Market
Aircraft and Aerospace Components
Cold Gas Thrusters Market
Aircraft and Aerospace Components
Rotary Wing Aircraft Rivets Market
Aircraft and Aerospace Components
Advanced Turbine Blade Design Market
Aircraft and Aerospace Components
Aircraft Insulation Market
Aircraft and Aerospace Components
Commercial Aircraft Turbine Blades and Vanes Market
Aircraft and Aerospace Components
Aircraft Wiring Harness Market
Aircraft and Aerospace Components
Aerospace and Defense C-Class Parts Market
Aircraft and Aerospace Components
Heat Shield Market
Aircraft and Aerospace Components
Composite Winglet and Sharklet Structures Market