
 Commercial Aircraft Lighting Market | 2026-2036
Commercial Aircraft Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Aircraft Lighting Market Analysis
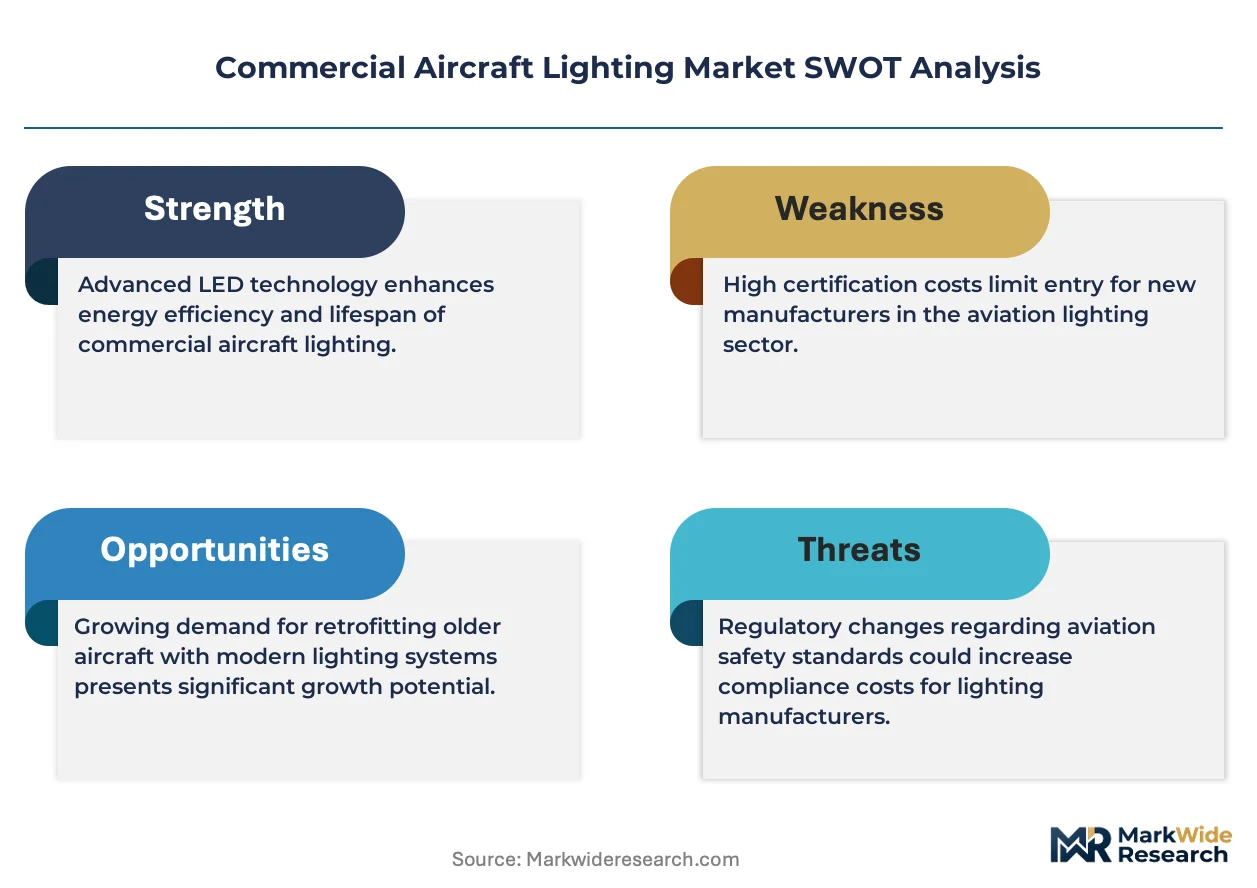
Modular lighting system bundling is pivoting buyer choice away from standalone component procurement toward integrated cabin packages. Collins Aerospace leverages its avionics heritage to bundle intelligent lighting with flight-deck systems, creating captive demand across OEM channels. Diehl Stiftung & Co. KG sustains manufacturing scale through in-house production of LED drivers and optical assemblies. Honeywell International Inc. anchors its position in emergency lighting through regulatory-certified power architectures.
Commercial aircraft lighting encompasses illumination systems engineered for cockpit, cabin, and exterior applications, typically operating on 28 VDC bus architectures with chromaticity coordinates calibrated to SAE ARP4103 standards. These systems serve critical functions spanning pilot situational awareness, passenger comfort modulation, and airframe visibility compliance. LED technology dominates new installations due to lumen-per-watt efficiency and reduced heat loads, while halogen retains a residual niche in legacy platform sustainment. Intelligent lighting represents the fastest-expanding technology segment as airlines deploy circadian-rhythm programming to reduce passenger jetlag on long-haul routes. Cabin lighting commands the largest application margin pool, driven by premium-class differentiation and retrofit cycles.
FAA airworthiness directives and EASA CS-25 certification requirements shape product standards by mandating redundant emergency illumination paths and specific color-temperature ranges for flight-deck readability. The EU AI Act and emerging cybersecurity frameworks are beginning to influence connected lighting architectures as data-enabled cabin systems proliferate. Stakeholders must monitor regulatory divergence between FAA and EASA on smart-lighting software validation, as dual-certification costs will determine competitive viability in transatlantic supply chains.
Market Dynamics
LED obsolescence mandates from the FAA are compressing replacement cycles across narrow-body fleets, forcing operators to accelerate cabin modernization timelines and reshaping supplier contracting patterns toward bundled system procurement.
Growth Catalysts
- FAA Airworthiness Directives:Burn-time reliability standards for emergency illumination are mandating technology refreshes across aging aircraft, creating replacement demand independent of fleet expansion.
- Circadian-rhythm programming:Long-haul carriers are deploying intelligent lighting systems to reduce passenger jetlag, opening premium cabin differentiation opportunities.
- Narrow-body retrofit intensity:United States-based MRO networks are driving specification upgrades as airlines modernize aging cabins to extend airframe economic life.
Market Restraints
- Dual-certification cost burden:Divergent FAA and EASA validation requirements for smart-lighting software are inflating development timelines and compliance overhead for transatlantic suppliers.
- LED driver supply concentration:In-house production capabilities at major tier-one manufacturers limit second-source availability for specialized optical assemblies.
- Halogen residual lock-in:Legacy platform sustainment requirements preserve incumbent technology footprints, constraining pure-play LED penetration in certain retrofit segments.
Strategic Opportunities
- Cybersecurity framework integration:The EU AI Act is creating certification pathways for data-enabled cabin systems, rewarding early movers in connected lighting architectures.
- Flight-deck avionics convergence:Bundling intelligent cabin lighting with cockpit systems is electrifying new OEM specification channels and creating captive demand.
- Emergency power architecture specialization:Regulatory-certified redundant illumination paths present margin expansion opportunities for suppliers with certified power management expertise.
Industry Challenges
- Software validation timelines:EASA CS-25 certification requirements for chromaticity calibration and emergency-path redundancy are extending product qualification cycles.
- Legacy system integration friction:28 VDC bus architectures in aging airframes constrain intelligent lighting retrofit options without substantial electrical system modification.
- Talent scarcity in optical engineering:Specialized expertise in SAE ARP4103 chromaticity standards and thermal management for LED assemblies is concentrating at established suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Aircraft Lighting Market |
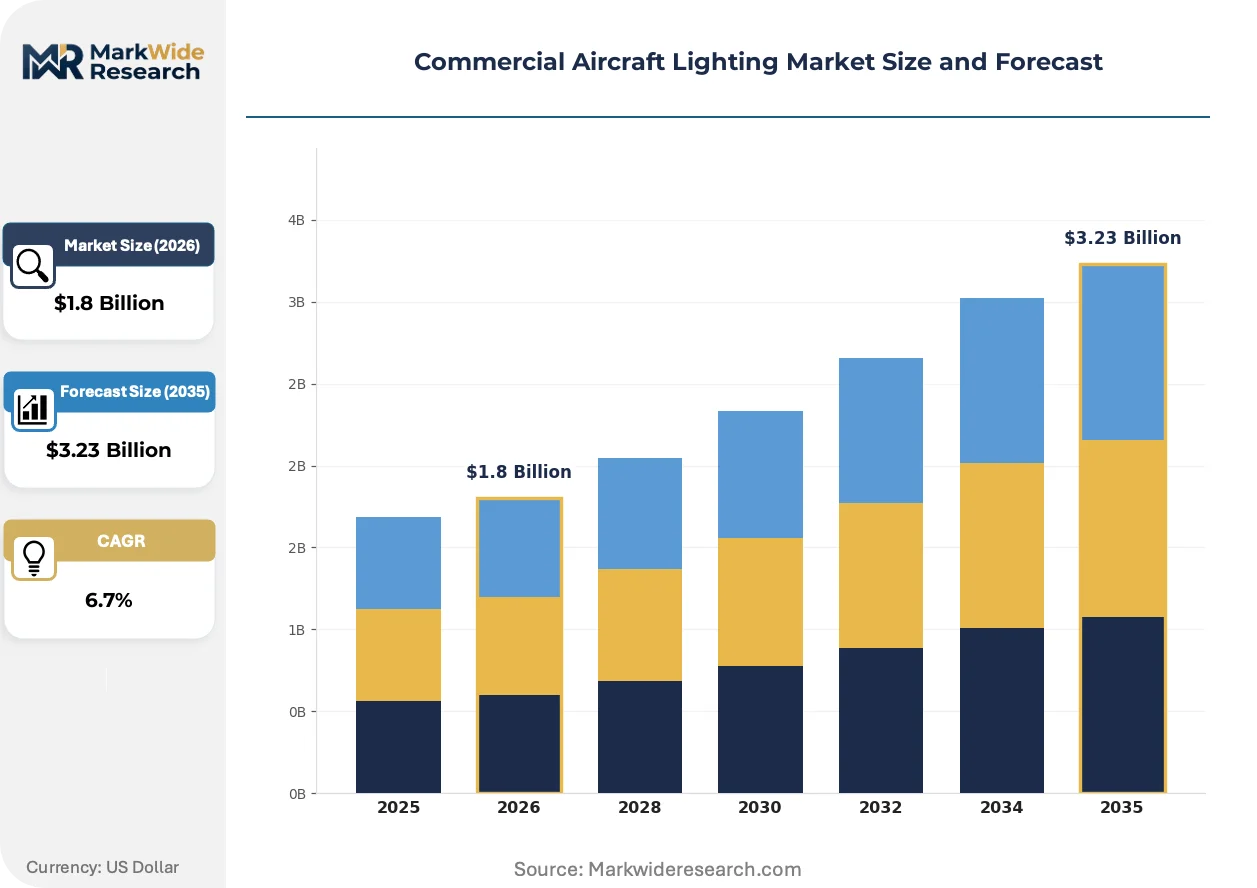
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, Halogen, Xenon, Fluorescent Technology: Intelligent Lighting, Emergency Lighting, Ambient Lighting, Navigation Lighting Application: Cockpit Lighting, Cabin Lighting, Exterior Lighting, Specialty Lighting End User: Commercial Airlines, Charter Services, Cargo Operators, Aircraft Manufacturers |
| Companies Covered | Astronics Corporation, Luminator Technology Group, Collins Aerospace, Soderberg Manufacturing Company Inc., Honeywell International Inc., STG Aerospace, Diehl Stiftung & Co. KG, SCHOTT AG, Safran, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Aircraft Lighting Market Emerging Trajectories
Intelligent lighting architectures are electrifying competitive positioning across the commercial aircraft cabin, compressing the traditional component supply model into integrated system packages.
Human-centric LED programming is electrifying passenger experience differentiation on long-haul routes. Airlines operating transpacific and transatlantic services are adopting tunable white-light systems that modulate color temperature across flight phases. This capability is electrifying premium cabin configuration decisions and reshaping supplier selection criteria toward software-enabled platform providers.
The EU AI Act is imposing algorithmic transparency requirements on connected cabin systems. European operators must now document decision logic for lighting automation that interacts with passenger data. This regulatory overlay is electrifying compliance investments among lighting OEMs seeking EASA validation for intelligent product lines.
Airline technical procurement teams are consolidating vendor relationships around full-cabin lighting packages. Component-level sourcing is giving way to system-of-systems contracting that bundles illumination with control software and installation support. United States major carriers are driving this consolidation, using fleet-scale retrofit programs to extract architectural commitments from tier-one suppliers.
Commercial Aircraft Lighting Market Segmentation
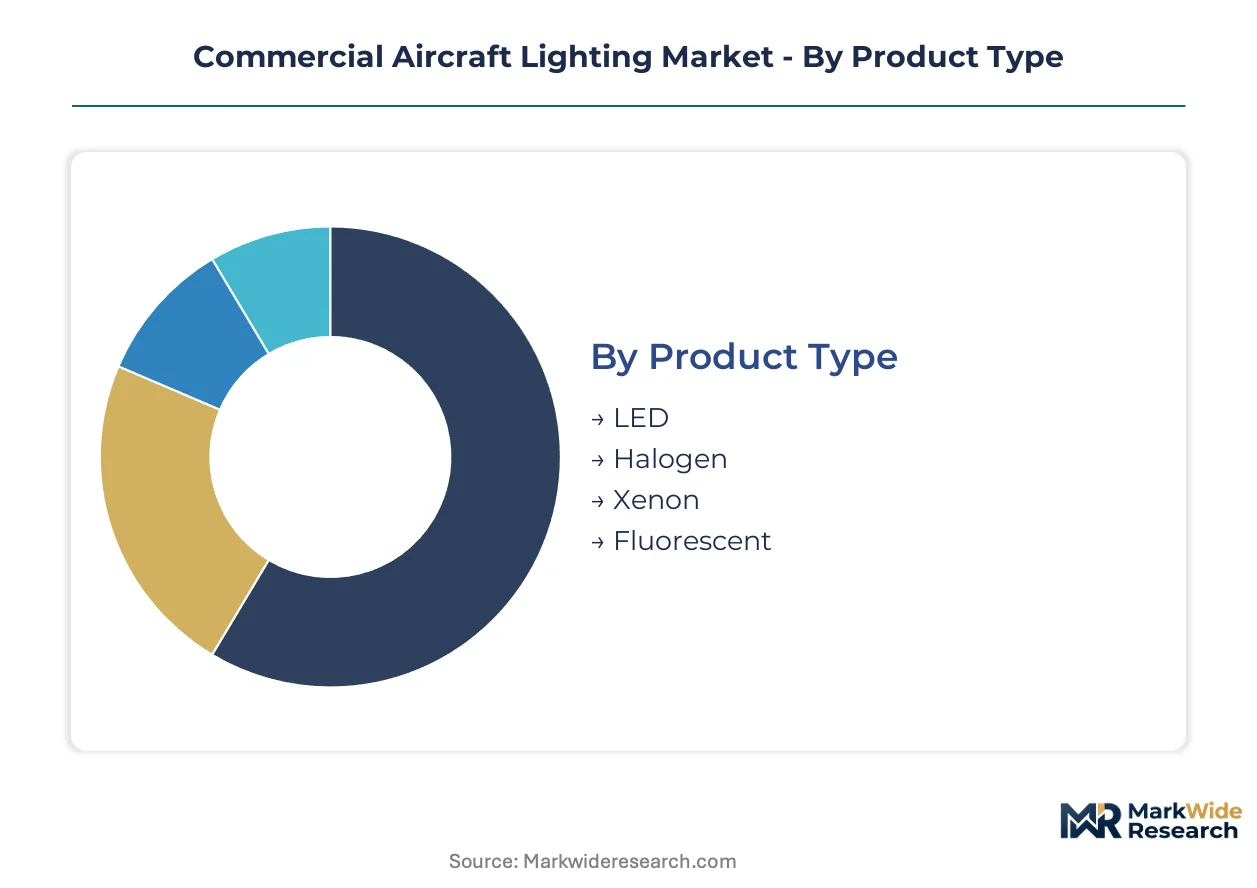
Segmentation in commercial aircraft lighting reveals how technology maturity, regulatory pressure, and fleet renewal cycles concentrate revenue across distinct product and application categories. Understanding these splits enables suppliers to align R&D investment with replacement-driven demand versus OEM specification capture.
Product Type:
LED systems command premium positioning against legacy alternatives, while halogen retains residual volume in sustainment markets.
- LED:Solid-state illumination operating on 28 VDC bus architectures with chromaticity calibrated to SAE ARP4103 standards. Narrow-body retrofits in the United States are accelerating specification upgrades as FAA airworthiness directives mandate burn-time reliability improvements.
- Halogen:Tungsten-filament technology operating at higher thermal loads with shorter service intervals. Aging fleet sustainment requirements in cargo operations preserve incumbent footprints where electrical system modification costs outweigh LED conversion economics.
- Xenon:High-intensity discharge systems delivering concentrated lumen output for exterior visibility applications.
- Fluorescent:Legacy gas-discharge technology retained in specific wide-body configurations where thermal management constraints favor established installations.
Today's leader: LED. Tomorrow's challenger: Xenon in specialized exterior applications.
Technology:
Intelligent systems are climbing the fastest as circadian-rhythm programming opens premium cabin differentiation, while emergency lighting anchors regulatory-mandated replacement demand.
- Intelligent Lighting:Software-enabled architectures with tunable white-light modulation across flight phases. Long-haul carriers operating transpacific routes are deploying chromaticity programming to reduce passenger jetlag and capture premium fare premiums.
- Emergency Lighting:Redundant illumination paths with battery-backed power architectures certified to FAA and EASA CS-25 requirements. United States MRO networks are driving specification refreshes as airworthiness directives compress replacement cycles independent of fleet expansion.
- Ambient Lighting:Mood-oriented cabin illumination systems enhancing passenger experience differentiation in premium class configurations.
- Navigation Lighting:Exterior visibility systems ensuring airframe compliance with ICAO Annex 2 operational requirements.
Intelligent lighting is expanding most quickly. Emergency lighting maintains the steadiest replacement-driven revenue base.
Application:
Cabin applications concentrate margin pools through premium-class configuration decisions, while cockpit systems anchor OEM specification relationships.
- Cabin Lighting:Passenger-facing illumination spanning mood, reading, and accent functions across seat classes. Major United States carriers are bundling full-cabin packages to extract architectural commitments from tier-one suppliers during fleet-scale retrofit programs.
- Cockpit Lighting:Flight-deck illumination with color-temperature ranges optimized for pilot situational awareness and night-vision compatibility. OEM channels favor integrated procurement alongside avionics systems.
- Exterior Lighting:Wingtip, landing, and anti-collision systems ensuring visibility compliance during ground and flight operations.
- Specialty Lighting:Cargo hold, galley, and lavatory applications with distinct thermal and durability specifications.
Cabin lighting commands the largest margin pool. Cockpit lighting offers the strongest OEM specification lock-in.
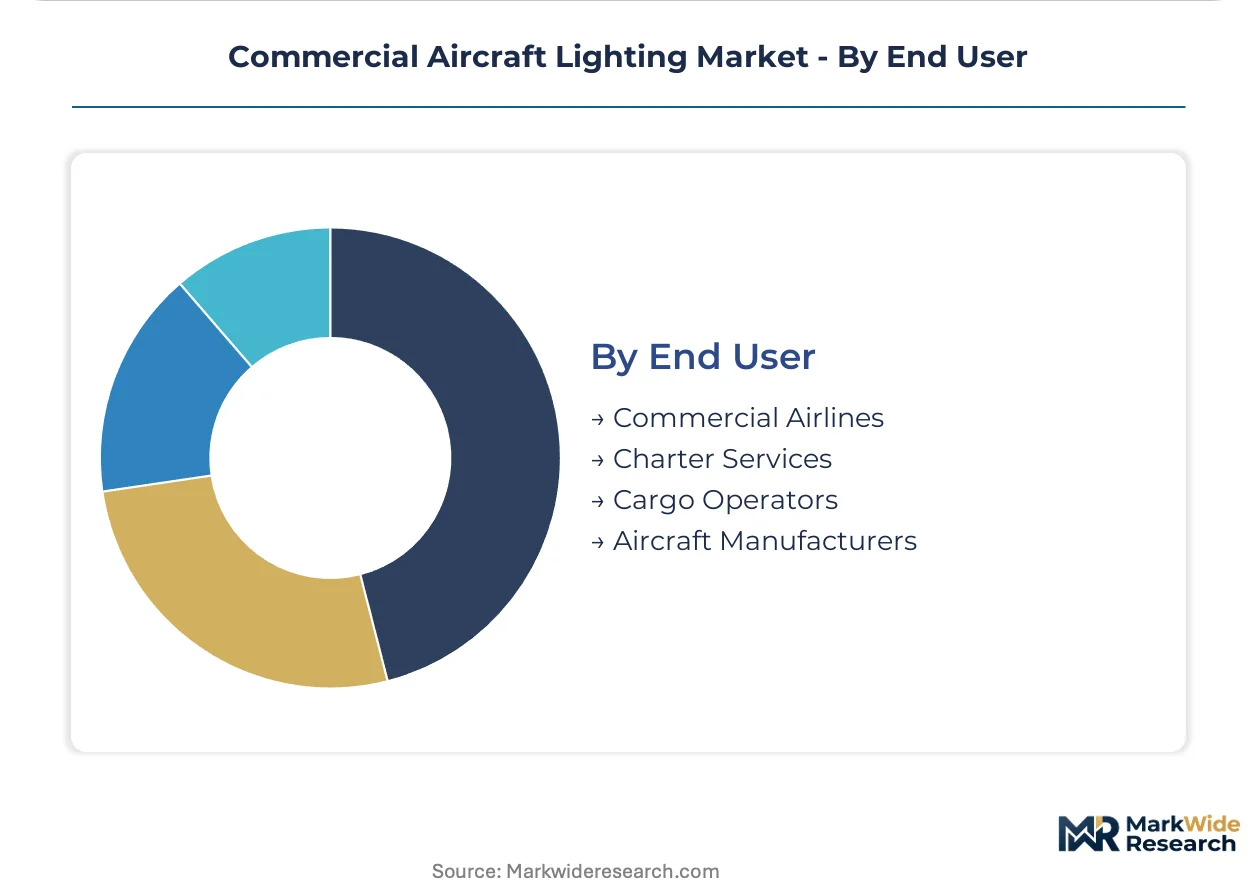
End User:
Commercial airlines drive retrofit intensity through narrow-body modernization, while aircraft manufacturers concentrate demand in OEM specification windows.
- Commercial Airlines:Scheduled passenger operators managing fleet-wide cabin refresh cycles to extend airframe economic life. United States-based networks are accelerating LED conversions as FAA mandates compress technology refresh timelines.
- Aircraft Manufacturers:OEM specification channels for new production airframes, where bundled system procurement favors suppliers with integrated avionics-cabin offerings.
- Cargo Operators:Freighter fleet sustainment with cost-optimized procurement prioritizing reliability over passenger experience features.
- Charter Services:On-demand operators with fragmented fleet profiles and opportunistic upgrade timing.
Commercial airlines dominate retrofit-driven volume. Aircraft manufacturers control OEM specification access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial aircraft lighting emerged from post-war American aviation manufacturing, with early systems developed for Boeing and Douglas airframes in the 1950s. European capabilities crystallized around French and German aerospace clusters during the jet age. Asian production gravity formed later around Japanese precision electronics and emerging Chinese MRO networks.
United States
Narrow-body retrofit intensity drives specification upgrades as American Airlines, Delta, and United modernize aging 737 and A320 fleets. FAA airworthiness directives on LED burn-time reliability compress replacement cycles independent of new aircraft deliveries. Wichita, Kansas anchors a dense aerospace supplier cluster where Collins Aerospace and Honeywell maintain engineering and certification operations.
Germany
Diehl Stiftung & Co. KG sustains manufacturing scale through captive LED driver production at its Nuremberg-area facilities. EASA CS-25 certification requirements shape chromaticity standards for flight-deck readability across Lufthansa Group retrofit programs. Bavaria's aerospace corridor, stretching from Munich to Augsburg, concentrates optical engineering talent and regulatory validation expertise.
France
Safran leverages Toulouse's Airbus manufacturing proximity to capture OEM specification windows for A350 and A320neo programs. The country's national aviation regulator enforces redundant emergency illumination paths under CS-25 mandates. The Occitanie region hosts specialized testing laboratories for chromaticity calibration and thermal management validation.
United Kingdom
STG Aerospace maintains production facilities in Wales serving both retrofit and OEM channels across European carrier networks. British Airways and Virgin Atlantic drive intelligent lighting adoption for premium cabin differentiation on transatlantic routes. The Southwest England aerospace cluster around Bristol concentrates MRO engineering capabilities for legacy platform sustainment.
Japan
Japanese precision electronics manufacturers supply optical assemblies to tier-one integrators under long-term supply agreements. ANA and JAL deploy circadian-rhythm programming on transpacific routes, creating specification pull for tunable white-light systems. The Nagoya aerospace manufacturing zone, centered on Mitsubishi Heavy Industries, anchors component fabrication for regional jet programs.
Commercial Aircraft Lighting Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification depth and system integration capability. The vendor base organizes into three tiers: avionics-heritage integrators bundling flight-deck and cabin systems, specialized lighting OEMs with captive optical manufacturing, and component suppliers feeding assembly networks. Consolidation pressure runs through bundled procurement contracts from United States major carriers. Geographic expansion and strategic partnerships constitute the dominant competitive moves as suppliers seek dual FAA-EASA validation coverage.
Within the avionics-heritage tier, Collins Aerospace and Honeywell International Inc. occupy positions shaped by decades of flight-deck system integration. Diehl Stiftung & Co. KG exemplifies the specialized OEM archetype with its in-house control over LED driver and optical assembly production. Astronics Corporation sits within the component-to-system supplier segment, representing the scale-driven fabrication model common among North American aerospace electronics providers.
| Leading Market Players |
|---|
| Astronics Corporation |
| Luminator Technology Group |
| Collins Aerospace |
| Soderberg Manufacturing Company Inc. |
| Honeywell International Inc. |
| STG Aerospace |
| Diehl Stiftung & Co. KG |
| SCHOTT AG |
| Safran |
| Others |
Supply Flow & Price Mechanics
United States major carrier bundling of full-cabin lighting packages during fleet-scale retrofit programs is forcing tier-two suppliers toward subsystem specialization or exit, compressing margin pools for component-only vendors while rewarding integrated platform providers with pricing power anchored to architectural commitments.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates commercial aircraft lighting procurement, with certification grade and volume scale as primary price differentiation drivers. Cost compression in standard-tier LED retrofits is intensifying because FAA airworthiness directives have commoditized baseline burn-time reliability specifications. Cargo operators exhibit highest price sensitivity due to cost-optimized sustainment priorities, while long-haul premium carriers demonstrate lowest sensitivity where circadian-rhythm programming justifies experience premiums.
Supply Chain Analysis
Optical engineering talent scarcity in Wichita, Kansas and Bavaria's aerospace corridor is constraining production scaling for intelligent lighting architectures. Supply concentrates in the United States, Germany, and France, with specialized LED driver production and chromaticity calibration equipment as critical input dependencies. Single-source vulnerability around FAA-certified emergency power architectures presents structural risk. Distribution runs through OEM specification channels and MRO network procurement offices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Commercial aircraft lighting has shifted into a late-cycle quality phase where retrofit-driven replacement demand favors suppliers with certified intelligent system platforms over commodity LED component vendors.
For Market Incumbents: Cement specification lock-in by deepening backward integration into LED driver production and chromaticity calibration capabilities. Threat from emerging software-native cabin integrators demands accelerated EASA CS-25 certification investment for dual-validation coverage. Channel control through long-term architectural commitments with United States major carriers remains the priority defensive lever. For New Entrants and Emerging Players: The EU AI Act in Europe opens a window for cybersecurity-certified connected lighting architectures where algorithmic transparency requirements create compliance barriers for legacy suppliers. White-space targets include EASA validation services for intelligent system software and specialized optical assembly production for narrow-body retrofit channels. Go-to-market positioning as a regulatory-compliance-native partner to European operators bypasses incumbent OEM relationships. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized optical engineering firms possessing captive LED driver production and existing FAA-EASA dual certification. Long-term viability centers on retrofit cycle duration and intelligent lighting penetration in premium cabin configurations. Acquisition target archetype: mid-cap suppliers with in-house chromaticity calibration and established MRO network relationships. Signal to watch: divergence in FAA-EASA software validation timelines as inflection indicator for compliance-cost advantage.| Strategic Initiative | Industry Significance |
|---|---|
| Emergency Power Architecture Certification | FAA-certified redundant illumination paths command premium positioning in narrow-body retrofit specifications. |
| Intelligent Lighting Platform Integration | Software-enabled circadian-rhythm programming captures premium cabin configuration decisions at long-haul carriers. |
| Backward Integration into LED Drivers | In-house optical assembly production insulates margin pools from second-source availability constraints. |
| Dual FAA-EASA Validation Investment | Transatlantic certification coverage unlocks specification access at Airbus and Boeing OEM channels simultaneously. |
| Cybersecurity Framework Alignment | EU AI Act compliance creates differentiation for data-enabled cabin systems in European operator procurement. |
Methodological Framework
Direct dialogue with airline technical procurement directors, MRO engineering leads, OEM specification managers, and optical engineering specialists grounded qualitative findings in operational realities. Secondary validation drew from FAA airworthiness directive filings, EASA CS-25 certification databases, airline fleet modernization disclosures, and aerospace supplier SEC filings. Bottom-up and top-down triangulation cross-checked segment-level demand against aggregate market sizing.
Market value and volume outputs across the analysis window reflect a structured analytical framework incorporating technology substitution curves, regulatory mandate timing, and fleet age distribution modeling. Segmentation dimensions included product type, technology architecture, application category, and end-user procurement channel. CAGRs derived from fitted growth curves applied to replacement-driven demand baselines and OEM specification capture rates, with narrow-body retrofit intensity and intelligent lighting penetration as primary forecast inputs.
Revisions become necessary when FAA-EASA regulatory divergence accelerates, LED driver supply concentration intensifies, or cybersecurity framework implementation timelines shift materially. Forecasts reflect documented assumptions regarding fleet renewal cycles and technology refresh economics. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Aircraft Inspection Covers Market
Aircraft
Flight Management Systems Market
Aircraft
Single-Seat Gyrocopter Market
Aircraft
Light Sport Aircraft (LSA) Market
Aircraft
Aircraft Cables Market
Aircraft
Aircraft Ailerons Market
Aircraft
Helicopter Wheels Market
Aircraft
Asia-Pacific Military Helicopters Market
Aircraft
Evtol Aircraft Market
Aircraft
Sailplane Market
Aircraft
Aircraft Sequencing System Market
Aircraft
North America Aviation Market
Aircraft
Commercial Turboprop Aircrafts Market
Aircraft
Aerospace Turbojet Market
Aircraft
Aircraft Hangar Market
Aircraft
South Korea Aviation Market