
 Asia-Pacific Aircraft MRO Market | 2026-2036
Asia-Pacific Aircraft MRO Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Aircraft MRO Market Outlook
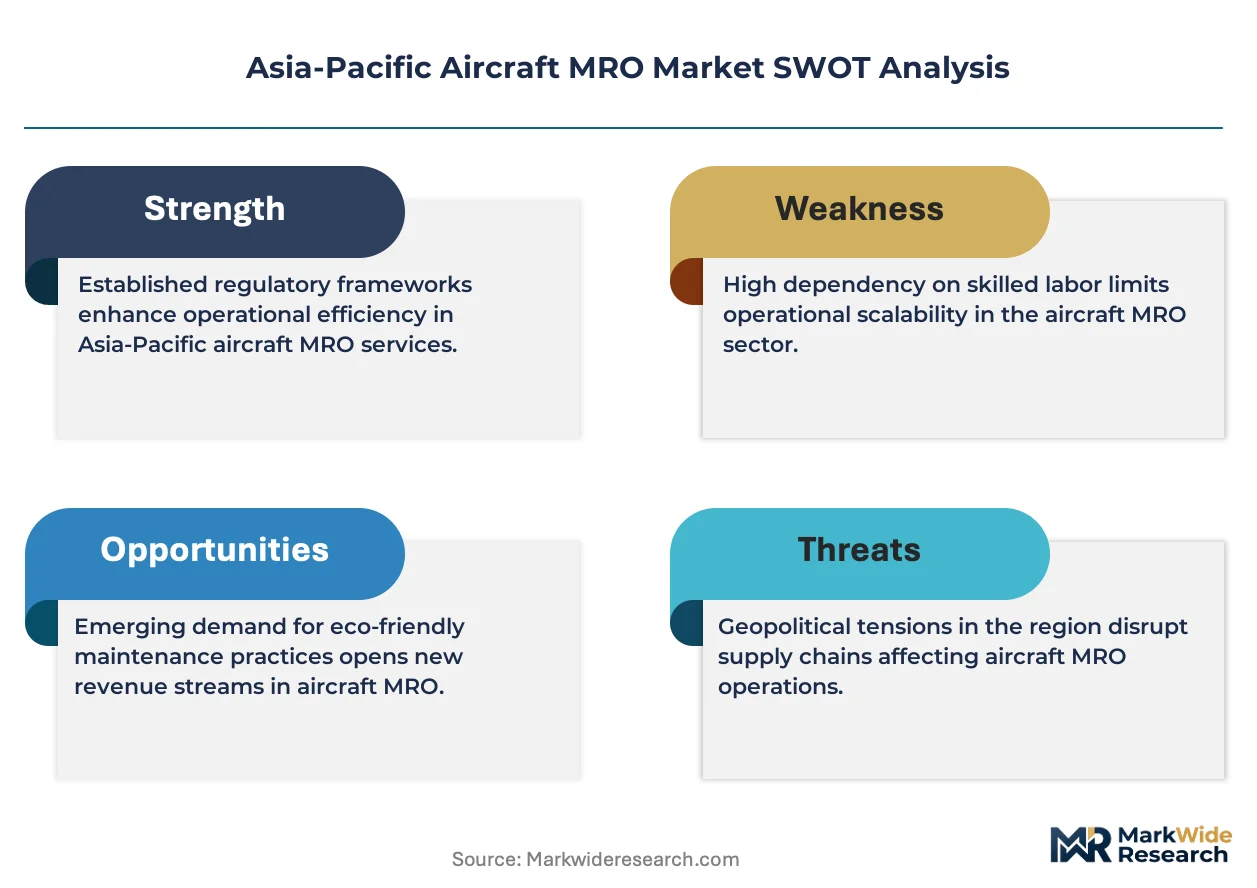
Composite materials are hardening cost structures as carbon fiber-reinforced polymers replace aluminum in next-generation narrowbody repairs. ST Engineering sustains dominance through its integrated aerospace campus in Singapore, combining line maintenance with heavy check capabilities. GMF AeroAsia anchors Indonesian operations with specialized Boeing and Airbus airframe services. HAECO differentiates through its Pearl River Delta network, leveraging proximity to mainland Chinese fleet operators.
Asia-Pacific Aircraft MRO encompasses the inspection, repair, overhaul, and modification of airframes, engines, and components to sustain airworthiness certification under ICAO Annex 8 standards, typically requiring 6,000–12,000 flight-hour intervals for C-check cycles. The primary purpose is to extend operational life while ensuring compliance with manufacturer maintenance planning documents and national aviation authority directives. Engine Repair commands the deepest margin pools due to specialized tooling and OEM intellectual property barriers, while Predictive Maintenance represents the fastest-expanding technology segment as operators deploy vibration analysis and oil-debris monitoring to compress turnaround times. Commercial Airlines remain the dominant end-user category, though Cargo Operators are expanding MRO commitments as converted freighter programs accelerate across the region.
CAAC airworthiness directives and EASA MOR requirements shape product standards for foreign-registered aircraft operating Chinese and European routes, while Singapore's CAAS enforces stringent maintenance organization approvals that filter market access. India's DGCA and Australia's CASA impose additional certification layers for cross-border component exchanges. Stakeholders must weigh predictive technology deployment against legacy manual inspection infrastructure as fleet age profiles diverge across the region.
Market Dynamics
Composite airframe penetration is forcing MRO infrastructure reinvestment across the Asia-Pacific region, as carbon fiber-reinforced polymer damage assessment requires entirely different tooling and technician certifications than traditional aluminum repair protocols.
Growth Catalysts
- Low-cost carrier fleet expansion:Southeast Asian budget airlines are compressing turnaround times and accelerating heavy check cycles, driving line maintenance volume at secondary airports across Indonesia, Vietnam, and the Philippines.
- CAAS maintenance organization approvals:Singapore's stringent certification standards create a quality filter that concentrates high-value MRO work in Changi-linked facilities, reinforcing the city-state's hub position for regional widebody overhauls.
- Predictive maintenance sensor deployment:Vibration analysis and oil-debris monitoring systems are reducing unscheduled engine removals, allowing operators to optimize shop visit timing and extend on-wing intervals.
Market Restraints
- OEM intellectual property barriers:Engine Repair and Overhaul (ERO) shops face restricted access to proprietary repair schemes and life-limited part data from manufacturers like Rolls-Royce and GE Aviation, constraining independent MRO capability development.
- Specialized technician scarcity:Composite repair certification programs produce insufficient qualified personnel relative to fleet transition rates, creating wage inflation and capacity bottlenecks at heavy check facilities.
- Import duty complexity on components:Cross-border parts movements between Association of Southeast Asian Nations members encounter non-tariff barriers and customs documentation delays, extending AOG resolution timelines.
Strategic Opportunities
- Converted freighter program acceleration:E-commerce logistics operators in China and Southeast Asia are driving demand for passenger-to-cargo conversion MRO, creating specialized airframe modification revenue streams distinct from scheduled maintenance.
- CAAC-EASA bilateral recognition expansion:Streamlined approval reciprocity between China's Civil Aviation Administration and the European Union Aviation Safety Agency reduces dual certification burdens for MROs serving Chinese-registered aircraft on European routes.
- Digital twin integration with blockchain parts traceability:Converging technologies enable component life-cycle documentation that satisfies both regulatory audit requirements and lessor return conditions, differentiating full-service MRO providers.
Industry Challenges
- ICAO Annex 8 compliance timeline compression:National aviation authorities are shortening approval windows for major repair design changes, straining engineering departments already managing multiple airworthiness directive implementations simultaneously.
- Legacy fleet age divergence:Simultaneous operation of 25-year-old aluminum airframes and new composite-intensive narrowbodies forces MROs to maintain dual capability sets without corresponding revenue scale in either specialization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Aircraft MRO Market |
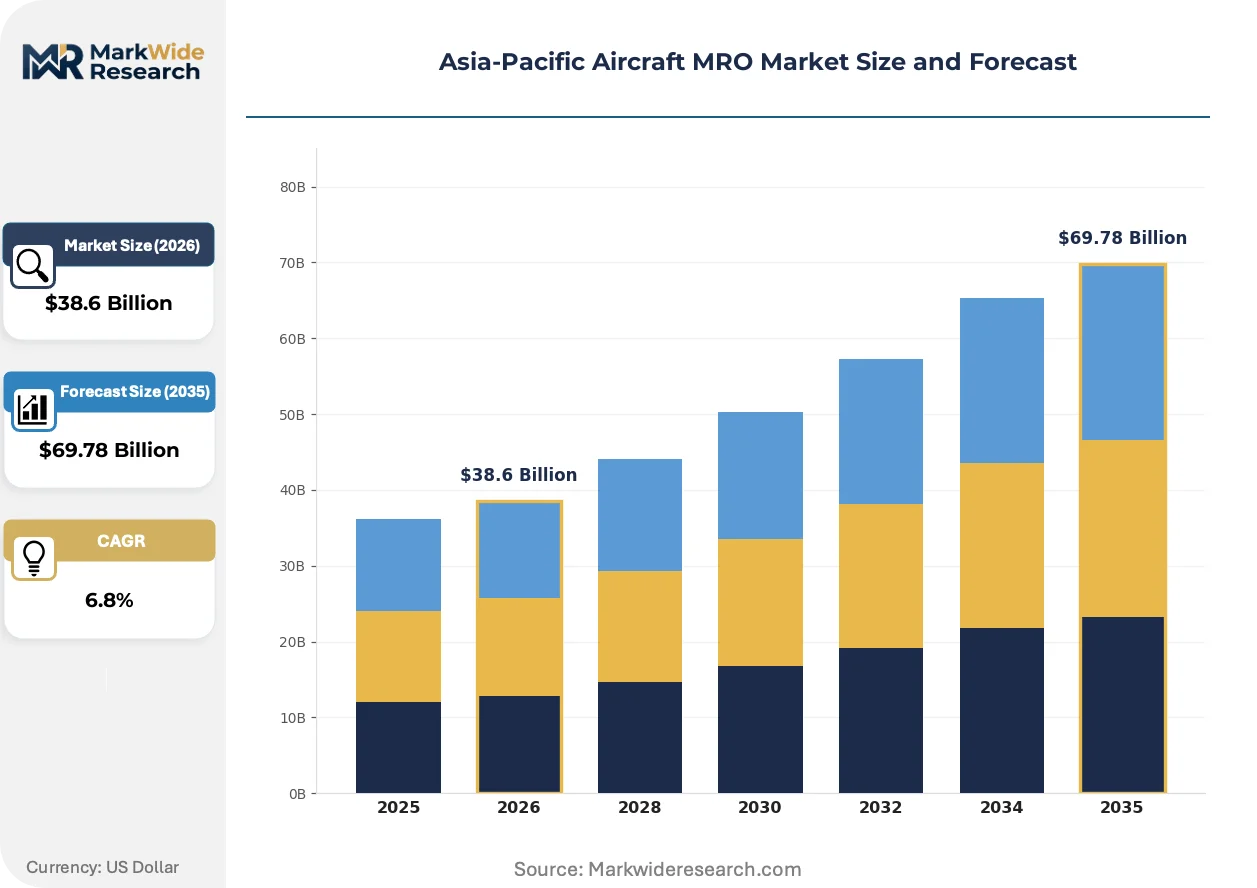
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $69.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Airframe Maintenance, Engine Repair, Component Overhaul, Line Maintenance End User: Commercial Airlines, Cargo Operators, Military, Private Operators Maintenance Type: Routine Maintenance, Scheduled Checks, Unscheduled Maintenance, Heavy Maintenance Technology: Predictive Maintenance, Condition-Based Maintenance, Manual Maintenance, Automated Systems |
| Companies Covered | GE Aerospace, GMF AeroAsia, ST Engineering, Sepang Aircraft Engineering Sdn Bhd, Guangzhou Aircraft Maintenance Engineering Company Limited, Hong Kong Aircraft Engineering Company Limited (HAECO), Lufthansa Technik AG, Rolls Royce PLC, SIA Engineering Company, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Aircraft MRO Market Strategic Shifts
Digital thread technologies are collapsing traditional inspection-to-repair handoffs, enabling real-time engineering feedback that compresses turnaround estimates and reduces parts ordering errors.
Additive manufacturing for non-structural aerospace components is modularizing spare parts supply chains, allowing MROs to print cabin interior brackets, ducting clips, and electrical connectors on-demand rather than maintaining OEM-dependent inventory positions. Regional operators with Singapore and Australian approvals are adopting polymer and metal deposition systems fastest, cutting AOG resolution times from days to hours for qualified part categories. This capability is modularizing the relationship between airlines and their parts distributors, shifting procurement toward raw material feedstock rather than finished components.
EASA's Management of Change (MOR) requirements for maintenance organization approvals are tightening documentation standards for foreign-registered aircraft operating European routes, forcing Asia-Pacific MROs to upgrade quality management systems. Facilities seeking Part-145 recognition must now demonstrate enhanced risk-based oversight protocols and expanded technical records retention. Indonesian and Thai MROs serving EU-destination carriers are investing most heavily in compliance infrastructure, treating EASA alignment as a competitive qualification for international airline contracts.
Airline procurement departments are unbundling line maintenance from heavy check contracts, creating separate competitive tenders for overnight A-checks versus C-check and D-check programs. Low-cost carriers in Malaysia and the Philippines are driving this fragmentation, seeking specialized line maintenance providers at outstations while concentrating heavy work at single-source partners. This pattern is most visible in the Pearl River Delta, where mainland Chinese operators split contracts between HAECO-network facilities for heavy checks and independent ground handlers for transit servicing.
Asia-Pacific Aircraft MRO Market Segmentation
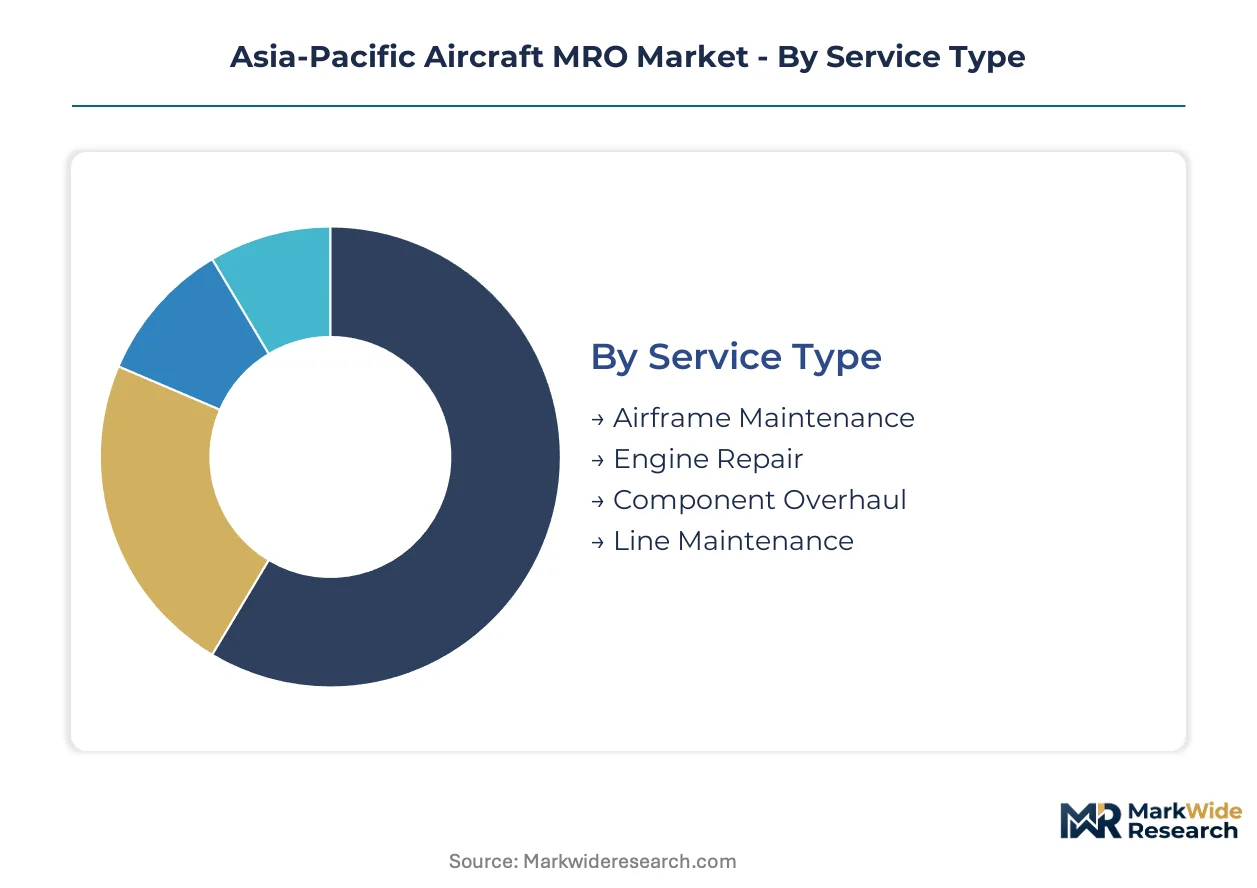
Service differentiation across Asia-Pacific MRO segments determines pricing power and contract tenure. Fleet complexity in Southeast Asia and China's regulatory environment create divergent capability requirements across service categories.
Service Type:
Customization intensity varies sharply across this category, from standardized line maintenance protocols to highly bespoke engine overhaul programs.
- Engine Repair:Specialized tooling and proprietary repair schemes from OEMs like Rolls-Royce and GE Aviation create deep margin pools. Demand concentrates in Singapore's Changi aviation cluster, where CAAS-approved facilities capture regional widebody engine work.
- Airframe Maintenance:Carbon fiber-reinforced polymer damage assessment requires entirely different technician certifications than aluminum protocols. Indonesian and Vietnamese facilities face reinvestment pressure as composite penetration accelerates across narrowbody fleets.
- Component Overhaul:Avionics and landing gear refurbishment cycles track flight-hour accumulation rates.
- Line Maintenance:Overnight A-checks and transit servicing compress turnaround times at secondary airports.
Leading the category by volume: Airframe Maintenance. Growing fastest: Engine Repair.
End User:
Customer scale and contract structure divide this category, from fragmented private operator relationships to consolidated airline procurement.
- Commercial Airlines:Low-cost carriers across Malaysia and the Philippines unbundle line maintenance from heavy check contracts. Procurement departments now tender overnight A-checks separately from C-check and D-check programs.
- Cargo Operators:E-commerce logistics demand in China and Southeast Asia accelerates passenger-to-freighter conversion programs. Specialized airframe modification revenue streams diverge from scheduled maintenance cycles.
- Military:Sovereign fleet requirements impose distinct certification and security protocols.
- Private Operators:Fractional ownership and business aviation fleets generate intermittent high-margin demand.
Dominating contract value: Commercial Airlines. Expanding most quickly: Cargo Operators.
Maintenance Type:
Regulatory interval rigidity separates this category, from flexible unscheduled responses to mandatory calendar-driven heavy checks.
- Scheduled Checks:C-check cycles at 6,000–12,000 flight-hour intervals sustain airworthiness certification under ICAO Annex 8 standards. China's CAAC mandates stricter directives under evolving safety protocols.
- Heavy Maintenance:D-check airframe teardowns require extended hangar occupancy and specialized jig infrastructure. Singapore's MRO campus density supports regional hub concentration for widebody programs.
- Routine Maintenance:Pre-flight and transit inspections maintain dispatch reliability.
- Unscheduled Maintenance:AOG resolution demands rapid parts availability and technician deployment.
Highest revenue concentration: Heavy Maintenance. Steepest expansion trajectory: Scheduled Checks.
Technology:
Capital deployment intensity distinguishes this category, from labor-dependent manual methods to sensor-heavy predictive platforms.
- Predictive Maintenance:Vibration analysis and oil-debris monitoring systems reduce unscheduled engine removals. Operators across the Pearl River Delta optimize shop visit timing and extend on-wing intervals through real-time data.
- Condition-Based Maintenance:Health monitoring triggers component replacement before failure, balancing cost against reliability. Australian and Singaporean facilities lead adoption with CAAS and CASA approval frameworks.
- Manual Maintenance:Visual inspection and technician judgment remain prevalent for legacy aluminum airframes.
- Automated Systems:Robotic non-destructive testing and drone inspection reduce hangar downtime.
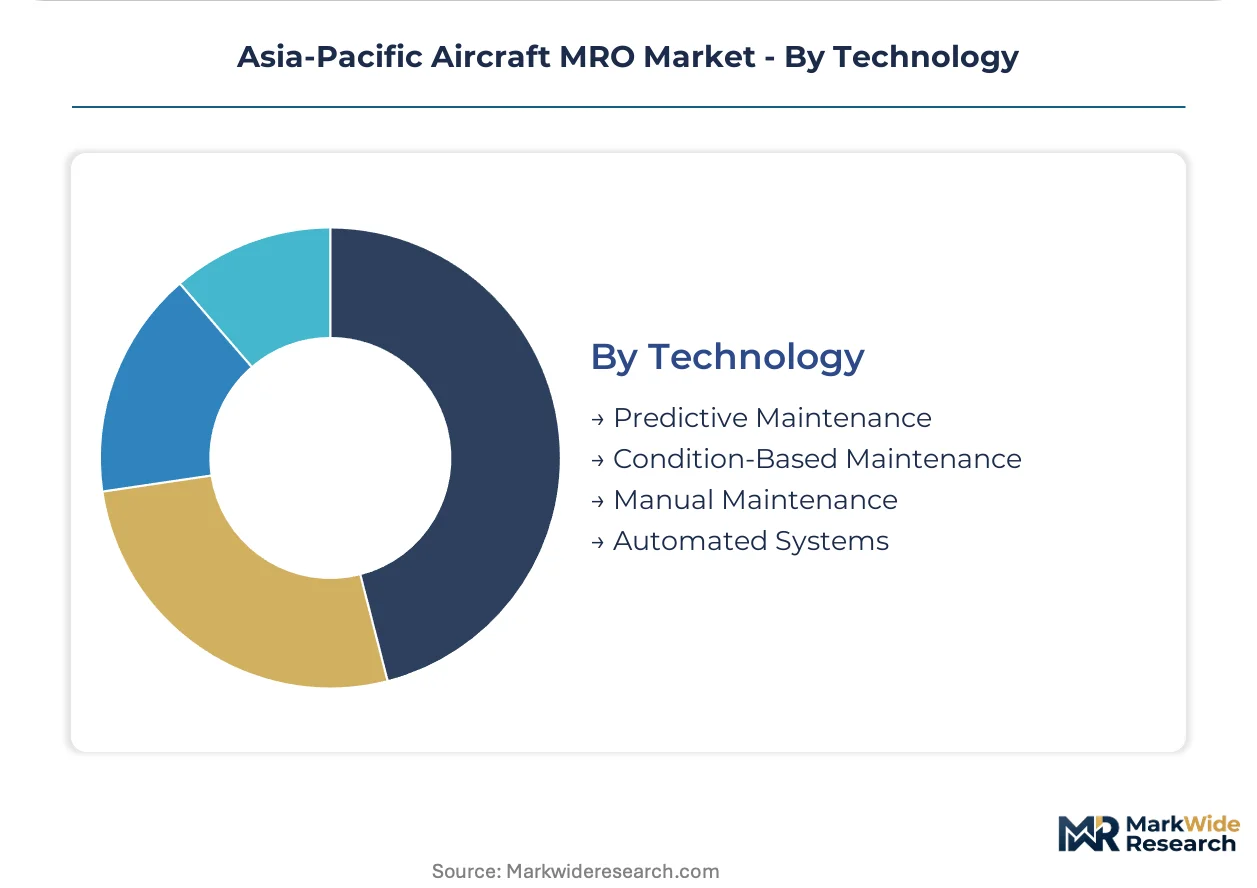
Widest installed base: Manual Maintenance. Gaining share fastest: Predictive Maintenance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore's Changi Aviation Park anchors regional MRO concentration through tax-advantaged status and CAAS-certified infrastructure density. Special economic zone treatment for aerospace activities draws heavy check capacity from competing hubs.
Singapore
CAAS maintenance organization approvals filter market access toward high-value widebody overhauls. The Changi aviation cluster integrates line maintenance with heavy check capabilities under unified campus operations. ST Engineering and SIA Engineering Company anchor this ecosystem through dedicated hangar complexes serving regional fleet operators.
China
CAAC airworthiness directives mandate stricter compliance protocols under evolving safety standards. The Pearl River Delta network leverages proximity to mainland fleet operators for contract concentration. Guangzhou Aircraft Maintenance Engineering occupies a central position within this geography through specialized airframe services.
Indonesia
Low-cost carrier fleet expansion accelerates maintenance cycles across secondary airport networks. DGCA certification requirements impose additional layers for cross-border component exchanges. GMF AeroAsia anchors Indonesian operations with dedicated Boeing and Airbus airframe capabilities at Jakarta-linked facilities.
Hong Kong
Cargo operator demand intensifies as e-commerce logistics drive freighter conversion programs. HAECO differentiates through integrated Pearl River Delta coverage spanning heavy checks and line maintenance. The jurisdiction's regulatory alignment with EASA standards supports European-registered aircraft servicing.
Malaysia
Sepang Aircraft Engineering concentrates narrowbody maintenance capacity near Kuala Lumpur International Airport. Unbundled procurement patterns separate overnight A-checks from C-check programs across low-cost carrier contracts. The facility occupies a position within the ASEAN cross-border parts movement corridor despite customs documentation friction.
Asia-Pacific Aircraft MRO Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with engine overhaul concentration favoring OEM-linked facilities against independent airframe shops. The vendor base organizes around three archetypes: integrated aerospace campuses combining multiple service lines, specialized engine repair and overhaul operations, and regional heavy check providers serving single-airline contracts. Consolidation pressures concentrate in engine services where intellectual property barriers protect incumbent positions, while airframe maintenance retains fragmentation due to lower capital thresholds. Competitive moves center on predictive technology licensing partnerships and composite repair certification investments.
Among Singapore-based integrated operators, ST Engineering and SIA Engineering Company exemplify the campus-model archetype through co-located capabilities. GMF AeroAsia represents the national-champion structure within Indonesia's market. GE Aerospace and Rolls Royce PLC occupy positions on the OEM-proprietary tier where repair scheme access determines competitive viability. These groupings illustrate how regulatory approval geography and intellectual property control shape contestable market space across service categories.
| Leading Market Players |
|---|
| GE Aerospace |
| GMF AeroAsia |
| ST Engineering |
| Sepang Aircraft Engineering Sdn Bhd |
| Guangzhou Aircraft Maintenance Engineering Company Limited |
| Hong Kong Aircraft Engineering Company Limited (HAECO) |
| Lufthansa Technik AG |
| Rolls Royce PLC |
| SIA Engineering Company |
| Others |
Value Chain & Pricing Dynamics
Low-cost carrier procurement departments across Southeast Asia drive contract fragmentation that splits pricing between line maintenance spot rates and heavy check bundled agreements. This buyer concentration forces MROs to maintain dual rate cards while absorbing composite tooling reinvestment costs.
Pricing Analysis
Lead-time premiums dominate contract negotiations, with overnight A-checks at secondary airports commanding spot-market surcharges against scheduled C-check slots booked quarters ahead. Pricing stratifies across CAAS-approved facilities, EASA-aligned operations, and uncertified independents based on audit documentation depth. Cost compression in engine overhaul stems from OEM intellectual property restrictions limiting independent repair scheme access. Cargo operators show least price sensitivity due to freighter conversion program urgency, while budget airlines squeeze line maintenance rates through competitive tender fragmentation.
Supply Chain Analysis
Regional distribution centers in Singapore, Hong Kong, and Kuala Lumpur anchor hub-and-spoke parts movement across the ASEAN corridor. Critical inputs draw from aerospace-grade titanium suppliers in Japan, composite pre-preg manufacturers in South Korea, and specialized avionics from the United States. Single-source vulnerability concentrates in proprietary engine life-limited parts controlled by Rolls-Royce and GE Aviation. Distribution runs through CAAS-certified bonded warehouses that filter cross-border customs documentation delays.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around predictive technology deployment and composite certification investments that weaker capitalized independents cannot match. OEM intellectual property barriers and regulatory approval costs accelerate exit pressures on undifferentiated airframe shops.
For Market Incumbents: Extend predictive maintenance platform licensing partnerships to lock in airline data-feed exclusivity. Deepen composite repair certification pipelines through Singapore Polytechnic and Australian technical institute partnerships before technician scarcity inflates wage structures. Defend against emerging digital-native entrants by integrating blockchain parts traceability into existing CAAS-approved quality systems. For New Entrants and Emerging Players: Digital-channel predictive analytics sales offer the lowest barrier route to airline procurement departments without heavy hangar infrastructure. Target Indonesian and Vietnamese secondary airports where low-cost carrier line maintenance contracts remain fragmented among independent ground handlers. Position through vibration-monitoring hardware-as-a-service models that bypass upfront CAPEX requirements. For Investors and Strategic Acquirers: Distressed-cycle entries favor CAAS-certified airframe specialists in Singapore with underutilized composite repair capacity. Long-term viability hinges on positioning for freighter conversion program acceleration across China-Southeast Asia trade lanes. Monitor CAAC-EASA bilateral recognition expansion as the inflection signal for cross-border contract scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Composite Repair Certification Investment | GMF AeroAsia and Sepang Aircraft Engineering expand technician pipelines to capture narrowbody fleet transition demand. |
| Predictive Maintenance Platform Licensing | Sensor-data partnerships with Pearl River Delta operators compress unscheduled engine removal rates. |
| Freighter Conversion Program Expansion | HAECO's dedicated modification lines address e-commerce logistics operator capacity constraints. |
| CAAS-EASA Dual Approval Pursuit | Indonesian MROs upgrade quality systems to qualify for European-registered aircraft servicing contracts. |
| Blockchain Parts Traceability Integration | Digital twin documentation satisfies lessor return conditions and regulatory audit requirements simultaneously. |
Study Parameters
Independent corroboration across MRO operations directors, airline fleet managers, and CAAS certification auditors underwrites the qualitative findings. Primary interviews with ST Engineering program leads, HAECO procurement heads, and GMF AeroAsia engineering directors combined with secondary validation from ICAO Annex 8 documentation, CAAC airworthiness directive filings, and EASA Management of Change requirement updates. Bottom-up service-type volume estimates triangulated against top-down regional fleet projection databases.
Comparable-period anchoring to historical heavy check cycle frequencies and engine shop visit intervals structured the forecast window. Segmentation dimensions modeled include service type, end-user category, maintenance interval rigidity, and technology deployment intensity. CAGRs derived from fleet age profile trajectories and composite penetration curves across the projection horizon. Forecast inputs incorporated low-cost carrier utilization rate assumptions and CAAC regulatory tightening schedules.
The model holds under stable bilateral aviation safety agreements; deviation in tariff escalation or OEM repair scheme licensing restrictions would shift independent MRO viability thresholds. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Maintenance and MRO Solutions
Aviation Test Equipment Market
Aircraft Maintenance and MRO Solutions
Air Transport MRO Market
Aircraft Maintenance and MRO Solutions
MRO Protective Coatings Market
Aircraft Maintenance and MRO Solutions
Global Aerospace Maintenance Chemical Market
Aircraft Maintenance and MRO Solutions
Aircraft Maintenance Market
Aircraft Maintenance and MRO Solutions
Middle-East and Africa Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Commercial Aircraft Maintenance Repair and Overhaul (MRO) Market
Aircraft Maintenance and MRO Solutions
Aircraft Washing Systems Market
Aircraft Maintenance and MRO Solutions
Aircraft Weight Scale Market
Aircraft Maintenance and MRO Solutions
Gas Turbine MRO Market
Aircraft Maintenance and MRO Solutions
United States Airframe MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Line Maintenance Market
Aircraft Maintenance and MRO Solutions
Aircraft Autoclave Market
Aircraft Maintenance and MRO Solutions
Cabin Reconfiguration and Retrofit MRO Services Market
Aircraft Maintenance and MRO Solutions
Aviation Maintenance Software Market
Aircraft Maintenance and MRO Solutions
Digital MRO Market