
 Middle-East and Africa Aircraft MRO Market | 2026-2036
Middle-East and Africa Aircraft MRO Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Aircraft MRO Market Foresight
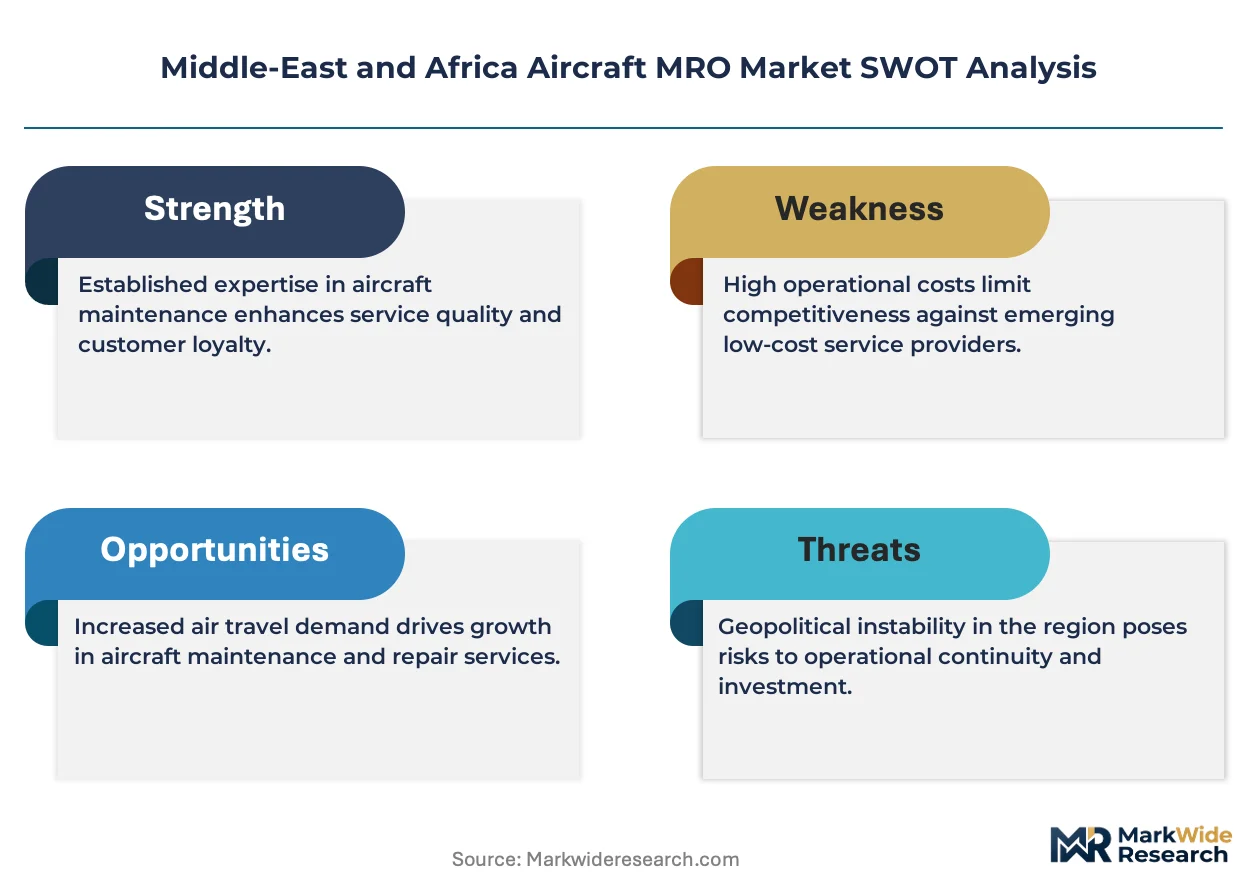
UAE GCAA airworthiness enforcement is hardening the cost-of-entry calculus for independent MRO providers seeking operating certificates. Emirates Engineering leverages its captive fleet scale to sustain in-house overhaul capacity at Dubai International Airport. Joramco anchors narrow-body airframe expertise from its Amman facility, while Sanad Aerotech competes on component repair specialization for LEAP and GTF engine families. Turkish Technic extends its geographic footprint through line maintenance stations across North African hubs.
Aircraft MRO encompasses the inspection, repair, overhaul, and modification of airframes, engines, and components to maintain type-certificated airworthiness standards, typically requiring compliance with manufacturer service bulletins and regulatory continuing airworthiness management. Engine overhaul commands the largest value share within the service type dimension due to thermal-cycle limits and life-limited part replacement schedules. Predictive maintenance within the technology dimension represents the fastest-expanding segment as airlines deploy vibration monitoring and oil-debris analysis to compress unscheduled downtime. Commercial airlines dominate the end-user structure, though cargo carriers are widening their MRO commitments as dedicated freighter conversions accelerate.
UAE GCAA directives, Saudi GACA regulations, and EASA Part-145 recognition agreements collectively shape technician certification requirements and facility audit frequencies across the Middle-East and Africa region. The EU AI Act's emerging classification of predictive maintenance algorithms as high-risk AI systems may cascade into MRO software procurement standards for carriers operating European routes. Stakeholders must monitor how regulatory reciprocity negotiations between Gulf aviation authorities and African civil aviation bodies reshape cross-border maintenance approvals and spare parts traceability obligations.
Market Dynamics
Fleet renewal programs across Gulf Cooperation Council states are compressing maintenance cycles and forcing MRO providers to recalibrate capacity for next-generation airframes and propulsion systems. This structural pressure is reshaping facility investments, technician training pipelines, and regulatory compliance architectures throughout the Middle-East and Africa region.
Growth Catalysts
- GCAA Airworthiness Directives:The UAE's tightened enforcement on aging aircraft is accelerating retirement timelines and generating surge demand for heavy maintenance checks on replacement fleets.
- LEAP and GTF Engine Proliferation:New-generation powerplants with complex composite fan cases and advanced thermal coatings require specialized component repair infrastructure that independent shops are racing to build.
- Cargo Carrier Fleet Expansion:Dedicated freighter conversions are widening the addressable MRO base beyond passenger airlines as e-commerce logistics operators commit to long-term maintenance contracts.
Market Restraints
- Certified Technician Scarcity:EASA Part-145 and GCAA-recognized training programs produce insufficient airframe and avionics specialists to match facility expansion timelines.
- Supply Concentration in OEM Networks:Boeing and Airbus proprietary diagnostics and approved parts distribution create captive dependencies that limit third-party MRO pricing leverage.
- Import Duty Complexity:Cross-border spare parts movements face inconsistent customs treatment between North African and Gulf jurisdictions, inflating working capital requirements.
Strategic Opportunities
- Saudi Arabia Localization Mandates:GACA's Vision 2030 aviation targets are creating greenfield MRO zones near Riyadh and Jeddah with subsidized land and expedited licensing.
- Predictive Maintenance Algorithm Deployment:Vibration monitoring and oil-debris analysis systems are converging with fleet management software to enable condition-based overhaul scheduling.
- Ethiopian Cargo Hub Expansion:Addis Ababa's growing freighter base offers untapped line maintenance and engine-on-wing support contracts for regional specialists.
Industry Challenges
- Composite Repair Certification Bottlenecks:Carbon fiber airframe damage assessment and bonded repair qualifications require OEM-specific training that stretches technician deployment timelines.
- Hangar Capacity Siting Constraints:Dubai International and Abu Dhabi International slot restrictions limit physical expansion for heavy maintenance bays despite demand concentration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Aircraft MRO Market |
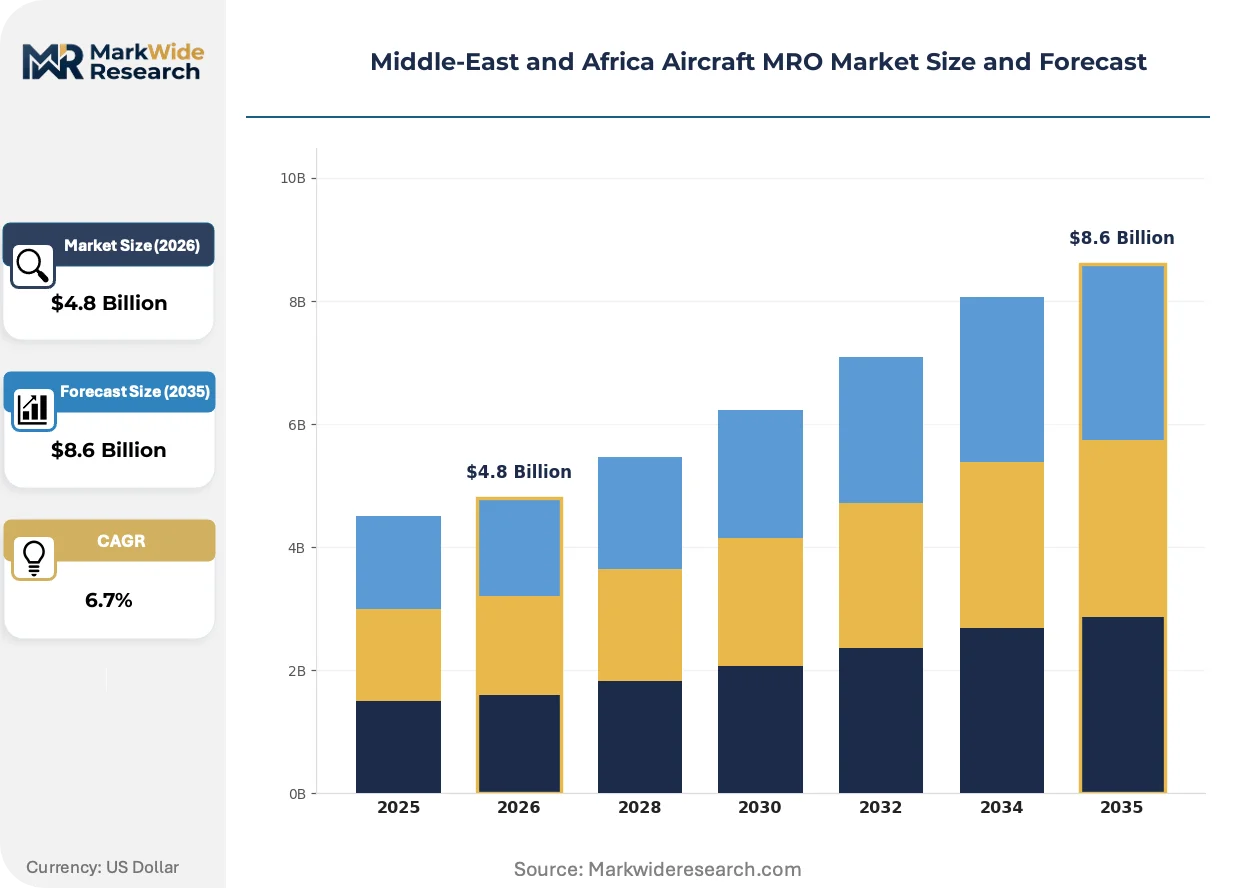
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Airframe Maintenance, Engine Overhaul, Component Repair, Line Maintenance End User: Commercial Airlines, Cargo Carriers, Government Agencies, Private Operators Maintenance Type: Routine Services, Scheduled Maintenance, Unscheduled Maintenance, Heavy Maintenance Technology: Traditional MRO, Predictive Maintenance, Digital Solutions, Advanced Analytics |
| Companies Covered | Joramco, Sanad Aerotech, Emirates Engineering, GE Aerospace, Lufthansa Technik, Saudia Technic, Turkish Technic, Rolls-Royce, Ethiopian Airlines MRO, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Aircraft MRO Market Shifts & Advancements
Digital thread technologies and regulatory harmonization pressures are restructuring how maintenance data flows between operators, MRO providers, and aviation authorities. These forces are compressing documentation cycles and elevating software competence alongside mechanical expertise.
Digital twin platforms for engine performance modeling are converging with live sensor feeds from aircraft health monitoring units. Emirates Engineering and Saudi Arabian Airlines Engineering are piloting these systems to transition from fixed-interval overhauls to condition-triggered shop visits. This convergence is compressing inventory holdings for life-limited parts and redistributing value toward data analytics capabilities.
EASA Part-145 recognition agreements with GCAA and GACA are tightening audit frequencies and documentation standards for facilities serving European-registered aircraft. MRO providers must now maintain dual-compliance architectures for local and EU airworthiness mandates. Component repair stations in Jordan and the UAE are investing in integrated quality management systems to satisfy these converging requirements.
Airline procurement departments are unbundling heavy maintenance packages into discrete engine, airframe, and component line items. This fragmentation enables competitive bidding across specialist providers rather than sole-source contracts with full-service MROs. The practice is most visible among low-cost carriers operating narrow-body fleets from Dubai and Sharjah hubs.
Middle-East and Africa Aircraft MRO Market Segmentation
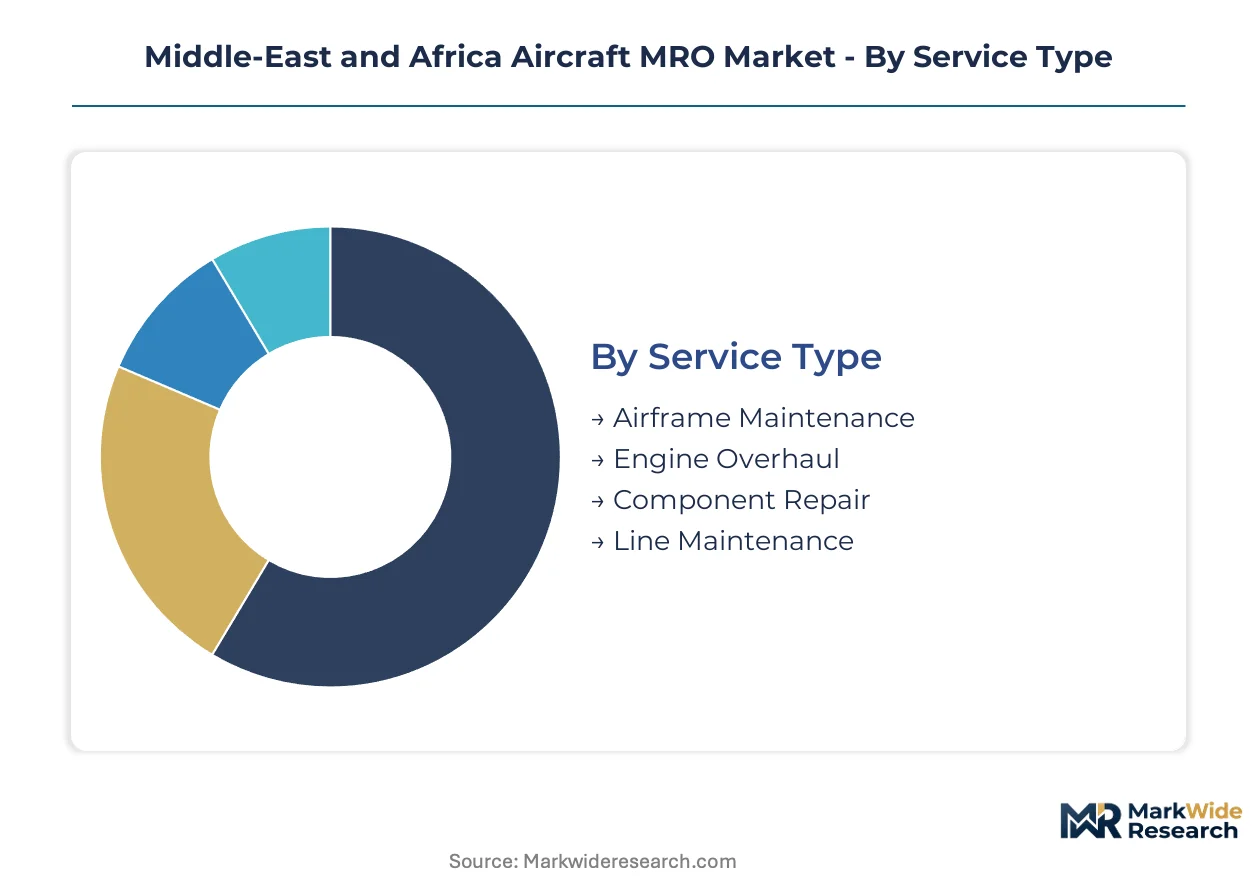
Aircraft MRO segmentation in the Middle-East and Africa region reflects divergent operational pressures across fleet types, regulatory jurisdictions, and technology adoption curves. Service providers must calibrate capabilities across multiple dimensions simultaneously to capture value from Gulf carrier renewal programs and African cargo hub expansion.
Service Type:
Customization intensity varies sharply across this category, from standardized line checks to bespoke engine rebuilds requiring OEM-certified tooling.
- Engine Overhaul:Thermal-cycle-limited part replacement and composite fan case restoration dominate value capture. Demand clusters at Dubai and Abu Dhabi facilities serving Emirates and Etihad fleets, pressured by LEAP and GTF proliferation timelines.
- Airframe Maintenance:Heavy structural inspections and corrosion treatment for aging aluminum fuselages require extensive hangar footprints. Joramco's Amman facility anchors narrow-body expertise, while Saudi GACA localization mandates redirect investment toward Riyadh greenfield sites.
- Component Repair:Avionics, landing gear, and auxiliary power unit refurbishment with shorter turnaround cycles.
- Line Maintenance:Overnight A-checks and transit defect rectification at hub airports.
Leading the category by volume: Engine Overhaul. Expanding most quickly: Airframe Maintenance.
End User:
Customer concentration tilts toward operators with captive maintenance strategies versus fragmented third-party demand.
- Commercial Airlines:Full-service and low-cost carriers operating scheduled passenger networks. Emirates Engineering sustains in-house overhaul capacity at Dubai International, while procurement fragmentation into discrete engine and airframe line items intensifies competitive bidding.
- Cargo Carriers:Dedicated freighter operators and converted passenger-to-cargo fleets. Ethiopian Airlines' Addis Ababa hub expansion and e-commerce logistics commitments widen long-term contract opportunities for regional specialists.
- Government Agencies:Military and state aviation departments with sovereign maintenance requirements.
- Private Operators:Corporate jet and charter fleets with dispersed geographic footprints.
Commercial Airlines command the largest addressable base. Cargo Carriers are gaining share fastest on conversion program acceleration.
Maintenance Type:
Scheduling predictability separates cost-efficient operations from crisis-driven expenditure spikes.
- Heavy Maintenance:C-check and D-check intervals requiring extended airframe downtime and deep structural access. UAE GCAA airworthiness enforcement on aging aircraft compresses these cycles, generating surge demand at Dubai and Abu Dhabi clusters.
- Scheduled Maintenance:Calendar-based A-check and B-check routines with predictable resource planning.
- Unscheduled Maintenance:Ad-hoc repairs from component failures or damage events.
- Routine Services:Daily transit checks and minor defect rectification.
Heavy Maintenance generates the highest revenue per event. Predictive algorithm deployment is compressing Unscheduled Maintenance incidence fastest.
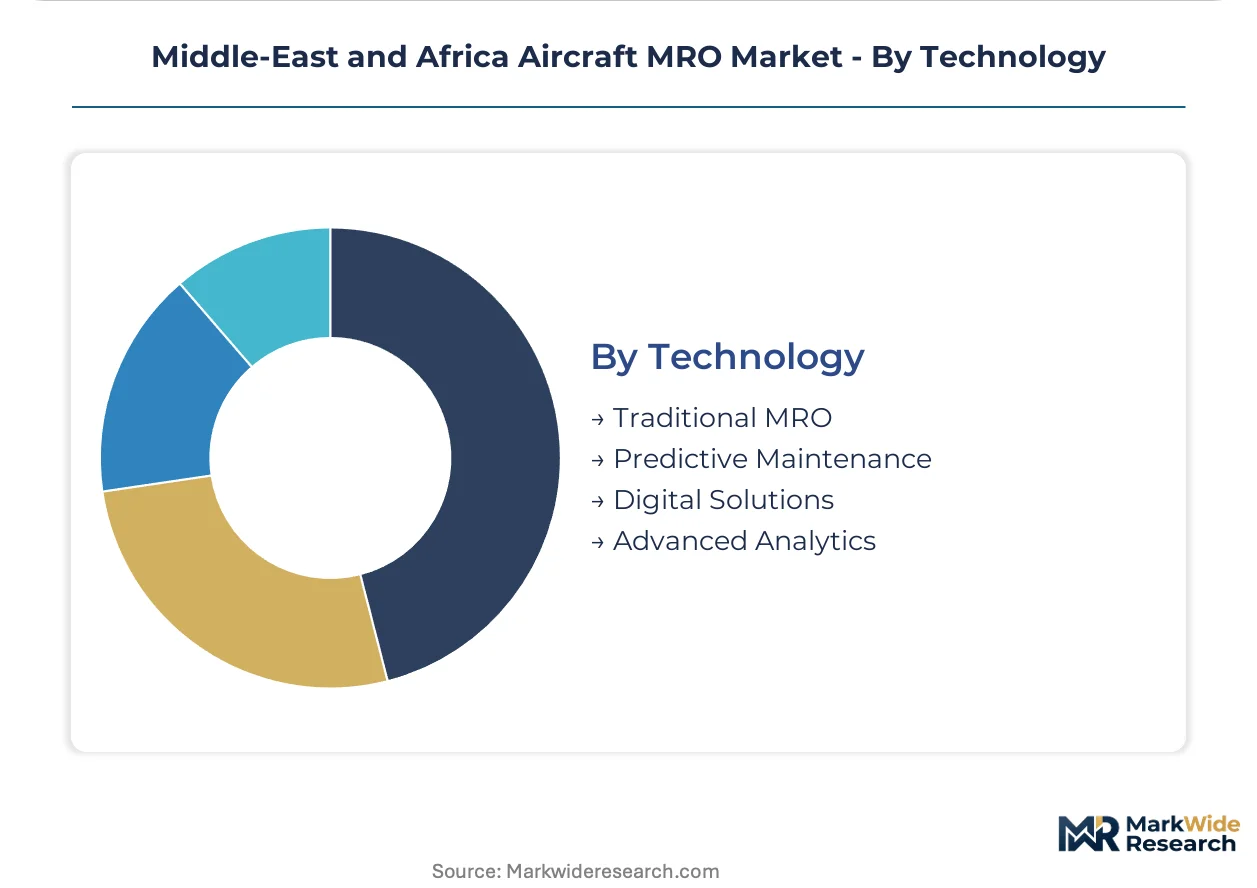
Technology:
Digital maturity stratifies providers between legacy documentation systems and integrated fleet health platforms.
- Predictive Maintenance:Vibration monitoring, oil-debris analysis, and sensor-driven failure anticipation. Emirates Engineering and Saudi Arabian Airlines Engineering pilot digital twin platforms to shift from fixed-interval to condition-triggered shop visits, compressing life-limited parts inventory.
- Digital Solutions:Electronic logbooks, mobile maintenance terminals, and cloud-based work package management.
- Advanced Analytics:Machine learning models for component life prediction and supply chain optimization.
- Traditional MRO:Paper-based documentation and experience-dependent troubleshooting.
Traditional MRO still dominates transaction volume. Predictive Maintenance climbs the fastest as EU AI Act classifications reshape software procurement standards for European-route operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai South's aviation district and Saudi Arabia's King Abdullah Economic City anchor MRO facility concentration through tax holidays and subsidized land leases. These zones compress capital recovery timelines for heavy maintenance infrastructure investments.
United Arab Emirates
Emirates Engineering's captive fleet scale and Etihad's engineering arm drive demand for wide-body overhaul capacity. GCAA airworthiness directives on aging aircraft tighten compliance thresholds for independent providers seeking operating certificates. Dubai International Airport and Al Ain host the densest maintenance clusters, with hangar slot scarcity now constraining physical expansion.
Saudi Arabia
GACA's Vision 2030 aviation targets mandate localization of MRO services previously outsourced to Gulf neighbors. Subsidized greenfield zones near Riyadh and Jeddah attract facility investments with expedited licensing frameworks. Saudia Technic anchors state-linked maintenance capacity, while private operators negotiate long-term contracts for narrow-body heavy checks.
Jordan
Joramco's Amman facility specializes in narrow-body airframe maintenance, serving low-cost carriers from European and Middle Eastern hubs. EASA Part-145 recognition agreements with the country's civil aviation regulator enable seamless work on EU-registered aircraft. Queen Alia International Airport's maintenance campus draws conversion programs for aging Airbus A320 family jets.
Turkey
Turkish Technic extends line maintenance stations across North African hubs, capturing transit traffic between Europe and sub-Saharan markets. The country's customs union with the EU simplifies spare parts movements for European-registered aircraft. Istanbul Airport's mega-hub status supports round-the-clock A-check capacity for carriers avoiding Gulf summer heat restrictions.
Ethiopian Cargo Hub Expansion
Addis Ababa's growing dedicated freighter base generates unmet demand for engine-on-wing support and line maintenance contracts. Ethiopian Airlines MRO leverages the country's strategic position on Asia-Europe cargo corridors. Bole International Airport's cargo terminal expansion attracts e-commerce logistics operators committing to long-term maintenance partnerships.
Middle-East and Africa Aircraft MRO Market Competitive Landscape
Gulf-based engineering divisions anchor the premium tier; Jordanian and Turkish specialists hold mid-market narrow-body positions. Market structure tilts toward captive airline engineering arms with in-house overhaul capacity, while independent providers compete on component repair specialization and geographic reach. Three archetypes dominate: fleet-captive engineering divisions, independent airframe specialists, and OEM-aligned component repair networks. Competitive moves concentrate on capacity expansion into Saudi greenfield zones and predictive maintenance technology licensing.
Within the fleet-captive tier, Emirates Engineering represents scale-driven in-house capability, while Joramco exemplifies independent narrow-body specialization. Sanad Aerotech occupies a position focused on next-generation engine component repair. These three entities anchor distinct competitive vectors: captive vertical integration, independent airframe expertise, and propulsion system component depth.
| Leading Market Players |
|---|
| Joramco |
| Sanad Aerotech |
| Emirates Engineering |
| GE Aerospace |
| Lufthansa Technik |
| Saudia Technic |
| Turkish Technic |
| Rolls-Royce |
| Ethiopian Airlines MRO |
| Others |
Supply & Pricing Matrix
OEM-certified tooling and proprietary diagnostic licenses cascade through pricing tiers, compressing margins for independent MRO providers while fleet-captive engineering divisions at Emirates and Saudia Technic internalize cost advantages through scale procurement of life-limited parts. GCAA and EASA Part-145 certification requirements stratify the market into premium OEM-aligned shops, mid-tier independent specialists like Joramco, and economy line maintenance stations competing on turnaround speed.
Pricing Analysis
Short lead-time premiums for AOG (aircraft on ground) situations command substantial markups over scheduled heavy maintenance slots, while spot inventory for LEAP and GTF engine components trades at distressed premiums when supply tightens. Three-tier pricing structure across premium OEM-certified, standard independent, and economy line maintenance tiers reflects certification grade and vertical integration depth. Pricing pressure stems from airline procurement departments unbundling heavy maintenance packages into discrete line items for competitive bidding. Low-cost carriers operating from Dubai and Sharjah hubs exhibit highest price sensitivity, while Emirates and Etihad prioritize turnaround reliability over unit cost.
Supply Chain Analysis
Dual-sourcing mandates from Gulf carriers require qualified alternates for critical engine components, forcing MRO providers to maintain redundant approved vendor lists across GE Aerospace and Rolls-Royce networks. Supply concentration rests on the United States, France, and the United Kingdom for OEM proprietary diagnostics and certified replacement parts. Raw material dependencies include titanium alloys for engine components, carbon fiber prepregs for composite repairs, and specialized aviation-grade lubricants. Single-source vulnerability from Boeing and Airbus approved parts distribution creates captive dependencies limiting third-party pricing leverage. Distribution runs through OEM-controlled logistics networks and regional bonded warehouses at Dubai South and King Abdullah Economic City.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle-East and Africa Aircraft MRO market sits in a technology-transition phase as predictive maintenance algorithms displace fixed-interval overhaul scheduling, compressing inventory holdings and redistributing value toward data analytics capabilities.
For Market Incumbents: Anchor defensive positioning through backward integration into predictive maintenance software licensing and exclusive component repair authorizations for LEAP and GTF engine families. Expand hangar capacity at Saudi greenfield zones near Riyadh to capture GACA localization mandates before competitors secure expedited licensing. The threat of airline procurement fragmentation into discrete line items demands certification investment beyond base EASA Part-145 to OEM-specific composite repair qualifications.
For New Entrants and Emerging Players: The price-point gap between premium OEM-aligned shops and economy line maintenance stations opens white-space for mid-tier specialists targeting narrow-body heavy checks at secondary hubs. Target Ethiopian Airlines MRO expansion at Addis Ababa for engine-on-wing support contracts as cargo conversion programs accelerate. Enter through component repair specialization rather than full-service airframe competition, leveraging shorter capital recovery timelines and lower regulatory barriers.
For Investors and Strategic Acquirers: GACA's first major greenfield MRO zone announcement is the leading indicator that Saudi localization mandates are creating structural capacity shortages addressable through acquisition. The five-to-ten year viability window favors platform plays consolidating independent component repair stations with complementary OEM authorizations. Watch for Emirates Engineering or Saudia Technic divesting non-core line maintenance stations as predictive maintenance investments shift capital allocation toward software capabilities.
| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Deployment | Digital twin integration at Emirates Engineering compresses unscheduled downtime and life-limited parts inventory. |
| Saudi Greenfield Facility Investment | GACA's subsidized land leases near Riyadh accelerate capital recovery timelines for heavy maintenance infrastructure. |
| LEAP/GTF Component Repair Authorization | OEM-certified tooling for next-generation engines captures value from fleet renewal programs across Gulf carriers. |
| Ethiopian Cargo Hub Partnership | Addis Ababa's Asia-Europe corridor position offers untapped line maintenance contracts for dedicated freighter operators. |
| EASA-GCAA Dual Certification Investment | Integrated quality management systems satisfy converging audit frequencies for European-registered aircraft serving Dubai hubs. |
Research Methodology
Independent corroboration across primary interviews with MRO operations directors, airline procurement executives, GCAA regulatory affairs officers, and component repair station managers, combined with secondary validation from EASA Part-145 audit disclosures, GCAA airworthiness directive filings, and customs/trade data for aviation parts movements, underwrites the qualitative findings. Bottom-up technician deployment timelines and facility capacity utilization rates triangulate against top-down fleet renewal program announcements from Emirates, Etihad, and Saudia.
Comparable-period anchoring to historical heavy maintenance cycle frequencies and engine shop visit intervals structures the projection framework across the analysis window. Segmentation dimensions modeled include service type, end-user category, maintenance scheduling approach, and technology adoption tier, with additional granularity on regulatory jurisdiction clustering. CAGRs derive from facility expansion announcements, technician training pipeline outputs, and OEM service bulletin proliferation rates for next-generation propulsion systems.
Underlying measurement precision varies by segment; engine overhaul and predictive maintenance technology carry tighter precision than fragmented line maintenance stations. Forecasts reflect assumptions on regulatory reciprocity negotiations between Gulf aviation authorities and African civil aviation bodies, LEAP and GTF engine reliability improvement trajectories, and airline unbundling of maintenance procurement packages. Deviation in OEM proprietary diagnostic licensing terms or GCAA enforcement intensity on aging aircraft would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Maintenance and MRO Solutions
US Aviation MRO Software Market
Aircraft Maintenance and MRO Solutions
Aircraft Weighing Scales Market
Aircraft Maintenance and MRO Solutions
Aviation Test Equipment Market
Aircraft Maintenance and MRO Solutions
Aircraft Vacuum Cleaners Market
Aircraft Maintenance and MRO Solutions
Cloud MRO Software Market
Aircraft Maintenance and MRO Solutions
Aviation Maintenance Repair and Overhaul MRO Software Market
Aircraft Maintenance and MRO Solutions
Aerospace and Defense MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Towing Equipment Market
Aircraft Maintenance and MRO Solutions
Air Transport MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Modernization Market
Aircraft Maintenance and MRO Solutions
Aircraft Exterior Strip and Repaint Services Market
Aircraft Maintenance and MRO Solutions
Commercial Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Regional Turboprop Engine MRO Services Market
Aircraft Maintenance and MRO Solutions
Aircraft Line Maintenance Market
Aircraft Maintenance and MRO Solutions
Commercial Aircraft Maintenance Repair and Overhaul (MRO) Market
Aircraft Maintenance and MRO Solutions
Digital MRO Market