
 Commercial Aircraft MRO Market | 2026-2036
Commercial Aircraft MRO Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Aircraft MRO Market Analysis
Freight carrier operations is realigning MRO demand toward cargo-converted aircraft and high-utilization freighter programs. Lufthansa Technik dominates wide-body cabin reconfiguration and VIP completion services. ST Engineering leverages its Singapore hub to anchor Southeast Asian line maintenance networks. GE Aviation sustains engine overhaul leadership through its TrueChoice portfolio and material science investments.
Commercial Aircraft MRO encompasses the inspection, repair, overhaul, and modification of airframes, engines, and components to maintain airworthiness and operational reliability, governed by flight cycle limits, corrosion thresholds, and fatigue-life monitoring protocols. Engine overhaul captures the deepest margin pools due to proprietary OEM tooling and life-limited part replacement cycles. Component repair is accelerating fastest as airlines pursue part-out economics and DER-approved repairs to defer new unit purchases. AI diagnostics and predictive maintenance are reshaping scheduled maintenance intervals, shifting volume from time-based to condition-based interventions.
The FAA mandates airworthiness directives under CFR Title 14, while EASA enforces continuing airworthiness through Part-M and Part-145 frameworks, compressing turnaround windows for non-compliant operators. India's DGCA aligns with ICAO standards but imposes additional localization requirements for foreign MRO providers seeking operating permits. Stakeholders must monitor regulatory divergence between FAA and EASA on additive manufacturing certification for flight-critical components.
Market Dynamics
The Commercial Aircraft MRO sector is experiencing a structural compression of maintenance intervals as predictive analytics and flight-hour accumulation patterns force operators to abandon rigid calendar-based schedules for condition-driven interventions.
Growth Catalysts
- FAA Airworthiness Directive enforcement:The CFR Title 14 framework mandates accelerated compliance timelines for aging narrow-body fleets, expanding heavy check volume at US-based facilities.
- Asia-Pacific low-cost carrier expansion:Indian and Southeast Asian airlines are pushing fleet utilization rates beyond 14 hours daily, compressing maintenance cycles and driving line maintenance network buildouts.
- Additive manufacturing qualification:DER-approved repairs and 3D-printed replacement components are extending component life cycles and reducing new part procurement lead times.
Market Restraints
- Life-limited part supply concentration:Proprietary OEM tooling and certified material supply chains concentrate in US and European tier-one manufacturers, creating single-source dependencies for critical engine components.
- Specialized technician scarcity:Airframe and powerplant certificated mechanics with composite repair expertise face structural shortages across North American and European maintenance bases.
- Freighter conversion input cost volatility:Wide-body feedstock aircraft pricing and cargo door modification kit availability fluctuate with passenger airline retirement cycles and raw aluminum sheet supply.
Strategic Opportunities
- India DGCA localization mandates:Foreign MRO providers establishing joint ventures with domestic partners gain preferential operating permits under revised bilateral maintenance agreements.
- AI diagnostics convergence with IoT sensor networks:Real-time engine health monitoring and predictive fault detection are enabling power-by-the-hour contract restructuring and risk-sharing models.
- Cargo-converted aircraft aftermarket:E-commerce fulfillment networks in Southeast Asia and the Middle East are generating dedicated freighter MRO demand separate from passenger fleet cycles.
Industry Challenges
- Part-out economics certification complexity:DER-approved repairs and used serviceable material traceability documentation create compliance bottlenecks at component shops.
- Legacy airframe documentation gaps:Aging aircraft original build records and modification histories complicate fatigue-life monitoring protocol establishment for pre-digital era fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Aircraft MRO Market |
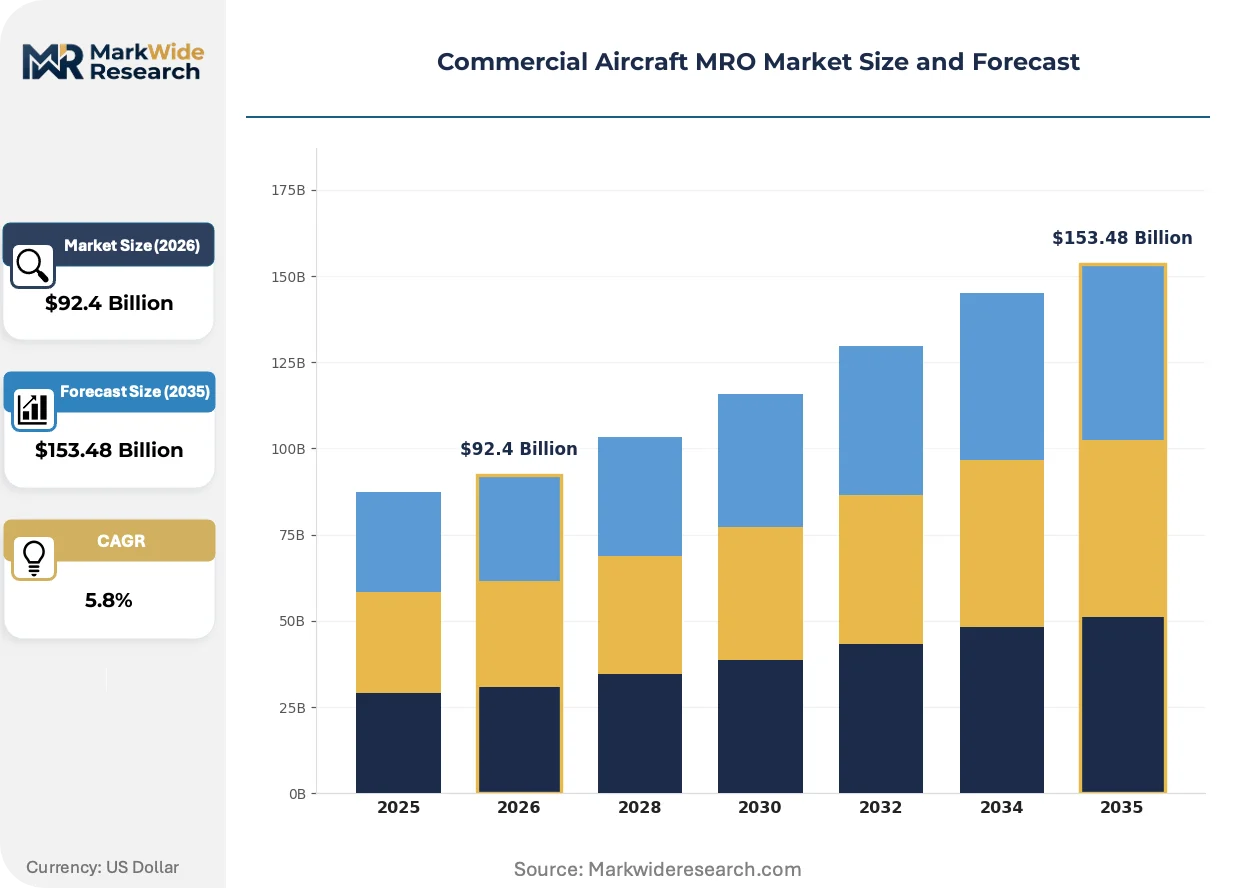
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $153.48 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Airframe Maintenance, Engine Overhaul, Component Repair, Line Maintenance End User: Airlines, Business Aviation, Military Operators, Freight Carriers Application: Scheduled Maintenance, Unscheduled Maintenance, Modification, Refurbishment Technological Focus: AI Diagnostics, Data Analytics, Predictive Maintenance, Digital Twin |
| Companies Covered | Lufthansa Technik, AAR Corp, Delta TechOps, ST Engineering, GE Aviation, HAECO, Airbus SE, RTX Corporation, Safran Aircraft Engines, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Aircraft MRO Market Emerging Trajectories
Predictive maintenance architectures are displacing fixed-interval interventions across engine, airframe, and component disciplines, compressing turnaround windows while extending on-wing performance.
Digital twin technology is consolidating maintenance planning workflows by integrating flight data recorder outputs, borescope inspection imagery, and material degradation models into unified asset health dashboards. Full-service carriers and lessors are deploying these platforms to optimize green time utilization before shop visits. The technology is consolidating vendor relationships as airlines reduce point-solution providers in favor of integrated analytics suites.
EASA's continuing airworthiness Part-M and Part-145 framework revisions are tightening non-compliance penalties and compressing documentation audit cycles for third-party maintenance organizations. European operators face accelerated adoption of electronic logbook standards and real-time airworthiness data submission. Component repair stations in Germany, France, and the Netherlands are investing in integrated quality management systems to maintain Part-145 certification under intensified surveillance.
Airline procurement teams are unbundling traditional heavy maintenance packages into discrete airframe, engine, and component workscopes awarded to specialized providers. Network carriers in India and Southeast Asia are fragmenting single-source relationships to capture competitive pricing and reduce dependency on integrated MRO groups. This pattern is most visible among low-cost carriers operating narrow-body fleets above 150 aircraft, where procurement functions have established dedicated vendor performance scorecards and annual sourcing events.
Commercial Aircraft MRO Market Segmentation
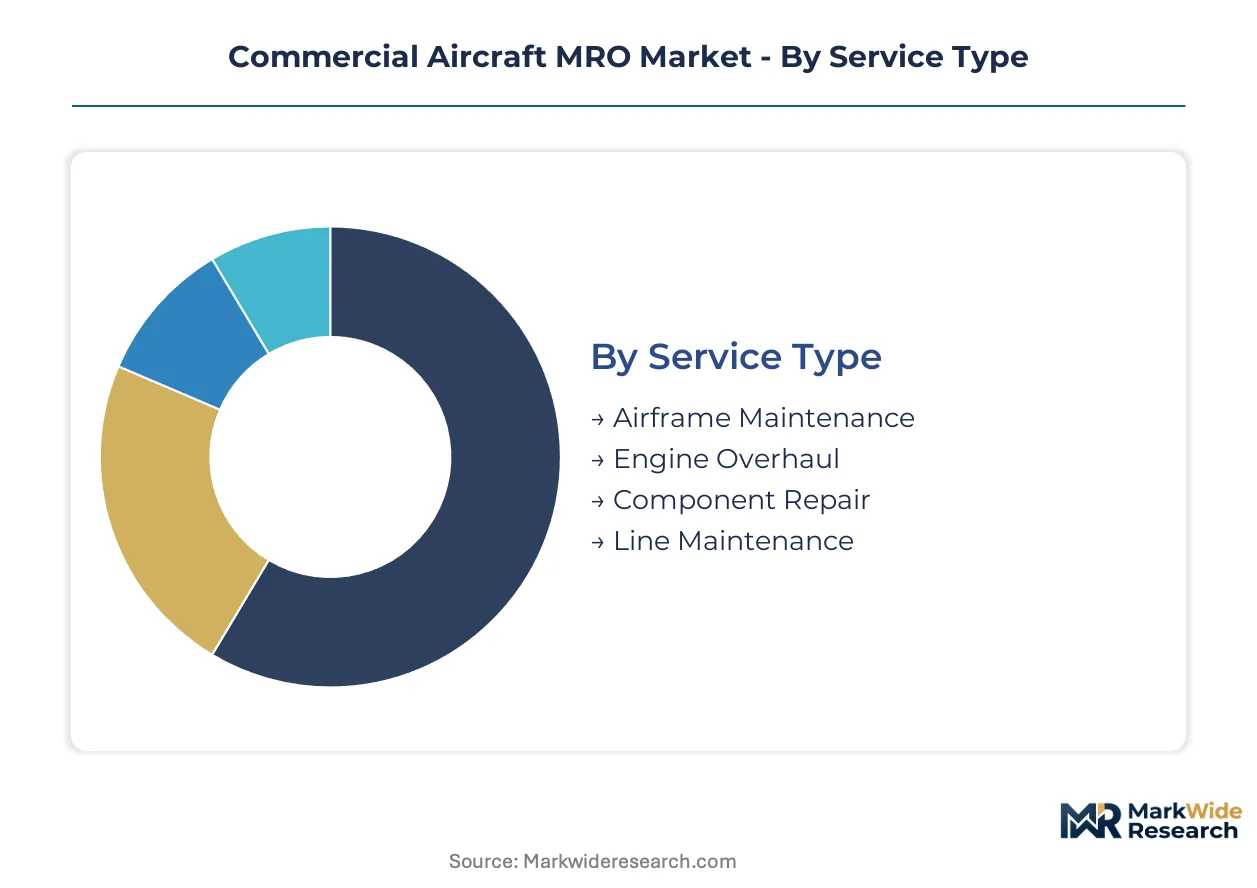
Commercial aircraft MRO segmentation reveals divergent margin profiles across service disciplines and technology adoption curves. Upgrade cycles and replacement economics vary sharply between airframe heavy checks and engine life-limited part programs.
Service Type:
Replacement-cycle intensity distinguishes overhaul economics across service categories, with engine programs commanding multi-million dollar shop visits against routine line maintenance touchpoints.
- Airframe Maintenance:Structural inspections, corrosion treatment, and fatigue-life extension programs for fuselage and wing assemblies. Demand clusters at Southeast Asian facilities serving narrow-body fleets accumulating high flight-hour density from low-cost carrier operations.
- Engine Overhaul:Disassembly, refurbishment, and life-limited part replacement for turbine modules using proprietary OEM tooling. Margin concentration follows CFM International and Pratt & Whitney powerplant installed bases in India and the United Arab Emirates.
- Component Repair:DER-approved repairs and used serviceable material refurbishment for avionics, landing gear, and auxiliary power units.
- Line Maintenance:Daily transit checks, A-check equivalents, and minor defect rectification at airport-based stations.
Volume placements concentrate in Line Maintenance; the faster expansion belongs to Component Repair.
End User:
Customer-type economics separate scheduled network carriers from opportunistic maintenance buyers with irregular flight profiles.
- Airlines:Full-service and low-cost carriers executing continuous airworthiness programs under EASA Part-M and FAA CFR Title 14 mandates. Procurement fragmentation is visible among Indian low-cost operators unbundling heavy maintenance into discrete workscopes.
- Freight Carriers:Dedicated cargo operators and converted freighter lessors pursuing high-utilization programs separate from passenger fleet cycles. E-commerce fulfillment networks in Southeast Asia and the Middle East anchor demand.
- Business Aviation:Corporate and private aircraft operators requiring VIP completion and cabin reconfiguration services.
- Military Operators:Defense airworthiness frameworks with sovereign maintenance infrastructure and limited commercial outsourcing.
Revenue concentration sits with Airlines; Freight Carriers are climbing the fastest.
Application:
Application-based segmentation tracks intervention timing from calendar-driven schedules toward condition-triggered responses.
- Scheduled Maintenance:Calendar and flight-hour based airworthiness interventions including C-checks and engine performance restoration. AI diagnostics and IoT sensor networks are compressing fixed-interval assumptions.
- Modification:Freighter conversion, cabin reconfiguration, and avionics retrofit programs. Wide-body feedstock availability and cargo door kit supply constrain program economics.
- Unscheduled Maintenance:AOG response and defect correction outside planned maintenance windows.
- Refurbishment:Aesthetic and functional cabin upgrades extending asset service life.
Intervention volume concentrates in Scheduled Maintenance; Modification workscopes are gaining share fastest.
Technological Focus:
Technology-segment maturity separates pilot implementations from scaled predictive architectures.
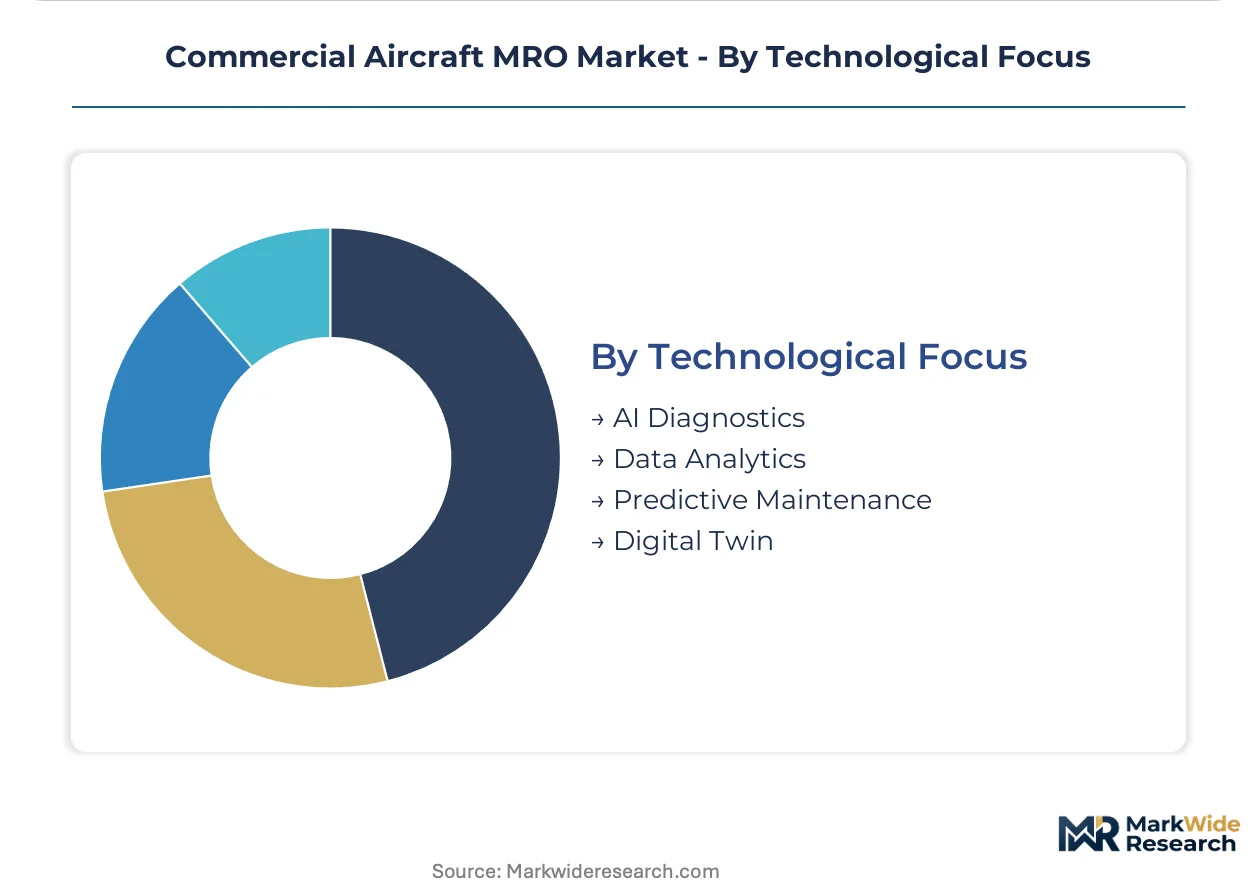
- Predictive Maintenance:Condition-based intervention scheduling using degradation models and real-time health indicators. Power-by-the-hour contract restructuring and risk-sharing models follow adoption.
- Digital Twin:Unified asset health dashboards integrating flight data, borescope imagery, and material science models. Full-service carriers and lessors deploy these platforms to optimize green time utilization.
- AI Diagnostics:Machine learning fault detection and automated inspection analysis.
- Data Analytics:Descriptive and diagnostic maintenance history mining.
Deployment volume concentrates in Data Analytics; Predictive Maintenance shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates engine overhaul capacity and proprietary OEM tooling, while consumption gravity shifts toward India and Southeast Asia where narrow-body fleet utilization rates exceed fourteen hours daily.
United States
FAA CFR Title 14 mandates accelerated compliance timelines for aging narrow-body fleets, expanding heavy check volume at US-based facilities. The FAA's Airworthiness Directive framework compresses turnaround windows for non-compliant operators. Dallas-Fort Worth anchors line maintenance networks serving domestic low-cost carriers with above-average flight-hour accumulation.
Germany
EASA Part-M and Part-145 framework revisions tighten non-compliance penalties and compress documentation audit cycles for third-party maintenance organizations. EASA's continuing airworthiness regulations enforce real-time airworthiness data submission standards. Hamburg concentrates wide-body cabin reconfiguration and VIP completion services for European full-service carriers.
India
DGCA localization mandates require foreign MRO providers to establish joint ventures with domestic partners for preferential operating permits. Indian low-cost carriers unbundle heavy maintenance into discrete airframe, engine, and component workscopes awarded through annual sourcing events. Mumbai and Delhi-NCR anchor Southeast Asian line maintenance network buildouts serving narrow-body fleets above 150 aircraft.
Singapore
ST Engineering leverages its Singapore hub to anchor Southeast Asian line maintenance networks serving high-utilization low-cost carrier operations. The country's national aviation regulator aligns with ICAO standards while maintaining bilateral maintenance agreements with regional partners. Changi Aviation Park concentrates component repair stations investing in integrated quality management systems.
United Arab Emirates
E-commerce fulfillment networks in the Middle East generate dedicated freighter MRO demand separate from passenger fleet cycles. The country's civil aviation authority enforces continuing airworthiness protocols for cargo-converted aircraft operating high-utilization programs. Dubai South anchors freighter conversion input sourcing and cargo door modification kit staging for regional cargo operators.
Commercial Aircraft MRO Market Vendor Landscape
Top-tier vendors anchor integrated full-service portfolios, while mid-tier specialists capture fragmented component repair and line maintenance niches. The market structures around OEM-captive engine overhaul shops, independent airframe heavy check providers, and diversified aerospace conglomerates with MRO divisions. Strategic archetypes include powerplant-focused OEM affiliates, airline-captive maintenance divisions, and independent third-party service networks. Competitive moves concentrate on geographic joint ventures for regulatory access and predictive maintenance technology licensing.
Within the integrated service tier, Lufthansa Technik and GE Aviation exemplify archetypes spanning wide-body cabin reconfiguration and engine overhaul leadership respectively. ST Engineering occupies a position representing Southeast Asian hub-based network strategies. AAR Corp and Delta TechOps sit within the airline-affiliated and independent third-party vectors, while HAECO anchors Asia-Pacific component repair concentration.
| Leading Market Players |
|---|
| Lufthansa Technik |
| AAR Corp |
| Delta TechOps |
| ST Engineering |
| GE Aviation |
| HAECO |
| Airbus SE |
| RTX Corporation |
| Safran Aircraft Engines |
| Others |
Supply Flow & Price Mechanics
Airframe and powerplant certificated mechanics with composite repair expertise in North America and Western Europe command wage premiums that compress pricing-tier spreads between premium OEM-captive overhaul shops and independent third-party facilities.
Pricing Analysis
Margin tightening in engine overhaul reflects proprietary OEM tooling lock-in and life-limited part replacement economics. Three-tier pricing structure across premium OEM-captive, standard independent heavy-check, and economy line-maintenance levels separates certification-grade capabilities. Cost-down pressure on component repair accelerates because airlines unbundle workscopes and pursue DER-approved repairs. Low-cost carriers in India and Southeast Asia exhibit highest price sensitivity; full-service carriers with power-by-the-hour contracts show lowest.
Supply Chain Analysis
Direct-to-OEM channels handle proprietary turbine module and life-limited part demand, while independent distributors manage used serviceable material flows. Supply concentrates in the United States, Germany, and Singapore for critical engine components, specialty alloys, and avionics systems. Raw material dependencies span nickel-based superalloys, titanium forgings, and composite prepregs. Single-source vulnerability around proprietary OEM tooling creates structural risk. Distribution runs through airline procurement functions, lessor technical asset managers, and third-party MRO procurement consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where proprietary material science capabilities and captive engine component supply determine margin capture.
For Market Incumbents: Extend predictive maintenance technology licensing to lock in airline data dependencies and reduce customer churn. Secure exclusive joint ventures with Indian domestic partners under DGCA localization mandates to defend against emerging regional competitors. Backward integration into additive manufacturing qualification for flight-critical components preserves proprietary repair margins.
For New Entrants and Emerging Players: Capture component repair white space in Southeast Asia where e-commerce fulfillment networks generate dedicated freighter MRO demand separate from passenger fleet cycles. Target India's fragmented procurement landscape where low-cost carriers unbundle heavy maintenance into discrete workscopes. Lead with DER-approved repair certification and rapid turnaround positioning against incumbent OEM-captive shops.
For Investors and Strategic Acquirers: The window for entry favors specialized component repair stations with established Part-145 certification and narrow-body fleet exposure. Long-term viability hinges on predictive maintenance platform integration and power-by-the-hour contract restructuring capabilities. Watch for AI diagnostics convergence with IoT sensor networks as the inflection signal for contract model shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Deployment | Enables power-by-the-hour restructuring and risk-sharing with airlines under EASA Part-M frameworks. |
| Joint Venture for Regulatory Access | DGCA localization mandates in India require domestic partnerships for preferential operating permits. |
| Additive Manufacturing Qualification | FAA-EASA divergence on flight-critical component certification creates first-mover advantage windows. |
| Freighter Conversion Capability Buildout | E-commerce networks in Southeast Asia and the Middle East generate dedicated cargo MRO demand. |
| Technician Training Pipeline Investment | Structural scarcity of A&P mechanics with composite expertise constrains capacity expansion. |
Methodological Framework
Independent corroboration across MRO operations executives, airline fleet planning directors, and regulatory compliance officers underwrites the qualitative findings. Primary fieldwork with engine overhaul shop managers, component repair station technical leads, and lessor asset management teams combined with secondary validation from FAA Airworthiness Directive filings, EASA Part-145 certification databases, and ICAO continuing airworthiness records. Bottom-up triangulation across facility capacity utilization and top-down cross-checks against fleet flight-hour accumulation patterns anchored segmentation outputs.
Rate-of-change decomposition across service type, end user, application, and technological focus dimensions modeled volume and value trajectories. CAGRs derived from regression analysis of historical shop visit intervals, fleet age distributions, and regulatory compliance cycle compression. Forecast inputs incorporated predictive maintenance adoption curves and narrow-body fleet utilization patterns across the analysis window.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory divergence on additive manufacturing certification and life-limited part supply chain disruptions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Maintenance and MRO Solutions
Southeast Asia Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Africa Aircraft Windshield Wiper and Washer System Market
Aircraft Maintenance and MRO Solutions
Colombia Commercial Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Global Aerospace Maintenance Chemical Market
Aircraft Maintenance and MRO Solutions
Commercial Aircraft Landing Gear MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Tire Balancer Market
Aircraft Maintenance and MRO Solutions
North America Aircraft Engine MRO Market
Aircraft Maintenance and MRO Solutions
Latin America Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Wheel Bead Breakers Market
Aircraft Maintenance and MRO Solutions
Global Aircraft Heavy Maintenance Visits Market
Aircraft Maintenance and MRO Solutions
US Aerospace Components MRO Market
Aircraft Maintenance and MRO Solutions
Aviation MRO Software Market
Aircraft Maintenance and MRO Solutions
Digital Aerospace MRO Market
Aircraft Maintenance and MRO Solutions
US Aviation MRO Software Market
Aircraft Maintenance and MRO Solutions
Nigeria Aircraft Maintenance Repair and Overhaul Market
Aircraft Maintenance and MRO Solutions
Global Aircraft Engine MRO Market