
 Colombia Commercial Aircraft MRO Market | 2026-2036
Colombia Commercial Aircraft MRO Market Size, Share, and Industry Trends Forecast 2026-2036
Colombia Commercial Aircraft MRO Market Outlook
Colombia's MRO sector is decoupling from legacy dependency on foreign overhaul capacity as domestic hangar infrastructure expands. Avianca Services leverages its integrated airline-operator heritage to anchor heavy maintenance workflows at El Dorado. Lufthansa Technik Colombia competes through specialized engine module repair capabilities serving Andean operators. Aeroman Colombia sustains cost-advantaged airframe overhaul lines that attract regional carrier contracts from Panama and Peru.
Commercial aircraft maintenance, repair, and overhaul encompasses scheduled inspections, structural repairs, engine restoration, and avionics upgrades performed on turbine-powered fixed-wing aircraft operating under Part 121 or equivalent commercial certificates. Colombian facilities typically handle C-check intervals of 4,000-6,000 flight hours and incorporate non-destructive testing protocols including eddy-current and ultrasonic inspection for fatigue-critical structures. Engine maintenance commands premium labor rates due to specialized tooling and OEM-authorized technician requirements, while line maintenance at Colombian hubs captures high-frequency, lower-margin turnaround volumes. Predictive maintenance technology adoption accelerates as carriers deploy aircraft health management systems to compress unscheduled downtime.
Colombia's civil aviation regulator enforces maintenance standards derived from FAA Part 145 equivalency agreements, while ICAO Annex 6 compliance mandates continuous airworthiness management program audits for all commercial operators. The country's central bank and tax authority administer import duty structures on aircraft parts that directly influence MRO sourcing economics between domestic repair and offshore alternatives. Stakeholders must monitor upcoming airworthiness directive harmonization between Colombian regulators and EASA to anticipate certification burden shifts.
Market Dynamics
Colombia's MRO sector is pivoting toward predictive maintenance architectures as narrow-body fleet utilization rates climb and carriers demand compressed turnaround windows at El Dorado's congested maintenance cluster.
Growth Catalysts
- FAA Part 145 Equivalency:Alignment with US maintenance standards streamlines technician certification pathways and unlocks bilateral airworthiness recognition for Colombian facilities serving US-registered aircraft.
- Narrow-Body Fleet Expansion:Low-cost carriers operating Airbus A320 and Boeing 737 families generate recurring component maintenance volumes that sustain dedicated line maintenance stations.
- Andean Geographic Positioning:Bogotá's elevation and central South American location position Colombian MRO providers as cost-competitive alternatives to Miami and São Paulo for regional carrier contracts.
Market Restraints
- Specialized Tooling Import Costs:OEM-authorized engine module repair requires capital-intensive diagnostic equipment subject to Colombian customs duties that inflate project economics versus offshore alternatives.
- Single-Hub Infrastructure Concentration:El Dorado International Airport hosts over 80 percent of certified heavy maintenance capacity, creating operational vulnerability to runway closures or regulatory enforcement actions.
- Technical Talent Pipeline Constraints:FAA-equivalent airframe and powerplant certification programs produce fewer than 200 qualified technicians annually, below replacement rates for retiring workforce cohorts.
Strategic Opportunities
- Medellín Secondary Hub Development:José María Córdova International Airport offers unconstrained hangar expansion potential and lower labor costs for airframe overhaul lines targeting Central American carrier contracts.
- Aircraft Health Management Convergence:Integration of IoT sensor networks with maintenance execution systems enables condition-based interventions that extend component life cycles beyond traditional hard-time limits.
- EASA Harmonization Pathway:Pending regulatory alignment with European aviation safety standards would open certification reciprocity for Colombian facilities seeking European-registered aircraft contracts.
Industry Challenges
- Composite Repair Certification Backlogs:Boeing 787 and Airbus A350 airframe technologies require specialized resin infusion and autoclave capabilities that exceed current Colombian technical training infrastructure.
- Legacy System Integration Friction:Paper-based maintenance release documentation persists at smaller Colombian operators, complicating digital logbook harmonization with international lessor requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Colombia Commercial Aircraft MRO Market |
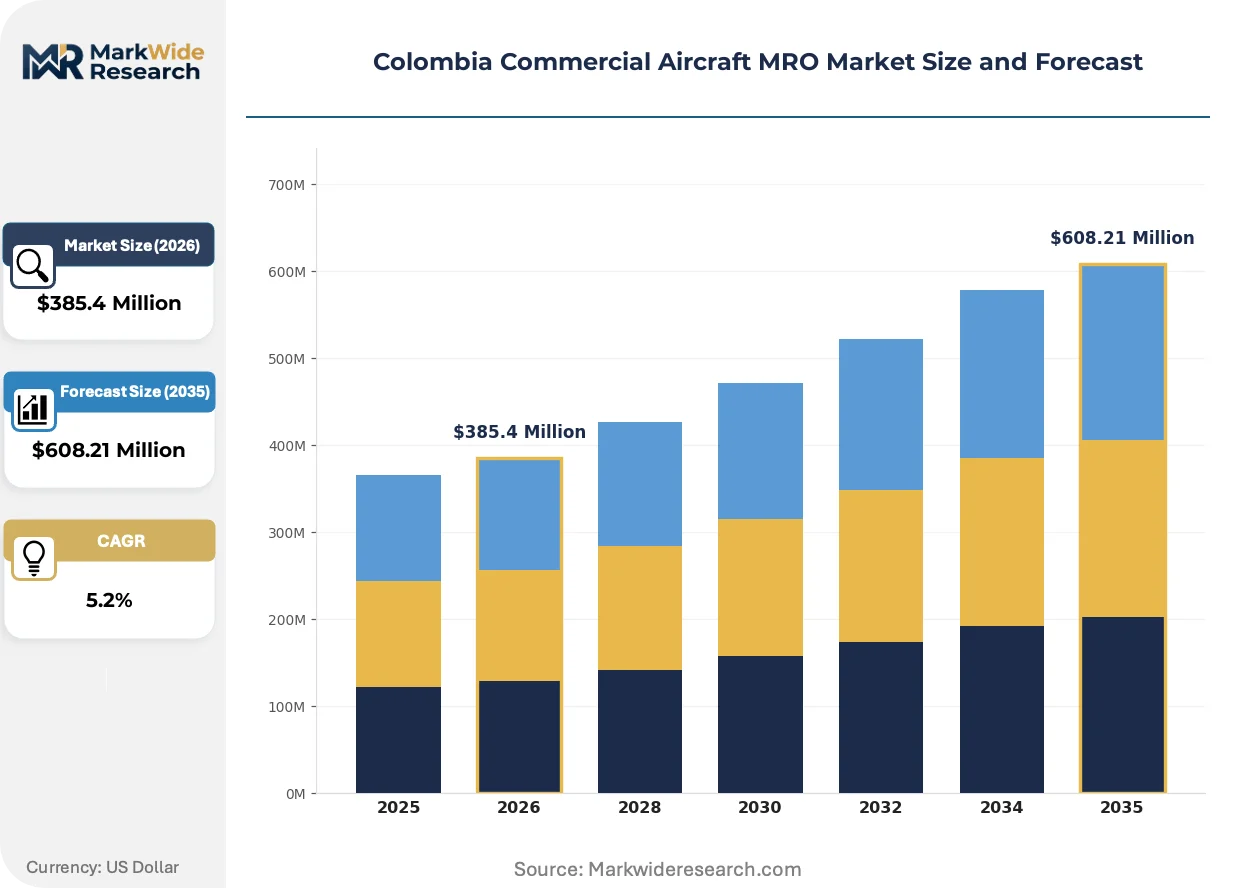
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $608.21 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Airframe Maintenance, Component Maintenance, Engine Maintenance, Line Maintenance Application: Airline Operators, Freight Carriers, Charter Services, Government Agencies Technology: Predictive Maintenance, Condition-Based Monitoring, Aircraft Health Management, Digital Twin End User: Commercial Airlines, Cargo Airlines, Maintenance Providers, Leasing Companies |
| Companies Covered | Avianca Group, Lufthansa Technik Colombia, Aeroman Colombia, SGS Colombia S.A.S, Safran SA, ACC Columbia Jet Service GmbH, Avianca Services, Copa Airlines Colombia Technical Services, Indaer Aviation Technical Services S.A.S, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Colombia Commercial Aircraft MRO Market Strategic Shifts
Predictive analytics and regulatory digitization are compressing maintenance planning cycles while reshaping how Colombian facilities compete for regional carrier contracts against established Miami and São Paulo hubs.
Digital twin technology is integrating aircraft structural and systems data into virtual replicas that simulate degradation patterns before physical inspection. Avianca and Viva Colombia are deploying these platforms to prioritize hangar slot allocation based on actual component condition rather than calendar intervals. This shift is integrating maintenance scheduling with flight operations in real-time, eliminating buffer days that previously padded turnaround timelines.
Colombia's civil aviation authority is implementing electronic maintenance release signatures and blockchain-anchored logbook verification to satisfy ICAO Annex 6 audit requirements. The regulatory transition forces smaller Part 145 repair stations to abandon paper-based documentation systems or face certificate limitations. Engine overhaul specialists at El Dorado are responding fastest, digitizing module tracking to secure lessor acceptance of Colombian maintenance releases.
Airline procurement departments are unbundling heavy maintenance contracts into discrete work packages awarded through competitive tender rather than sole-source legacy relationships. Low-cost carriers now separate airframe checks from engine overhauls and component repairs, pitting Lufthansa Technik Colombia against Aeroman on individual line items. This fragmentation is most visible in Viva Colombia's recent maintenance strategy, which sources C-check airframe work domestically while shipping engine modules to Central American facilities.
Colombia Commercial Aircraft MRO Market Segmentation
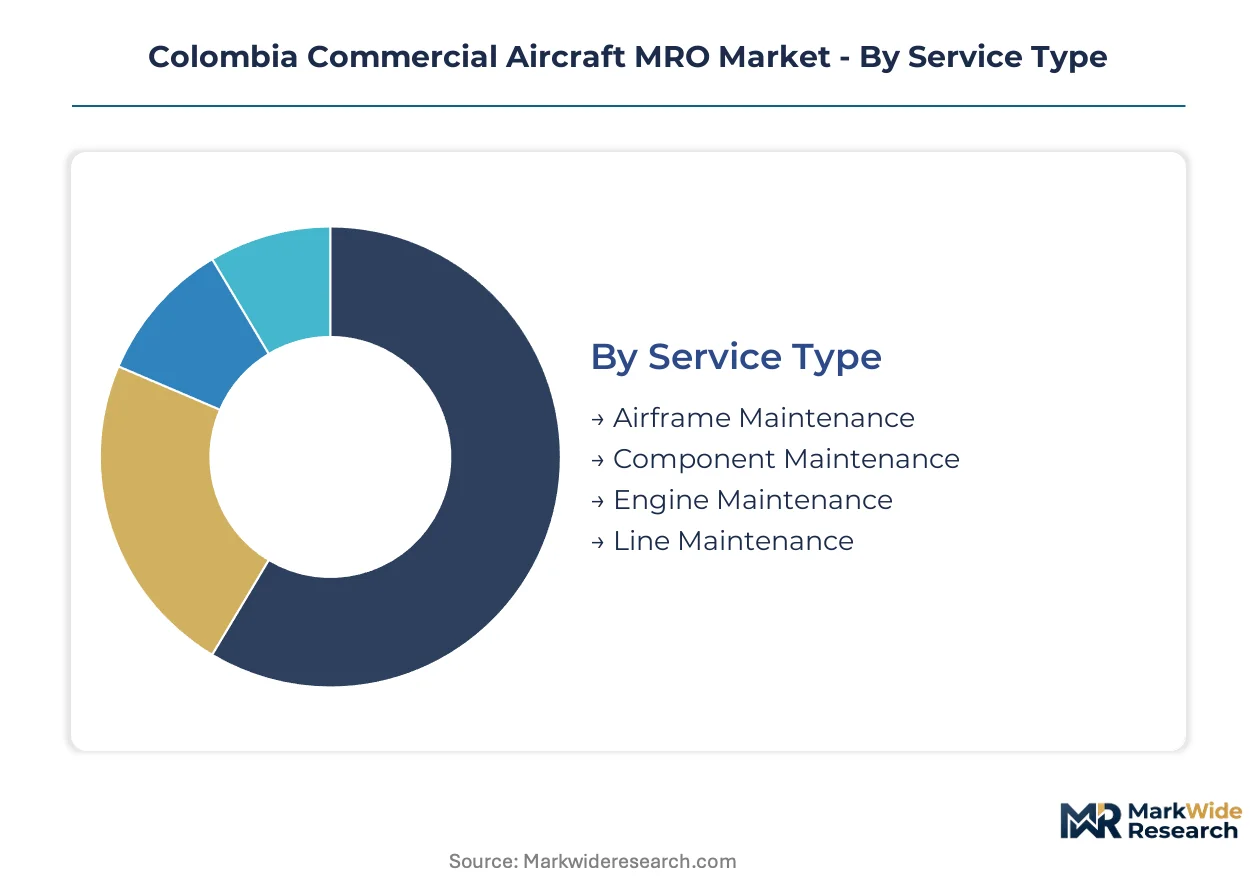
Colombia's MRO market segments reflect divergent margin profiles and capital intensity requirements. Service type determines facility infrastructure needs, while technology adoption separates legacy operators from digitally integrated competitors.
Service Type:
Supply concentration at El Dorado International Airport concentrates heavy maintenance capacity in airframe and engine disciplines, while line maintenance disperses across regional airports serving low-cost carrier networks.
- Airframe Maintenance:Heavy structural inspections and C-check intervals demand dedicated hangar bays with non-destructive testing capabilities. Bogotá's maintenance cluster captures the bulk of narrow-body airframe contracts from Avianca and Viva Colombia as carriers consolidate heavy checks domestically.
- Engine Maintenance:Module repair and overhaul require OEM-authorized tooling and specialized technician certifications that command premium labor rates. Lufthansa Technik Colombia anchors this segment through bilateral airworthiness recognition for US-registered powerplants.
- Component Maintenance:Landing gear, avionics, and auxiliary power unit repairs sustain dedicated workshop lines at Aeroman Colombia.
- Line Maintenance:High-frequency turnaround services at José María Córdova International Airport and Rafael Núñez International Airport support point-to-point carrier networks.
Airframe maintenance absorbs the bulk of installed capacity; engine maintenance is expanding most quickly through foreign specialist investment.
Application:
Customer type dictates contract structure and payment terms, with airline operators demanding integrated fleet management while freight carriers prioritize unit cost minimization on aging aircraft.
- Airline Operators:Scheduled carriers under Part 121 certificates require continuous airworthiness management programs with predictive maintenance integration. Avianca Services leverages vertical integration to internalize heavy maintenance workflows and compress turnaround windows at El Dorado.
- Freight Carriers:Cargo operators running converted narrow-body freighters prioritize cost-advantaged airframe checks and deferred engine overhauls. Colombian integrators source C-check work from Aeroman Colombia while shipping powerplants to Central American facilities with lower labor rates.
- Charter Services:Non-scheduled operators under Part 135 certificates generate sporadic maintenance demand with less predictable hangar scheduling.
- Government Agencies:Presidential and military transport fleets require specialized security-cleared maintenance releases with restricted facility access.
Airline operators dominate contract value; freight carriers are climbing the fastest as e-commerce logistics expands Andean cargo volumes.
Technology:
Digital infrastructure investment separates facilities competing for lessor acceptance from legacy operators facing certificate limitations.
- Predictive Maintenance:Machine learning algorithms analyzing flight data recorder outputs enable condition-based component replacement before hard-time limits. Avianca and Viva Colombia deploy these platforms to eliminate buffer days from maintenance scheduling.
- Condition-Based Monitoring:Real-time sensor networks on engine modules and landing gear track degradation patterns without physical inspection. Colombian facilities integrating these systems capture lessor contracts requiring digital logbook harmonization.
- Aircraft Health Management:Centralized data platforms aggregate fleet-wide performance metrics to prioritize hangar slot allocation.
- Digital Twin:Virtual replicas simulating structural fatigue enable simulated inspection protocols that reduce physical teardown requirements.
Predictive maintenance commands the steepest investment trajectory; condition-based monitoring is gaining share fastest among mid-size Part 145 repair stations.
End User:
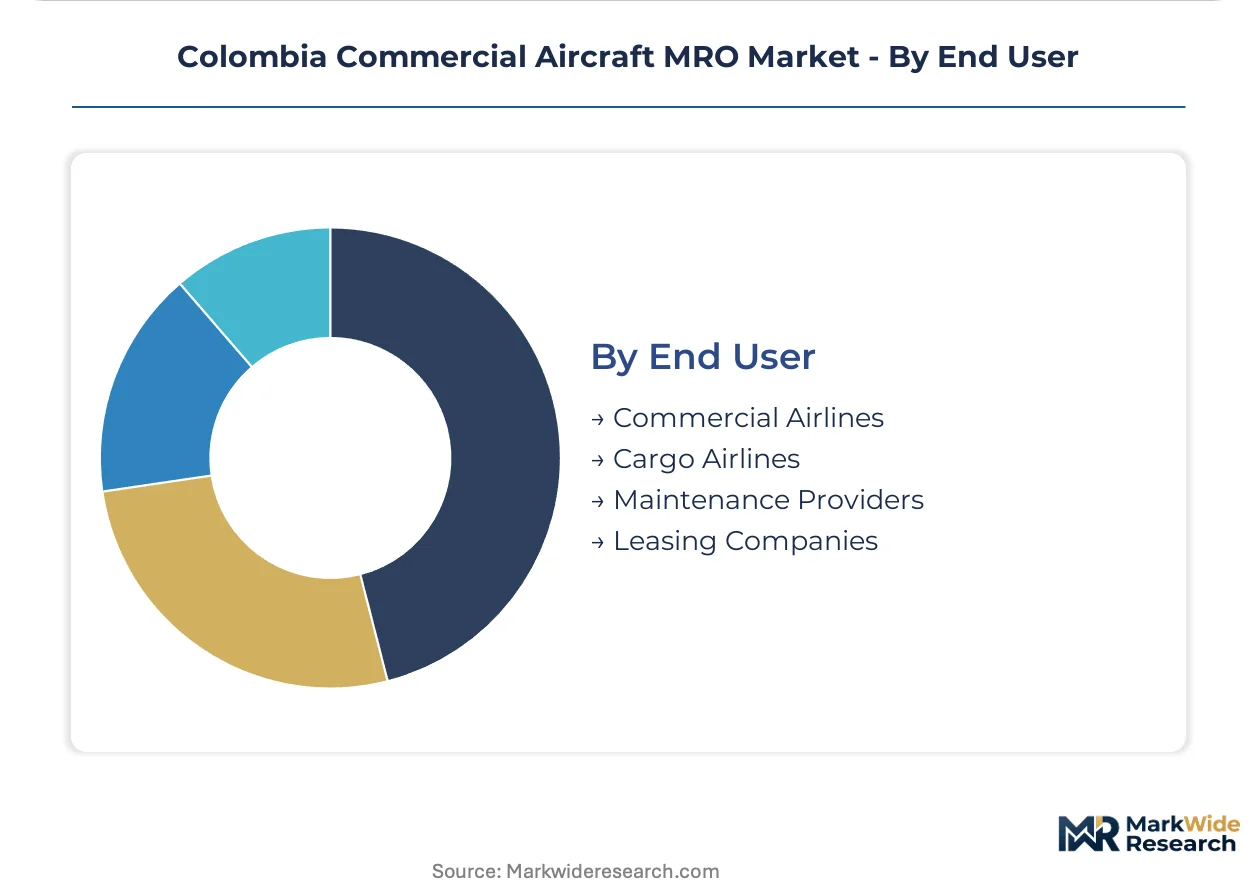
Procurement authority varies across end-user categories, with leasing companies imposing maintenance release standards that filter eligible Colombian facilities.
- Commercial Airlines:Passenger carriers operating under Colombian civil aviation authority jurisdiction generate recurring heavy maintenance volumes that sustain dedicated airframe lines. FAA Part 145 equivalency unlocks bilateral recognition for facilities serving US-registered aircraft in Avianca's fleet.
- Cargo Airlines:Freighter operators running aging converted narrow-bodies demand cost-optimized C-check intervals with deferred non-critical repairs. Colombian cargo specialists source airframe work domestically while negotiating engine module exchanges through Central American intermediaries.
- Maintenance Providers:Third-party MRO facilities serving regional carrier contracts from Panama and Peru compete on labor rate differentials against Miami and São Paulo hubs.
- Leasing Companies:Aircraft lessors impose maintenance release documentation standards that favor digitally integrated facilities with blockchain-anchored logbook verification.
Commercial airlines anchor facility utilization; leasing companies are expanding most quickly as lessor influence over maintenance sourcing intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jet fuel refining capacity in Cartagena anchors Colombia's aviation supply chain, positioning the Andean nation as a maintenance hub for narrow-body fleets serving regional carrier networks.
Bogotá Capital District
El Dorado International Airport concentrates over 80 percent of certified heavy maintenance hangar capacity, with Avianca Services and Lufthansa Technik Colombia operating adjacent facilities. Colombia's civil aviation authority enforces FAA Part 145 equivalency standards that streamline technician certification for US-registered aircraft. The airport's maintenance cluster handles C-check intervals for Airbus A320 and Boeing 737 families serving Avianca and Viva Colombia.
Medellín Metropolitan Area
José María Córdova International Airport offers unconstrained hangar expansion potential with labor costs 15-20 percent below Bogotá levels. Antioquia's regional government administers tax incentive programs targeting aerospace investment under Colombia's productive transformation agenda. Aeroman Colombia operates cost-advantaged airframe overhaul lines attracting contracts from Panama and Peruvian carriers.
Cali and Valle del Cauca
Alfonso Bonilla Aragón International Airport supports line maintenance stations for low-cost carrier point-to-point networks linking Pacific coast destinations. The Valle del Cauca governor's office coordinates with Colombia's civil aviation authority on technical training partnerships with local polytechnic institutes. Palmira's emerging logistics corridor positions the sub-region for component distribution to Andean operators.
Barranquilla and Caribbean Coast
Ernesto Cortissoz International Airport captures maintenance demand from cargo operators running converted narrow-body freighters on US-Colombia routes. Atlántico Department's port infrastructure facilitates import of specialized engine tooling subject to national customs duty structures. The sub-region's humidity-controlled warehousing addresses corrosion-sensitive component storage requirements.
Colombia Commercial Aircraft MRO Market Competitive Environment
Global majors compete with regional champions across certification standards and labor rate differentials in Colombia's MRO sector. The market structure concentrates heavy maintenance capacity at El Dorado while fragmenting line maintenance across secondary airports. Three archetypes dominate: integrated airline-operator services, foreign specialist joint ventures, and independent third-party overhaul providers. Competitive dynamics center on bilateral airworthiness recognition and hangar slot allocation at congested primary hubs.
Among integrated airline-affiliated operators, Avianca Services and Avianca Group exemplify the vertical control archetype through captive fleet maintenance workflows. Lufthansa Technik Colombia occupies the foreign specialist position, leveraging German parent-company engine module expertise for Andean carrier contracts. Aeroman Colombia represents the independent third-party model, competing on labor rate advantages for regional airframe overhaul sourcing.
| Leading Market Players |
|---|
| Avianca Group |
| Lufthansa Technik Colombia |
| Aeroman Colombia |
| SGS Colombia S.A.S |
| Safran SA |
| ACC Columbia Jet Service GmbH |
| Avianca Services |
| Copa Airlines Colombia Technical Services |
| Indaer Aviation Technical Services S.A.S |
| Others |
Value Chain & Pricing Dynamics
Captive maintenance workflows at Avianca Services anchor pricing power through vertical control over hangar slots at El Dorado, while unbundled procurement by low-cost carriers fragments contract structures across competing facilities. FAA Part 145 equivalency requirements create tiered labor rate premiums that separate OEM-authorized engine specialists from airframe generalists competing on turnaround speed.
Pricing Analysis
Warranty bundling separates OEM-authorized engine overhauls with full module guarantees from unbundled airframe checks where carriers assume post-work risk. Pricing stratifies across OEM-certified, FAA-equivalent, and non-certified facility tiers based on bilateral airworthiness recognition and technician specialization depth. Cost compression in line maintenance intensifies as Viva Colombia and regional carriers tender individual work packages rather than sole-source contracts. Freight carriers running converted narrow-bodies exhibit highest price sensitivity, deferring non-critical repairs and negotiating extended payment terms, while leasing companies prioritize digital documentation standards over unit cost minimization.
Supply Chain Analysis
Direct-to-MRO channels handle specialized engine tooling and OEM-authorized diagnostic equipment flowing from Germany, the United States, and Singapore to Colombian facilities. Critical inputs include turbine blade alloys, composite resin systems, and avionics test benches that draw from concentrated aerospace manufacturing clusters. Tariff exposure on imported diagnostic equipment inflates project economics versus offshore alternatives in Miami or São Paulo. Distribution runs through El Dorado's bonded warehousing for customs-deferred component storage, with secondary routing to Medellín emerging for cost-advantaged airframe lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FAA Part 145 equivalency functions as a cost-of-compliance barrier that moats certified Colombian facilities from uncertified competitors seeking heavy maintenance contracts. The regulatory alignment requires capital-intensive technician training and OEM authorization investments that filter market participation.
For Market Incumbents: Lock in hangar slot allocation at El Dorado through long-term airline service agreements before Medellín infrastructure matures. Expand predictive maintenance technology integration to capture lessor contracts requiring digital logbook harmonization. Counter the threat of Central American labor rate competition by emphasizing bilateral airworthiness recognition for US-registered aircraft.
For New Entrants and Emerging Players: Enter via José María Córdova International Airport's unconstrained expansion zone to undercut Bogotá labor costs on airframe overhaul lines. Target freight carrier contracts from Panama and Peru where price sensitivity exceeds certification brand requirements. Pursue component maintenance specialization in landing gear or APU repair rather than competing head-to-head with Lufthansa Technik Colombia on engine modules.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by global MRO networks seeking Andean geographic positioning. Five-to-ten year viability hinges on EASA harmonization completion and digital infrastructure deployment rates. Monitor Colombian civil aviation authority progress toward European regulatory alignment as the primary inflection signal for certification reciprocity value.
| Strategic Initiative | Industry Significance |
|---|---|
| EASA Harmonization Certification | Unlocks European-registered aircraft contracts for Colombian facilities seeking geographic expansion. |
| Predictive Maintenance Platform Deployment | Enables condition-based interventions that extend component life cycles beyond traditional hard-time limits. |
| Medellín Hangar Capacity Expansion | Captures cost-advantaged airframe contracts from Central American carriers at 15-20% below Bogotá labor rates. |
| Blockchain-Anchored Logbook Verification | Satisfies leasing company documentation standards that filter eligible maintenance providers. |
| Composite Repair Capability Investment | Addresses Boeing 787 and Airbus A350 technical requirements exceeding current Colombian training infrastructure. |
Study Parameters
Multi-period observation of fleet utilization rates, hangar capacity utilization, and regulatory certification timelines anchored the trend analysis, supplemented by interviews with maintenance directors at Colombian carriers, FAA-certification officers, leasing company technical asset managers, and OEM field service representatives. Secondary validation drew from Colombian civil aviation authority regulatory filings, ICAO Annex 6 audit reports, airline procurement disclosures, and customs data on aircraft parts imports. Bottom-up facility capacity modeling triangulated against top-down fleet growth projections across the analysis window.
Segment-weighting approaches applied differential growth assumptions to engine maintenance, airframe overhaul, component repair, and line maintenance categories based on capital intensity and labor rate trajectories. The analytical framework incorporated narrow-body fleet composition shifts, predictive technology adoption curves, and bilateral airworthiness recognition expansion throughout the forecast period. CAGRs derived from installed base depreciation schedules and maintenance interval compression factors modeled against El Dorado capacity constraints.
Revisions become necessary when EASA-Colombia regulatory harmonization delays, composite repair certification backlogs, or Medellín infrastructure investment shortfalls materialize differently than baseline assumptions. Forecasts reflect documented judgments on technician pipeline output, import duty structures, and lessor acceptance thresholds for Colombian maintenance releases. Practitioners should monitor civil aviation authority regulatory correspondence, hangar construction permits in Antioquia, and airline RFP unbundling patterns for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Maintenance and MRO Solutions
US Aviation MRO Software Market
Aircraft Maintenance and MRO Solutions
Aircraft Exterior Strip and Repaint Services Market
Aircraft Maintenance and MRO Solutions
Wide-Body Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Global Aircraft Heavy Maintenance Visits Market
Aircraft Maintenance and MRO Solutions
MRO Software Market
Aircraft Maintenance and MRO Solutions
Aviation Engine MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Modernization Market
Aircraft Maintenance and MRO Solutions
GCC Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Component MRO Market
Aircraft Maintenance and MRO Solutions
Global Aircraft Engine MRO Market
Aircraft Maintenance and MRO Solutions
Cabin Reconfiguration and Retrofit MRO Services Market
Aircraft Maintenance and MRO Solutions
US Aerospace Components MRO Market
Aircraft Maintenance and MRO Solutions
Latin America Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Helicopter MRO Market
Aircraft Maintenance and MRO Solutions
Europe Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Autoclave Market