
 Aircraft Autoclave Market | 2026-2036
Aircraft Autoclave Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Autoclave Market Insights
The EU Green Deal's industrial decarbonization mandate is broadening the addressable market for energy-efficient autoclave systems across European aerospace supply chains. ASC Process Systems leverages its installed base in North American defense programs to sustain long-term service contracts. Ilshin Autoclave dominates Asian commercial aerospace expansion with standardized composite curing platforms. Bondtech anchors European demand through specialized vacuum-assisted systems aligned with REACH material compliance.
An aircraft autoclave is a pressure vessel operating at controlled temperature and pressure cycles, typically reaching 180°C and 6-10 bar, designed to cure thermoset composite prepregs and bond structural aerospace components. Horizontal autoclaves occupy the largest installed base due to fuselage panel and wing skin dimensions, while vacuum-assisted technology captures the fastest expansion as out-of-autoclave alternatives mature. Composite curing applications concentrate margin pools where Boeing and Airbus tier-one suppliers require AS9100-certified process validation.
FAA airworthiness directives and EASA CS-25 certification standards govern autoclave-processed structural integrity, compelling manufacturers to maintain Nadcap-accredited thermal processing. EPA emissions controls and OSHA workplace safety regulations further shape equipment specification for US-based facilities. Stakeholders must monitor evolving composite material qualifications under updated MDR frameworks and assess captive versus outsourced curing capacity as defense procurement shifts toward next-generation airframe programs.
Market Dynamics
Composite airframe penetration targets under FAA and EASA emissions mandates are forcing tier-one suppliers to expand thermal processing capacity faster than equipment lead times permit, creating structural backlogs in autoclave availability.
Growth Catalysts
- FAA Emissions Frameworks:Binding CO2 reduction targets for new aircraft certifications compel manufacturers to substitute aluminum with carbon-fiber composites, directly expanding autoclave throughput requirements across Boeing's supply chain.
- Defense Procurement Cycles:Next-generation military airframe programs in the United States and allied nations specify thermoset composite primary structures, sustaining demand for large-diameter horizontal autoclaves with defense-grade security protocols.
- Prepreg Material Advancement:Out-of-autoclave resin systems are maturing, yet high-performance structural applications still require traditional pressure-vessel curing, preserving autoclave relevance for critical load-bearing components.
Market Restraints
- Energy Input Volatility:Natural gas and electricity price swings directly compress operating margins for thermal processing facilities, particularly in European markets exposed to supply disruptions.
- Supply-Side Concentration:Specialized pressure-vessel steel and advanced insulation materials concentrate among a limited supplier base in Germany and Japan, creating procurement bottlenecks for autoclave fabricators.
- Substitute Process Maturation:Electron-beam curing and microwave-assisted processing are advancing for non-structural components, threatening addressable volume in secondary aerospace applications.
Strategic Opportunities
- EU Green Deal Industrial Mandates:Decarbonization requirements for manufacturing facilities create demand for heat-recovery autoclave designs and renewable-energy-integrated thermal systems across French and German aerospace clusters.
- Urban Air Mobility Expansion:Electric vertical take-off and landing vehicle manufacturers require standardized composite curing platforms at smaller scales than commercial aviation, opening a new equipment tier.
- Service Contract Unbundling:Predictive maintenance analytics and remote thermal cycle monitoring are enabling aftermarket revenue streams separate from equipment sales, particularly for installed defense-sector autoclaves.
Industry Challenges
- Nadcap Certification Timeline:Aerospace suppliers face 12-18 month accreditation cycles for thermal processing special processes, delaying revenue recognition and compressing project IRRs.
- Specialized Technician Scarcity:Pressure-vessel operation and composite cure engineering expertise concentrates among retiring workforce cohorts, forcing manufacturers to internalize training costs.
- Legacy System Integration:Brownfield facilities struggle to retrofit digital monitoring and automated loading systems onto 1990s-era autoclaves without triggering full recertification requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Autoclave Market |
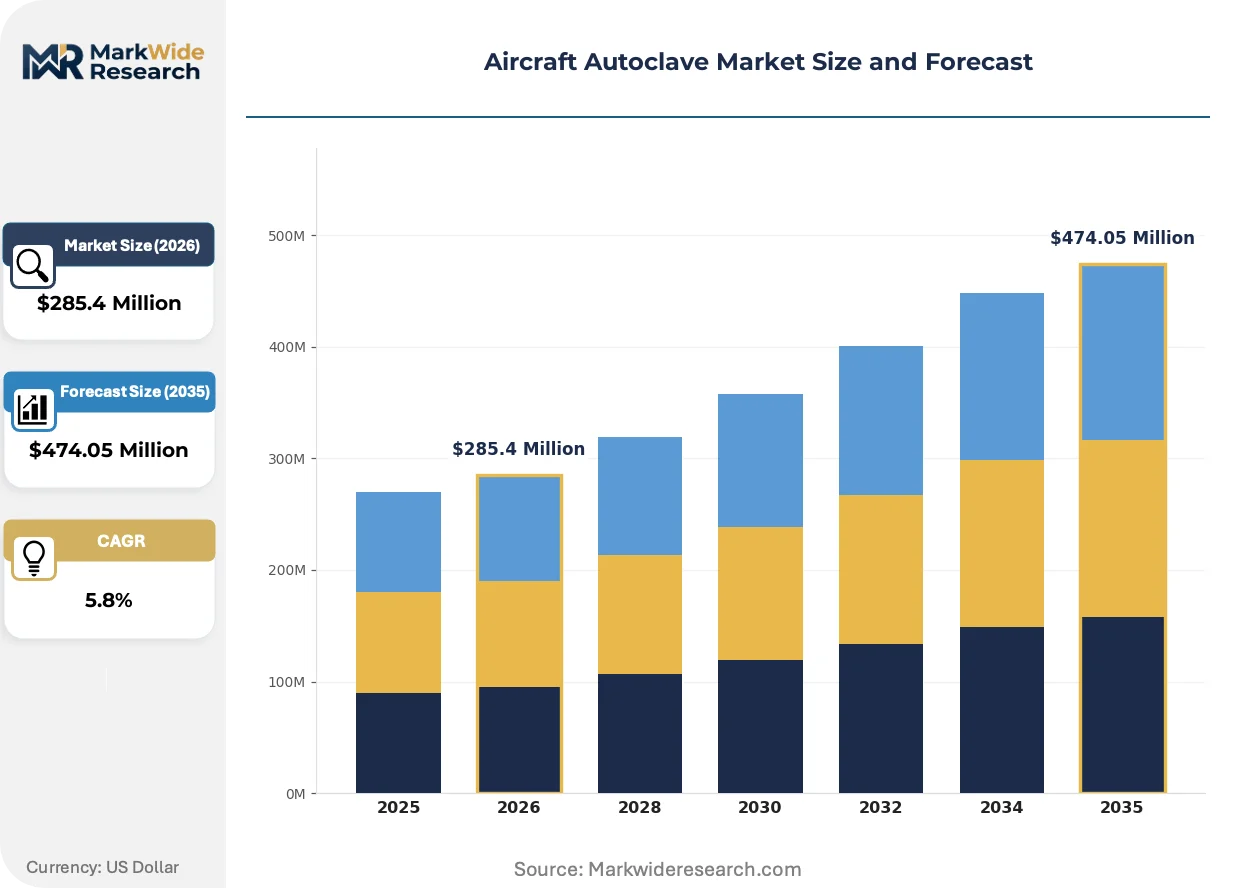
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $474.05 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vertical Autoclaves, Horizontal Autoclaves, Portable Autoclaves, Vacuum Autoclaves, Hybrid Autoclaves Technology: Steam Injection, Dry Air, Composite Curing, Vacuum Assisted, Microwave Heating Application: Aerospace Component Curing, Structural Bonding, Material Sterilization, Surface Treatment, Composite Fabrication End User: Aircraft Manufacturers, Maintenance Facilities, Defense Contractors, Aviation OEMs |
| Companies Covered | ASC Process Systems, Taricco Corporation, Bondtech, Olmar, ATTSU Industrial Group, Ilshin Autoclave, Thermal Engineering, Didion's Mechanical, Teruzzi Fercalx, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Autoclave Market Trends and Innovations
Digital thermal profiling and predictive maintenance architectures are displacing manual cure cycle management, while regulatory pressure on embodied carbon intensifies scrutiny of energy-intensive processing equipment.
Multi-zone temperature control systems with real-time fiber-optic sensing are consolidating process uniformity standards across large-format autoclaves. Airbus tier-one suppliers in France and Germany are mandating these systems for new fuselage panel contracts. The technology is consolidating quality variance between shifts and facilities, reducing rework rates and compressing the competitive advantage of manual process expertise.
REACH material compliance updates from ECHA are restricting legacy resin formulations used in vacuum-assisted cure cycles. European aerospace suppliers must reformulate prepregs or invest in emissions-abatement retrofits. The regulation most affects mid-tier composite shops in Italy and Spain that lack captive R&D resources to qualify alternative chemistries.
Buyers are consolidating procurement authority at the OEM level rather than distributing it across tier-one and tier-two suppliers. Boeing and Airbus now specify approved equipment vendors directly, bypassing traditional distributor channels. This concentration is most visible in the United States, where defense primes have adopted similar centralized vendor qualification for military composite programs.
Aircraft Autoclave Market Segmentation
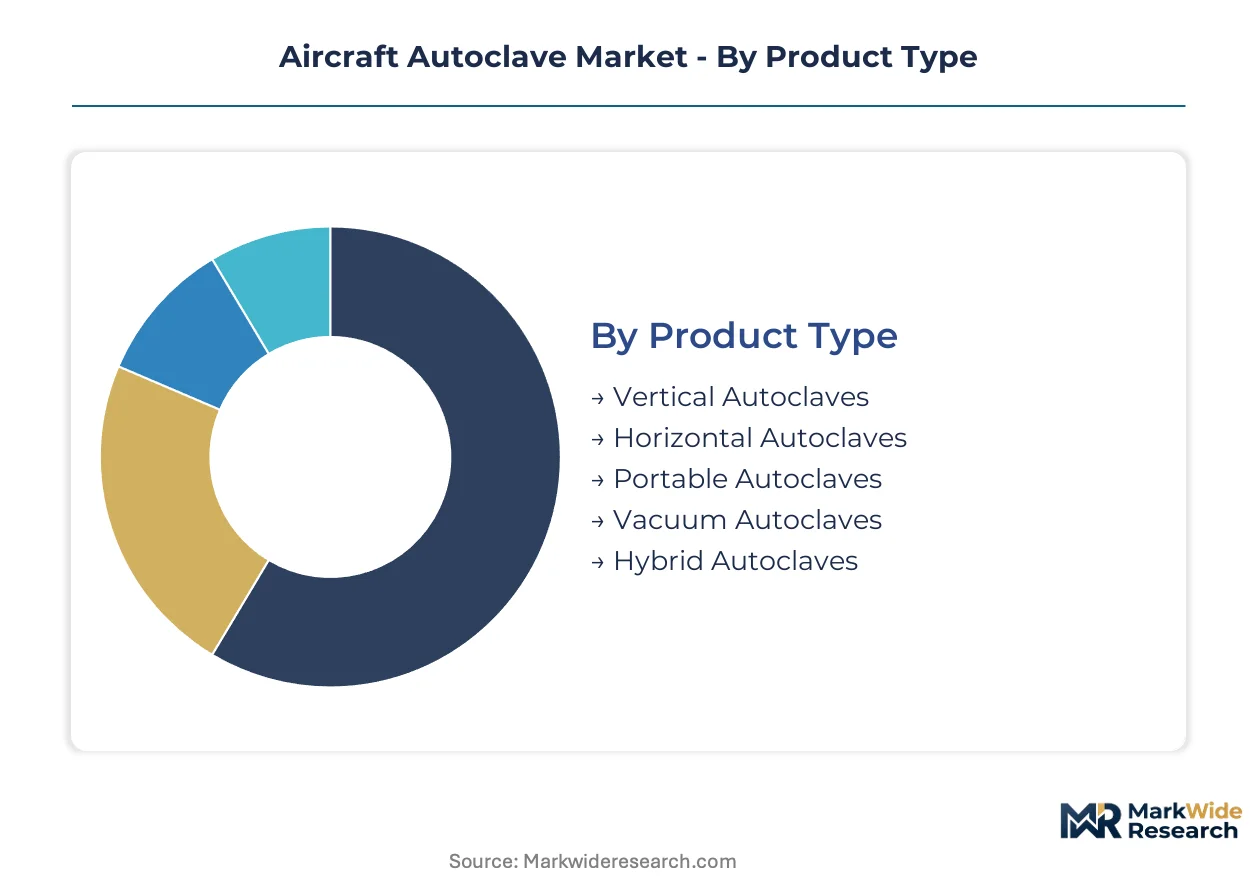
Aircraft autoclave procurement decisions hinge on pressure-vessel dimensions, thermal uniformity specifications, and cure cycle throughput requirements. Boeing and Airbus tier-one suppliers segment their capital allocation across product formats and heating technologies based on airframe component scale and composite material certification status.
Product Type:
Capital intensity varies dramatically across pressure-vessel configurations, with floor space requirements and foundation engineering costs driving total project economics.
- Horizontal Autoclaves:Cylindrical pressure vessels oriented lengthwise accommodate fuselage panels and wing skins exceeding 15 meters. Boeing's supply chain in the United States concentrates demand for large-diameter units requiring reinforced concrete foundations and specialized rail loading systems.
- Vertical Autoclaves:Upright cylindrical chambers suit smaller structural components and control surfaces with reduced floor space requirements. European maintenance facilities in France and Germany favor these configurations for MRO applications where real estate constraints limit horizontal expansion.
- Portable Autoclaves:Modular skid-mounted units serve field repair operations and temporary production surges.
- Vacuum Autoclaves:Integrated vacuum-bag systems consolidate layup and cure operations for complex geometries.
- Hybrid Autoclaves:Dual-mode pressure vessels switch between autoclave and out-of-autoclave processing protocols.
Horizontal autoclaves absorb the bulk of installed capacity; vacuum autoclaves are expanding most quickly as out-of-autoclave alternatives mature.
Technology:
Heating methodology determines energy consumption profiles, temperature ramp rates, and regulatory compliance pathways for emissions-intensive thermal processing.
- Composite Curing:Multi-zone thermal management systems with programmable pressure cycles cure thermoset prepregs for primary aerospace structures. FAA airworthiness directives mandate these systems for flight-critical components in Boeing and Airbus supply chains.
- Steam Injection:Direct steam heating achieves rapid temperature elevation for high-volume production environments. Defense contractors in the United States specify steam-based systems for legacy military airframe programs with established cure specifications.
- Dry Air:Electric resistance heating eliminates moisture-related contamination risks for sensitive resin formulations.
- Vacuum Assisted:Integrated vacuum pumps consolidate bagging and cure operations for complex tool geometries.
- Microwave Heating:Electromagnetic energy delivery enables selective heating of conductive reinforcements.
Composite curing technology commands premium pricing; vacuum assisted systems are climbing the fastest as tier-two suppliers seek process flexibility.
Application:
Process validation requirements and Nadcap accreditation scope vary sharply across functional use cases, determining equipment specification stringency.
- Aerospace Component Curing:Pressure-temperature cycles cure carbon-fiber prepregs for wing skins, fuselage barrels, and empennage assemblies. Tier-one suppliers in Germany and France require AS9100-certified thermal processing for Airbus A350 and A320neo programs.
- Structural Bonding:Adhesive cure cycles join metallic and composite subassemblies with controlled pressure distribution. Boeing's 787 production line in the United States depends on large-format autoclaves for fuselage section bonding operations.
- Material Sterilization:Steam-pressure protocols eliminate biological contaminants from production tooling and fixturing.
- Surface Treatment:Controlled oxidation and coating cure cycles prepare substrates for adhesive bonding.
- Composite Fabrication:Prepreg consolidation and resin flow management for prototype and low-rate initial production.
Aerospace component curing dominates capital deployment; structural bonding is gaining share fastest as bonded joints replace mechanical fasteners.
End User:
Procurement authority concentration and security clearance requirements segment the customer base across commercial and defense aerospace value chains.
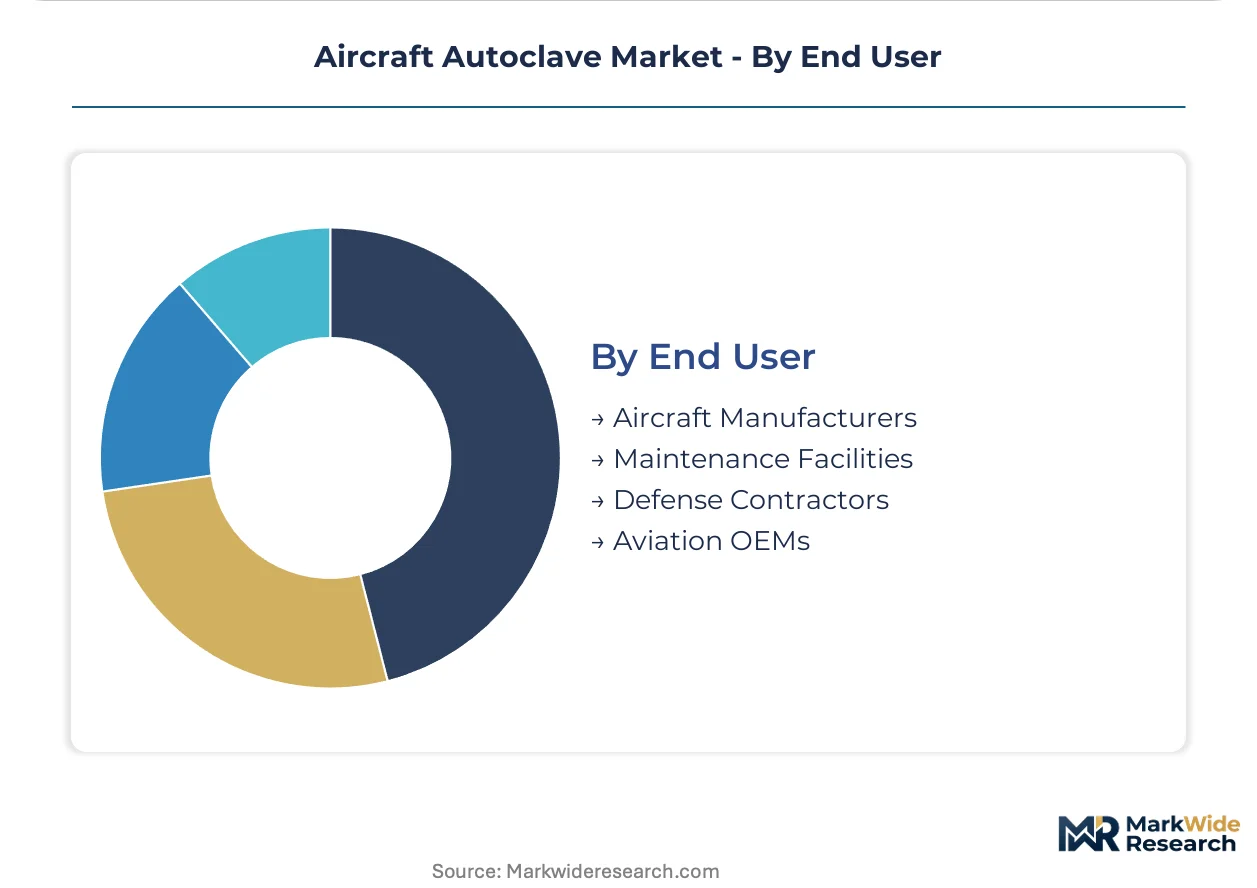
- Aircraft Manufacturers:Boeing and Airbus directly specify approved autoclave vendors for tier-one supplier qualification. These OEMs in the United States and France mandate Nadcap-accredited thermal processing for all flight-critical composite structures.
- Defense Contractors:Lockheed Martin and Northrop Grumman require defense-grade security protocols and US-origin pressure vessels for classified programs. ITAR compliance restricts equipment sourcing for military composite applications.
- Maintenance Facilities:MRO operators in Germany and the United Kingdom service aging fleets with smaller-diameter units.
- Aviation OEMs:Tier-one subsystem suppliers produce control surfaces, engine nacelles, and interior components.
Aircraft manufacturers control the bulk of procurement authority; defense contractors are expanding fastest as next-generation military programs accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wichita, Kansas anchors North American aerospace manufacturing, where Boeing's tier-one suppliers operate dense autoclave networks for 737 and 787 fuselage production. The city's composite curing capacity concentrates around McConnell Air Force Base and Spirit AeroSystems facilities.
United States
Defense procurement cycles sustain demand for large-diameter horizontal autoclaves across Lockheed Martin and Northrop Grumman supply chains. FAA airworthiness directives mandate Nadcap-accredited thermal processing for all flight-critical composite structures. Everett, Washington hosts Boeing's primary 787 production line, where fuselage section bonding requires reinforced concrete foundations and specialized rail loading systems.
Germany
Airbus tier-one suppliers in Hamburg and Bremen expand composite curing capacity for A350 and A320neo programs. EASA CS-25 certification standards govern autoclave-processed structural integrity across German aerospace clusters. The EU Green Deal's industrial decarbonization mandate drives heat-recovery autoclave adoption in Bavarian and Baden-Württemberg manufacturing facilities.
France
Toulouse and Nantes aerospace corridors concentrate demand for multi-zone temperature control systems with real-time fiber-optic sensing. REACH material compliance updates from ECHA restrict legacy resin formulations used in vacuum-assisted cure cycles. Saint-Nazaire's Airbus assembly plant mandates AS9100-certified process validation for all composite wing and fuselage panel suppliers.
Japan
Mitsubishi Heavy Industries and Subaru Corporation sustain autoclave installations for Boeing 787 wing box production in Nagoya and Hiroshima prefectures. METI's industrial efficiency standards shape equipment specification for thermal processing facilities. Chubu region aerospace suppliers face specialized pressure-vessel steel procurement bottlenecks from concentrated German and Japanese material sources.
United Kingdom
Bristol and Broughton aerospace clusters service Airbus wing production with Nadcap-accredited curing capacity. UK defense procurement shifts toward next-generation Tempest fighter programs specify thermoset composite primary structures. Northern England composite shops struggle with 12-18 month accreditation cycles for thermal processing special processes.
Aircraft Autoclave Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification tier and defense security clearance requirements. The vendor base stratifies between integrated pressure-vessel fabricators with captive metallurgy capabilities and specialized thermal system assemblers sourcing standardized pressure chambers. Three archetypes dominate: defense-security specialists with ITAR compliance infrastructure, commercial aerospace platform providers with Airbus and Boeing vendor qualification, and regional maintenance-focused operators serving MRO networks. Consolidation pressure concentrates on technology licensing partnerships and geographic expansion into emerging urban air mobility equipment tiers.
Within the defense-security tier, ASC Process Systems exemplifies North American prime contractor positioning through long-term service contract structures. Bondtech anchors European demand archetypes through specialized vacuum-assisted system configurations aligned with REACH material frameworks. Ilshin Autoclave occupies the Asian commercial expansion vector with standardized composite curing platforms. These three fabricators represent distinct geographic and regulatory positioning strategies rather than overlapping competitive territory.
| Leading Market Players |
|---|
| ASC Process Systems |
| Taricco Corporation |
| Bondtech |
| Olmar |
| ATTSU Industrial Group |
| Ilshin Autoclave |
| Thermal Engineering |
| Didion's Mechanical |
| Teruzzi Fercalx |
| Others |
Pricing and Supply Chain Analysis
Specialized pressure-vessel steel procurement costs cascade through three distinct equipment tiers, with German and Japanese metallurgy premiums compressing margins for mid-tier fabricators while defense-grade security protocols sustain pricing power at the certification-heavy top tier.
Pricing Analysis
Throughput-based value anchoring dominates commercial aerospace procurement, with Boeing and Airbus tier-one suppliers paying premiums for Nadcap-accredited thermal uniformity guarantees. Pricing stratifies across defense-security, commercial-platform, and maintenance-service tiers, with ITAR compliance requirements widening spreads between US-origin and import equipment. Cost compression in mid-tier composite curing systems is intensifying because Asian standardized platforms are displacing European vacuum-assisted configurations. Defense contractors exhibit lowest price sensitivity due to security clearance mandates, while tier-two Italian and Spanish shops face acute budget constraints under REACH reformulation costs.
Supply Chain Analysis
Advanced pressure-vessel steel and ceramic insulation supply rests on concentrated German and Japanese specialty producers, creating single-source vulnerability for autoclave fabricators outside these geographies. Equipment assembly draws from Italian control system integrators, Chinese electrical component suppliers, and US software architecture providers. Tariff exposure on pressure-vessel-grade alloys threatens margin stability for North American fabricators dependent on overseas metallurgy. Distribution runs through OEM-direct vendor qualification channels, with Boeing and Airbus consolidating procurement authority away from traditional tier-one distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment lead times stretching 18-24 months for large-diameter horizontal units prop sustained pricing power, with backlog accumulation insulating premium vendors from demand cyclicality.
For Market Incumbents: Lock in long-term service contracts with defense primes before next-generation airframe program awards consolidate vendor selection. ASC Process Systems exemplifies this model through captive aftermarket revenue streams. Backward integration into pressure-vessel metallurgy procurement mitigates German-Japanese supply bottlenecks. Certification investment in EU Green Deal heat-recovery designs captures decarbonization-driven replacement cycles. For New Entrants and Emerging Players: Launch via urban air mobility equipment tier, where standardized smaller-scale platforms bypass entrenched Boeing-Airbus vendor qualification barriers. Electric vertical take-off and landing manufacturers in the United States and Germany present penetrable demand with shorter sales cycles. Target aftermarket predictive maintenance software as entry wedge, piggybacking on installed base expansion rather than competing for capital equipment awards. For Investors and Strategic Acquirers: Nadcap accreditation timeline compression is the leading indicator that service-provider roll-up opportunities are ripening, as 12-18 month delays force distressed exits among mid-tier European composite shops. The 5-10 year viability window favors vendors with captive defense relationships over pure commercial plays exposed to out-of-autoclave substitution. Acquisition target archetype: regional maintenance-focused operators with established MRO network relationships and untapped digital monitoring upgrade potential.| Strategic Initiative | Industry Significance |
|---|---|
| Heat-Recovery System Development | EU Green Deal mandates in France and Germany drive retrofit demand for energy-efficient thermal processing. |
| Predictive Maintenance Platform Launch | Remote thermal cycle monitoring unlocks recurring revenue from defense-sector installed bases. |
| Urban Air Mobility Equipment Tier Entry | Standardized smaller-scale platforms address electric vertical take-off and landing manufacturing needs. |
| Backward Integration into Metallurgy Sourcing | Captive pressure-vessel steel procurement mitigates German-Japanese supply concentration risks. |
| Nadcap Accreditation Service Expansion | 12-18 month certification delays create consulting and expedited qualification revenue opportunities. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews involving autoclave fabrication engineers, thermal processing quality managers at tier-one aerospace suppliers, defense procurement officers, and aftermarket service directors. FAA airworthiness directive databases, EASA CS-25 certification registries, Nadcap accreditation records, and EU ECHA REACH compliance filings supplied structural validation. Bottom-up equipment shipment tallies triangulated against top-down aerospace composite demand forecasts.
Granularity-level modeling tracked horizontal, vertical, and vacuum-assisted configurations separately across composite curing, steam injection, and dry air heating technologies. End-use segmentation distinguished aircraft manufacturer procurement, defense contractor specifications, and maintenance facility demand. Application-level detail captured aerospace component curing, structural bonding, and surface treatment cycles. CAGRs derived from slope-intercept analysis of historical capacity expansion patterns correlated with Boeing and Airbus delivery schedules. Energy price volatility assumptions and defense procurement cycle phasing informed scenario-weighted outputs across the projection horizon.
Defense budget reallocation, out-of-autoclave technology maturation, and REACH resin formulation restrictions are the dominant revision risks to installed base forecasts. Regulatory timeline slippage for next-generation military airframe programs and composite material qualification delays under updated MDR frameworks present additional uncertainty vectors. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Maintenance and MRO Solutions
Aircraft Buffing Wheel Market
Aircraft Maintenance and MRO Solutions
MRO Software Market
Aircraft Maintenance and MRO Solutions
Regional Turboprop Engine MRO Services Market
Aircraft Maintenance and MRO Solutions
Aircraft Maintenance Market
Aircraft Maintenance and MRO Solutions
Gas Turbine MRO Market
Aircraft Maintenance and MRO Solutions
Africa Aviation MRO Market
Aircraft Maintenance and MRO Solutions
Asia-Pacific Aircraft Engine MRO Market
Aircraft Maintenance and MRO Solutions
Aviation Maintenance Software Market
Aircraft Maintenance and MRO Solutions
North America Aerospace Maintenance Chemical Market
Aircraft Maintenance and MRO Solutions
Digital MRO Market
Aircraft Maintenance and MRO Solutions
US Aerospace Components MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Exterior Strip and Repaint Services Market
Aircraft Maintenance and MRO Solutions
Asia-Pacific Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Landing Gear Repair and Overhaul Market
Aircraft Maintenance and MRO Solutions
Aircraft Storage, Preservation and Reactivation Services Market
Aircraft Maintenance and MRO Solutions
Wide-Body Aircraft MRO Market